
 Global Evaporative Cooler Market | 2026-2036
Global Evaporative Cooler Market Size, Share, and Industry Trends Forecast 2026-2036
Global Evaporative Cooler Market Analysis
Asset-light leasing and cooling-as-a-service models is rewriting competitive entry barriers for evaporative cooler deployment across industrial campuses. Munters Group AB leverages its captive rental fleet to anchor long-term contracts with mining operators in Australia's Pilbara region. EBARA Corporation sustains manufacturing scale advantages through backward integration into corrosion-resistant alloy components. SPX Cooling Technologies competes on channel control, embedding its systems directly into original equipment manufacturer specifications for power plant retrofits.
An evaporative cooler is a heat rejection device that uses the latent heat of water evaporation to reduce air temperature, typically achieving wet-bulb depression within 80-90% effectiveness across dry climates. Industrial evaporative coolers dominate absolute unit volume due to their integration into continuous-process manufacturing plants where uptime requirements exceed 8,000 annual operating hours. Two-stage evaporative cooling represents the fastest-growing technology segment as hybrid designs combining direct and indirect stages address humidity constraints in semi-arid zones. Ceiling-mounted evaporative coolers occupy a narrower but higher-margin niche within agricultural facilities requiring uniform air distribution across livestock housing and greenhouse operations.
The US EPA Energy Star program and California's Title 24 building efficiency standards shape product certification requirements for residential and commercial evaporative cooler sales. India's Bureau of Energy Efficiency mandates star ratings for cooling appliances through its Standards and Labeling program, while the EU F-Gas Regulation restricts hydrofluorocarbon refrigerants in vapor-compression systems, indirectly expanding addressable demand for adiabatic alternatives. Stakeholders must monitor how evolving refrigerant phase-down schedules and carbon border adjustment mechanisms reshape total cost-of-ownership calculations against conventional air conditioning across key demand corridors.
Market Dynamics
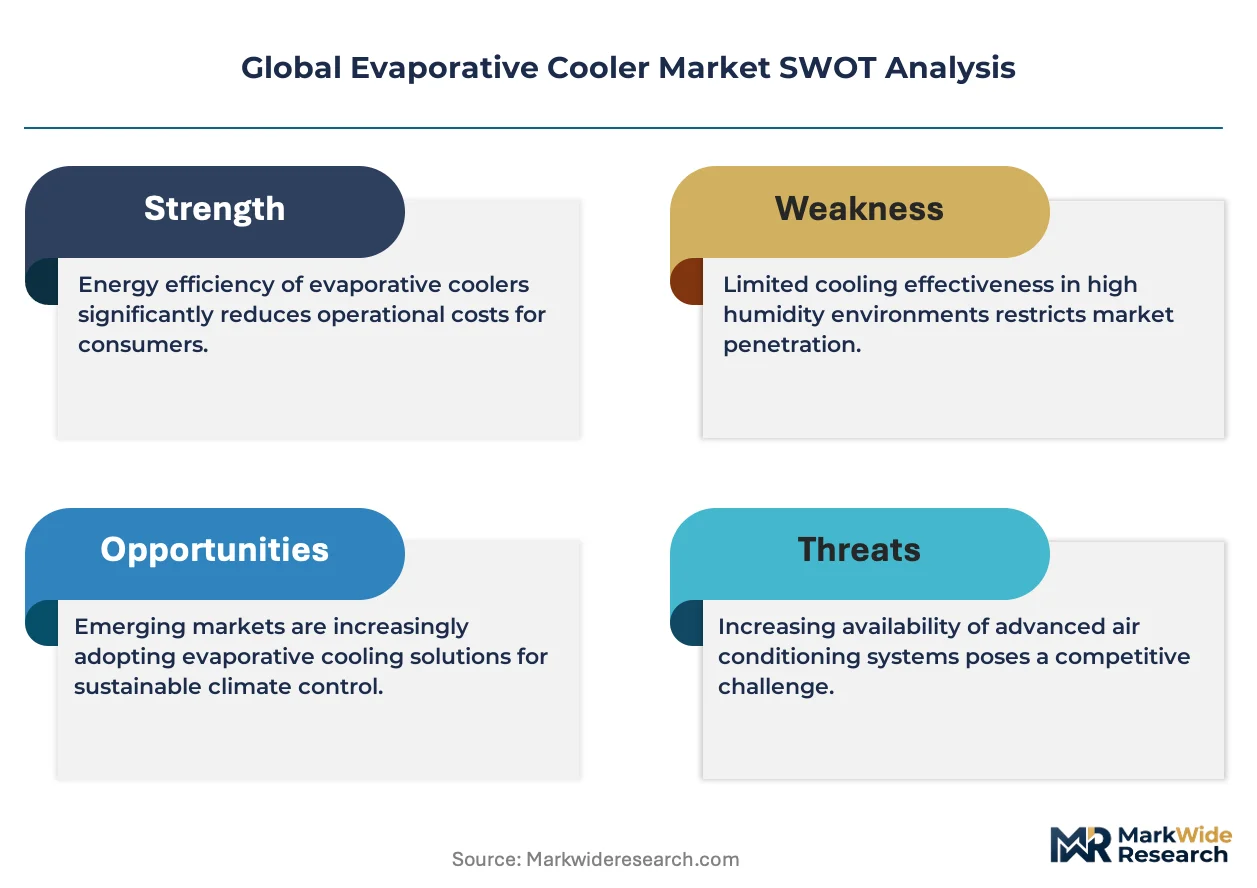
Water scarcity regulations across arid climate zones are forcing evaporative cooler manufacturers to redesign water consumption profiles and recirculation systems, compressing product development cycles while expanding addressable markets into semi-arid humidity corridors.
Growth Catalysts
- EU F-Gas Regulation phase-down:Hydrofluorocarbon restrictions on vapor-compression systems redirect commercial cooling procurement toward adiabatic alternatives in Spain, Italy, and Greece.
- Mining sector uptime requirements:Australia's Pilbara and Western Australia's iron ore corridors demand continuous-process cooling exceeding 8,000 annual operating hours where evaporative systems outperform mechanical refrigeration.
- Two-stage hybrid designs:Direct-indirect combined systems address humidity constraints in semi-arid zones, opening installations across Morocco's Ouarzazate solar complex and Jordan's phosphate processing facilities.
Market Restraints
- Corrosion-resistant alloy costs:Stainless steel and specialized coating inputs for wet-section components face price volatility tied to nickel supply concentration in Indonesia and the Philippines.
- Water availability thresholds:Municipal water restrictions in California's Central Valley and Arizona's Maricopa County cap deployment density for agricultural evaporative cooling installations.
- Vapor-compression efficiency gains:Variable-refrigerant-flow systems with improved coefficient-of-performance metrics retain share in mixed-humidity climate zones.
Strategic Opportunities
- Saudi Arabia gigaproject pipeline:NEOM, Red Sea Global, and Qiddiya developments specify adiabatic cooling for outdoor entertainment venues and worker housing in extreme-arid conditions.
- Cooling-as-a-service contracts:Asset-light leasing models reduce capital barriers for Indian textile processors and Vietnamese electronics assembly plants.
- India BIS star-rating expansion:Bureau of Energy Efficiency mandate extensions to industrial evaporative coolers create compliance-driven replacement cycles across Maharashtra and Gujarat manufacturing belts.
Industry Challenges
- Adiabatic process engineering talent:Wet-bulb depression optimization and psychrometric system design expertise concentrates among aging specialist cohorts in Australia and the southwestern United States.
- Legacy building integration:Retrofit installations in existing HVAC infrastructure require ductwork reconfiguration and controls interoperability with building management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Evaporative Cooler Market |
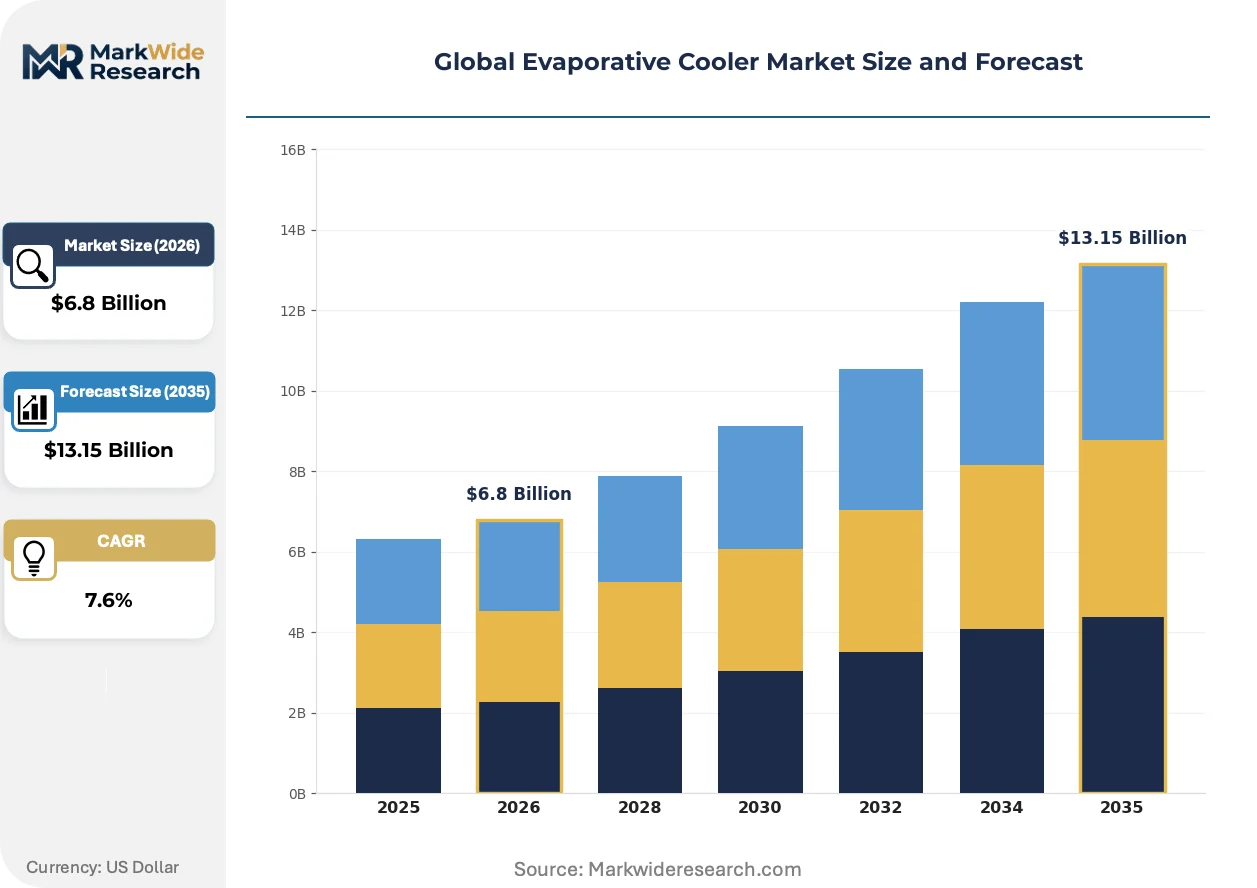
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Evaporative Coolers, Window Evaporative Coolers, Industrial Evaporative Coolers, Ceiling-mounted Evaporative Coolers Technology: Direct Evaporative Cooling, Indirect Evaporative Cooling, Two-stage Evaporative Cooling, Hybrid Cooling Systems End User: Manufacturing Plants, Warehouses, Agricultural Facilities, Commercial Establishments Distribution Channel: Online Retailers, Specialty Stores, HVAC Dealers, Direct Sales |
| Companies Covered | Munters Group AB, EBARA Corporation, SPX Cooling Technologies, Evapco Group, GEA Group, Condair Group AG, Kelvion Holding GmbH, Delta Cooling Towers, Baltimore Aircoil Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Evaporative Cooler Market Emerging Trajectories
Sensor networks and predictive maintenance algorithms are penetrating evaporative cooler installations, converting static heat-rejection equipment into connected assets that generate operational data and enable remote diagnostics.
Variable-speed fan arrays paired with real-time wet-bulb temperature sensors are digitizing airflow modulation across Saudi Aramco's Dhahran facilities and Chile's Escondida copper concentrator plants. Mining operators and petrochemical processors deploy these systems to trim water consumption during peak tariff periods. The technology is digitizing maintenance scheduling, compressing unplanned downtime intervals from days to hours through vibration monitoring and bearing-temperature telemetry.
California's Title 24 building efficiency standards now mandate economizer integration for cooling systems above specified tonnage thresholds, pushing evaporative cooler OEMs to certify hybrid economizer-adiabatic packages. The regulation compresses approval timelines for conventional mechanical-only designs while expanding rebate eligibility for two-stage evaporative configurations. Commercial real estate developers in Los Angeles County and San Diego County accelerate specification of compliant systems to secure utility incentive pools.
Leasing structures displace capital purchase models across Australian mining camps and Chilean lithium extraction sites, with operators preferring per-ton-cooled contracts that bundle equipment, maintenance, and water treatment. Channel intermediaries lose margin to captive rental fleets operated by original manufacturers. This pattern concentrates in remote-site deployments where logistics complexity favors single-source accountability over multi-vendor procurement.
Global Evaporative Cooler Market Segmentation
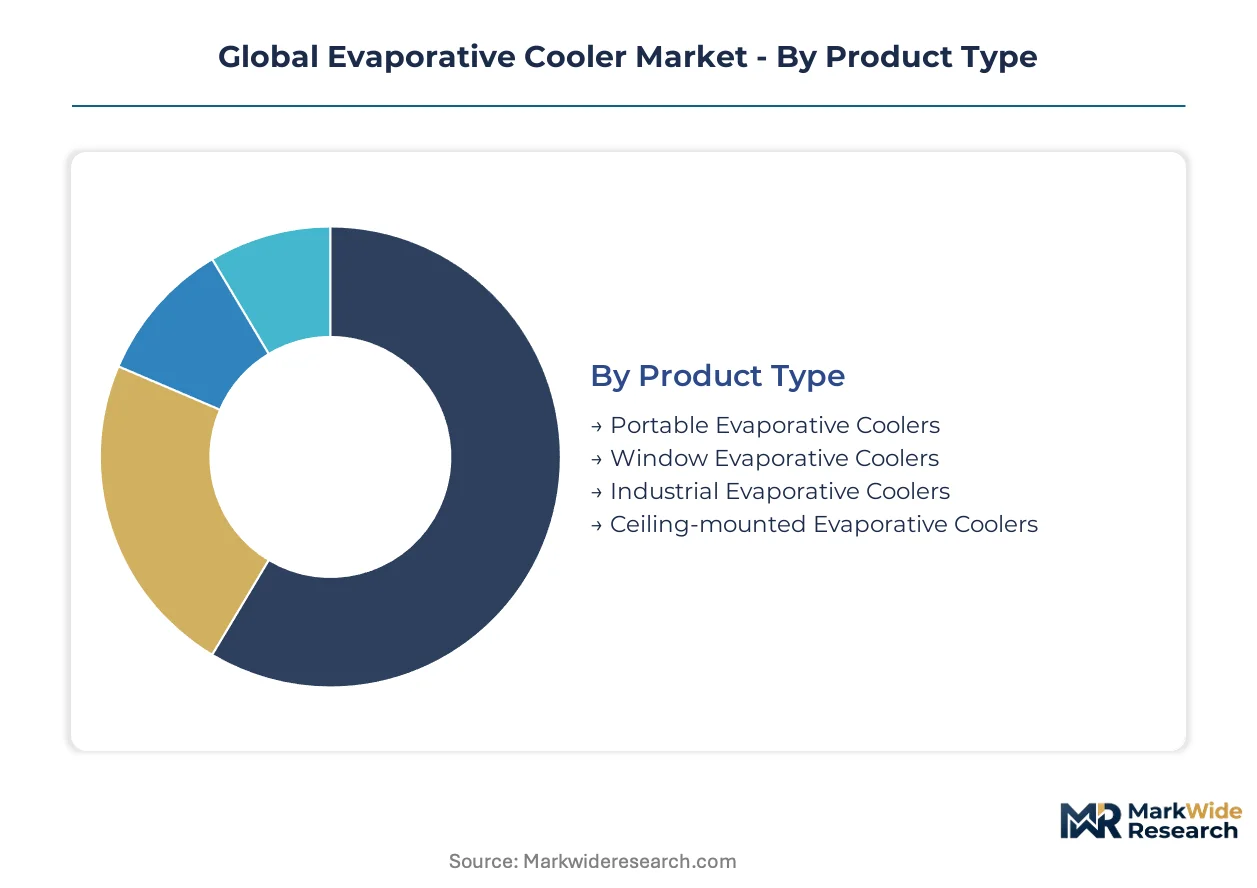
Evaporative cooler segmentation reveals distinct performance profiles across product architectures, cooling technologies, and procurement pathways. Each dimension carries divergent margin structures, regulatory exposure, and customer lifetime value characteristics that reshape competitive priorities.
Product Type:
Cost tier differentiation separates portable residential units from engineered industrial systems requiring continuous-duty metallurgy and controls integration.
- Industrial Evaporative Coolers:Continuous-process designs rated for 8,000+ annual operating hours dominate mining and petrochemical installations. Australia's Pilbara iron ore corridors and Saudi Aramco's Dhahran facilities specify these systems for uptime-critical cooling where mechanical refrigeration fails on energy economics. Nickel-alloy wet sections and variable-speed fan arrays command premium pricing against standard commercial alternatives.
- Ceiling-mounted Evaporative Coolers:Suspended distribution systems achieve uniform air mixing across agricultural facilities requiring precise temperature stratification. Livestock housing operations in California's Central Valley and greenhouse complexes in Almeria, Spain deploy these units where floor space constraints eliminate pad-and-fan alternatives. Specialized corrosion coatings and washdown-rated motors differentiate agricultural-specified models from standard commercial variants.
- Portable Evaporative Coolers:Mobile units with caster-mounted reservoirs serve construction sites and event venues requiring temporary cooling capacity.
- Window Evaporative Coolers:Through-wall residential installations concentrate in southwestern US housing stock and Australian suburban retrofits.
Industrial evaporative coolers command the established base. The steepest expansion runs through ceiling-mounted agricultural configurations.
Technology:
Application requirements determine cooling stage selection, with humidity tolerance and wet-bulb depression targets driving specification decisions.
- Two-stage Evaporative Cooling:Direct-indirect hybrid designs combine primary wet-bulb depression with secondary heat exchanger isolation, extending operational range into semi-arid zones. Morocco's Ouarzazate solar complex and Jordan's phosphate processing facilities specify these systems where single-stage direct cooling fails on humidity constraints. The technology opens installations across Mediterranean coastal corridors previously closed to adiabatic alternatives.
- Direct Evaporative Cooling:Single-stage wet-pad systems achieve maximum efficiency in extreme-arid conditions with wet-bulb depressions approaching 90% effectiveness. NEOM gigaproject worker housing and Saudi entertainment venues specify direct systems where ambient humidity remains below 20% annually. Simpler mechanical architecture and lower first cost sustain dominance in desert climate zones.
- Indirect Evaporative Cooling:Heat-exchanger-isolated designs deliver cooled air without moisture addition, serving sensitive manufacturing environments.
- Hybrid Cooling Systems:Integrated vapor-compression backup configurations address peak-load conditions in transitional climate zones.
Direct evaporative cooling retains volume leadership across extreme-arid installations. Two-stage hybrid configurations are gaining share fastest in semi-arid expansion corridors.
End User:
Customer type segmentation aligns procurement authority, maintenance capability, and total cost-of-ownership sensitivity across distinct operational contexts.
- Manufacturing Plants:Continuous-process facilities with 24/7 cooling requirements specify industrial-grade systems with predictive maintenance integration. Indian textile processors in Maharashtra and Gujarat manufacturing belts drive compliance-driven replacement cycles under BIS star-rating mandates. Asset-light leasing models penetrate this segment as capital constraints favor per-ton-cooled contracts over equipment ownership.
- Agricultural Facilities:Livestock housing and greenhouse operations demand uniform air distribution with washdown-rated construction. California's Central Valley dairy operations and Spain's Almeria greenhouse clusters specify corrosion-resistant ceiling-mounted units. Water availability thresholds in Arizona's Maricopa County and municipal restrictions cap deployment density for this user category.
- Warehouses:Distribution centers with intermittent occupancy patterns favor economizer-integrated systems under California Title 24 mandates.
- Commercial Establishments:Retail and hospitality venues in Spain, Italy, and Greece redirect procurement toward adiabatic alternatives under EU F-Gas Regulation phase-down schedules.
Manufacturing plants anchor current installed base. Agricultural facilities show the steepest expansion trajectory on livestock welfare regulation tightening.
Distribution Channel:
Supply concentration varies by channel, with captive rental fleets and OEM specification control displacing traditional intermediary margins.
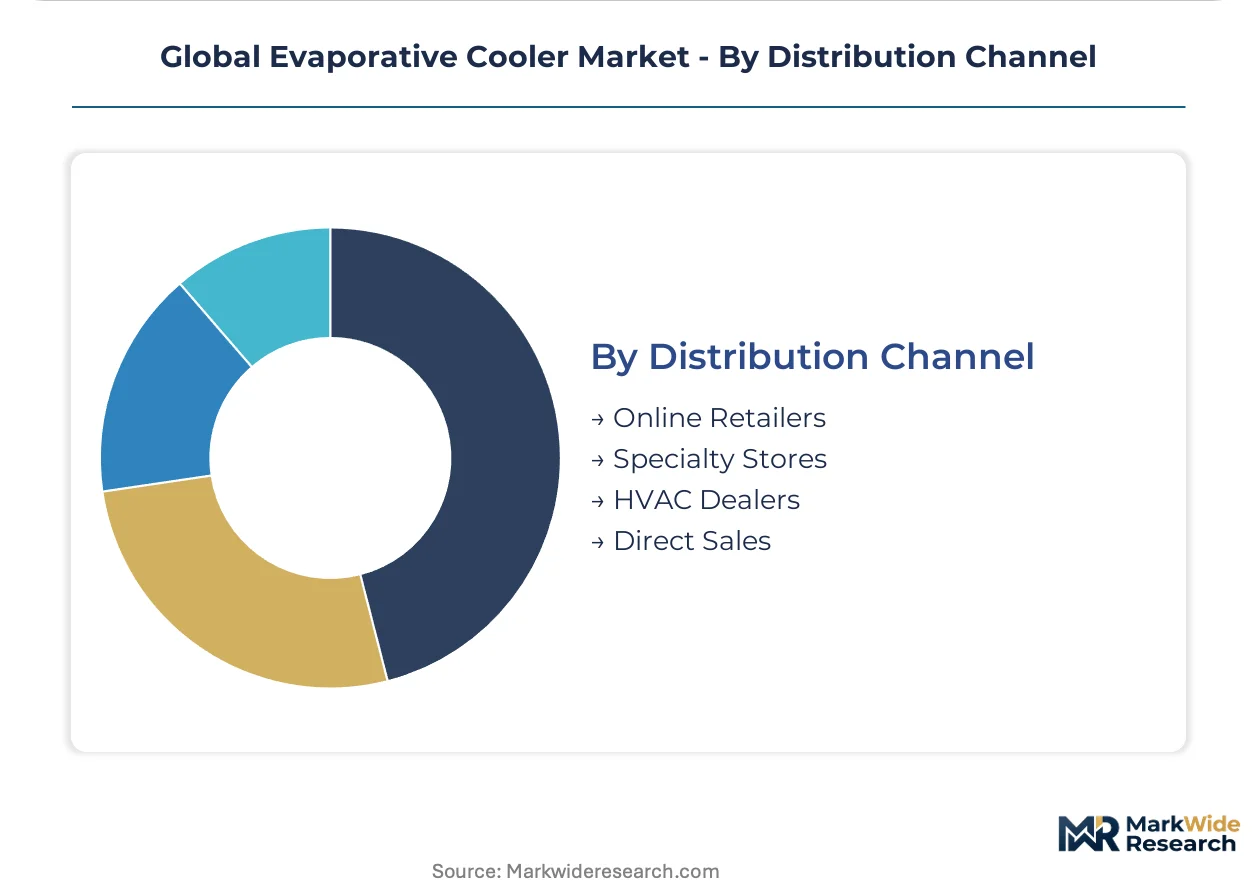
- Direct Sales:Manufacturer-account relationships dominate industrial and mining deployments where single-source accountability reduces logistics complexity. Australian mining camps and Chilean lithium extraction sites prefer direct procurement of bundled equipment-maintenance-water treatment packages. Channel intermediaries lose margin to captive rental fleets operated by original manufacturers in remote-site contexts.
- HVAC Dealers:Specification influence persists in power plant retrofits and commercial building integration where ductwork reconfiguration requires controls interoperability expertise. SPX Cooling Technologies embeds systems directly into OEM specifications through this channel. Dealer networks carry inventory risk on standard commercial units while project-engineering margins concentrate on custom industrial configurations.
- Online Retailers:E-commerce platforms serve portable and residential window unit replacement demand.
- Specialty Stores:Regional HVAC equipment distributors retain relevance in agricultural replacement parts and service contracting.
HVAC dealers retain specification influence across retrofit infrastructure. Direct sales channels are displacing intermediary roles fastest in remote industrial deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Australia's mining corridors where uptime premiums justify nickel-alloy wet sections, while Indian textile processors face compressed margins under BIS compliance mandates that accelerate replacement cycles without commensurate pricing flexibility.
Australia
Pilbara iron ore operators specify continuous-duty evaporative systems rated for 8,000+ annual operating hours where mechanical refrigeration fails on energy economics. The country's national energy regulator enforces efficiency benchmarks through NCC Section J commercial building provisions. Perth-based engineering firms anchor maintenance contracts across Western Australia's lithium extraction sites where remote logistics favor single-source equipment leasing.
India
Maharashtra and Gujarat manufacturing belts drive compliance-driven replacement cycles under BIS star-rating mandate extensions to industrial evaporative coolers. The Bureau of Energy Efficiency tightens cooling appliance standards through its Standards and Labeling program. Surat textile processors adopt asset-light leasing models as capital constraints favor per-ton-cooled contracts over equipment ownership.
Saudi Arabia
NEOM, Red Sea Global, and Qiddiya gigaprojects specify adiabatic cooling for outdoor entertainment venues and worker housing in extreme-arid conditions. The Saudi Standards, Metrology and Quality Organization enforces product conformity through SASO energy efficiency labeling. Riyadh-based contractors embed two-stage hybrid systems across Diriyah Gate developments where humidity tolerance extends operational range.
United States
California's Central Valley dairy operations and Arizona agricultural facilities face municipal water restrictions that cap deployment density for evaporative cooling installations. The EPA Energy Star program and California Title 24 building efficiency standards shape product certification requirements through economizer integration mandates. Los Angeles County commercial real estate developers accelerate specification of compliant hybrid systems to secure utility incentive pools.
Spain
Almeria greenhouse clusters and Mediterranean coastal agricultural facilities deploy ceiling-mounted units where floor space constraints eliminate pad-and-fan alternatives. The EU F-Gas Regulation phase-down redirects commercial cooling procurement toward adiabatic alternatives in Spain's retail and hospitality sectors. Valencia-based HVAC contractors specify two-stage configurations across Murcia's agro-industrial zones where semi-arid humidity previously excluded evaporative options.
Global Evaporative Cooler Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying corrosion-resistant alloys and variable-speed drives. The vendor base stratifies across three tiers: multinational engineering conglomerates with captive rental fleets, mid-scale regional fabricators serving agricultural replacement markets, and specialized controls integrators digitizing legacy installations. Two competitive moves dominate: backward integration into nickel-alloy wet section production compressing input cost volatility, and cooling-as-a-service contract structures displacing capital purchase models in remote industrial deployments.
Within the multinational platform tier, Munters Group AB and EBARA Corporation exemplify divergent scale strategies. Munters anchors long-term mining contracts through its captive rental fleet across Australian Pilbara operations. EBARA sustains manufacturing position through upstream control over corrosion-resistant alloy component supply. SPX Cooling Technologies occupies a specification-driven position, embedding systems directly into OEM requirements for power plant retrofit infrastructure. These three entities represent distinct competitive archetypes: asset-light service integration, vertical manufacturing control, and channel specification capture.
| Leading Market Players |
|---|
| Munters Group AB |
| EBARA Corporation |
| SPX Cooling Technologies |
| Evapco Group |
| GEA Group |
| Condair Group AG |
| Kelvion Holding GmbH |
| Delta Cooling Towers |
| Baltimore Aircoil Company |
| Others |
Supply Flow & Price Mechanics
Indonesian and Philippine nickel mining concentration determines wet-section alloy pricing for industrial evaporative coolers, concentrating margin capture among manufacturers with captive supply arrangements while squeezing fabricators exposed to spot market volatility.
Pricing Analysis
Configured-to-order industrial systems command premiums of 40-60% above standard commercial units due to nickel-alloy wet sections and predictive maintenance integration. Three-tier pricing structure across premium, standard, and economy levels separates continuous-process mining specifications from agricultural ceiling-mounted variants. Cost compression in the portable residential tier is intensifying because of e-commerce price transparency and Chinese manufacturing scale. Agricultural processors in water-restricted jurisdictions exhibit highest price sensitivity, while Australian mining operators prioritize uptime guarantees over acquisition cost.
Supply Chain Analysis
Stainless steel feedstock draws from Indonesian nickel smelters, Chinese cold-rolling mills, and European specialty alloy foundries. Variable-speed drive electronics rest on semiconductor supply from Taiwan and South Korea. Single-source vulnerability concentrates in corrosion-resistant coating formulations held by German and Japanese chemical specialists. Distribution runs through captive rental fleets for remote mining deployments and HVAC dealer networks for commercial retrofit specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through BIS star-rating mandates and EU F-Gas phase-down schedules protects incumbent positions against substitute technology encroachment.
For Market Incumbents: Build switching-cost moats through cooling-as-a-service contract structures that bundle equipment, water treatment, and predictive maintenance into multi-year agreements. Backward integration into nickel-alloy component production compresses input cost volatility from Indonesian supply concentration. Channel control through OEM specification capture defends against emerging controls integrators digitizing legacy installations. For New Entrants and Emerging Players: Mid-market commercial buildings in Vietnam and Indonesia represent the most penetrable entry point where capital constraints favor leasing models over equipment ownership. Two-stage hybrid system retrofits across Spain's Mediterranean coastal corridor exploit EU F-Gas Regulation redirection of procurement toward adiabatic alternatives. Go-to-market execution should anchor on utility rebate eligibility certification under California Title 24 and comparable efficiency standards. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional fabricators serving agricultural replacement parts markets in California's Central Valley and Australia's dairy corridors. Long-term viability hinges on water scarcity regulation trajectory and mining sector capital expenditure durability. Watch for BIS mandate expansion beyond Maharashtra and Gujarat as inflection signal for compliance-driven replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cooling-as-a-Service Contract Expansion | Asset-light leasing reduces capital barriers for Indian textile processors and Vietnamese electronics plants. |
| Backward Integration into Nickel-Alloy Components | Captive wet-section production insulates margin from Indonesian supply volatility. |
| Two-Stage Hybrid System Certification | EU F-Gas phase-down redirects Spanish and Italian commercial procurement toward adiabatic alternatives. |
| Predictive Maintenance Platform Deployment | Sensor networks convert static equipment into connected assets generating recurring service revenue. |
| Channel Specification Capture through HVAC Dealers | OEM integration into power plant retrofit infrastructure locks out competitor access. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade databases, SEC filings from listed HVAC equipment manufacturers, Bureau of Energy Efficiency notification records, and EU regulatory gazettes. Plant engineers at continuous-process manufacturing facilities, procurement leads at Australian mining operators, HVAC contractor specification managers, and aftermarket service heads provided operational perspective. Bottom-up unit deployment estimates triangulate against top-down energy consumption modeling for adiabatic cooling penetration.
Forecast inputs span product architecture segmentation, cooling technology stage configuration, end-use industry vertical, and procurement pathway channel structure across the analysis window. CAGRs derive from regression against historical efficiency standard implementation patterns and mining sector capital expenditure cycles. Modeled variables include wet-bulb depression effectiveness thresholds, water availability constraint indices, and refrigerant phase-down schedule compliance costs.
Practitioners should monitor nickel price volatility, municipal water restriction expansion, and F-Gas Regulation enforcement intensity for early signals of forecast revision. Quarterly review of BIS notification drafts, Australian NCC Section J amendment proposals, and Saudi gigaproject contractor prequalification announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Evaporative Cooling Tower Market
Cooling Systems
Battery Cooling Plate Market
Cooling Systems
Global Air Coolers Market
Cooling Systems
Chilled Water System Market
Cooling Systems
Air Source Heat Pump Market
Cooling Systems
Horizontal Air Flow Condensers Market
Cooling Systems
Roll Bond Evaporator Market
Cooling Systems
Global Air Cooled Condenser Market
Cooling Systems
Heat Pump Dryer Market
Cooling Systems
Industrial Radiators Market
Cooling Systems
Europe Air Source Heat Pump Market
Cooling Systems
Cryosystem Market
Cooling Systems
Seawater Condensers Market
Cooling Systems
Adaptive Cooling Fan Market
Cooling Systems
Three Phase Cooling Fans Market
Cooling Systems
Solar Air Conditioning Market