
 Truck Loader Crane Market | 2026-2036
Truck Loader Crane Market Size, Share, and Industry Trends Forecast 2026-2036
Truck Loader Crane Market Analysis
Electrification of auxiliary power systems is narrowing the performance gap between hydraulic and electric truck loader crane architectures. PALFINGER AG leverages its European service network to sustain aftermarket revenue across aging installed bases. Sany Group Co. Ltd anchors its position through captive manufacturing of high-tensile boom steel in Xuzhou. Tadano Ltd competes on precision load-moment control systems for urban utility applications.
A truck loader crane is a hydraulically or electrically powered articulating boom crane permanently mounted on a commercial truck chassis, typically offering lifting capacities from one to over one hundred metric tons with outreach distances exceeding thirty meters; its primary purpose is to enable self-loading and unloading of heavy cargo at sites lacking dedicated material-handling infrastructure. Hydraulic systems dominate current installed capacity due to established service ecosystems and raw lifting power, while electric drivetrains represent the fastest-expanding technology segment as fleet operators face tightening urban emissions protocols. Remote controlled technology commands premium positioning in defense and infrastructure end-user segments where operator safety mandates drive specification.
The EU Machinery Directive and CE marking requirements enforce load-safety interlocks and stability monitoring across European deployments, while China's GB standards and MIIT certification govern domestic manufacturing quality and export eligibility. The US OSHA and NHTSA frameworks impose operator training protocols and vehicle weight distribution rules that shape chassis-engineering decisions. Stakeholders must weigh electrification capital outlays against regulatory compliance timelines and residual value trajectories.
Market Dynamics
Electrification of auxiliary power systems is forcing fleet operators to recalculate total cost of ownership across hydraulic and electric architectures, while EU Stage V emissions standards accelerate powertrain replacement cycles in municipal procurement.
Growth Catalysts
- Urban Emissions Mandates:Germany's KBA enforces Stage V compliance for municipal fleet renewals, redirecting capital toward electric-hybrid loader crane configurations in city infrastructure contracts.
- Defense Logistics Modernization:NATO members specify remote-controlled loader cranes for hazardous material handling, creating specification pull for precision load-moment systems in tactical vehicle programs.
- Steel Supply Integration:Captive production of high-tensile boom steel in Xuzhou and Duisburg reduces input cost volatility for crane manufacturers serving Asian and European construction equipment hubs.
Market Restraints
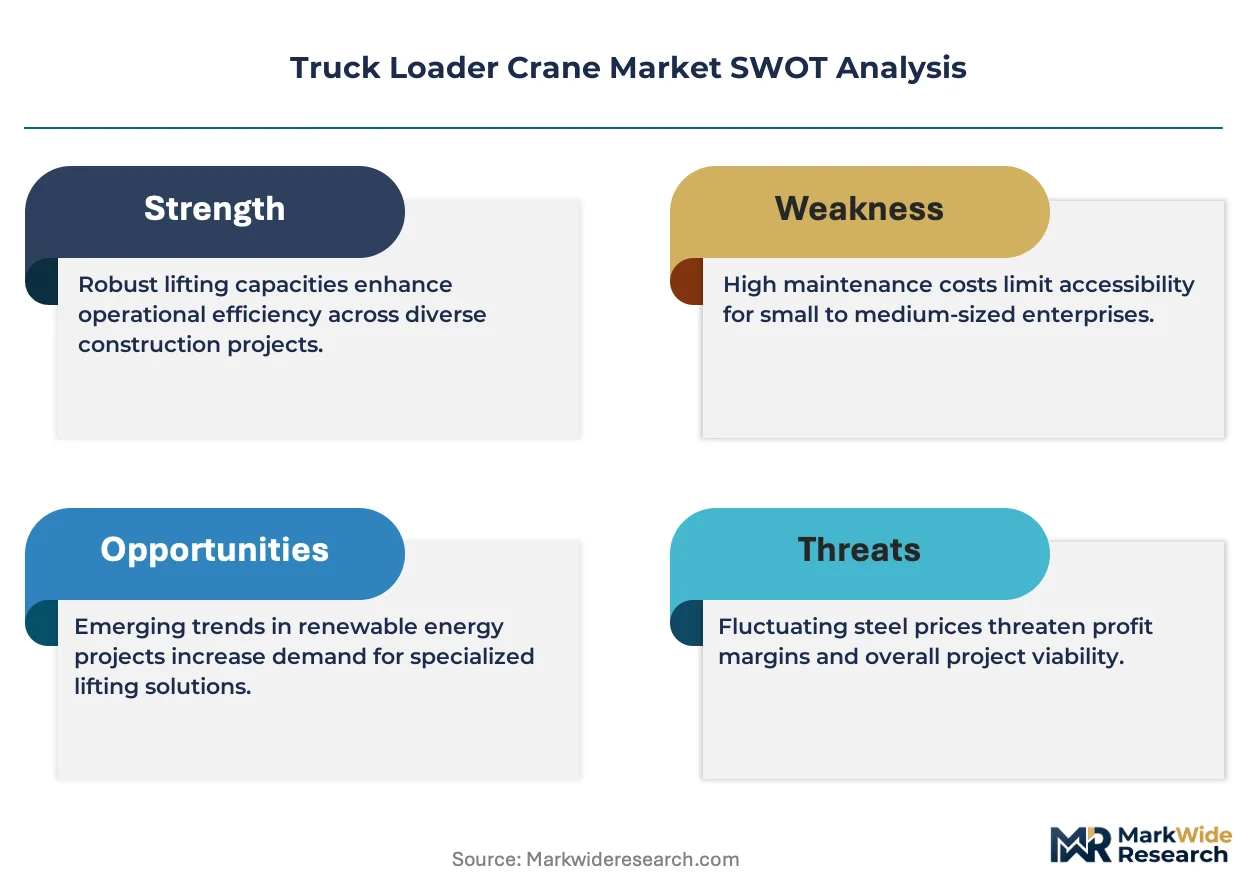
- Battery Energy Density Limits:Lithium-ion pack weight penalties restrict electric crane lifting capacity below 35 metric tons, confining electrification to light-duty urban delivery segments.
- Hydraulic Component Concentration:Precision valve and pump manufacturing concentrates in German and Italian supplier clusters, exposing OEMs to single-source risk during supply disruptions.
- CE Certification Timeline:EU Machinery Directive load-safety interlock testing extends product launch cycles by 8-14 months for non-European manufacturers seeking European market entry.
Strategic Opportunities
- Wind Turbine Service Expansion:Offshore maintenance vessel operators in the North Sea specify compact loader cranes for nacelle component replacement, opening maritime application demand.
- Railway Electrification Programs:India's CEA mandates overhead line equipment installation timelines that favor truck-mounted cranes with rapid deployment booms for trackside infrastructure.
- Telematics-Enabled Leasing:Usage-based financing models for construction SMEs bundle loader crane access with remote diagnostics, displacing traditional equipment ownership in fragmented contractor markets.
Industry Challenges
- Load-Moment System Calibration:Operator certification for precision control interfaces requires 40-60 hours of simulator training, extending workforce readiness timelines for fleet operators.
- Legacy Chassis Integration:Retrofitting electric power take-off systems onto existing diesel truck platforms demands custom driveline engineering that fragments spare parts availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Truck Loader Crane Market |
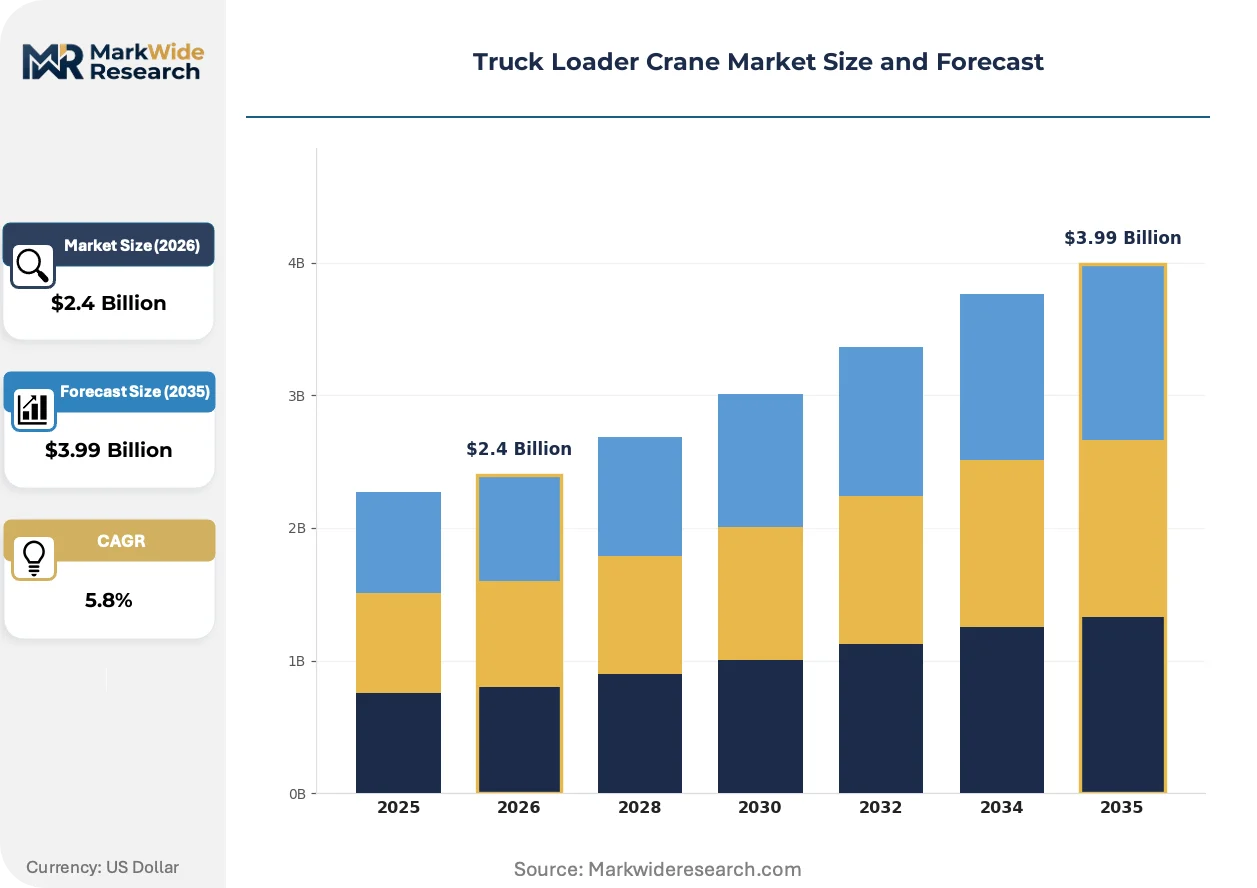
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic, Electric, Pneumatic, Mechanical Application: Construction, Mining, Transportation, Logistics End User: Contractors, Warehousing, Infrastructure, Defense Technology: Automated, Remote Controlled, Hybrid, Conventional |
| Companies Covered | Tadano Ltd, Sany Group Co. Ltd, Cargotec Corporation, Cormach S.R.L, PM Group S.r.l., PALFINGER AG, Xuzhou Construction Machinery Group Co., Ltd., EFFER S.r.l., Fassi Gru S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Truck Loader Crane Market Emerging Trajectories
Powertrain architecture is fragmenting across parallel development tracks, with hydraulic-electronic convergence creating intermediate technology categories that complicate procurement standardization for fleet managers.
Electro-hydraulic actuation is hybridizing conventional hydraulic circuits with servo-electric valve control, enabling millimeter-precision boom positioning. Defense contractors and nuclear facility operators in France and the UK specify these systems for explosive ordnance disposal and radiological material handling. The technology is compressing the performance gap between full-electric and legacy hydraulic architectures in the 20-50 ton capacity segment.
China's MIIT certification requirements for construction machinery exports now mandate real-time operational data transmission to provincial quality supervision databases. This industrial consequence forces OEMs to embed cellular connectivity modules as standard equipment rather than optional accessories. European manufacturers serving Chinese joint-venture partners face the steepest compliance adaptation costs.
Rental channel consolidation is concentrating fleet purchasing power among national equipment lessors with standardized specification protocols. Independent crane distributors in the US and Germany are losing specification influence as United Rentals and Loxam deploy proprietary telematics platforms that lock in preferred supplier relationships. This pattern is most visible in North American municipal procurement, where cooperative purchasing agreements aggregate demand across multiple jurisdictions.
Truck Loader Crane Market Segmentation
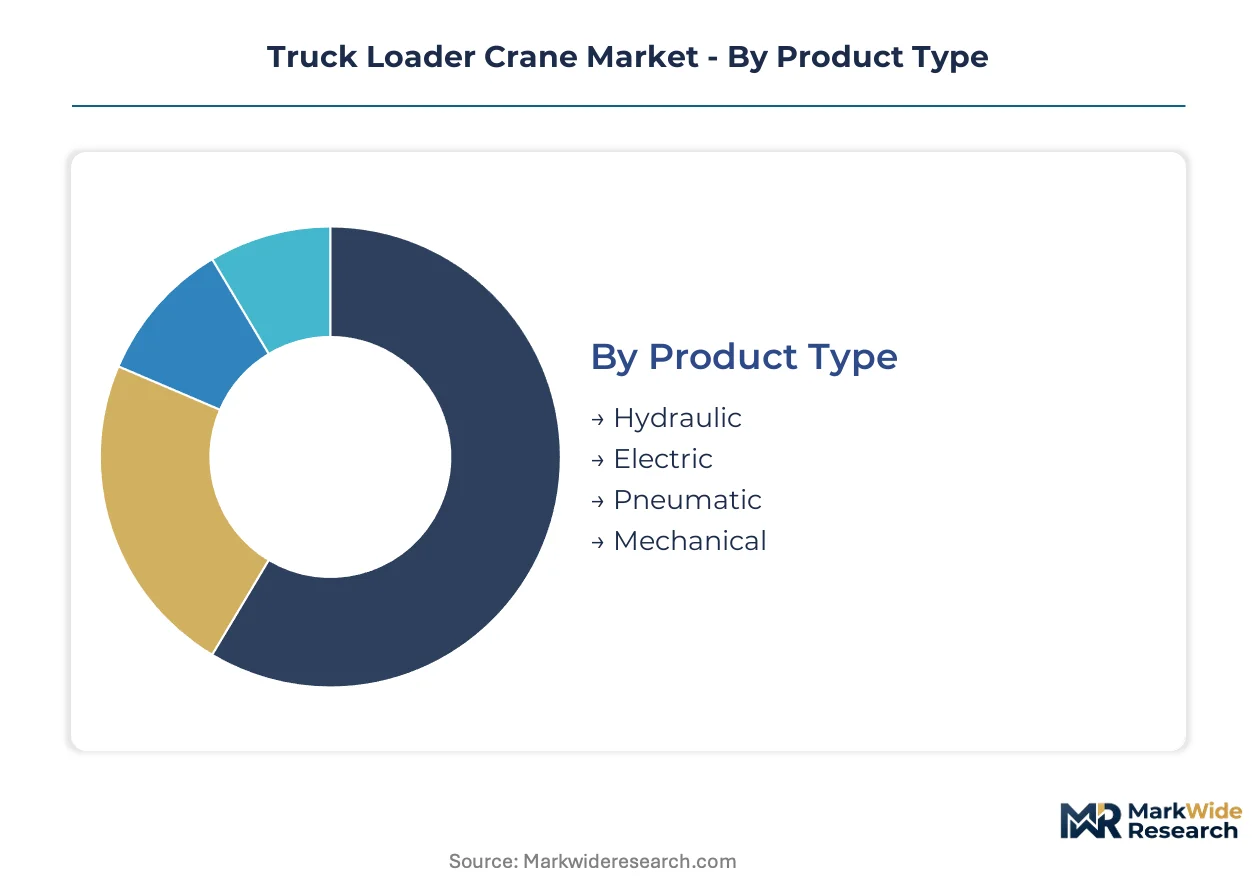
Truck loader crane procurement decisions fragment across powertrain architecture, operational environment, and control system sophistication. Fleet operators weigh emissions compliance timelines against lifting capacity requirements when specifying equipment across these dimensions.
Product Type:
Cost tier differentiation separates mature hydraulic infrastructure from emerging electric architectures with capital premium structures.
- Hydraulic:Fluid power systems deliver raw lifting force exceeding 100 metric tons through piston and gear pump configurations. German municipal fleets in Stuttgart and Hamburg specify these units for heavy infrastructure contracts where Stage V compliance deadlines remain distant.
- Electric:Battery-electric drivetrains eliminate tailpipe emissions through permanent magnet motors and regenerative boom lowering. Urban delivery operators in Rotterdam and Copenhagen face zero-emission zone mandates that accelerate procurement of sub-35-ton capacity configurations.
- Pneumatic:Compressed air actuation serves explosion-risk environments in chemical processing facilities.
- Mechanical:Linkage and winch systems persist in budget-constrained emerging markets with limited service infrastructure.
Hydraulic systems hold installed capacity. Electric architectures are rotating up the share rankings.
Application:
Volume concentration patterns reflect construction cycle intensity and materials handling automation imperatives.
- Construction:Building sector deployments require rapid boom cycling and all-terrain chassis compatibility for site access. Chinese equipment hubs in Xuzhou and Changsha concentrate manufacturing capacity serving domestic urbanization programs and Belt and Road export demand.
- Transportation:Self-loading freight operations demand compact stowage profiles and sub-10-minute deployment cycles. German logistics corridors along the Rhine-Alpine TEN-T network specify lightweight cranes for intermodal container transfers.
- Mining:Surface extraction operations prioritize dust-sealed hydraulics and reinforced boom structures for abrasive environments.
- Logistics:E-commerce fulfillment centers specify electric units for indoor warehouse operations with ventilation constraints.
Construction commands volume leadership. Transportation is climbing the fastest among application categories.
End User:
Customer type procurement authority varies with fleet scale and specification standardization maturity.
- Contractors:Fragmented construction SMEs favor rental access over ownership, driving telematics-enabled usage-based financing models. United Rentals and Loxam procurement protocols now mandate standardized connectivity modules across their North American and European fleets.
- Defense:NATO tactical vehicle programs specify remote-controlled precision systems for explosive ordnance disposal and hazardous material handling in contested logistics environments.
- Infrastructure:Municipal agencies in Germany and France aggregate demand through cooperative purchasing agreements that lock in preferred supplier relationships.
- Warehousing:Third-party logistics operators prioritize indoor electric configurations with reduced noise signatures for 24-hour fulfillment operations.
Contractor demand holds installed capacity. Defense procurement is rotating up the share rankings.
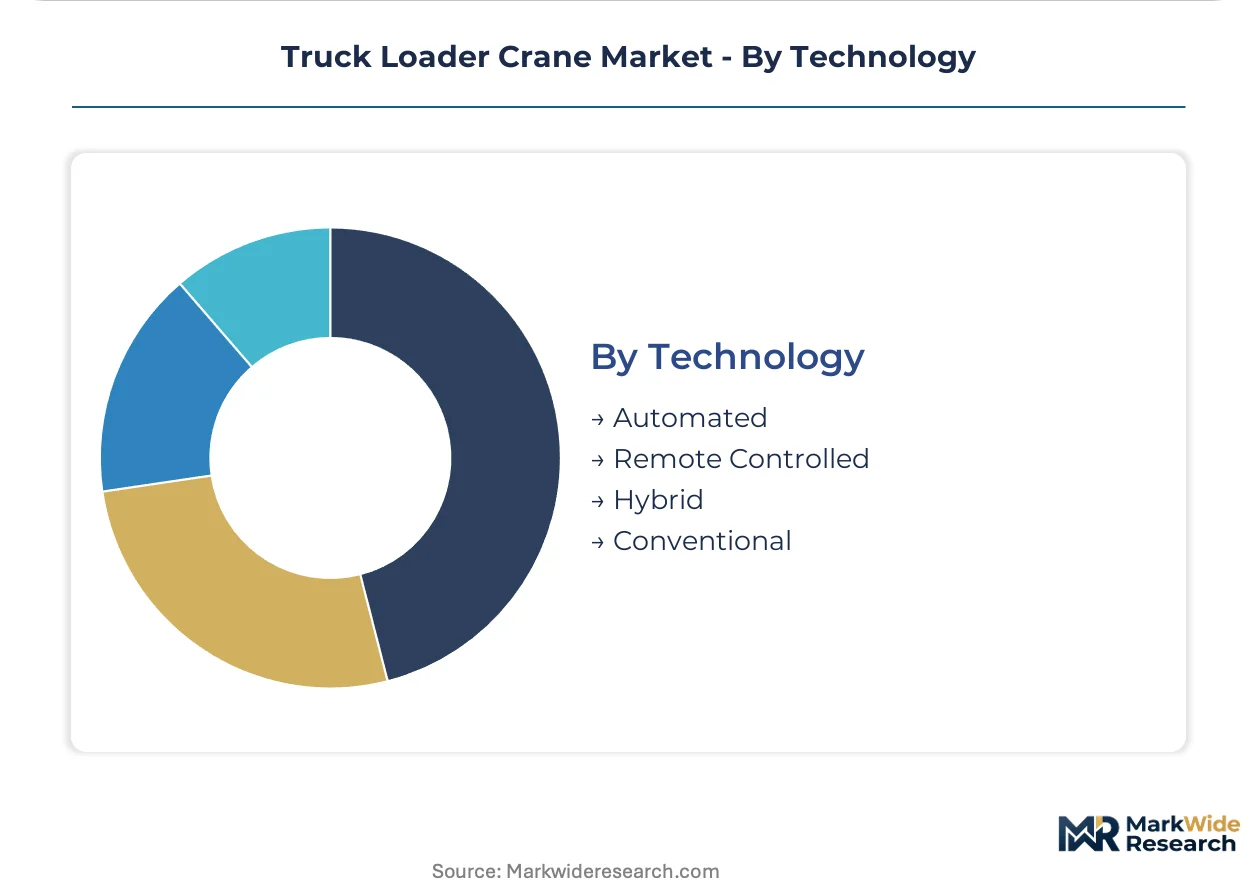
Technology:
Maturity gradients separate conventional operator-controlled systems from precision automation architectures.
- Remote Controlled:Radio-frequency and fiber-optic operator separation enables hazardous material handling at standoff distances. UK and French nuclear facility operators mandate these systems for radiological waste container manipulation.
- Automated:Pre-programmed boom positioning and load sequencing reduce cycle times in repetitive logistics applications. Port terminal operators in Rotterdam deploy these configurations for container stuffing operations.
- Hybrid:Electro-hydraulic actuation combines servo-electric valve control with conventional fluid power for millimeter-precision positioning in the 20-50 ton segment.
- Conventional:Direct operator control through manual levers persists in cost-sensitive markets with limited technical workforce availability.
Conventional systems hold installed capacity. Remote controlled configurations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal fleet operators and defense procurement authorities concentrate demand across industrialized economies with aging infrastructure replacement cycles. Equipment lessors with standardized telematics platforms now control specification authority in fragmented contractor markets. Steel supply integration and emissions compliance timelines differentiate regional competitive positioning.
Germany
KBA Stage V enforcement redirects municipal capital toward electric-hybrid configurations in Stuttgart and Hamburg fleet renewals. The EU Machinery Directive mandates load-safety interlocks that extend certification timelines for non-European entrants. Duisburg's high-tensile steel production clusters reduce input cost volatility for boom manufacturers serving Rhine-Alpine logistics corridors.
China
MIIT certification requirements for construction machinery exports now mandate cellular connectivity modules as standard equipment rather than options. Xuzhou's equipment manufacturing hub anchors captive production of high-tensile boom steel for domestic urbanization programs. GB standards govern quality benchmarks for Belt and Road export eligibility to emerging markets.
United States
OSHA operator training protocols and NHTSA weight distribution rules shape chassis-engineering decisions for self-loading freight operators. Cooperative purchasing agreements among municipal agencies aggregate demand across multiple jurisdictions, concentrating specification influence. United Rentals' proprietary telematics platforms lock in preferred supplier relationships across North American municipal procurement.
France
ANSM and nuclear facility operators mandate remote-controlled precision systems for radiological waste container manipulation in hazardous environments. CE marking requirements enforce stability monitoring across all European deployments of loader crane equipment. French defense contractors specify electro-hydraulic actuation for explosive ordnance disposal applications requiring millimeter-precision boom positioning.
India
CEA mandates for overhead line equipment installation favor truck-mounted cranes with rapid deployment booms for trackside railway electrification programs. BIS certification governs domestic manufacturing quality for construction equipment serving infrastructure modernization. Fragmented contractor markets drive telematics-enabled usage-based financing models that displace traditional equipment ownership.
Truck Loader Crane Market Vendor Landscape
Channel-controlling players compete with product-specialist players across procurement hierarchies that fragment specification authority. Equipment lessors with national scale concentrate fleet purchasing power through standardized connectivity mandates. Strategic archetypes separate hydraulic-system incumbents with established service ecosystems from electric-architecture entrants targeting urban emissions zones. Competitive moves center on captive steel supply integration and telematics platform deployment.
Within the European hydraulic-specialist tier, PALFINGER AG and Fassi Gru S.p.A. exemplify established service-network incumbents defending aftermarket revenue across aging installed bases. Among Asia-Pacific scale players, Sany Group Co., Ltd. anchors a position through upstream control over high-tensile boom steel production. Tadano Ltd occupies a position emphasizing precision load-moment control systems for defense and utility applications where operator safety mandates drive specification.
| Leading Market Players |
|---|
| Tadano Ltd |
| Sany Group Co. Ltd |
| Cargotec Corporation |
| Cormach S.R.L |
| PM Group S.r.l. |
| PALFINGER AG |
| Xuzhou Construction Machinery Group Co., Ltd. |
| EFFER S.r.l. |
| Fassi Gru S.p.A. |
| Others |
Supply Flow & Price Mechanics
High-tensile boom steel production concentrates in Xuzhou and Duisburg, anchoring margin pools with OEMs that command captive supply and exposing price-takers to volatile spot market exposure. This upstream concentration shapes downstream pricing power across hydraulic and electric architecture tiers.
Pricing Analysis
Cost-plus contracts with steel indexation dominate long-term municipal procurement in Germany and France. Three-tier pricing structure across premium, standard, and economy levels separates CE-certified precision systems from basic hydraulic configurations. Cost compression in the economy tier intensifies as Chinese manufacturers export through Belt and Road channels. Fleet operators in fragmented contractor markets exhibit highest price sensitivity; defense procurement authorities demonstrate lowest sensitivity due to safety mandates.
Supply Chain Analysis
High-grade structural steel feeds from integrated mills in China, Germany, and Japan. Precision valve and pump manufacturing draws from supplier clusters in Italy and Germany. Single-source vulnerability in electro-hydraulic servo components exposes OEMs to disruption risk. Distribution runs through national equipment lessors with standardized telematics protocols that lock in preferred supplier relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Powertrain architecture fragmentation creates niche opportunities as fleet operators split procurement across hydraulic, electric, and hybrid configurations. Electrification mandates in European urban centers and China's dual carbon goals accelerate specification divergence.
For Market Incumbents: Insulate aftermarket revenue through predictive maintenance platform deployment and captive parts distribution networks. Deepen service ecosystem lock-in to counter emerging electric entrants with direct-to-fleet sales models. Invest in Stage V compliance certification ahead of municipal renewal cycles.
For New Entrants and Emerging Players: Pursue white-space positioning in sub-35-ton electric configurations for zero-emission zone operators in Rotterdam and Copenhagen. Target railway electrification programs in India where rapid-deployment boom specifications remain undersupplied. Lead with usage-based financing partnerships to bypass entrenched lessor relationships.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with captive steel supply and established CE certification pathways. Long-term viability favors OEMs that bridge hydraulic service infrastructure with electric architecture development. Watch MIIT connectivity mandate compliance costs as an inflection indicator for Chinese market access profitability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Boom Steel | Xuzhou and Duisburg mills reduce input cost volatility for crane manufacturers. |
| Telematics Platform Deployment | United Rentals and Loxam protocols lock in preferred supplier relationships. |
| CE Certification Pre-Investment | EU Machinery Directive timelines extend launch cycles for non-European entrants. |
| Electric-Hybrid Configuration Launch | KBA Stage V enforcement redirects German municipal capital toward compliance. |
| Defense Contractor Partnership | NATO tactical vehicle programs specify remote-controlled precision systems. |
Methodological Framework
Desk research of customs trade data, OEM procurement disclosures, and regulatory filings preceded structured interviews with fleet procurement managers, aftermarket service directors, and municipal equipment specification officers. Primary fieldwork with defense logistics contractors and nuclear facility operators validated remote-control technology demand patterns. Secondary triangulation drew from KBA enforcement records, MIIT certification databases, and steel industry production reports. Bottom-up unit economics and top-down market sizing were reconciled across analysis frameworks.
Assumptions held fixed include Stage V compliance timelines, lithium-ion energy density limits, and CE certification procedural durations; variables included municipal fleet renewal rates and Belt and Road export intensity. Segmentation modeling spanned powertrain architecture, lifting capacity tier, control system sophistication, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and electrification penetration curves. Forecast inputs incorporated steel price index trajectories and urban emissions zone expansion schedules.
Macroeconomic conditions sit as an overlay; deviation in construction equipment capital expenditure cycles or municipal debt financing availability would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and technology cost reduction curves. Cross-checking against equipment lessor fleet deployment data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Europe Conveyor Belt Market
Material Handling Equipment
Hoist Controller Market
Material Handling Equipment
Mobile Crane Market
Material Handling Equipment
Gantry Crane Market
Material Handling Equipment
Pick and Carry (PNC) Crane Market
Material Handling Equipment
Pedestal Boom System Market
Material Handling Equipment
Selective Pallet Racking System Market
Material Handling Equipment
Wire Pulling and Tensioning Market
Material Handling Equipment
Construction Lifts Market
Material Handling Equipment
Froth Flotation Equipment Market
Material Handling Equipment
Gas Connectors and Gas Hoses Market
Material Handling Equipment
Electric Wire Rope Hoist Market
Material Handling Equipment
Sweep Depalletizers Market
Material Handling Equipment
Forklift Tire Market
Material Handling Equipment
Scraper Conveyor Market
Material Handling Equipment
Cut-To-Length Line Systems Market