
 Electric Wire Rope Hoist Market | 2026-2036
Electric Wire Rope Hoist Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Wire Rope Hoist Market Foresight
Industrial distributor networks across North America and Europe are reshaping how electric wire rope hoists reach end users, with authorized service dealers now controlling technical specification and aftermarket revenue streams. Columbus McKinnon Corporation leverages its vertically integrated manufacturing footprint to sustain pricing power in high-capacity segments. Konecranes anchors its position through crane-as-a-service contracts that embed hoist replacement within broader maintenance agreements. KITO Corporation dominates Asian supply channels with localized production that reduces lead times for standardized three-phase units.
An electric wire rope hoist is a motorized lifting device that uses a drum-and-wire-rope mechanism to raise, lower, and position loads, typically operating at lifting speeds between 2 and 16 meters per minute with duty classifications ranging from light intermittent to heavy continuous cycles per ISO 4301-1. Its primary purpose is to provide controlled vertical material handling in industrial environments where precision positioning and safety interlocks prevent uncommanded load movement. Three-phase configurations lead volume due to their suitability for continuous-duty manufacturing lines, while explosion-proof variants command premium positioning in oil, gas, and chemical processing where ignition protection is mandatory. Warehousing applications represent the fastest-growing end-user channel as e-commerce fulfillment centers deploy high-bay storage systems requiring synchronized hoist arrays.
OSHA 1910.179 standards in the United States and the EU Machinery Directive 2006/42/EC enforce periodic inspection intervals, load testing protocols, and documentation retention that directly determine product lifecycle economics and replacement demand. China's GB/T 3811 crane design standards and Japan's JIS B 8811 further fragment certification requirements, compelling manufacturers to maintain multiple compliance portfolios. Stakeholders must monitor evolving carbon-footprint disclosure rules under the EU CSRD, which will soon require embodied-emissions reporting for capital equipment procurement decisions.
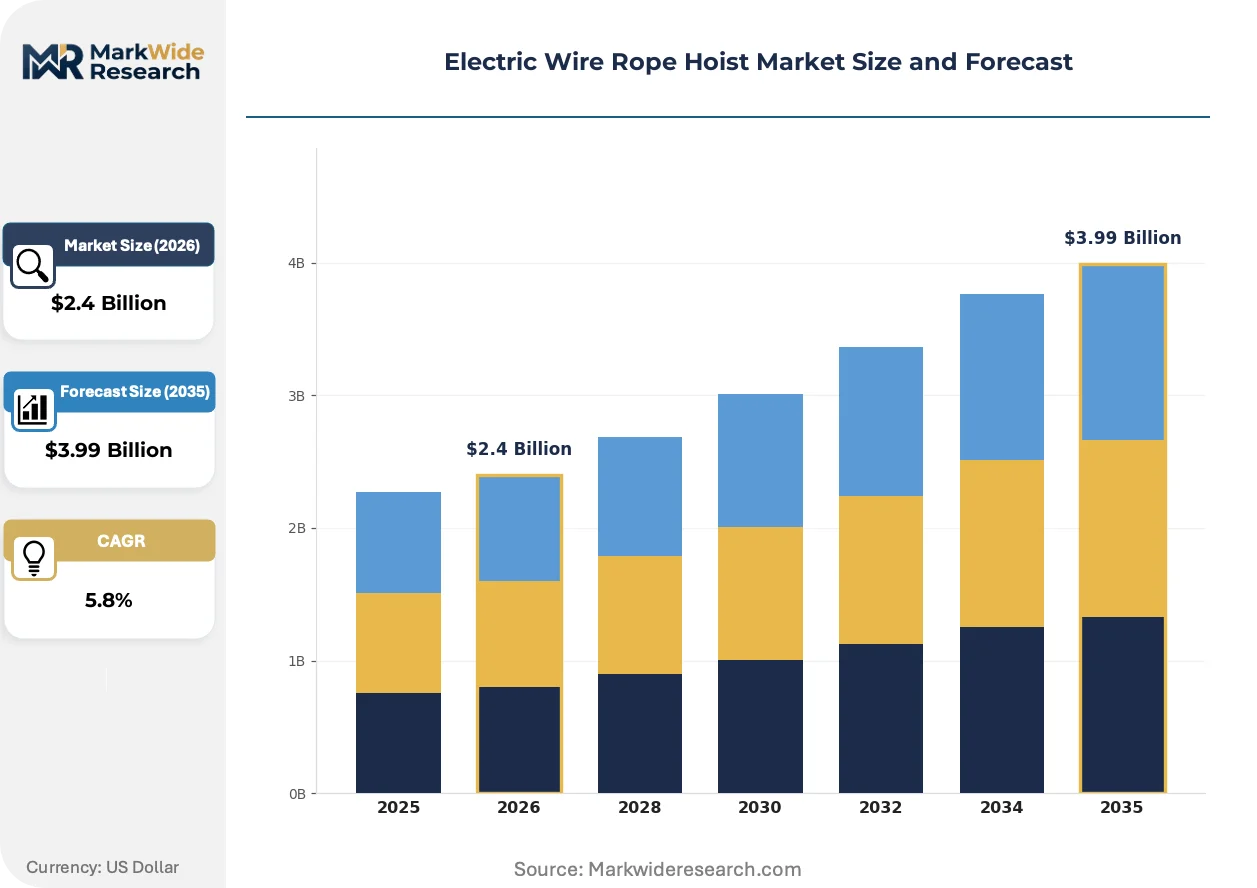
Market Dynamics
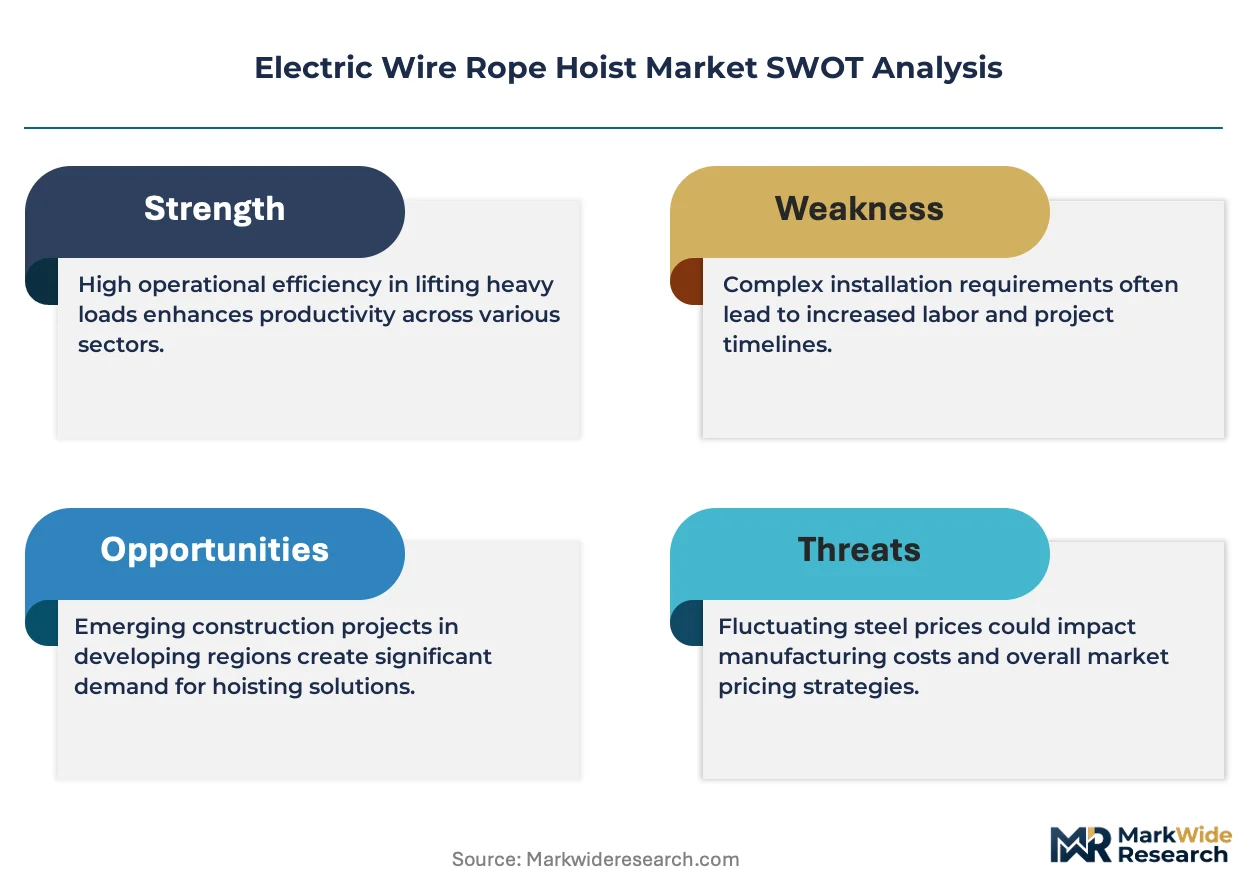
OSHA 1910.179 inspection mandates and EU Machinery Directive 2006/42/EC compliance deadlines are compressing replacement cycles for aging hoist fleets while simultaneously raising barriers for uncertified suppliers.
Growth Catalysts
- Port Automation:Container terminal expansion in China and Germany requires synchronized high-capacity hoist arrays for ship-to-shore crane retrofits.
- EU CSRD Disclosure Rules:Embodied-emissions reporting mandates for capital equipment procurement are favoring certified manufacturers with verified carbon footprints.
- Three-Phase Electrification:Continuous-duty manufacturing lines in automotive and steel production are phasing out pneumatic alternatives for precision positioning.
Market Restraints
- Steel Wire Rope Volatility:Specialty alloy cable prices fluctuate with nickel and chromium commodity markets, compressing margin predictability for mid-cap manufacturers.
- Chinese Supply Concentration:GB/T 3811-certified component sourcing clusters around Jiangsu and Zhejiang provinces, creating single-point vulnerability for European assemblers.
- Explosion-Proof Certification Burden:ATEX and IECEx testing protocols for oil and gas applications extend product development timelines by 8-14 months versus standard-duty units.
Strategic Opportunities
- Indian Infrastructure Buildout:Dedicated Freight Corridor and metro rail projects are generating first-time demand for ISO 4301-1 heavy-duty classifications in a historically manual-lifting market.
- Warehouse-as-a-Service Models:Third-party logistics operators are outsourcing entire hoist fleets to crane-as-a-service providers, shifting capital expenditure to recurring revenue streams.
- EU Green Deal Incentives:Carbon-border adjustment mechanisms and green public procurement rules are creating preferential tender access for low-emission hoist systems.
Industry Challenges
- Certified Inspector Shortage:OSHA-qualified crane inspectors and EU-notified body assessors are aging out faster than training programs replace them, extending compliance backlogs.
- Legacy System Integration:Brownfield manufacturing facilities require custom adapter kits to interface modern variable-frequency drives with 1980s-era pendant control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Wire Rope Hoist Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Phase, Three Phase, Explosion Proof, Manual End User: Construction, Manufacturing, Shipping, Warehousing Load Capacity: 1 Ton, 5 Ton, 10 Ton, 15 Ton Technology: Electric, Pneumatic, Hydraulic, Chain |
| Companies Covered | Columbus McKinnon Corporation, Konecranes, ABUS Kransysteme GmbH, Demag Cranes & Components GmbH, KITO Corporation, Ingersoll Rand, Hitachi, Ltd., Harrington Hoists, Inc., Verlinde, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Wire Rope Hoist Market Shifts & Advancements
Variable-frequency drive technology and IoT-enabled condition monitoring are redefining performance benchmarks while regulatory disclosure requirements reshape competitive differentiation.
Regenerative braking systems with active front-end converters are capturing and returning descent energy to facility grids. Automotive stamping plants in Germany and the United States are retrofitting existing monorail systems with these drives to reduce peak demand charges. Mechanical drum brakes with wear-prone friction linings are rendering obsolete in facilities where continuous-duty cycles exceed 300 starts per hour.
EU CSRD carbon-footprint disclosure rules will require embodied-emissions documentation for all capital equipment procurement above defined thresholds by 2026. Manufacturers must now maintain third-party-verified lifecycle assessments from raw material extraction through end-of-life recycling. Explosion-proof hoist suppliers serving North Sea oil platforms and Rotterdam chemical clusters are investing in supply-chain traceability systems to meet these audit requirements.
Buyers are unbundling aftermarket service contracts from initial equipment procurement, selecting independent service organizations based on response-time guarantees rather than manufacturer affiliation. E-commerce fulfillment centers in the United States are driving this fragmentation by negotiating multi-vendor maintenance agreements covering heterogeneous hoist fleets. This shift compresses OEM service margins while elevating specialized regional repair shops with ISO 9001 quality certifications.
Electric Wire Rope Hoist Market Segmentation
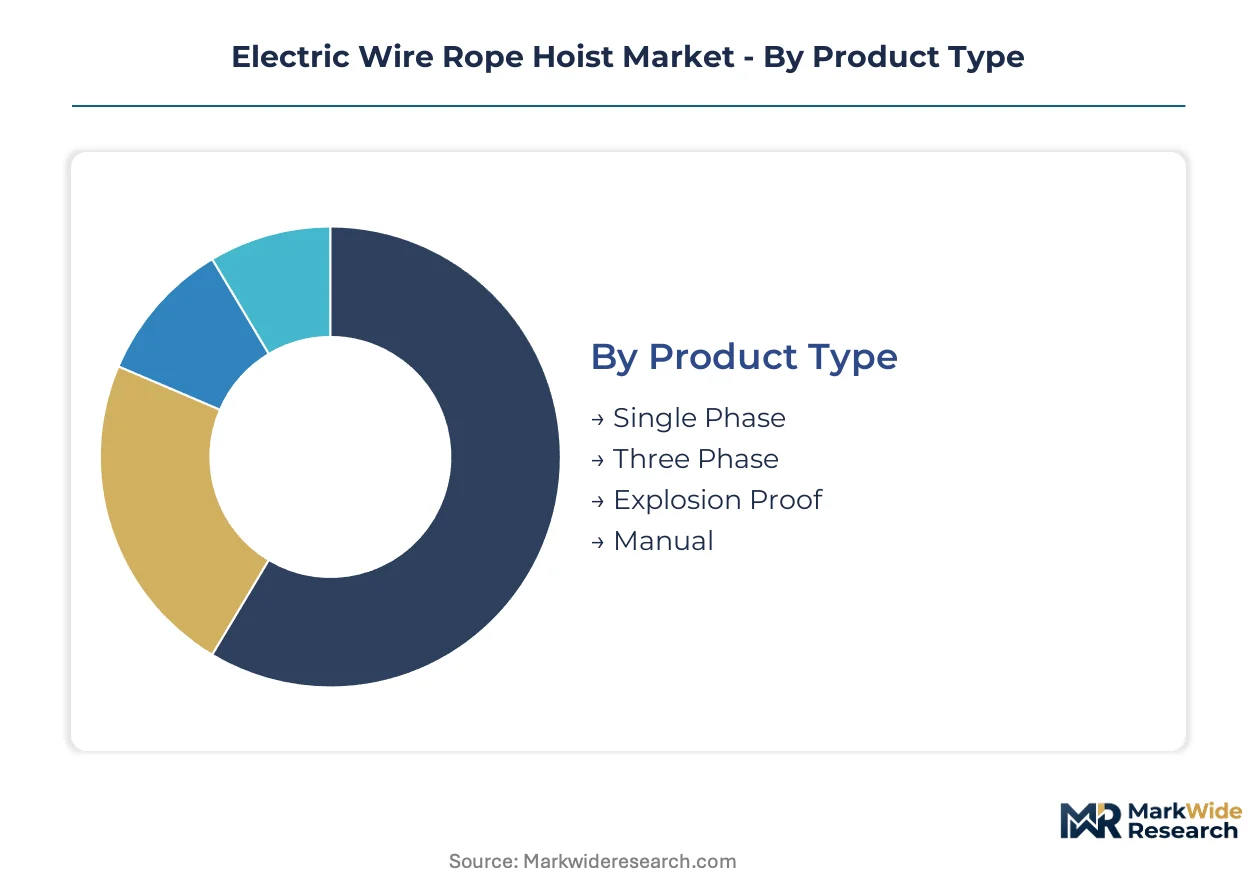
Segmentation in the electric wire rope hoist market reveals how service intensity, duty cycles, and regulatory exposure vary dramatically across power configurations and end-use environments. Understanding these divisions allows manufacturers to align production capacity with replacement-cycle timing and aftermarket revenue potential.
Product Type:
After-sales service intensity varies sharply across power configurations, with continuous-duty units demanding predictive maintenance contracts and intermittent-duty models relying on break-fix arrangements.
- Three Phase:These continuous-duty units operate on industrial three-phase power supplies rated for 380-480V, enabling sustained lifting cycles without thermal derating. Automotive stamping plants in Germany and steel mills in the United States specify these for synchronized production lines where downtime costs exceed $50,000 per hour. Predictive maintenance contracts with vibration monitoring and oil analysis generate recurring revenue streams that often exceed initial equipment margins.
- Explosion Proof:Encapsulated motors and sealed enclosures prevent ignition in hazardous atmospheres classified under ATEX Zone 1 and NEC Class I Division 1 standards. North Sea oil platforms and Rotterdam chemical clusters mandate these for hydrocarbon processing environments where standard motors would trigger catastrophic ignition. Extended certification timelines of 8-14 months create order backlogs that protect pricing power for qualified suppliers.
- Single Phase:Residential and light commercial installations in the United States rely on 230V single-phase supplies for intermittent lifting tasks under 2 tons.
- Manual:Hand-chain operation serves backup and emergency lifting scenarios where power failure contingencies are mandatory per OSHA 1910.179.
By volume, Three Phase leads. By growth pace, Explosion Proof is ahead.
End User:
Cost tier stratification separates capital-intensive infrastructure projects from operational-expenditure-driven logistics operations with divergent procurement authority structures.
- Warehousing:E-commerce fulfillment centers deploy synchronized hoist arrays for high-bay storage systems exceeding 12 meters in lift height. Amazon and Alibaba distribution hubs in the United States and China specify variable-frequency drive compatibility for precise positioning of mixed-SKU pallets. Third-party logistics operators are outsourcing entire fleets to crane-as-a-service providers, shifting capital expenditure to recurring revenue models.
- Construction:Infrastructure modernization across the Dedicated Freight Corridor in India and metro rail expansion in Saudi Arabia is generating first-time demand for ISO 4301-1 heavy-duty classifications. Tower crane integration requires custom drum configurations and anti-two-block systems that extend engineering lead times.
- Manufacturing:Automotive and heavy machinery production lines in Japan and Germany specify duty classifications matching continuous-cycle operations.
- Shipping:Container terminal automation in China and Germany demands ship-to-shore crane retrofits with synchronized high-capacity arrays.
By installed base, Construction dominates. By expansion trajectory, Warehousing is climbing the fastest.
Load Capacity:
Volume concentration in mid-range capacities reflects the dominance of general manufacturing and commercial construction, while extreme ratings serve specialized heavy-lifting niches with premium pricing.
- 5 Ton:This capacity bracket captures the broadest cross-section of industrial applications from machine shop maintenance to light assembly operations. General manufacturing facilities in the United States and Germany standardize on this rating for overhead crane retrofits, creating replacement-cycle predictability. Component commonality with 10-ton frames reduces inventory carrying costs for distributors.
- 10 Ton:Steel service centers and automotive press shops require this rating for die handling and coil positioning where single-lift efficiency outweighs capital cost sensitivity. German automotive stamping plants specify regenerative braking compatibility to reduce peak demand charges from frequent acceleration cycles.
- 1 Ton:Light assembly and maintenance bays in Japan and South Korea specify these for precision component handling.
- 15 Ton:Heavy infrastructure and shipyard applications in China and the United States demand this extreme rating for specialized project lifting.
By shipment volume, 5 Ton leads. By margin expansion, 10 Ton is gaining share fastest.
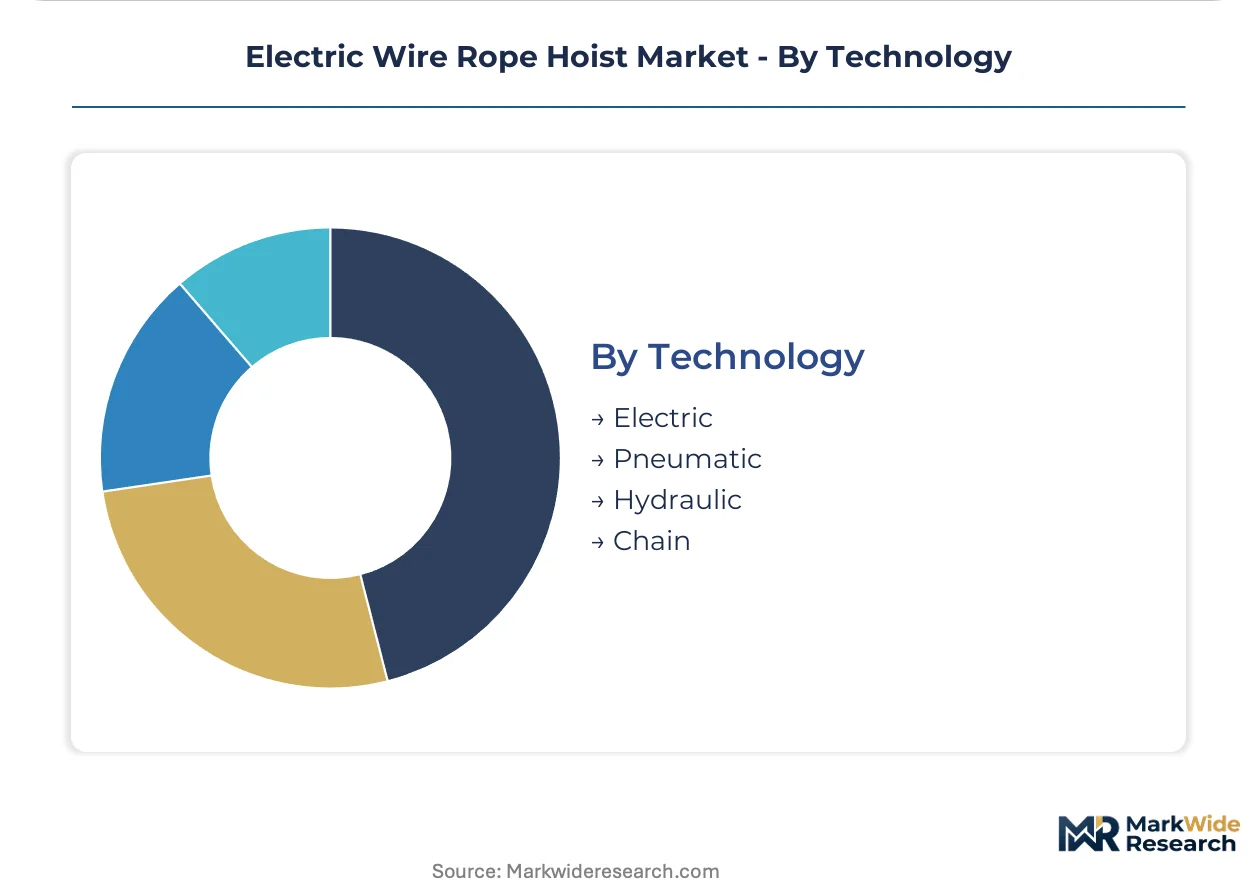
Technology:
Customer type bifurcation separates industrial facilities with three-phase infrastructure from legacy operations maintaining pneumatic and hydraulic systems for specific duty requirements.
- Electric:Variable-frequency drive integration enables precise speed control and regenerative energy recovery that pneumatic systems cannot match. German automotive plants and U.S. steel mills are retrofitting monorail systems with active front-end converters to capture descent energy and reduce facility peak demand charges. IoT-enabled condition monitoring with vibration sensors and thermal imaging is becoming standard specification for new procurement.
- Pneumatic:Explosion-risk environments without electrical certification budgets maintain these for spark-free operation in legacy chemical processing facilities.
- Hydraulic:Extreme precision requirements in aerospace assembly and nuclear component handling specify these for micro-positioning accuracy.
- Chain:Manual backup systems and low-headroom applications in maintenance bays retain this mechanical simplicity.
By installed base, Electric dominates. By replacement momentum, Electric is also expanding most quickly as pneumatic and hydraulic systems face phase-out in carbon-disclosure procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA 1910.179 inspection mandates anchor procurement patterns in the United States while EU Machinery Directive 2006/42/EC compliance deadlines compress replacement cycles across European industrial corridors. Demand concentrates in manufacturing belts where overhead lifting infrastructure serves continuous-duty production lines.
United States
Automotive stamping plants in Michigan and Ohio specify three-phase units for synchronized production lines where thermal derating is unacceptable. OSHA 1910.179 mandates periodic inspection intervals and load testing protocols that accelerate fleet replacement in aging industrial facilities. E-commerce fulfillment centers in Pennsylvania and California deploy high-bay storage systems requiring synchronized hoist arrays with variable-frequency drive compatibility.
Germany
Steel mills in the Ruhr region and automotive press shops in Baden-Württemberg specify regenerative braking systems to reduce peak demand charges from frequent acceleration cycles. EU Machinery Directive 2006/42/EC enforces documentation retention and conformity assessment procedures that favor established suppliers with notified body relationships. Port terminal expansion in Hamburg drives ship-to-shore crane retrofits requiring synchronized high-capacity arrays.
China
Container terminal automation in Shanghai and Shenzhen demands heavy-duty classifications for continuous cargo handling operations. GB/T 3811 crane design standards fragment certification requirements and compel manufacturers to maintain compliance portfolios distinct from Western norms. Jiangsu and Zhejiang provinces concentrate component sourcing clusters that supply both domestic assemblers and European integrators.
India
Dedicated Freight Corridor infrastructure projects and metro rail expansion in Mumbai and Delhi generate first-time demand for ISO 4301-1 heavy-duty classifications in a historically manual-lifting market. Central Electricity Authority regulations govern electrical safety in industrial installations and shape procurement specifications for three-phase configurations. Manufacturing investment corridors in Gujarat and Tamil Nadu attract hoist fleet deployment for greenfield automotive and electronics assembly plants.
Japan
Precision component handling in automotive and electronics factories around Nagoya and Osaka specifies single-phase and light-capacity units for assembly line integration. METI industrial standards and JIS B 8811 certification requirements maintain technical barriers that protect domestic supplier relationships. Steel production facilities in Chiba and Kawasaki maintain continuous-duty fleets requiring predictive maintenance contracts with vibration monitoring.
Electric Wire Rope Hoist Market Competitive Landscape
Vertically integrated conglomerates and specialized hoist fabricators split the market into distinct capability tiers. Consolidation pressure intensifies as crane-as-a-service contracts embed equipment procurement within long-term maintenance agreements. Three archetypes dominate: diversified industrial conglomerates with captive distribution networks, regional specialists with deep aftermarket penetration, and Asian volume manufacturers with localized cost structures. Competitive moves center on backward integration into wire rope and motor production, plus technology licensing partnerships for variable-frequency drive integration.
Within the diversified conglomerate tier, Columbus McKinnon Corporation and Konecranes occupy positions anchored by vertically integrated manufacturing footprints and service infrastructure density. KITO Corporation exemplifies the Asian volume archetype with production localization that reduces lead times for standardized three-phase units. Among European specialists, ABUS Kransysteme GmbH and Demag Cranes & Components GmbH represent engineering-intensive positioning focused on custom drum configurations and anti-two-block safety systems for tower crane integration.
| Leading Market Players |
|---|
| Columbus McKinnon Corporation |
| Konecranes |
| ABUS Kransysteme GmbH |
| Demag Cranes & Components GmbH |
| KITO Corporation |
| Ingersoll Rand |
| Hitachi, Ltd. |
| Harrington Hoists, Inc. |
| Verlinde |
| Others |
Supply & Pricing Matrix
Jiangsu and Zhejiang provinces anchor global component fabrication for electric wire rope hoists, concentrating motor winding and drum machining capacity that grants integrated assemblers leverage over spot-market buyers. This geographic clustering compresses procurement timelines for certified manufacturers while exposing tier-two suppliers to alloy price volatility that ripples through quoted equipment costs.
Pricing Analysis
Chinese-manufactured three-phase units trade at substantial discounts to German-engineered alternatives, with price spreads widening further for explosion-proof variants burdened by ATEX certification timelines. Three-tier pricing structure across premium, standard, and economy levels separates OEM-branded systems with predictive maintenance bundling from unmarked imports sold through distributor gray channels. Cost compression in the economy tier is intensifying because Jiangsu-based assemblers are absorbing steel wire rope volatility to maintain volume commitments. Third-party logistics operators negotiating crane-as-a-service contracts exhibit lowest price sensitivity, while independent maintenance shops purchasing break-fix spares drive hardest bargain on component list prices.
Supply Chain Analysis
Specialty alloy steel wire rope draws from mills in China, Japan, and South Korea, with nickel and chromium content tethering input costs to London Metal Exchange fluctuations. High-tensile drum forgings and sealed explosion-proof motor housings rest on concentrated foundry capacity in Jiangsu province and the Ruhr region. Single-source vulnerability pervades the ATEX-certified motor segment, where only two European suppliers qualify for North Sea platform procurement. Distribution runs through authorized service dealers in North America and Europe who control technical specification and capture aftermarket revenue streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Crane-as-a-service contracts are transforming capital equipment procurement into subscription economics, with interoperability between hoist fleets and warehouse management systems becoming the decisive platform lock-in mechanism.
For Market Incumbents: Build switching-cost moats through predictive maintenance platform integration that embeds vibration monitoring and oil analysis into multi-year service agreements. Backward integration into wire rope production secures margin protection against nickel commodity swings. Columbus McKinnon Corporation and Konecranes must defend against independent service organizations fragmenting aftermarket revenue by acquiring regional ISO 9001-certified repair shops. For New Entrants and Emerging Players: India's Dedicated Freight Corridor and metro rail buildout represents the most penetrable geography for first-time ISO 4301-1 heavy-duty classifications in a historically manual-lifting market. Warehouse-as-a-service models in third-party logistics offer white-space entry through outsourced fleet procurement rather than direct capital sales. Go-to-market positioning should emphasize rapid-response maintenance guarantees over equipment specification to bypass entrenched OEM relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among crane-as-a-service providers with embedded hoist replacement within long-term maintenance agreements. Five-to-ten year viability favors regional specialists with deep aftermarket penetration over pure-play manufacturers lacking service infrastructure. The signal to watch is GB/T 3811 certification adoption by European assemblers seeking to dual-source from Chinese component clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wire Rope Production | Captive supply of specialty alloy cables insulates margins from LME nickel volatility. |
| Predictive Maintenance Platform Deployment | Vibration monitoring contracts with automotive stamping plants generate recurring revenue exceeding equipment margins. |
| ATEX Certification Acceleration | Eight-month reduction in explosion-proof approval timelines unlocks North Sea oil platform procurement. |
| Crane-as-a-Service Contract Expansion | Third-party logistics outsourcing shifts capital expenditure to multi-year subscription revenue. |
| EU CSRD Supply-Chain Traceability Investment | Third-party-verified lifecycle assessments secure preferential tender access under green procurement rules. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs records, SEC filings, and notified body certification databases to establish baseline market sizing. Plant engineers, maintenance directors at automotive stamping facilities, aftermarket service heads, and OEM procurement teams provided operational data on replacement cycles and duty classifications. Bottom-up triangulation across equipment shipments and top-down validation against industrial capital expenditure surveys ensure dimensional consistency.
Forecast inputs span power configuration, load capacity tier, end-use environment, and regional regulatory cluster across the projection horizon. Segmentation modeling incorporates duty classification intensity, certification requirements, and crane-as-a-service penetration rates. CAGRs derive from fitted growth curves against historical replacement patterns and disclosed infrastructure project pipelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Jiangsu-based assemblers or accelerated EU carbon-border enforcement would shift outcomes. Cross-checking against customs wire rope import volumes and notified body ATEX certificate issuance is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Wire Pulling and Tensioning Market
Material Handling Equipment
Swivel Coupler Market
Material Handling Equipment
Hydraulic Cylinder Rod Market
Material Handling Equipment
High Pressure Grease Hose Market
Material Handling Equipment
Chain-Driven Roller Conveyors Market
Material Handling Equipment
Selective Pallet Racking System Market
Material Handling Equipment
High Pressure Grinding Rollers Market
Material Handling Equipment
Hoist Controller Market
Material Handling Equipment
Global Cargo Handling Equipment Market
Material Handling Equipment
Resistance Welding Products Market
Material Handling Equipment
Air Hoist Market
Material Handling Equipment
Bulk Material Handling System Market
Material Handling Equipment
Tree Milling Machine Market
Material Handling Equipment
Hydraulic Hose and Fittings Market
Material Handling Equipment
GCC Conveyor Belt Market
Material Handling Equipment
Portable Loading Ramps Market