
 Gas Connectors and Gas Hoses Market | 2026-2036
Gas Connectors and Gas Hoses Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Connectors and Gas Hoses Market Foresight
ISO 10380 certification for corrugated metallic hose assemblies is unwinding the competitive landscape, forcing smaller fabricators to invest in burst-testing and cyclic-fatigue validation or exit the supply chain. Parker Hannifin leverages its captive metallurgy and crimping technology to sustain premium positioning across aerospace and petrochemical accounts. Dormont anchors the North American foodservice segment with brass-connector assemblies certified for commercial kitchen gas appliance hookups. Swagelok dominates high-purity gas delivery in semiconductor fabs, where helium and specialty-gas integrity tolerances exclude commodity suppliers.
Gas connectors and gas hoses are pressure-rated conduits—typically corrugated stainless steel, reinforced elastomer, or fluoropolymer-composite constructions—engineered to transmit fuel gases, process gases, or cryogenic media between fixed infrastructure and movable or vibrating equipment. Their primary purpose is to maintain seal integrity across thermal cycling, mechanical flexure, and pressure pulsation while accommodating installation misalignment in industrial, commercial, and residential energy systems. Flexible hoses lead product-type revenue due to retrofit compatibility and vibration-dampening performance in aging industrial plants, whereas rigid stainless steel tubes capture margin in high-pressure hydrogen refueling skids where permeation resistance is critical. On the material front, neoprene and polyurethane compete for mid-pressure natural-gas distribution, but Teflon-lined assemblies are the fastest-growing category as chemical processors specify them for corrosive sulfur-compound streams.
FDA regulations governing food-contact materials and gas-path cleanliness directly shape connector specifications for food processing equipment, while EPA methane-emission rules and OSHA process-safety mandates tighten inspection intervals and replacement schedules across oilfield and manufacturing installations. In Europe, the EU Green Deal's hydrogen-readiness requirements and CE marking under the Pressure Equipment Directive are redrawing product-test protocols for gas distribution systems. Stakeholders must monitor how hydrogen-embrittlement testing standards evolve, as the shift from natural gas to hydrogen-dense blends will disqualify legacy connector alloys and reward suppliers with validated high-pressure hydrogen portfolios.
Market Dynamics
ISO 10380 certification mandates for corrugated metallic hose assemblies are compressing the supplier base by disqualifying fabricators lacking burst-testing and cyclic-fatigue validation infrastructure. This regulatory tightening is redistributing volume toward metallurgy-capable incumbents while forcing exit or consolidation among regional commodity producers.
Growth Catalysts
- Hydrogen blending infrastructure:Germany's scaling of hydrogen-dense gas distribution networks is expanding demand for high-pressure-rated connector assemblies with validated embrittlement resistance.
- EU Green Deal hydrogen-readiness:CE marking requirements under the Pressure Equipment Directive are accelerating replacement cycles in legacy natural-gas systems across industrial installations.
- Biomethane injection:Agricultural and wastewater treatment facilities in Denmark and the Netherlands are deploying sulfur-resistant Teflon-lined hoses to handle corrosive biogas streams.
Market Restraints
- Nickel alloy cost volatility:Price swings in 316L and 321 stainless steel feedstocks compress margin predictability for corrugated hose fabricators serving mid-pressure segments.
- Supplier concentration in aerospace-grade metallurgy:Captive refining and crimping capabilities cluster among vertically integrated North American and German producers, limiting second-source options.
- Legacy brass connector substitution:Residential and light commercial installations continue specifying lower-cost brass assemblies despite stainless steel's superior fatigue life.
Strategic Opportunities
- Underpenetrated hydrogen refueling skids:South Korea's expanding H2 mobility corridor presents white space for permeation-resistant rigid tube suppliers with validated high-pressure portfolios.
- Semiconductor fab expansion:Helium and specialty-gas integrity requirements in Arizona and Texas fabs are creating premium positioning for electropolished VCR-compatible connector systems.
- Remote monitoring integration:IoT-enabled pressure and leak-detection sensors bundled with hose assemblies are opening recurring-revenue service models in oilfield and chemical processing accounts.
Industry Challenges
- Hydrogen-embrittlement testing capacity:Validating 700-bar hydrogen compatibility requires capital-intensive autoclave infrastructure that few third-party labs currently operate.
- Cross-standard harmonization:Misalignment between ISO 10380, ASME B31.3, and country-specific pressure equipment directives extends certification timelines for multi-jurisdiction suppliers.
- Skilled orbital welding technician scarcity:High-purity gas delivery systems in semiconductor and pharmaceutical end-uses depend on certified welders whose training pipelines lag demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Connectors and Gas Hoses Market |
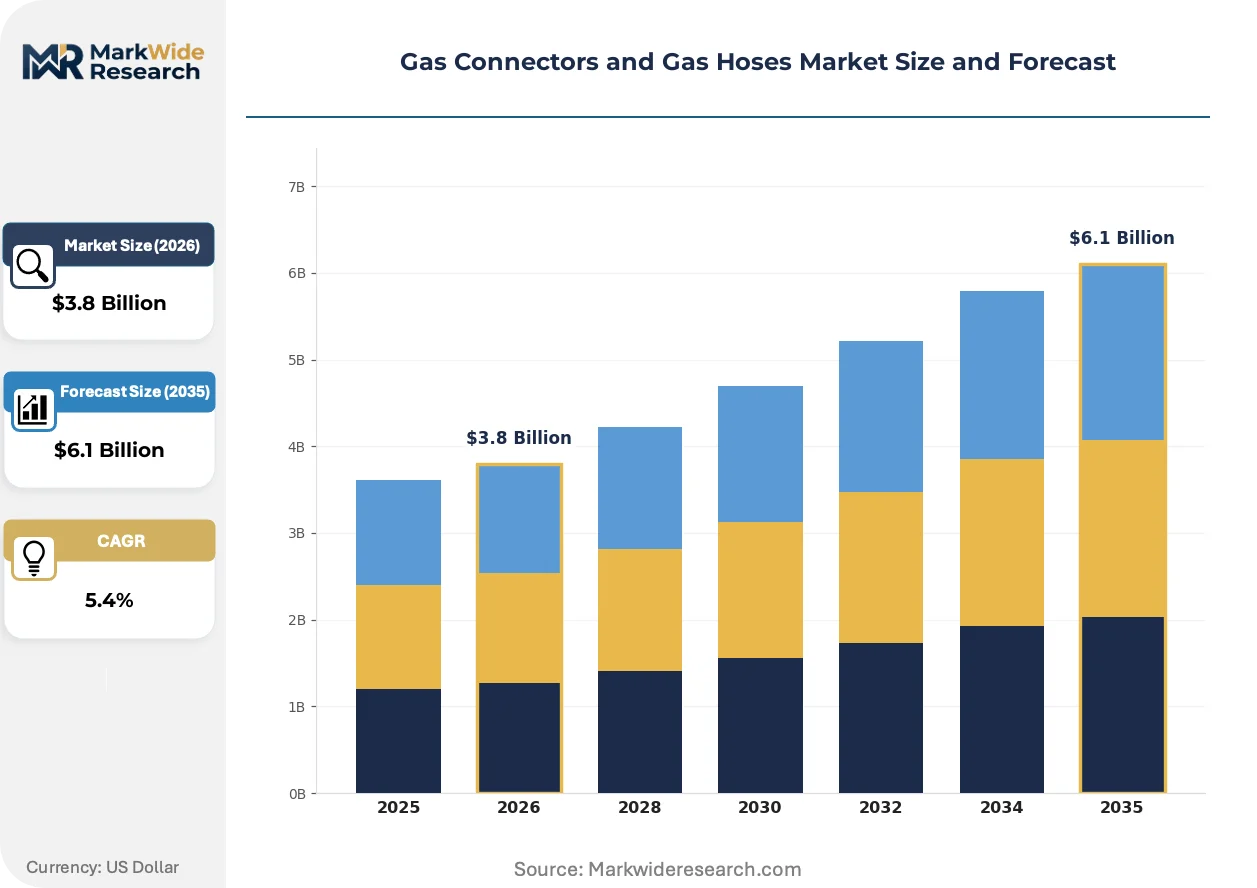
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Hoses, Rigid Connectors, Composite Tubing, Stainless Steel Tubes, PVC Hoses Material: Natural Rubber, Neoprene, Polyurethane, Teflon, Silicone, Brass Application: Industrial Manufacturing, Food Processing Equipment, Gas Distribution Systems, HVAC Systems, Oilfield Equipment End User: Manufacturing Plants, Food & Beverage Producers, Construction Contractors, Oil & Gas Operators, Maintenance Service Providers |
| Companies Covered | Watts, Dormont, Parker Hannifin, OMEGA Flex, Titeflex, Swagelok, Gastite, GCE Group, Cavagna Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Connectors and Gas Hoses Market Shifts & Advancements
Corrugated hose construction is converging with embedded sensor architectures and advanced metallurgy to address hydrogen-service validation demands. These developments are compressing traditional equipment procurement cycles while elevating technical barriers to supply-chain entry.
Multi-layer fluoropolymer-composite barrier technology is miniaturizing. This construction integrates helical stainless-steel armor with extruded PTFE liners to block hydrogen permeation at 700-bar operating pressures. Semiconductor equipment OEMs in Taiwan and South Korea are specifying these assemblies for sub-fab gas distribution retrofits. The technology is miniaturizing footprint requirements in high-density tool hookups while displacing rigid tube runs that complicate vibration isolation.
EPA methane-emission monitoring rules under the Clean Air Act are tightening inspection intervals and replacement schedules across oilfield gathering systems and processing plants. Operators must now document connector integrity across thermal cycling histories or face escalating penalty structures. Onshore shale basins in Texas and North Dakota are responding by consolidating procurement with suppliers offering bundled inspection and replacement service contracts.
Certification-driven specification preferences are consolidating buyer decision criteria around validated hydrogen portfolios rather than legacy natural-gas ratings alone. European industrial gas distributors are disqualifying suppliers lacking documented 100% hydrogen compatibility testing. This behavioral shift compresses vendor shortlists in Germany and the Netherlands while elevating contract values for qualified incumbents with established embrittlement validation protocols.
Gas Connectors and Gas Hoses Market Segmentation
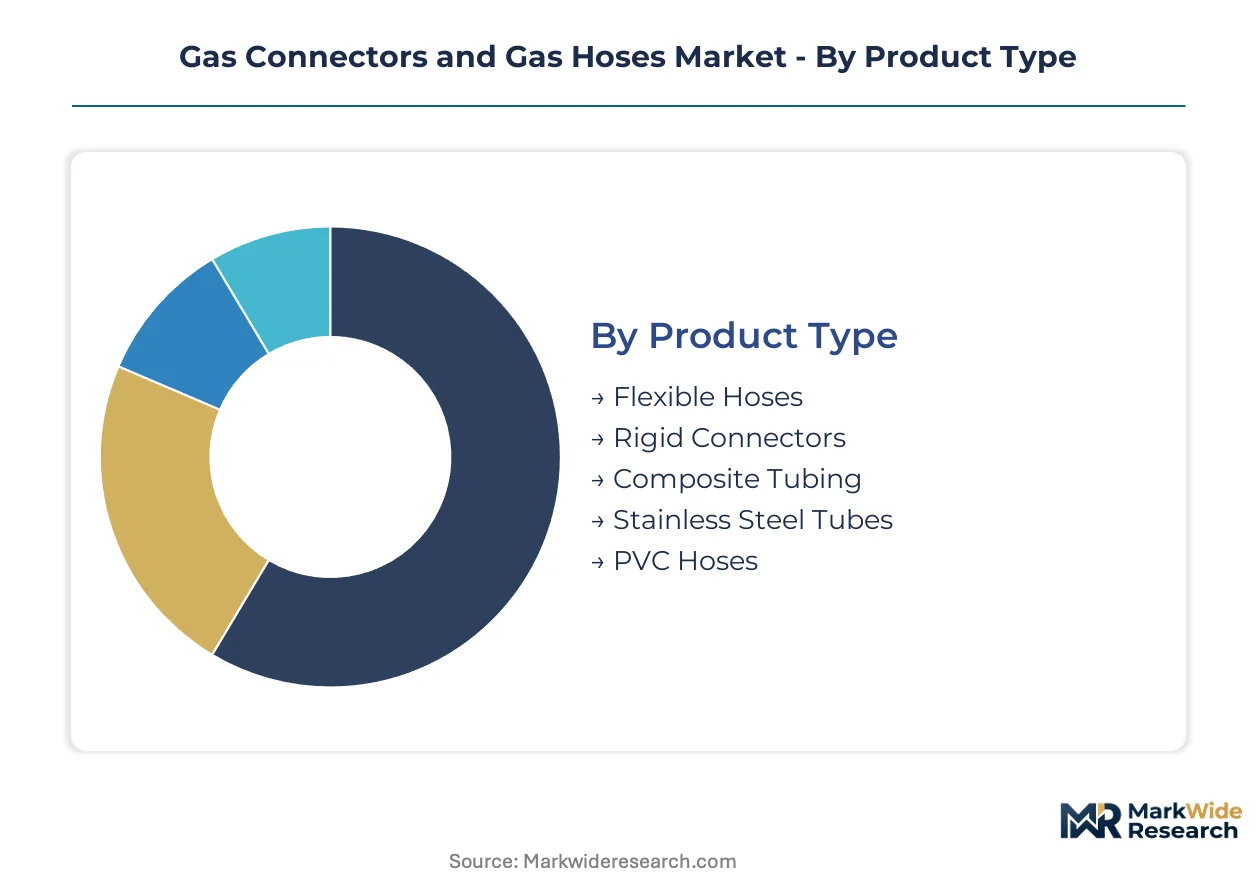
Gas connectors and gas hoses serve radically different performance regimes across pressure ratings, chemical compatibility, and flexure demands. Segmentation clarity determines specification accuracy for procurement teams navigating ISO 10380 certification tiers and hydrogen-service validation requirements.
Product Type:
ISO 10380 burst-testing mandates and pressure equipment directives split procurement between validated corrugated assemblies and commodity rigid runs.
- Flexible Hoses:Corrugated stainless-steel or reinforced elastomer constructions accommodate vibration dampening and installation misalignment in aging industrial plants. Demand concentrates in Germany's hydrogen-blending distribution retrofits where thermal cycling tolerance disqualifies rigid alternatives.
- Rigid Connectors:Seamless stainless-steel tube assemblies deliver zero-permeation performance for high-pressure hydrogen refueling skids. South Korea's H2 mobility corridor expansion is driving specification of 700-bar-rated rigid tube portfolios with documented embrittlement resistance.
- Composite Tubing:Multi-layer fluoropolymer-barrier constructions integrate helical armor with PTFE liners for sub-fab semiconductor gas distribution.
- Stainless Steel Tubes:Electropolished 316L assemblies serve high-purity helium delivery in Arizona and Texas semiconductor fabs.
- PVC Hoses:Reinforced thermoplastic constructions dominate residential natural-gas appliance hookups where cost sensitivity overrides fatigue-life requirements.
Flexible hoses handle the majority of throughput; rigid connectors are the fastest mover on share.
Material:
Cost tiers stratify from commodity elastomers through nickel-alloy metallurgy, with hydrogen-embrittlement validation creating a premium tier that captures disproportionate margin.
- Natural Rubber:Reinforced gum-rubber hoses serve low-pressure residential and commercial natural-gas distribution with limited chemical resistance profiles.
- Neoprene:Chloroprene-polymer constructions balance oil resistance and flexure life for mid-pressure industrial manufacturing applications.
- Polyurethane:Thermoplastic elastomer tubes deliver abrasion resistance and kink recovery for construction-site temporary gas distribution.
- Teflon:PTFE-lined assemblies with stainless-steel braid armor block hydrogen permeation and resist corrosive sulfur compounds in biomethane injection streams. Danish agricultural biogas facilities specify these for digester-to-grid connections handling hydrogen sulfide-laden output.
- Silicone:Platinum-cured elastomer hoses maintain flexibility across cryogenic-to-elevated temperature ranges in pharmaceutical process gas delivery.
- Brass:Lead-free brass connector assemblies anchor North American foodservice equipment hookups where Dormont-certified commercial kitchen specifications dominate procurement.
Brass captures the highest unit volumes; Teflon-lined constructions are expanding most quickly on specification preference.
Application:
End-use severity determines pressure rating, material specification, and replacement interval requirements across regulatory jurisdictions.
- Industrial Manufacturing:Corrugated metallic hose assemblies transmit process gases between fixed headers and vibrating compressors, pumps, and heat exchangers. EPA methane-emission monitoring rules are tightening inspection intervals across Texas and North Dakota shale basins.
- Food Processing Equipment:FDA gas-path cleanliness mandates specify electropolished stainless or platinum-cured silicone for product-contact zones.
- Gas Distribution Systems:High-pressure-rated connector assemblies with validated hydrogen compatibility serve Germany's hydrogen-dense network scaling under EU Green Deal hydrogen-readiness requirements.
- HVAC Systems:Refrigerant and fuel-gas connectors for commercial building climate systems face F-Gas Regulation phase-down pressures in Europe.
- Oilfield Equipment:Sour-gas-resistant hose assemblies handle hydrogen sulfide-laden production streams in gathering systems and processing plants.
Industrial manufacturing commands the largest installed base; gas distribution systems are gaining share fastest on infrastructure transition spending.
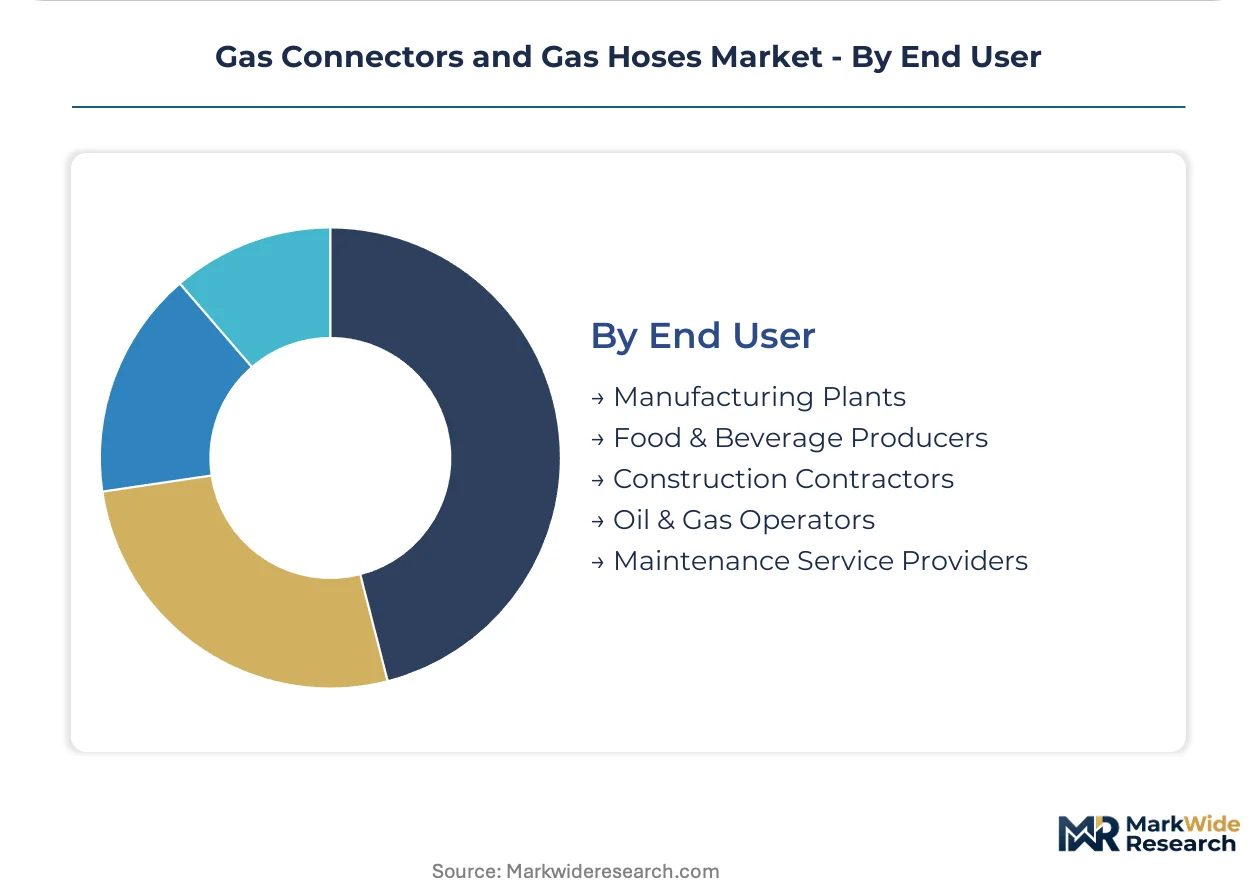
End User:
Procurement sophistication varies from specification-driven OEMs to price-sensitive maintenance contractors, fragmenting vendor engagement models.
- Manufacturing Plants:Process engineers specify validated connector portfolios with documented cyclic-fatigue and burst-test histories.
- Food & Beverage Producers:Quality teams enforce FDA material compliance and gas-path cleanliness protocols for product-contact equipment.
- Construction Contractors:Temporary gas distribution for heating and equipment fueling prioritizes rental-compatible flexible hose durability.
- Oil & Gas Operators:Asset integrity teams bundle connector procurement with inspection and replacement service contracts to satisfy EPA methane-emission documentation requirements.
- Maintenance Service Providers:Independent service contractors source commodity brass and reinforced elastomer assemblies for residential and light commercial repair cycles.
Manufacturing plants represent the deepest specification engagement; oil and gas operators are climbing the fastest on bundled service contract adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's hydrogen-readiness mandates under the EU Green Deal are redrawing procurement specifications across industrial gas infrastructure. National regulators in Denmark, the Netherlands, and South Korea are accelerating connector replacement cycles through tightened pressure equipment directives and emission monitoring rules.
United States
EPA methane-emission monitoring rules under the Clean Air Act are tightening inspection intervals across Texas shale basins and North Dakota oilfields. OSHA process-safety mandates enforce documented thermal cycling histories for connector integrity. Houston and Midland energy corridors are consolidating procurement with suppliers offering bundled inspection and replacement service contracts.
Germany
Hydrogen-dense gas distribution network scaling is expanding demand for high-pressure-rated connector assemblies with validated embrittlement resistance. CE marking requirements under the Pressure Equipment Directive are disqualifying legacy natural-gas-rated suppliers. Industrial clusters in North Rhine-Westphalia and Bavaria are specifying 100% hydrogen compatibility testing for new infrastructure hookups.
China
Dual carbon goals and industrial gas infrastructure expansion are concentrating demand in Yangtze River Delta manufacturing hubs. GB standards for pressure equipment are tightening certification requirements for corrugated metallic hose assemblies. Shanghai and Jiangsu province chemical processors are specifying Teflon-lined constructions for corrosive sulfur-compound streams.
South Korea
H2 mobility corridor expansion is creating specification pull for 700-bar-rated rigid tube portfolios with documented embrittlement resistance. MFDS-equivalent pressure equipment regulations are accelerating validation timelines for hydrogen service. Ulsan and Gwangju industrial zones are deploying permeation-resistant assemblies in refueling skid installations.
Denmark
Agricultural biogas facility expansion is driving sulfur-resistant Teflon-lined hose deployment for digester-to-grid connections. National renewable energy integration targets are widening the addressable base for biomethane injection infrastructure. Jutland peninsula agricultural cooperatives are specifying PTFE-lined assemblies for hydrogen sulfide-laden output handling.
Gas Connectors and Gas Hoses Market Competitive Landscape
Player mix skews toward metallurgy-capable incumbents with captive crimping infrastructure and ISO 10380 validation capabilities. Regional commodity fabricators lacking burst-testing and cyclic-fatigue infrastructure face exit or consolidation pressure. Three archetypes dominate: vertically integrated North American and German producers with aerospace-grade metallurgy, specialized foodservice brass-connector suppliers, and high-purity gas delivery specialists serving semiconductor fabs. Competitive moves concentrate on backward integration into nickel alloy refining and strategic partnerships for hydrogen-embrittlement testing capacity.
Within the metallurgy-capable tier, Parker Hannifin and Swagelok occupy positions reflecting premium-tier specialization across divergent end-use vectors. Dormont anchors the foodservice equipment segment among North American commercial kitchen fabricators. These three names exemplify how validation depth and captive manufacturing capabilities stratify competitive positioning as hydrogen-service specifications compress vendor shortlists.
| Leading Market Players |
|---|
| Watts |
| Dormont |
| Parker Hannifin |
| OMEGA Flex |
| Titeflex |
| Swagelok |
| Gastite |
| GCE Group |
| Cavagna Group |
| Others |
Supply & Pricing Matrix
Twenty-to-thirty-day lead times for ISO 10380-certified corrugated hose assemblies concentrate procurement leverage among metallurgy-capable incumbents with captive crimping infrastructure, compressing margin recovery for fabricators lacking burst-testing validation capacity.
Pricing Analysis
Certification level (ISO 10380/CE marking/FDA-grade) creates the primary spread across pricing tiers, with hydrogen-embrittlement validated portfolios commanding premium positioning against commodity natural-gas-rated alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects validation depth, nickel alloy grade, and bundled after-sales service intensity. Cost compression in mid-pressure segments intensifies because nickel alloy feedstock volatility erodes predictability for corrugated hose fabricators. Residential maintenance contractors exhibit highest price sensitivity, specifying brass connectors despite inferior fatigue life, while semiconductor fabs demonstrate lowest sensitivity, prioritizing helium integrity tolerances over unit cost.
Supply Chain Analysis
Autoclave infrastructure scarcity for 700-bar hydrogen validation constitutes a critical chokepoint, constraining third-party testing capacity and elongating certification timelines for multi-jurisdiction suppliers. Manufacturing gravity centers on Germany, the United States, and China, with captive nickel alloy refining and orbital welding capabilities clustering among vertically integrated North American and German producers. Feedstock dependencies draw from 316L and 321 stainless steel, PTFE resin, and lead-free brass billet. Single-source vulnerability in aerospace-grade metallurgy limits second-source options for high-pressure hydrogen skids. Distribution runs through authorized distributor networks for validated assemblies, with direct OEM engagement dominating semiconductor and refueling skid accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from Teflon-lined composite tubing displacing rigid stainless runs in sub-fab semiconductor retrofits, requiring portfolio adaptation to defend positioning.
For Market Incumbents: Consolidate hydrogen-embrittlement testing capacity through backward integration into autoclave infrastructure or exclusive partnerships with validated third-party labs, neutralizing the threat from regional commodity fabricators achieving ISO 10380 compliance. Deepen captive nickel alloy refining to insulate margin from 316L feedstock volatility. Prioritize certification investment in 100% hydrogen compatibility to disqualify legacy natural-gas-rated competitors from Germany's distribution network scaling. For New Entrants and Emerging Players: Differentiate on IoT-enabled sensor integration bundled with hose assemblies, targeting oilfield operators in Texas shale basins facing EPA methane-emission documentation mandates. Penetrate South Korea's H2 mobility corridor through 700-bar rigid tube portfolios with documented embrittlement resistance, where permeation-resistant specifications exclude incumbent commodity suppliers. Pursue white-space in Danish agricultural biogas facilities specifying sulfur-resistant PTFE-lined constructions for digester-to-grid connections. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because hydrogen-readiness mandates under EU Green Deal and country-specific pressure equipment directives are compressing vendor shortlists toward validated portfolios. Target acquisition profiles should emphasize metallurgy-capable fabricators with ISO 10380 infrastructure and documented high-pressure hydrogen testing histories. Monitor hydrogen-embrittlement standard evolution as the inflection signal—accelerated 700-bar validation requirements would disqualify substantial legacy capacity and revalue qualified incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Compatibility Certification | CE marking under Pressure Equipment Directive disqualifies legacy natural-gas-rated suppliers from EU infrastructure procurement. |
| Backward Integration into Nickel Alloy Refining | Captive 316L and 321 stainless supply insulates margin from feedstock volatility in corrugated hose fabrication. |
| IoT Sensor Bundling | EPA methane-emission rules in Texas and North Dakota create recurring-revenue service models for leak-detection integration. |
| Autoclave Testing Partnership | 700-bar hydrogen validation capacity scarcity limits third-party certification options for multi-jurisdiction suppliers. |
| Semiconductor Fab Direct Engagement | Arizona and Texas helium delivery specifications exclude commodity suppliers from electropolished VCR-compatible connector procurement. |
Research Methodology
The analysis maps flexible hose, rigid connector, composite tubing, and stainless steel tube sub-sectors, each validated through maintenance directors at manufacturing plants, procurement leads at oil and gas operators, quality teams at food and beverage producers, and asset integrity managers at chemical processors. Primary interview intelligence triangulates against customs and trade data, SEC 10-K filings from listed industrial components suppliers, pressure equipment directive regulatory filings, and hydrogen infrastructure project development databases. Bottom-up unit economics and top-down macroeconomic drivers converge through iterative reconciliation.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models product type, material grade tier, application severity, and end-user procurement sophistication dimensions. CAGRs derive from segment-level growth rate reconciliation with macro infrastructure spending trajectories. Hydrogen refueling skid deployment timelines and semiconductor fab construction pipelines constitute industry-specific forecast inputs.
Decision-makers should treat outputs as directional under base assumptions of sustained hydrogen infrastructure investment and regulatory tightening; material deviation in nickel alloy cost trajectories or standard harmonization timelines would warrant model refresh. Practitioners should keep alternative scenarios live as hydrogen-embrittlement testing capacity expansion and cross-standard alignment evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Roll Handling Machine Market
Material Handling Equipment
Elevator Ropes Market
Material Handling Equipment
Forklift Tire Market
Material Handling Equipment
Automatic Conveyor Market
Material Handling Equipment
Log Stackers Market
Material Handling Equipment
Asia-Pacific Forklift Truck Market
Material Handling Equipment
Hydraulic Hoist Market
Material Handling Equipment
Australia Forklift Market
Material Handling Equipment
Belt Scales Market
Material Handling Equipment
Automated Material Handling (AMH) Equipment Market
Material Handling Equipment
Can Racks Market
Material Handling Equipment
Wagon Tipplers Market
Material Handling Equipment
Global Telescopic Boom Forklift Truck Market
Material Handling Equipment
Global Large Conveyor Chain Market
Material Handling Equipment
Level Loader Market
Material Handling Equipment
Slag Handling Equipment Market