
 Loader Crane Market | 2026-2036
Loader Crane Market Size, Share, and Industry Trends Forecast 2026-2036
Loader Crane Market Outlook
The EU Green Deal is restructuring loader crane procurement across European municipal and commercial fleets by embedding CO2 performance criteria into public tender frameworks. Palfinger AG leverages its Austrian manufacturing base to sustain knuckle boom output for utility operators navigating these standards. Hiab AB anchors Nordic demand through electric-hybrid loader crane systems designed for forestry and urban logistics. XCMG Group competes on manufacturing scale, dominating volume shipments into Middle Eastern and African construction markets.
A loader crane is a hydraulically or electrically powered articulated lifting device mounted on commercial vehicles, typically offering load moment capacities from 1 to over 100 tonne-meters and controlled via remote or cabin-operated proportional valve systems. Its primary purpose is to enable self-loading and unloading of heavy materials at distributed worksites without dedicated handling equipment. Knuckle boom configurations lead European urban logistics due to their compact stowage and maneuverability in confined delivery zones, while telescopic boom designs command premium positioning in North American oilfield and utility sectors where reach extension outweighs folding efficiency. Electric technology represents the fastest-growing segment as lithium-ion powerpack integration enables zero-emission operation in European low-emission zones, though hydraulic systems retain margin dominance in heavy-lift marine and offshore applications where power density requirements exceed current battery capabilities.
Fleet operators in Germany face KBA vehicle approval requirements that now incorporate crane-mounted weight distribution and stability testing under amended UN ECE R29 cabin safety protocols. The EU Machinery Directive (2006/42/EC) mandates CE marking with conformity to EN 12999 standards for loader crane design, directly shaping product development cycles and market access timelines for non-European manufacturers. OSHA and FCC frameworks in the United States impose parallel but distinct operator certification and remote-control frequency allocation rules that fragment compliance pathways. Stakeholders must monitor how divergent electrification subsidy schemes across European national governments and U.S. state-level clean fleet programs reshape total cost of ownership calculations and regional procurement priorities.
Market Dynamics
Electrification mandates embedded in EU Green Deal procurement frameworks are compressing technology migration timelines for municipal and commercial fleet operators across European urban logistics corridors.
Growth Catalysts
- EU Green Deal tender criteria:CO2 performance benchmarks now govern public procurement of loader cranes for municipal infrastructure fleets in Germany and France, accelerating specification upgrades.
- Lithium-ion powerpack integration:Battery-electric systems enable zero-emission operation in European low-emission zones, opening access to restricted urban delivery corridors previously closed to diesel-hydraulic units.
- Rhine-Ruhr construction logistics:Concentrated demand from Germany's industrial corridor drives knuckle boom crane procurement for multi-drop distribution networks serving dense urban worksites.
Market Restraints
- Battery power density limitations:Lithium-ion systems cannot yet match hydraulic power density for heavy-lift marine and offshore applications exceeding 50 tonne-meters, preserving hydraulic dominance in these segments.
- CE marking compliance timelines:Non-European manufacturers face extended product development cycles to conform with EN 12999 standards and Machinery Directive 2006/42/EC requirements.
- Steel and aluminum input volatility:Boom fabrication costs fluctuate with commodity pricing, compressing margins for manufacturers without long-term supply agreements or in-house metallurgical processing.
Strategic Opportunities
- Nordic utility electrification:Sweden and Norway lead specification migration toward electric-hybrid systems for forestry and remote infrastructure maintenance, creating premium positioning for technology-forward suppliers.
- Remote-control frequency allocation:FCC framework modernization in the United States opens channel capacity for advanced teleoperation, enabling new service models in hazardous material handling.
- Aftermarket service digitization:Predictive maintenance platforms using IoT sensor arrays create recurring revenue streams and customer lock-in independent of new equipment sales cycles.
Industry Challenges
- UN ECE R29 cabin stability certification:Amended protocols require crane-mounted weight distribution testing that extends KBA vehicle approval timelines and complicates fleet retrofit programs.
- Electro-hydraulic control integration:Legacy fleet operators face technical complexity when retrofitting proportional valve systems with electric actuators, requiring specialized technician training and extended downtime.
- OSHA operator certification fragmentation:Divergent state-level requirements for remote-control operation create compliance overhead for national rental fleet operators seeking standardized training programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Loader Crane Market |
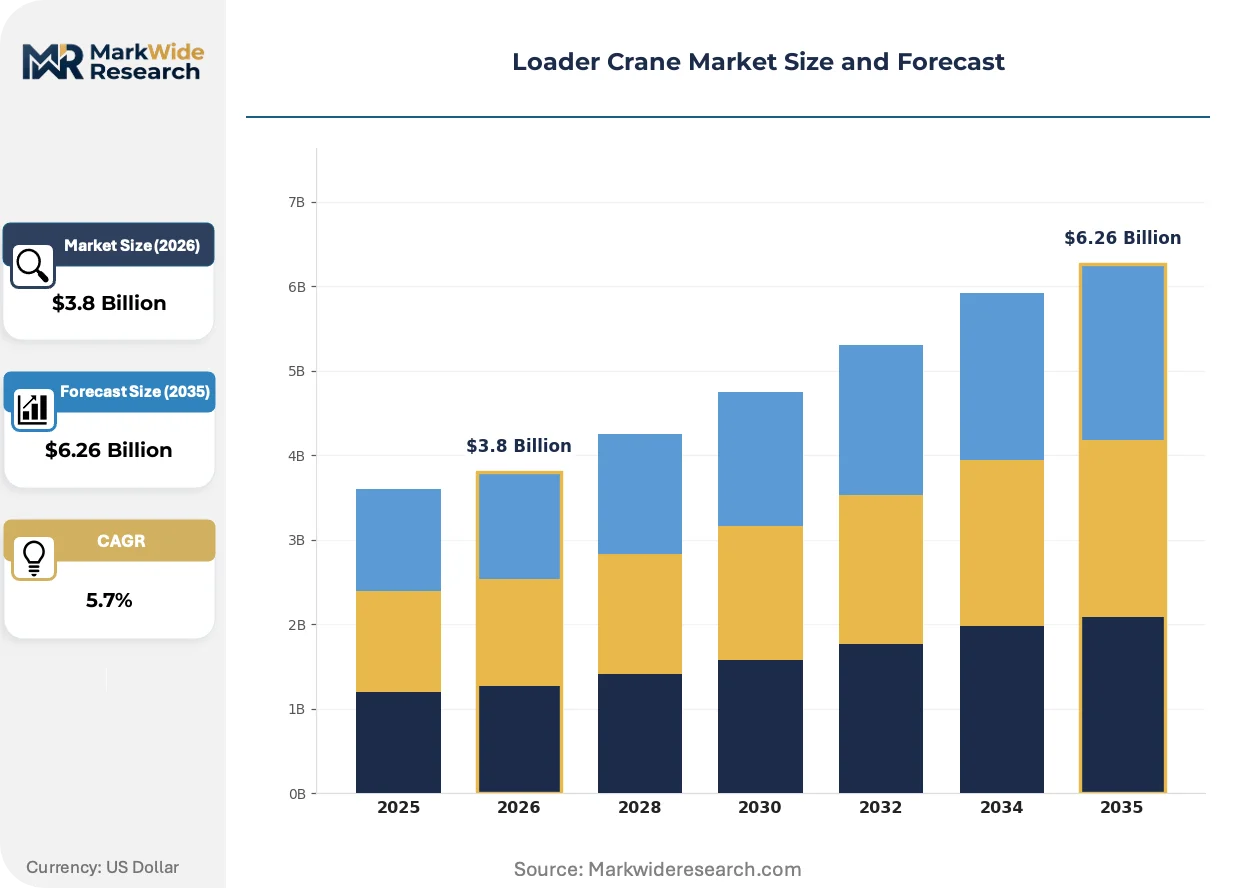
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Knuckle Boom, Telescopic Boom, Articulated Boom, Fixed Boom End User: Construction, Transportation, Forestry, Marine Deployment: On-Road, Off-Road, Portable, Stationary Technology: Electric, Hydraulic, Pneumatic, Manual |
| Companies Covered | Palfinger AG, Hiab AB, Fassi Gru S.p.A., PM Group, Effer S.r.l., Tadano Ltd., XCMG Group, Sany Group Co., Ltd., ATLAS GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Loader Crane Market Strategic Shifts
Technology convergence between electrification and digital control systems is redefining loader crane performance specifications and procurement criteria across municipal and commercial fleet segments.
Modular battery-swapping architectures are converging with standardized chassis interfaces to enable rapid energy replenishment without dedicated charging infrastructure. Urban logistics operators in German municipal fleets are piloting these systems to maintain utilization rates comparable to diesel equivalents. This convergence is compressing total cost of ownership calculations and accelerating specification migration away from permanent battery integration.
REACH chemical restrictions and F-Gas Regulation phase-down schedules are forcing reformulation of hydraulic fluids and refrigerants used in crane climate control systems. Manufacturers must redesign seal compatibility and thermal management systems to maintain warranty coverage under amended substance restrictions. Nordic forestry equipment specifications are most affected, driving accelerated R&D allocation toward fully electric alternatives that eliminate fluid-dependent subsystems.
Fleet operators are unbundling after-sales service contracts from equipment procurement, selecting specialized regional providers for maintenance and remote diagnostics. This disintermediation compresses OEM service revenue but creates channel openings for independent technical service networks with certified technician pools. The pattern is most visible in French municipal procurement, where multi-year service agreements are now tendered separately from crane supply contracts.
Loader Crane Market Segmentation
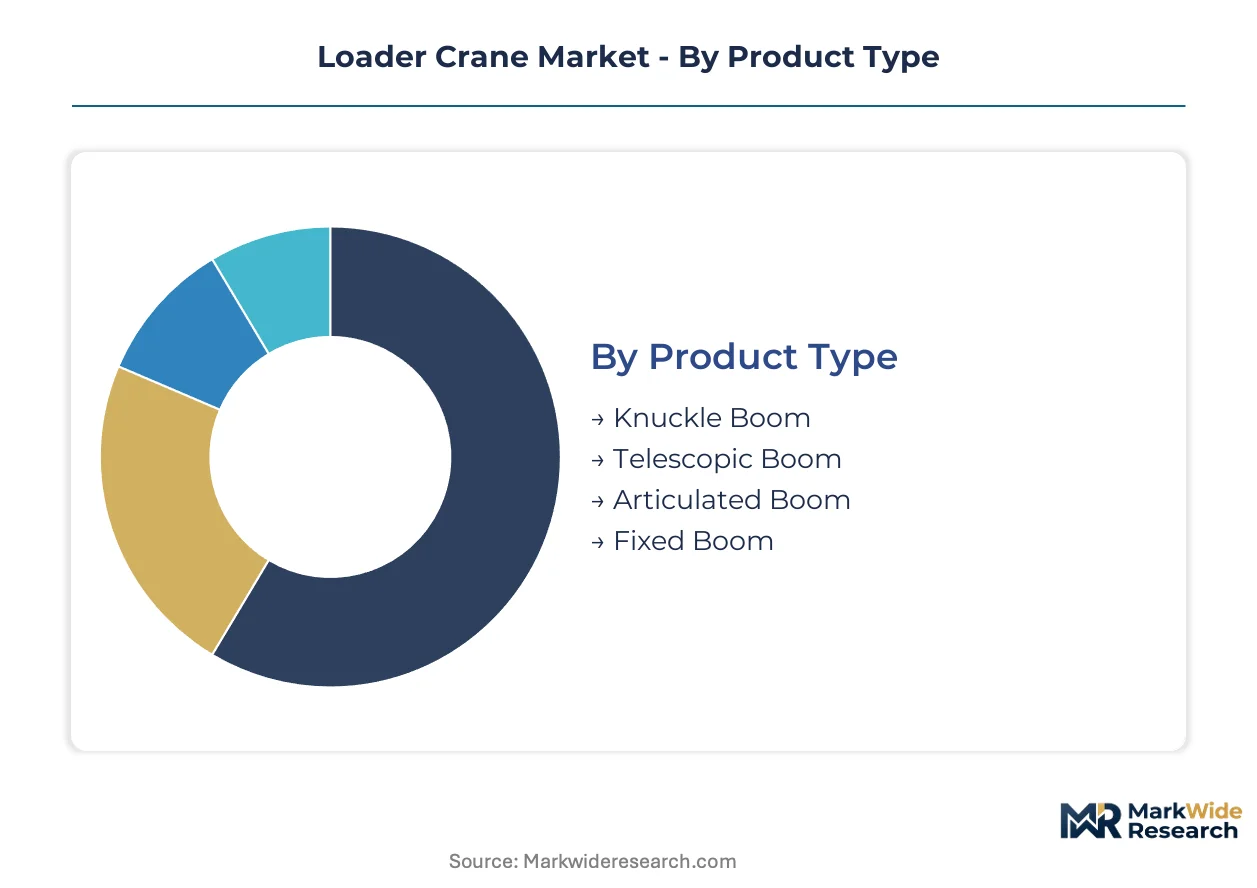
Loader crane segmentation reveals how lifting configurations, power systems, and mobility specifications align with distinct operational economics across municipal fleets and commercial logistics networks. Procurement patterns diverge sharply between urban delivery corridors requiring compact stowage and remote infrastructure sites prioritizing reach extension.
Product Type:
Knuckle boom configurations dominate embedded vehicle-integrated systems where folding efficiency determines chassis payload optimization, while telescopic designs serve standalone heavy-lift applications requiring maximum reach extension.
- Knuckle Boom:Articulated arm with multiple pivot joints enables compact stowage parallel to truck beds, preserving vehicle maneuverability in dense urban delivery zones. German municipal fleets along the Rhine-Ruhr corridor specify these units for multi-drop construction logistics where street width constraints limit boom overhang.
- Telescopic Boom:Nested cylindrical sections extend linearly to achieve superior reach-to-weight ratios for oilfield and utility maintenance applications. North American energy sector procurement favors these designs despite higher stowed profile penalties.
- Articulated Boom:Hybrid joint-and-sleeve architecture balances maneuverability with reach extension for forestry and agricultural loading.
- Fixed Boom:Rigid single-section construction serves dedicated material handling at permanent worksites with predictable load geometries.
Knuckle boom configurations lead volumes today; electric-hybrid variants are gaining share fastest in European municipal procurement.
End User:
Cost tier stratification separates premium-specification marine and offshore installations from standard construction fleet deployments, with transportation logistics occupying the mid-tier value band.
- Construction:General building and civil engineering applications drive baseline volume demand for 10-30 tonne-meter capacity units. French infrastructure stimulus programs under EU Green Deal frameworks accelerate fleet renewal toward electric-hybrid specifications.
- Transportation:Commercial vehicle-mounted cargo handling requires rapid deployment cycles and remote-control operation for driver-only logistics. Nordic operators pilot battery-swapping architectures to maintain utilization parity with diesel equivalents.
- Forestry:Timber harvesting and remote road maintenance demand all-terrain mobility with grapple attachment compatibility.
- Marine:Port cargo handling and offshore supply vessel operations specify corrosion-resistant finishes and heavy-lift capacities exceeding 50 tonne-meters where hydraulic power density retains technology dominance.
Construction absorbs the highest absolute unit volumes; transportation electrification shows the steepest specification migration trajectory.
Deployment:
Application context determines whether cranes deploy as permanent vehicle fixtures or transferable assets across multiple chassis platforms.
- On-Road:Highway-legal truck mounting requires compliance with axle weight distribution regulations and KBA vehicle approval protocols in Germany. Operators face amended UN ECE R29 cabin stability testing when crane mass exceeds threshold percentages of gross vehicle weight.
- Off-Road:Rough-terrain carriers with articulated steering serve mining and quarry operations where surface conditions preclude standard commercial chassis.
- Portable:Demountable subframe systems enable rapid crane transfer between vehicles, appealing to rental fleet operators seeking asset utilization flexibility.
- Stationary:Fixed foundation mounting at recycling yards and industrial facilities prioritizes lift capacity over mobility.
On-road deployment commands the largest installed base; portable configurations are climbing the fastest as rental penetration deepens.
Technology:
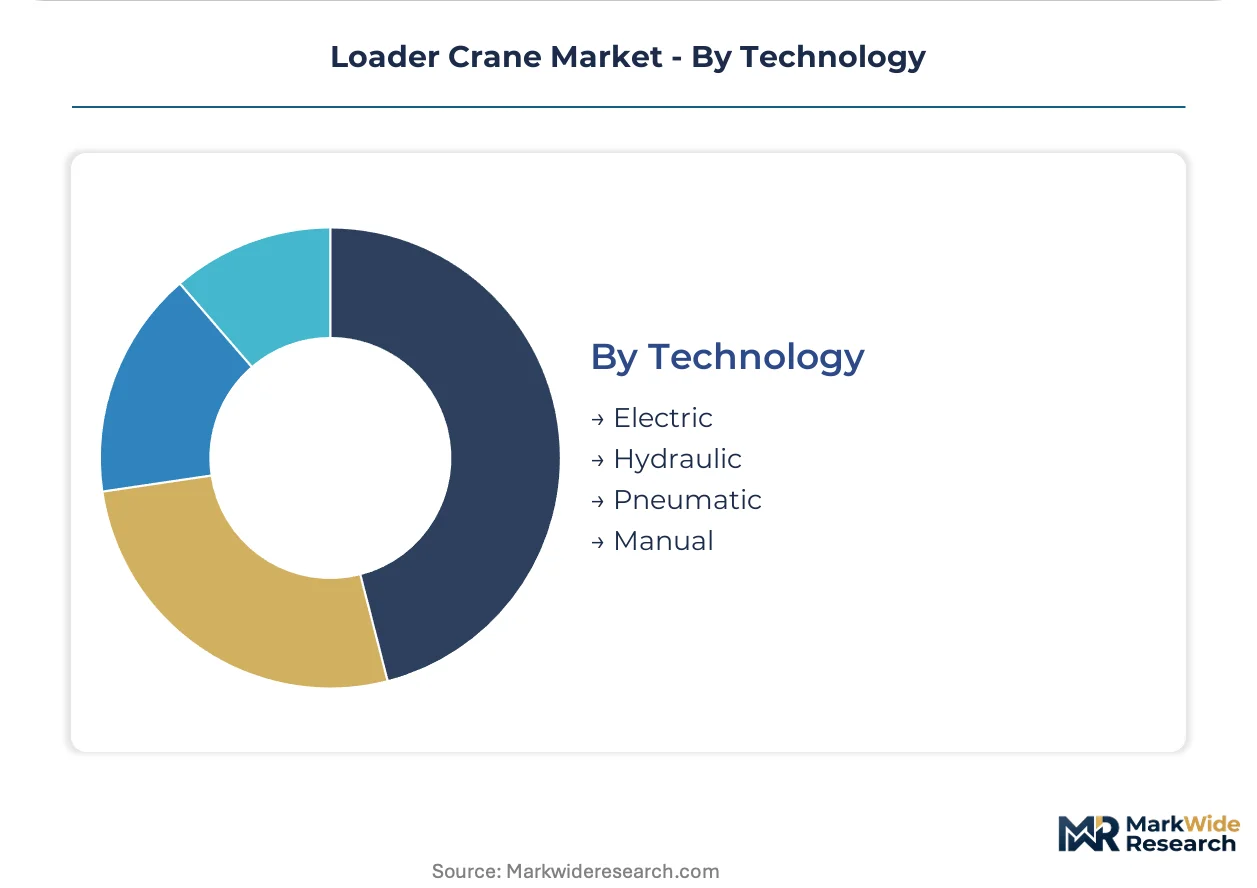
Maturity gradients separate established hydraulic dominance in heavy-lift segments from emerging electric penetration in weight-constrained urban applications.
- Electric:Lithium-ion powerpacks and permanent-magnet motors enable zero-emission operation within European low-emission zones. Swedish utility specifications now mandate electric-hybrid systems for urban forestry contracts.
- Hydraulic:Pressurized fluid power transmission delivers unmatched power density for marine and offshore loads exceeding battery thermal limits. REACH chemical restrictions force progressive hydraulic fluid reformulation.
- Pneumatic:Compressed air actuation serves specialized explosive atmosphere applications where spark ignition risks preclude electrical systems.
- Manual:Hand-cranked winch mechanisms persist in developing market entry segments and emergency backup configurations.
Hydraulic systems retain margin leadership in heavy-lift segments; electric technology is expanding most quickly in municipal fleet specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Loader crane manufacturing originated in post-war Europe, with Austrian and Italian fabricators pioneering knuckle boom designs for Alpine construction logistics. German engineering standards subsequently scaled hydraulic system reliability for commercial vehicle integration.
Germany
KBA vehicle approval requirements now incorporate crane-mounted weight distribution testing under amended UN ECE R29 protocols. The EU Machinery Directive mandates CE marking with EN 12999 conformity, extending product development timelines for non-European suppliers. Rhine-Ruhr corridor municipalities procure knuckle boom units for multi-drop construction logistics serving dense urban worksites.
France
Infrastructure stimulus programs under EU Green Deal frameworks accelerate fleet renewal toward electric-hybrid specifications. ANSM and CNIL oversight extends to telematics data handling in connected crane systems. French municipal procurement now tenders multi-year service agreements separately from crane supply contracts.
Sweden
Forestry and remote infrastructure maintenance contracts now mandate electric-hybrid systems for urban operations. REACH chemical restrictions force hydraulic fluid reformulation, accelerating R&D allocation toward fully electric alternatives. Stockholm-based utility operators pilot battery-swapping architectures to maintain utilization parity with diesel equivalents.
United States
OSHA operator certification requirements fragment across state-level remote-control operation standards, creating compliance overhead for national rental fleets. FCC framework modernization opens channel capacity for advanced teleoperation in hazardous material handling. Texas and North Dakota oilfield procurement favors telescopic boom designs despite higher stowed profile penalties.
China
GB standards and MIIT industrial policy shape domestic loader crane specifications for Belt and Road construction exports. Dual carbon goals accelerate battery-electric prototyping for municipal fleet trials in Yangtze River Delta megacities. XCMG and Sany manufacturing scale dominates volume shipments into Middle Eastern and African construction markets.
Loader Crane Market Competitive Environment
Premium-margin players sit above commodity-margin players across technology integration depth and aftermarket service density. The vendor base organizes into three tiers: European specialists commanding knuckle boom premiums, Asian scale manufacturers driving volume economics, and regional fabricators serving protected procurement channels. Consolidation pressure concentrates among mid-tier hydraulic specialists lacking electric transition roadmaps. Dominant competitive moves include strategic partnerships for battery supply security and geographic licensing arrangements to bypass CE marking barriers.
Within the European specialist tier, Palfinger AG and Hiab AB exemplify premium positioning through Austrian and Swedish manufacturing heritage respectively. Fassi Gru S.p.A. anchors Italian engineering traditions in articulated boom design. Among Asian scale manufacturers, XCMG Group and Sany Group Co., Ltd. represent volume-driven competitive economics. Tadano Ltd. occupies a position bridging precision Japanese fabrication with regional Asia-Pacific distribution networks. ATLAS GmbH exemplifies German mid-tier specialists navigating electrification transition costs.
| Leading Market Players |
|---|
| Palfinger AG |
| Hiab AB |
| Fassi Gru S.p.A. |
| PM Group |
| Effer S.r.l. |
| Tadano Ltd. |
| XCMG Group |
| Sany Group Co., Ltd. |
| ATLAS GmbH |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal procurement mandates for zero-emission municipal fleets are forcing crane manufacturers to absorb lithium-ion powerpack costs while maintaining competitive positioning against hydraulic legacy units, compressing margins and reshaping supplier tier relationships.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates electric-hybrid systems with telematics integration from basic hydraulic units and entry-level manual configurations. Price differentiation hinges on CE marking tier and after-sales service bundling, with French municipal tenders now unbundling multi-year maintenance contracts from equipment supply. Cost compression in mid-tier hydraulic segments is intensifying because Nordic utility operators demand electric specifications without accepting full technology premiums. Rental fleet operators show highest price sensitivity; marine offshore contractors least.
Supply Chain Analysis
Single-source vulnerability sits with Chinese lithium-ion cell suppliers and German precision hydraulic component fabricators. Boom fabrication draws from Swedish specialty steel mills, Italian aluminum extruders, and Chinese casting foundries. Raw material dependencies include high-strength steel plate, lithium carbonate, and rare-earth permanent magnets. Tariff exposure on Chinese battery components threatens cost stability for European electric-hybrid assembly. Distribution runs through OEM-integrated channels, independent rental networks, and direct municipal procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards geographic arbitrage between EU regulatory compliance costs and Chinese manufacturing scale, with the gap between KBA approval timelines and MIIT production cycles creating margin capture opportunities for dual-footprint operators.
For Market Incumbents: Anchor electric-hybrid R&D allocation in Swedish and German engineering centers to preempt EU Green Deal specification tightening. Secure backward integration into lithium-ion powerpack assembly through joint ventures with Chinese cell suppliers. Defend against Asian scale manufacturers by deepening CE marking expertise and KBA relationship networks that extend approval timelines for non-European competitors.
For New Entrants and Emerging Players: Battery-swapping architecture standardization offers entry into German municipal fleet procurement where utilization parity requirements block permanent-battery competitors. Target French transportation logistics operators piloting separated service-contract tendering. Pursue telematics-first positioning with predictive maintenance platforms that create recurring revenue independent of equipment sales cycles.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier hydraulic specialists possessing electric transition roadmaps and established KBA approval track records. Five-to-ten-year viability hinges on successful technology migration before EU low-emission zone expansion accelerates. Watch for inflection in Nordic forestry contract specifications mandating electric-hybrid systems as signal of specification cascade into broader European municipal procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell allocation from Chinese suppliers for EU electric-hybrid assembly lines. |
| CE Marking Pathway Investment | Accelerates EN 12999 conformity timelines for non-European manufacturers seeking market access. |
| Predictive Maintenance Platform Launch | Creates recurring revenue streams through IoT sensor arrays and remote diagnostics for fleet operators. |
| Joint Venture for Nordic Electrification | Combines Swedish engineering heritage with battery technology for forestry and utility specifications. |
| Service Contract Unbundling | Aligns with French municipal procurement patterns separating multi-year maintenance from equipment supply. |
Study Parameters
Multiple input streams — OEM procurement directors, municipal fleet managers, aftermarket service heads, and regulatory affairs specialists — were reconciled against customs trade data, EU Machinery Directive filing records, and SEC filings from listed equipment manufacturers. Bottom-up unit shipment estimates across knuckle boom, telescopic boom, and electric-hybrid configurations were triangulated with top-down value projections derived from public tender databases and rental fleet asset registers.
Data-stream reconciliation applied CAGRs derived from historical specification migration patterns and electrification subsidy trajectories across the analysis window. Segmentation modeling incorporated product type, power system technology, deployment configuration, and end-use industry vertical. Forecast inputs included EU Green Deal implementation timelines, REACH chemical restriction phase-down schedules, and lithium-ion powerpack cost curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery power density breakthroughs, steel commodity volatility, and divergent national electrification subsidy schemes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Trencher Attachments Market
Material Handling Equipment
Air Hose Market
Material Handling Equipment
Global Refuse Compactor Market
Material Handling Equipment
Global Mechanical Seals Market
Material Handling Equipment
Global Lifting Columns Market
Material Handling Equipment
India Automated Material Handling (AMH) Market
Material Handling Equipment
Middle East Conveyor Belts Market
Material Handling Equipment
Global Bucket Loader Market
Material Handling Equipment
Gantry Crane Market
Material Handling Equipment
Robotic Palletizers and De-Palletizers Market
Material Handling Equipment
Light Duty Telehandler Market
Material Handling Equipment
Telehandler Market
Material Handling Equipment
Vibrating Screen Market
Material Handling Equipment
Wear Plates Market
Material Handling Equipment
Conveying Equipment Market
Material Handling Equipment
High-Performance Seals Market