
 Pick and Carry (PNC) Crane Market | 2026-2036
Pick and Carry (PNC) Crane Market Size, Share, and Industry Trends Forecast 2026-2036
Pick and Carry (PNC) Crane Market Analytics
EU machinery directives are repositioning the compliance burden for PNC crane manufacturers selling into European job sites. Tadano Ltd. leverages its Japanese engineering heritage to sustain premium positioning in high-specification electric crane variants. XCMG Group anchors volume supply through integrated casting and hydraulics operations in Xuzhou. Manitex International, Inc. competes through specialized boom configurations tailored for confined-space warehousing deployments.
A Pick and Carry crane is a self-propelled, rubber-tyred mobile lifting machine with a telescopic or lattice boom mounted on a rotating superstructure, designed to transport loads while suspended and rated typically from one to over ten tonnes capacity; its primary purpose is to execute repetitive lift-and-carry cycles on congested industrial and construction sites without fixed runway infrastructure. Hydraulic cranes dominate current fleet composition due to proven power density and field-serviceability across rental pools, while electric cranes represent the fastest-expanding product category as site emission rules tighten and battery energy density improves. The 2-5 ton capacity band captures the broadest addressable base of warehousing and light industrial users, whereas above-10-ton units command concentrated margin pools in heavy infrastructure applications.
FAA crane safety advisories and OSHA mobile equipment standards shape operator certification and inspection protocols for units deployed on US federal and commercial projects. EMA machinery guidelines and CE marking requirements enforce structural integrity documentation and electromagnetic compatibility testing for European market access. India's BIS certification mandates load-testing verification for imported cranes operating at ports and power plants. Stakeholders must monitor how overlapping national safety regimes affect cross-border fleet interoperability and spare parts logistics.
Market Dynamics
China's GB standards for mobile crane stability are forcing structural redesigns across the PNC crane supply base, compressing development cycles for manufacturers serving cross-border markets while elevating compliance costs for smaller fabricators.
Growth Catalysts
- India's PLI scheme for construction equipment:Domestic production incentives are drawing component suppliers to Gujarat and Maharashtra industrial corridors, shortening lead times for fleet operators.
- Battery energy density improvements:Lithium-ion pack configurations now deliver sufficient duty cycles for electric PNC cranes to complete full warehouse shifts without interim charging.
- OSHA mobile equipment standards:Updated operator certification requirements are accelerating replacement demand in US rental pools as older units fail revised inspection protocols.
Market Restraints
- High-strength steel price volatility:Boom fabrication costs fluctuate with alloy supply from integrated mills, squeezing margin predictability for mid-tier assemblers.
- Hydraulic component concentration:Precision valve and pump sourcing clusters in German and Japanese supplier networks, exposing buyers to extended lead times during capacity constraints.
- CE marking documentation burden:EMA machinery guidelines require extensive electromagnetic compatibility testing that delays European market entry for new entrants lacking established certification teams.
Strategic Opportunities
- Vietnam's port modernization:Container throughput expansion at Hai Phong and Cai Mep is generating demand for compact load handlers in congested yard environments.
- EU Green Deal procurement mandates:Public infrastructure tenders increasingly specify zero-emission equipment, creating preferential positioning for electric crane vendors.
- Telematics-ERP convergence:Real-time fleet data integration with warehouse management systems is enabling outcome-based equipment contracts.
Industry Challenges
- Certified hydraulic technician scarcity:Field service capacity limits fleet uptime guarantees in remote industrial zones.
- BIS load-testing bottlenecks:India's port and power plant import verification creates month-long customs delays for urgent project deliveries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pick and Carry (PNC) Crane Market |
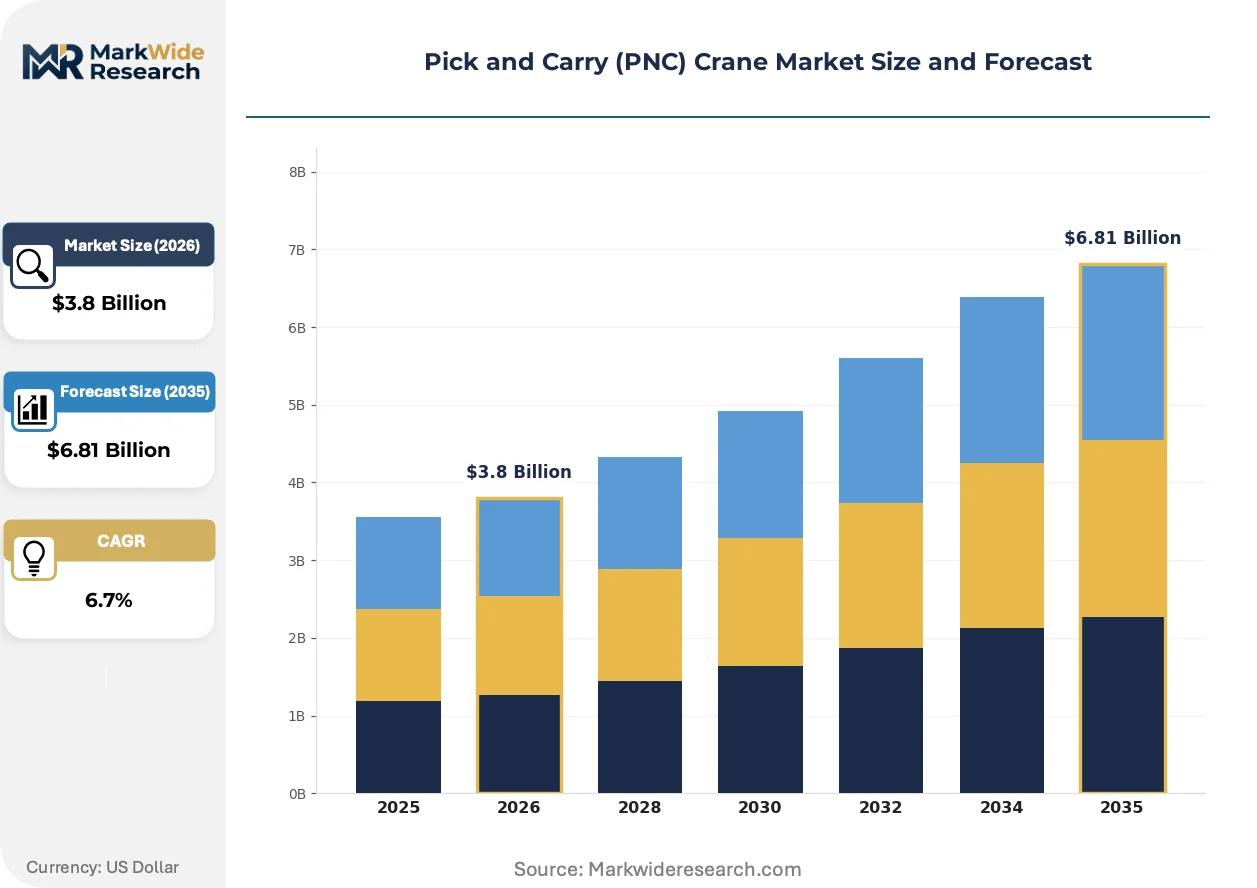
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mini Cranes, Electric Cranes, Hydraulic Cranes, All-Terrain Cranes Application: Construction, Warehousing, Industrial, Landscaping End User: Construction Companies, Logistics Providers, Manufacturing Facilities, Rental Services Capacity: 1-2 Tons, 2-5 Tons, 5-10 Tons, Above 10 Tons |
| Companies Covered | Terex Corporation, Manitex International, Inc., Tadano Ltd., XCMG Group, Zoomlion Heavy Industry Science & Technology Co., Ltd., Liebherr Group, Sany Heavy Industry Co., Ltd., Palfinger AG, ACE (Action Construction Equipment Ltd.), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pick and Carry (PNC) Crane Market Evolving Landscape
Electrification is compressing the technology gap between premium and standard equipment tiers, while regulatory divergence across major economies is fragmenting product platform strategies.
Lithium-ion battery packs with integrated thermal management are electrifying the sub-5-ton capacity segment. Third-party logistics operators in European distribution centers are adopting these configurations fastest, replacing diesel units to comply with indoor air quality rules. This shift is compressing residual values for conventional hydraulic fleets and accelerating write-down cycles.
REACH substance restrictions on hydraulic fluids are forcing reformulation of seal materials and lubricant chemistries. European manufacturers must document full material composition through supply chains to maintain CE marking validity. The 2-5 ton warehousing segment faces the steepest compliance burden due to high unit volumes and thin margin structures.
Rental fleet operators are unbundling maintenance contracts from equipment leases, shifting toward hourly-availability guarantees with penalty clauses. Construction contractors in Southeast Asia are driving this model fastest, prioritizing uptime over ownership to manage project cash flow. Channel intermediaries with regional service networks are capturing margin previously held by manufacturers.
Pick and Carry (PNC) Crane Market Segmentation
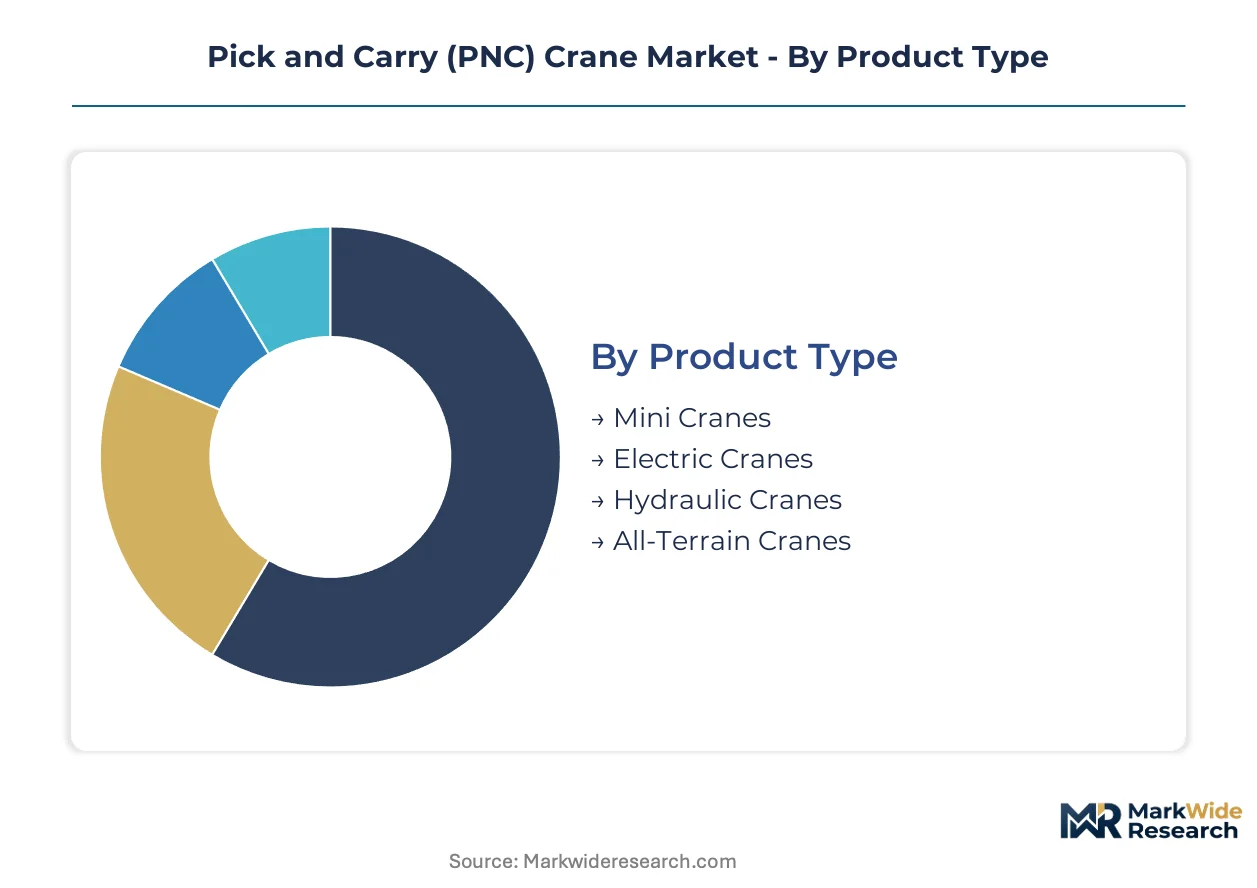
PNC crane buyers segment demand across four intersecting dimensions that determine procurement priorities. Fleet operators weigh duty cycle requirements against site access constraints, while rental pools balance utilization rates against residual value risk. Understanding these trade-offs clarifies why product configuration and capacity band selections diverge across end-use contexts.
Product Type:
Hydraulic cranes anchor current fleet volumes while electric variants capture the steepest expansion trajectory as emission rules tighten.
- Hydraulic Cranes:Proven power density and field-serviceability sustain dominance across rental pools and remote job sites. Demand concentrates in India's industrial corridor projects where technician scarcity limits electric crane deployment.
- Electric Cranes:Lithium-ion packs with integrated thermal management now deliver full-shift duty cycles in sub-5-ton configurations. Third-party logistics operators in European distribution centers are replacing diesel units fastest to comply with indoor air quality rules.
- Mini Cranes:Compact footprints serve confined-space warehousing and interior construction in dense urban environments.
- All-Terrain Cranes:Rubber-tyred mobility with outrigger-free operation suits congested yard environments at Vietnam's expanding port facilities.
Today's leader: Hydraulic Cranes. Tomorrow's challenger: Electric Cranes.
Capacity:
Mid-range bands capture warehousing standardization while heavy units command infrastructure project premiums.
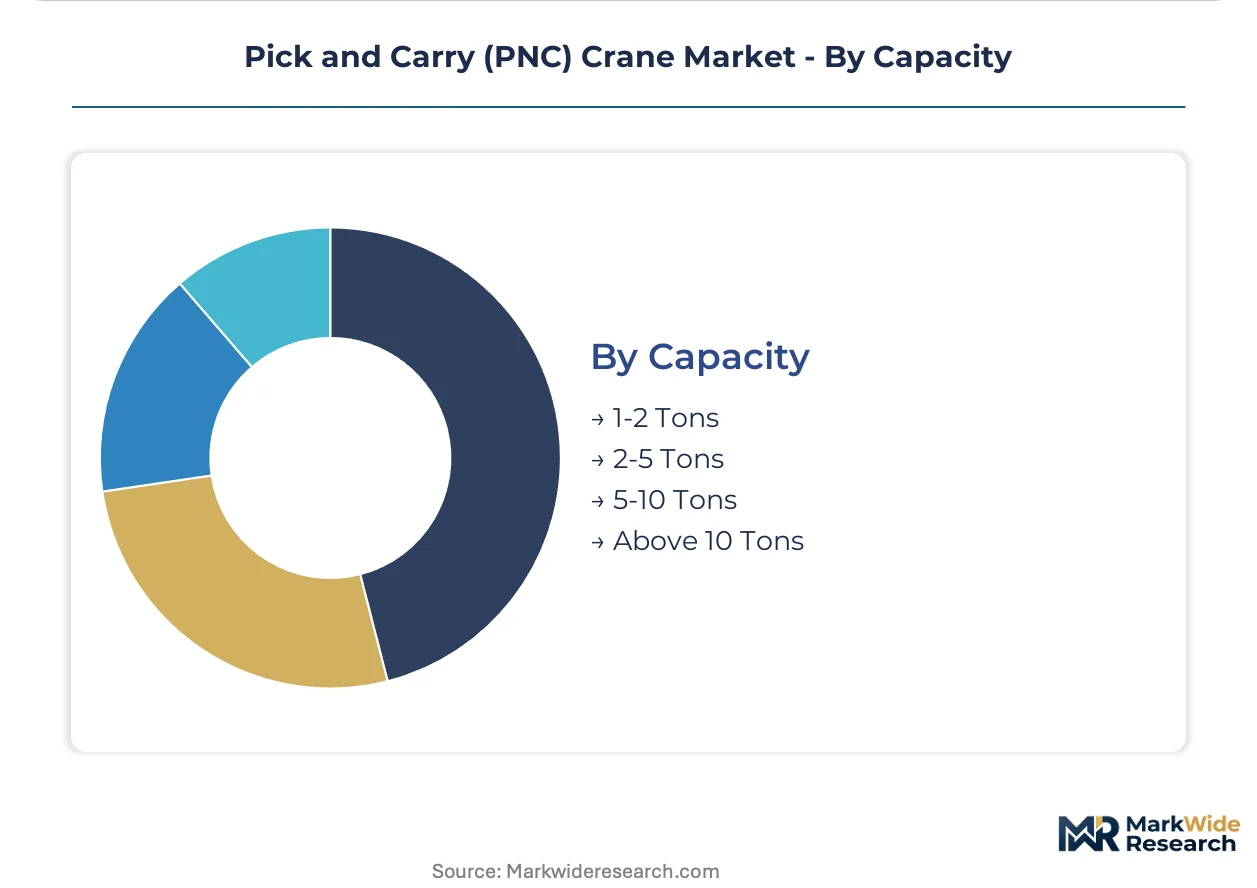
- 2-5 Tons:The broadest addressable base serves warehousing and light industrial users with repetitive lift-and-carry cycles. European REACH substance restrictions on hydraulic fluids impose the steepest compliance burden here due to high unit volumes and thin margin structures.
- Above 10 Tons:Concentrated margin pools attach to heavy infrastructure applications including port modernization and power plant construction. China's tightening GB standards for mobile crane stability force structural redesigns that compress development cycles for this segment.
- 1-2 Tons:Compact material handlers address landscaping and light maintenance tasks in confined sites.
- 5-10 Tons:Bridges light industrial and heavier construction applications with flexible fleet deployment.
The 2-5 Tons band generates the highest unit velocity. Above 10 Tons delivers the strongest margin capture.
Application:
Construction absorbs the largest equipment volume while warehousing drives the fastest technology refresh.
- Construction:Repetitive lift-and-carry cycles on congested job sites demand rubber-tyred mobility without fixed runway infrastructure. Fleet orders from Southeast Asian infrastructure contractors are expanding fastest as compact material handlers replace traditional tower crane setups.
- Warehousing:Indoor air quality rules and emission mandates are accelerating electric crane adoption. Telematics-ERP convergence is enabling outcome-based equipment contracts with hourly-availability guarantees.
- Industrial:Manufacturing facilities require reliable uptime for production line feeding and maintenance operations.
- Landscaping:Mini crane configurations address tree handling and terrain work in residential and commercial property development.
Construction commands current fleet investment. Warehousing sets the pace for electrification.
End User:
Rental services intermediate the largest equipment flows while logistics providers lead specification upgrades.
- Rental Services:Unbundling maintenance from equipment leases shifts risk to regional service networks with uptime guarantees. OSHA mobile equipment standards are accelerating replacement demand as older units fail revised inspection protocols.
- Logistics Providers:Third-party operators in European distribution centers prioritize zero-emission configurations to meet EU Green Deal procurement mandates. Real-time fleet data integration with warehouse management systems is enabling penalty-clause contracting.
- Construction Companies:Project cash flow management favors rental over ownership in Southeast Asian markets.
- Manufacturing Facilities:Captive fleets emphasize reliability and spare parts availability for continuous operations.
Rental Services intermediate today's volume. Logistics Providers set tomorrow's specification standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified crane operators and hydraulic technicians concentrate in Germany's industrial belt, India's western manufacturing corridors, and Japan's precision engineering hubs, anchoring regional deployment capacity for fleet operators and rental services.
United States
Infrastructure contractors in Texas and Florida are expanding compact crane fleets for congested urban job sites. OSHA mobile equipment standards enforce updated operator certification protocols that accelerate replacement cycles in rental pools. The Gulf Coast petrochemical corridor around Houston drives demand for all-terrain configurations in refinery maintenance.
Germany
REACH substance restrictions on hydraulic fluids force seal material reformulation across boom fabrication supply chains. EMA machinery guidelines and CE marking requirements enforce electromagnetic compatibility documentation that delays market entry for non-European fabricators. The Ruhr industrial region hosts service networks specializing in electric crane deployment for warehouse automation.
India
PLI scheme incentives for construction equipment are drawing component suppliers to Gujarat and Maharashtra industrial corridors. BIS certification mandates load-testing verification for imported cranes at ports and power plants, creating month-long customs delays. The Delhi-Mumbai Industrial Corridor anchors the heaviest fleet investment for infrastructure megaprojects.
China
GB standards for mobile crane stability are tightening structural requirements on imported equipment, compressing development cycles for cross-border manufacturers. Xuzhou's integrated casting and hydraulics operations anchor domestic volume supply for the Asia-Pacific rental market. Yangtze River Delta warehouse operators are piloting electric configurations for indoor logistics.
Japan
METI industrial policy supports precision engineering heritage in electric crane variant development. JIS standards govern structural integrity documentation for domestic and export certification. The Nagoya-Tokyo manufacturing belt concentrates technician training capacity that sustains premium service networks across Southeast Asian project sites.
Pick and Carry (PNC) Crane Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: integrated steel-and-hydraulics manufacturers with captive component supply, regional fabricators serving rental fleet procurement, and precision engineering houses specializing in electric variants. Consolidation pressure operates through backward integration into boom casting and strategic partnerships for battery pack sourcing.
Within the diversified industrial tier, Terex Corporation and XCMG Group occupy positions reflecting scale-driven manufacturing footprints across multiple equipment categories. Tadano Ltd. exemplifies the precision engineering archetype with heritage positioning in high-specification variants. Manitex International, Inc. sits within the specialized configuration segment, serving confined-space deployment requirements through tailored boom geometries. Liebherr Group anchors the premium-tier European fabricator position, while Sany Heavy Industry Co., Ltd. and Zoomlion Heavy Industry Science & Technology Co., Ltd. represent Chinese-scale manufacturers with integrated supply chain control.
| Leading Market Players |
|---|
| Terex Corporation |
| Manitex International, Inc. |
| Tadano Ltd. |
| XCMG Group |
| Zoomlion Heavy Industry Science & Technology Co., Ltd. |
| Liebherr Group |
| Sany Heavy Industry Co., Ltd. |
| Palfinger AG |
| ACE (Action Construction Equipment Ltd.) |
| Others |
Value Network & Pricing Analysis
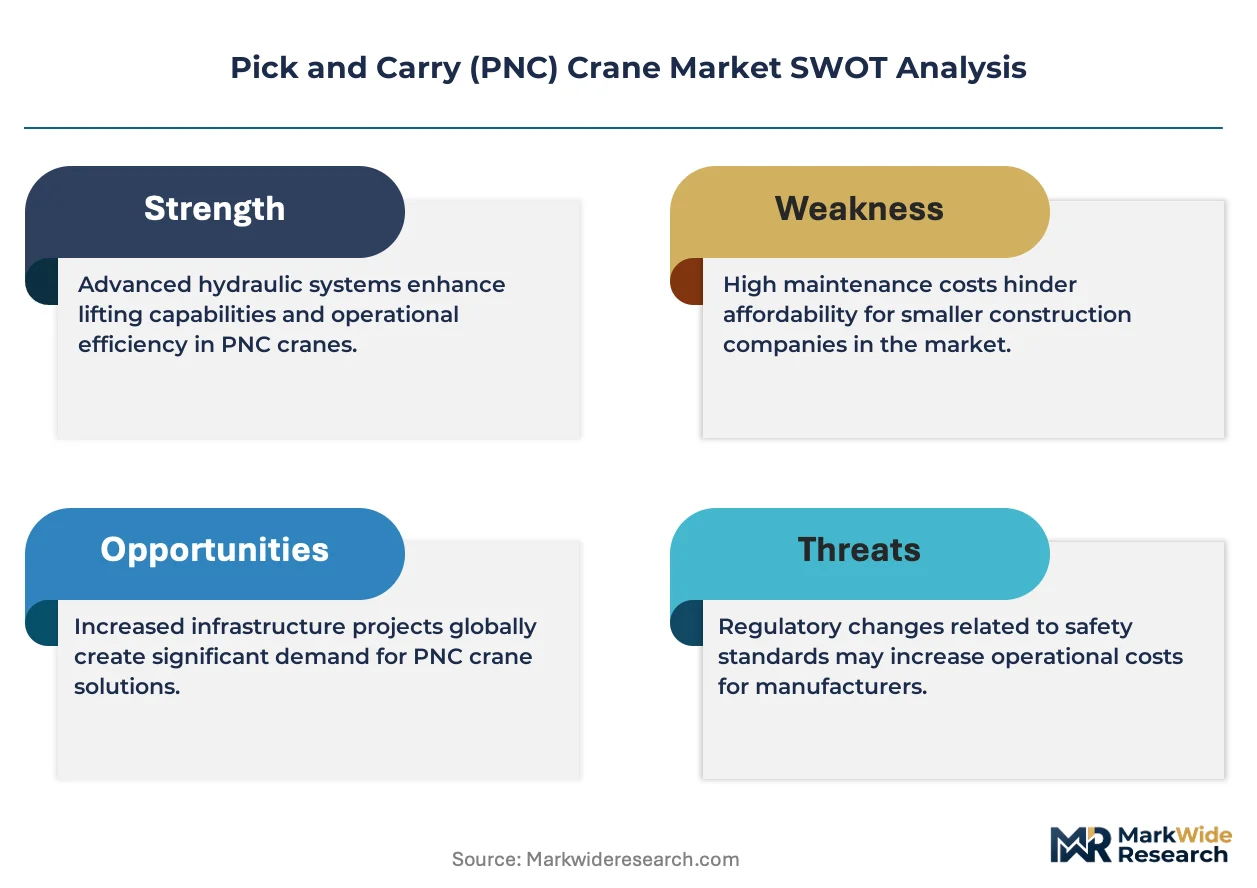
High-strength steel price volatility cascades through PNC crane manufacturing tiers, compressing margins for mid-tier assemblers while amplifying pricing power for integrated producers with captive alloy sourcing. Boom fabrication costs fluctuate with supply from integrated mills, forcing buyers to absorb volatility or shift toward fixed-price service contracts that bundle maintenance with equipment lease terms.
Pricing Analysis
The bundled-versus-unbundled service split now defines procurement economics across rental and end-user segments. Premium-mid-economy pricing differentiation separates manufacturers with certified technician networks from commodity assemblers competing on upfront capital cost. Price differentiation hinges on after-sales service bundling and CE marking documentation completeness. Pricing pressure stems from REACH substance compliance costs in the 2-5 ton warehousing segment, where thin margins amplify buyer price sensitivity. Logistics providers in European distribution centers exhibit lowest price sensitivity due to EU Green Deal procurement mandates favoring zero-emission configurations.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping component sourcing patterns, drawing suppliers to Gujarat and Maharashtra industrial corridors. Boom fabrication draws from German and Japanese precision valve networks, while lithium-ion battery packs source from integrated Asian cell manufacturers. Supply chain risk centers on hydraulic component concentration, exposing buyers to extended lead times during capacity constraints. Distribution runs through regional rental fleet operators and OEM-authorized service networks that intermediate equipment flows to project sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, where overlapping national safety regimes create compliance-driven replacement cycles. OSHA mobile equipment standards and China's tightening GB standards for mobile crane stability are accelerating fleet turnover across multiple geographies.
For Market Incumbents: Lock in technician certification capacity and captive alloy sourcing to defend against margin compression from high-strength steel price volatility. Deepen backward integration into boom casting operations in Xuzhou or comparable industrial clusters. Prioritize CE marking documentation teams to preempt EMA machinery guideline delays that disadvantage cross-border competitors. For New Entrants and Emerging Players: Capture the electric crane aftermarket service gap in India's industrial corridors, where BIS certification bottlenecks and technician scarcity limit incumbent response speed. Target Vietnam's port modernization at Hai Phong and Cai Mep, where container throughput expansion outpaces established service network coverage. Lead with telematics-ERP integration as a differentiated procurement pitch for third-party logistics operators. For Investors and Strategic Acquirers: Asymmetric upside sits with regional fabricators possessing established certification teams and port-proximate assembly capacity. Long-term viability favors vendors with electric variant development pipelines and battery pack sourcing partnerships. Monitor BIS load-testing queue lengths as an inflection indicator for import substitution opportunity windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Boom Casting | Captive alloy supply insulates margin from high-strength steel price volatility in German and Japanese mill markets. |
| Electric Crane Certification Investment | CE marking and OSHA compliance documentation accelerates market entry ahead of REACH substance restriction deadlines. |
| Regional Service Network Expansion | Technician density in Gujarat and Maharashtra industrial corridors shortens response times for PLI-scheme production clusters. |
| Battery Pack Sourcing Partnership | Lithium-ion thermal management integration secures full-shift duty cycles for sub-5-ton warehouse configurations. |
| Telematics-ERP Platform Development | Real-time fleet data integration enables penalty-clause contracting with European distribution center operators. |
Research Methodology
Coverage spans the United States, Germany, India, China, and Japan, with primary inputs from each market cluster combining fleet operator interviews with regulatory documentation review. The research incorporated discussions with maintenance directors at rental services, plant engineers at manufacturing facilities, OEM procurement teams at construction contractors, and aftermarket service heads at regional distributors. Secondary validation drew from OSHA mobile equipment standards filings, EMA machinery guideline publications, BIS certification records, GB standards documentation, and METI industrial policy releases. Bottom-up equipment shipment data triangulated against top-down infrastructure investment forecasts.
Granularity-level modeling operated at product type, capacity band, application, and end-user dimensions across the projection horizon. The analytical framework projected hydraulic and electric crane volumes separately, with above-10-ton infrastructure applications distinguished from 2-5-ton warehousing configurations. CAGRs derived from regression analysis against port throughput indices, industrial corridor investment flows, and emission regulation phase-in schedules. Forecast inputs included battery energy density improvement curves and certified hydraulic technician supply constraints.
Steel price volatility, regulatory timeline acceleration, and technician training bottlenecks are the dominant revision risks that could compress or extend replacement cycle assumptions. Forecasts reflect documented stakeholder input and secondary source triangulation without claiming predictive certainty. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Industrial Lifting Equipment Market
Material Handling Equipment
Container Handler Market
Material Handling Equipment
North America Conveyor Belt Market
Material Handling Equipment
Spiral Fitting Machines Market
Material Handling Equipment
Global Refuse Compactor Market
Material Handling Equipment
Flux Spraying Machine Market
Material Handling Equipment
High-Precision Gear Reducer Market
Material Handling Equipment
Metal Plain Washer Market
Material Handling Equipment
Sifter Fitment Market
Material Handling Equipment
Brazil Forklift Market
Material Handling Equipment
Industrial Bag Dust Filter Market
Material Handling Equipment
Hydraulic Hoist Market
Material Handling Equipment
Lump Breaker Machines Market
Material Handling Equipment
Container Handling Equipment Market
Material Handling Equipment
North America Forklift Market
Material Handling Equipment
Canada Forklift Market