
 Forklift Tire Market | 2026-2036
Forklift Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Forklift Tire Market Intelligence
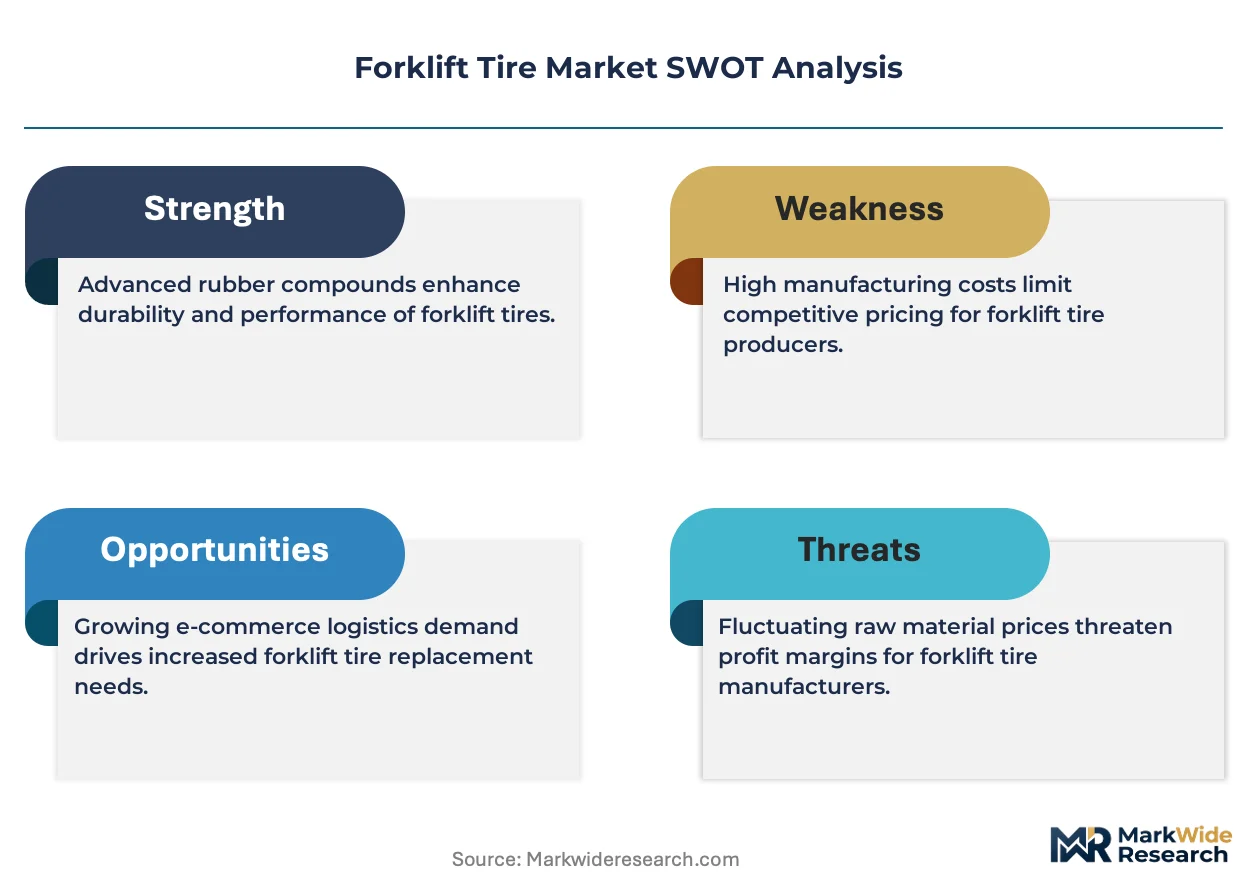
Radial-grade construction is reorganizing procurement priorities across the forklift tire landscape. Michelin leverages its R&D intensity to command premium positioning in European material handling fleets. Bridgestone Corporation anchors its competitive stance through backward integration into synthetic rubber supply chains. Continental AG differentiates via specialized tread compounds engineered for high-cycle warehousing environments.
Forklift tires are industrial load-bearing components manufactured from natural and synthetic rubber compounds reinforced with steel or fabric plies, designed to withstand static and dynamic loads exceeding rated capacities while maintaining stability on smooth or uneven surfaces. Solid and cushion tire categories dominate replacement cycles due to their puncture resistance and lower total cost of ownership in indoor warehousing applications. Radial technology leads in outdoor heavy-lift segments where heat dissipation and tread longevity determine fleet uptime, while polyurethane formulations capture niche demand in cleanroom manufacturing facilities requiring non-marking floor contact.
EPA emission standards for off-road equipment and OSHA workplace safety regulations govern tire integrity and replacement protocols in United States industrial environments. ECHA REACH compliance and EU F-Gas Regulation indirectly shape rubber compound formulations through chemical restriction frameworks. Stakeholders must monitor evolving sustainability mandates from ISO lifecycle standards and national regulators as circular economy requirements penetrate procurement specifications across material handling supply chains.
Market Dynamics
Warehouse automation intensity and REACH-mandated compound reformulation are restructuring procurement specifications across material handling fleets. Fleet managers now prioritize heat-dissipating radial constructions and low-aromatic rubber formulations to satisfy uptime targets and chemical compliance simultaneously.
Growth Catalysts
- E-commerce fulfillment expansion:Amazon, Walmart, and regional logistics operators are accelerating forklift fleet turnover to match same-day delivery velocity. Replacement tire demand concentrates in automated storage and retrieval system environments.
- REACH chemical restrictions:ECHA-mandated limits on polycyclic aromatic hydrocarbons are forcing compound reformulation across European manufacturing. Suppliers with certified low-PAH rubber gain preferential access to German and French procurement channels.
- Polyurethane cleanroom adoption:Semiconductor and pharmaceutical manufacturing facilities in Taiwan, South Korea, and Germany are specifying non-marking polyurethane tires to protect epoxy and vinyl flooring surfaces from carbon black residue.
Market Restraints
- Natural rubber price volatility:Thai and Indonesian supply disruptions transmit directly to solid tire cost structures. Manufacturers lack pricing power to pass through input spikes in contracted fleet maintenance agreements.
- Steel cord supply concentration:Radial tire production depends on high-tensile steel bead wire sourced from a narrow base of East Asian metallurgical suppliers. Geographic concentration creates vulnerability to trade policy friction.
- Technical limitation in extreme cold:Standard solid rubber compounds stiffen below minus-twenty degrees Celsius, degrading traction and load stability. Arctic logistics and cold-storage warehousing in Canada and Scandinavia face operational constraints without specialized formulations.
Strategic Opportunities
- India warehouse infrastructure buildout:PLI scheme incentives and GST harmonization are accelerating organized retail and third-party logistics penetration. Domestic tire manufacturers can capture share before multinational brands establish localized compound production.
- EU Green Deal circular economy mandates:Upcoming extended producer responsibility frameworks will reward retreadable radial designs and recycled rubber content. Early certification creates differentiation in public-sector fleet tenders.
- Telematics-integrated tire monitoring:IoT pressure and temperature sensors embedded in tire carcasses enable predictive replacement scheduling. Technology convergence between sensor hardware and fleet management software opens subscription revenue models.
Industry Challenges
- Compound formulation expertise scarcity:Formulators capable of balancing abrasion resistance, heat buildup, and REACH compliance command premium compensation. Technical talent migration from legacy automotive tire divisions creates recruitment friction.
- ISO 3691-5 certification timeline:New stability and load-testing protocols for non-standard tire dimensions extend product validation cycles. Smaller manufacturers face working capital strain during extended approval periods.
- Legacy fleet compatibility constraints:Radial tire retrofits on older cushion-tire chassis require rim and axle modifications. Integration complexity slows upgrade adoption in cost-sensitive operations running depreciated equipment.
Report Scope
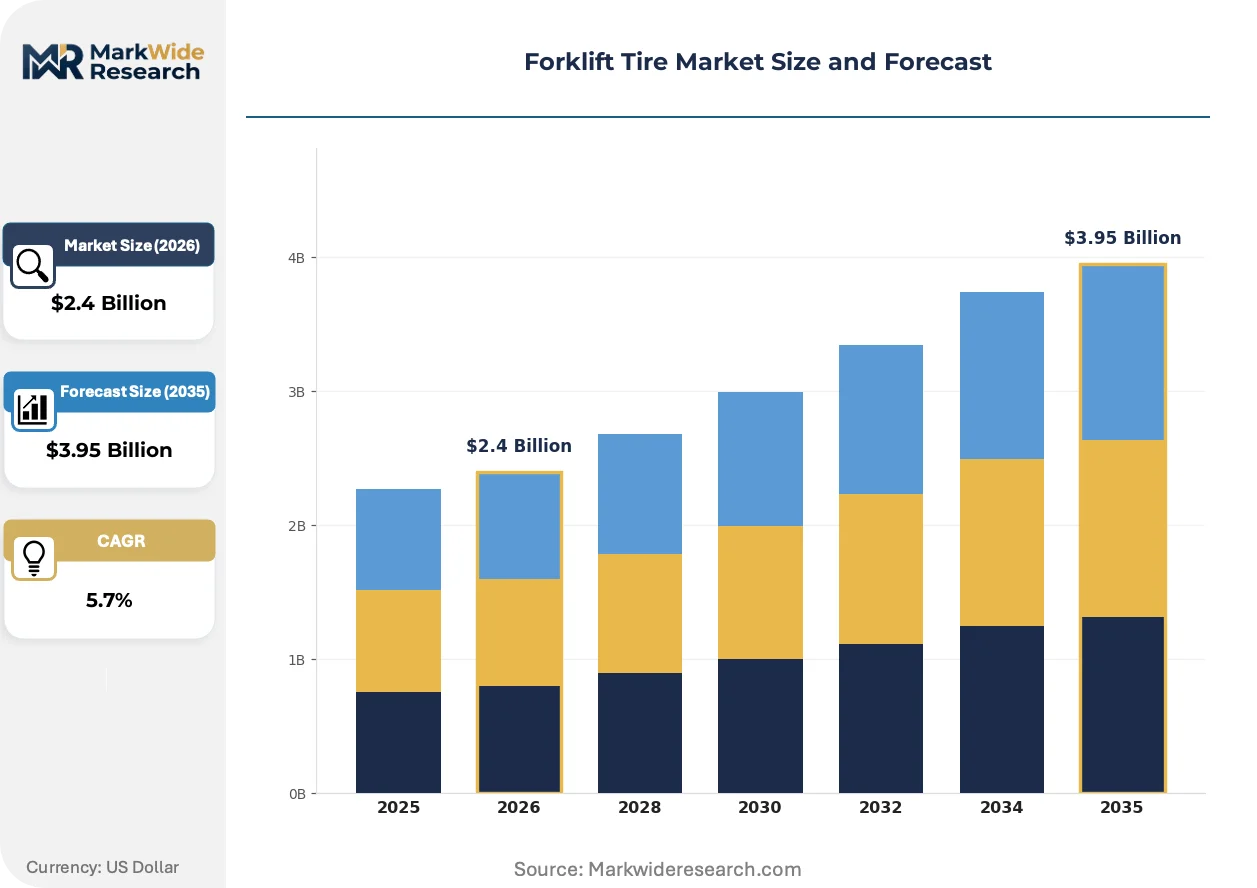
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Forklift Tire Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.95 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pneumatic, Solid, Cushion, Polyurethane Technology: Bias Ply, Radial, Wire Ply, Foam Filled Application: Warehousing, Construction Sites, Manufacturing Facilities, Shipping Yards End User: Material Handling Companies, Logistics Providers, Distribution Centers, Port Operators |
| Companies Covered | Trelleborg AB, Hankook Tire & Technology, Michelin, Maxam Tire, Goodyear Tire & Rubber Company, Bridgestone Corporation, The Yokohama Rubber Co. Ltd., Balkrishna Industries Limited, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Forklift Tire Market Strategic Shifts & Innovations
Material substitution and predictive service models are compressing traditional replacement cycles while elevating performance specifications. Three developments are restructuring competitive positioning across the value chain.
Radial construction with steel belt packages is supplanting cross-ply bias designs in outdoor container handling and lumber yard applications. Port operators in Rotterdam, Hamburg, and Long Beach are specifying radial tires for reach stackers and heavy-duty counterbalance trucks to extend tread life and reduce heat-related failures. This technology is supplanting conventional solid tires in applications exceeding eight-ton lift capacity, compressing the addressable market for basic cushion compounds.
EU F-Gas Regulation and ECHA SVHC candidate list updates are accelerating fluoropolymer and plasticizer phaseouts in tire manufacturing auxiliary chemicals. Compounders must reformulate curing agents and mold-release agents to maintain process yields while eliminating restricted substances. German and Benelux material handling fleets are now requiring full material disclosure documentation in procurement specifications, transferring compliance burden upstream to component suppliers.
Integrated tire-as-a-service contracts are displacing transactional spot purchasing in multi-site warehouse operations. Linde Material Handling and Jungheinrich are bundling tire replacement, pressure monitoring, and downtime guarantees into full-fleet maintenance agreements. This procurement consolidation is most visible in North American and Western European third-party logistics providers managing distributed fulfillment networks with standardized equipment pools.
Forklift Tire Market Segmentation
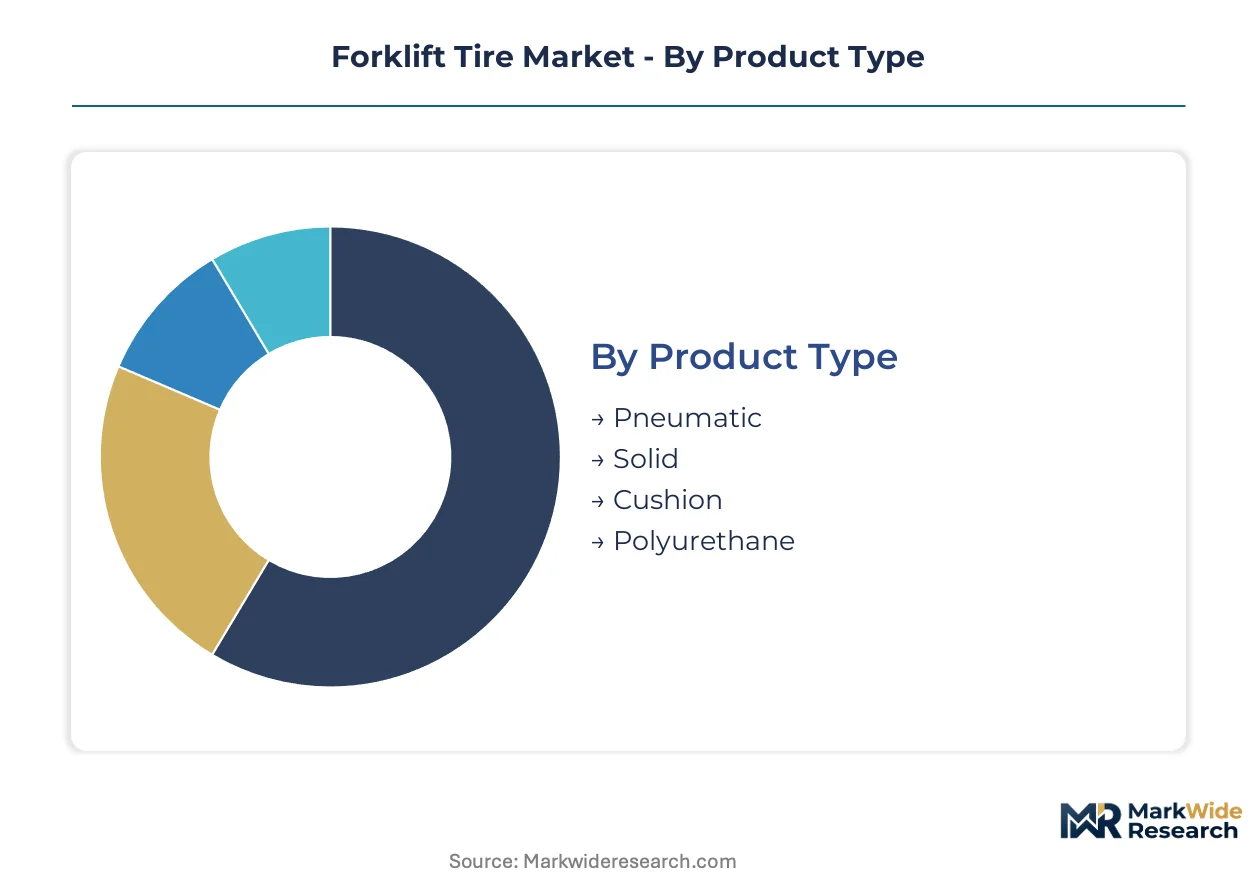
Forklift tire procurement divides sharply across operational environments, with each segment facing distinct substitution pressures from alternative compounds and construction methods. Fleet managers navigate trade-offs between puncture resistance, heat dissipation, and floor surface protection when specifying tire categories.
Product Type:
Pneumatic and solid tire categories face the strongest substitution pressure from polyurethane formulations in cleanroom and automated warehousing environments where floor marking creates liability exposure.
- Pneumatic:Air-filled rubber construction with reinforced sidewalls absorbs shock across uneven outdoor terrain. Demand concentrates at Port of Long Beach and Hamburg container terminals where reach stackers navigate rough asphalt and embedded debris under heavy lift cycles.
- Solid:Molded rubber compounds eliminate puncture risk entirely. German automotive parts distribution centers specify solid tires for three-shift operations running 22 hours daily, prioritizing zero-downtime reliability over ride comfort on smooth concrete.
- Cushion:Press-on band construction mounts directly to steel wheels for indoor counterbalance trucks. Taiwan semiconductor fabs favor cushion compounds for their lower rolling resistance and reduced battery drain in electric forklift fleets.
- Polyurethane:Cast elastomer formulations deliver non-marking floor contact with superior load distribution. South Korean pharmaceutical manufacturing facilities mandate polyurethane for epoxy-coated cleanrooms where carbon black residue triggers contamination protocols.
Solid retains volume leadership; polyurethane holds the steepest expansion curve.
Technology:
Cost tier stratification separates premium radial constructions from commodity bias-ply alternatives, with wire-ply and foam-filled options occupying intermediate positions based on heat management requirements.
- Radial:Steel belt packages arranged at 90 degrees to the direction of travel reduce heat buildup and extend tread life. Lumber yards in the Pacific Northwest specify radial tires for outdoor forklifts handling saturated loads where bias constructions overheat and delaminate.
- Bias Ply:Cross-ply nylon or polyester cords create stiff sidewalls resistant to impact damage. Indian third-party logistics warehouses continue specifying bias-ply for cost-sensitive operations running lower annual hour counts on standardized equipment.
- Wire Ply:Hybrid construction incorporating steel cables within traditional bias architecture. Brazilian sugar processing facilities use wire-ply tires for rough-terrain forklifts navigating crushed cane residue and embedded metal fragments.
- Foam Filled:Pneumatic casings injected with polyurethane foam eliminate flat risk while retaining some cushioning. Canadian mining supply depots specify foam-filled for outdoor yard trucks operating across gravel and frozen ground conditions.
Bias ply commands the largest installed base; radial is climbing the fastest as outdoor heavy-lift specifications tighten.
Application:
Application segmentation tracks directly to surface conditions and duty cycle intensity, with warehousing environments driving replacement frequency through continuous operation schedules.
- Warehousing:Smooth concrete surfaces and climate-controlled interiors favor solid and cushion compounds with optimized abrasion resistance. Amazon fulfillment centers in Poland and the Czech Republic standardize on polyurethane for automated storage and retrieval system aisles.
- Construction Sites:Aggregate surfaces, rebar exposure, and load variability demand puncture-proof solid tires with reinforced beads. UAE infrastructure projects specify heavy-duty solid tires for telehandlers and rough-terrain forklifts operating across sand and demolition debris.
- Manufacturing Facilities:Cleanroom protocols and just-in-time logistics create hybrid requirements combining non-marking surfaces with high-speed stability. German automotive assembly plants specify specialized tread compounds for tugger trains delivering sequenced parts to production lines.
- Shipping Yards:Container handling and intermodal transfer operations subject tires to extreme point loads and thermal cycling. Rotterdam port operators mandate radial tires for straddle carriers and reach stackers moving 40-ton containers across uneven pavement.
Warehousing generates the highest replacement volume; shipping yards impose the most demanding performance specifications.
End User:
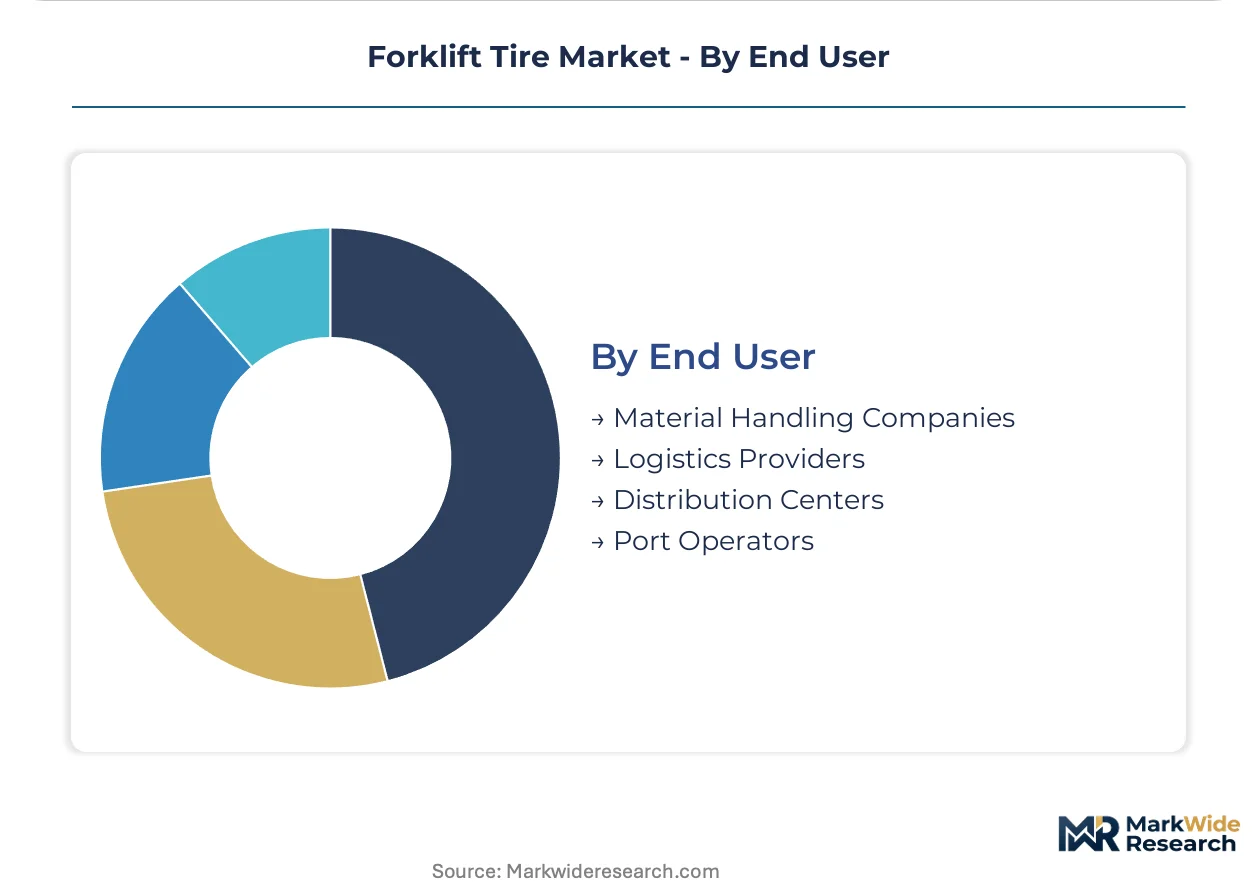
Customer type segmentation reveals divergent procurement sophistication, with multinational logistics providers consolidating tire-as-a-service contracts while independent operators retain transactional purchasing patterns.
- Material Handling Companies:Equipment rental and lease fleets require standardized tire specifications across mixed manufacturer chassis. United Rentals and Sunbelt specify cross-brand compatible cushion tires to simplify inventory management across North American branch networks.
- Logistics Providers:DHL Supply Chain and XPO Logistics negotiate enterprise tire agreements bundling replacement, monitoring, and downtime guarantees. Their procurement teams prioritize telematics-integrated pressure sensors for predictive maintenance across distributed fulfillment networks.
- Distribution Centers:Single-site operators with captive maintenance staff favor spot purchasing based on immediate availability. Regional grocery distribution centers in France and Italy maintain relationships with local tire dealers for same-day replacement during peak seasonal volume.
- Port Operators:Public and quasi-public entities face extended tender cycles with stringent technical specifications. Port Authority of New York and New Jersey requires ISO 3691-5 certification and full REACH material disclosure for all tire suppliers.
Logistics providers are consolidating procurement fastest; port operators maintain the most rigid qualification barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel cord supply chains and compound formulation expertise concentrate in East Asian metallurgical clusters and German chemical corridors. This geographic split shapes regional competitive dynamics and procurement risk profiles across material handling fleets.
United States
Amazon, Walmart, and regional logistics operators drive fleet replacement cycles to match same-day delivery velocity. OSHA workplace safety regulations govern tire integrity protocols in industrial environments. The Port of Long Beach and Chicago distribution corridors concentrate demand for heavy-duty radial constructions in container handling applications.
Germany
Automotive parts distribution centers specify solid tires for three-shift operations running 22 hours daily. ECHA REACH compliance mandates low-aromatic rubber compound formulations across European manufacturing. The Ruhr industrial basin and Bavarian logistics clusters prioritize heat-dissipating radial designs for automated storage and retrieval systems.
China
E-commerce fulfillment infrastructure expansion accelerates forklift fleet turnover in coastal manufacturing zones. GB standards and MIIT regulations shape industrial equipment safety specifications. The Yangtze River Delta and Pearl River Delta warehouse automation projects concentrate polyurethane tire demand for cleanroom manufacturing facilities.
India
PLI scheme incentives and GST harmonization accelerate organized retail and third-party logistics penetration. BIS certification requirements govern industrial tire quality standards. Maharashtra and Gujarat logistics corridors offer domestic manufacturers first-mover advantage before multinational brands establish localized compound production.
Japan
Semiconductor and pharmaceutical manufacturing facilities mandate non-marking polyurethane tires for epoxy-coated cleanrooms. METI industrial standards and JIS specifications influence material handling equipment procurement. The Kanto and Kansai industrial belts concentrate demand for specialized tread compounds in just-in-time logistics operations.
Forklift Tire Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the forklift tire landscape. Premium radial constructions with steel belt packages command position in outdoor heavy-lift segments, while commodity solid and cushion compounds dominate high-volume replacement cycles. The market structures around three archetypes: integrated rubber compounders with captive synthetic rubber supply, specialized industrial tire divisions of automotive majors, and regional fabricators serving price-sensitive fleet operators. Dominant competitive moves include backward integration into steel cord and synthetic rubber supply chains, plus geographic expansion through localized compound production facilities.
Among European-integrated compounders, Continental AG and Michelin exemplify technology-forward positioning through specialized tread formulations and R&D intensity. Bridgestone Corporation anchors the Asia-Pacific competitive stance through upstream control over synthetic rubber supply chains. These three players represent divergent strategic paths: compound specialization, vertical integration, and scale-driven cost architecture.
| Leading Market Players |
|---|
| Trelleborg AB |
| Hankook Tire & Technology |
| Michelin |
| Maxam Tire |
| Goodyear Tire & Rubber Company |
| Bridgestone Corporation |
| The Yokohama Rubber Co. Ltd. |
| Balkrishna Industries Limited |
| Continental AG |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between German automotive parts distributors and Continental AG lock in compound supply visibility while insulating buyers from Thai natural rubber price spikes. These agreements bundle volume commitments with REACH-compliant formulation guarantees, transferring regulatory compliance risk upstream to suppliers with certified low-PAH rubber capabilities.
Pricing Analysis
REACH chemical restrictions dictate the pricing tier structure across European procurement channels. Three-tier pricing structure across premium radial, standard solid, and economy bias-ply levels separates heat-dissipating steel-belt constructions from basic molded compounds. Certification to ISO 3691-5 stability protocols and full material disclosure documentation command measurable premiums in Port Authority tenders. Price erosion runs through economy bias-ply tiers as Indian domestic manufacturers expand capacity and compress replacement cycle margins. Fleet operators running depreciated cushion-tire chassis exhibit highest price sensitivity, while automated warehousing operators prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Malacca Strait transit underwrites steel cord delivery schedules from East Asian metallurgical clusters to European tire plants. High-tensile bead wire production concentrates in China, South Korea, and Japan, with synthetic rubber feedstocks anchored in Thai and Indonesian petrochemical corridors. Raw material dependencies span natural rubber latex, carbon black, and specialized curing agents subject to ECHA SVHC candidate list revisions. Single-source vulnerability in steel cord supply creates exposure to trade policy friction between major economies. Distribution runs through OEM captive service networks and independent tire dealers serving spot replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polyurethane formulations for cleanroom manufacturing present a substitution threat that rubber compounders must neutralize through performance differentiation and compliance bundling.
For Market Incumbents: Compound backward integration into synthetic rubber supply chains to capture margin compression from natural rubber volatility. Secure ISO 3691-5 certification ahead of extended validation timelines to lock out smaller competitors from public-sector fleet tenders. Defend against polyurethane encroachment by embedding telematics sensors for predictive replacement scheduling. For New Entrants and Emerging Players: BIS certification fast-track for domestic Indian manufacturers captures share before multinational brands establish localized compound production in Maharashtra and Gujarat logistics corridors. Target warehouse automation projects specifying non-marking floor contact for semiconductor fabs. Lead with tire-as-a-service subscription models to bypass capital-intensive spot purchasing relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among logistics providers bundling tire replacement, pressure monitoring, and downtime guarantees into full-fleet maintenance agreements. Five-to-ten year viability favors compounders with captive synthetic rubber supply and REACH-certified formulation expertise. Watch for ECHA SVHC list expansion signals that would accelerate fluoropolymer phaseouts and reward early reformulation investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Rubber | Bridgestone Corporation's upstream control insulates margin structure from Thai supply disruptions. |
| REACH-Compliant Compound Certification | Continental AG's low-PAH formulations unlock preferential access to German automotive procurement channels. |
| Telematics-Integrated Tire Monitoring | Linde Material Handling embeds IoT sensors enabling predictive replacement scheduling across distributed fleets. |
| Localized Production in India | Domestic manufacturers capture PLI scheme incentives before multinational brands establish compound facilities. |
| Retreadable Radial Design Investment | Early EU Green Deal certification creates differentiation in circular economy-mandated public tenders. |
Research Approach
A spread of perspectives from fleet maintenance directors, OEM procurement teams, tire compound R&D leads, and aftermarket service heads converged on the working assumptions driving replacement cycle forecasts. Primary fieldwork combined structured interviews with secondary validation against customs trade data, SEC 10-K filings, ECHA substance restriction updates, and industrial equipment registration databases. Bottom-up triangulation across product-type demand curves and top-down cross-checks against national forklift fleet statistics anchored volume estimates.
Segmentation dimensions modeled span product type, construction technology, application environment, and end-user procurement sophistication across the projection horizon. CAGRs derived from regression analysis of historical replacement frequencies against warehouse automation intensity indicators and regulatory compliance cost trajectories. Industry-specific inputs include REACH-mandated compound reformulation timelines and e-commerce fulfillment center buildout pipelines.
The analysis sits within stated boundaries; outcomes outside sustained warehouse automation investment and stable natural rubber supply conditions would require recalibration. Forecasts reflect documented assumptions regarding fleet turnover rates and chemical regulatory enforcement intensity. Practitioners should keep alternative scenarios live as ECHA SVHC candidate list expansions and East Asian trade policy developments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Wear Plates Market
Material Handling Equipment
Conveyor Scales Market
Material Handling Equipment
Electric Hoist Market
Material Handling Equipment
Europe Conveyor Belt Market
Material Handling Equipment
Europe Forklift Truck Market
Material Handling Equipment
Automated Material Handling Systems Market
Material Handling Equipment
Vibratory Feeder Machine Market
Material Handling Equipment
Overhead Hoist Transport (OHT) Market
Material Handling Equipment
Pipe Wrapping Machines Market
Material Handling Equipment
Manual Lifting Mobile Light Tower Market
Material Handling Equipment
Flux Spraying Machine Market
Material Handling Equipment
Conveying Equipment Market
Material Handling Equipment
Air Hose Market
Material Handling Equipment
Material Handling Automation Market
Material Handling Equipment
Hoist Market
Material Handling Equipment
High-Precision Gear Reducer Market