
 Europe Conveyor Belt Market | 2026-2036
Europe Conveyor Belt Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Conveyor Belt Market Intelligence
Subscription-based predictive maintenance services is rebalancing how conveyor belt value gets captured across Europe. Sempertrans leverages its integrated manufacturing footprint to control cost positions in heavy-duty mining applications. Habasit AG specializes in modular plastic belts for food-safe environments, sustaining premium positioning through Swiss-engineered hygiene standards. Forbo Siegling dominates lightweight conveyor solutions for airport baggage handling, extending its service network across Central European hubs.
A conveyor belt is a continuous moving band of fabric, rubber, metal, or polymer that transports materials or products along a predetermined path, typically rated by tensile strength, operating temperature range, and abrasion resistance measured in DIN or ISO standards. Its primary industrial purpose is to automate material flow, reduce manual handling labor, and synchronize production line speeds across manufacturing and distribution operations. Flat belts still occupy the largest installed base in European manufacturing, though modular belts are capturing faster growth in food processing where sanitation cycles demand frequent component replacement. Metal belts command the highest margin pools in heat-intensive applications such as bakery ovens and automotive paint curing lines.
REACH and the EU Green Deal are tightening chemical disclosure requirements for polymer-based belts, compelling reformulation of PVC and polyurethane compounds. CE marking under the Machinery Directive governs safety integration of automated conveyor systems, while Germany's KBA influences belt specifications in automotive assembly through vehicle-type approval standards. Stakeholders must monitor how the EU AI Act shapes liability frameworks for smart conveyor networks deploying sensor-based predictive analytics.
Market Dynamics
REACH chemical disclosure mandates are forcing wholesale reformulation of PVC and polyurethane belt compounds across European manufacturing, redrawing supplier qualification criteria and raw material sourcing patterns from the Ruhr to Lombardy.
Growth Catalysts
- Automated fulfillment expansion:German intralogistics operators are deploying sensor-integrated belt systems in high-throughput distribution centers, compressing order cycle times.
- EU Green Deal compliance:Lower-emission polymer formulations are unlocking preferential procurement status among sustainability-scored buyers in food processing.
- Heat-intensive manufacturing:Metal belt specifications for bakery ovens and automotive paint curing lines are capturing margin expansion in temperature-rated segments.
Market Restraints
- Petrochemical input volatility:Crude-derived synthetic rubber and thermoplastic elastomer costs swing with refinery capacity constraints in Rotterdam and Antwerp.
- Supplier concentration in heavy-duty mining:Integrated manufacturing footprints for steel-cord belting cluster in Central Europe, limiting buyer negotiation leverage.
- REACH registration timelines:ECHA substance evaluation delays extend new compound approval cycles, freezing product line refreshes.
Strategic Opportunities
- Eastern European manufacturing reshoring:Czech and Polish automotive assembly plants are localizing conveyor procurement to shorten spare parts lead times.
- Predictive maintenance services:Subscription-based vibration monitoring and belt-wear analytics are creating recurring revenue streams distinct from equipment sales.
- EU AI Act liability frameworks:Early compliance with smart conveyor network certification is positioning vendors for preferred supplier status in automated facilities.
Industry Challenges
- Polymer chemistry specialization:Formulating REACH-compliant compounds without sacrificing abrasion resistance requires scarce materials engineering expertise.
- Legacy system integration:Retrofitting Industry 4.0 sensors onto installed flat belt infrastructure demands custom mechanical adapters and extended commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Conveyor Belt Market |
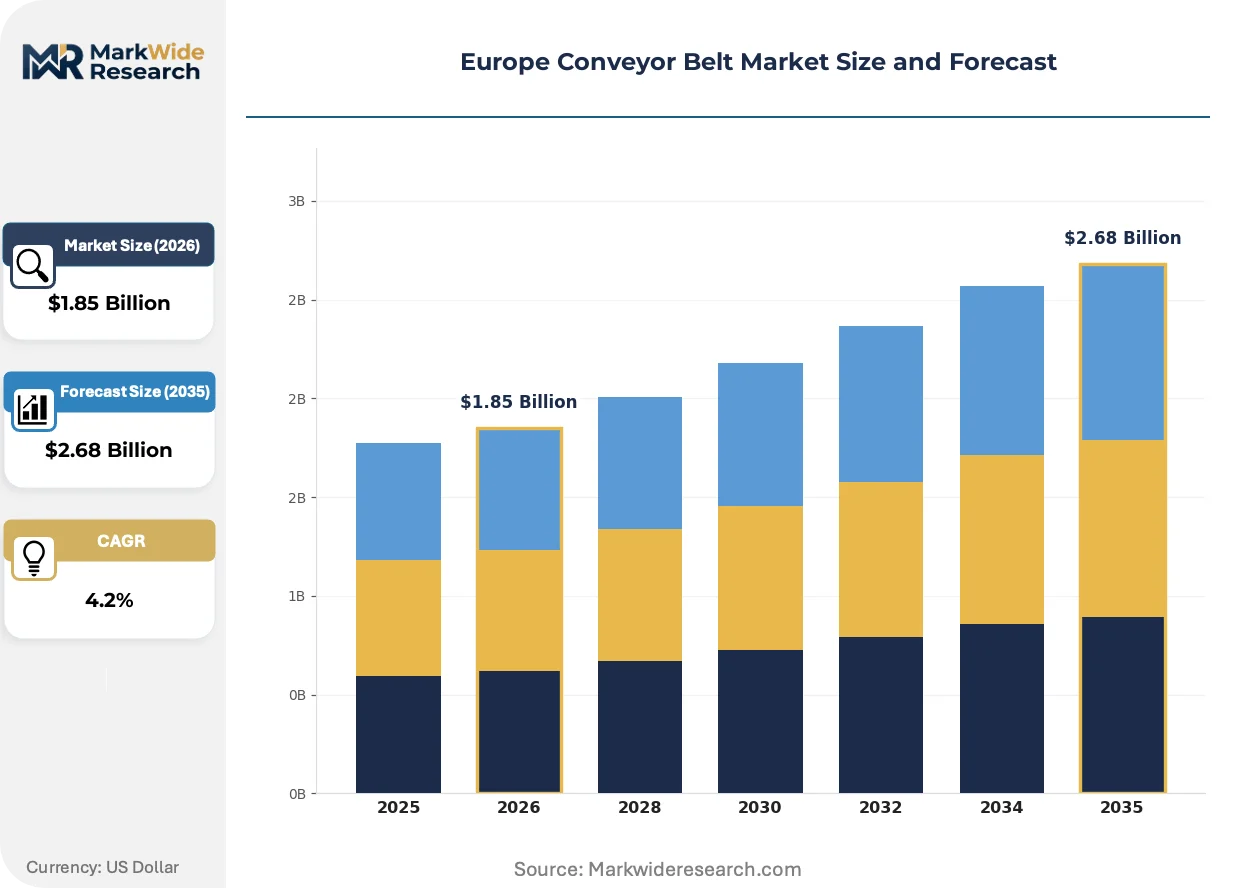
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.68 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Belt, Modular Belt, Curved Belt, Timing Belt Material: Polymer, Metal, Fabric, Rubber End User: Food & Beverage, Mining, Automotive, Retail Technology: Automated, Manual, Hybrid, Smart |
| Companies Covered | Sempertrans, Forbo Siegling, ContiTech, Fenner Group, Yokohama Rubber, Bridgestone Corporation, Habasit AG, Rulmeca Holding S.p.A., Fenner Dunlop, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Conveyor Belt Market Strategic Shifts & Innovations
Digitalization of belt condition monitoring and polymer chemistry advances are converging to transform how European manufacturers specify, procure, and maintain conveyor infrastructure across food, automotive, and logistics verticals.
Embedded fiber-optic strain sensing is rewriting predictive maintenance economics in high-value continuous processes. Chemical plants in the German industrial corridor are piloting real-time tension monitoring to eliminate unplanned shutdowns. The technology is compressing service contract structures from scheduled replacement toward usage-based performance guarantees.
REACH substance restriction proposals are accelerating bio-based polyurethane development for food-contact applications. ECHA evaluation of ortho-phthalates is forcing compounders to validate alternative plasticizers under migration testing protocols. Bakery and meat processing facilities in Northern Europe are prioritizing belts pre-certified for anticipated 2027 restriction lists.
Consolidated procurement by pan-European logistics operators is concentrating specification authority among fewer technical buyers. DHL and Kuehne+Nagel category managers are mandating unified belt standards across multi-country hub networks. Vendor qualification friction is highest in the Benelux corridor where cross-border service coverage determines contract awards.
Europe Conveyor Belt Market Segmentation
European conveyor belt procurement patterns diverge sharply across product architectures and end-use environments. Specification authority concentrates with technical buyers who weight replacement-cycle economics against compliance burdens in REACH-regulated polymer formulations.
Product Type:
Upgrade cycles vary dramatically by belt architecture, with sanitation-driven replacement in food processing compressing intervals versus heavy-duty mining installations running to fatigue limits.
- Flat Belt:Continuous woven or extruded surfaces dominate legacy manufacturing footprints across the German industrial corridor. Demand concentrates in automotive assembly plants from Stuttgart to Wolfsburg where synchronized line speeds require minimal stretch characteristics under DIN 22102 tensile specifications.
- Modular Belt:Interlocking plastic segments enable rapid component replacement without full belt removal. Food processing facilities in Northern Europe prioritize these configurations where EFSA hygiene mandates demand frequent sanitation cycles and component-level traceability.
- Curved Belt:Custom-fabricated radius configurations navigate spatial constraints in compact distribution centers. Benelux logistics hubs specify tight-turn solutions to maximize cubic utilization in automated fulfillment.
- Timing Belt:Positive-drive tooth profiles synchronize precision positioning in packaging machinery. Pharmaceutical serialization lines in Switzerland and Germany specify these for track-and-trace accuracy.
Volume placements concentrate in Flat Belt; the faster expansion belongs to Modular Belt.
Material:
Raw material selection directly determines compliance pathways under REACH substance restrictions and operating temperature envelopes.
- Polymer:PVC and polyurethane formulations face ECHA-driven reformulation pressure as ortho-phthalate evaluations advance. Food-contact applications in France and Germany are migrating toward bio-based polyols to preempt anticipated restriction lists.
- Metal:Stainless steel and carbon steel constructions withstand continuous heat exposure beyond 200°C. Bakery oven manufacturers in Austria and Italy specify metal belts where thermal cycling destroys polymer alternatives.
- Fabric:Multi-ply textile carcasses provide cost-efficient light-load transport. Eastern European textile belt production serves regional agricultural processing with shorter lead times than polymer imports.
- Rubber:Natural and synthetic rubber compounds retain dominance in abrasive material handling. Mining operations in Poland and the Czech Republic specify steel-cord rubber belts for ore transport durability.
Polymer captures the largest installed base; Metal commands the steepest expansion trajectory in heat-rated segments.
End User:
Industry-specific regulatory burdens and automation maturity reshape procurement criteria across vertical applications.
- Food & Beverage:EFSA migration limits and HACCP protocols drive belt specification toward certified food-contact materials. Dairy and meat processors in Denmark and the Netherlands prioritize pre-certified modular configurations to minimize validation overhead.
- Mining:Abrasion resistance and fire-safety ratings under EN 14973 govern underground specifications. Surface mining in Scandinavia and Central Europe demands steel-cord constructions with 10,000-hour service life guarantees.
- Automotive:KBA vehicle-type approval standards influence assembly line belt specifications. Paint shop curing lines require metal belts tolerant of sustained 180°C exposure during electrocoat baking.
- Retail:E-commerce fulfillment centers drive sensor-integrated belt deployments for sortation accuracy. German intralogistics operators specify automated systems with embedded strain monitoring to compress order cycle times.
Automotive maintains the deepest specification expertise; Retail is gaining share fastest through fulfillment automation.
Technology:
Integration complexity and capital intensity stratify adoption curves across facility automation maturity levels.
- Automated:Sensor-integrated drive systems enable synchronized speed control across distributed conveyor networks. High-throughput distribution centers in Germany and the Netherlands deploy these for sub-minute order processing.
- Manual:Basic motorized configurations persist in low-volume operations and legacy manufacturing. Smaller food processors in Southern Europe retain these where product variety resists full automation.
- Hybrid:Segmented automation allows selective mechanization of high-labor intensity zones. Regional logistics operators pilot these to balance capital constraints against throughput targets.
- Smart:Predictive analytics platforms process vibration and temperature data for usage-based maintenance. Chemical plants in the Ruhr corridor pilot fiber-optic strain sensing to eliminate unplanned shutdowns.
Manual systems retain volume dominance in fragmented manufacturing; Smart configurations are climbing the fastest as EU AI Act liability frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European conveyor belt production concentrates in Central European manufacturing clusters while consumption spreads across automated logistics corridors from the Ruhr to Lombardy. This geographic split shapes procurement patterns and service network investments.
Germany
Automotive assembly plants in Stuttgart and Wolfsburg drive precision flat belt specifications under KBA vehicle-type approval standards. REACH compliance mandates from ECHA are accelerating reformulation of polyurethane compounds in the Ruhr industrial corridor. Intralogistics operators across Bavaria deploy sensor-integrated belt systems in high-throughput fulfillment centers.
Italy
Metal belt demand from bakery oven manufacturers in Milan and Turin sustains premium heat-rated segments. EFSA migration limits are pushing compounders toward bio-based polyol validation for food-contact applications. The Emilia-Romagna packaging machinery cluster specifies timing belts for pharmaceutical serialization accuracy.
France
Dairy and meat processors in Brittany and Normandy prioritize modular belt configurations to minimize HACCP validation overhead. The EU Green Deal is unlocking preferential procurement status for lower-emission polymer formulations among sustainability-scored buyers. Lyon-based chemical plants pilot fiber-optic strain sensing for predictive maintenance.
Poland
Surface mining operations in Silesia specify steel-cord rubber belts for ore transport durability under EN 14973 fire-safety ratings. Automotive assembly reshoring from Czech and Slovak plants is localizing conveyor procurement to shorten spare parts lead times. Warsaw distribution hubs deploy curved belt solutions for cubic utilization in compact facilities.
Netherlands
Benelux logistics corridors concentrate specification authority among pan-European operators mandating unified belt standards across multi-country hub networks. Cross-border service coverage determines contract awards in Rotterdam and Antwerp port zones. Petrochemical input volatility from regional refinery capacity constraints is pressuring synthetic rubber cost positions.
Europe Conveyor Belt Market Key Industry Players
Top-tier vendors anchor integrated manufacturing footprints for heavy-duty applications, while specialized fabricators occupy niche hygiene and precision segments. The vendor base stratifies across three tiers: multinational polymer compounders with captive steel-cord capacity, Swiss-engineered modular specialists, and regional service-intensive distributors. Strategic archetypes include vertical integration defenders, premium hygiene certifiers, and predictive maintenance platform builders. Competitive moves center on M&A for geographic coverage expansion and technology licensing for smart conveyor network certification.
Within the premium-tier vector, Sempertrans and Forbo Siegling occupy positions exemplifying integrated manufacturing control and lightweight solution dominance respectively. Habasit AG represents the Swiss-engineered modular specialist archetype, anchoring food-safe environment positioning through hygiene certification depth. These three names illustrate how geographic origin and corporate structure suffixes map to distinct competitive vectors across the European landscape.
| Leading Market Players |
|---|
| Sempertrans |
| Forbo Siegling |
| ContiTech |
| Fenner Group |
| Yokohama Rubber |
| Bridgestone Corporation |
| Habasit AG |
| Rulmeca Holding S.p.A. |
| Fenner Dunlop |
| Others |
Cost & Logistics Intelligence
Rotterdam-sourced synthetic rubber price indices cascade through European conveyor belt manufacturing, compressing margins in standard-grade polymer formulations while steel-cord heavy-duty tiers absorb volatility through captive compounder relationships. REACH registration timelines freeze new product introductions, concentrating pricing power among incumbent compounders with validated substance portfolios.
Pricing Analysis
Margin tightening in standard polymer tiers reflects ortho-phthalate reformulation costs and ECHA substance evaluation delays. Three-tier pricing structure across premium certified, standard industrial, and economy textile-reinforced levels separates buyers by compliance burden and temperature rating. Cost-down pressure on PVC formulations accelerates as sustainability-scored procurement mandates spread through German food processing. Retail fulfillment operators show highest price sensitivity, while automotive paint shop specifications tolerate premium positioning for metal belt heat tolerance.
Supply Chain Analysis
Freight cost volatility from Rotterdam-Antwerp petrochemical corridors shapes raw material sourcing economics for compounders across the Ruhr and Lombardy. Manufacturing gravity centers on Germany, Italy, and Poland for steel-cord capacity, polymer extrusion, and textile carcass production respectively. Supply chains draw from crude-derived synthetic rubber, stainless steel strip, and high-tenacity polyester yarn. Single-source vulnerability concentrates in specialty polyurethane formulations validated for EFSA food-contact migration limits. Distribution runs through regional service-intensive distributors with cross-border coverage mandates in the Benelux corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European conveyor belt supply is tightening around REACH-compliant compound capacity, with ECHA substance evaluation queues extending qualification timelines and propping pricing for validated manufacturers.
For Market Incumbents: Deploy predictive maintenance platform investments to capture recurring revenue streams distinct from equipment sales. Sempertrans and Habasit AG should deepen backward integration into polymer compounding to defend margin positions against petrochemical input volatility. Consolidate service network density in the Czech-Polish automotive reshoring corridor before regional distributors establish cross-border coverage. For New Entrants and Emerging Players: Mid-sized dairy processors in Southern Europe represent an underserved buyer archetype seeking modular belt configurations with shorter validation cycles than Northern European hygiene mandates require. Bio-based polyurethane compounders can capture preferential procurement status among sustainability-scored French food processors ahead of anticipated 2027 restriction lists. Partner with regional textile belt producers in Eastern Europe to leverage shorter lead times against polymer import dependencies. For Investors and Strategic Acquirers: Distressed-cycle entries favor Swiss-engineered modular specialists with EFSA pre-certification depth in Northern European food processing clusters. Long-term viability hinges on smart conveyor network certification readiness as EU AI Act liability frameworks mature. Monitor ECHA substance restriction proposal advancement as inflection signal for bio-based compounder valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Compound Reformulation | ECHA-driven reformulation secures preferential procurement status among sustainability-scored German food processors. |
| Predictive Maintenance Platform Launch | Subscription-based vibration monitoring creates recurring revenue streams distinct from equipment sales in Ruhr chemical plants. |
| Smart Conveyor Network Certification | EU AI Act early compliance positions vendors for preferred supplier status in automated German fulfillment centers. |
| Eastern European Service Network Expansion | Cross-border coverage in Czech-Polish automotive corridors shortens spare parts lead times against incumbent distributors. |
| Bio-Based Polyol Validation Investment | Pre-certification for anticipated ECHA restriction lists captures premium positioning in French dairy processing. |
Research Approach
Independent corroboration across maintenance directors at German automotive assembly plants, procurement leads at Benelux logistics operators, and technical R&D directors at polymer compounders underwrites the qualitative findings. Secondary validation draws from ECHA substance registration databases, EU customs trade data for rubber and polymer imports, and SEC filings of listed belting manufacturers. Bottom-up installation base estimates and top-down industrial production indices triangulate market sizing across product architectures.
Comparable-period anchoring to historical replacement cycles in food processing and mining verticals shaped the projection horizon. The analytical framework segments by belt architecture, material composition, end-use industry, and automation technology tier across the modeling period. CAGRs derive from regression against industrial production indices, intralogistics capital expenditure trajectories, and REACH compliance cost pass-through assumptions. Heat-intensive manufacturing expansion and sensor-integrated fulfillment automation serve as primary demand-side forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA substance restriction timelines and EU AI Act certification implementation. Forecasts reflect documented assumptions regarding polymer reformulation cost trajectories and automotive reshoring velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Hi Lift Jack Market
Material Handling Equipment
Freight Elevators Market
Material Handling Equipment
Heavy Duty Ramp Market
Material Handling Equipment
Flux Spraying Machine Market
Material Handling Equipment
Coal Handling Equipment Market
Material Handling Equipment
Lever Hoist Market
Material Handling Equipment
Global Loading Dock Lifts Market
Material Handling Equipment
Autonomous Warehouse Equipment Market
Material Handling Equipment
Portable Forklift Ramps Market
Material Handling Equipment
Global Mechanical Seals Market
Material Handling Equipment
Container Handler Market
Material Handling Equipment
Precision Gearbox Machinery Market
Material Handling Equipment
Swivel Coupler Market
Material Handling Equipment
Autonomous Material Handling Equipment Market
Material Handling Equipment
Hydraulic Seals Market
Material Handling Equipment
Air Classifying Mill Market