
 Mobile Crane Market | 2026-2036
Mobile Crane Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Crane Market Intelligence
Heavy-lift capacity tier upgrades above 500-tonne ratings is collapsing the boundary between traditional mobile cranes and dedicated crawler systems. Liebherr Group leverages its in-house component production to control lead times on super-lift configurations. Tadano Ltd. anchors its position through all-terrain specialization and precision load-moment systems. XCMG Construction Machinery Co., Ltd. competes on manufacturing scale and cost-engineered rough-terrain platforms for developing markets.
Mobile cranes are self-propelled lifting machines mounted on wheeled or crawler undercarriages, rated by maximum load capacity, boom length, and working radius, designed to transport heavy materials across job sites without external assembly. The primary industrial purpose centers on vertical and horizontal material placement where fixed tower cranes lack mobility or setup time is prohibitive. All-terrain and rough-terrain product types command premium positioning due to their dual highway and off-road capability, while crawler cranes dominate margin pools in wind-energy and heavy infrastructure applications where stability requirements override transit speed. Hydraulic technology still leads installed base volumes, though electric drivetrains are gaining fastest in urban construction zones with emissions restrictions.
OSHA crane safety standards in the United States, the EU Machinery Directive with CE marking requirements in Europe, and China's GB standards enforced by SAMR collectively dictate operator certification, load-testing protocols, and manufacturing compliance across major supply destinations. These frameworks raise entry barriers for uncertified producers while steering procurement toward established OEMs with documented conformity assessment. Stakeholders must monitor how emerging battery-electric lifting systems interface with evolving grid infrastructure and site-power availability before committing capital to next-generation fleet configurations.
Market Dynamics
Emissions compliance deadlines in the European Union and select US states are compressing fleet replacement cycles while simultaneously elevating electric drivetrain R&D spend, forcing manufacturers to absorb dual development costs for parallel ICE and battery-electric platforms.
Growth Catalysts
- Urban construction density:Megacity vertical build-out in Mumbai, São Paulo, and Lagos generates demand for compact all-terrain units capable of highway transit and confined-site operation without disassembly.
- EU Machinery Directive enforcement:CE marking requirements for load-moment indicators and anti-two-block systems are mandating control-system upgrades across European fleets, pulling forward replacement demand.
- Wind turbine scaling:Nacelle weights exceeding 15 tonnes and hub heights above 150 meters require crawler crane mobilization for both onshore and offshore installation phases.
Market Restraints
- High-strength steel plate volatility:Boom and mast fabrication depends on quenched-and-tempered alloy grades subject to energy-intensive production constraints and tariff exposure.
- Hydraulic component supply concentration:Precision piston pumps and proportional valves for super-lift systems source predominantly from German and Japanese specialist suppliers.
- Site power infrastructure gaps:Battery-electric crane deployment requires megawatt-scale charging or battery swap logistics that most construction sites lack, limiting addressable market for zero-emission units.
Strategic Opportunities
- India infrastructure pipeline:National highway expansion, metro rail construction, and renewable energy auctions create sustained demand for rough-terrain and truck-mounted units across tier-2 and tier-3 cities.
- Telematics-enabled predictive maintenance:Integration of load-cycle data with hydraulic oil analysis and structural strain monitoring allows OEMs to capture recurring service revenue.
- US Inflation Reduction Act credits:Domestic content bonuses and clean energy manufacturing incentives reduce effective cost for battery-electric crane production sited in qualifying facilities.
Industry Challenges
- Certified operator scarcity:OSHA crane operator certification requirements and state-level licensing create bottlenecks for fleet expansion, particularly for lattice-boom crawler classifications.
- Dual-platform engineering overhead:Simultaneous ICE and electric product development strains R&D allocation and complicates supplier qualification.
- Legacy fleet integration:Telematics retrofit and safety-system upgrades for aging hydraulic units face cost-justification barriers against outright replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Crane Market |
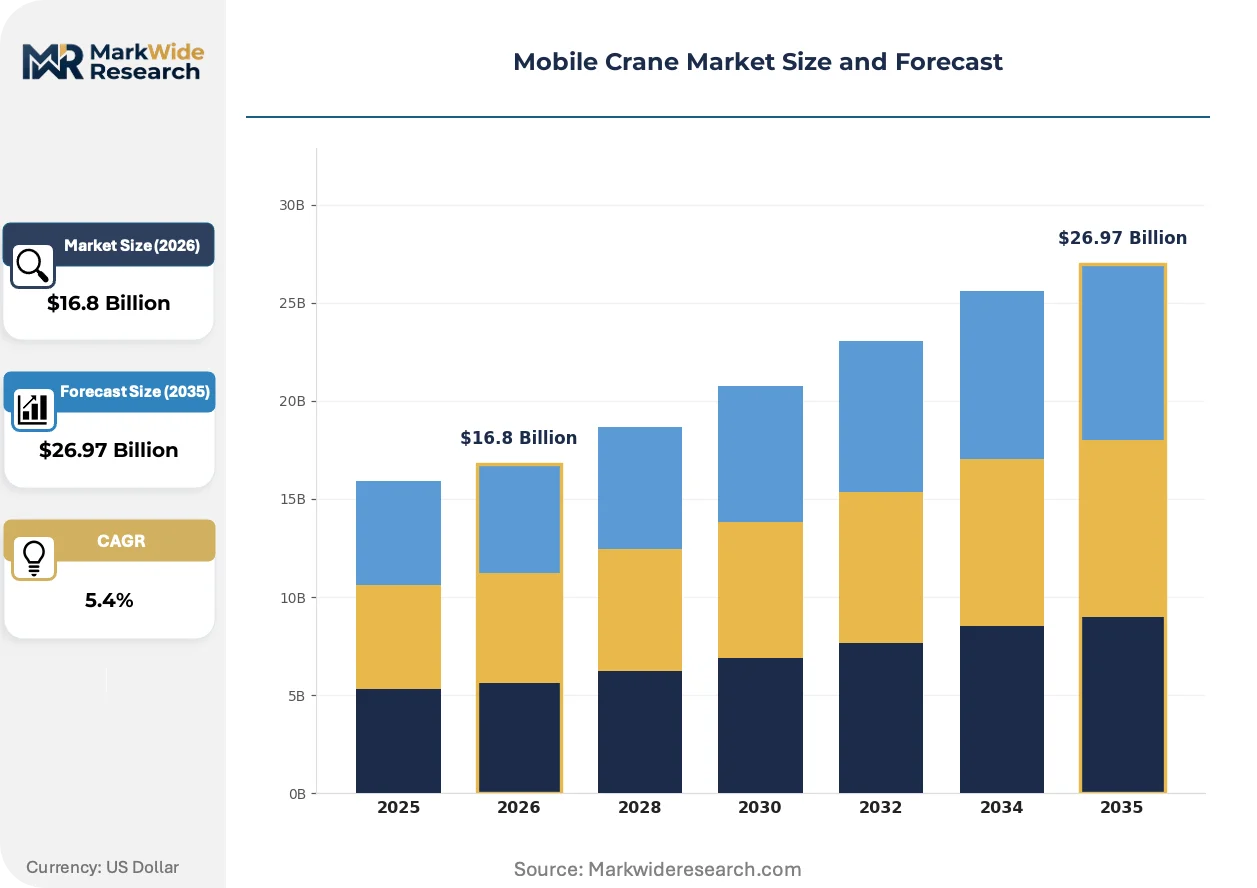
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $26.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Truck-Mounted, Crawler, Rough Terrain, All Terrain End User: Construction, Mining, Shipping, Oil & Gas Application: Heavy Lifting, Material Handling, Infrastructure Development, Demolition Technology: Hydraulic, Electric, Pneumatic, Mechanical |
| Companies Covered | Liebherr Group, Terex Corporation, Tadano Ltd., XCMG Construction Machinery Co., Ltd., Sany Heavy Industry Co., Ltd., KATO WORKS CO., LTD., Kobelco Construction Machinery Co., Ltd., Zoomlion Heavy Industry Science and Technology Co., Ltd., The Manitowoc Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Crane Market Strategic Shifts & Innovations
Electrification, autonomy, and data-centric service models are converging to redefine crane ownership economics and reshape competitive differentiation around total cost of ownership rather than upfront capital outlay.
Battery-electric drivetrain development is bifurcating the product roadmap. Urban construction contractors in emissions-restricted zones are piloting 50-100 tonne electric all-terrain units with onboard energy storage sufficient for full-shift operation. This technology is bifurcating the market into highway-capable electric platforms for municipal work and conventional diesel crawlers for remote heavy-lift applications where grid access is nonexistent.
OSHA's updated crane operator qualification requirements and the EU Machinery Directive's expanded conformity assessment procedures are tightening documentation burdens. Manufacturers must now supply third-party-verified structural calculations and software validation for load-moment limiters. Rough-terrain and all-terrain segments face the steepest compliance cost escalation due to their higher unit volumes and model proliferation.
Rental fleet operators are consolidating procurement decisions around lifecycle cost metrics rather than acquisition price. Major equipment lessors in the United States and Germany now specify telematics integration and predictive maintenance clauses in multi-year supply agreements. Wind energy contractors exhibit the most pronounced preference shift, bundling crane provision with specialized rigging and transport services under single-source contracts.
Mobile Crane Market Segmentation
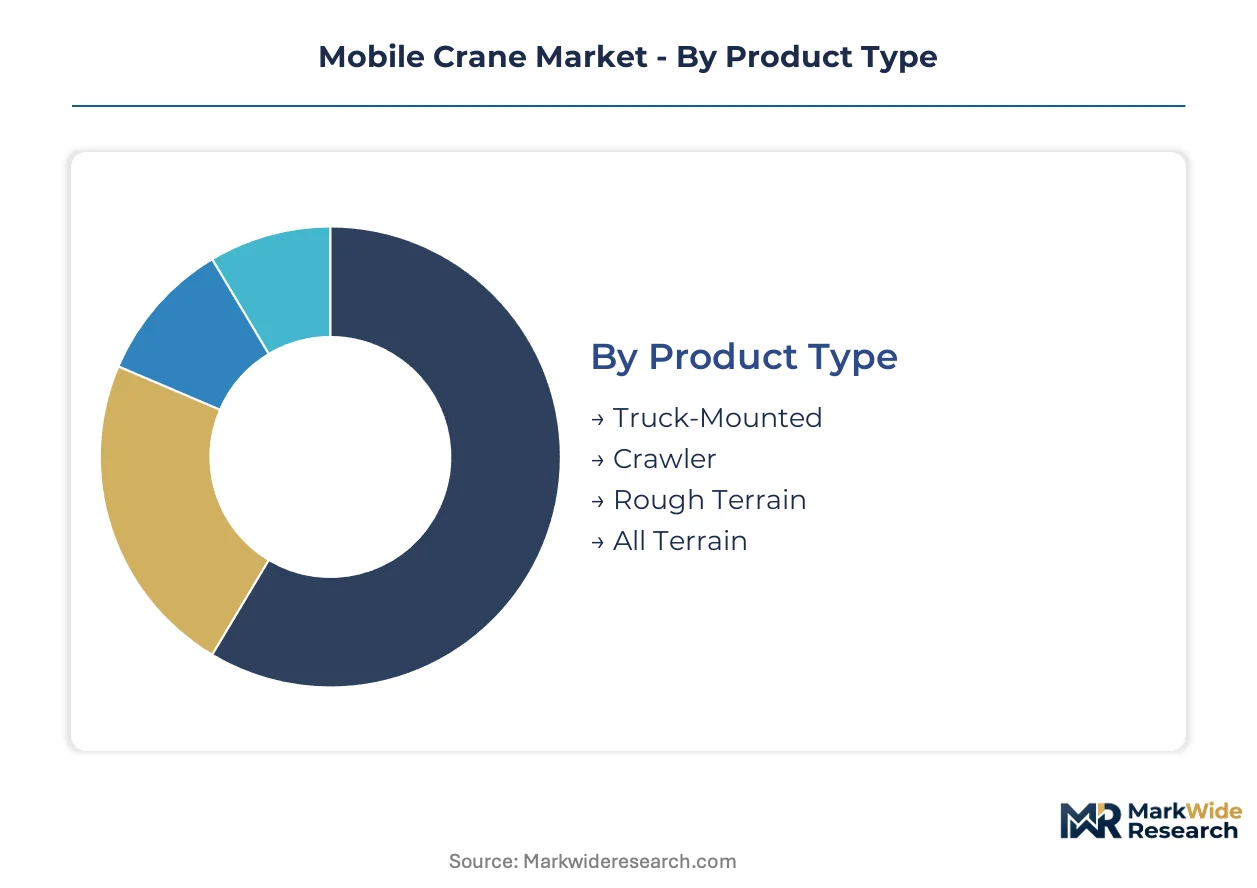
Mobile crane procurement channels diverge sharply by segment—rental fleets dominate all-terrain and rough-terrain volumes, while project contractors direct-purchase crawler units for dedicated infrastructure assignments. Understanding these channel-segment pairings clarifies where OEMs must build distribution partnerships versus direct sales capabilities.
Product Type:
Rental yards and construction equipment lessors stock disproportionately toward highway-mobile categories, whereas energy and infrastructure contractors acquire crawler systems through direct manufacturer relationships.
- All Terrain:Dual-axle highway capability combined with multi-axle steering delivers rapid site-to-site transit without disassembly. Demand clusters in German and French urban renewal zones where emissions zones restrict diesel access and contractors require same-day repositioning between municipal projects.
- Crawler:Lattice or telescopic boom configurations mounted on tracked undercarriages provide stability for lifts exceeding 500 tonnes. Wind farm developers in Texas and offshore fabrication yards in South Korea anchor procurement volumes as turbine nacelle weights climb past 15-tonne thresholds.
- Rough Terrain:Compact outrigger-equipped units with single-cab operation excel on undeveloped sites lacking paved access.
- Truck-Mounted:Highway-legal boom trucks serve utility maintenance and light commercial construction through rapid deployment.
All-terrain units dominate installed base. Crawler configurations represent where expansion concentrates.
End User:
Cost tier segmentation separates premium-specification units for hazardous environment deployment from standardized fleets for general construction.
- Construction:General building contractors and specialty trade contractors constitute the volume tier, sourcing primarily through rental channels for project-specific deployment. Indian metro rail expansion and Brazilian affordable housing programs sustain rough-terrain and truck-mounted demand.
- Oil & Gas:Refinery turnaround contractors and offshore platform service providers require explosion-proof electrical systems and API-certified lifting configurations. North Sea decommissioning activity and Middle East petrochemical expansion anchor premium pricing tiers.
- Mining:Open-pit and underground extraction operations utilize modified rough-terrain units with reinforced booms for abrasive environments.
- Shipping:Port terminal operators and shipyard riggers deploy heavy-lift crawlers for vessel section assembly and container crane maintenance.
Construction commands installed base volumes. Oil & gas represents where margin expansion concentrates.
Application:
Application-driven specification requirements determine whether units deploy through spot rental, long-term lease, or capital purchase channels.
- Infrastructure Development:Bridge segment placement, railway construction, and power transmission line erection demand precision load-moment systems with certified operators. Chinese high-speed rail corridors and Indian national highway widening sustain crawler and all-terrain procurement through state-backed contractors.
- Heavy Lifting:Industrial plant relocation, power generation component installation, and modular construction module placement require capacity-rated configurations with engineered lift plans. German chemical plant upgrades and US data center construction drive super-lift specification demand.
- Material Handling:General freight movement and precast component positioning utilize standardized truck-mounted and rough-terrain fleets.
- Demolition:High-reach configurations with reinforced cabs and debris protection attachments serve building decommissioning contractors.
Material handling dominates fleet counts. Infrastructure development is climbing the fastest.
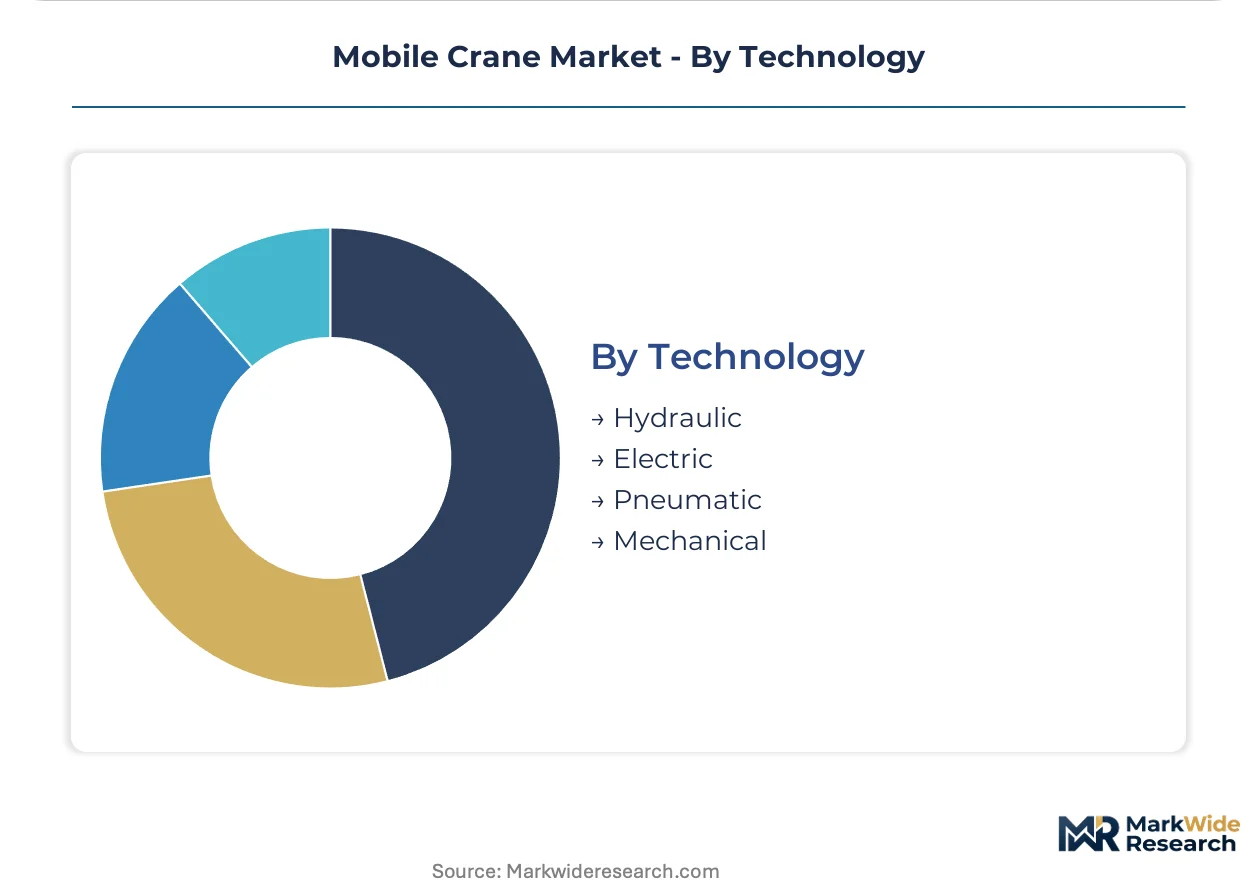
Technology:
Technology maturity curves separate established hydraulic installed bases from emerging electric penetration in regulated urban environments.
- Hydraulic:Axial piston pumps and proportional valve control systems deliver established performance across load ratings from 20 to 1,000+ tonnes. Chinese and Indian domestic manufacturers compete aggressively on cost-engineered hydraulic platforms for developing market price sensitivity.
- Electric:Battery-electric drivetrains with onboard energy storage and regenerative lowering systems enable zero-emission operation in municipal construction zones. European Union emissions compliance deadlines and California Air Resources Board regulations accelerate pilot deployments in Paris, Amsterdam, and Los Angeles urban cores.
- Pneumatic:Compressed-air actuation serves specialized hazardous environment applications with spark-resistant requirements.
- Mechanical:Gear and clutch systems persist in legacy fleet maintenance and developing market basic configurations.
Hydraulic systems anchor installed base. Electric drivetrains represent where R&D investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component fabrication for super-lift configurations clusters in Germany and Japan, while final assembly scales concentrate in China and the United States. Fleet procurement patterns diverge sharply between emissions-regulated urban zones and remote heavy-lift sites lacking grid infrastructure.
United States
Wind farm developers in Texas and Oklahoma anchor crawler crane demand as turbine nacelle weights exceed 15-tonne thresholds. OSHA crane operator certification requirements and state-level licensing create bottlenecks for fleet expansion, particularly for lattice-boom classifications. Houston and Corpus Christi serve as Gulf Coast heavy-lift hubs where petrochemical turnaround contractors deploy explosion-proof configurations.
Germany
Urban renewal zones in Berlin and Hamburg drive compact all-terrain procurement where emissions zones restrict diesel access. The EU Machinery Directive with CE marking requirements mandates load-moment indicator upgrades across European fleets, pulling forward replacement demand. Baden-Württemberg hosts specialized hydraulic component suppliers serving super-lift system integrators.
China
High-speed rail corridor construction and metro rail expansion in tier-2 cities sustain rough-terrain and truck-mounted volumes. GB standards enforced by SAMR dictate manufacturing compliance and operator certification protocols across domestic supply chains. Xuzhou and Changzhou anchor manufacturing clusters where cost-engineered platforms compete aggressively on price sensitivity.
India
National highway widening and renewable energy auctions create sustained demand across tier-2 and tier-3 urban construction zones. The Ministry of Road Transport and Highways infrastructure pipeline directs state-backed contractor procurement toward fleet renewal cycles. Mumbai and Delhi-NCR concentrate rental fleet operations serving megacity vertical build-out projects.
Japan
Offshore fabrication yards in Nagasaki and Yokohama require heavy-lift crawlers for vessel section assembly and wind turbine component staging. METI industrial standards govern precision load-moment system certification and structural validation requirements. Kansai region manufacturers specialize in all-terrain units with highway-transit optimization for confined-site operation.
Mobile Crane Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. European and Japanese manufacturers anchor premium positioning through in-house component production and precision control systems, while Chinese producers compete on manufacturing scale and cost-engineered platforms for developing markets. Three archetypes dominate: vertically integrated super-lift specialists, all-terrain precision manufacturers, and scale-driven rough-terrain fabricators. Competitive moves concentrate on dual-platform engineering for parallel ICE and electric development, plus telematics integration for predictive maintenance revenue capture.
Among German-based integrated manufacturers, Liebherr Group exemplifies the super-lift specialist archetype through captive supply of critical components. Tadano Ltd. represents Japanese precision engineering in all-terrain configurations. XCMG Construction Machinery Co., Ltd. occupies the scale-driven position serving cost-sensitive developing market demand.
| Leading Market Players |
|---|
| Liebherr Group |
| Terex Corporation |
| Tadano Ltd. |
| XCMG Construction Machinery Co., Ltd. |
| Sany Heavy Industry Co., Ltd. |
| KATO WORKS CO., LTD. |
| Kobelco Construction Machinery Co., Ltd. |
| Zoomlion Heavy Industry Science and Technology Co., Ltd. |
| The Manitowoc Company, Inc. |
| Others |
Cost & Logistics Intelligence
High-strength steel plate substitution for conventional alloy grades is redrawing supplier geography toward energy-intensive production regions while compressing margin structures for boom and mast fabricators. This input shift simultaneously elevates procurement risk for quenched-and-tempered grades and forces OEMs to absorb volatility through long-term offtake contracts or captive rolling capacity.
Pricing Analysis
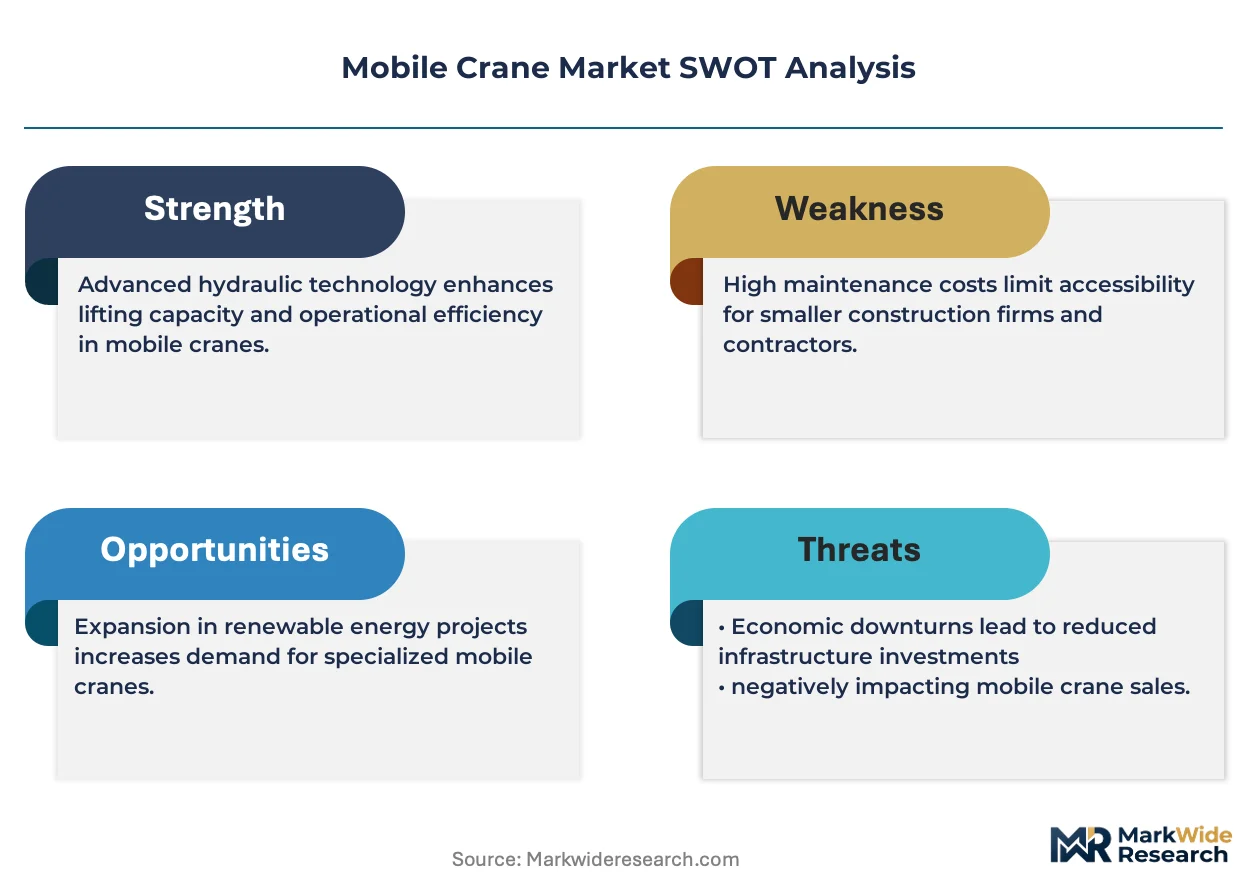
The EU Machinery Directive with CE marking requirements dictates the pricing tier structure across European mobile crane procurement. Three-tier pricing structure across premium, standard, and economy levels separates super-lift crawler configurations with certified load-moment systems from cost-engineered rough-terrain platforms for developing markets. Pricing pressure stems from dual-platform engineering overhead as manufacturers sustain parallel ICE and electric development programs. Rental fleet operators exhibit the highest price sensitivity due to lifecycle cost scrutiny, while wind energy contractors accept premium positioning for specialized heavy-lift capability.
Supply Chain Analysis
Inventory buffers for precision hydraulic components extend lead times beyond six months for super-lift system integrators. Component fabrication clusters in Germany and Japan for axial piston pumps and proportional valves, while final assembly scales concentrate in China and the United States. Boom fabrication draws from quenched-and-tempered steel plate subject to tariff exposure and energy-intensive production constraints. Single-source vulnerability persists for German and Japanese hydraulic specialists. Distribution runs through rental fleet operators for highway-mobile categories and direct manufacturer relationships for crawler systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile crane demand is recovering through infrastructure investment cycles in emerging economies, with fleet renewal timing tied to emissions compliance deadlines in regulated markets.
For Market Incumbents: Shield margin position by deepening captive supply of critical hydraulic components and securing long-term steel plate offtake agreements. Accelerate telematics platform development to capture recurring service revenue as rental operators consolidate procurement around lifecycle cost metrics. Battery-electric R&D spend pressure from EU and California regulations threatens near-term profitability without offsetting service income. For New Entrants and Emerging Players: Aftermarket telematics retrofit and predictive maintenance services for aging hydraulic fleets present immediate white-space opportunity where established OEMs under-serve cost-constrained operators. Target tier-2 and tier-3 Indian cities for rough-terrain unit distribution through state-backed contractor relationships. Pursue partnership-based go-to-market models with regional rental fleet consolidators rather than direct sales infrastructure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed rental fleet operators holding aging all-terrain units requiring replacement timing assessment. Long-term viability centers on electrification readiness and telematics integration capability rather than manufacturing scale alone. Monitor California Air Resources Board enforcement patterns and EU Machinery Directive implementation timelines as inflection indicators for electric platform adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Platform Engineering Investment | Parallel ICE and electric development programs satisfy EU emissions deadlines and California CARB requirements. |
| Telematics Integration Partnership | Load-cycle data capture enables predictive maintenance revenue from US and German rental fleet operators. |
| Steel Plate Supply Agreement | Long-term offtake contracts with German and Japanese mills hedge quenched-and-tempered grade volatility. |
| India Distribution Expansion | State-backed contractor relationships in tier-2 cities access national highway and metro rail construction pipelines. |
| Operator Certification Program | OSHA-compliant training infrastructure addresses certified operator scarcity constraining US fleet expansion. |
Research Approach
A standing panel of rental fleet procurement directors, plant maintenance engineers, OEM sales executives, and aftermarket service managers provided ongoing calibration across the research program. Primary interview data combined with customs trade records, SEC equipment manufacturer filings, and EU Machinery Directive compliance databases. Bottom-up unit demand modeling triangulated against top-down infrastructure investment forecasts.
Consistency checks validated volume and value outputs against wind turbine installation pipelines, petrochemical turnaround schedules, and metro rail construction databases across the projection horizon. Segmentation modeling captured product type, end-use industry, application, and technology maturity dimensions. CAGRs derived from historical replacement cycles, fleet age distributions, and emissions regulatory phase-in schedules.
Forecasts assume regulatory continuity in EU Machinery Directive enforcement and OSHA certification requirements; material policy shifts would require re-modeling. Supply chain disruptions from steel plate tariffs or hydraulic component export restrictions could revise procurement timing assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Vibrating Feed Conveyors Market
Material Handling Equipment
Middle East and Africa Conveyors Market
Material Handling Equipment
Rotating Fork Clamp Market
Material Handling Equipment
Centrifugal Industrial Dryer Market
Material Handling Equipment
Compaction Machines Market
Material Handling Equipment
High-Performance Seals Market
Material Handling Equipment
Heavy Hex Nuts Market
Material Handling Equipment
Drum Dumper Market
Material Handling Equipment
Industrial Mezzanines Market
Material Handling Equipment
Asia-Pacific Forklift Rental Market
Material Handling Equipment
Pallet Circulation System Market
Material Handling Equipment
Steel Coil Handling Equipment Market
Material Handling Equipment
Outdoor Power Equipment (OPE) Market
Material Handling Equipment
Ship Loader and Unloader Market
Material Handling Equipment
Forklift Truck Market
Material Handling Equipment
Wagon Tipplers Market