
 Hoist Controller Market | 2026-2036
Hoist Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Hoist Controller Market Intelligence
Aftermarket service revenue is reconfiguring margin pools away from pure hardware sales across the hoist controller supply chain. Schneider Electric leverages its global service network to capture recurring maintenance contracts. Conductix-Wampfler anchors its position through integrated festoon and conductor bar systems paired with controller retrofit programs. Magnetek specializes in digital radio remote controls that extend into predictive diagnostics for crane fleets.
A hoist controller governs the acceleration, deceleration, lifting direction, and load positioning of electric overhead cranes and hoists through contactor logic, variable frequency drives, or programmable automation controllers rated for continuous-duty cycles. Its primary industrial purpose centers on eliminating uncontrolled load swing while protecting mechanical brake systems from thermal overload. Inverter controllers now dominate new installations where precise speed modulation replaces legacy contactor-based staging across manufacturing plants and ports. Microprocessor-based technology captures the fastest expansion as embedded load-cell integration enables real-time overload cutoff and anti-sway algorithms. Relay-based systems persist in cost-sensitive retrofit environments where electromechanical simplicity outweighs connectivity requirements.
FAA crane safety directives for airport construction zones, OSHA 1910.179 overhead crane standards, and IEC 60204-1 electrical equipment specifications collectively dictate controller architecture, emergency-stop redundancy, and operator interface design across the market. CE marking under the EU Machinery Directive further constrains export-qualified products to dual-channel safety relay configurations. Stakeholders must monitor how functional safety certifications fragment between regional test house approvals and whether embedded IoT telemetry triggers new cybersecurity compliance layers.
Market Dynamics
Microprocessor-based architectures are displacing relay logic across port and mining installations as IEC 60204-1 compliance mandates dual-channel safety configurations and real-time load monitoring.
Growth Catalysts
- OSHA 1910.179 enforcement:US manufacturing facilities face stepped-up inspection protocols for overhead crane braking systems, accelerating controller replacement cycles in heavy fabrication clusters.
- Programmable logic controllers:Mining operators in Australia and Chile deploy automated load management to reduce unplanned downtime in extraction hoists operating at depth.
- Port modernization drives:Container terminal expansions in Hamburg, Rotterdam, and Singapore require anti-sway algorithms for ship-to-shore crane fleets handling ultra-large vessels.
Market Restraints
- Semiconductor supply concentration:Microprocessor and IGBT module fabrication clusters in Taiwan and South Korea create vulnerability for controller lead times during geopolitical friction.
- Copper and rare earth magnet volatility:Motor winding and permanent magnet costs fluctuate with extraction quotas from Chinese state-owned mining consortia.
- Relay-based system persistence:Cost-sensitive retrofit environments in Eastern European steel mills resist connectivity premiums where electromechanical simplicity suffices.
Strategic Opportunities
- Indian port infrastructure:Sagarmala program investments at Jawaharlal Nehru Port and Visakhapatnam create demand for automated material handling systems with integrated controller retrofits.
- Predictive maintenance convergence:Embedded vibration sensors and edge computing platforms enable condition-based brake monitoring, shifting revenue toward software-enabled service contracts.
- EU Green Deal machinery retrofits:CE-marked energy efficiency mandates for existing crane fleets open retrofit windows for variable frequency drive upgrades across German and Polish manufacturing.
Industry Challenges
- Functional safety certification timelines:TÜV and SGS validation cycles for SIL-rated safety relays extend product launch schedules by six to nine months.
- Legacy system integration friction:Analog signal compatibility between 1990s-era crane pendant systems and digital fieldbus protocols requires custom gateway engineering.
- Embedded cybersecurity gaps:IoT-enabled remote diagnostics expose industrial controllers to ransomware vectors not addressed in original IEC 62443 implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hoist Controller Market |
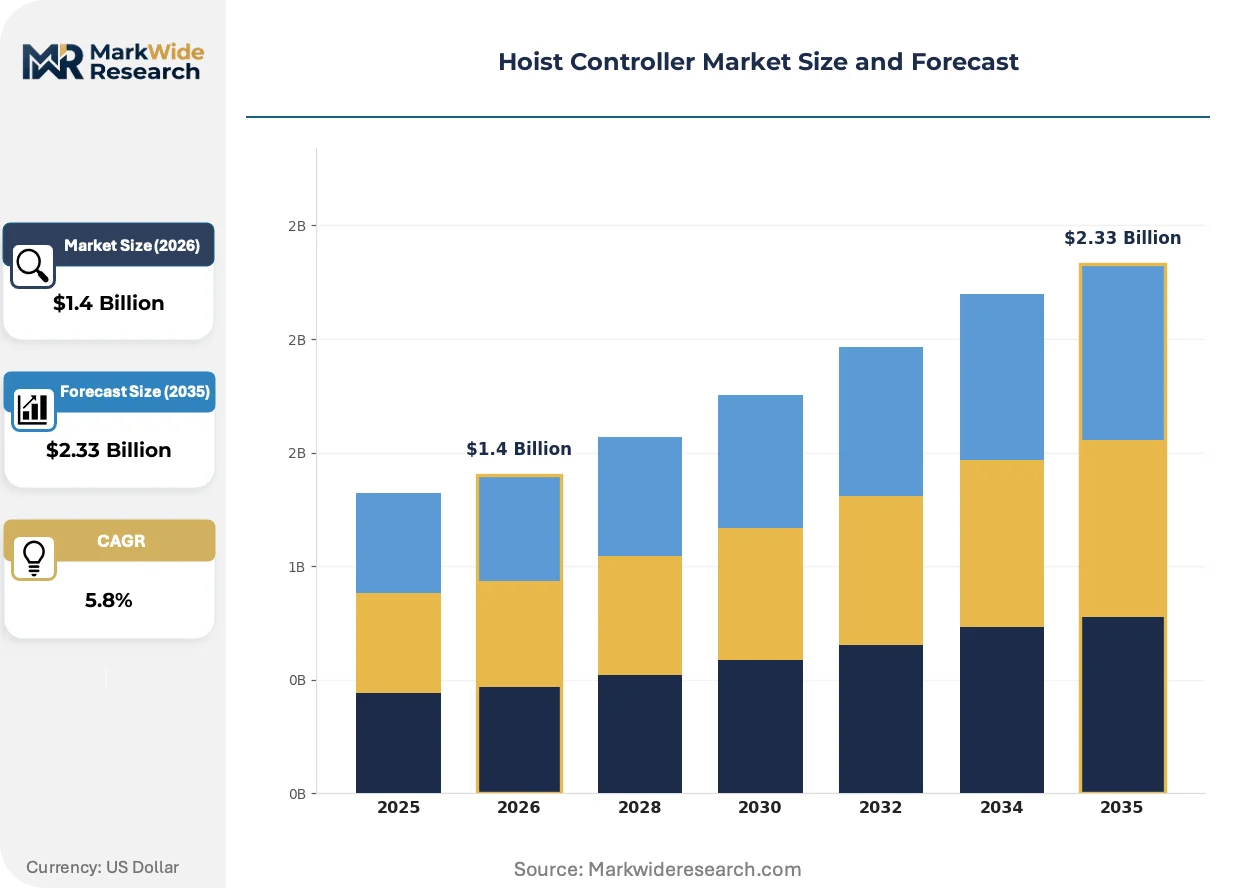
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drum Controllers, Inverter Controllers, DC Drive Controllers, Programmable Logic Controllers Technology: Electromechanical, Solid State, Microprocessor-based, Relay-based Application: Construction Sites, Mining Operations, Manufacturing Plants, Ports & Shipyards End User Industry: Heavy Equipment Fabricators, Material Handling Firms, Infrastructure Developers, Logistics Providers |
| Companies Covered | Schneider Electric, Conductix-Wampfler, Magnetek, The Rowland Company, Demag Cranes & Components, Speed-O-Controls, Uesco Cranes, PLS Electronics, Eastern Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hoist Controller Market Strategic Shifts & Innovations
Controller architecture is converging around software-defined safety functions and wireless operator interfaces, compressing hardware differentiation while expanding service attach rates.
Variable frequency drive technology is hybridizing contactor staging with precise speed modulation. Port operators in Long Beach and Rotterdam adopt these systems for container handling where load positioning accuracy reduces vessel turnaround time. The technology is hybridizing procurement criteria toward total-cost-of-ownership metrics that include energy recovery and brake wear reduction.
IEC 60204-1:2018 amendments now mandate emergency-stop redundancy and protective conductor continuity monitoring for all new crane installations. European manufacturers must redesign operator pendant enclosures to accommodate dual-channel safety relay configurations. Mining equipment suppliers in Germany and Sweden are pre-certifying controller platforms to accelerate export qualification for Australian and Chilean projects.
Aftermarket service unbundling is fragmenting traditional hardware-margin pools. Crane fleet operators in US Gulf Coast petrochemical corridors now procure predictive diagnostics separately from controller hardware, favoring vendors with telemetry-enabled remote monitoring. This pattern is most visible in Texas and Louisiana where integrated maintenance contracts reduce in-house electrical technician headcount.
Hoist Controller Market Segmentation
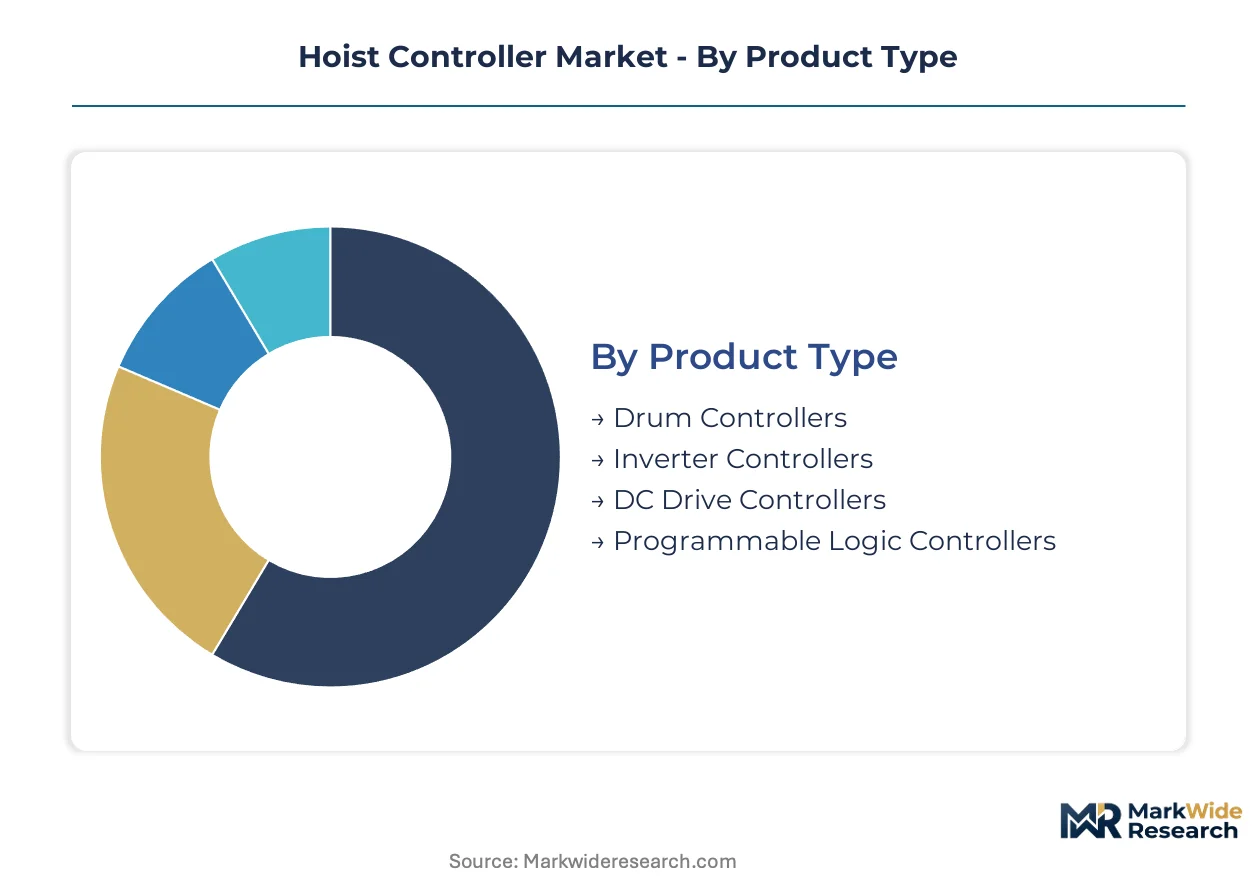
Hoist controller procurement patterns diverge sharply across technology generations and end-use intensity. Mining extraction demands programmable automation with overload protection, while port retrofit programs prioritize cost-efficient electromechanical replacements.
Product Type:
Mature contactor-based architectures coexist with emerging digital drive platforms across installation bases.
- Inverter Controllers:Variable frequency drives modulate motor speed through IGBT power modules, enabling precise acceleration curves and regenerative braking. Container terminals at Rotterdam and Singapore specify these systems for ship-to-shore cranes handling ultra-large vessels where positioning accuracy compresses vessel turnaround.
- Programmable Logic Controllers:Embedded microprocessors execute ladder logic for automated load sequencing with real-time feedback from integrated load cells. Underground mining operations in Australia and Chile deploy PLC-based hoists for extraction shafts where unplanned downtime costs exceed equipment replacement value.
- Drum Controllers:Mechanical cam-operated contactors govern motor direction through resistor staging; legacy steel mills in Eastern Europe retain these for bridge crane retrofits where capital constraints limit digital migration.
- DC Drive Controllers:Ward Leonard or thyristor-based armature voltage control persists in magnet crane applications at scrap metal yards requiring sustained low-speed torque.
Inverter controllers retain volume leadership; programmable logic controllers hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium microprocessor platforms from economy relay installations.
- Microprocessor-based:ARM or PIC architectures execute anti-sway algorithms and predictive brake monitoring through embedded firmware. German manufacturers pre-certify these platforms to IEC 60204-1 dual-channel safety requirements for export to Australian mining projects.
- Relay-based:Electromechanical logic with hardwired interlocks persists where electromagnetic immunity and field-service simplicity outweigh connectivity requirements; Polish and Czech steel fabricators specify these for overhead crane rebuilds.
- Solid State:Thyristor or triac switching eliminates mechanical contact wear in high-cycle staging applications.
- Electromechanical:Drum and cam controllers with carbon brush commutation serve duty cycles below ten operations per hour.
Microprocessor-based systems command the premium tier; relay-based technology anchors economy retrofit demand.
Application:
Geography concentrates demand where extractive and logistics infrastructure intersect heavy fabrication clusters.
- Ports & Shipyards:Ship-to-shore and rubber-tired gantry crane fleets require synchronized multi-axis control with anti-sway compensation. Hamburg and Long Beach terminal operators specify IEC-compliant controllers with redundant emergency-stop channels for ultra-large container vessel handling.
- Mining Operations:Extraction hoists and slope conveyors demand SIL-rated safety systems with continuous load monitoring. Chilean copper mines and Western Australian iron ore pits drive specification toward automated load management at operating depths exceeding one kilometer.
- Manufacturing Plants:Overhead bridge cranes in automotive and heavy equipment fabrication require precise positioning for assembly line feeding.
- Construction Sites:Tower and mobile cranes operate under temporary power with simplified pendant control interfaces.
Ports and mining retain the largest installed base; manufacturing plant retrofits are gaining share fastest.
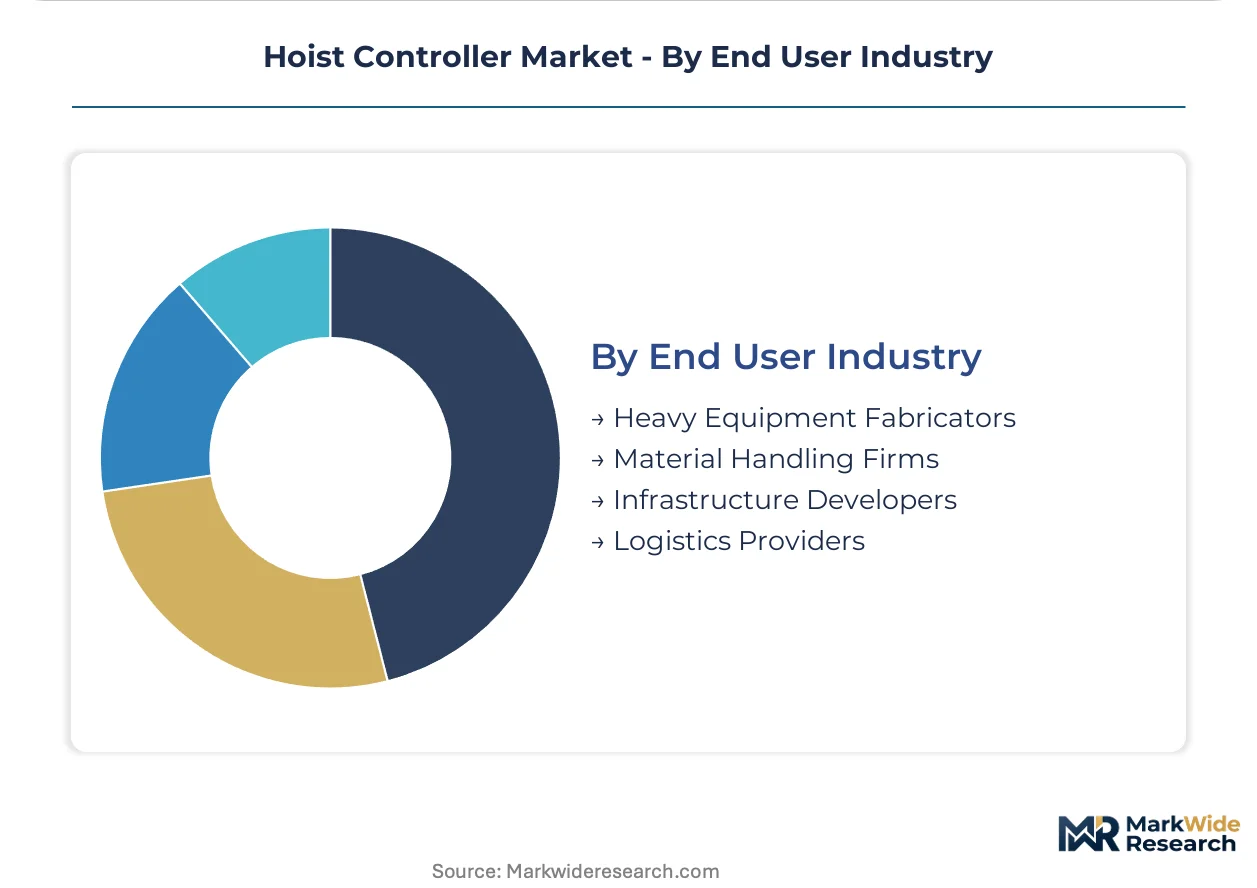
End User Industry:
Customer type determines procurement sophistication from integrated fleet management to single-unit replacement.
- Material Handling Firms:Crane rental and leasing companies operate mixed-vintage fleets requiring controller standardization for technician mobility. US Gulf Coast petrochemical corridor operators now unbundle predictive diagnostics from hardware procurement.
- Heavy Equipment Fabricators:Original equipment manufacturers integrate controllers during crane assembly, specifying platforms with global certification packages for export markets.
- Infrastructure Developers:Port authority and airport construction projects procure under FAA and OSHA compliance mandates with documented safety validation.
- Logistics Providers:Third-party warehouse operators prioritize energy recovery and brake wear reduction in total-cost-of-ownership calculations.
Material handling firms drive aftermarket service revenue; heavy equipment fabricators anchor original equipment specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hoist controller procurement patterns diverge sharply by geography: mining economies demand programmable automation for extraction hoists, while port-centric markets prioritize anti-sway precision for container handling.
United States
OSHA 1910.179 enforcement drives controller replacement cycles in heavy fabrication clusters across the Gulf Coast petrochemical corridor. FAA crane safety directives for airport construction zones mandate dual-channel emergency-stop redundancy. Houston and New Orleans terminal operators specify IEC-compliant systems for ship-to-shore crane fleets.
Germany
EU Green Deal machinery retrofits open windows for variable frequency drive upgrades across manufacturing plants in North Rhine-Westphalia. CE marking under the EU Machinery Directive constrains export-qualified products to dual-channel safety relay configurations. Hamburg port modernization requires synchronized multi-axis control for ultra-large container vessel handling.
China
Port infrastructure expansion at Shanghai and Ningbo-Zhoushan drives demand for automated material handling systems with integrated controller architectures. GB standards and MIIT regulations shape domestic certification requirements for crane electrical equipment. Heavy equipment fabrication clusters in the Yangtze River Delta concentrate controller manufacturing capacity.
Australia
Underground mining operations in Western Australia's Pilbara region deploy PLC-based hoists for iron ore extraction shafts exceeding one kilometer in depth. The country's national mining safety regulator mandates SIL-rated safety systems with continuous load monitoring. Perth-based engineering firms pre-certify controller platforms for Chilean copper mine exports.
India
Sagarmala program investments at Jawaharlal Nehru Port and Visakhapatnam create demand for automated material handling systems with integrated controller retrofits. BIS certification requirements shape domestic procurement specifications for overhead crane electrical equipment. Gujarat and Maharashtra manufacturing clusters drive specification toward cost-efficient electromechanical replacements.
Hoist Controller Market Key Industry Players
Capability concentration sits with specialists in programmable automation and radio remote systems; scale advantage sits with diversified electrical equipment conglomerates. The supplier base organizes into three tiers: global automation platforms with integrated service networks, regional crane component specialists with festoon and conductor bar integration, and niche remote control vendors with predictive diagnostics offerings. Consolidation pressure favors M&A activity between controller hardware manufacturers and telemetry-enabled service providers. Technology licensing agreements proliferate as safety firmware development costs escalate.
Among diversified electrical equipment conglomerates, Schneider Electric exemplifies the global service network archetype through recurring maintenance contract capture. Conductix-Wampfler occupies a position within the integrated systems tier, anchoring market presence through festoon and conductor bar pairings with retrofit programs. Magnetek represents the specialized remote control segment, sitting within the predictive diagnostics tier for crane fleet applications.
| Leading Market Players |
|---|
| Schneider Electric |
| Conductix-Wampfler |
| Magnetek |
| The Rowland Company |
| Demag Cranes & Components |
| Speed-O-Controls |
| Uesco Cranes |
| PLS Electronics |
| Eastern Electric Corporation |
| Others |
Cost & Logistics Intelligence
Overcapacity in Taiwanese semiconductor foundries is compressing lead times for microprocessor-based controllers while simultaneously eroding pricing power among IGBT module suppliers, forcing hoist controller manufacturers to renegotiate component contracts and pass selective discounts to port operators in Hamburg and Rotterdam.
Pricing Analysis
Long-term offtake agreements dominate procurement between mining operators in Chile and German controller manufacturers, locking in volume commitments for SIL-rated safety systems. Three-tier pricing structure across premium, standard, and economy levels separates IEC 60204-1 certified platforms from relay-based retrofit units and basic contactor assemblies. Cost compression in the economy tier is intensifying because Polish and Czech steel fabricators prioritize capital expenditure minimization over connectivity premiums. Material handling firms in the US Gulf Coast petrochemical corridor exhibit the lowest price sensitivity due to unbundled predictive diagnostics contracts, while Eastern European retrofit buyers remain the most margin-conscious.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic planning for controller manufacturers sourcing ARM architecture chips and rare earth magnets. Component fabrication clusters in Taiwan, South Korea, and Germany anchor the upstream network for microprocessors and power modules. Copper windings, IGBT semiconductors, and permanent magnet materials constitute the critical input trinity. Single-source vulnerability concentrates in Taiwanese wafer foundries serving safety-critical firmware platforms. Distribution runs through heavy equipment OEMs in Germany, specialized crane component distributors in North America, and direct procurement channels for Australian mining consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hoist controller incumbents face substitution pressure from software-defined automation platforms that bypass dedicated hardware through edge computing deployments, requiring defensive repositioning around firmware-anchored safety certifications.
For Market Incumbents: Build switching-cost moats through embedded predictive maintenance subscriptions that tether crane fleet operators to proprietary telemetry ecosystems. Deepen backward integration into safety relay manufacturing to insulate margins from TÜV certification bottlenecks. Defend against open-source controller architectures by pre-certifying platforms to IEC 60204-1 amendments before Australian and Chilean export deadlines. For New Entrants and Emerging Players: Build out white-space positions in Indian port infrastructure under the Sagarmala program, where automated material handling retrofits outpace established supplier penetration. Target PLC-based mining hoist controllers for Western Australian iron ore operations as the most penetrable premium segment. Pursue telemetry-enabled service contracts as the primary go-to-market mechanism rather than hardware-only procurement. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across microprocessor-based controller sub-segments as firmware development costs amortize across larger installed bases. Five-to-ten year viability favors suppliers with recurring service revenue attached to hardware platforms. Acquisition targets should demonstrate pre-certified safety platforms and established maintenance contract books. Monitor SIL-rated safety relay validation timelines as the critical inflection signal for product launch velocity and working capital efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Safety Relay Manufacturing | TÜV certification bottlenecks in Germany constrain launch schedules for Australian mining exports. |
| Predictive Maintenance Platform Launch | US Gulf Coast petrochemical operators unbundle diagnostics from hardware procurement. |
| IEC 60204-1 Pre-Certification Investment | Dual-channel safety configurations are mandatory for Hamburg port modernization contracts. |
| Indian Port Authority Partnership | Sagarmala program investments at Jawaharlal Nehru Port create retrofit demand windows. |
| Firmware-Defined Safety Function Development | Software-defined architectures compress hardware differentiation across Rotterdam container terminals. |
Research Approach
Cross-validation between OEM procurement interviews and regulatory filing analysis anchors the qualitative findings in this study. Primary fieldwork encompassed maintenance directors at US manufacturing plants, plant engineers in German heavy fabrication clusters, aftermarket service heads at crane rental companies, and procurement teams at Australian mining operators. Secondary sources included IEC 60204-1 amendment documentation, OSHA 1910.179 enforcement records, SEC filings from diversified electrical equipment conglomerates, and customs data for IGBT module trade flows. Bottom-up unit economics triangulate against top-down market sizing across technology generations.
Calibration against historical replacement cycles and port infrastructure investment pipelines shapes the analytical framework across the projection horizon. Segmentation dimensions span product architecture, safety certification tier, end-use intensity, and regional regulatory cluster. CAGRs derive from installed base turnover rates and technology substitution curves. Mining extraction depth economics and container vessel size evolution constitute industry-specific forecast inputs.
Stress conditions across semiconductor lead time volatility, copper price fluctuation, and safety certification delay scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding IEC amendment adoption timelines and port modernization funding continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Forklift Work Platforms Market
Material Handling Equipment
Drag Chain for Machine Market
Material Handling Equipment
Conveyors and Belt Loaders Market
Material Handling Equipment
Industrial Sheaves and Pulleys Market
Material Handling Equipment
Pick and Carry (PNC) Crane Market
Material Handling Equipment
Air Classifying Mill Market
Material Handling Equipment
Circular Stacker and Reclaimer Market
Material Handling Equipment
Industrial Parts Feeders Market
Material Handling Equipment
Gas Connectors and Gas Hoses Market
Material Handling Equipment
Log Loaders Market
Material Handling Equipment
Global Bop Handling Systems Market
Material Handling Equipment
Wood Chipper Market
Material Handling Equipment
Electric Wire Rope Hoist Market
Material Handling Equipment
Vertical Lifts Market
Material Handling Equipment
Global Bucket Loader Market
Material Handling Equipment
Sifter Fitment Market