
 Explosion Proof Crane Market | 2026-2036
Explosion Proof Crane Market Size, Share, and Industry Trends Forecast 2026-2036
Explosion Proof Crane Market Insights
Oil and gas capital expenditure is pivoting toward downstream chemical complexes, redirecting crane procurement from offshore platforms to onshore processing installations. Konecranes leverages its ATEX-certified overhead hoist portfolio to dominate European refinery retrofits. STAHL CraneSystems anchors German manufacturing with specialized spark-resistant components for Zone 1 environments. Weihua Group extends cost-competitive electric crane lines across Asian chemical corridors.
An explosion proof crane incorporates flameproof enclosures, intrinsically safe electrical circuits, and non-sparking material construction to operate in atmospheres containing flammable gases or combustible dusts, typically achieving IP55 ingress protection and temperature class ratings from T1 to T6. Electric crane configurations lead unit shipments due to precision load control in hazardous zones, while above 20 tons capacity segments command premium pricing from custom engineering requirements. Oil and gas applications remain the largest revenue pool, though chemical processing represents the fastest-growing end-use channel as brownfield expansions multiply.
ATEX directives, IECEx certification schemes, and OSHA 1910.179 standards collectively mandate third-party verified explosion protection for crane installations in classified atmospheres, creating compliance barriers that filter non-specialized suppliers. EPA and EU Green Deal methane reduction protocols indirectly stimulate crane replacement by accelerating facility modernization timelines. Stakeholders must monitor evolving harmonization between regional certification regimes to anticipate product redesign cycles and market access costs.
Market Dynamics
Tightening ATEX and IECEx certification timelines are compressing crane replacement cycles across European petrochemical corridors, forcing facility operators to accelerate capital deployment toward third-party-verified explosion protection systems.
Growth Catalysts
- Zone 1 Environment Mandates:ATEX Directive 2014/34/EU now requires flameproof enclosures for all lifting equipment in classified atmospheres, compelling German and Dutch refineries to modernize aging overhead crane infrastructure.
- Methane Reduction Protocols:EPA leak detection rules and EU Green Deal methane targets accelerate facility upgrades, indirectly stimulating crane procurement tied to comprehensive plant modernization programs.
- Brownfield Chemical Expansions:Downstream oil and gas investment pivots toward onshore processing complexes in the Middle East, redirecting demand from offshore platforms to intrinsically safe electric crane installations.
Market Restraints
- Specialized Component Concentration:Spark-resistant copper-beryllium alloys and flameproof motor housings concentrate among a narrow supplier base in Germany and Japan, creating input bottlenecks.
- Certification Cost Escalation:Third-party ATEX and IECEx testing fees for custom-engineered cranes above 20 tons capacity inflate total cost of ownership, filtering mid-tier buyers from premium segments.
- Extended Lead Times:Zone 1-rated electrical enclosures and intrinsically safe circuit designs require specialized manufacturing, stretching delivery schedules to 26-32 weeks versus 12-16 weeks for standard cranes.
Strategic Opportunities
- Asian Chemical Corridor Penetration:China's dual carbon goals and NMPA safety mandates create demand for cost-competitive electric explosion proof cranes in Sinopec and PetroChina refinery expansions.
- Digital Twin Integration:Convergence of IoT sensor networks with predictive maintenance platforms enables remote monitoring of crane health in hazardous zones, opening recurring revenue streams.
- Service Contract Unbundling:Aftermarket parts and certified inspection services separate from equipment sales, allowing manufacturers to capture lifetime value from installed base expansion.
Industry Challenges
- Certified Technician Scarcity:Qualified inspectors for ATEX and IECEx compliance verification remain concentrated in Western Europe, constraining deployment speed in emerging chemical processing hubs.
- Legacy System Integration:Retrofitting flameproof cranes into existing plant layouts requires custom engineering to accommodate confined headroom and obsolete electrical infrastructure.
- Harmonization Delays:Divergent testing protocols between OSHA 1910.179 and EU machinery directives force redundant certification cycles, extending time-to-market for multinational suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Explosion Proof Crane Market |
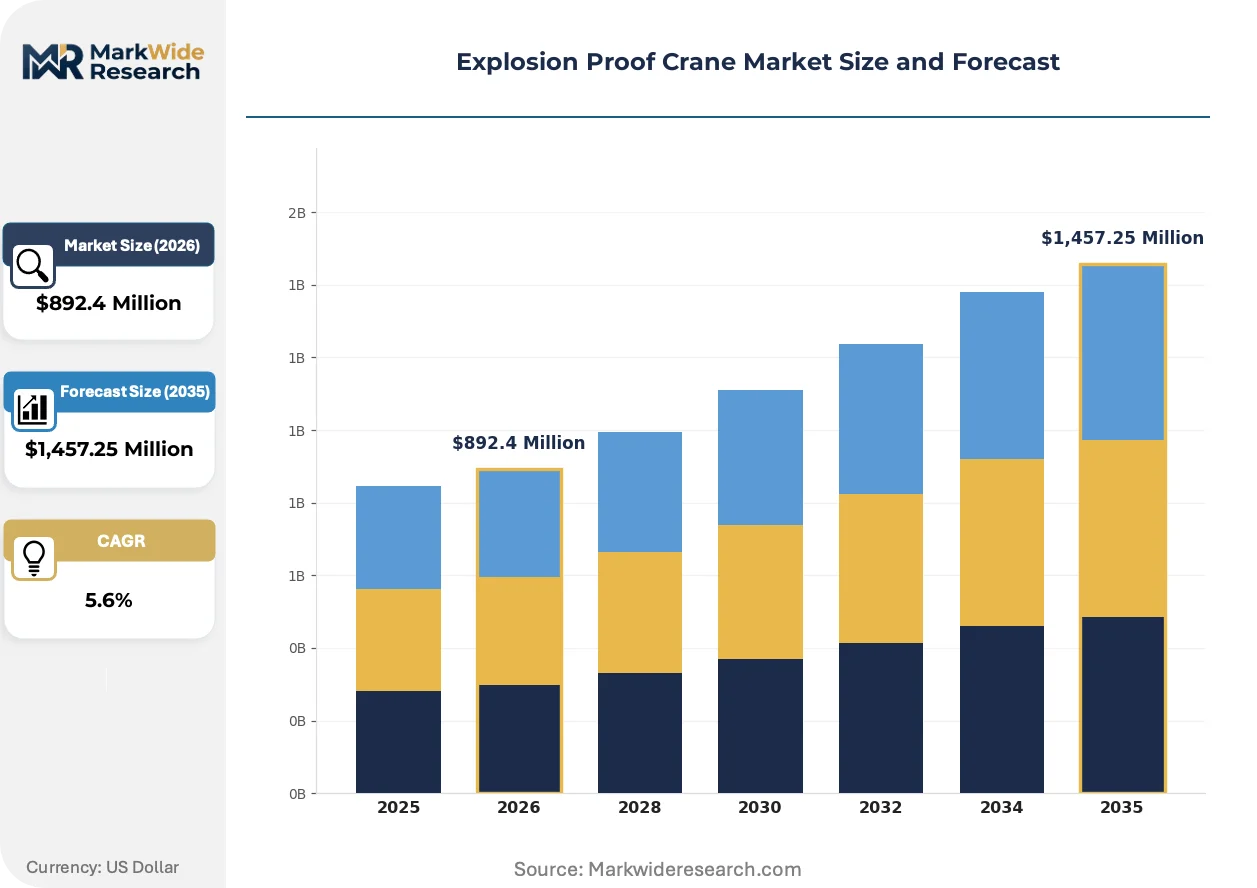
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,457.25 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Electric, Hydraulic, Pneumatic, Manual Application: Oil & Gas, Chemical Processing, Mining, Military Capacity: Up to 5 tons, 5-10 tons, 10-20 tons, Above 20 tons End User: Industrial Facilities, Construction Sites, Marine Applications, Warehousing |
| Companies Covered | Konecranes, STAHL CraneSystems, MHE-Demag, Weihua Group, Hitachi Industrial Equipment Systems, ABUS Kransysteme, Eilbeck Cranes, SWF Krantechnik, Zinter Handling, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Explosion Proof Crane Market Trends and Innovations
Explosion proof crane engineering is converging with digitalization and modular construction methods, reshaping how hazardous zone lifting equipment is specified, manufactured, and maintained across chemical processing and energy infrastructure.
Variable frequency drive technology is integrating with permanent magnet motors to deliver precise load positioning in Zone 1 environments while reducing spark generation risks. Major petrochemical operators in Germany and the Netherlands specify these configurations for new ethylene cracker installations. The technology is integrating safety-critical control architectures that compress commissioning timelines by enabling factory acceptance testing prior to hazardous site deployment.
EU Green Deal industrial emissions targets are tightening fugitive emission standards for chemical processing equipment, including crane components in volatile organic compound service. The European Commission's forthcoming revision to the Industrial Emissions Directive will mandate sealed bearing housings and enhanced gasket materials for cranes operating in classified atmospheres. German refinery operators are responding by pre-emptively specifying IP66 ingress protection and T6 temperature class ratings in procurement tenders.
Buyer preference is migrating from capital purchase toward performance-based maintenance agreements that bundle equipment, spare parts, and certified inspection services. Large chemical conglomerates in the Ruhr industrial cluster now favor ten-year total cost of ownership contracts over traditional unit sales. This shift is most pronounced in brownfield modernization projects where operational continuity outweighs upfront capital constraints.
Explosion Proof Crane Market Segmentation
Explosion proof crane procurement patterns diverge sharply across power systems, operational environments, and load specifications. Understanding these divisions reveals where certification complexity drives premium engineering versus where standardized configurations dominate unit economics.
Type:
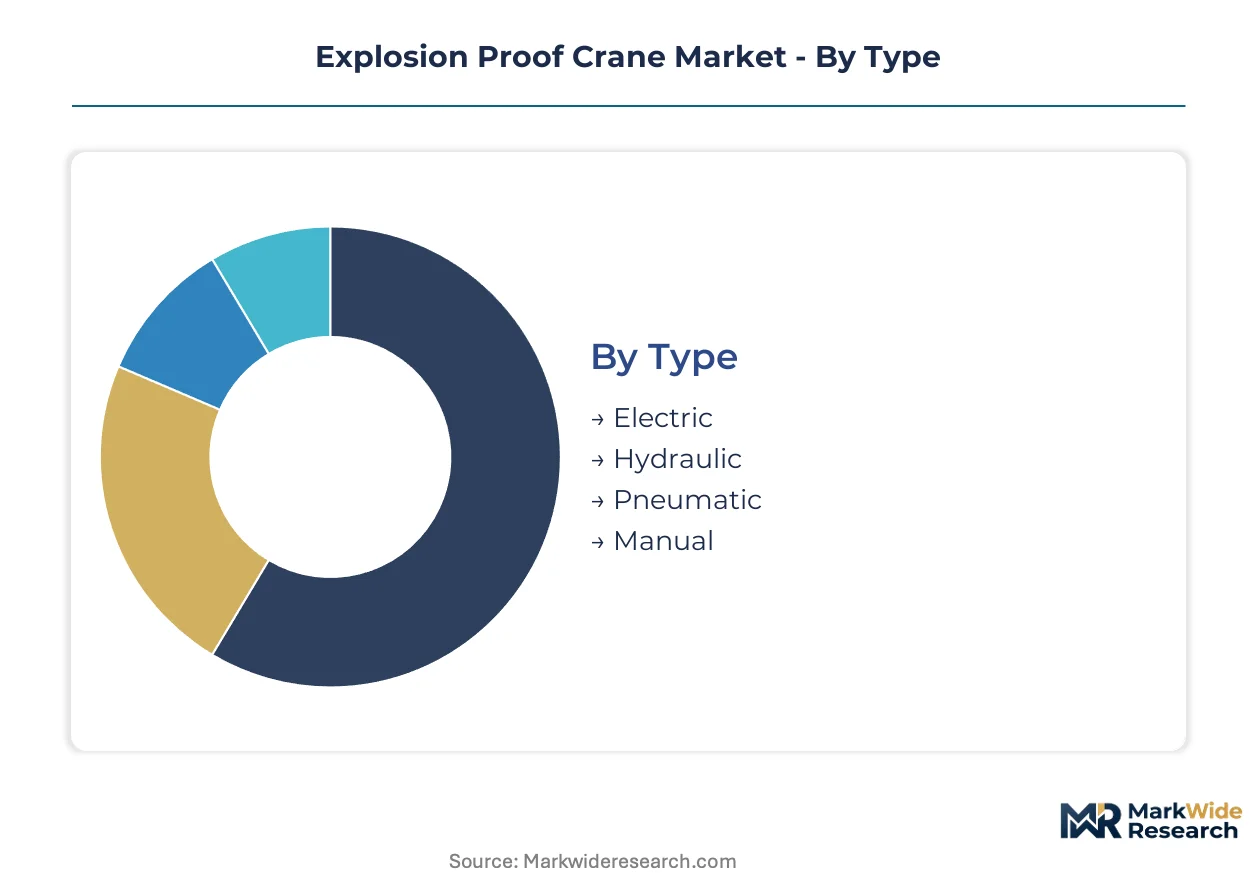
Standalone electric systems anchor most hazardous zone installations, while pneumatic and manual alternatives serve embedded roles where electrical ignition risks prove prohibitive.
- Electric:Variable frequency drive integration with permanent magnet motors delivers precise load positioning in Zone 1 chemical processing corridors. German ethylene cracker operators specify these configurations for new downstream complexes, prioritizing spark-reduction engineering over initial capital outlay.
- Hydraulic:Fluid power transmission eliminates electrical arcing risks entirely, suiting military ordnance handling and underground mining where intrinsic safety overrides efficiency metrics. Extended lead times for flameproof hydraulic power units constrain deployment speed in brownfield expansions.
- Pneumatic:Compressed air actuation serves temporary lifting operations in volatile organic compound service where permanent electrical infrastructure is impractical.
- Manual:Hand-chain and lever configurations persist in confined maintenance access points across aging European refinery infrastructure.
Volume placements concentrate in Electric configurations; the faster expansion belongs to Pneumatic systems in temporary hazardous zone applications.
Application:
Cost tier stratification separates capital-intensive downstream processing from price-sensitive extraction and defense procurement channels.
- Oil & Gas:Offshore platform decommissioning redirects capital toward onshore chemical processing, compressing crane replacement cycles in North Sea installations. Methane reduction protocols accelerate facility-wide modernization timelines.
- Chemical Processing:ATEX Directive 2014/34/EU mandates flameproof enclosures for all lifting equipment in classified atmospheres, compelling Ruhr industrial cluster operators to modernize aging overhead infrastructure. Brownfield expansions multiply demand for intrinsically safe electric configurations.
- Mining:Underground coal and metal ore extraction requires spark-resistant copper-beryllium alloy components certified for combustible dust environments.
- Military:Ordnance handling specifications demand redundant safety architectures with specialized procurement protocols.
Revenue concentration sits with Oil & Gas; Chemical Processing climbs the fastest as downstream investment pivots from offshore to onshore installations.
Capacity:
Margin structure inverts across the tonnage spectrum, with custom engineering above 20 tons commanding substantial premiums over standardized sub-5-ton configurations.
- Above 20 tons:Custom-engineered bridge cranes with Zone 1-rated electrical enclosures require 26-32 week delivery schedules versus 12-16 weeks for standard units. Third-party ATEX and IECEx testing fees inflate total cost of ownership, filtering mid-tier buyers from this segment.
- Up to 5 tons:Standardized jib and monorail configurations serve maintenance and material handling in chemical processing facilities where volume procurement offsets certification overhead. Weihua Group and Asian manufacturers compete aggressively on unit economics.
- 5-10 tons:Intermediate capacity range bridges maintenance lifting and light production duty in refinery retrofit applications.
- 10-20 tons:Process crane configurations for reactor vessel handling and catalyst changeout operations in petrochemical complexes.
Unit shipments dominate Up to 5 tons; value expansion concentrates in Above 20 tons where engineering complexity sustains pricing power.
End User:
Customer type fragmentation separates owner-operated industrial facilities from contractor-procured construction and marine channels with diverging specification authority.
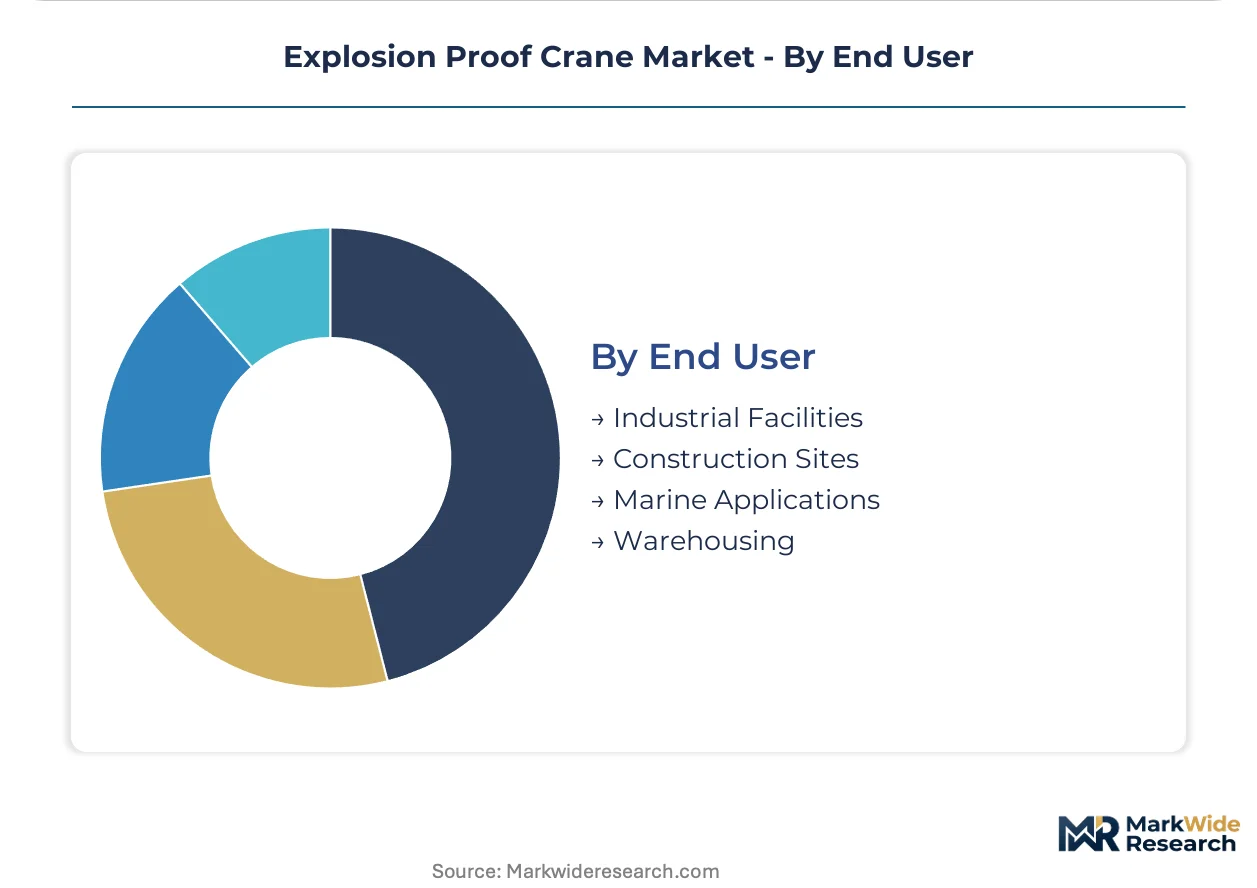
- Industrial Facilities:Petrochemical conglomerates in Germany's Ruhr cluster now favor ten-year total cost of ownership contracts bundling equipment, spare parts, and certified inspection services. Operational continuity priorities outweigh upfront capital constraints in brownfield modernization programs.
- Marine Applications:Offshore platform crane replacement faces compressed timelines as North Sea operators accelerate decommissioning schedules. Salt corrosion resistance requirements layer atop explosion protection specifications.
- Construction Sites:Temporary lifting installations in pipeline and terminal construction rely on rental and lease channels with shorter certification verification cycles.
- Warehousing:Hazardous materials storage facilities in Rotterdam and Antwerp port zones require ATEX-compliant handling equipment for flammable liquid and aerosol operations.
Procurement volume centers on Industrial Facilities; Marine Applications gain share fastest as offshore-to-onshore capital reallocation reshapes fleet composition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ruhr industrial cluster tax incentives and German federal modernization grants concentrate petrochemical crane procurement in North Rhine-Westphalia. Special economic zones in Rotterdam-Antwerp and Singapore's Jurong Island channel comparable investment flows.
Germany
North Sea offshore platform decommissioning redirects capital toward onshore chemical processing in the Ruhr. ATEX Directive 2014/34/EU mandates flameproof enclosures for all lifting equipment in classified atmospheres. BASF and Bayer facilities in Ludwigshafen and Leverkusen accelerate overhead crane replacement cycles.
United States
EPA methane leak detection rules accelerate facility-wide modernization timelines across Gulf Coast petrochemical corridors. OSHA 1910.179 standards mandate third-party verified explosion protection for crane installations in classified atmospheres. ExxonMobil and Dow Chemical operations in Texas and Louisiana compress procurement schedules for Zone 1-rated equipment.
China
Sinopec and PetroChina refinery expansions in Yangtze River Delta and Pearl River Delta corridors drive demand for cost-competitive electric configurations. NMPA safety mandates and dual carbon goals tighten equipment certification requirements. Shanghai and Ningbo chemical processing zones specify IP66 ingress protection for new installations.
Netherlands
Rotterdam port zone hazardous materials storage facilities require ATEX-compliant handling equipment for flammable liquid operations. EU Green Deal methane reduction protocols stimulate crane replacement tied to comprehensive plant modernization. Shell and Dow Benelux operations in the Rotterdam-Botlek industrial cluster favor ten-year total cost of ownership contracts.
Saudi Arabia
Downstream oil and gas investment pivots toward onshore chemical processing complexes in Jubail and Yanbu. SFDA industrial safety regulations align with IECEx certification schemes for hazardous zone equipment. SABIC and Saudi Aramco joint ventures in the Eastern Province specify intrinsically safe electric crane installations for ethylene cracker expansions.
Explosion Proof Crane Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium engineering above 20 tons capacity concentrating among Western European fabricators while standardized sub-5-ton configurations face aggressive Asian competition. The vendor base organizes into three strategic archetypes: full-system integrators with ATEX-certified portfolios, component specialists supplying spark-resistant subassemblies, and regional fabricators competing on delivery speed and unit economics. Dominant competitive moves include backward integration into flameproof electrical enclosures and strategic partnerships with petrochemical EPC contractors for brownfield modernization programs.
Among European full-system integrators, Konecranes anchors premium positioning through overhead hoist portfolios targeting refinery retrofits, while STAHL CraneSystems exemplifies component-specialist concentration with spark-resistant manufacturing rooted in German industrial clusters. Weihua Group occupies the cost-competitive tier, extending electric crane lines across Asian chemical corridors where volume procurement offsets certification overhead. These three archetypes—Finnish-German premium integration, German component depth, and Chinese scale fabrication—structure competitive dynamics across certification tiers and geographic markets.
| Leading Market Players |
|---|
| Konecranes |
| STAHL CraneSystems |
| MHE-Demag |
| Weihua Group |
| Hitachi Industrial Equipment Systems |
| ABUS Kransysteme |
| Eilbeck Cranes |
| SWF Krantechnik |
| Zinter Handling |
| Others |
Pricing and Supply Chain Analysis
Copper-beryllium alloy price indices cascade through explosion proof crane manufacturing, compressing margins in standardized sub-5-ton configurations while amplifying pricing power for custom-engineered systems above 20 tons capacity. Zone 1-rated electrical enclosure costs concentrate among German and Japanese suppliers, forcing procurement arbitrage between certification-grade premiums and volume-driven unit economics.
Pricing Analysis
Spot inventory availability commands steep discounts versus engineered-to-order configurations with 26-32 week delivery schedules. Three-tier pricing structure across premium, standard, and economy levels stratifies by ATEX certification grade and after-sales service bundling. Cost compression in sub-5-ton segments intensifies because Asian manufacturers compete aggressively on unit economics. Mid-tier chemical processors exhibit highest price sensitivity; petrochemical conglomerates in Germany's Ruhr cluster prioritize operational continuity over upfront capital outlay.
Supply Chain Analysis
Refurbishment flows for flameproof electrical enclosures and spark-resistant components extend asset life cycles in aging European refinery infrastructure. Manufacturing concentration centers on Germany, Japan, and China for specialized motor housings and intrinsically safe circuit assemblies. Input dependencies rest on copper-beryllium alloys, flameproof gasket materials, and permanent magnet motor systems. Single-source vulnerability concentrates in Zone 1-rated enclosure fabrication. Distribution runs through petrochemical EPC contractors and certified aftermarket service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Explosion proof crane procurement functions as a cost-of-compliance story where ATEX Directive 2014/34/EU erects certification barriers that filter non-specialized suppliers and sustain margin premiums for verified third-party testing.
For Market Incumbents: Extend backward integration into flameproof electrical enclosure manufacturing to capture margin compression from specialized component suppliers in Germany and Japan. Deepen captive supply of spark-resistant copper-beryllium alloy subassemblies against emerging Asian competitors. Strengthen ten-year total cost of ownership contract penetration in Ruhr industrial cluster brownfield retrofits.
For New Entrants and Emerging Players: Temporary lifting contractors in Middle Eastern chemical corridor expansions represent an underserved buyer archetype with compressed certification verification cycles and rental-channel price elasticity. Target pneumatic crane configurations for volatile organic compound service where permanent electrical infrastructure proves impractical. Pursue digital twin integration partnerships with predictive maintenance platforms to open recurring revenue streams.
For Investors and Strategic Acquirers: Distressed-cycle entries favor component specialists with ATEX-certified spark-resistant manufacturing in German industrial clusters during European petrochemical capital expenditure troughs. Long-term viability hinges on certification regime harmonization between OSHA 1910.179 and EU machinery directives. Monitor IECEx scheme adoption rates in Asian chemical processing corridors as inflection indicators for geographic expansion returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flameproof Enclosures | Captures margin from German and Japanese component suppliers while securing Zone 1 certification capacity. |
| Digital Twin Integration Partnership | Enables remote crane health monitoring in hazardous zones through IoT sensor convergence with predictive platforms. |
| Long-term Service Contract Bundling | Aligns with Ruhr petrochemical operators favoring ten-year total cost of ownership agreements over unit sales. |
| Asian Chemical Corridor Expansion | Addresses Sinopec and PetroChina refinery demand under NMPA safety mandates and dual carbon goals. |
| Certified Technician Training Programs | Alleviates ATEX and IECEx inspector scarcity constraining deployment speed in emerging processing hubs. |
Research Methodology
Multi-period observation of ATEX certification timelines, methane reduction protocol implementation, and petrochemical capital expenditure flows anchored the trend analysis, supplemented by interviews with plant maintenance directors, OEM procurement teams, aftermarket service heads, and EPC project engineers. Secondary validation drew from customs and trade data, SEC filings of listed industrial equipment manufacturers, chemical industry association reports, and hazardous zone equipment certification databases. Bottom-up unit shipment estimates triangulated against top-down petrochemical infrastructure investment forecasts.
Segment-weighting across power system type, application channel, capacity tier, and end-user category structured the analytical framework over the projection horizon. CAGRs derived from regression analysis of historical replacement cycles against regulatory mandate acceleration timelines. Industry-specific forecast inputs incorporated ethylene cracker expansion pipelines and offshore platform decommissioning schedules.
Revisions become necessary when harmonization delays between OSHA 1910.179 and EU machinery directives extend time-to-market, or when copper-beryllium alloy supply disruptions concentrate input bottlenecks. Practitioners should monitor IECEx scheme adoption rates in Asian chemical processing corridors and certified technician training program expansion for early signals of geographic demand shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Forklift Rental Market
Material Handling Equipment
Global Precision Gearboxes Market
Material Handling Equipment
Global Loading Dock Bumpers Market
Material Handling Equipment
Air Classifying Mill Market
Material Handling Equipment
North America Conveyor Belt Market
Material Handling Equipment
Global Pipe and Tube Bending Machine Market
Material Handling Equipment
Conveying Equipment Market
Material Handling Equipment
Sand Washing Machine Market
Material Handling Equipment
Europe Forklift Truck Market
Material Handling Equipment
US Forklift Market
Material Handling Equipment
United States Hand Holes Market
Material Handling Equipment
Motorized Decoiler Machine Market
Material Handling Equipment
Pallet Truck Market
Material Handling Equipment
Hoist Controller Market
Material Handling Equipment
Conveyor Scales Market
Material Handling Equipment
Drag Chain for Machine Market