
 Selective Pallet Racking System Market | 2026-2036
Selective Pallet Racking System Market Size, Share, and Industry Trends Forecast 2026-2036
Selective Pallet Racking System Market Analytics
Chinese steel roll-forming capacity is shifting toward higher-gauge structural profiles used in selective pallet racking systems. Interlake Mecalux leverages its North American manufacturing footprint to sustain rapid fulfillment of large-scale warehouse projects. SSI Schaefer anchors its competitive position through integrated software-hardware offerings that combine racking with warehouse management systems. Daifuku Co., Ltd. specializes in automated storage and retrieval systems that interface directly with selective rack configurations.
Selective pallet racking consists of adjustable beam-and-upright frameworks engineered from cold-rolled steel, typically rated for loads between 2,000 and 30,000 pounds per beam level depending on configuration and beam length. The system permits direct access to every pallet position, making it the dominant storage architecture for facilities managing high SKU variety with moderate turnover velocity. Standard racks occupy the largest share of product type demand due to their adaptability across warehousing and retail backroom environments. Cold storage applications represent the fastest-growing application segment as pharmaceutical and food-grade facilities expand capacity to meet stringent temperature chain requirements. Steel remains the overwhelming material choice for load-bearing components, though composite upright protectors are gaining traction in high-traffic aisles where forklift impact resistance matters.
FDA food safety regulations and OSHA material handling standards directly influence racking design specifications, particularly in facilities storing perishables or hazardous materials where structural failure carries severe liability exposure. The EU Machinery Directive and CE marking requirements shape export competitiveness for racking manufacturers serving European distribution networks. Stakeholders must monitor evolving seismic design codes and automated equipment interoperability standards as warehouse automation densities increase and racking systems integrate with robotic picking platforms.
Market Dynamics
Warehouse automation density is compressing aisle widths and forcing selective rack manufacturers to engineer higher-density configurations compatible with robotic retrieval systems. This structural shift is reshaping load-bearing specifications, inspection protocols, and the competitive positioning of racking suppliers across major distribution corridors.
Growth Catalysts
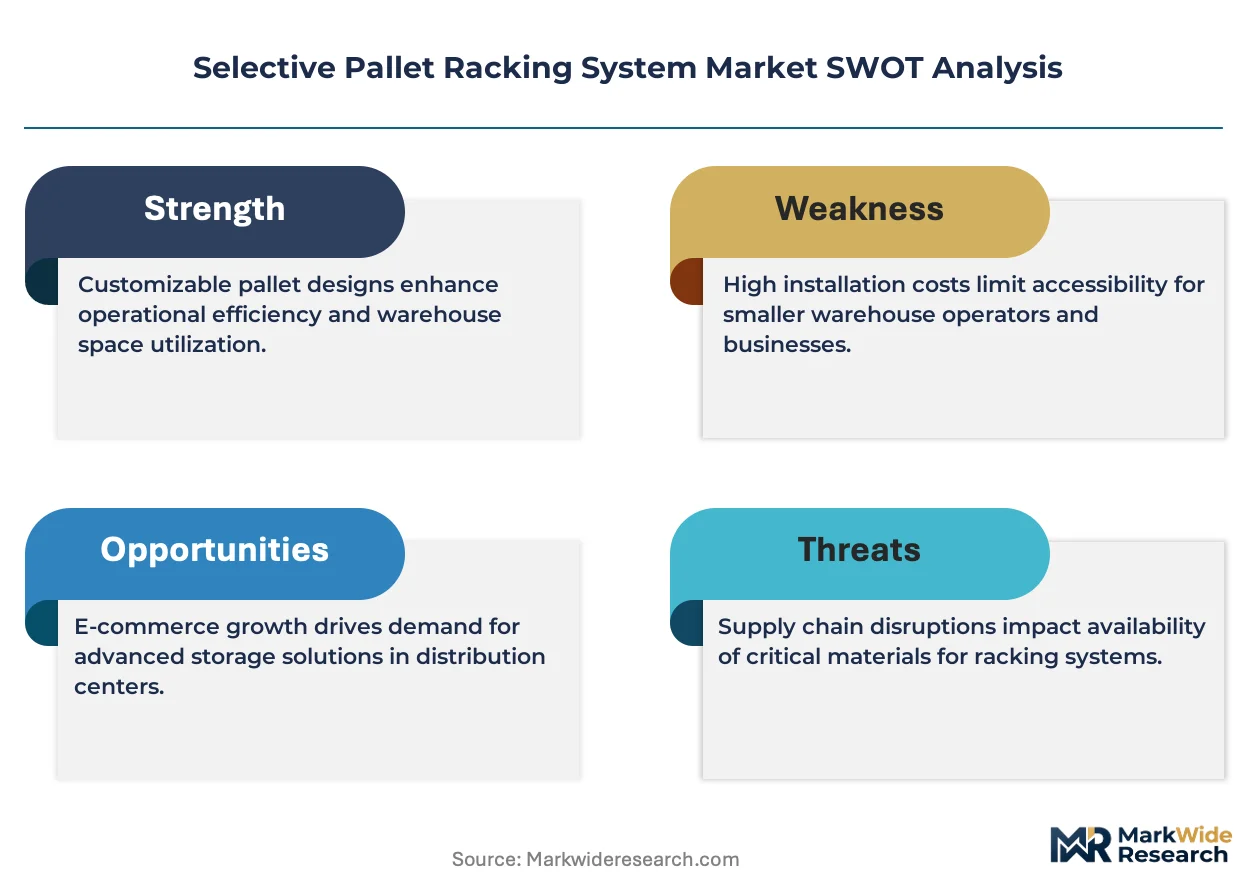
- Cold storage expansion:Pharmaceutical and food-grade facilities are installing selective racking to meet FDA food safety regulations and temperature chain requirements for perishable inventory.
- OSHA compliance mandates:Stricter material handling standards are compelling warehouse operators to replace aging rack systems with certified load-rated configurations.
- E-commerce fulfillment center construction:Third-party logistics providers in the United States are deploying selective racks to manage high SKU variety with direct pallet access.
Market Restraints
- Steel price volatility:Cold-rolled steel input costs fluctuate with Chinese export policy and energy pricing, compressing manufacturer margins on fixed-price contracts.
- Seismic code compliance:California and other high-risk zones require engineered rack anchoring and bracing systems that add material cost and installation complexity.
- Mezzanine storage substitution:Multi-level platform systems capture floor space optimization demand in facilities with sufficient clear height, limiting selective rack addressable market.
Strategic Opportunities
- Automated storage convergence:Integration of selective racking with warehouse management systems and robotic picking platforms creates premium configuration demand.
- Composite upright protectors:High-traffic distribution centers are adopting polymer-based column guards to reduce forklift impact damage and maintenance downtime.
- ISO 9001 quality certification:Certified racking manufacturers capture specification-driven procurement from multinational retailers with centralized vendor qualification programs.
Industry Challenges
- Seismic engineering talent scarcity:Qualified structural engineers capable of certifying rack systems to evolving building codes command premium compensation and extend project timelines.
- Legacy WMS integration friction:Older warehouse management systems lack API connectivity for real-time rack occupancy tracking, complicating automation retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Selective Pallet Racking System Market |
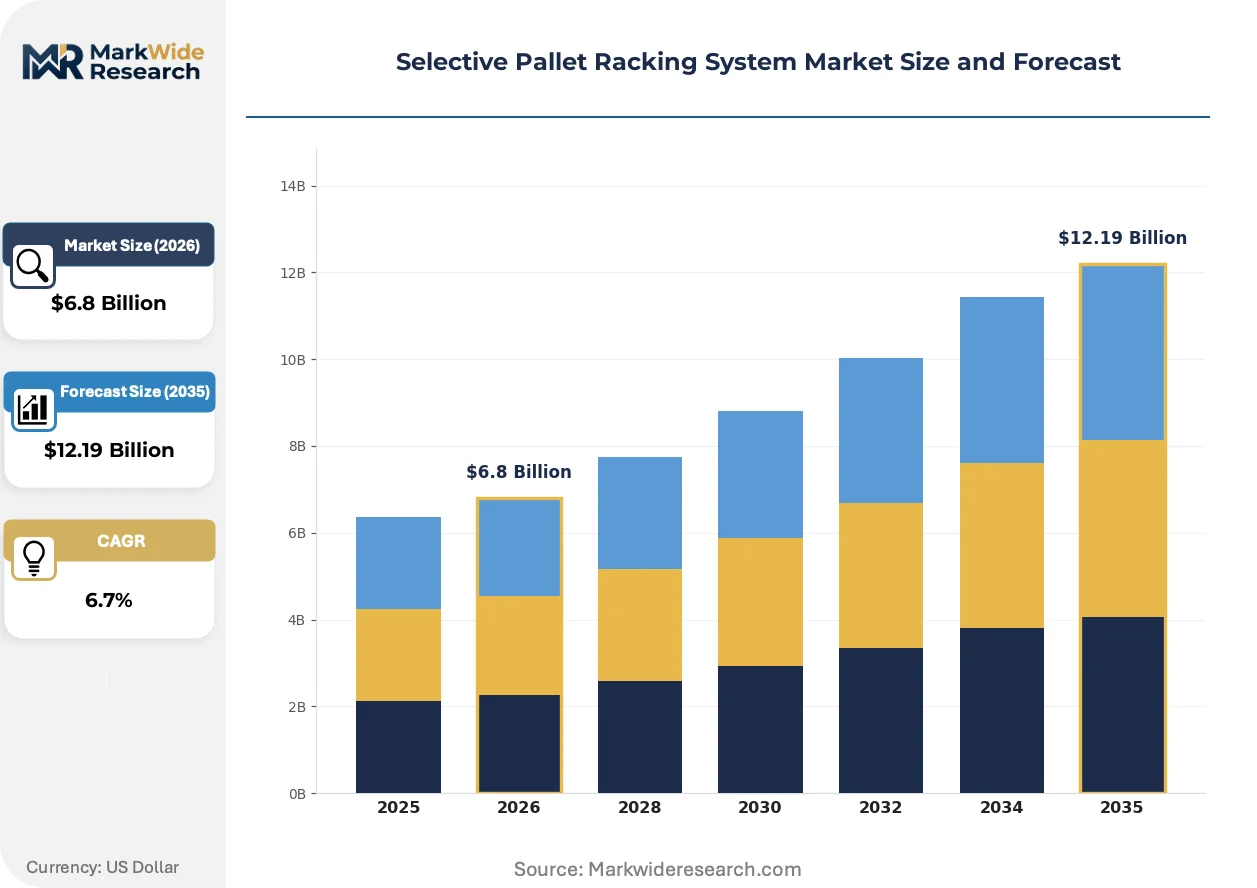
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Racks, Drive-In Racks, Cantilever Racks, Push Back Racks Application: Warehousing, Retail, Cold Storage, Manufacturing Material: Steel, Aluminum, Resin, Composite End User: Food & Beverage, Pharmaceuticals, Electronics, Automotive |
| Companies Covered | Interlake Mecalux, SSI Schaefer, Daifuku Co., Ltd., Mecalux, Ridg-U-Rak, Dematic, Steel King Industries, Dexion, AR Racking, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Selective Pallet Racking System Market Evolving Landscape
Material science advances and regulatory pressure are converging to transform selective pallet racking from static steel infrastructure into intelligent, sensor-integrated storage architecture. Three developments are compressing traditional design paradigms and opening new specification categories.
Wireless load monitoring is electrifying selective rack installations by embedding strain sensors within beam assemblies to transmit real-time weight data to facility management systems. Cold storage operators in the pharmaceutical sector are adopting these configurations fastest, driven by FDA validation requirements for inventory traceability. This electrification is compressing the market for basic uninstrumented racking while expanding the addressable premium for connected infrastructure.
REACH substance restrictions in Europe are compelling racking manufacturers to eliminate hexavalent chromium surface treatments and migrate to zinc-nickel or organic coating alternatives. The industrial consequence is extended corrosion testing protocols and supply chain requalification for export-bound production. Facilities storing hazardous materials or operating in humid environments face the steepest compliance burden, driving specification shifts toward certified coating systems.
Third-party logistics providers are unbundling rack procurement from turnkey warehouse fit-out contracts, creating direct manufacturer relationships that bypass traditional material handling integrators. This channel disintermediation concentrates purchase authority with facility engineering teams rather than general contractors. The United States exhibits this pattern most visibly, where speculative industrial development and build-to-suit fulfillment centers accelerate direct specification cycles.
Selective Pallet Racking System Market Segmentation
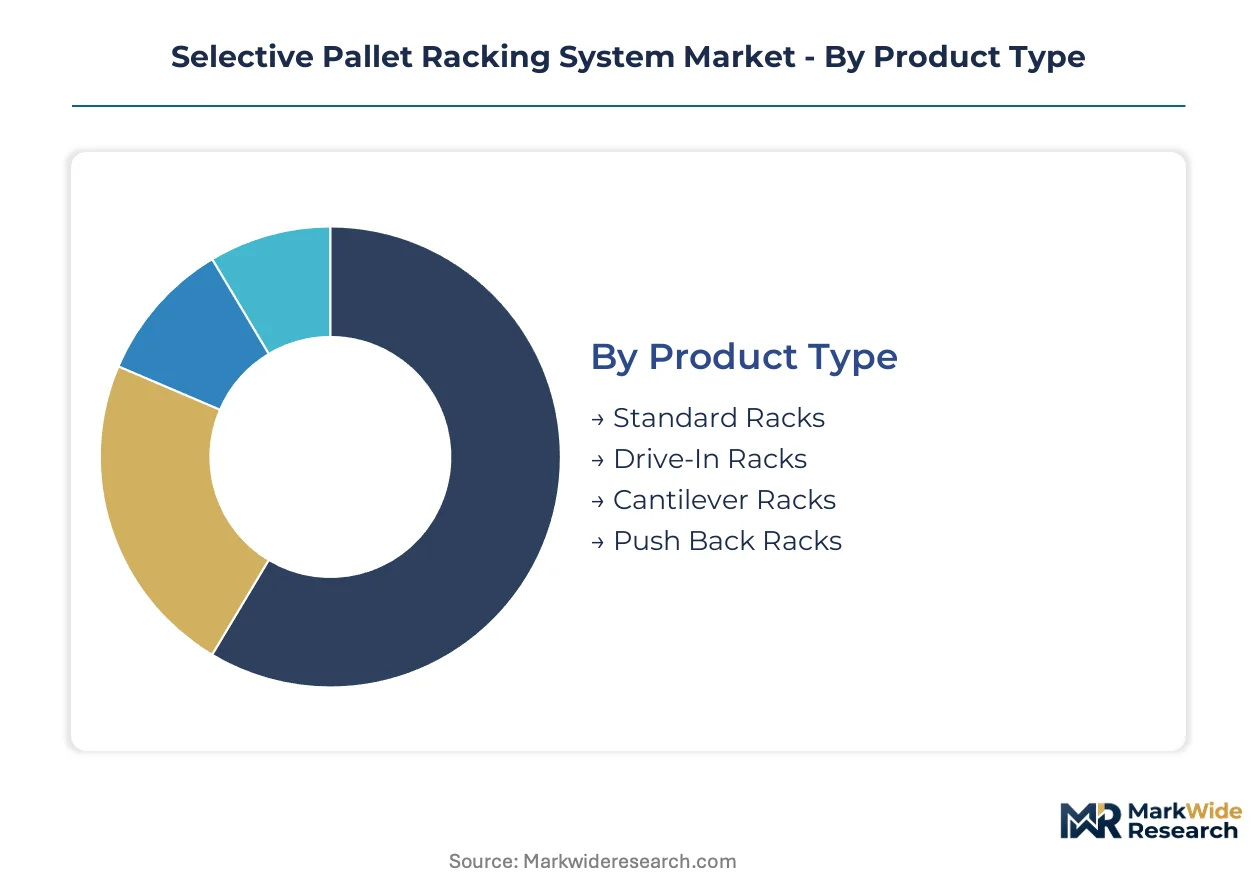
Selective pallet racking configurations diverge sharply across facility types, with load-bearing specifications and aisle geometry requirements driving fundamentally different procurement patterns. Understanding segment boundaries clarifies where engineering margins concentrate versus where price competition dominates.
Product Type:
Upgrade cycles vary dramatically by rack architecture, with facilities replacing standard configurations on 15-20 year horizons while specialized high-density systems turn over faster due to automation obsolescence.
- Standard Racks:Adjustable beam-and-upright frameworks engineered from cold-rolled steel, rated for loads between 2,000 and 30,000 pounds per beam level. United States e-commerce fulfillment centers are deploying these most aggressively as third-party logistics providers prioritize direct pallet access over density.
- Drive-In Racks:Deep-lane configurations allowing forklift entry into rack structure itself, eliminating aisles to maximize cube utilization. Cold storage operators in the food and beverage sector favor these for homogeneous pallet flows where FIFO flexibility matters less than thermal efficiency.
- Cantilever Racks:Single-sided or double-sided column systems with projecting arms for long, irregular loads.
- Push Back Racks:Nested cart configurations enabling LIFO retrieval from single aisle face.
Standard Racks sits at the top of the volume ranking, with Drive-In Racks climbing the fastest.
Application:
Cost tier segmentation separates facilities where racking represents capital infrastructure from those treating it as operational expense recoverable through lease structures.
- Cold Storage:Temperature-controlled installations demanding specialized coatings and thermal-bridge mitigation to prevent condensation corrosion. Pharmaceutical and food-grade facilities are expanding capacity fastest to meet FDA food safety regulations and temperature chain validation requirements.
- Warehousing:General-purpose distribution environments spanning ambient storage through cross-dock operations. United States distribution corridors along Interstate 95 and Interstate 10 are seeing concentrated deployment as automated storage integration accelerates.
- Retail:Backroom and reserve stock configurations in big-box and grocery environments.
- Manufacturing:Work-in-process and raw material staging adjacent to production lines.
Cold Storage commands the steepest expansion trajectory, while Warehousing retains the largest installed base.
Material:
Supply concentration in Chinese steel roll-forming capacity is compressing margins for carbon steel configurations while creating specification gaps for corrosion-resistant alternatives.
- Steel:Cold-rolled structural profiles dominate load-bearing components across all rated capacities. Chinese export policy and energy pricing volatility directly impact manufacturer margins on fixed-price contracts.
- Composite:Polymer-based upright protectors gaining traction in high-traffic aisles where forklift impact resistance reduces maintenance downtime. Distribution centers with dense material handling activity are specifying these for column guard applications.
- Aluminum:Lightweight alternatives for corrosive environments and cleanroom applications.
- Resin:Molded polymer components for non-structural elements and specialized inserts.
Steel dominates absolute volume, with Composite gaining share fastest in premium configurations.
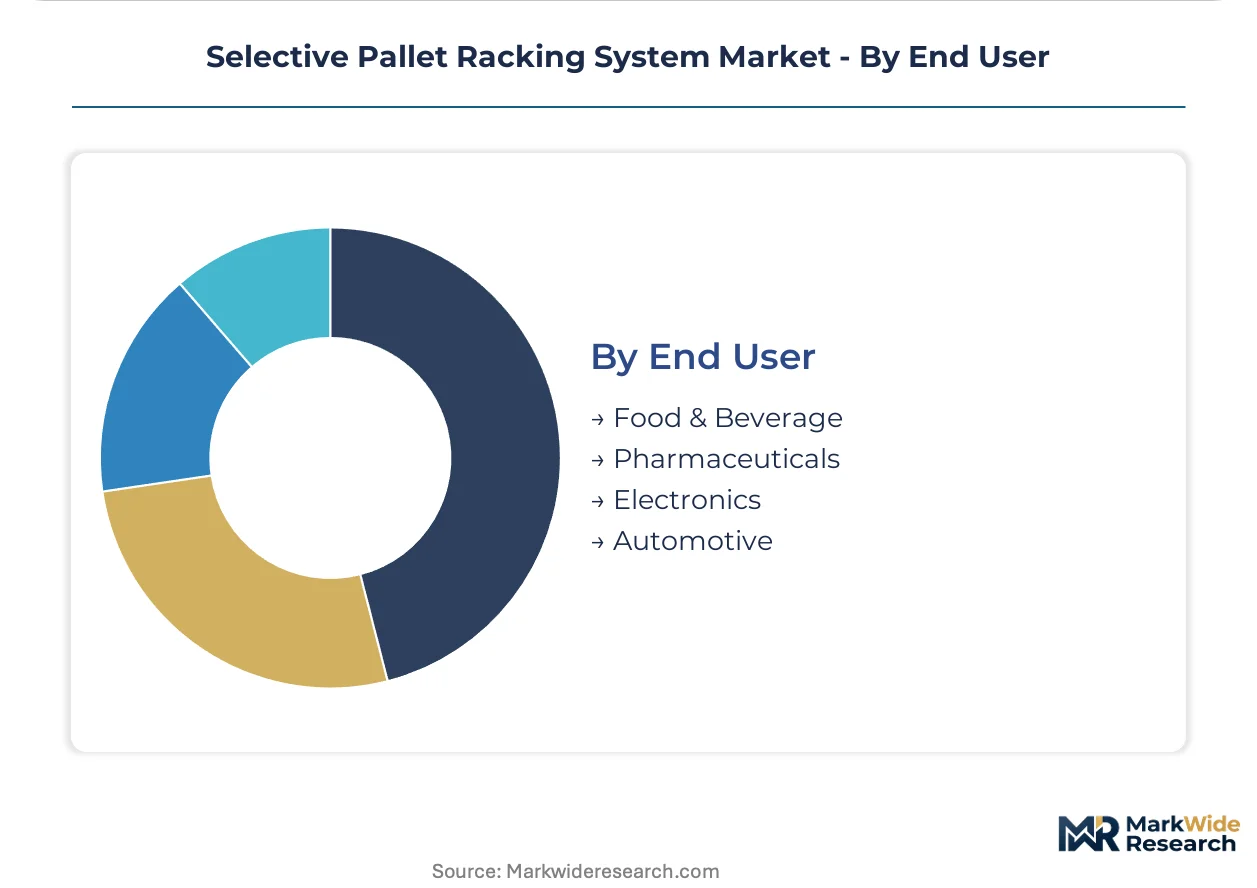
End User:
Customer type segmentation reveals divergent procurement authority patterns, with multinational retailers centralizing vendor qualification while independent operators delegate to general contractors.
- Food & Beverage:Cold chain operators installing selective racking to meet FDA food safety regulations and temperature chain requirements for perishable inventory. Facility expansions are concentrating in temperature-controlled logistics networks serving protein and dairy distribution.
- Pharmaceuticals:cGMP-validated environments requiring documented load ratings and traceable material certifications. FDA validation requirements for inventory traceability are driving fastest adoption of wireless load monitoring configurations.
- Electronics:High-velocity fulfillment operations with sensitive static-control requirements.
- Automotive:Just-in-sequence and aftermarket parts distribution with heavy-load staging needs.
Food & Beverage leads by installed capacity, with Pharmaceuticals expanding most quickly on a percentage basis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping selective pallet racking procurement as manufacturers migrate production toward jurisdictions with favorable steel input costs and streamlined building code enforcement. This geographic rebalancing concentrates supply chain influence in specific industrial corridors while elevating compliance complexity for multinational warehouse operators.
United States
Third-party logistics providers along the Interstate 95 and Interstate 10 corridors are deploying selective racking at unprecedented velocity to service e-commerce fulfillment demand. OSHA material handling standards and FDA food safety regulations compel facility operators toward certified load-rated configurations with documented inspection protocols. The Dallas-Fort Worth metroplex anchors the fastest-growing concentration of automated storage integration projects.
Germany
Industrial machinery exporters and automotive parts distributors drive specification demand for high-density selective rack configurations compatible with robotic retrieval systems. The EU Machinery Directive and CE marking requirements shape procurement criteria for racking systems serving European distribution networks. The Stuttgart industrial region concentrates engineering-intensive rack customization for just-in-sequence manufacturing supply chains.
China
Domestic cold chain expansion and cross-border e-commerce fulfillment infrastructure are accelerating selective racking installations in temperature-controlled logistics facilities. GB standards and MIIT industrial policy guide structural steel specifications for load-bearing components. The Yangtze River Delta manufacturing belt dominates roll-forming capacity for higher-gauge structural profiles used in export-bound racking systems.
Japan
Pharmaceutical cGMP facilities and precision electronics distribution centers specify selective racking with integrated wireless load monitoring for inventory traceability compliance. METI industrial standards and JIS certification protocols govern material specifications and seismic resistance ratings. The Chubu region around Nagoya concentrates automated storage and retrieval system integration with selective rack configurations.
India
Food-grade cold storage expansion and organized retail backroom modernization are driving selective racking demand across temperature-controlled logistics networks. FSSAI food safety regulations and BIS structural standards reshape load-bearing specifications for perishable inventory facilities. The Maharashtra-Gujarat industrial corridor anchors the fastest-growing concentration of pharmaceutical and protein distribution center construction.
Selective Pallet Racking System Market Competitive Landscape
North American producers anchor one tier of the selective pallet racking market; East Asian specialists hold another through integrated automation capabilities. The vendor base organizes around three strategic archetypes: steel roll-forming fabricators with captive galvanizing capacity, warehouse automation integrators bundling racking with retrieval systems, and engineering-focused specialists delivering seismic-certified configurations. Competitive positioning depends on backward integration into steel supply and forward integration into software-hardware offerings.
Within the automation-integrated tier, Daifuku Co., Ltd. and SSI Schaefer exemplify convergence strategies that combine physical racking infrastructure with control systems. Among North American fabricators, Interlake Mecalux and Steel King Industries occupy positions shaped by proximity to major distribution corridor construction. The competitive perimeter is compressing as warehouse management system providers extend into rack specification authority and as direct procurement relationships between end-users and manufacturers displace traditional material handling integrators.
| Leading Market Players |
|---|
| Interlake Mecalux |
| SSI Schaefer |
| Daifuku Co., Ltd. |
| Mecalux |
| Ridg-U-Rak |
| Dematic |
| Steel King Industries |
| Dexion |
| AR Racking |
| Others |
Value Network & Pricing Analysis
Direct procurement relationships between third-party logistics providers and racking manufacturers are compressing distributor margins and forcing supply chain reconfiguration toward build-to-suit fulfillment center construction. This channel disintermediation concentrates specification authority with facility engineering teams and elevates price transparency across standard versus certified rack configurations.
Pricing Analysis
Distributor margins in selective pallet racking typically range from 15-25 percent for standard configurations, collapsing to single digits for large-scale direct contracts with national fulfillment operators. Price differentiation hinges on ISO 9001 certification tier and seismic engineering documentation, with FDA-compliant cold storage installations commanding substantial premiums over ambient warehousing specifications. Cost compression in economy-tier steel configurations is intensifying because Chinese export policy volatility feeds directly into cold-rolled steel input pricing. Small independent warehouse operators exhibit the highest price sensitivity, while pharmaceutical cGMP facilities prioritize traceable material certifications over unit cost.
Supply Chain Analysis
Workforce availability constraints in the Yangtze River Delta manufacturing belt are elevating labor costs for higher-gauge structural profile production used in export-bound racking systems. Supply concentrates in China, the United States, and Germany, with cold-rolled steel, zinc-nickel coating chemistries, and polymer composite formulations serving as critical input dependencies. Single-source vulnerability in Chinese steel roll-forming capacity exposes manufacturers to energy pricing volatility and export license uncertainty. Distribution runs through material handling integrators for smaller installations, while direct manufacturer relationships dominate speculative industrial development and build-to-suit projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Selective pallet racking functions as a regulatory compounder where OSHA material handling standards and FDA food safety mandates create non-negotiable specification upgrades that sustain replacement demand regardless of macroeconomic cycles.
For Market Incumbents: Deploy captive galvanizing capacity and in-house seismic engineering certification to defend against automation-integrators bundling racking with warehouse management systems. Consolidate position in cold storage applications by securing FDA-validated coating system qualifications before REACH substance restrictions eliminate hexavalent chromium alternatives. Backward integration into steel supply hedges margin pressure from Chinese export policy volatility. For New Entrants and Emerging Players: The 40-60 percent price-point gap between premium seismic-certified configurations and economy-tier standard racks creates entry space for mid-tier specialists offering certified load ratings without full automation integration. Target independent cold storage operators in the protein and dairy distribution segment where facility engineering teams increasingly specify directly. Lead with composite upright protector bundling to differentiate on total cost of ownership rather than upfront rack pricing. For Investors and Strategic Acquirers: Asymmetric upside sits with racking manufacturers possessing both captive steel roll-forming capacity and software-hardware integration capabilities serving automated storage convergence demand. Long-term viability over a multi-year horizon rests on regulatory compliance infrastructure rather than commodity fabrication scale. Watch wireless load monitoring adoption rates in pharmaceutical cGMP facilities as the inflection indicator for premium configuration demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Seismic Engineering Certification Investment | OSHA compliance mandates in California and high-risk zones create specification barriers for uncertified competitors. |
| Composite Upright Protector Manufacturing Scale-Up | Polymer-based column guards reduce forklift impact damage in dense material handling environments. |
| Warehouse Management System Integration Partnership | Real-time rack occupancy tracking via API connectivity addresses legacy WMS friction in automation retrofits. |
| Zinc-Nickel Coating Supply Chain Requalification | REACH substance restrictions in Europe compel migration from hexavalent chromium surface treatments. |
| Direct Procurement Channel Development | Bypassing material handling integrators captures specification authority from facility engineering teams. |
Research Methodology
Coverage spans the United States, Germany, China, Japan, and India, with primary inputs from each market gathered through structured interviews with warehouse engineering directors, cold storage facility operators, material handling integrators, and steel procurement specialists at racking manufacturers. Secondary validation draws from OSHA enforcement data, FDA food safety guidance documents, EU Machinery Directive implementation reports, and customs trade statistics for cold-rolled steel structural profiles. Bottom-up installation tracking across major distribution corridors triangulates against top-down steel consumption estimates for warehouse construction applications.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon, with segmentation modeling across rack architecture type, application environment, material specification, and end-use industry vertical. CAGRs derive from facility construction pipeline analysis, automation integration adoption curves, and replacement cycle timing for aging rack installations. Industry-specific forecast inputs include e-commerce fulfillment center build rates and pharmaceutical cold storage capacity expansion tied to temperature chain validation requirements.
Caveats apply where seismic code revisions, steel tariff implementations, or warehouse automation technology discontinuities could materially shift the outlook for selective racking demand. Forecasts reflect assumptions regarding sustained cold chain investment and continued OSHA enforcement intensity. Material deviation in Chinese steel export policy or automated storage retrieval system cost curves warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Industrial Fasteners Market
Material Handling Equipment
Pipe Clamp Market
Material Handling Equipment
Elevator Ropes Market
Material Handling Equipment
Loader Bucket Attachments Market
Material Handling Equipment
Automated Material Handling (AMH) Equipment Market
Material Handling Equipment
Die Casting Market
Material Handling Equipment
Global Cargo Handling Equipment Market
Material Handling Equipment
Rolling Mill Machine Market
Material Handling Equipment
Stacker Market
Material Handling Equipment
Hoist Chains Market
Material Handling Equipment
Telehandler Market
Material Handling Equipment
Heavy Duty Ramp Market
Material Handling Equipment
North America Industrial Duct for Dust Collection Market
Material Handling Equipment
Global Precision Gearboxes Market
Material Handling Equipment
Global Rolling Mill Rolls Market
Material Handling Equipment
Container Handling Equipment Market