
 Pedestal Boom System Market | 2026-2036
Pedestal Boom System Market Size, Share, and Industry Trends Forecast 2026-2036
Pedestal Boom System Market Analytics
The pedestal boom system market is recalibrating around a widening split between premium remote-operated units with integrated automation and commodity-grade hydraulic booms serving cost-sensitive quarry operators. Sandvik AB leverages its automation software stack to command premium positioning in mining applications where teleremote operation reduces personnel exposure. NPK Construction Equipment, Inc. anchors the North American aftermarket through dense dealer coverage and rebuild program infrastructure. Tecman Rock Breakers specializes in custom-engineered boom geometries for narrow-vein underground operations where standard configurations fail.
A pedestal boom system comprises a stationary or semi-mobile base column, articulated arm assembly, and mounted breaker or tool head designed for repetitive rock fragmentation, material handling, or demolition at fixed industrial sites. Hydraulic systems dominate product type segmentation due to superior impact energy density and proven reliability in dust-laden mining environments; electric booms gain traction in underground settings where emissions compliance restricts diesel-hydraulic power packs. Application segmentation shows mining sustaining the largest revenue pool while construction rental fleets drive unit volume through shorter replacement cycles. Installation type preferences skew fixed for primary crusher stations and semi-mobile for quarry face operations requiring periodic repositioning.
OSHA workplace safety standards and the EU Machinery Directive mandate guarding, emergency stop integration, and operator isolation features that elevate engineering costs but barrier out uncertified imports. Australia's state mining regulators enforce mandatory hazard identification protocols that favor pedestal booms with documented fatigue-life analysis and third-party structural certification. Stakeholders must weigh automation readiness against total cost of ownership as end users increasingly specify fleet-wide telemetry compatibility and predictive maintenance interfaces in procurement criteria.
Market Dynamics
Remote-operated pedestal boom systems are displacing manual breaker fleets across surface and underground mining operations as OSHA and EU Machinery Directive mandates harden around operator isolation and emergency-stop integration. Tier-one miners in Australia's Pilbara region now specify teleremote compatibility as a procurement gate, forcing engineering upgrades across the supplier base.
Growth Catalysts
- OSHA workplace safety mandates:US mining operations face escalating penalties for manual rock-breaking exposure, accelerating capital allocation toward guarded, remote-operated pedestal systems with documented fatigue-life certification.
- Underground emissions compliance:Diesel-hydraulic power pack restrictions in European and Australian deep mines are pulling electric boom installations into development roadmaps ahead of original replacement schedules.
- Autonomous extraction compatibility:Pilbara iron ore majors require fleet-wide telemetry integration and predictive maintenance interfaces, creating specification pull-through for automation-ready pedestal booms.
Market Restraints
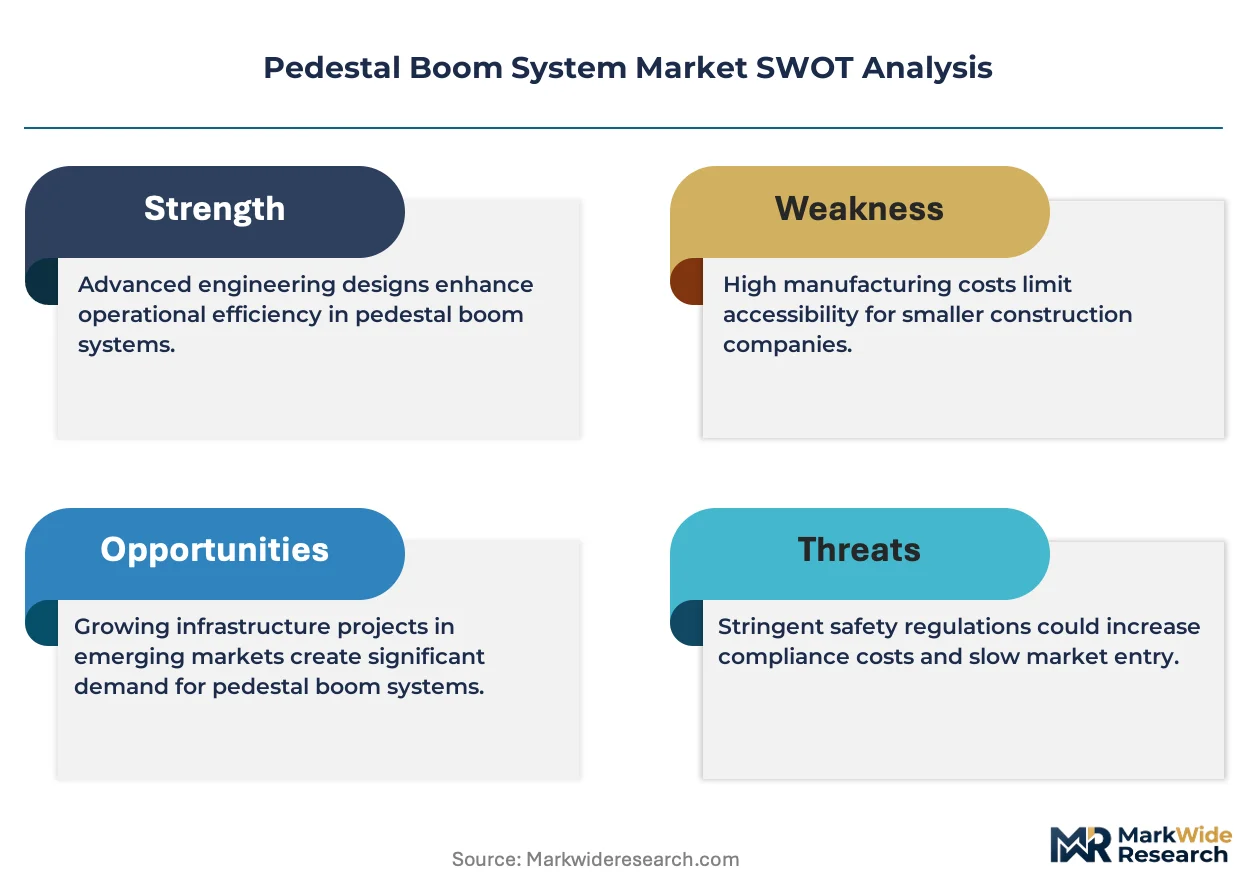
- High-grade alloy supply concentration:Articulated arm fabrication depends on specialized steel grades sourced through concentrated European and Japanese mill networks, exposing lead times to geopolitical friction.
- EU Machinery Directive compliance costs:Third-party structural certification, guarding integration, and emergency-stop system validation add engineering overhead that commodity-grade quarry operators resist absorbing.
- Used equipment substitution:Rebuilt hydraulic booms from North American aftermarket channels underprice new certified units, capturing budget-constrained construction rental fleets.
Strategic Opportunities
- Underground narrow-vein mining:Chilean and Canadian hardrock operations lack purpose-engineered boom geometries for restricted headings, creating white space for custom arm configurations.
- Construction equipment rental digitization:Telematics-enabled rental platforms in the US and Germany are opening channel access for shorter-cycle pedestal boom deployments outside traditional mining procurement.
- Australian state mining regulator protocols:Mandatory hazard identification documentation requirements favor suppliers with pre-certified fatigue analysis, creating compliance-based preference lock-in.
Industry Challenges
- Teleremote operator certification gaps:Mining contractors struggle to source personnel qualified in simultaneous boom manipulation and crusher feed optimization, slowing automation ROI realization.
- Legacy hydraulic system integration:Semi-mobile quarry installations face control architecture mismatches when retrofitting remote-operation kits onto existing fixed-base columns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pedestal Boom System Market |
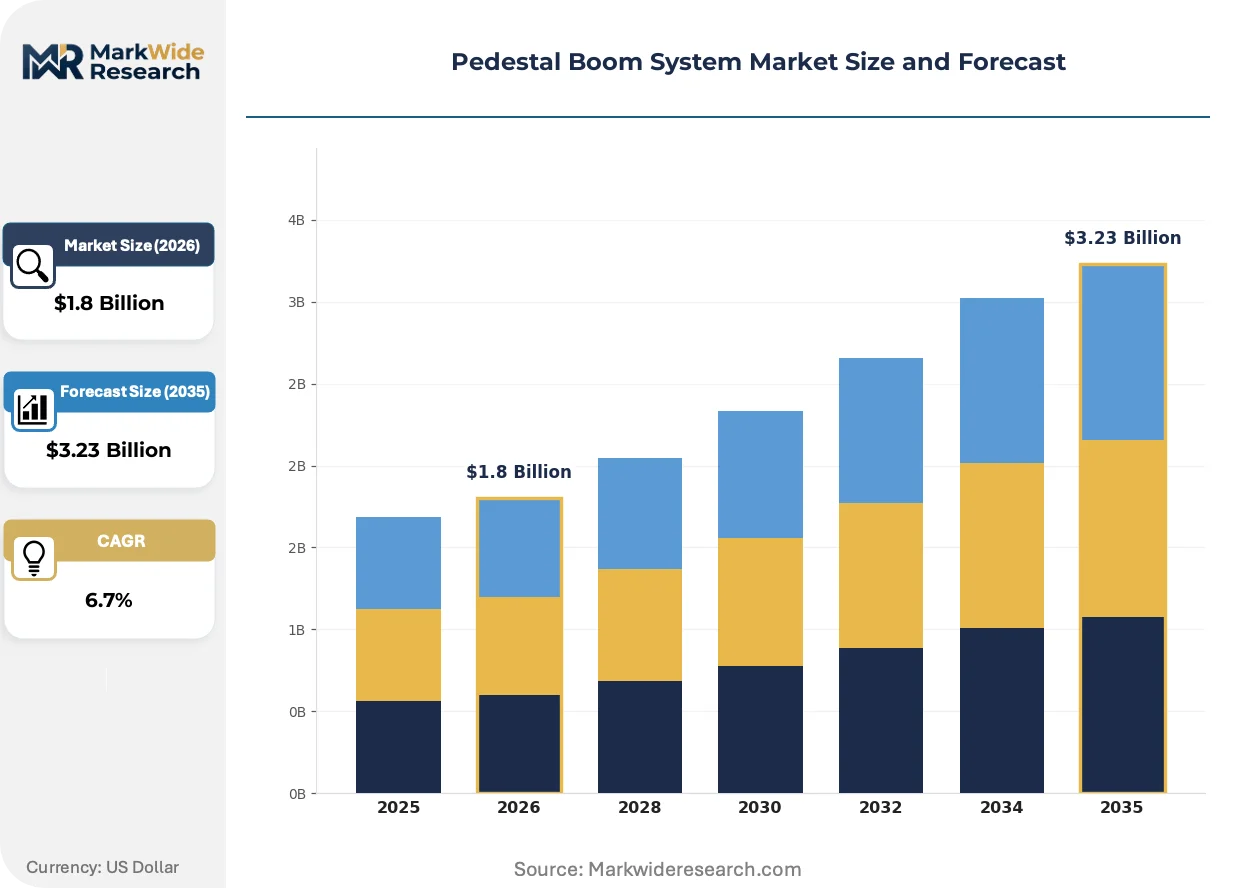
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Boom, Electric Boom, Pneumatic Boom, Manual Boom Application: Construction, Mining, Oil & Gas, Marine End User: Contractors, Equipment Rental Companies, Mining Firms, Shipping Companies Installation Type: Fixed, Mobile, Semi-Mobile, Stationary |
| Companies Covered | NPK Construction Equipment, Inc., Okada America Inc., Allied Pedestal Boom Systems, LLC, Metso Corporation, Sandvik AB, Pierce Pacific Manufacturing, Inc., INDECO IND. SpA, Tecman Rock Breakers, Tramac Equipment Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pedestal Boom System Market Evolving Landscape
Electrification and automation are converging to redefine pedestal boom system architecture, with hydraulic power packs giving ground to electric drives and standalone operation yielding to integrated fleet telemetry. These shifts are compressing supplier differentiation around software competence rather than mechanical engineering alone.
Electric drive systems are absorbing the underground mining segment previously dominated by diesel-hydraulic configurations, with zero-emission powertrains now specified for development headings in EU and Australian deep mines. Sandvik and specialist vendors are accelerating electric boom rollouts to satisfy ventilation-constrained customers. The technology is absorbing engineering talent and R&D budgets from conventional hydraulic programs, narrowing the supplier field to electrification-capable manufacturers.
The EU Machinery Directive's 2023 guarding and emergency-stop amendments are forcing redesign cycles across European-sourced pedestal boom portfolios, with compliance validation now extending to software safety integrity levels. Manufacturers serving EU-registered mining operations must recertify existing product lines or exit the market. Underground installations in Germany and Poland face the steepest compliance timelines, with procurement frozen pending third-party validation.
After-sales service unbundling is disrupting traditional full-service contracts in North American quarry markets, with rental fleet operators purchasing base equipment and sourcing maintenance through independent hydraulic service networks. This fragmentation compresses OEM margin capture and shifts competitive emphasis to parts availability and technical documentation quality. The pattern is most visible in US construction aggregates regions where dealer density supports alternative service channels.
Pedestal Boom System Market Segmentation
Pedestal boom procurement diverges sharply between capital-intensive mining operators seeking decades-long service life and rental fleets cycling equipment through shorter construction contracts. Specification requirements vary by installation permanence, emission constraints, and automation readiness.
Product Type:
Cost tier separates buyers seeking premium remote-operated systems from quarry operators prioritizing replacement part availability.
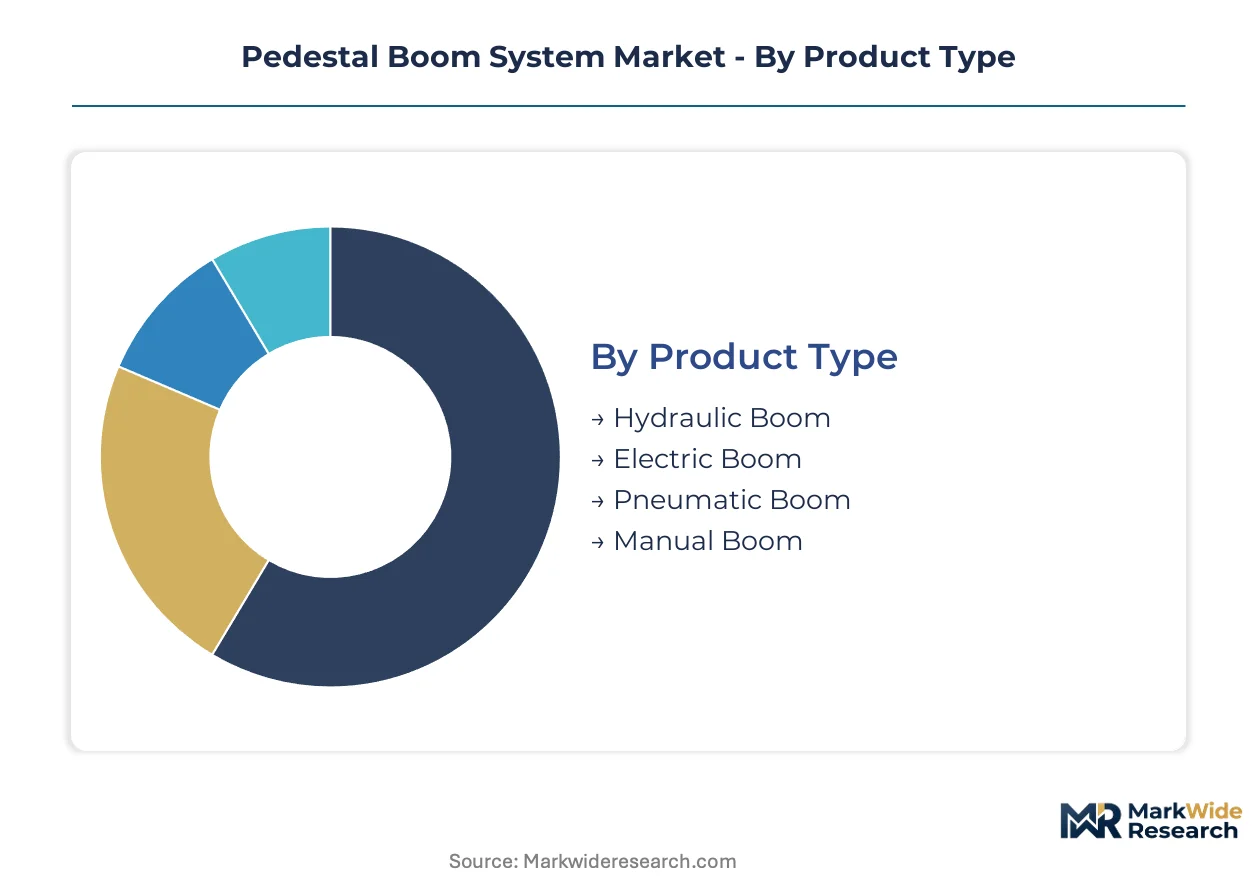
- Hydraulic Boom:Diesel-hydraulic power packs deliver superior impact energy density for primary rock breaking at gyratory crusher stations. Demand concentrates in Australia's Pilbara iron ore region where tier-one miners pursue autonomous extraction compatibility with fleet-wide telemetry integration.
- Electric Boom:Zero-emission drive systems eliminate ventilation load in underground headings where diesel restrictions apply. EU and Australian deep mines are pulling electric installations ahead of original replacement schedules to satisfy emissions compliance mandates.
- Pneumatic Boom:Compressed-air systems serve explosive atmospheres in underground coal operations where ignition risk restricts electrical and hydraulic alternatives.
- Manual Boom:Unpowered configurations persist in small-scale quarry face operations with limited capital budgets and minimal safety oversight.
Volume sits with hydraulic configurations; growth tilts toward electric systems as underground emissions rules harden.
Application:
Application maturity determines whether buyers specify automation-ready architectures or commodity-grade mechanical systems.
- Mining:Surface and underground hardrock operations sustain the largest revenue pool through primary crusher installations and development heading fragmentation. Australia's state mining regulators enforce mandatory hazard identification protocols favoring booms with documented fatigue-life analysis.
- Construction:Rental fleets drive unit volume through shorter replacement cycles in demolition and aggregate processing. North American aftermarket channels capture budget-constrained operators through rebuilt hydraulic boom substitution.
- Oil & Gas:Offshore platform maintenance and wellhead demolition require corrosion-resistant coatings and explosion-proof electrical enclosures.
- Marine:Port infrastructure and shipbreaking yards demand extended reach configurations for bulk carrier dismantling.
Revenue concentrates in mining; construction delivers the steepest expansion trajectory through rental fleet digitization.
End User:
Customer type dictates procurement complexity, from single-unit rental transactions to multi-year fleet agreements with predictive maintenance clauses.
- Mining Firms:Tier-one operators in Chile and Australia specify teleremote compatibility and third-party structural certification as procurement gates. These buyers demand integration with autonomous haulage and crusher control systems.
- Equipment Rental Companies:Shorter asset cycles favor standard hydraulic configurations with dense dealer service coverage. US construction aggregates regions support alternative maintenance channels through independent hydraulic service networks.
- Contractors:Project-based procurement favors semi-mobile installations requiring periodic repositioning between quarry faces.
- Shipping Companies:Vessel dismantling and port maintenance operations drive demand for extended-boom geometries with marine-grade corrosion protection.
Procurement volume flows through rental channels; specification pull originates with mining firms mandating automation readiness.
Installation Type:
Mobility requirements separate fixed infrastructure investments from repositionable assets serving evolving extraction geometries.
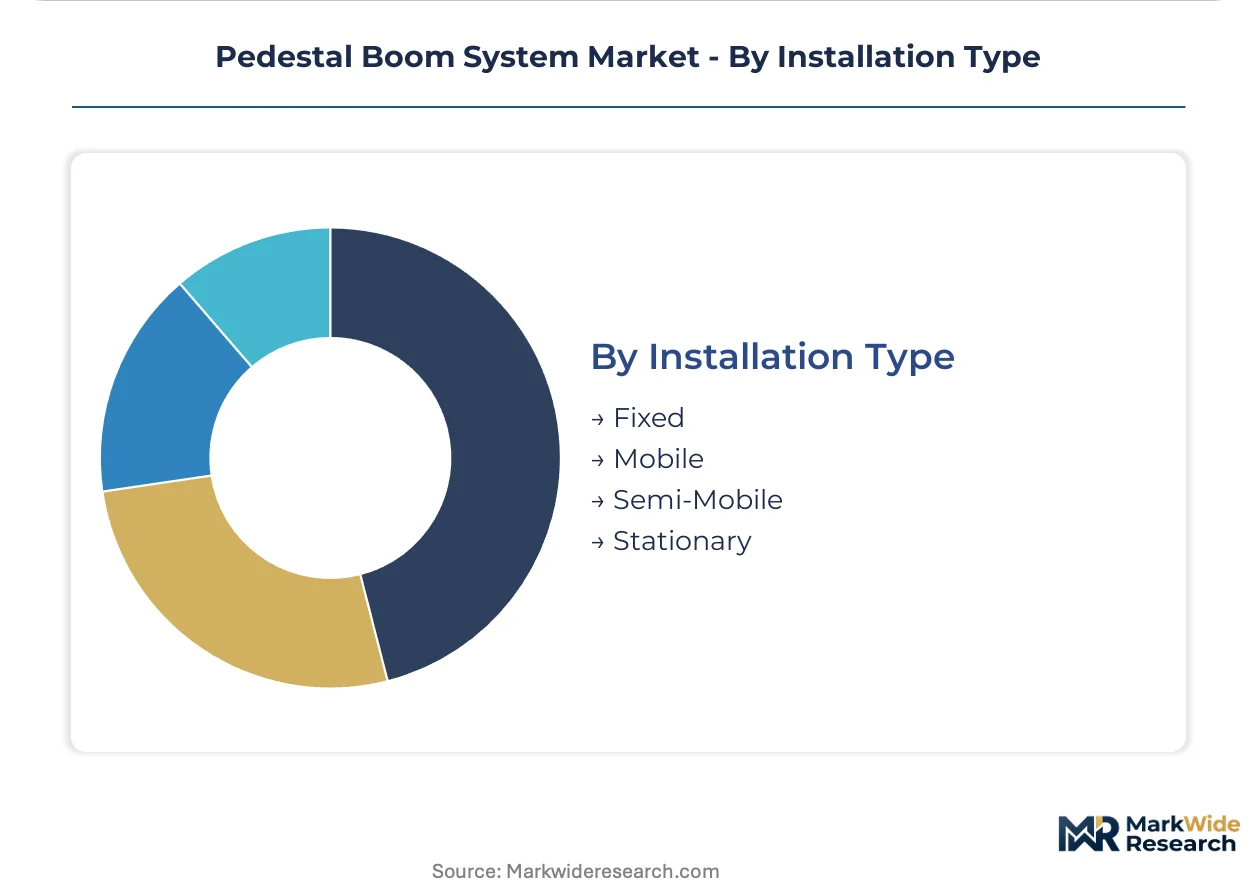
- Fixed:Permanent mounting at primary crusher stations demands fatigue-life certification and emergency-stop integration under OSHA and EU Machinery Directive mandates. These installations anchor the highest-value contracts.
- Semi-Mobile:Skid or rail-mounted configurations serve quarry face operations requiring periodic relocation as extraction fronts advance. Chilean and Canadian narrow-vein underground operations lack purpose-engineered geometries for restricted headings.
- Mobile:Trailer-mounted systems support construction demolition contracts with rapid site-to-site transfer requirements.
- Stationary:Heavy-duty base columns anchor permanent processing plant installations with decades-long service horizons.
Fixed installations command premium pricing; semi-mobile configurations gain share fastest as quarry operators seek operational flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pilbara iron ore corridor in Western Australia commands the densest concentration of pedestal boom deployments, with tier-one miners retrofitting gyratory crusher stations for autonomous haulage compatibility.
Australia
Western Australia's Pilbara region drives fleet-wide telemetry specifications as BHP and Rio Tinto mandate predictive maintenance interfaces. The country's state mining regulators enforce mandatory hazard identification protocols under Work Health and Safety laws. Perth-based engineering clusters supply fatigue-life certification services that lock in supplier preference for documented structural analysis.
Chile
Copper majors in the Atacama Desert are expanding hydraulic pedestal deployments at concentrator plants facing labor shortages. The National Geology and Mining Service enforces strict equipment certification for high-altitude operations. Antofagasta's mining services corridor concentrates aftermarket rebuild capacity serving Codelco's Chuquicamata and Escondida installations.
United States
Appalachian coal operators and Southwest copper mines face escalating OSHA penalties for manual rock-breaking exposure. The Mine Safety and Health Administration mandates guarding integration and emergency-stop systems at primary crushing stations. Arizona's Morenci copper complex and Nevada's Goldstrike operations anchor demand for remote-operated configurations.
Germany
Underground potash and salt mines in Lower Saxony are accelerating electric boom adoption ahead of diesel-hydraulic phase-out deadlines. The EU Machinery Directive's 2023 amendments force recertification of existing product lines for guarding and software safety integrity. The Ruhr industrial basin hosts specialized steel fabrication networks supplying articulated arm components.
Canada
Ontario's Sudbury Basin nickel operations and British Columbia's Highland Valley copper mine specify semi-mobile configurations for development heading flexibility. The country's provincial mining regulators align with CSA standards for fatigue-life documentation. Vancouver's mining finance cluster channels capital toward automation-ready fleet procurement.
Pedestal Boom System Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the certification-automation divide, with automation-ready suppliers capturing multi-year mining contracts while rebuild-focused dealers serve construction rental cycles. The supplier base organizes into three tiers: integrated mining technology conglomerates, specialized boom fabricators, and regional aftermarket rebuilders. Consolidation pressure concentrates among mid-scale hydraulic specialists lacking electrification roadmaps. Dominant competitive moves include backward integration into fatigue-analysis certification services and strategic partnerships with autonomous haulage system vendors.
Within the premium automation tier, Sandvik AB and Metso Corporation occupy positions defined by software-stack integration and fleet telemetry compatibility. NPK Construction Equipment, Inc. anchors the North American aftermarket through dealer density and rebuild program infrastructure. Tecman Rock Breakers exemplifies the specialized fabricator archetype, occupying a position tied to custom-engineered geometries for restricted underground headings.
| Leading Market Players |
|---|
| NPK Construction Equipment, Inc. |
| Okada America Inc. |
| Allied Pedestal Boom Systems, LLC |
| Metso Corporation |
| Sandvik AB |
| Pierce Pacific Manufacturing, Inc. |
| INDECO IND. SpA |
| Tecman Rock Breakers |
| Tramac Equipment Ltd. |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap fabricators in Northern Italy and Japan's Chubu region anchor specialized steel forging capacity for articulated arm production, concentrating pricing power among European and Japanese mill networks while forcing buyers into long-term offtake arrangements or premium spot premiums.
Pricing Analysis
Outcome-based pricing tied to crusher throughput uptime anchors premium tiers for automation-ready pedestal booms serving Pilbara iron ore operators. Three-tier pricing structure across premium, standard, and economy levels separates teleremote-certified systems with fatigue-life documentation from commodity hydraulic units and rebuilt aftermarket alternatives. Cost compression in the construction rental tier is intensifying because independent hydraulic service networks unbundle after-sales support and undercut OEM service contracts. Mining firms with fleet-wide telemetry mandates show least price sensitivity; budget-constrained quarry operators in North American aggregates regions exhibit highest elasticity.
Supply Chain Analysis
Australian state mining regulator protocols mandating domestic-content documentation for structural certification are reshaping sourcing patterns for fatigue-analysis services and third-party validation. Articulated arm fabrication draws from specialized high-grade alloy steel mills concentrated in Germany, Japan, and Sweden; hydraulic power pack components source from established industrial clusters in the United States and Finland. Single-source vulnerability concentrates in European steel grade supply for fatigue-critical boom geometries. Distribution runs through OEM-direct channels for mining fleet procurement and dense dealer networks for construction rental fleet replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as suppliers pursue captive control over fatigue-life certification services to lock in compliance-based preference with Australian and Chilean mining regulators.
For Market Incumbents: Anticipate margin compression from rebuilt hydraulic boom substitution in North American construction channels by deepening backward integration into aftermarket rebuild program infrastructure. Lock in multi-year fleet agreements with tier-one miners by embedding predictive maintenance interfaces and telemetry compatibility as non-negotiable procurement gates. Prioritize certification investment for EU Machinery Directive software safety integrity levels to freeze out non-compliant competitors.
For New Entrants and Emerging Players: Launch via telematics-enabled rental platforms in US construction aggregates regions and German equipment leasing markets to bypass entrenched OEM-direct mining procurement channels. Target narrow-vein underground mining in Chilean and Canadian hardrock operations where purpose-engineered boom geometries remain undersupplied. Pursue custom arm configuration partnerships with regional mining services contractors lacking in-house engineering capacity.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale hydraulic specialists lacking electrification roadmaps in European industrial basins where diesel-hydraulic phase-out deadlines strand legacy product portfolios. Long-term viability over the coming decade hinges on software-stack competence and automation integration rather than mechanical fabrication scale alone. Watch Australian state regulator adoption of mandatory autonomous haulage compatibility as the signal for specification pull-through acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fatigue-Life Certification | Captures compliance-based preference lock-in with Australian state mining regulators enforcing Work Health and Safety documentation mandates. |
| Electric Drive System Product Line Expansion | Addresses EU and Australian underground emissions restrictions pulling zero-emission installations ahead of replacement schedules. |
| Telematics Platform Partnership | Opens channel access for shorter-cycle deployments through construction equipment rental digitization in US and German markets. |
| Custom Geometry Engineering Service | Serves Chilean and Canadian narrow-vein operations lacking purpose-engineered boom configurations for restricted headings. |
| Predictive Maintenance Interface Development | Meets Pilbara iron ore miner procurement gates mandating fleet-wide telemetry integration and crusher feed optimization compatibility. |
Research Methodology
Trade association filings, customs and import-export records, and equipment registration databases formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with mine maintenance directors, plant engineers at gyratory crusher installations, OEM procurement teams, and aftermarket service heads supplied operational validation and specification trend intelligence. Bottom-up unit deployment tracking across Australia's Pilbara region, Chile's Atacama Desert, and North American copper belts combined with top-down capital expenditure analysis from mining firm disclosures to establish market boundaries.
Bottom-up modeling of installed base replacement cycles and fleet expansion programs across the projection horizon anchored volume forecasts, while value outputs reflected tiered pricing segmentation by automation readiness and certification grade. Segmentation dimensions included product type, application maturity, installation permanence, emission constraint profile, and end-user procurement complexity. CAGRs were derived from regression analysis of historical capital equipment deployment patterns against regulatory mandate timelines and autonomous extraction adoption curves.
Regulatory enforcement variance, commodity price volatility affecting mining capital allocation, and teleremote operator certification availability are the dominant revision risks that could compress or extend replacement schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Slow Speed Shredding Machines Market
Material Handling Equipment
Heavy Equipment Movers Market
Material Handling Equipment
Industrial Static Equipment Market
Material Handling Equipment
Material Handling Equipment Tires Market
Material Handling Equipment
Clinching Machines Market
Material Handling Equipment
Trommel Screen Market
Material Handling Equipment
Global Warehouse Racking Market
Material Handling Equipment
Truck Mounted Cranes Market
Material Handling Equipment
Pneumatic Conveying Systems Market
Material Handling Equipment
Construction Lifts Market
Material Handling Equipment
High-Pressure Die Casting Market
Material Handling Equipment
North America Forklift Market
Material Handling Equipment
Industrial Jacks Market
Material Handling Equipment
Vertical Baling Press Market
Material Handling Equipment
Sorting Equipment Market
Material Handling Equipment
Global Large Conveyor Chain Market