
 Cut-To-Length Line Systems Market | 2026-2036
Cut-To-Length Line Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Cut-To-Length Line Systems Market Analysis
The capital-intensity divergence between players is unwinding as tier-1 equipment makers separate from mid-size fabricators on automation depth and in-house control-system development. SMS Group leverages its integrated metallurgical technology stack to anchor large-scale steel processor contracts across Europe. Heinrich Georg GmbH sustains precision engineering leadership through dedicated R&D on high-tension leveling subsystems. FIMI Group competes on flexible line configurations that accommodate both steel and aluminum coil without mechanical changeover delays.
Cut-to-length line systems are industrial metal processing equipment that uncoil, flatten, measure, shear, and stack flat-rolled material to precise customer-specified lengths, typically operating at line speeds exceeding 150 meters per minute for thin-gauge steel. These systems serve primary metal service centers and integrated manufacturers requiring dimensional accuracy within ±0.5 millimeter tolerance for downstream stamping, welding, and assembly operations. Automatic product types dominate installed base value due to labor-cost arbitrage and throughput requirements in high-volume automotive blanking. Hybrid configurations represent the fastest-expanding segment as processors seek to retrofit existing mechanical lines with servo-electric shear and stacker modules. Steel material processing commands the largest application share, though aluminum lines are gaining share in automotive lightweighting programs where OEMs and Tier-1 Suppliers specify tailored blank geometries.
CE marking under the EU Machinery Directive and OSHA machine-guarding standards in the United States enforce interlocked safety architectures and emergency-stop redundancy that elevate system cost but reduce liability exposure for end users. China's GB standards for metal forming equipment and Japan's JIS certification requirements create additional compliance layers for suppliers seeking access to Asian automotive supply chains. Stakeholders must monitor servo-electric technology maturation against conventional mechanical drive economics, as the tipping point for full electrification will reshape maintenance revenue models and aftermarket parts demand.
Market Dynamics
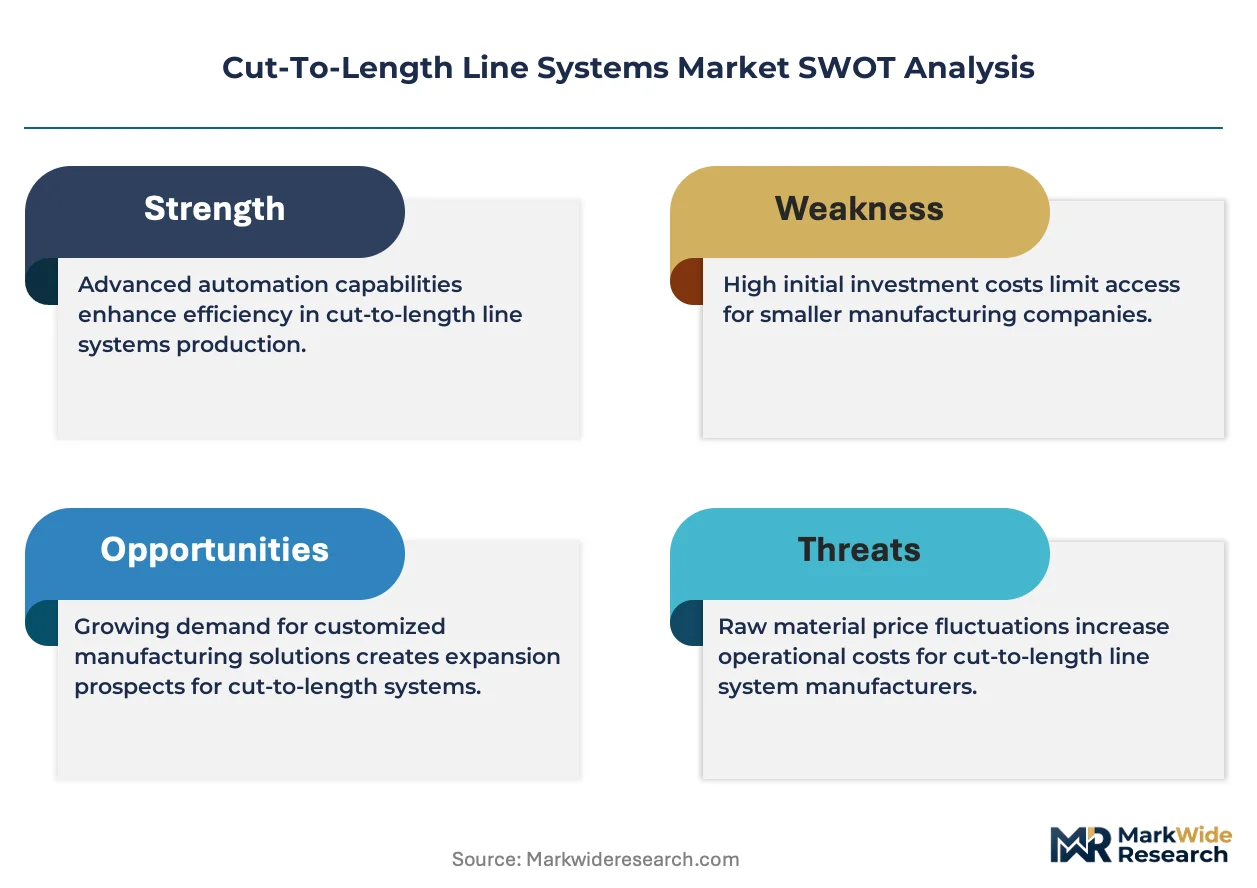
Servo-electric shear and drive technology is compressing the total cost of ownership differential against mechanical systems, forcing incumbent fabricators to retool or exit mid-market segments entirely.
Growth Catalysts
- EPA emissions standards:North American metal processors face mandates to replace hydraulic systems with energy-efficient servo drives, accelerating replacement cycles for legacy equipment.
- Automotive lightweighting programs:OEMs specify tailored aluminum blank geometries that require precision leveling and shearing capabilities beyond conventional steel lines.
- Germany's automotive cluster concentration:Dense machinery and steel processing ecosystems in Baden-Württemberg and North Rhine-Westphalia sustain above-average investment rates in high-speed processing equipment.
Market Restraints
- Copper and rare-earth magnet cost volatility:Servo-electric line builds depend on permanent magnet motors and high-grade copper windings, exposing margins to commodity swings.
- Control system supplier concentration:Proprietary PLC and motion-control architectures from a limited set of European automation vendors create single-source dependencies for tier-2 fabricators.
- REACH chemical compliance:Restrictions on hydraulic fluids and surface treatment chemistries extend commissioning timelines for mechanical-to-servo retrofits.
Strategic Opportunities
- India's PLI scheme for specialty steel:Domestic capacity expansion under production-linked incentives creates demand for cut-to-length lines serving cold-rolled and coated product mills.
- CE marking and EU Machinery Directive convergence:Unified safety and interoperability standards reduce certification duplication costs for suppliers targeting multiple European markets.
- Digital twin integration with cloud-based maintenance:Convergence of physics-based modeling and predictive analytics enables remote commissioning and outcome-based service pricing.
Industry Challenges
- Motion-control engineering talent scarcity:Servo-electric line commissioning requires specialized expertise in multi-axis synchronization that outpaces vocational training pipeline output.
- Legacy mechanical line integration:Retrofit projects face mechanical interface mismatches and control architecture incompatibilities that extend project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cut-To-Length Line Systems Market |
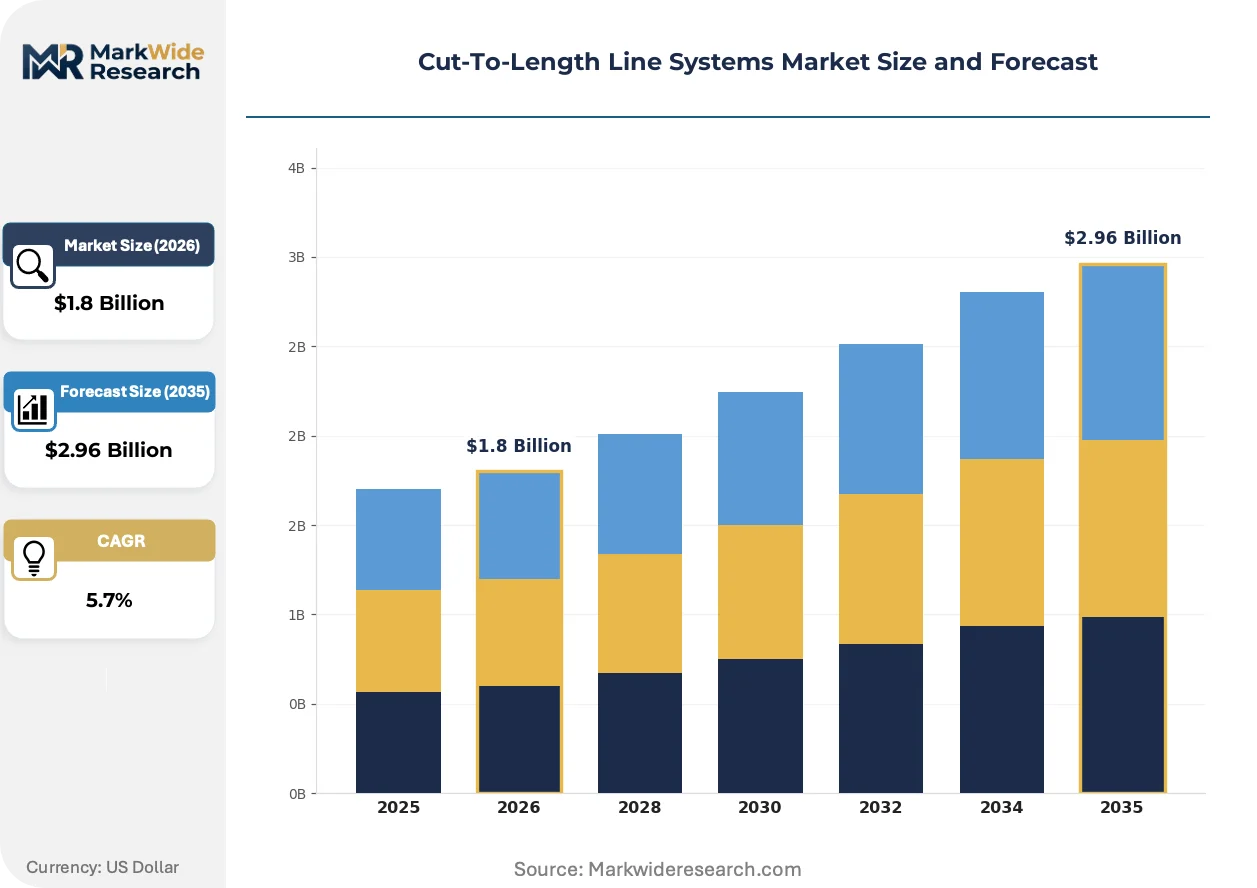
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Hybrid Material: Steel, Aluminum, Plastic, Composite Application: Construction, Automotive, Aerospace, Manufacturing End User: OEMs, Tier-1 Suppliers, Fabricators, Machine Shops |
| Companies Covered | Prima Power, SMS Group, Heinrich Georg GmbH, ANDRITZ AG, ARKU GmbH, FIMI Group, Baumer Group, Häfner GmbH, LPR Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cut-To-Length Line Systems Market Emerging Trajectories
Servo-electric architectures are rewriting the competitive economics of metal processing equipment, compressing maintenance revenue pools while opening new service monetization channels.
Direct-drive servo motors with integrated encoders are supplanting mechanical flywheel and clutch-brake shear drives in thin-gauge steel applications. Tier-1 automotive blanking operations in Germany and the United States have adopted full servo lines for runs below 2 millimeter gauge, eliminating mechanical wear components and reducing changeover downtime. This shift is compressing aftermarket parts demand for clutch plates and brake bands while expanding software-based performance optimization contracts.
REACH compliance deadlines for industrial hydraulic fluids are accelerating phase-out timelines for wet clutch systems across European metal service centers. The regulation forces processors to either retrofit existing mechanical lines with dry shear mechanisms or commission entirely new servo-electric configurations. Steel service centers in Belgium and the Netherlands report extended procurement cycles as they evaluate total cost of ownership across compliance-adjusted equipment lifespans.
Blanking operations are consolidating procurement authority from plant-level engineers to corporate capital planning functions with standardized total-cost-of-ownership models. Equipment specification decisions now route through centralized engineering teams that prioritize interoperability and remote diagnostics over localized vendor relationships. This concentration is most visible among North American automotive Tier-1 suppliers with multi-plant footprints, where corporate mandates favor single-platform standardization across stamping facilities.
Cut-To-Length Line Systems Market Segmentation
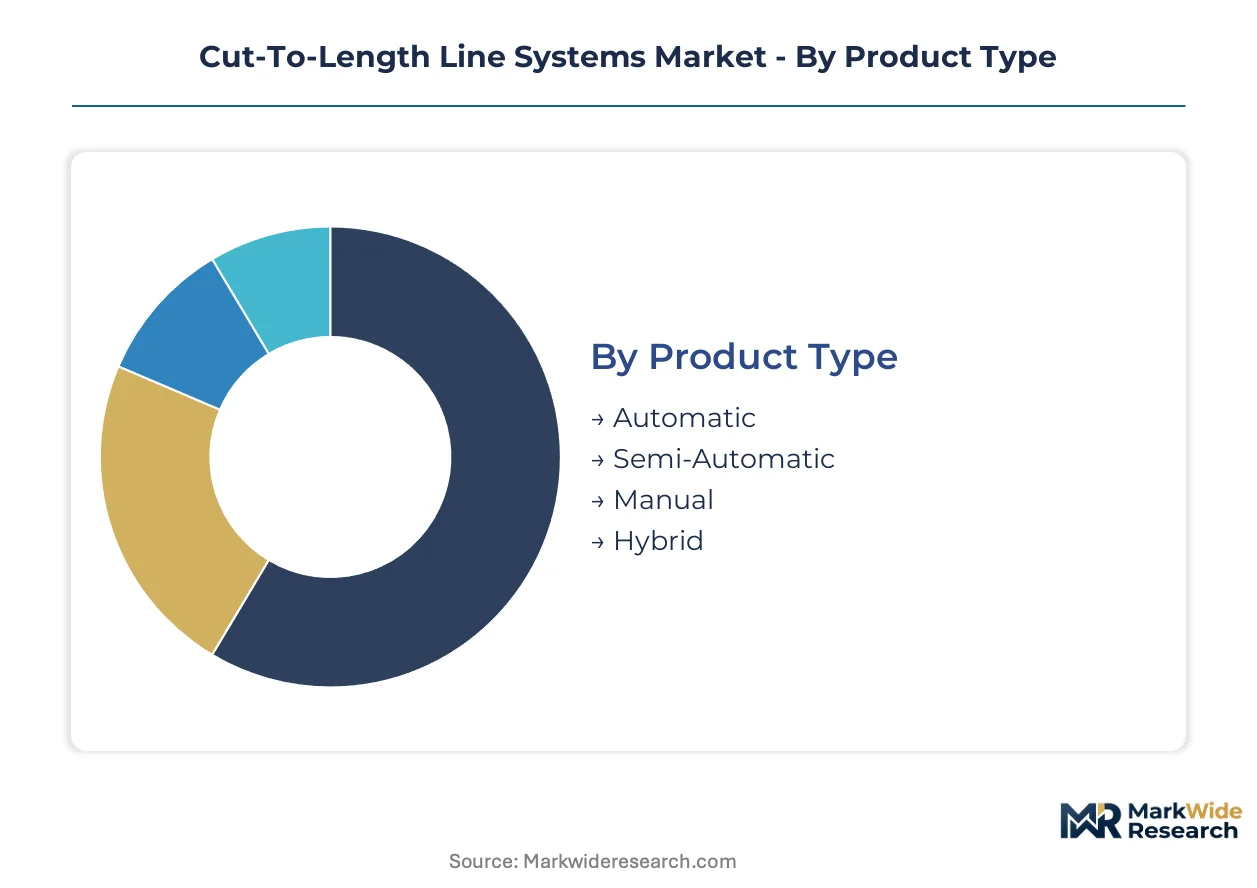
Cut-to-length line procurement channels diverge sharply by automation depth and material specification. Metal service centers route high-volume steel contracts through integrated OEM-direct channels, while aluminum lightweighting programs and retrofit projects flow through specialized system integrators.
Product Type:
Automatic and hybrid configurations dominate direct OEM procurement, with servo-electric architectures consolidating share in automotive blanking operations. Semi-automatic and manual systems persist in job-shop distribution through regional machinery dealers.
- Automatic:Full servo-electric architectures with integrated uncoiling, leveling, shearing, and stacking modules achieve line speeds exceeding 150 meters per minute. Demand concentrates in German automotive clusters where Baden-Württemberg OEMs specify precision blanking for high-volume stamping operations.
- Hybrid:Retrofit configurations combine existing mechanical uncoilers and levelers with servo-electric shear and stacker upgrades. North American metal processors favor this path to satisfy EPA emissions mandates without full line replacement.
- Semi-Automatic:Operator-assisted material handling with automated shear and stacker functions serves mid-volume service centers balancing throughput against capital constraints.
- Manual:Hand-fed configurations with mechanical shear drives persist in small-batch fabrication shops and developing-market machine shops with limited automation budgets.
Automatic lines dominate installed base value in automotive-direct channels. Hybrid configurations are where expansion concentrates as regulatory pressure accelerates mechanical-to-servo transitions.
Material:
Material specification determines leveling subsystem complexity and shear drive torque requirements, creating distinct margin tiers across processor contracts.
- Steel:Cold-rolled and hot-rolled carbon steel processing commands the largest equipment installed base, with high-tension leveling requirements for automotive exposed-panel grades. German and U.S. Gulf Coast service centers sustain replacement demand for thin-gauge precision lines.
- Aluminum:Automotive lightweighting programs specify tailored blank geometries with strict flatness tolerances for hood, door, and structural applications. Tier-1 suppliers in Michigan and Ontario drive specification authority toward dedicated aluminum-capable configurations.
- Plastic:Coil-fed thermoplastic processing for appliance and electronics housings requires heated leveling zones and specialized shear blade materials.
- Composite:Fiber-reinforced polymer coils for aerospace and wind energy applications demand precision tension control to prevent delamination during uncoiling and shearing.
Steel maintains volume leadership across metal service center procurement. Aluminum is climbing the fastest as OEM lightweighting mandates reshape material specifications.
Application:
Application end-use dictates tolerance specifications, stacker automation depth, and integration requirements with downstream stamping or welding cells.
- Automotive:Blanking operations for body-in-white and structural components require ±0.5 millimeter length tolerance and automated destacking for robotic transfer press feeding. Corporate procurement consolidation among multi-plant Tier-1 suppliers standardizes platform specifications across stamping facilities.
- Construction:Structural steel and decking processors prioritize throughput over absolute precision, favoring mechanical shear economics for standard beam and purlin lengths.
- Aerospace:Titanium and aluminum precision blanking for airframe components demands specialized leveling for high-strength alloys and traceable quality documentation.
- Manufacturing:General industrial metal service centers process mixed material portfolios with quick-changeover flexibility between steel gauges and aluminum alloys.
Automotive applications anchor premium pricing tiers through precision and automation requirements. Construction represents the highest-volume, lowest-margin channel for standard mechanical configurations.
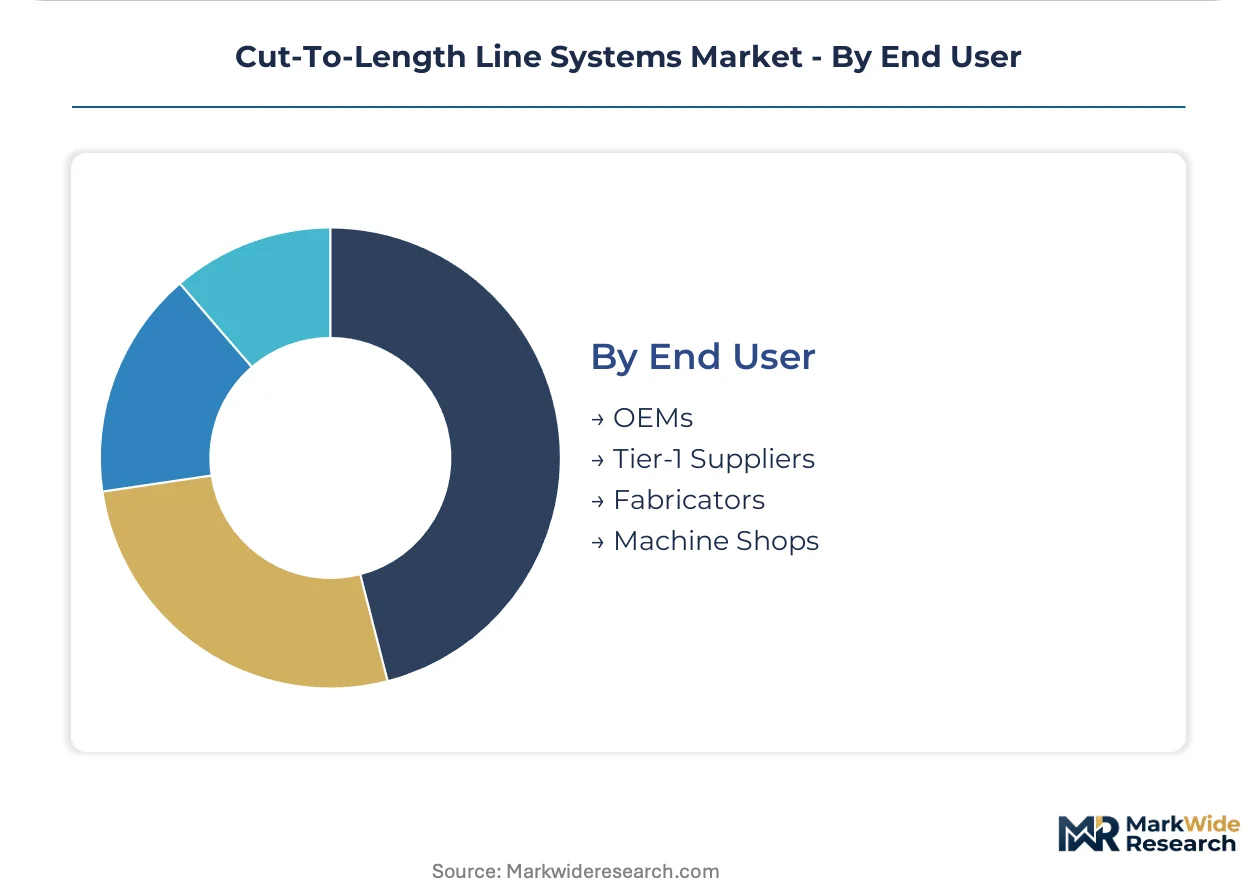
End User:
End-user scale and integration depth determine specification authority, with centralized engineering teams displacing plant-level procurement autonomy.
- OEMs:Integrated automotive and appliance manufacturers with captive blanking operations specify total-cost-of-ownership models prioritizing energy efficiency and remote diagnostics interoperability.
- Tier-1 Suppliers:Multi-plant stamping specialists with corporate engineering mandates favor single-platform standardization across facilities in Germany, the United States, and Mexico.
- Fabricators:Independent metal service centers balance material versatility against capital efficiency, often selecting hybrid retrofits over greenfield servo lines.
- Machine Shops:Small-batch processors with project-based demand rely on manual or semi-automatic systems through regional distributor networks.
OEMs and Tier-1 Suppliers concentrate specification authority and drive technology adoption curves. Fabricators and machine shops sustain mid-market mechanical equipment demand through replacement and limited retrofit investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in precision metal processing equipment favor established manufacturing clusters with deep automotive supply chain integration. Equipment flows concentrate from German and Italian fabricators toward emerging Asian steel processing capacity. Currency volatility and localized content requirements increasingly shape procurement decisions.
Germany
Automotive OEMs in Baden-Württemberg and North Rhine-Westphalia sustain replacement demand for high-speed servo-electric lines. REACH compliance deadlines for hydraulic fluids accelerate mechanical-to-servo retrofits across metal service centers. The Stuttgart machinery cluster anchors specification authority for European blanking operations.
United States
EPA emissions mandates drive hydraulic system phase-outs among Gulf Coast and Midwest steel processors. Tier-1 automotive suppliers in Michigan consolidate procurement across multi-plant footprints. The Detroit-Windsor corridor concentrates demand for aluminum-capable configurations serving lightweighting programs.
China
GB standards for metal forming equipment create compliance layers for foreign suppliers accessing automotive supply chains. Domestic cold-rolled and coated steel capacity expansion under dual carbon goals generates equipment demand. Yangtze River Delta processors prioritize energy-efficient configurations to meet provincial emissions targets.
India
The PLI scheme for specialty steel attracts cold-rolled and coated product mill investments requiring cut-to-length integration. BIS certification requirements shape equipment specification for automotive-grade processing. Maharashtra and Gujarat metal service centers drive initial servo-electric adoption among domestic fabricators.
Japan
JIS certification requirements enforce quality documentation standards for precision blanking equipment. METI efficiency standards push domestic processors toward servo drive retrofits. The Nagoya automotive cluster maintains demand for high-tension leveling subsystems serving exposed-panel grades.
Cut-To-Length Line Systems Market Vendor Landscape
Concentration sits with integrated metallurgical technology providers and precision engineering specialists that control in-house motion-control development. Tier-1 equipment makers separate from mid-size fabricators on automation depth and servo-electric integration capabilities. Strategic archetypes include integrated technology stack providers, flexible line configuration specialists, and regional system integrators. Competitive moves center on strategic partnerships for control system access and geographic expansion into emerging Asian steel processing markets.
Within the integrated technology tier, SMS Group and Heinrich Georg GmbH exemplify divergent paths: the former anchors large-scale steel processor contracts through metallurgical integration, while the latter occupies a precision engineering position through dedicated R&D investment. FIMI Group represents the flexible configuration archetype, accommodating multi-material processing without mechanical changeover delays. These three entities collectively illustrate how automation depth and control-system ownership determine competitive positioning.
| Leading Market Players |
|---|
| Prima Power |
| SMS Group |
| Heinrich Georg GmbH |
| ANDRITZ AG |
| ARKU GmbH |
| FIMI Group |
| Baumer Group |
| Häfner GmbH |
| LPR Global |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at German and Italian fabrication clusters shapes both supply concentration and price floors for precision metal processing equipment. OEM-direct procurement channels leverage scale economies to compress margins for mid-tier fabricators while sustaining premium tiers for servo-electric architectures with integrated control systems.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation centers on automation depth and CE certification tier, with servo-electric lines commanding substantial premiums over mechanical configurations. Cost compression in standard-tier equipment is intensifying because tier-2 fabricators face permanent magnet motor cost volatility. Tier-1 automotive suppliers exhibit lowest price sensitivity due to total-cost-of-ownership procurement mandates, while independent metal service centers remain most price-sensitive and favor hybrid retrofit paths.
Supply Chain Analysis
Just-in-time component sourcing dominates servo-electric line builds, though strategic stockpiling of rare-earth magnets and high-grade copper windings persists among tier-1 fabricators. Supply concentrates in Germany, Italy, and China for precision leveling subsystems, motion-control hardware, and specialized shear blade materials. The chain draws from permanent magnet suppliers in China, precision bearing manufacturers in Germany, and industrial automation vendors in Italy. Single-source vulnerability in proprietary PLC architectures creates structural risk. Distribution runs through OEM-direct channels for high-volume automotive contracts and specialized system integrators for retrofit projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cut-to-length line market exhibits cyclical recovery characteristics as automotive capital expenditure cycles turn and regulatory replacement mandates accelerate equipment refresh timelines.
For Market Incumbents: Fortify control-system ownership through backward integration into motion-control hardware or exclusive partnerships with European automation vendors. Expand captive service capabilities to offset compressed aftermarket parts revenue from servo-electric transitions. Defensive positioning requires preemptive certification investment for REACH-compliant hydraulic fluid phase-outs before compliance deadlines harden procurement decisions. For New Entrants and Emerging Players: Remote commissioning and predictive maintenance service layers represent underexploited white space where incumbents under-serve mid-market fabricators. Target India's PLI-driven specialty steel capacity expansion as the most penetrable geography, where domestic equipment demand outpaces local fabrication capability. A digital-first go-to-market angle—cloud-based performance optimization contracts—sidesteps capital-intensive manufacturing barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision engineering specialists with demonstrated servo-electric integration capability over legacy mechanical fabricators. Long-term viability across the next decade hinges on control-system intellectual property ownership and aftermarket service monetization potential. The signal to watch as inflection indicator is corporate procurement consolidation among multi-plant Tier-1 suppliers favoring single-platform standardization mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motion-Control Hardware | Reduces single-source dependency on European PLC vendors while capturing margin from servo-electric transitions. |
| Servo-Electric Retrofit Service Expansion | Captures regulatory-driven replacement demand from EPA emissions mandates and REACH hydraulic fluid deadlines. |
| Digital Twin Platform Development | Enables remote commissioning and outcome-based pricing models that differentiate from equipment-only competitors. |
| Geographic Expansion into India PLI Corridors | Positions for domestic specialty steel capacity growth in Maharashtra and Gujarat processing clusters. |
| Multi-Material Line Configuration Investment | Addresses aluminum lightweighting specifications from Michigan and Ontario automotive Tier-1 suppliers. |
Methodological Framework
Desk research of trade association filings, customs records, and equipment specification databases preceded structured interviews with plant engineers, OEM procurement teams, aftermarket service heads, and maintenance directors at metal service centers. Primary fieldwork captured procurement decision criteria, replacement cycle timing, and technology adoption barriers. Secondary validation drew from SEC filings of publicly traded fabricators, EU Machinery Directive implementation guidance, and EPA emissions standard enforcement records. Bottom-up unit demand estimates triangulated against top-down capital expenditure projections from automotive and steel processing sectors.
Variance decomposition across product type, material specification, automation architecture, and regional regulatory clusters informed the analytical framework. Modeled dimensions spanned automatic, hybrid, semi-automatic, and manual configurations; steel, aluminum, plastic, and composite materials; and automotive, construction, aerospace, and manufacturing end-uses. CAGRs were derived from regression-adjusted trend extrapolation incorporating equipment lifespan assumptions and regulatory phase-out timelines. Industry-specific forecast inputs included servo-electric technology maturation curves and automotive lightweighting program specifications.
Forecasts assume regulatory continuity in EPA emissions enforcement, REACH chemical compliance, and EU Machinery Directive safety standards; material policy shifts would require re-modeling. Specific risk factors encompass rare-earth magnet supply disruption, motion-control engineering talent scarcity, and legacy mechanical line integration failures extending project timelines. Revision becomes warranted when automotive capital expenditure contraction or trade barrier escalation crosses thresholds that alter replacement cycle assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Industrial Jacks Market
Material Handling Equipment
Vapor Blasting Equipment Market
Material Handling Equipment
Hydraulic Cylinder Rod Market
Material Handling Equipment
Australia Forklift Market
Material Handling Equipment
Global Large Conveyor Chain Market
Material Handling Equipment
Elevator Ropes Market
Material Handling Equipment
Weighbridge Market
Material Handling Equipment
Push-Back Racking System Market
Material Handling Equipment
Container Handling Equipment Market
Material Handling Equipment
Global Rolling Mill Rolls Market
Material Handling Equipment
High-Density Racks Market
Material Handling Equipment
Global Refuse Compactor Market
Material Handling Equipment
Gravity Conveyor Market
Material Handling Equipment
Europe Automated Material Handling (AMH) Market
Material Handling Equipment
Global Telescopic Boom Forklift Truck Market
Material Handling Equipment
Asia Pacific Mobile Crane Market