
 Hydraulics Components Market | 2026-2036
Hydraulics Components Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulics Components Market Intelligence
German hydraulic component manufacturing is expanding capacity for high-pressure precision systems. Bosch Rexroth AG leverages in-house foundry operations to control alloy quality for aerospace-grade valves. Parker Hannifin Corporation anchors North American distribution through captive service networks spanning industrial equipment hubs. Danfoss specializes in compact power-dense units for mobile agricultural machinery, occupying a defensible niche against full-line competitors.
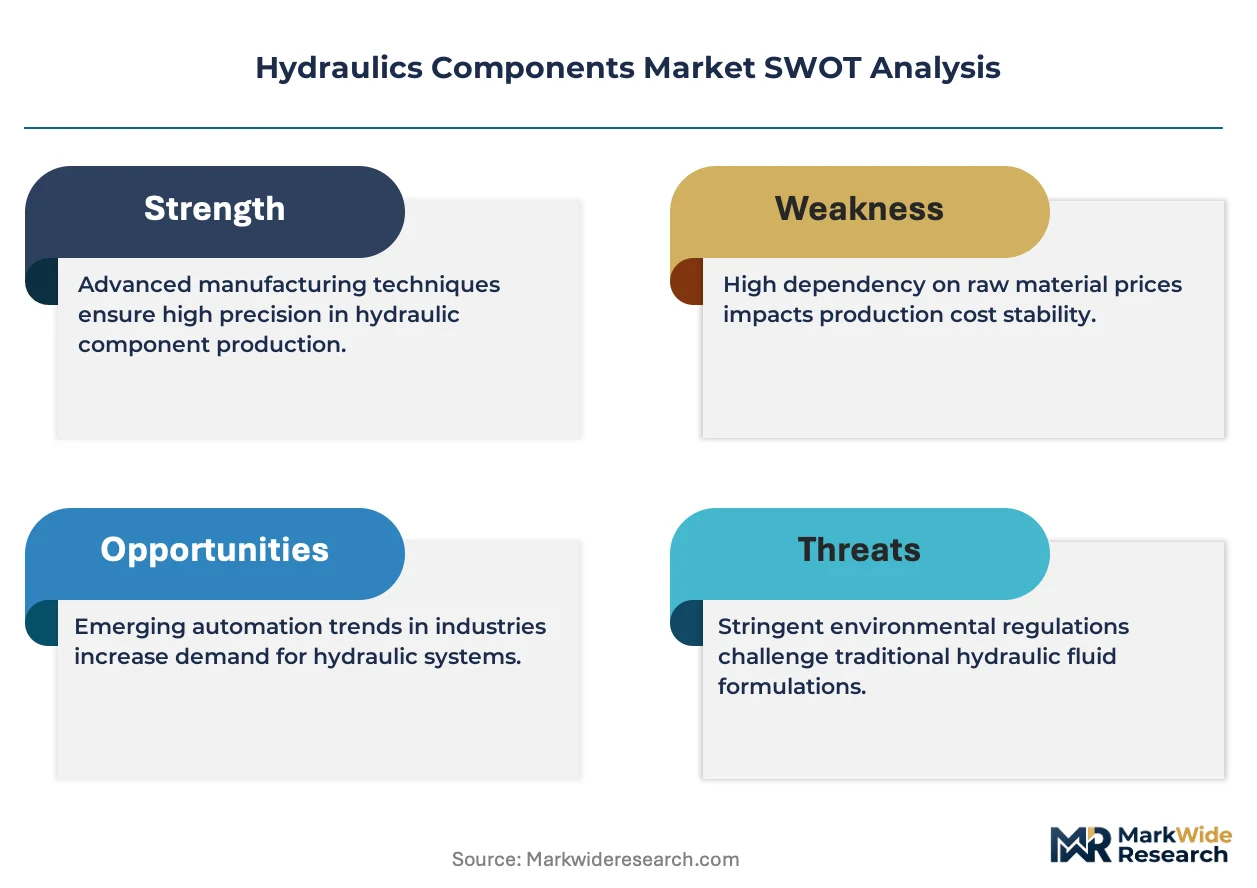
Hydraulics components encompass sealed fluid power systems that transmit force through pressurized oil, typically operating at 3,000 to 6,000 PSI in industrial settings, to actuate mechanical motion in heavy machinery. Their primary purpose lies in converting rotational pump energy into linear or rotary actuator force with precise load control across construction, mining, and manufacturing environments. Pumps represent the mature revenue base where replacement cycles dominate, while electro-hydraulic technology captures the fastest expansion as OEMs retrofit conventional hydraulic architectures with sensor-integrated servo control. Cylinders command concentrated margin pools in custom mining and marine applications where metallurgical specifications resist commoditization.
EPA emission standards for off-road diesel equipment in the United States force hydraulic system redesigns to reduce parasitic power losses, while REACH compliance in Europe restricts certain seal elastomers and anti-wear additives in hydraulic fluids. Japan's METI energy efficiency directives accelerate domestic adoption of variable-displacement pump technologies that cut idle power consumption. Stakeholders must weigh regional regulatory divergence against platform standardization economics when configuring global product portfolios.
Market Dynamics
Electro-hydraulic system architectures are displacing conventional fluid power configurations as construction and mining OEMs pursue measurable fuel efficiency gains and emission compliance across regulatory jurisdictions.
Growth Catalysts
- EU F-Gas Regulation:Tightening restrictions on high-GWP refrigerants in cooling circuits force German and Japanese equipment manufacturers to accelerate procurement of closed-loop electro-hydraulic systems with integrated thermal management.
- Port machinery modernization:State-backed infrastructure programs in China sustain concentrated orders for heavy-duty cylinders and high-pressure pumps in coastal industrial corridors.
- Variable-displacement pump technology:Japan's METI energy efficiency directives accelerate domestic retrofit cycles that cut idle power consumption in mobile hydraulic equipment.
Market Restraints
- Specialized alloy supply concentration:Aerospace-grade valve production depends on captive foundry operations concentrated among integrated German manufacturers, limiting second-source availability.
- Seal elastomer compliance costs:REACH restrictions on specific anti-wear additives and seal materials in hydraulic fluids force reformulation cycles that extend product development timelines.
- Electric actuator substitution:Linear electric drive systems penetrate light-load material handling applications below 500 PSI, compressing addressable volume for compact hydraulic units.
Strategic Opportunities
- Agricultural machinery electrification:Danfoss occupies a defensible niche in compact power-dense units for mobile farm equipment, with expansion potential into precision planting and autonomous harvester platforms.
- Marine cylinder customization:Specialized metallurgical specifications for offshore and subsea applications resist commoditization, preserving margin pools for engineered-to-order actuator suppliers.
- EPA Tier 4 Final compliance:Off-road diesel emission standards in the United States force hydraulic system redesigns that reduce parasitic power losses, creating specification windows for efficiency-optimized component architectures.
Industry Challenges
- Cross-functional engineering talent scarcity:Integration of sensor-embedded servo control with mechanical hydraulic systems demands mechatronics expertise that outpaces vocational pipeline output in industrial regions.
- Legacy fleet retrofit complexity:Sensor integration and control architecture upgrades on installed construction and mining equipment face compatibility barriers with existing hydraulic circuit geometries.
- Multi-jurisdiction certification timelines:Divergent EPA, REACH, and METI compliance requirements force parallel testing protocols that delay platform standardization for global product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulics Components Market |
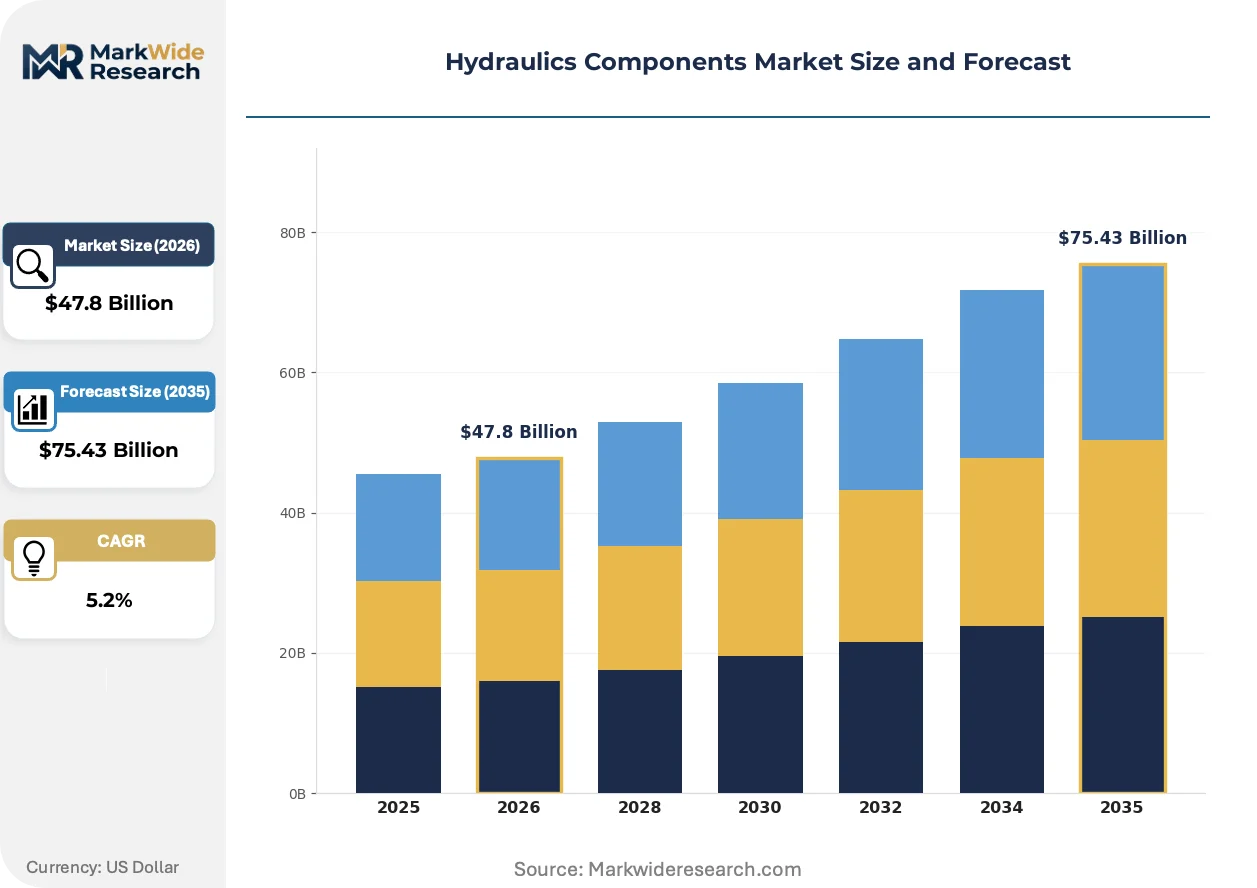
| Market Size in 2026 | $47.8 Billion |
| Market Size in 2035 | $75.43 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pumps, Valves, Cylinders, Accumulators End User: Agriculture, Construction, Manufacturing, Aerospace Technology: Hydraulic, Pneumatic, Electro-hydraulic, Servo-driven Application: Automotive, Mining, Marine, Industrial Equipment |
| Companies Covered | Bosch Rexroth AG, Parker Hannifin Corporation, Danfoss, Kawasaki Heavy Industries, Ltd., KYB Corporation, Eaton Corporation, HYDAC International GmbH, Caterpillar, Inc., SMC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulics Components Market Strategic Shifts & Innovations
Sensor-integrated hydraulic architectures are compressing the boundary between mechanical fluid power and digital control systems, with adoption patterns diverging sharply between premium OEM specification and aftermarket retrofit channels.
Electro-hydraulic servo valves are expanding into construction equipment drivetrains as the core enabling technology for load-sensing, precision-positioning applications. Caterpillar and Komatsu specification engineers embed these units in next-generation excavator booms where fuel efficiency targets demand millisecond response times. The technology is expanding into mid-tier equipment classes as cost curves compress and sensor reliability improves.
Japan's METI energy efficiency directives are accelerating variable-displacement pump adoption across domestic mobile equipment fleets. These regulations mandate measurable idle power reduction, forcing hydraulic system redesigns that displace fixed-displacement architectures in compact loaders and aerial work platforms. Domestic Japanese manufacturers respond with integrated pump-motor units that combine hydraulic power generation with regenerative braking energy recovery.
Aftermarket service unbundling is fragmenting traditional distribution relationships in North American industrial equipment hubs. End-users source replacement cylinders and seal kits through direct digital channels, compressing distributor margin capture and forcing Parker Hannifin and comparable full-line suppliers to deploy captive service networks for specification-sensitive repairs. This pattern concentrates in mining and marine verticals where downtime costs exceed premium component pricing differentials.
Hydraulics Components Market Segmentation
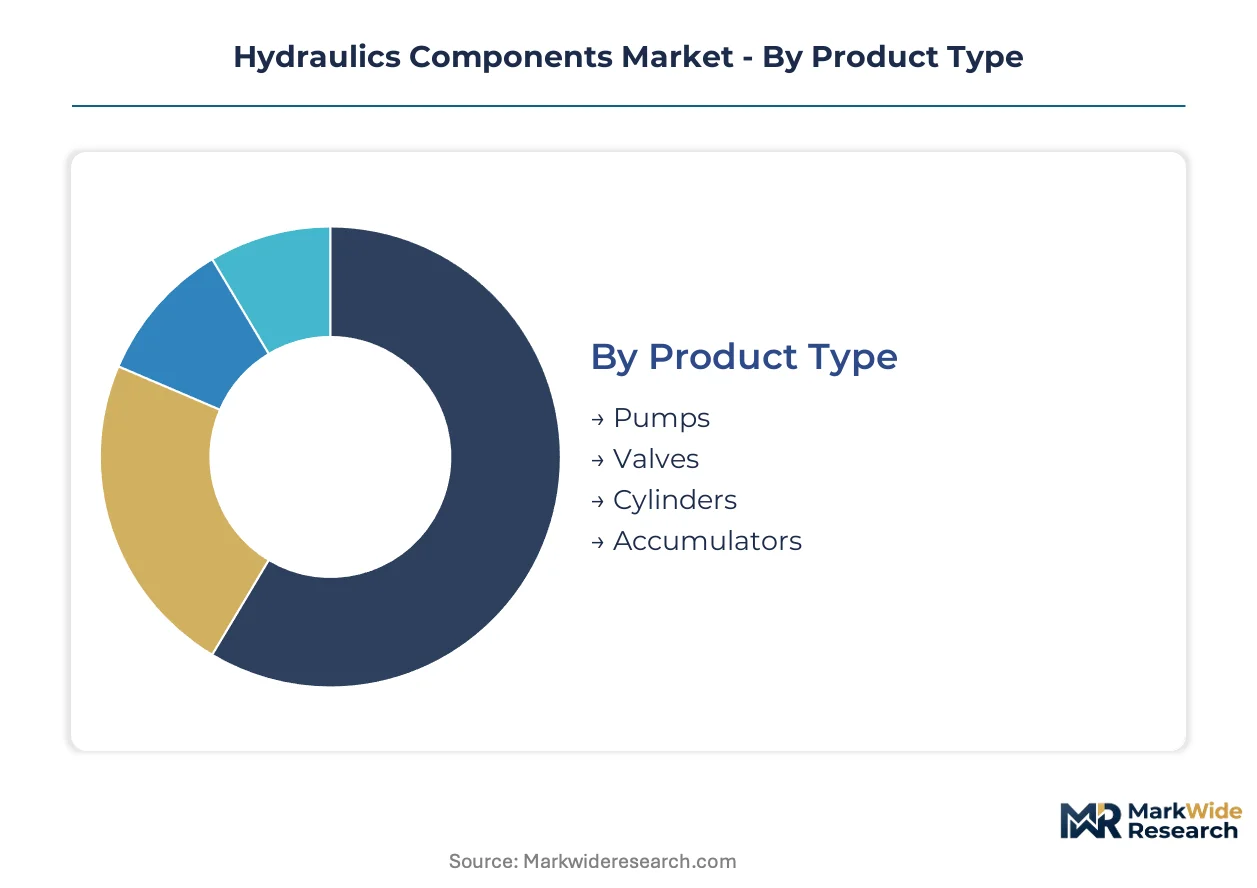
Hydraulics components segment across four dimensions that determine procurement economics and specification complexity. Product type dictates foundry and machining capital requirements, while technology choice governs control system integration costs and aftermarket service intensity.
Product Type:
Pumps and cylinders demand the heaviest upfront capital, with high-pressure units requiring captive foundry operations and precision honing equipment that limits supplier entry.
- Pumps:Fixed-displacement and variable-displacement architectures convert rotational mechanical energy into pressurized fluid flow. Replacement cycles dominate revenue in mature industrial markets, while Japan's METI energy efficiency directives accelerate retrofit demand for variable-displacement units that cut idle power consumption.
- Cylinders:Single-acting and double-acting actuators transform fluid pressure into linear mechanical force. Custom mining and marine applications concentrate margin pools where metallurgical specifications resist commoditization; China's port machinery modernization sustains heavy cylinder orders in coastal industrial corridors.
- Valves:Directional, pressure, and flow control components regulate circuit behavior. Aerospace-grade production depends on specialized alloy supply chains concentrated among integrated German manufacturers.
- Accumulators:Bladder, piston, and diaphragm types store pressurized fluid energy for emergency actuation or pulsation damping. Offshore and subsea specifications drive engineered-to-order demand.
Pumps absorb the bulk of installed capacity; electro-hydraulic pump-motor units are expanding most quickly as OEMs retrofit for fuel efficiency compliance.
End User:
Construction and mining verticals concentrate the highest specification intensity, where downtime costs justify premium component pricing and captive service relationships.
- Construction:Excavators, loaders, and aerial work platforms demand load-sensing architectures with millisecond response times. Caterpillar and Komatsu specification engineers embed electro-hydraulic servo valves in next-generation excavator booms.
- Agriculture:Tractors, harvesters, and precision planting equipment require compact power-dense units. Danfoss occupies a defensible niche in mobile farm machinery with expansion potential into autonomous harvester platforms.
- Manufacturing:Presses, injection molding machines, and metal forming equipment utilize high-pressure precision systems. Bosch Rexroth leverages in-house foundry operations to control alloy quality for demanding industrial applications.
- Aerospace:Flight control actuation and landing gear systems impose stringent weight and reliability specifications. Specialized valve production depends on captive foundry capacity that limits second-source availability.
Construction commands the largest share of component volume; agriculture is climbing the fastest as farm equipment electrification accelerates.
Technology:
Control architecture determines the boundary between mechanical fluid power and digital system integration, with sensor-embedded variants commanding specification premiums.
- Electro-hydraulic:Sensor-integrated servo control architectures enable precision positioning and load-sensing with millisecond response. EU F-Gas Regulation tightening on high-GWP refrigerants forces German and Japanese equipment manufacturers to accelerate procurement of closed-loop systems with integrated thermal management.
- Hydraulic:Conventional fluid power configurations without electronic control remain dominant in price-sensitive equipment classes and legacy fleet maintenance.
- Pneumatic:Compressed air systems compete in light-load applications below 500 PSI where linear electric drives also penetrate.
- Servo-driven:Direct electric actuation with hydraulic force multiplication hybridizes power density with digital control precision.
Conventional hydraulic technology retains the largest installed base; electro-hydraulic architectures are gaining share fastest as emission compliance tightens across regulatory jurisdictions.
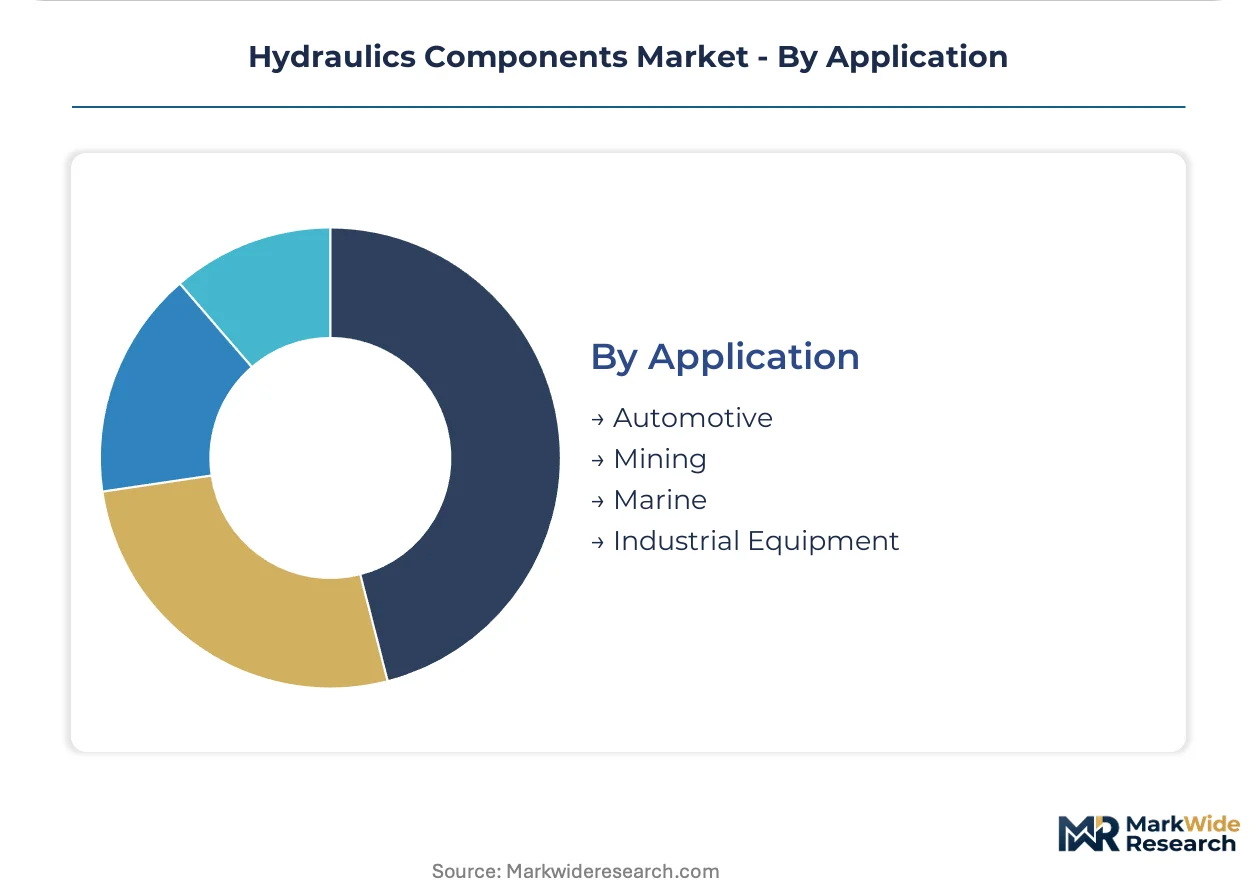
Application:
Operating environment dictates material specifications and service intensity, with subsea and underground applications imposing the most severe durability requirements.
- Mining:Underground and surface extraction equipment operates in abrasive, high-vibration environments. Specialized metallurgical specifications for custom cylinders resist commoditization and preserve margin pools for engineered-to-order suppliers.
- Marine:Offshore platforms, subsea installations, and cargo handling systems require corrosion-resistant alloys and redundant sealing architectures. Downtime costs exceed premium component pricing differentials, concentrating specification-sensitive procurement.
- Industrial Equipment:Factory automation and material handling systems span pressure ranges from 500 PSI light-load to 6,000 PSI heavy-duty industrial settings.
- Automotive:Vehicle braking, suspension, and power steering applications face electric actuator substitution in light-load segments.
Industrial equipment spans the broadest pressure range; mining and marine applications command the steepest specification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized alloy foundries in Germany's Ruhr industrial belt supply the metallurgical base for aerospace-grade valve production, anchoring European precision manufacturing capacity for high-pressure hydraulic systems.
Germany
Construction equipment manufacturers in Baden-Württemberg accelerate procurement of electro-hydraulic systems as the EU F-Gas Regulation tightens refrigerant restrictions. Bosch Rexroth leverages captive foundry operations in Lohr am Main to control alloy quality for demanding industrial applications. The Stuttgart industrial corridor concentrates R&D investment in sensor-integrated servo architectures.
China
State-backed modernization of port machinery and mining fleets sustains heavy cylinder and pump orders along coastal industrial corridors. The country's national environmental regulator enforces dual carbon goals that accelerate variable-displacement pump adoption in mobile equipment. Shanghai's Yangtze River Delta manufacturing cluster hosts integrated suppliers serving domestic OEM specification requirements.
Japan
Domestic mobile equipment fleets face accelerated retrofit cycles under METI energy efficiency directives targeting idle power reduction. Kawasaki Heavy Industries and KYB Corporation anchor production in the Kansai and Chubu industrial regions. The Nagoya manufacturing belt specializes in integrated pump-motor units combining hydraulic power generation with regenerative braking recovery.
United States
EPA Tier 4 Final emission standards force hydraulic system redesigns to cut parasitic power losses in off-road diesel equipment. Parker Hannifin anchors North American distribution through captive service networks spanning industrial equipment hubs. The Midwest manufacturing belt concentrates specification engineering for construction and mining OEM compliance programs.
India
Domestic infrastructure expansion drives procurement of heavy-duty cylinders for earthmoving and material handling equipment. The Bureau of Indian Standards enforces mechanical safety codes that shape component certification requirements. Maharashtra's Pune-Nashik industrial corridor hosts emerging fabrication capacity serving regional construction equipment demand.
Hydraulics Components Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue electrification-adjacent sensor integration and thermal management architectures. The vendor base stratifies across three tiers: integrated full-line suppliers with captive foundry capacity, specialized component fabricators serving niche pressure ranges, and regional assemblers competing on replacement cycle velocity. Dominant competitive moves include backward integration into alloy supply chains and geographic expansion of captive service networks to capture aftermarket specification-sensitive repairs.
Within the integrated tier, Bosch Rexroth AG and Parker Hannifin Corporation exemplify full-line positioning through in-house production of precision-machined components. Danfoss occupies a defensible specialist position in compact power-dense architectures. Kawasaki Heavy Industries, Ltd. anchors Japanese domestic capacity for mobile equipment pump-motor integration. Eaton Corporation and HYDAC International GmbH represent mid-tier European fabricators with regional density in industrial equipment corridors. KYB Corporation and SMC Corporation illustrate component-specialist models concentrated in Asian manufacturing clusters. Caterpillar, Inc. leverages captive vertical integration for construction equipment specification control.
| Leading Market Players |
|---|
| Bosch Rexroth AG |
| Parker Hannifin Corporation |
| Danfoss |
| Kawasaki Heavy Industries, Ltd. |
| KYB Corporation |
| Eaton Corporation |
| HYDAC International GmbH |
| Caterpillar, Inc. |
| SMC Corporation |
| Others |
Cost & Logistics Intelligence
EU F-Gas Regulation tightening on high-GWP refrigerants forces German and Japanese equipment manufacturers to accelerate procurement of closed-loop electro-hydraulic systems, compelling suppliers to absorb certification costs and reconfigure thermal management architectures that compress margin structures across component tiers.
Pricing Analysis
Warranty and aftermarket service bundling separates premium-tier suppliers from unbundled digital channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and captive service network coverage. Pricing pressure stems from direct digital procurement of replacement cylinders and seal kits in North American mining and marine verticals. Construction OEMs exhibit lowest price sensitivity where downtime costs dominate, while light-load material handling applications face electric actuator substitution below 500 PSI.
Supply Chain Analysis
Specialized alloy supply for aerospace-grade valve production rests on captive foundry operations concentrated in Germany, with secondary precision machining capacity anchored in Japan and the United States. High-strength steel billets, rare-earth magnet materials for servo motors, and REACH-compliant seal elastomers constitute critical input dependencies. Single-source vulnerability in German Ruhr industrial belt foundries threatens second-source availability for demanding specifications. Distribution runs through captive service networks for specification-sensitive repairs, particularly in mining and marine applications where downtime costs exceed premium component pricing differentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Component suppliers face a vertical-integration race where control over specialized alloy quality and sensor-embedded control architectures determines margin capture across regulatory jurisdictions.
For Market Incumbents: Lock in aerospace-grade valve production through in-house foundry capacity expansion in Germany's Ruhr industrial belt. Deepen backward integration into rare-earth magnet supply chains for servo motor integration to defend against emerging electro-hydraulic specialists. Acquire mechatronics engineering talent pools faster than vocational pipeline output to address cross-functional integration bottlenecks. For New Entrants and Emerging Players: Mid-tier agricultural equipment manufacturers in China's Yangtze River Delta represent an underserved buyer archetype seeking compact power-dense units for electrification retrofits. Precision planting and autonomous harvester platforms offer white-space penetration before Danfoss consolidates platform control. Pursue specification engineering partnerships with domestic Chinese OEMs to bypass established distribution relationships. For Investors and Strategic Acquirers: The window for entry favors vertically integrated mid-cap specialists with captive foundry capacity and sensor integration capabilities. Long-term viability hinges on regulatory compliance architecture spanning EPA Tier 4 Final, REACH, and METI directives simultaneously. Watch for variable-displacement pump retrofit cycle acceleration in Japanese mobile equipment fleets as inflection indicator for electro-hydraulic technology share gains.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Capacity Expansion | Bosch Rexroth's Lohr am Main operations demonstrate alloy quality control for aerospace-grade specifications. |
| Sensor-Embedded Servo Integration | Caterpillar and Komatsu specification requirements drive millisecond response time architectures in excavator booms. |
| Regulatory Compliance Architecture | Parallel EPA, REACH, and METI certification protocols delay platform standardization for global portfolios. |
| Aftermarket Service Network Captivity | Parker Hannifin's North American hubs capture specification-sensitive repairs where downtime costs dominate. |
| Pump-Motor Unit Integration | Kawasaki Heavy Industries combines hydraulic power generation with regenerative braking in Nagoya manufacturing belt. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across OEM procurement teams, aftermarket service heads, plant engineers, and mechatronics R&D directors. SEC 10-K disclosures, EU F-Gas Regulation compliance databases, and Japanese METI energy efficiency filings provided secondary validation. Bottom-up component shipment analysis and top-down equipment production estimates were triangulated to cross-verify volume assumptions.
Segment-level modeling addressed product type, end-use vertical, technology architecture, and application environment across the analysis window. CAGRs were derived from equipment fleet replacement cycles, regulatory compliance deadlines, and technology substitution elasticities. Variable-displacement pump retrofit penetration in Japanese mobile equipment and electro-hydraulic servo valve specification rates in construction OEM programs served as industry-specific forecast inputs.
Revisions become necessary when regulatory divergence accelerates beyond parallel certification timelines, specialized alloy supply disruptions emerge, or electric actuator substitution penetrates above 500 PSI applications. Forecasts reflect documented assumptions on technology cost curves and compliance enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Compactor Market
Material Handling Equipment
Hooklifts Market
Material Handling Equipment
Bridge Cable Sockets Market
Material Handling Equipment
Low Clearance Loaders Market
Material Handling Equipment
Conveyor Scales Market
Material Handling Equipment
Latin America Conveyors Market
Material Handling Equipment
Carry Deck Crane Market
Material Handling Equipment
Trommel Screen Market
Material Handling Equipment
Precision Gearbox Machinery Market
Material Handling Equipment
Elevator Component Market
Material Handling Equipment
Cable Conduit Market
Material Handling Equipment
Industrial Carts Market
Material Handling Equipment
Resistance Welding Products Market
Material Handling Equipment
Global Lifting Columns Market
Material Handling Equipment
Reach Trucks Market
Material Handling Equipment
Reinforced Ultrafine Mill Market