
 Ship Loader and Unloader Market | 2026-2036
Ship Loader and Unloader Market Size, Share, and Industry Trends Forecast 2026-2036
Ship Loader and Unloader Market Intelligence
European engineering firm consolidation is recalibrating the competitive landscape for high-capacity ship loading systems. Thyssenkrupp AG leverages its extensive industrial project background to secure large-scale port automation contracts. Cargotec Corp., through its MacGregor and Kalmar brands, specializes in integrated cargo flow solutions for container and bulk terminals. Meanwhile, FLSmidth & Co. A/S focuses on complete material handling systems for the mining and cement industries, controlling a significant portion of that specific value chain.
Ship loaders and unloaders are port-based machines designed for transferring bulk solids, liquids, or containers between vessels and docks. These systems are specified by their handling capacity, often exceeding thousands of tonnes per hour, and are engineered to minimize vessel turnaround times. The bulk material handling application segment continues to represent the largest share of the market, driven by commodity trade. Within technology, automated control systems are seeing accelerated uptake as port authorities and mining companies prioritize operational efficiency and safety.
Equipment design and market access are governed by a complex web of standards, including ISO 4309 for crane safety and maintenance. Regulations such as the US EPA's port emissions rules and the EU's Machinery Directive (requiring CE marking) impose strict environmental and safety requirements on manufacturers. The critical decision for port operators now revolves around the capital allocation choice between retrofitting existing assets with new technology versus investing in fully new, automated systems.
Market Dynamics
The push for automation to reduce port congestion and vessel turnaround times is the central force shaping the market. This pressure compels port operators to evaluate the significant capital investment in new systems against long-term operational efficiency gains and safety improvements.
Growth Catalysts
- Commodity Trade Expansion:Global demand for bulk materials like Australian iron ore necessitates port investment in high-capacity equipment to manage export volumes.
- Automation Technologies:Remote operation and automated control systems are adopted to increase terminal throughput and improve worker safety, justifying new system investments.
- Emission Regulations:Mandates from bodies like the US EPA accelerate the replacement of diesel machinery with cleaner, electric-powered systems, driving demand.
Market Restraints
- High Capital Expenditure:The substantial upfront cost for new automated systems is a major barrier for smaller ports with constrained capital budgets.
- Infrastructure Limitations:Existing port infrastructure, including quay strength and power grids, often cannot support the latest generation of high-capacity loading systems.
- Alternative Equipment:Mobile harbor cranes offer a flexible, lower-cost substitute for dedicated loaders in ports with varied cargo and lower throughput needs.
Strategic Opportunities
- Modernization Services:Retrofitting aging loaders with new automation packages and control systems is a significant service-based revenue opportunity for vendors.
- Emerging Market Ports:Greenfield port projects in Southeast Asia and Africa create demand for complete ship loading systems to support regional trade growth.
- Digital Twin Integration:Offering digital twin models for simulation and predictive maintenance is a high-value service addition to core equipment sales.
Industry Challenges
- Skilled Labor Gap:A shortage of technicians and operators skilled in programming, maintaining, and supervising advanced automated and remote-controlled port machinery hinders adoption.
- Legacy System Integration:Integrating new automated loaders with existing, often proprietary, terminal operating systems is a complex and costly technical hurdle for port operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ship Loader and Unloader Market |
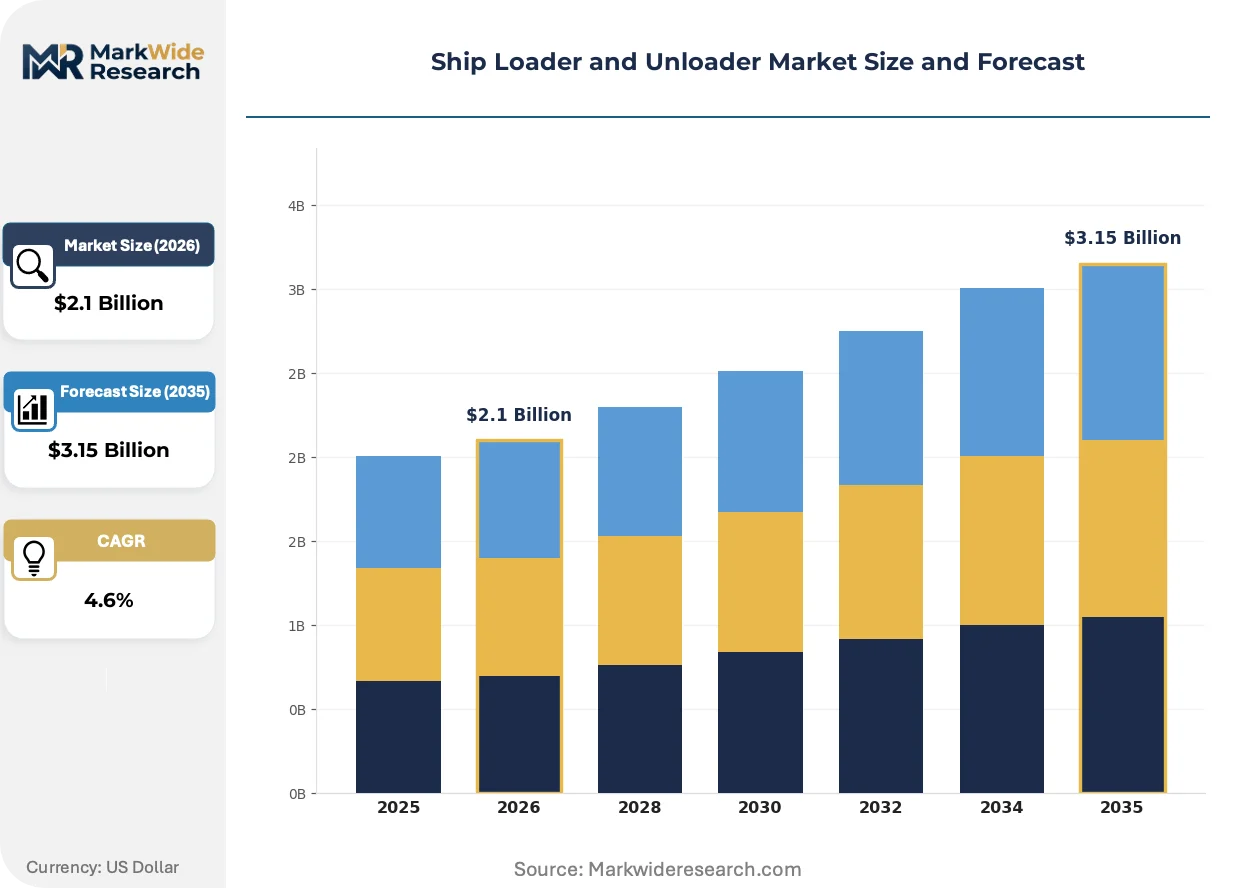
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gantry Crane, Portal Crane, Stacker Reclaimer, Bucket Wheel Loader, Traveling Crane, Hoe Loader Technology: Electro-Mechanical, Hydraulic, Pneumatic, Automated Control, Remote Operation, Manual Control Application: Bulk Material Handling, Container Loading, Coal Handling, Grain Transshipment, Mineral Transport, Cement Distribution End User: Port Authorities, Mining Companies, Shipping Firms, Logistics Providers, Construction Contractors, Heavy Equipment Renters |
| Companies Covered | FLSmidth & Co. A/S, Thyssenkrupp AG, Siwertell AB, Cargotec Corp., Buhler AG, Sandvik AB, Liebherr-International AG, NEUERO Industrietechnik für Förderanlagen GmbH, Vigan Engineering S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ship Loader and Unloader Market Strategic Shifts & Innovations
Convergence of heavy mechanical engineering with digital technologies defines the next generation of port equipment. This synthesis transforms operational data into actionable insights for efficiency and asset longevity, moving beyond the core function of simple material transfer.
Digital twin technology creates a virtual, data-rich replica of a physical ship loader for analysis. Major port operators and mining firms are adopting this for operational simulation and predictive maintenance planning. The technology is unifying disparate data sources like sensor outputs, maintenance logs, and operational schedules into a single, cohesive management platform.
The European Union's Machinery Directive mandates stringent safety compliance, including CE marking, for all new equipment placed on the market. This forces manufacturers to engineer advanced safety features like anti-collision systems and automated emergency stops from the outset. The bulk material handling segment is most affected, with engineering teams integrating these safety protocols into initial system designs.
Port operators are increasingly evaluating equipment based on total cost of ownership rather than just initial capital outlay. This procurement model favors suppliers who can demonstrate long-term value through robust service, maintenance, and upgrade packages. The shift is most visible in large-scale port concessions across Australia and Europe where long-term operational efficiency is critical.
Ship Loader and Unloader Market Segmentation
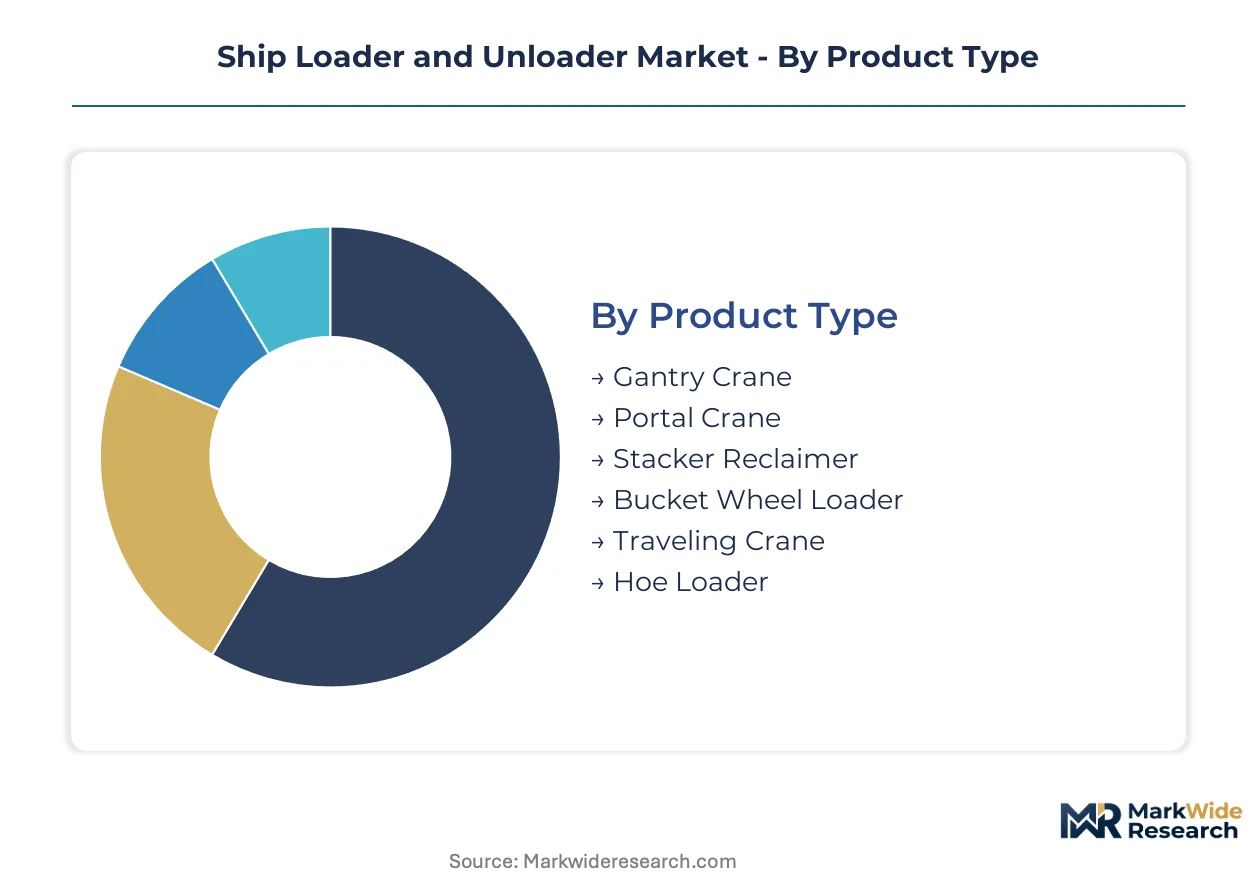
Segmentation within the ship loader and unloader market provides a critical framework for understanding the specialized demands and technological evolution driving this capital-intensive industry. Analyzing distinct product types, underlying technologies, diverse applications, and varied end-user groups reveals where investment is concentrating and which solutions are gaining traction.
Product Type:
Product type segmentation for ship loaders and unloaders highlights the diverse mechanical specifications crucial for efficient port operations.
- Gantry Crane:These large, rail-mounted structures typically span container terminals, designed for lifting and moving heavy loads between vessels and shore. Demand concentrates in high-throughput container ports like Rotterdam and Shanghai due to increasing vessel sizes and containerized trade.
- Stacker Reclaimer:Large, complex machines used in bulk material yards, they efficiently stack incoming material into stockpiles and reclaim it for outbound transport. Mining companies in Australia and Brazil extensively deploy these systems for iron ore and coal handling, driven by massive export volumes.
- Portal Crane:These cranes feature a fixed or rail-mounted base and are commonly employed for handling general cargo and moderate bulk materials.
- Bucket Wheel Loader:This equipment is specifically designed for excavating and loading bulk materials from large stockpiles onto conveyors or trucks.
- Traveling Crane:Overhead cranes mounted on rails provide versatile lifting capabilities, often utilized for lighter bulk or varied general cargo.
- Hoe Loader:Specialized heavy equipment, hoe loaders are robustly designed for excavating and loading dense and challenging bulk materials.
Mature deployment sits with Gantry Crane systems. Newer deployment is concentrated in Stacker Reclaimer solutions for large-scale bulk operations.
Technology:
Technology segmentation reveals how operational demands in different applications drive the adoption of specific control and power systems.
- Automated Control:This technology integrates sensors, programmable logic controllers, and advanced software to enable autonomous operation and optimize loading/unloading cycles. Port authorities in Europe and North America prioritize automated control systems for enhanced efficiency and compliance with safety mandates.
- Remote Operation:Remote operation systems allow personnel to control machinery from a central station, removing them from hazardous operational zones. Mining companies in remote regions like Western Australia utilize these systems for continuous operation in extreme environmental conditions and to improve worker safety.
- Electro-Mechanical:Utilizing electric motors and gearboxes, electro-mechanical systems provide reliable power and movement for many modern ship loading and unloading systems.
- Hydraulic:These systems employ fluid pressure to generate powerful and precise movements, making them suitable for heavy-duty and demanding applications.
- Pneumatic:Pneumatic systems use compressed air for lighter material handling tasks, often found in specialized applications such as grain suction.
- Manual Control:Manual control relies on human operators directly interacting with machine controls, prevalent in older equipment or smaller-scale port operations.
Automated Control and Remote Operation technologies are expanding most quickly, driven by efficiency and safety imperatives across port operations.
Application:
Application segmentation demonstrates how diverse end-user requirements shape the specialized design and deployment of ship loading and unloading systems.
- Bulk Material Handling:This segment involves systems specifically designed for loose, unpackaged materials such as ores, grains, or chemicals, facilitating high-capacity transfer. Major export hubs like the Port of Tubarão in Brazil heavily invest in these systems for iron ore, driven by global commodity trade expansion.
- Container Loading:Specialized cranes and systems handle standardized shipping containers, enabling rapid transfer between vessels and land transport networks. Mega-ports in Asia and Europe utilize these solutions extensively to manage the increasing volumes of containerized global trade.
- Coal Handling:Dedicated systems for loading and unloading coal often incorporate specific features for dust suppression and environmental control.
- Grain Transshipment:Specialized equipment ensures the gentle and efficient transfer of agricultural grains, preserving product quality during handling.
- Mineral Transport:Tailored solutions address the specific characteristics of various raw minerals, considering factors like material density and abrasiveness.
- Cement Distribution:Systems designed for handling cement powder frequently require enclosed transfer mechanisms to minimize product loss and dust emissions.
Bulk Material Handling applications continue to dominate the market, while Container Loading solutions are climbing the fastest due to global trade dynamics.
End User:
End-user segmentation highlights how operational scale and throughput volumes dictate the specific investment patterns in ship loading and unloading equipment.
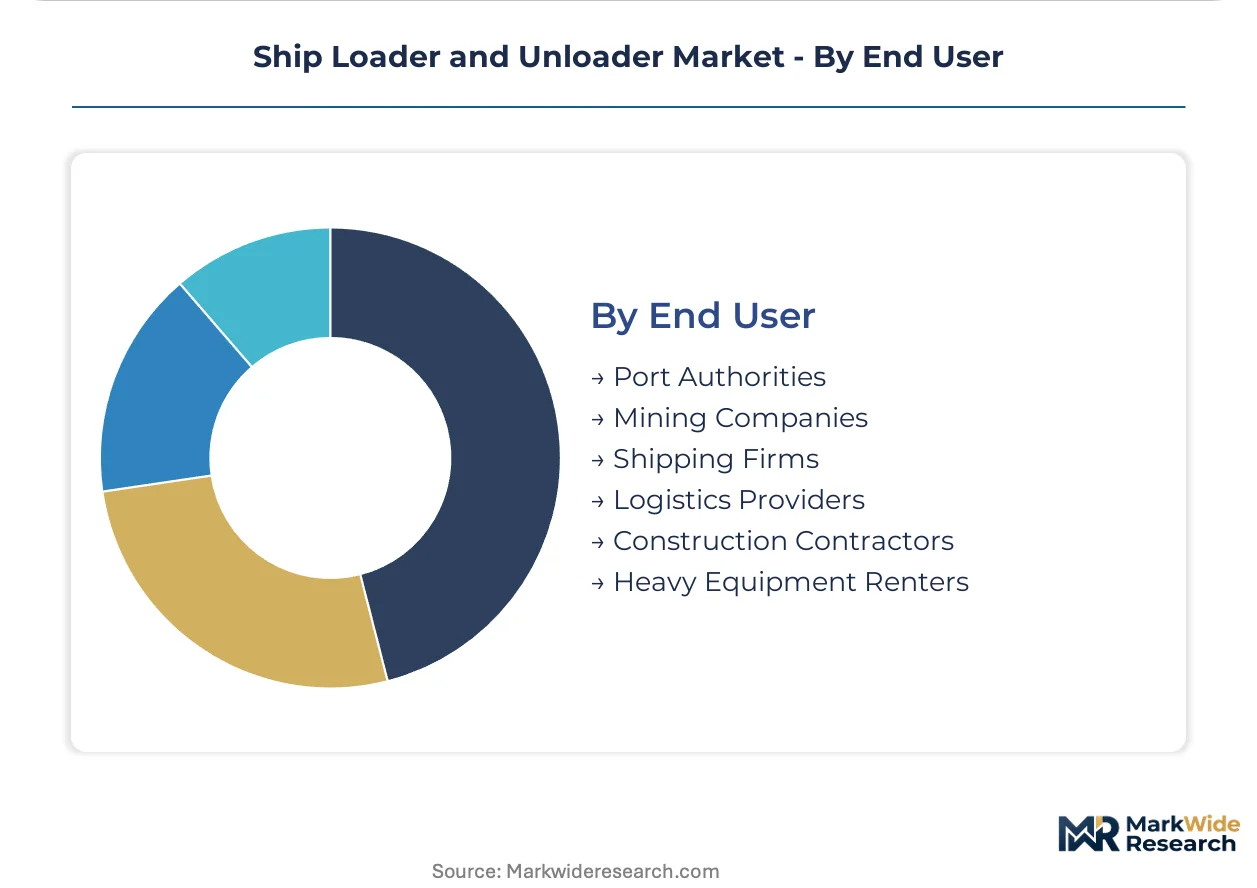
- Port Authorities:These entities manage port infrastructure and operations, making significant investments in large-scale terminal equipment to ensure efficient vessel turnaround and cargo flow. Major maritime gateways in Germany and the Netherlands prioritize these systems for overall port efficiency and to address congestion.
- Mining Companies:Firms involved in raw material extraction require dedicated, high-capacity systems at export terminals for loading bulk commodities like iron ore and coal onto vessels. Large-scale operations in Australia and Chile are key investors, driven by global demand for primary commodities.
- Shipping Firms:Companies operating vessels sometimes invest in specialized onboard or port-side equipment to optimize their fleet's loading and unloading processes.
- Logistics Providers:Third-party companies managing complex supply chains occasionally require specialized handling equipment at their facilities to support cargo movement.
- Construction Contractors:Firms undertaking large infrastructure projects may utilize temporary or mobile loading solutions for specific material handling needs.
- Heavy Equipment Renters:These companies provide specialized machinery on a rental basis, serving various industrial clients including smaller ports or those with fluctuating demand.
Port Authorities and Mining Companies represent the largest end-user segments, with Logistics Providers gaining share fastest through specialized service offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's significant iron ore and coal production anchors the global demand for high-capacity ship loading and unloading systems. These specialized port machines are essential for efficient commodity export across major maritime trade routes. Investments in advanced bulk material handling infrastructure are therefore critical for sustained economic growth in resource-rich regions.
Australia
Western Australia's massive iron ore exports drive continuous investment in stacker reclaimers and ship loaders. The country’s environmental protection standards influence equipment design, emphasizing dust suppression and energy efficiency. Port Hedland, a major iron ore export hub, sees ongoing upgrades to its bulk handling facilities for increased throughput.
Brazil
Brazil's vast mineral resources, particularly iron ore from Minas Gerais, necessitate robust port infrastructure for global trade. National environmental regulations guide the development of new port projects and the modernization of existing terminals. The Port of Tubarão in Espírito Santo remains a key site for high-capacity iron ore loading operations.
Germany
German port authorities prioritize automated control systems for enhancing operational efficiency and managing containerized cargo volumes. The EU's Machinery Directive mandates stringent safety compliance, including CE marking, for all new equipment. The Port of Hamburg, a major European gateway, consistently upgrades its gantry cranes and bulk handling equipment.
Netherlands
Dutch maritime logistics demand advanced ship loading solutions to minimize vessel turnaround times and reduce port congestion. European emissions rules accelerate the adoption of electric-powered systems in port operations. The Port of Rotterdam, Europe's largest port, continuously invests in automated solutions for both container and bulk terminals.
United States
American port operators focus on modernizing infrastructure to handle larger vessels and comply with strict environmental regulations. The US EPA's port emissions rules drive demand for cleaner, electric-powered machinery across coastal terminals. The Port of Los Angeles, a critical West Coast hub, implements automated systems to streamline container loading processes.
Ship Loader and Unloader Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized automation and digital integration services. The market structure exhibits a blend of large industrial conglomerates and specialized material handling providers. Consolidation through strategic mergers and acquisitions remains a primary competitive move, alongside continuous investment in advanced automation technologies.
Within the industrial equipment manufacturing landscape, several key players anchor distinct market segments. Thyssenkrupp AG, a German industrial conglomerate, exemplifies the capability to secure large-scale port automation contracts, leveraging its extensive project background. Cargotec Corp., through its MacGregor and Kalmar brands, represents a focus on integrated cargo flow solutions for both container and bulk terminals globally. Another significant European entity, FLSmidth & Co. A/S, occupies a strong position in providing complete material handling systems, particularly serving the mining and cement industries worldwide. These companies collectively demonstrate the varied approaches to market leadership, from broad industrial solutions to specialized segment offerings.
| Leading Market Players |
|---|
| FLSmidth & Co. A/S |
| Thyssenkrupp AG |
| Siwertell AB |
| Cargotec Corp. |
| Buhler AG |
| Sandvik AB |
| Liebherr-International AG |
| NEUERO Industrietechnik für Förderanlagen GmbH |
| Vigan Engineering S.A. |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps and large industrial conglomerates in Europe shape supply behavior and pricing discipline within the ship loader and unloader market. These entities often manage long-term project-based contracts, influencing cost structures.
Pricing Analysis
Warranty and service bundling often dictates the total cost of ship loading systems, influencing long-term value propositions. The dominant pricing model remains project-based, with significant customization and after-sales service packages driving price differentiation. Pricing softness stems from port operators' increasing focus on total cost of ownership rather than initial capital outlay. Smaller ports with constrained capital budgets exhibit the highest price sensitivity, while major port authorities prioritize long-term operational efficiency.
Supply Chain Analysis
Direct sales channels predominantly serve major port authorities and mining companies for ship loader procurement. Geographic supply concentration centers on European engineering hubs in Germany, Finland, and Denmark. Production relies on heavy steel fabrication and specialized automation components sourced globally. Single-source vulnerability for advanced control systems presents a significant supply chain risk, exacerbated by potential global logistics chokepoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is navigating a significant technology-transition phase, with automated control systems rapidly displacing older manual and electro-mechanical operations. Stakeholders must adapt strategies to leverage these evolving capabilities.
For Market Incumbents:To counter the commoditization of standard equipment and new entrants in automation, incumbents must pursue strategic mergers and acquisitions for advanced digital integration capabilities. Expand modernization services for existing port infrastructure, focusing on retrofitting legacy systems with automated control packages. Invest in R&D for AI-driven predictive maintenance and digital twin integration to offer higher value. Secure long-term service contracts to reinforce channel control and customer loyalty.
For New Entrants and Emerging Players:Begin with targeting greenfield port projects in emerging markets like Southeast Asia and Africa, where demand for complete systems is high. Focus on specialized smaller bulk terminals requiring flexible, modular, and lower-capex solutions. Offer integrated digital twin services and remote operation packages as a differentiated value proposition. Develop partnerships with local engineering firms to navigate regulatory landscapes and installation challenges.
For Investors and Strategic Acquirers:Distressed-cycle entries favor specialized automation providers in Europe, particularly those with strong intellectual property in control systems. Focus on firms offering modernization services for aging infrastructure, ensuring long-term viability over the next decade. Acquisition targets should possess proven capabilities in integrating automated loaders with diverse terminal operating systems. The signal to watch is the accelerated uptake of digital twin subscriptions among major port authorities and mining companies.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in AI-driven Predictive Maintenance | Enhances asset longevity and operational uptime for port operators, reducing unscheduled downtime. |
| Expand Retrofitting Services for Legacy Systems | Addresses infrastructure limitations at smaller ports, extending equipment lifespan and improving efficiency. |
| Develop Integrated Digital Twin Platforms | Provides port authorities with simulation capabilities for operational optimization and predictive planning. |
| Secure Long-Term Service & Maintenance Contracts | Establishes recurring revenue streams and reinforces customer relationships for equipment manufacturers. |
| Target Greenfield Projects in Emerging Markets | Captures demand for complete ship loading systems in regions like Southeast Asia and Africa. |
Research Approach
Document review covered port authority annual reports, IMO regulations, industry association publications, and patent databases, complemented by interviews with industry stakeholders. Primary interviews included port operations managers, mining company procurement teams, equipment design engineers, and terminal IT specialists. This approach integrated bottom-up data collection with top-down market validation. Triangulation across these sources ensured data accuracy and comprehensive market understanding.
Historical market data was cross-referenced with expert panel input to construct the forecast framework across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, application, end-user, and regional port development. Compound annual growth rates were derived from projected shifts in demand and supply dynamics. Key forecast inputs included global vessel traffic volumes and commodity export forecasts from major producing nations.
Underlying measurement precision varies by segment; bulk material handling and automated control systems carry tighter precision than others. Forecasts reflect assumptions regarding geopolitical shifts and global trade fluctuations. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Mobile Conveyor Market
Material Handling Equipment
Electric Tugger Market
Material Handling Equipment
Roller Crusher Market
Material Handling Equipment
Clinching Machines Market
Material Handling Equipment
Industrial Hose Assemblies Market
Material Handling Equipment
Flux Spraying Machine Market
Material Handling Equipment
North America Forklift Market
Material Handling Equipment
Drag Chain for Machine Market
Material Handling Equipment
Rolling Mill Machine Market
Material Handling Equipment
Material Rack Correction Machine Market
Material Handling Equipment
North America Conveyor Belt Market
Material Handling Equipment
Pipe Jacking Machines Market
Material Handling Equipment
Australia Forklift Rental Market
Material Handling Equipment
High-Pressure Die Casting Market
Material Handling Equipment
Vertical Baling Press Market
Material Handling Equipment
Brazil Forklift Market