
 Wire Pulling and Tensioning Market | 2026-2036
Wire Pulling and Tensioning Market Size, Share, and Industry Trends Forecast 2026-2036
Wire Pulling and Tensioning Market Analysis
UL 60974-1 certification for arc welding and related electrical equipment is rotating as a baseline qualification for manufacturers seeking utility-grade contracts. Southwire Company leverages its integrated cable-to-tool ecosystem to sustain pricing power across North American distribution networks. TESMEC S.p.A anchors its position through specialized tensioning systems designed for high-voltage overhead lines across European transmission corridors.
Wire pulling and tensioning encompasses mechanical and powered devices engineered to install, tension, and terminate conductive and fiber-optic cables within specified load tolerances, typically operating at tensile ratings from 1,000 to 100,000 pounds depending on conductor gauge and span length. Power tools and tensioning devices command premium positioning due to electrification mandates and labor cost pressures, while hand tools retain volume leadership in residential and light commercial construction. Application demand in utilities and telecommunications outpaces construction growth as fiber densification and grid hardening programs accelerate equipment replacement cycles.
OSHA workplace safety directives and NEC electrical installation codes in the United States, alongside CE marking and EU machinery directives in Europe, mandate insulated grips, load-rated shackles, and operator certification protocols that elevate product compliance costs while filtering marginal suppliers. China's GB standards and MIIT equipment certifications impose parallel technical barriers for market entry across Asian procurement channels. Stakeholders must track evolving interoperability standards between manual and automated tensioning systems as utilities evaluate robotic cable deployment for hazardous environments.
Market Dynamics
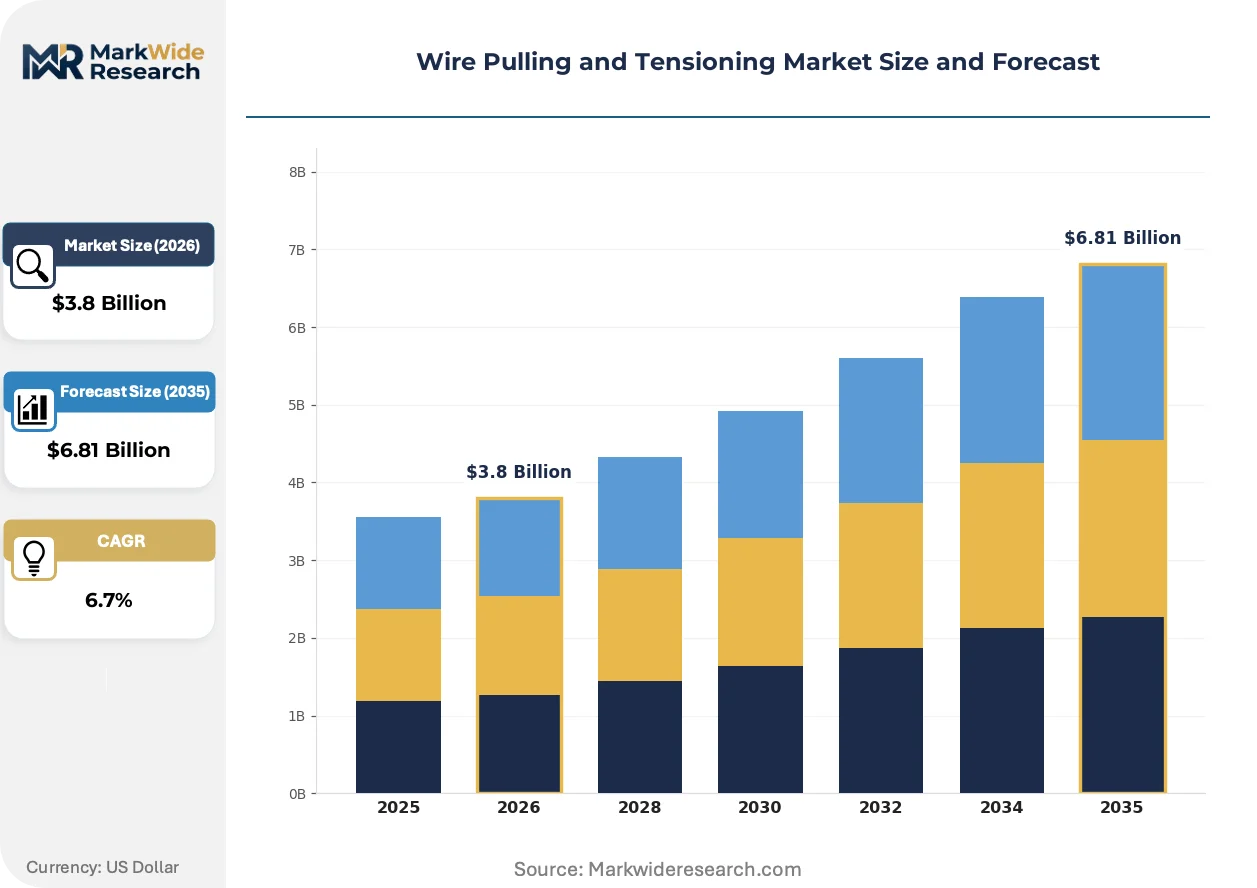
Grid hardening mandates and renewable interconnection queues are compressing equipment replacement cycles while elevating specification thresholds for load-rated tensioning systems across utility procurement channels.
Growth Catalysts
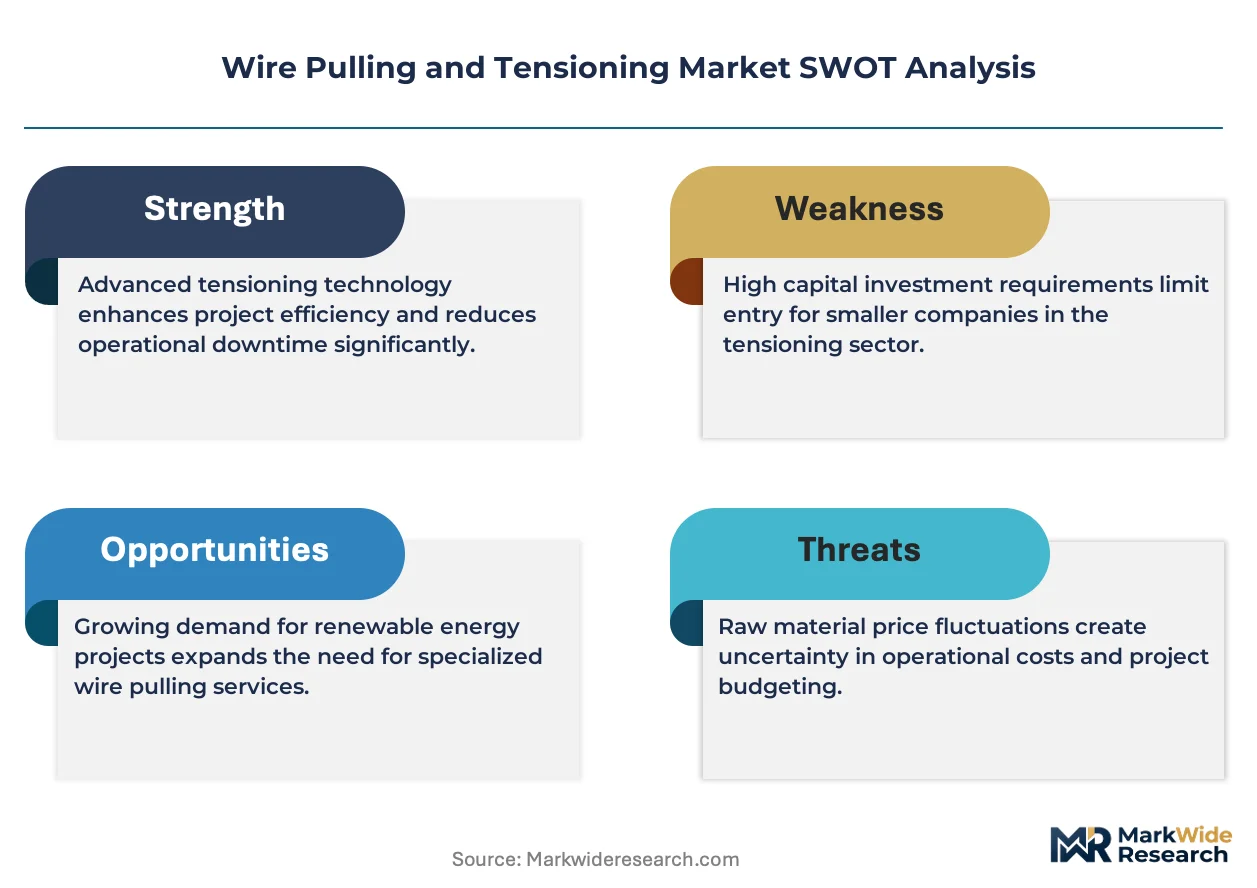
- OSHA 1926 Subpart V compliance:Utility contractors in the United States face elevated workplace safety enforcement for energized line work, accelerating replacement of non-insulated manual tools with certified tensioning equipment.
- Fiber densification programs:Telecommunications carriers are deploying micro-trenching and aerial fiber overlays that require precision tensioning systems for optical ground wire installations.
- High-temperature low-sag conductors:Aluminum composite core and gap-type technologies are expanding span lengths and tension loads, forcing upgrades to hydraulic pullers and electronic tension monitors.
Market Restraints
- Steel and aluminum price volatility:Raw material input costs for cable grips, sheaves, and bullwheel liners fluctuate with commodity markets, compressing margin stability for equipment fabricators.
- Supply concentration in castings and forgings:Foundry capacity for load-rated hardware concentrates in China's Hebei and Shandong provinces, exposing procurement timelines to regional energy rationing and export licensing.
- Manual tool substitution persistence:Residential electrical contractors continue deploying basic fish tapes and hand pullers for short-run installations, limiting premium equipment penetration in the building trades.
Strategic Opportunities
- India's Green Energy Corridors:The country's transmission expansion for solar parks and wind zones creates demand for mobile tensioning systems capable of desert and high-altitude deployment.
- Robotic cable deployment:Convergence of autonomous crawler systems with real-time tension sensing is opening hazardous environment applications where human lineman exposure is being restricted.
- CE marking harmonization:The EU Machinery Directive's updated conformity assessment routes are streamlining market access for modular tensioning platforms that can be field-reconfigured across voltage classes.
Industry Challenges
- Certified lineman shortage:Journeyman training programs for live-line tensioning work cannot match utility hiring needs, constraining fleet utilization rates for advanced equipment.
- UL 60974-1 testing backlog:Arc welding and electrical equipment certification queues at NRTLs are extending product launch timelines for manufacturers seeking utility-grade qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wire Pulling and Tensioning Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hand Tools, Power Tools, Cable Grips, Tensioning Devices Application: Construction, Telecommunications, Utilities, Manufacturing Installation Type: Onshore, Offshore, Indoor, Outdoor Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Greenlee (Emerson Electric Co.), Southwire Company, General Machine Products (GMP), Sherman + Reilly, TESMEC S.p.A, Condux International, Milwaukee Tool, Klein Tools, Hilti Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wire Pulling and Tensioning Market Emerging Trajectories
Electrification of field operations and digital instrumentation are redefining equipment specifications, with buyers prioritizing telemetry-enabled systems that integrate with utility asset management platforms.
Battery-powered hydraulic pullers are fragmenting the traditional diesel-powered equipment segment. Distribution cooperatives and municipal utilities are adopting these units for urban underground installations where emissions and noise restrictions apply. The technology is fragmenting rental fleet composition and compressing residual values for conventional engine-driven systems.
OSHA's updated enforcement posture on energized work is tightening compliance documentation requirements. Incident investigation protocols now mandate load-cell calibration records and operator certification trails for tensioning operations. United States transmission contractors are responding by consolidating procurement with suppliers offering integrated training and recertification programs.
Equipment-as-a-service arrangements are displacing capital purchase models among mid-sized electrical contractors. Rental channels and manufacturer-direct subscription programs are capturing maintenance and calibration responsibilities that previously burdened fleet owners. This shift is most visible in Germany's commercial construction sector, where labor cost pressures favor operational expenditure treatment over asset ownership.
Wire Pulling and Tensioning Market Segmentation
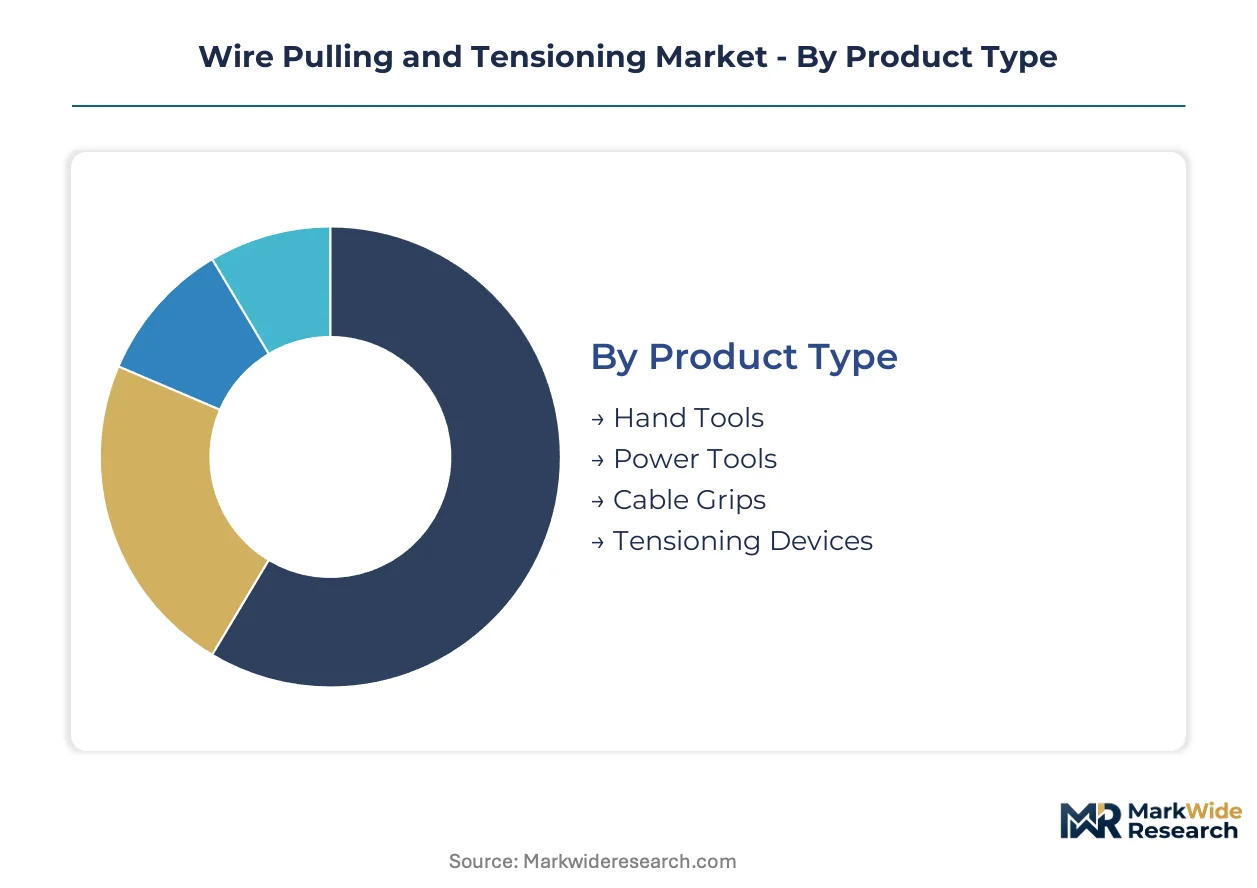
Equipment specifications diverge sharply across voltage classes and deployment environments, creating distinct procurement channels for utility-grade tensioning systems versus residential hand tools. Channel specialization intensifies as OSHA and NEC compliance documentation becomes a mandatory filter for contractor purchasing decisions.
Product Type:
Channel mix splits sharply: power tools and tensioning devices flow through manufacturer-direct and distributor networks with certified training bundles, while hand tools and cable grips dominate wholesale and online retail for residential electrical contractors.
- Power Tools:Battery-powered hydraulic pullers and electric cable pullers deliver tensile ratings from 2,000 to 50,000 pounds with integrated load monitoring. Demand concentrates among United States municipal utilities deploying underground distribution networks where emissions restrictions apply. OSHA 1926 Subpart V compliance documentation requirements accelerate replacement of legacy diesel units.
- Tensioning Devices:Hydraulic tensioners, bullwheel pullers, and electronic tension monitors manage conductor installation across transmission span lengths exceeding 1,000 feet. European transmission corridor projects in Germany and Poland specify CE-marked modular platforms capable of field reconfiguration across 132kV to 400kV classes.
- Hand Tools:Fish tapes, manual pullers, and basic cable grips serve short-run residential and light commercial installations through hardware retail channels.
- Cable Grips:Wire mesh grips and pulling eyes in galvanized steel or aluminum construction handle conductor termination across construction sites and utility maintenance yards.
By volume, Hand Tools leads. By growth pace, Power Tools is expanding most quickly.
Application:
Cost tier stratification separates utility procurement with capital equipment budgets from telecommunications fiber densification programs operating on accelerated depreciation schedules.
- Utilities:Grid hardening mandates and renewable interconnection queues compress replacement cycles for load-rated tensioning fleets. United States transmission contractors face elevated specification thresholds from investor-owned utilities modernizing aging infrastructure across Texas, California, and Midwest ISO regions.
- Telecommunications:Precision tensioning systems for optical ground wire and aerial fiber overlays align with carrier micro-trenching programs. China's MIIT equipment certifications and GB standards govern procurement for 5G backbone deployments across eastern provinces.
- Construction:Commercial and residential electrical contractors deploy mixed equipment fleets with rental channel preference for mid-tier hydraulic units.
- Manufacturing:Captive maintenance operations for industrial power distribution require portable tensioning equipment for in-plant cable routing and machinery relocation.
By installed base, Utilities dominates. By specification intensity, Telecommunications is climbing the fastest.
Installation Type:
Margin structure inverts across environments: offshore and outdoor deployments command premium pricing for corrosion-resistant hardware and weatherproof instrumentation, while indoor installations favor standardized rental fleet equipment.
- Outdoor:Overhead transmission line construction and aerial fiber deployment expose equipment to UV degradation, temperature cycling, and moisture ingress. German transmission operators specify IP-rated tensioning systems for North Sea wind farm interconnection corridors.
- Onshore:Desert solar park and high-altitude wind zone installations in India's Green Energy Corridors demand mobile tensioning platforms with all-terrain mobility and dust-sealed hydraulics.
- Indoor:Underground vault and substation installations prioritize compact footprints and emissions compliance for urban utility environments.
- Offshore:Submarine cable laying and platform electrification require specialized marine-grade tensioning systems with saltwater corrosion resistance.
By revenue per unit, Offshore leads. By deployment volume, Onshore is gaining share fastest.
Distribution Channel:
Customer type determines channel selection: large utilities consolidate procurement through direct manufacturer relationships with integrated training and calibration services, while mid-sized contractors shift toward equipment-as-a-service rental models.
- Direct Sales:Manufacturer-direct relationships capture utility-grade contracts with bundled operator certification, load-cell calibration records, and maintenance agreements. Southwire Company and TESMEC S.p.A anchor positions through integrated cable-to-tool ecosystems.
- Distributors:Electrical supply houses and industrial distributors serve contractor fleets with regional inventory positioning and same-day availability for standard tensioning equipment.
- Online Retail:E-commerce platforms capture residential electrical contractor and maintenance technician purchases for replacement cable grips, fish tapes, and consumable hardware.
- Wholesalers:Volume procurement channels for construction project material packages include basic wire pulling accessories alongside conduit and conductor orders.
By transaction value, Direct Sales leads. By model innovation, Distributors are ahead with subscription rental programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grid modernization incentives and renewable interconnection mandates are redirecting capital toward transmission infrastructure across major economies. Procurement patterns concentrate where utility-scale electrification programs intersect with aging conductor replacement cycles.
United States
Investor-owned utilities in Texas, California, and Midwest ISO regions are accelerating fleet replacement for load-rated tensioning equipment. OSHA 1926 Subpart V enforcement tightens compliance documentation for energized line work. Houston and Dallas-Fort Worth anchor contractor procurement clusters for transmission hardening projects.
Germany
North Sea wind farm interconnection corridors drive specification intensity for CE-marked modular tensioning platforms. The EU Machinery Directive's updated conformity assessment routes streamline cross-border equipment certification. Bavaria and North Rhine-Westphalia concentrate transmission corridor construction activity.
China
MIIT equipment certifications and GB standards govern procurement for 5G backbone and ultra-high-voltage transmission deployments. State Grid Corporation's renewable integration queues compress replacement cycles for hydraulic puller fleets. Hebei and Shandong provinces concentrate foundry capacity for load-rated hardware.
India
Green Energy Corridor transmission expansion for solar parks and wind zones creates demand for mobile desert and high-altitude tensioning systems. CEA technical standards mandate insulated grip specifications for live-line work. Gujarat and Rajasthan anchor solar park interconnection equipment procurement.
Wire Pulling and Tensioning Market Vendor Landscape
Player mix skews toward integrated cable-to-tool ecosystems and specialized transmission equipment fabricators. Market structure tiers across premium utility-grade suppliers, mid-tier rental fleet providers, and volume hand tool manufacturers. Strategic archetypes include vertically integrated electrical conglomerates, regional tensioning specialists, and professional tool brands. Competitive moves center on certification bundling with operator training programs and equipment-as-a-service subscription models.
Among North American integrated suppliers, Southwire Company anchors the cable-to-tool ecosystem archetype. TESMEC S.p.A represents the European transmission specialist tier. Greenlee, operating under Emerson Electric Co., occupies a position within the professional tool and utility equipment segment. These three exemplify how geographic origin and corporate structure map to distinct competitive positioning vectors.
| Leading Market Players |
|---|
| Greenlee (Emerson Electric Co.) |
| Southwire Company |
| General Machine Products (GMP) |
| Sherman + Reilly |
| TESMEC S.p.A |
| Condux International |
| Milwaukee Tool |
| Klein Tools |
| Hilti Corporation |
| Others |
Supply Flow & Price Mechanics
Battery-powered hydraulic puller substitution for diesel units simultaneously relocates supply chain gravity toward lithium-ion cell manufacturing clusters and compresses pricing premiums for legacy engine-driven equipment. This displacement concentrates procurement leverage with municipal utilities enforcing emissions restrictions while eroding residual values for conventional fleet assets.
Pricing Analysis
Certification level creates the primary spread between utility-grade and contractor-tier equipment, with UL 60974-1 and CE marking commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across premium certified, mid-tier rental, and economy hand tool levels stratifies the market, with OSHA 1926 Subpart V documentation requirements intensifying cost compression in the mid-tier segment. Residential electrical contractors exhibit highest price sensitivity, while investor-owned utilities prioritize bundled training and calibration services over unit economics.
Supply Chain Analysis
Foundry capacity concentration in China's Hebei and Shandong provinces anchors load-rated hardware production for cable grips, sheaves, and bullwheel liners. Steel and aluminum raw material inputs draw from domestic Chinese smelters and Australian bauxite channels, exposing fabricators to regional energy rationing and export licensing volatility. Single-source vulnerability in castings and forgings feeds procurement timeline risk. Distribution runs through manufacturer-direct relationships for utility contracts and electrical supply houses for contractor fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grid electrification mandates and robotic cable deployment convergence signal high-growth disruption, with OSHA's energized work enforcement creating regulatory inflection for certified equipment demand.
For Market Incumbents: Consolidate certification bundling with operator training programs to defend against equipment-as-a-service rental models eroding capital purchase volumes. Deepen backward integration into foundry capacity to mitigate Hebei and Shandong supply concentration risk. Prioritize telemetry-enabled system development integrating with utility asset management platforms. For New Entrants and Emerging Players: Differentiate on battery-powered hydraulic puller specialization targeting municipal utilities with urban underground installation mandates. India's Green Energy Corridors for solar and wind transmission expansion represent the most penetrable geography, with mobile desert and high-altitude deployment capabilities as the critical go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional tensioning specialists holding established utility relationships but lacking digital platform integration. Five-to-ten year viability hinges on electrification compliance adaptation. Monitor UL 60974-1 certification backlog duration at NRTLs as the key inflection signal for manufacturer launch timeline risk.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Subscription Launch | Captures maintenance and calibration responsibilities from fleet owners facing OSHA documentation mandates. |
| Battery-Powered Hydraulic Puller Platform Expansion | Addresses municipal utility emissions restrictions while fragmenting diesel equipment rental composition. |
| Robotic Cable Deployment System Development | Opens hazardous environment applications where OSHA restricts human lineman exposure. |
| Integrated Training and Recertification Program | Consolidates contractor procurement with suppliers meeting OSHA 1926 Subpart V enforcement. |
| Foundry Capacity Backward Integration | Reduces exposure to Hebei and Shandong energy rationing and export licensing disruptions. |
Methodological Framework
A standing panel of utility procurement officers, transmission contractors, electrical supply distributors, and aftermarket service managers provided ongoing calibration against field conditions. Primary interview insights combined with secondary validation from OSHA enforcement records, FERC grid investment filings, utility capital expenditure disclosures, and equipment certification databases. Bottom-up segment sizing and top-down macro triangulation anchored volume and value estimates.
Cross-checking against external benchmarks confirmed consistency across product type, application, installation environment, and voltage class segmentation dimensions. CAGRs derived from equipment replacement cycle compression analysis and renewable interconnection queue growth rates. Forecast inputs incorporated grid hardening mandate timelines and fiber densification program acceleration curves.
The analysis sits within stated boundaries; outcomes outside sustained utility capital commitment or accelerated robotic deployment adoption would require recalibration. Forecasts reflect documented assumptions regarding OSHA enforcement posture and raw material price stability. Practitioners should keep alternative scenarios live as certification backlog durations and foundry capacity utilization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Hoist Sling Chains Assemblies Market
Material Handling Equipment
Industrial Mezzanines Market
Material Handling Equipment
Middle East and Africa Automated Material Handling Market
Material Handling Equipment
Hydraulic Hoist Market
Material Handling Equipment
Shiplifts & Transfer Systems Market
Material Handling Equipment
Material Handling Integration Market
Material Handling Equipment
Global Dewatering Equipment Market
Material Handling Equipment
Retractable Lift Market
Material Handling Equipment
Container Handler Market
Material Handling Equipment
Global Pipe and Tube Bending Machine Market
Material Handling Equipment
Apron Feeder Market
Material Handling Equipment
Fluid Conveyance Systems Market
Material Handling Equipment
Wood Chipper Market
Material Handling Equipment
Hydraulic Fittings Market
Material Handling Equipment
Fork Lift Attachments Market
Material Handling Equipment
India Automated Material Handling (AMH) Market