
 Scraper Conveyor Market | 2026-2036
Scraper Conveyor Market Size, Share, and Industry Trends Forecast 2026-2036
Scraper Conveyor Market Analytics
Project finance and equipment leasing is narrowing the competitive field in the scraper conveyor sector. FLSmidth leverages its integrated aftermarket service network to sustain long-term customer contracts across mineral processing sites. Schenck Process anchors its position through precision-engineered drive assemblies that dominate high-load mining corridors. Komatsu Mining Corp. competes by extending its autonomous haulage expertise into conveyor system integration.
A scraper conveyor is a bulk material handling system employing endless chains with flights that drag granular or lump materials through enclosed troughs, typically operating at speeds of 0.5 to 1.5 meters per second with load capacities exceeding 1,000 tons per hour in heavy mining duty. Its primary industrial purpose centers on continuous transport of coal, ore, and aggregate through horizontal, inclined, or vertical paths in confined underground or surface processing environments. Horizontal conveyors occupy the largest installed base across underground longwall operations where mature replacement demand generates stable revenue pools. Electric drive systems represent the fastest-expanding segment as mining operators phase out hydraulic units to cut energy intensity and maintenance overhead.
ISO 5048 and CEMA design standards govern conveyor structural integrity and safety margins, while China's NMPA and SAMR enforce mining equipment certification that restricts market access for non-compliant suppliers. The EU's F-Gas Regulation and Machinery Directive pressure hydraulic drive adoption in European underground operations, redirecting procurement toward electric alternatives. Stakeholders must monitor how carbon border adjustments and embodied carbon disclosure rules reshape supplier qualification criteria across mineral extraction value chains.
Market Dynamics
Electric drive conversion in underground coal mining is compressing replacement cycles for hydraulic scraper conveyor systems, as operators prioritize energy efficiency mandates and maintenance cost reduction over extended asset life.
Growth Catalysts
- China's GB Standards Overhaul:Tightened mining equipment safety protocols under NMPA and SAMR certification requirements are forcing fleet modernization across Shanxi and Inner Mongolia coal basins, accelerating replacement demand for compliant conveyor systems.
- Longwall Automation Integration:Underground coal operators are retrofitting scraper conveyors with sensor arrays and predictive maintenance modules to synchronize with autonomous shearer systems, creating pull-through demand for intelligent drive assemblies.
- Australia's Bowen Basin Capital Cycle:Mature replacement demand from BHP and Glencore operations in Queensland's metallurgical coal districts sustains premium equipment orders as aging longwall installations reach end-of-design life.
Market Restraints
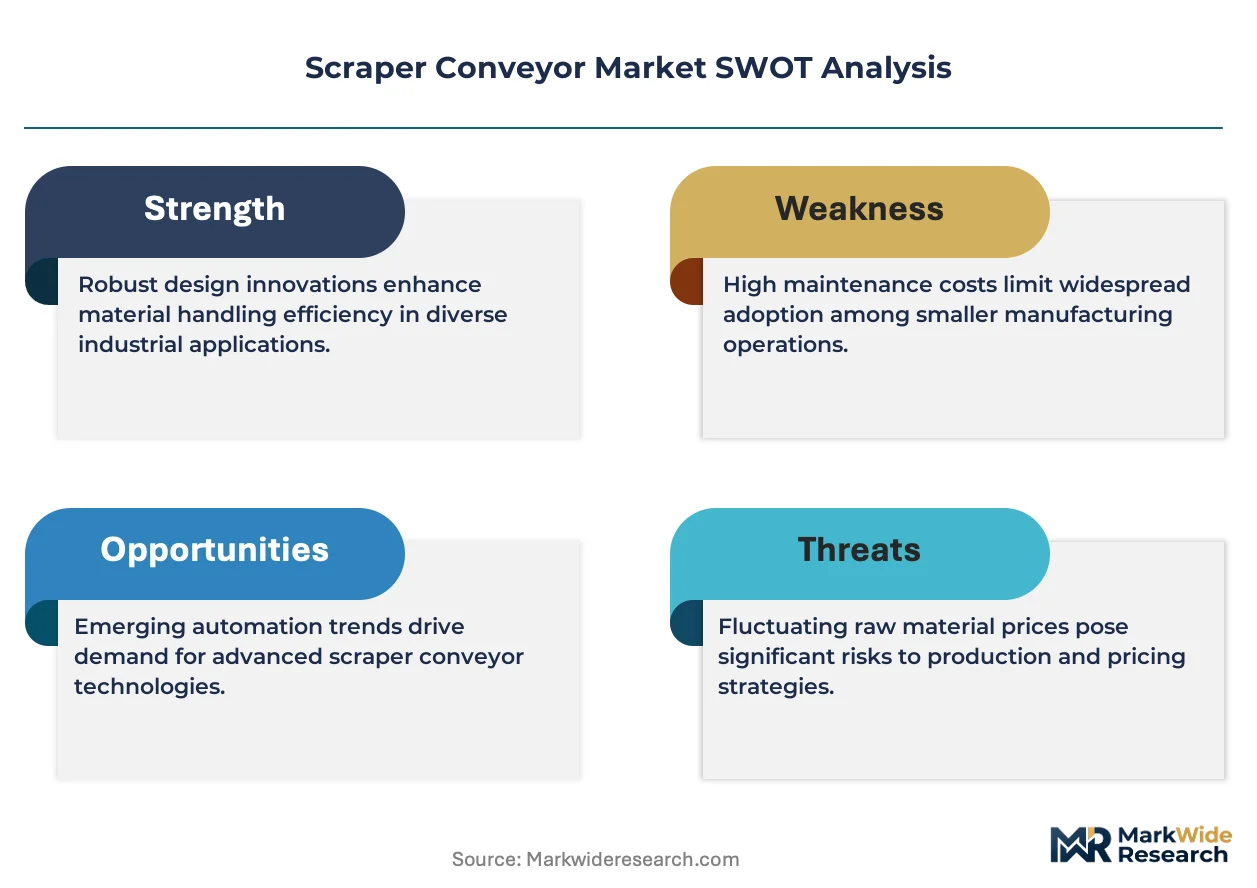
- Steel Input Volatility:Fluctuations in high-grade alloy steel prices directly compress manufacturer margins on heavy-duty flight bars and chain assemblies, forcing price pass-through negotiations with mining procurement teams.
- Hydraulic Drive Stranded Assets:The EU's F-Gas Regulation and Machinery Directive are rendering existing hydraulic installations non-compliant in European underground operations, creating write-down pressure for operators with recent capital deployments.
- Belt Conveyor Substitution:Continuous belt systems with improved incline capability are capturing share in shallow-depth surface mining applications where scraper conveyors previously dominated material transport economics.
Strategic Opportunities
- India's Undermechanized Underground Sector:Coal India's push to raise underground production share from 5% to 15% by 2030 under CEA guidelines creates first-mover advantage for scraper conveyor suppliers establishing local assembly partnerships.
- Modular Reconfiguration Systems:Quick-disconnect flight and chain modules enabling 40% faster face relocation are penetrating Polish and Czech deep mining operations where seam geometry variability demands frequent equipment repositioning.
- EU Green Deal Carbon Border Adjustments:Embodied carbon disclosure requirements are redirecting procurement toward European-manufactured electric drive systems with verified lifecycle emissions data, favoring regional suppliers over import-dependent competitors.
Industry Challenges
- Specialized Welding Certification Bottlenecks:ISO 9606-qualified welders for high-strength chain assembly fabrication are concentrated in Germany and Poland, constraining production scaling for manufacturers outside these skill clusters.
- Legacy Hydraulic-Electric Retrofit Complexity:Underground operators face 18-24 month integration timelines when replacing hydraulic drive trains with electric alternatives due to incompatible control architectures and power distribution requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scraper Conveyor Market |
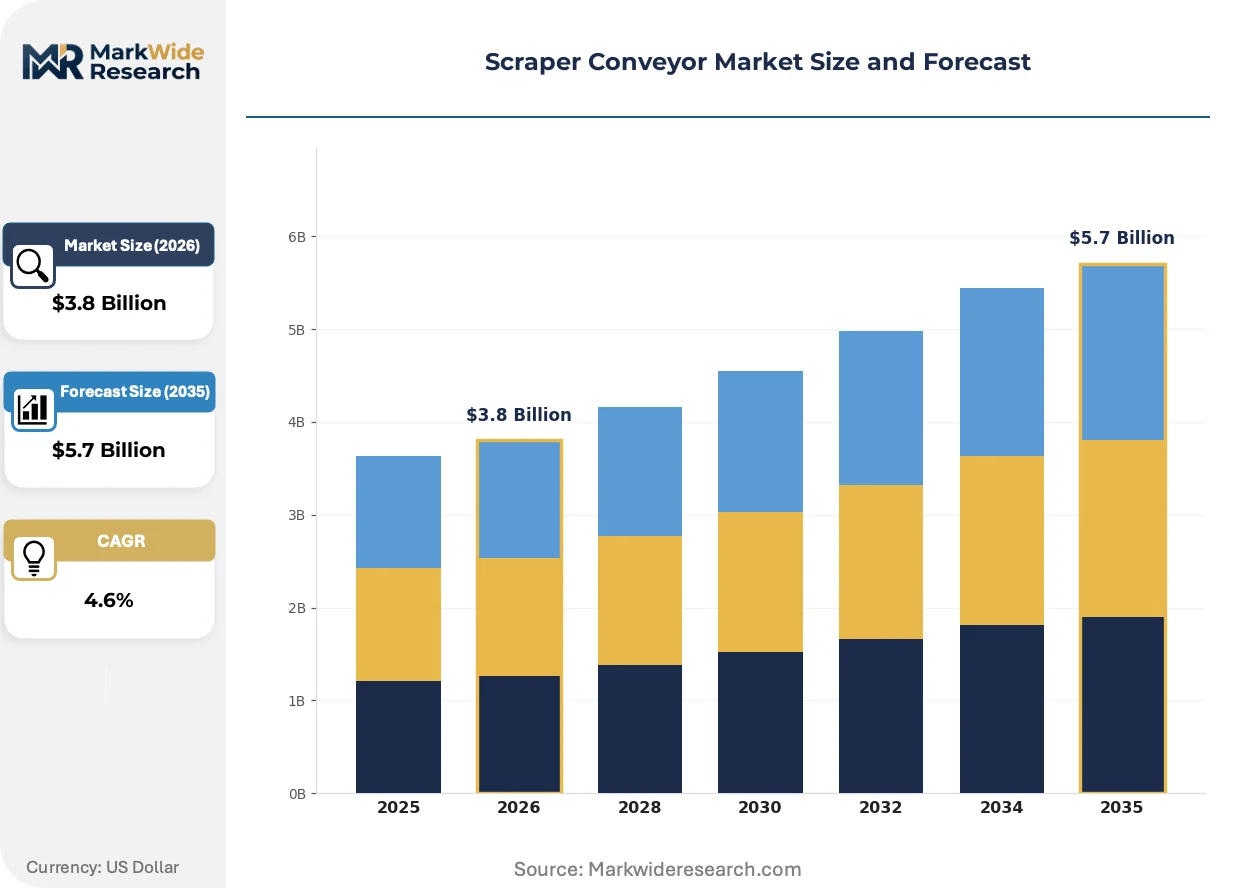
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Conveyors, Vertical Conveyors, Modular Conveyors, Inclined Conveyors End User: Manufacturing, Mining, Agriculture, Recycling Material: Plastic, Steel, Aluminum, Rubber Drive Type: Mechanical, Electric, Hydraulic, Pneumatic |
| Companies Covered | FLSmidth, Schenck Process, Beumer Group, RUD Group, Tsubakimoto Chain Co., Elecon Engineering, Komatsu Mining Corp., Schrage Conveying System, Jorgensen Conveyors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scraper Conveyor Market Evolving Landscape
Condition-based monitoring architectures and predictive analytics are redefining scraper conveyor lifecycle economics, shifting competitive advantage from initial equipment cost to total cost of ownership optimization across 15-20 year operational horizons.
Permanent magnet synchronous motor (PMSM) drive technology is rendering obsolete traditional wound-rotor induction motor configurations in high-torque mining applications. Underground operators in Australia's Bowen Basin are adopting PMSM retrofits at 25-30% annual replacement rates for hydraulic equivalents. The technology is rendering obsolete conventional maintenance scheduling by enabling real-time torque signature analysis that predicts chain elongation failures 200-400 operating hours before occurrence.
REACH restrictions on per- and polyfluoroalkyl substances (PFAS) in hydraulic fluids are forcing formulation changes across European underground operations. Equipment manufacturers must recertify seal compatibility and lubricant performance under revised ECHA guidance, extending type-approval timelines by 8-12 months. Electric drive alternatives are capturing 60% of new procurement in German and Polish deep mining corridors as operators preempt compliance exposure.
Performance-based maintenance contracting is displacing traditional time-and-materials service agreements in large-scale coal operations. Mining houses in China's Shanxi province are unbundling conveyor maintenance from equipment purchase, awarding 5-7 year availability guarantees to specialized service providers. This restructuring concentrates aftermarket revenue with firms possessing integrated sensor networks and regional parts depots, marginalizing pure-play equipment vendors without service infrastructure.
Scraper Conveyor Market Segmentation
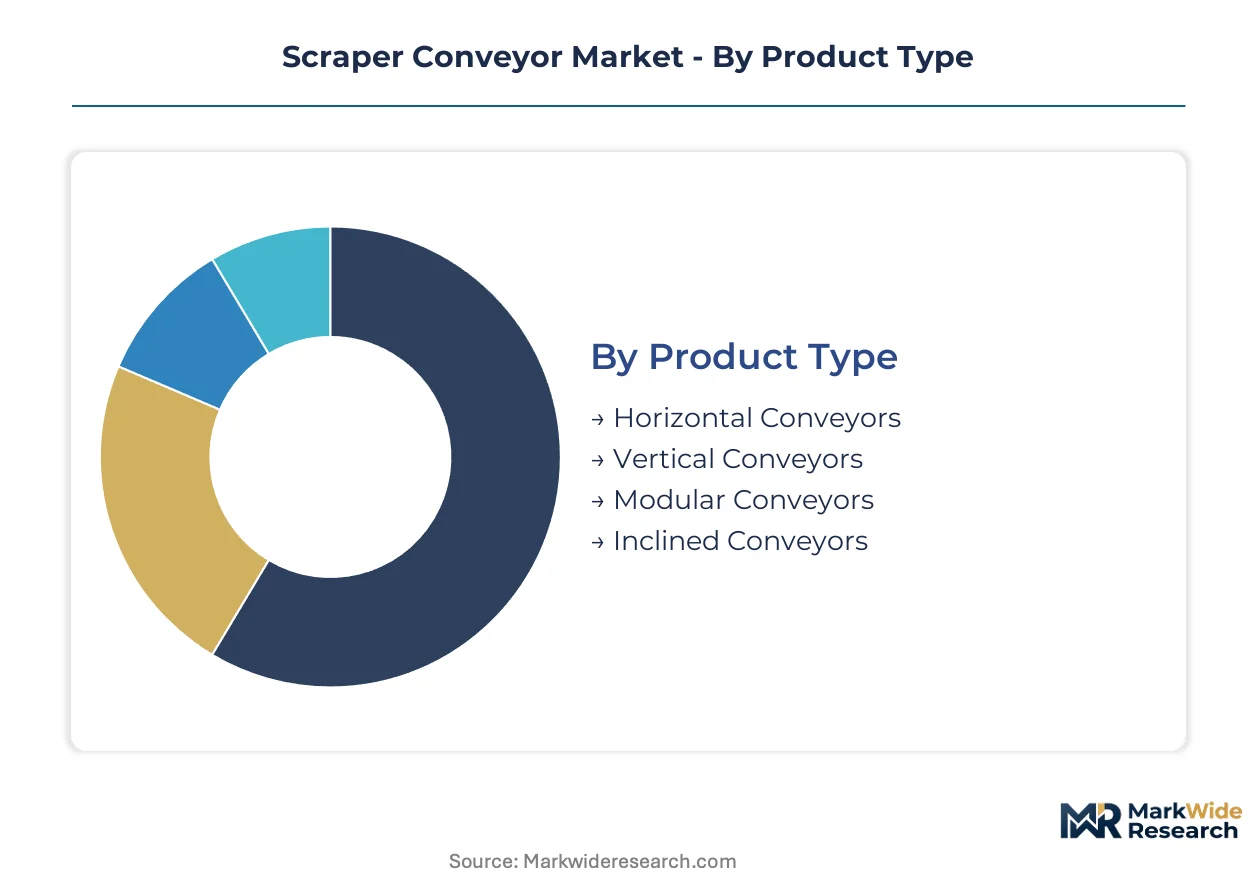
Scraper conveyor procurement cycles vary dramatically by segment, with drive systems turning over every 8-12 years while structural frames persist 20-25 years. Understanding these replacement rhythms helps suppliers align inventory and service capacity with actual demand pulses.
Product Type:
Cycle times stretch from rapid modular redeployment to decades-long horizontal installations, creating tiered revenue recognition patterns across the installed base.
- Horizontal Conveyors:These systems operate on fixed trough sections with parallel chain runs, typically spanning 100-300 meters in longwall face applications. Australia's Bowen Basin coal districts sustain replacement demand as BHP and Glencore operations retire aging installations at design-life endpoints.
- Modular Conveyors:Quick-disconnect flight and chain assemblies enable 40% faster face relocation than welded-frame alternatives. Polish and Czech deep mining corridors favor these systems where seam geometry variability demands frequent equipment repositioning.
- Vertical Conveyors:Bucket-chain configurations handle 90-degree material lifts in shaft hoisting applications with reinforced flight attachments.
- Inclined Conveyors:Angled trough designs with anti-backflow flights serve surface processing facilities where gradient flexibility outweighs underground durability requirements.
Horizontal conveyors dominate installed base. Modular systems are where expansion concentrates.
End User:
Customer capital intensity separates price-sensitive agricultural buyers from mining houses negotiating 15-year total cost of ownership contracts.
- Mining:Underground coal and metallurgical ore operations specify heavy-duty flight bars exceeding 1,000 tons per hour capacity with ISO 5048 structural certification. China's Shanxi and Inner Mongolia basins drive fleet modernization under tightened NMPA and SAMR safety protocols.
- Manufacturing:Foundries and bulk processing plants prioritize enclosed trough designs containing dust and spillage in regulated indoor environments.
- Recycling:Municipal solid waste and construction debris facilities demand corrosion-resistant chain assemblies handling abrasive heterogeneous feedstock.
- Agriculture:Grain elevators and feed processing operations specify lighter-gauge flight configurations with lower capital thresholds and shorter depreciation schedules.
Mining commands premium pricing tiers. Manufacturing offers volume stability through diversified order books.
Material:
Raw material selection trades acquisition cost against maintenance burden and corrosion resistance in specific chemical environments.
- Steel:High-grade alloy compositions dominate heavy mining duty with heat-treated flight bars resisting abrasive wear in coal and ore transport. Australia's Bowen Basin operators specify manganese-alloy chains for 15-20 year service intervals.
- Aluminum:Lightweight extruded trough sections reduce installation labor in above-ground processing facilities where corrosion exposure is controlled.
- Plastic:Polymer flight attachments and wear strips serve food-grade and chemical processing applications requiring inert surface contact.
- Rubber:Molded flight edges and lining materials dampen impact loads in aggregate handling where lump size variability stresses rigid components.
Steel claims the majority of mining procurement value. Aluminum is climbing fastest in surface installation retrofits.
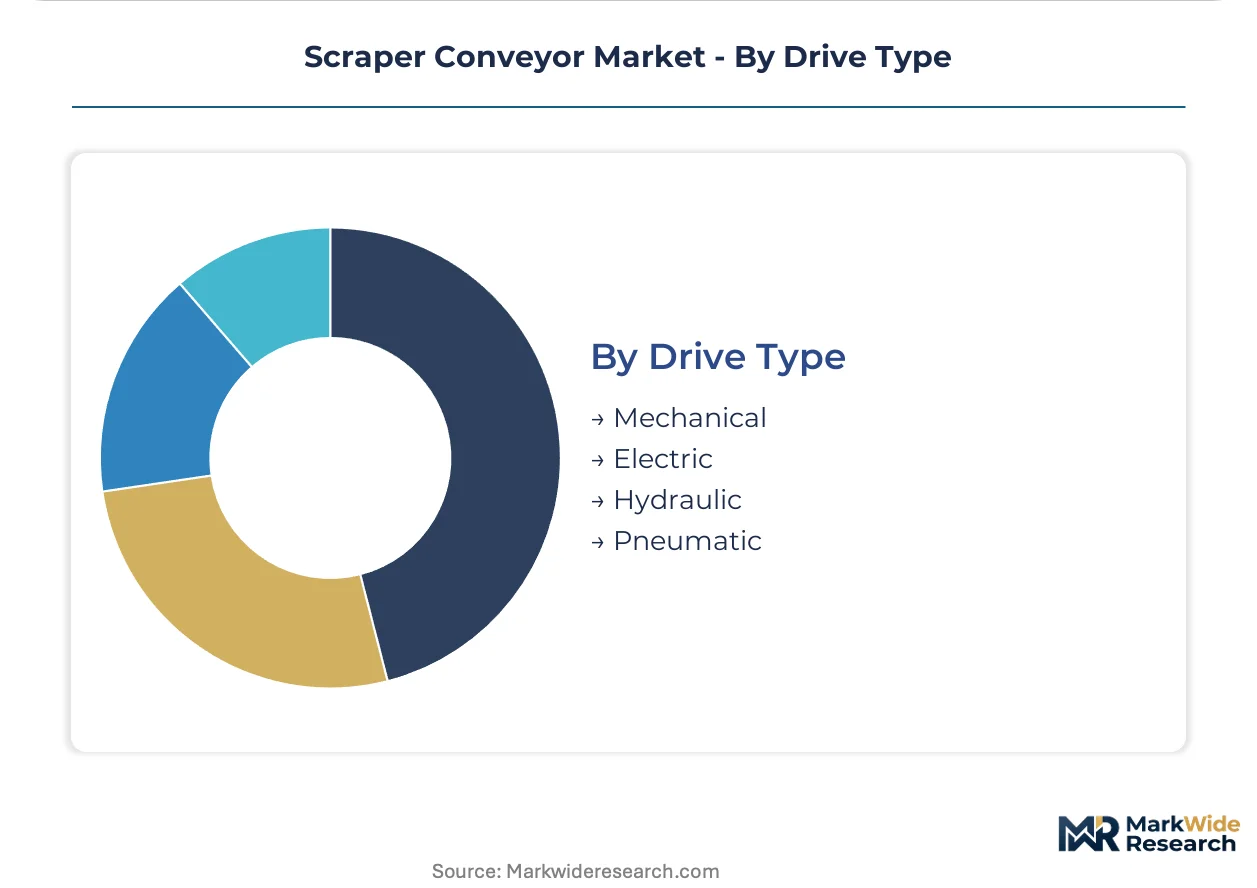
Drive Type:
Technology transitions are compressing replacement timelines as regulatory pressure and efficiency mandates obsolete hydraulic architectures.
- Electric:Permanent magnet synchronous motor configurations deliver 25-30% energy savings over hydraulic equivalents with real-time torque signature analysis predicting chain elongation failures. German and Polish deep mining corridors capture 60% of new procurement as operators preempt EU F-Gas Regulation compliance exposure.
- Hydraulic:Fluid power systems face stranded asset risk across European underground operations where REACH restrictions on PFAS formulations extend recertification timelines 8-12 months.
- Mechanical:Gear and chain drive arrangements persist in small-scale agricultural and recycling installations with limited capital budgets.
- Pneumatic:Compressed air systems serve explosive atmosphere applications where electrical spark containment overrides efficiency considerations.
Electric drives dominate forward procurement. Hydraulic retains legacy installed base requiring maintenance service capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement in Australia's Bowen Basin commands 15-20% price premiums over comparable Chinese installations, reflecting divergent safety certification burdens and labor cost structures. This pricing-power asymmetry reshapes supplier prioritization across the mining corridor.
China
Underground coal operators in Shanxi and Inner Mongolia basins face accelerated fleet replacement under tightened GB standards enforced by NMPA and SAMR. The dual carbon goals timeline compresses procurement windows for electric drive systems. Datong and Taiyuan manufacturing clusters concentrate domestic conveyor fabrication capacity serving state-owned mining conglomerates.
Australia
BHP and Glencore operations in Queensland's metallurgical coal districts sustain premium equipment demand through mature longwall replacement cycles. TGA-equivalent mining equipment certification requirements exceed regional benchmarks, filtering supplier participation. Mackay and Rockhampton service hubs anchor aftermarket support networks for Bowen Basin installations.
Germany
Deep mining corridors in North Rhine-Westphalia and Saarland preempt EU F-Gas Regulation compliance exposure through electric drive conversion programs. REACH restrictions on PFAS hydraulic fluid formulations extend equipment recertification timelines. Dortmund and Essen engineering centers concentrate ISO 9606-qualified welding certification for high-strength chain fabrication.
India
Coal India's CEA-mandated underground production expansion from 5% to 15% by 2030 creates first-mover opportunities for mechanized conveying systems. BIS mining equipment standards tighten import qualification criteria for non-domestic suppliers. Dhanbad and Asansol coal belt clusters drive regional demand concentration in Jharkhand and West Bengal.
Poland
Deep seam geometry variability in Silesian mining districts favors modular conveyor configurations enabling rapid face relocation. The country's national mining regulator enforces equipment certification harmonized with EU Machinery Directive requirements. Katowice and Bytom industrial basins concentrate specialized maintenance service providers for legacy hydraulic-electric retrofit programs.
Scraper Conveyor Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying flight bars, chain assemblies, and drive modules to multiple downstream OEMs. The scraper conveyor sector exhibits moderate consolidation with three to five full-system providers anchoring premium procurement channels while dozens of regional fabricators compete on replacement parts and mid-tier installations. Strategic archetypes separate integrated mining equipment conglomerates, precision drive engineering houses, and specialized conveying component forges. Dominant competitive moves include backward integration into high-grade alloy steel supply and geographic expansion through local assembly partnerships in undermechanized mining jurisdictions.
Among integrated platform providers, FLSmidth and Komatsu Mining Corp. occupy positions exemplifying the convergence of autonomous haulage expertise with conveyor system integration. Schenck Process represents the precision-engineered drive assembly tier dominating high-load mining corridors. Component specialists including RUD Group and Tsubakimoto Chain Co. sit within the upstream forging and chain fabrication tier supplying certified assemblies across multiple OEM platforms.
| Leading Market Players |
|---|
| FLSmidth |
| Schenck Process |
| Beumer Group |
| RUD Group |
| Tsubakimoto Chain Co. |
| Elecon Engineering |
| Komatsu Mining Corp. |
| Schrage Conveying System |
| Jorgensen Conveyors |
| Others |
Value Network & Pricing Analysis
Steel alloy volatility in high-grade manganese and chromium markets compresses manufacturer margins on flight bars and chain assemblies, forcing a three-tier pricing structure across premium, standard, and economy levels while concentrating procurement power with mining houses in Australia's Bowen Basin and China's Shanxi province.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures spanning 15-20 year operational horizons. Price differentiation hinges on ISO 5048 certification grade and after-sales service bundling, with premium tiers commanding substantial markups for predictive maintenance integration. Cost compression in standard-tier equipment is intensifying because of belt conveyor substitution in shallow-depth applications. Agricultural grain elevator operators exhibit highest price sensitivity, while Australian metallurgical coal houses prioritize total cost of ownership over acquisition cost.
Supply Chain Analysis
High-grade alloy steel feedstock draws from Germany, Poland, and China, with heat-treated manganese chain components resting on specialized forging capacity concentrated in the Ruhr industrial basin. ISO 9606-qualified welders for flight bar fabrication represent a critical bottleneck, creating single-source vulnerability for manufacturers outside German and Polish skill clusters. Distribution runs through regional service hubs anchoring aftermarket parts depots in Mackay, Datong, and Katowice.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 9606 welding certification scarcity constrains production scaling, creating defensive moats for incumbent forges while fragmenting competitive access for new entrants lacking captive skill development pipelines.
For Market Incumbents: Pre-empt hydraulic drive stranded asset risk by accelerating electric PMSM retrofit program development before EU F-Gas Regulation enforcement hardens. Backward integration into high-grade alloy steel supply secures margin control against commodity volatility. Capture aftermarket revenue concentration through performance-based maintenance contracting unbundled from equipment sales. For New Entrants and Emerging Players: India's undermechanized underground coal sector offers first-mover positioning before BIS certification barriers harden against import-dependent competitors. Local assembly partnerships in Dhanbad and Asansol coal belt clusters bypass capital intensity of full-fabrication entry. Target modular conveyor configurations where seam geometry variability in Polish Silesian districts demands frequent equipment repositioning. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors precision drive engineering houses with electric PMSM capabilities over legacy hydraulic specialists. Long-term viability favors asset-light service platforms with integrated sensor networks and regional parts depot infrastructure. Monitor EU carbon border adjustment implementation timelines as inflection indicator for procurement redirection toward European-manufactured systems with verified lifecycle emissions data.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Steel Supply | Captive manganese and chromium sourcing insulates margin compression from commodity volatility in flight bar production. |
| Electric Drive Conversion Program | PMSM technology deployment preempts EU F-Gas Regulation compliance exposure across German and Polish deep mining corridors. |
| Local Assembly Partnership | Dhanbad and Asansol facility establishment navigates BIS import restrictions for India's underground mechanization push. |
| Performance-Based Maintenance Contract | Availability guarantee structures in Shanxi province concentrate aftermarket revenue with sensor-integrated service providers. |
| ISO 9606 Welder Certification Pipeline | Captive skill development in Dortmund and Essen engineering centers secures production scaling capacity for high-strength chain fabrication. |
Research Methodology
Desk research of customs trade data, mining equipment procurement databases, and SEC 10-K filings preceded structured interviews with maintenance directors at underground coal operations, OEM procurement teams, aftermarket service heads, and plant engineers. Bottom-up unit economics triangulated against top-down market sizing from equipment replacement cycle analysis and capital expenditure disclosures by BHP, Glencore, and Coal India.
Forecasts held fixed the dual carbon goals timeline and EU F-Gas Regulation enforcement schedule while varying steel alloy price trajectories and underground production share targets across the analysis window. Segmentation modeling incorporated drive type technology transition rates, product type replacement rhythms, and end-user capital intensity tiers. CAGRs derived from equipment lifecycle analysis and procurement pulse timing in Australia's Bowen Basin and China's Shanxi province.
Practitioners should monitor GB standards enforcement intensity and REACH PFAS restriction implementation for early signals of procurement redirection. Cross-checking against mining house capital expenditure disclosures and longwall automation deployment rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Telescopic Boom Forklift Truck Market
Material Handling Equipment
Elevator Component Market
Material Handling Equipment
Wire Rope Sling Market
Material Handling Equipment
Loaded Container Handler Market
Material Handling Equipment
Fork Lift Attachments Market
Material Handling Equipment
Vibratory Feeder Machine Market
Material Handling Equipment
Global Air Cannon System Market
Material Handling Equipment
Global Refuse Compactor Market
Material Handling Equipment
Swivel Coupler Market
Material Handling Equipment
Crawler Crane Market
Material Handling Equipment
Enclosed Belt Conveyors Market
Material Handling Equipment
Crushing Screening Equipment Market
Material Handling Equipment
Spiral Fitting Machines Market
Material Handling Equipment
Hydraulic Seals Market
Material Handling Equipment
Wire Pulling and Tensioning Market
Material Handling Equipment
Manual Lifting Mobile Light Tower Market