
 Automotive Appearance Chemicals Market | 2026-2036
Automotive Appearance Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Appearance Chemicals Market Intelligence
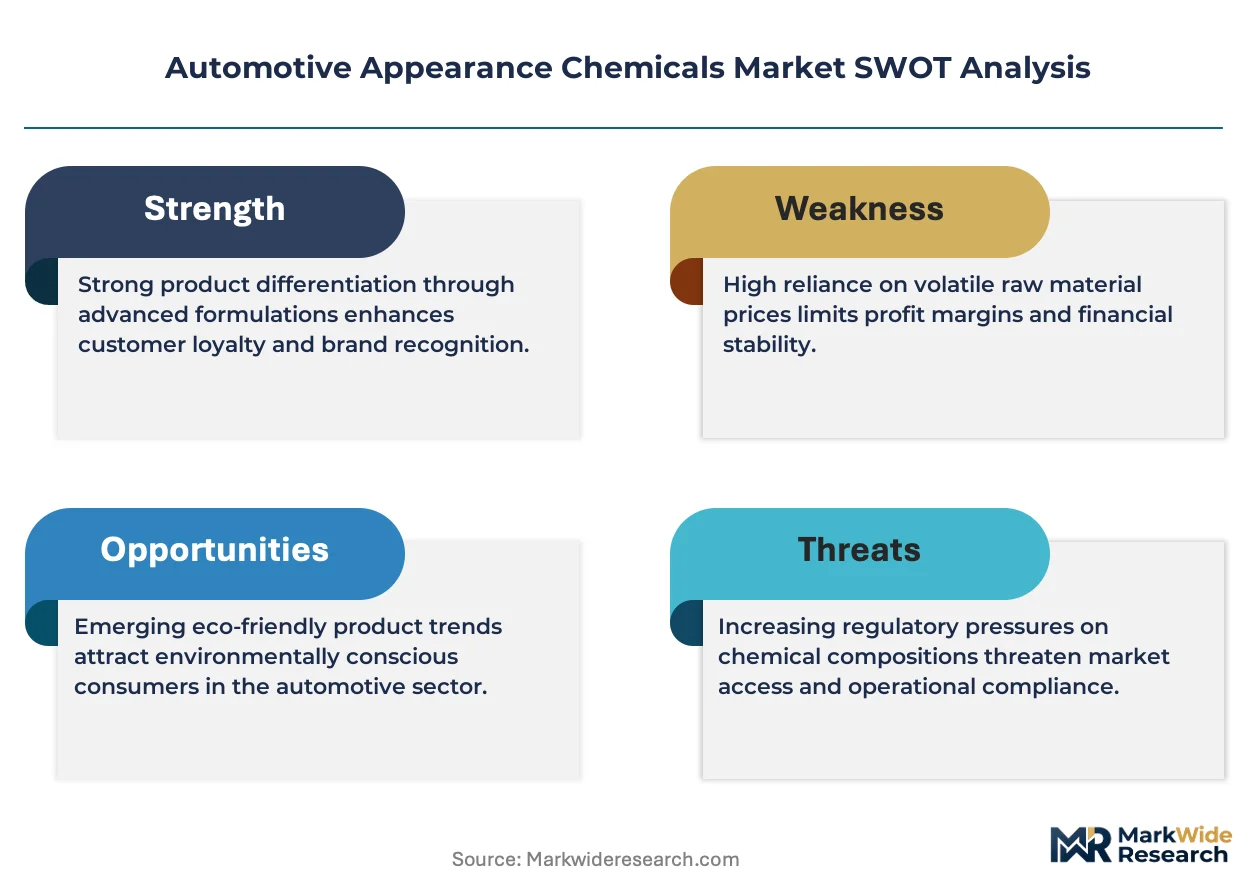
Premium ceramic coating formulations is decoupling from commodity spray waxes in both pricing and distribution channels. BASF SE leverages its integrated polymer supply chain to dominate high-performance sealant chemistry. 3M competes through proprietary fluoropolymer technology that sustains premium positioning in professional detailing channels. Turtle Wax anchors the mass-market tier through supermarket and auto-parts retail dominance.
Automotive appearance chemicals encompass polishes, waxes, cleaners, and sealants formulated with silicones, abrasives, solvents, and nano-ceramic compounds to restore gloss, protect substrates, and extend vehicle finish life. Manufacturing relies on controlled particle-size distribution for abrasives and pH-balanced surfactant systems to prevent clear-coat damage. Wax and sealant products command the thickest margin pools due to recurring application cycles and premium pricing power, while exterior detailing applications lead volume through dealership and aftermarket service bay throughput. Interior care formulations are gaining fastest as cabin air quality and antimicrobial claims attract health-conscious vehicle owners.
EPA VOC regulations in the United States restrict solvent content in aerosol and liquid formulations, while REACH in Europe mandates disclosure of nano-ingredient hazards and drives substitution toward bio-based solvents. China's MEE enforces emissions controls on coating chemical production facilities, raising compliance costs for local and imported suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to avoid formulation fragmentation that strains R&D budgets and complicates global product portfolios.
Market Dynamics
Waterborne formulation mandates from EPA and REACH are forcing manufacturers to rebuild solvent-dependent product architectures from the ground up, compressing margins for legacy suppliers while rewarding integrated polymer producers with captive R&D capacity.
Growth Catalysts
- EPA VOC restrictions:Regulatory pressure on solvent content is accelerating R&D investment in low-emission chemistries, creating first-mover advantages for compliant suppliers in US detailing channels.
- Nano-ceramic compound adoption:Professional service bays are integrating ceramic sealants into standard detailing packages, extending application cycles and locking in recurring revenue streams.
- China automotive production clusters:Dense manufacturing corridors in Shanghai and Guangzhou are generating concentrated demand for OEM-compatible appearance chemicals through integrated supply contracts.
Market Restraints
- Petrochemical feedstock volatility:Silicone and fluoropolymer precursor costs fluctuate with crude oil indices, squeezing formulation margins for non-integrated compounders.
- German chemical supplier concentration:Specialty polymer production clusters in the Rhine-Ruhr region create single-source dependency risks for sealant manufacturers.
- Clear-coat damage liability:Abrasive particle-size tolerance windows are narrowing as OEM warranties tighten, limiting product performance claims and differentiation.
Strategic Opportunities
- India aftermarket expansion:Underdeveloped professional detailing infrastructure in Mumbai and Delhi corridors offers whitespace for service-network partnerships and product localization.
- Antimicrobial interior formulations:Cabin air quality claims are opening premium pricing tiers for health-positioned cleaners in consumer retail channels.
- EU Green Deal bio-solvent incentives:Substitution mandates for petroleum-derived carriers are creating procurement advantages for bio-based formulation suppliers.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in pH-balanced surfactant systems and particle-size engineering is concentrated among aging technical workforces in Germany and Japan.
- REACH nano-ingredient disclosure timelines:Extended hazard documentation requirements are delaying product launches and fragmenting EU product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Appearance Chemicals Market |
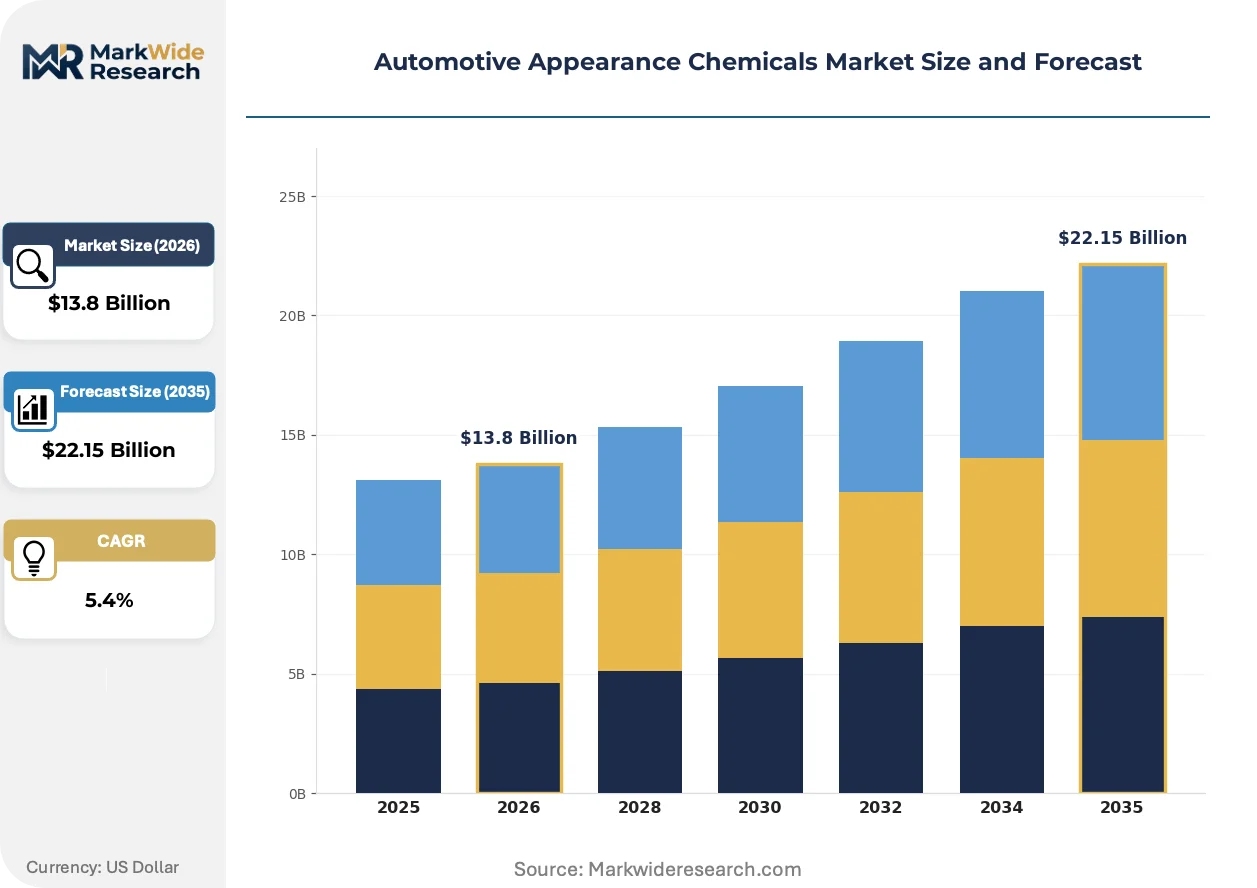
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $22.15 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polishes, Wax, Cleaners, Sealants Application: Exterior Detailing, Interior Care, Wheel Cleaners, Engine Cleaners End User: Dealerships, Aftermarket Providers, Vehicle Assemblers, DIY Consumers Sales Channel: Online Retail, Automotive Stores, Wholesale Distributors, Supermarkets |
| Companies Covered | BASF SE, 3M, PPG Industries, Inc., Nippon Paint Holdings Co., Ltd., The Dow Chemical Company, Axalta Coating Systems Ltd., The Sherwin-Williams Company, Turtle Wax, Inc., Akzo Nobel N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Appearance Chemicals Market Strategic Shifts & Innovations
Robotic application systems and AI-guided surface analysis are compressing labor dependency in professional detailing, while regulatory chemistry mandates and health-conscious consumer preferences reshape formulation priorities and channel economics.
Self-healing ceramic coatings with embedded microcapsule repair agents are automating scratch remediation in high-end detailing workflows. Premium service operators in Germany and California are deploying these systems to reduce rework rates and warranty claims. The technology is automating quality assurance processes previously requiring manual inspection and touch-up labor.
REACH nano-ingredient hazard classification protocols are forcing disclosure of particle-size distribution and toxicity data for ceramic and silica-based formulations. European compounders are restructuring supply chains to source pre-certified raw materials from ECHA-registered suppliers. Professional-grade sealant categories face the steepest compliance cost inflation as reformulation cycles compress.
Subscription-based chemical replenishment models are displacing traditional distributor stocking arrangements in US dealership service bays. Fixed monthly fees covering wax, polish, and sealant supplies eliminate inventory carrying costs and lock in supplier relationships. This pattern is most visible in Texas and Florida metro markets where multi-roof dealership groups concentrate procurement leverage.
Automotive Appearance Chemicals Market Segmentation
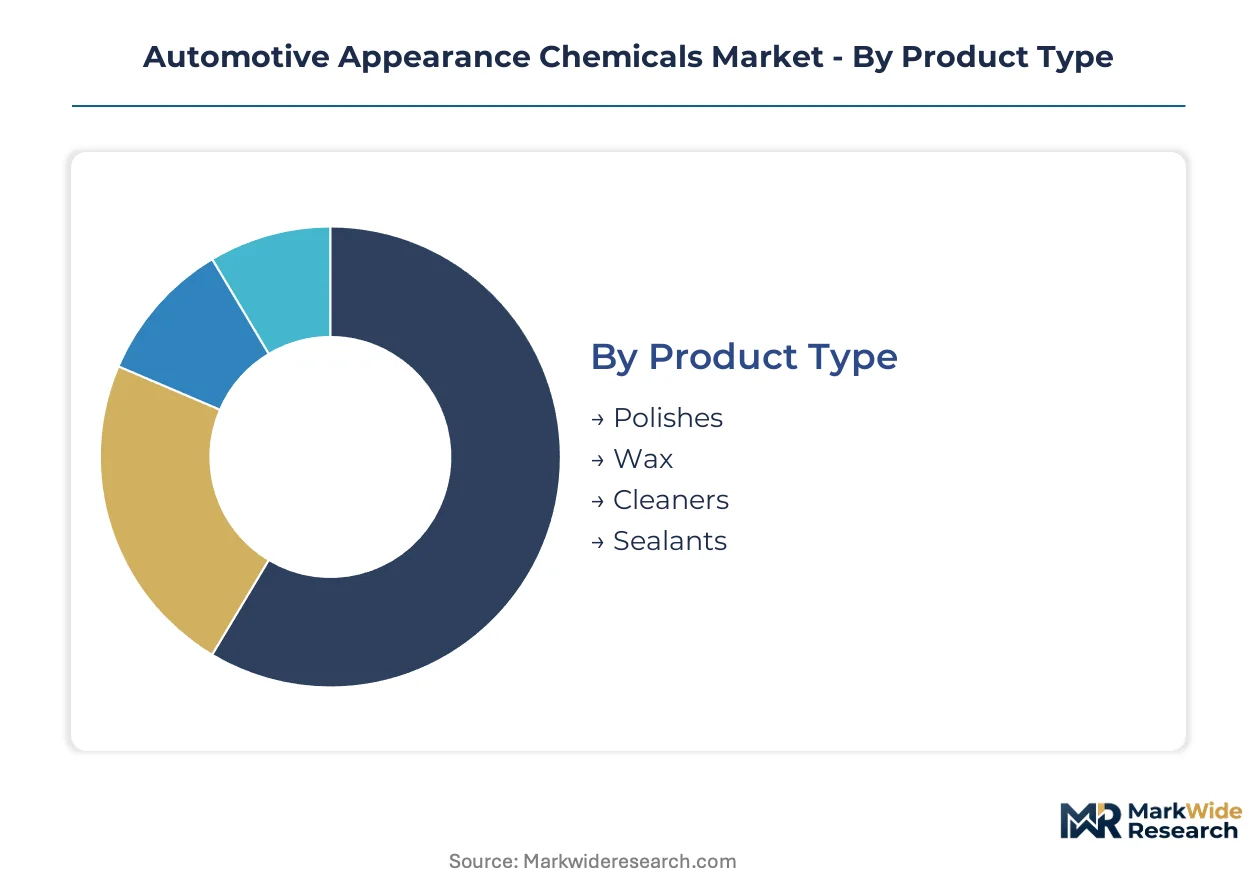
Automotive appearance chemicals fragment across four distinct dimensions, each commanding different margin profiles and channel economics. Product formulation dictates technical barriers to entry, while application type and end-user concentration determine pricing power and purchase frequency.
Product Type:
Volume concentrates in commodity formulations with thin margins, while premium chemistry commands outsized profitability through recurring application cycles.
- Polishes:Abrasive compounds with controlled particle-size distribution restore gloss by removing oxidized clear-coat layers. Demand clusters in professional detailing bays across California and Florida where sun exposure accelerates finish degradation.
- Wax:Natural carnauba and synthetic polymer formulations provide sacrificial barrier layers against environmental contaminants. Recreational vehicle owners in Texas and Arizona drive premium natural wax demand through enthusiast retail channels.
- Cleaners:pH-balanced surfactant systems dissolve road film without etching OEM finishes.
- Sealants:Nano-ceramic and fluoropolymer chemistries bond molecularly with clear-coat substrates for extended protection intervals.
Today's leader: Wax. Tomorrow's challenger: Sealants.
Application:
Exterior applications dominate throughput volume, yet interior formulations are climbing the fastest as cabin health positioning unlocks premium pricing tiers.
- Exterior Detailing:Comprehensive wash, clay, polish, and protect workflows consume the bulk of professional service bay chemical throughput. German dealership networks and Guangzhou assembly plant integrated service centers anchor demand concentration.
- Interior Care:Dashboard dressings, leather conditioners, and antimicrobial fabric treatments target cabin air quality concerns. California and New York metro consumers pay 40-60% premiums for health-claimed formulations in retail channels.
- Wheel Cleaners:Acid-free and pH-neutral formulations dissolve brake dust without corroding alloy finishes.
- Engine Cleaners:Degreasing surfactants and solvent blends remove petroleum residue from bay components.
Exterior detailing generates the revenue base. Interior care offers the steepest expansion trajectory.
End User:
Procurement authority splits between integrated OEM supply contracts and fragmented aftermarket service networks with divergent technical specifications.
- Dealerships:Fixed operations departments source appearance chemicals through approved supplier programs tied to OEM warranty compliance. Multi-roof groups in Texas and Florida leverage consolidated procurement to extract volume discounts.
- Aftermarket Providers:Independent detailers and collision repair shops purchase through wholesale distributors with flexible formulation specifications. Mumbai and Delhi corridor service networks represent whitespace for professional-grade product penetration.
- Vehicle Assemblers:Paint shop and pre-delivery inspection operations require OEM-certified chemistry with documented clear-coat compatibility.
- DIY Consumers:Enthusiast and maintenance-oriented vehicle owners buy through retail auto parts and supermarket channels.
Dealerships lock in supplier relationships. Aftermarket providers fragment purchasing decisions.
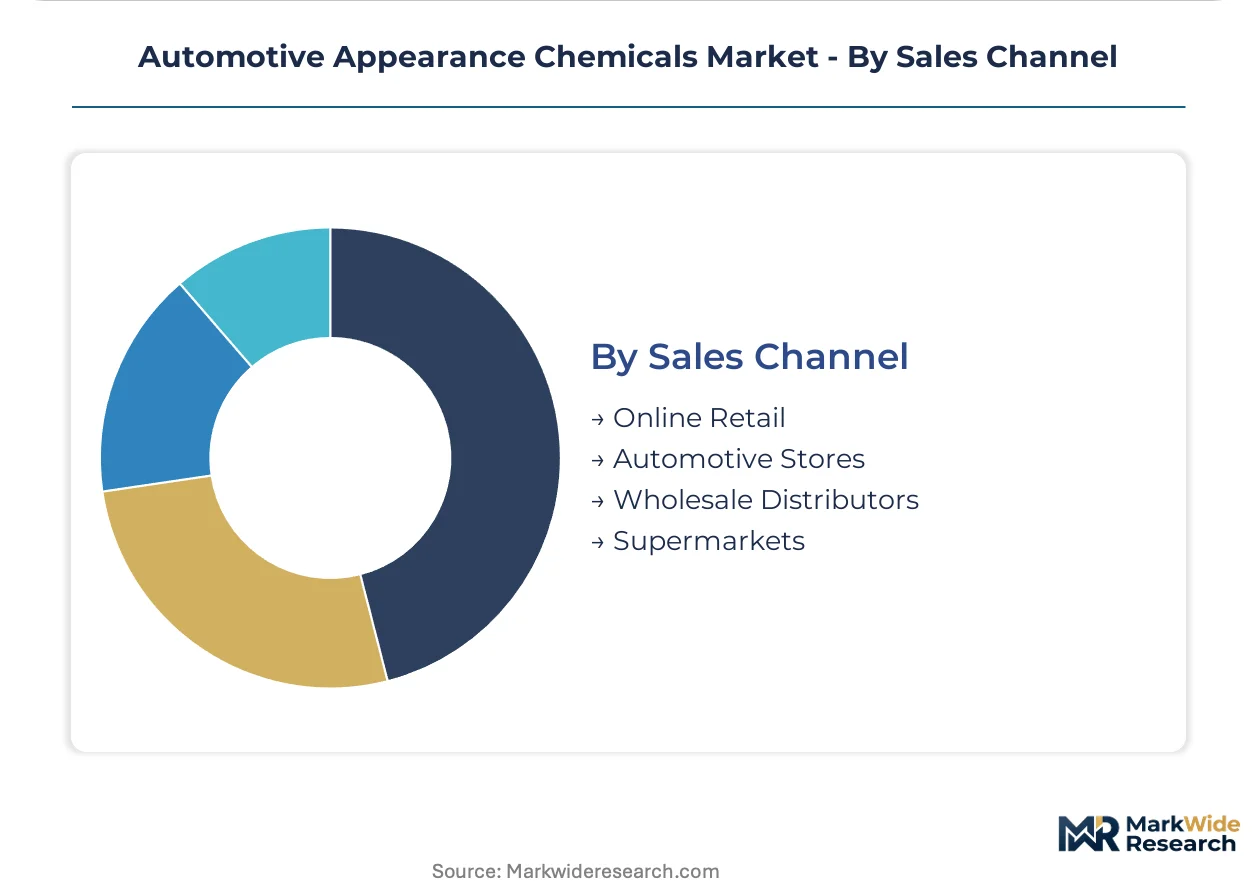
Sales Channel:
Physical distribution still dominates chemical replenishment, yet subscription models are displacing traditional stocking arrangements in concentrated metro markets.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators serve enthusiast segments with specialized ceramic coating kits. German and US consumers research nano-ceramic formulations through video demonstration content before purchase.
- Automotive Stores:Specialized retailers stock professional-grade chemistry alongside application equipment and training resources.
- Wholesale Distributors:Regional warehouses service dealership and independent detailer accounts with just-in-time replenishment.
- Supermarkets:Mass-market spray waxes and wash concentrates reach price-sensitive maintenance buyers through grocery retail placement.
Automotive stores defend the professional core. Online retail captures the enthusiast fringe.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation chemists cluster in Germany and Japan, anchoring technical innovation while production scale concentrates in China and the United States where automotive assembly density drives procurement volume.
Germany
Rhine-Ruhr specialty polymer producers supply sealant manufacturers with fluoropolymer and silicone precursors. REACH nano-ingredient disclosure protocols force ECHA-registered raw material sourcing. Stuttgart and Munich automotive clusters integrate appearance chemical supply through captive OEM service contracts.
United States
Texas and Florida multi-roof dealership groups drive subscription-based chemical replenishment adoption. EPA VOC restrictions on solvent content accelerate low-emission formulation R&D in California and Texas metro markets. Detroit assembly plant pre-delivery inspection operations anchor OEM-certified chemistry procurement.
China
Shanghai and Guangzhou manufacturing corridors generate concentrated demand through integrated supply contracts with vehicle assemblers. MEE emissions controls on coating chemical production facilities raise compliance costs for local compounders. Pearl River Delta detailing service networks expand professional-grade product penetration.
Japan
Aging technical workforces in Osaka and Nagoya concentrate pH-balanced surfactant expertise among legacy compounders. METI standards guide clear-coat compatibility testing protocols. Kanto region professional detailing bays adopt ceramic sealant packages for extended protection intervals.
India
Mumbai and Delhi corridor aftermarket providers represent whitespace for service-network partnerships. BIS quality standards shape import compliance for sealant formulations. Underdeveloped professional detailing infrastructure in Maharashtra and Gujarat offers localization opportunities for premium chemistry suppliers.
Automotive Appearance Chemicals Market Key Industry Players
Top-tier vendors anchor integrated polymer supply chains, while mid-tier compounders compete through formulation specialization and regional distribution density. The vendor base stratifies across captive R&D capacity holders, specialty chemical licensors, and mass-market retail suppliers. Strategic archetypes include backward-integrated polymer producers, fluoropolymer technology specialists, and supermarket channel dominators. Competitive moves concentrate on M&A for raw material security and strategic partnerships for service-network access.
Within the integrated polymer tier, BASF SE and The Dow Chemical Company exemplify backward-integrated suppliers controlling silicone and fluoropolymer precursor production. 3M occupies a position in proprietary technology licensing for professional detailing channels. Among mass-market retailers, Turtle Wax anchors supermarket and auto-parts retail placement through brand recognition and price-positioning discipline.
| Leading Market Players |
|---|
| BASF SE |
| 3M |
| PPG Industries, Inc. |
| Nippon Paint Holdings Co., Ltd. |
| The Dow Chemical Company |
| Axalta Coating Systems Ltd. |
| The Sherwin-Williams Company |
| Turtle Wax, Inc. |
| Akzo Nobel N.V. |
| Others |
Cost & Logistics Intelligence
Backward integration into silicone and fluoropolymer precursor production anchors both supply security and premium pricing power for sealant manufacturers serving OEM-certified channels. Captive polymer supply insulates integrated compounders from petrochemical feedstock volatility while locking in margin pools that non-integrated competitors cannot access.
Pricing Analysis
Bundled service packages versus unbundled product sales split pricing power between professional detailing channels and retail consumers. Three-tier pricing structure across premium ceramic sealants, standard polymer waxes, and economy spray formulations separates performance claims by durability interval and OEM certification status. Pricing pressure stems from REACH nano-ingredient compliance costs forcing reformulation investment in European product portfolios. DIY consumers in supermarket channels exhibit highest price sensitivity while dealership service bays prioritize warranty-compliant chemistry over unit cost.
Supply Chain Analysis
OEM certification requirements gate supplier access through documented clear-coat compatibility testing and ECHA-registered raw material sourcing. Specialty polymer production clusters in Germany, fluoropolymer precursor facilities in the United States, and surfactant manufacturing bases in Japan concentrate upstream supply. Formulation draws from silicone resins, nano-ceramic compounds, and bio-solvent carriers subject to petrochemical price volatility. Single-source dependency risks in the Rhine-Ruhr region threaten sealant manufacturer procurement security. Distribution runs through wholesale distributors serving dealership networks and auto-parts retailers reaching enthusiast consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive appearance chemicals constitute a late-cycle quality story as ceramic sealant durability claims extend application intervals and concentrate procurement with certified suppliers. Cabin air quality positioning for interior formulations accelerates premium tier demand in health-conscious consumer segments.
For Market Incumbents: Extend ceramic coating subscription models into multi-roof dealership groups to lock in replenishment revenue and raise switching costs for rival suppliers. Defend against bio-based solvent substitution mandates by securing EU Green Deal-compliant raw material contracts ahead of competitor qualification. Prioritize captive R&D capacity in pH-balanced surfactant systems where formulation chemist scarcity concentrates technical leverage.
For New Entrants and Emerging Players: Launch via service-network partnerships in Mumbai and Delhi corridor aftermarket channels where professional detailing infrastructure remains underdeveloped relative to vehicle ownership growth. Target antimicrobial interior formulations for California and New York metro retail placement where health-claimed products command 40-60% pricing premiums. Penetrate through direct-to-consumer ceramic coating kits distributed through video demonstration content platforms.
For Investors and Strategic Acquirers: Roll-up economics work for regional formulation compounders with established OEM certification dossiers because REACH compliance timelines and documentation costs create barriers to organic new entrant expansion. Acquisition targets should demonstrate documented clear-coat compatibility libraries and ECHA-registered supplier relationships. Watch ceramic sealant adoption rates in German and California professional detailing bays as inflection indicators for premium tier margin sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Precursors | Captive silicone and fluoropolymer supply secures margin pools against petrochemical volatility. |
| REACH Nano-Ingredient Pre-Certification | ECHA-registered raw material sourcing accelerates European product launch timelines. |
| Subscription-Based Replenishment Models | Fixed monthly fee structures eliminate dealership inventory carrying costs and lock supplier relationships. |
| Antimicrobial Interior Formulation Development | Cabin air quality claims unlock premium pricing tiers in California and New York retail channels. |
| India Service-Network Partnership Expansion | Mumbai and Delhi corridor detailing infrastructure gaps offer whitespace for professional-grade penetration. |
Research Approach
Multiple input streams — primary interviews with formulation chemists, OEM procurement managers, and aftermarket distributors; secondary validation through EPA VOC filing databases, ECHA registration records, and ACC industry reports; customs trade data for silicone and fluoropolymer precursor flows — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations spanned technical R&D directors at integrated polymer producers, dealership fixed operations managers in Texas and Florida, and independent detailing shop owners in Guangzhou and Stuttgart.
Data-stream reconciliation across product type, application, end-user, and regional production cluster dimensions generated volume and value estimates across the projection horizon. CAGRs were derived from segment-level growth rate blending informed by vehicle production forecasts, detailing service bay throughput trends, and ceramic sealant adoption curves in professional channels. Industry-specific inputs included OEM clear-coat compatibility certification timelines and REACH nano-ingredient disclosure compliance schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt petrochemical feedstock price spikes or accelerated EPA solvent restriction timelines. Model outputs reflect assumptions regarding ceramic coating durability claim validation and dealership consolidation rates in concentrated metro markets. A model refresh is warranted upon material change in REACH nano-hazard classification protocols or MEE emissions enforcement intensity on Chinese coating chemical production facilities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Europe Methanol Market
Chemicals
Calcium Hydroxide Market
Chemicals
South America Construction Chemicals Market
Chemicals
Potassium Hydrogen Fluoride Market
Chemicals
India Methanol Market
Chemicals
Tanning Agents Market
Chemicals
China Methanol Market
Chemicals
Fine Chemicals Market
Chemicals
Electronic Grade Hydrofluoric Acid Market
Chemicals
Sodium Fluorosilicate Market
Chemicals
Diphenyl Sulfone Market
Chemicals
Global Benzalkonium Chloride Market
Chemicals
Hydrogen Chloride Market
Chemicals
Global Aldehyde Market
Chemicals
Medical Grade Zinc Sulfate Market
Chemicals
Global Oxo Alcohols Market