
 Isooctyl Chloride Market | 2026-2036
Isooctyl Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Isooctyl Chloride Market Analytics
Buyer concentration among specialty coatings formulators is rebalancing as regional mid-tier producers fragment procurement across multiple chlorinated intermediate suppliers. BASF SE leverages integrated C4 chemistry streams to sustain captive isooctyl chloride output for internal plasticizer and solvent derivatives. Dow Chemical Company anchors North American supply through Gulf Coast chlor-alkali infrastructure, while INEOS competes on scale across European chlorinated solvent networks.
Isooctyl chloride denotes a branched-chain alkyl chloride synthesized via hydrochlorination of isooctene or chlorination of corresponding alcohol precursors, typically exhibiting boiling points between 170-190°C and serving as a reactive intermediate or non-polar solvent in specialty chemical manufacturing. The intermediate segment dominates volume flows as chemical producers convert isooctyl chloride into downstream plasticizer alcohols and surfactant feedstocks, while the solvent category captures premium pricing in high-purity coating and electronics cleaning applications. The adhesives application channel is expanding fastest as formulators substitute isooctyl chloride for restricted aromatic solvents under tightening VOC regulations.
EPA oversight under the Toxic Substances Control Act and REACH registration requirements in Europe constrain market access for unregistered importers and mandate comprehensive toxicological dossiers for commercial volumes. China's MEE enforces emission caps on chlorinated solvent production that favor integrated producers with waste-gas recovery systems. Stakeholders must monitor regulatory divergence between jurisdictions to align product specifications and avoid supply disruptions from non-compliant batch rejections.
Market Dynamics
Specialty coatings formulators are fragmenting procurement across multiple chlorinated intermediate suppliers, breaking historical single-source relationships as REACH compliance and EPA purity mandates force qualification protocol overhauls.
Growth Catalysts
- Adhesives substitution wave:Formulators are replacing restricted aromatic solvents with isooctyl chloride under tightening VOC regulations, expanding addressable demand in sealant and tape manufacturing.
- China captive production scaling:Domestic chemical producers are building backward-integrated isooctyl chloride units to feed downstream plasticizer and surfactant synthesis, reducing import dependency.
- Electronics cleaning purity premiums:Semiconductor and display manufacturers are qualifying high-grade isooctyl chloride for precision solvent applications, creating pricing tier separation from industrial grades.
Market Restraints
- Feedstock cost volatility:Isooctene and C4 olefin pricing swings directly compress chlorination economics, squeezing merchant producer margins during ethylene cycle downturns.
- European supply concentration:INEOS and integrated German chlor-alkali networks control bulk European chlorinated solvent infrastructure, limiting new entrant access to cost-competitive chlorine supply.
- Alcohol-based ester substitution:Bio-based plasticizer alcohols and non-chlorinated surfactant intermediates are capturing share in flexible PVC and personal care applications.
Strategic Opportunities
- India specialty chemicals buildout:PLI scheme incentives and BIS standard harmonization are attracting chlorinated intermediate investments for domestic coatings and adhesive supply chains.
- MEA solvent recovery services:Waste-gas recovery system deployment creates aftermarket revenue streams as Saudi and UAE environmental enforcement tightens on chlorinated solvent emissions.
- Waterborne coating convergence:Hybrid solvent systems combining isooctyl chloride with emerging waterborne resin technologies are opening formulation flexibility in automotive OEM coatings.
Industry Challenges
- Process safety engineering scarcity:Chlorination reactor design and HCl handling expertise concentrates among legacy Gulf Coast and Rhine-Ruhr operators, constraining brownfield expansion timelines.
- REACH dossier maintenance burden:ECHA substance evaluation updates and extended one-generation reproductive toxicity studies demand sustained toxicological investment for continued EU market access.
- Multi-jurisdiction specification drift:Diverging EPA, REACH, and China MEE purity thresholds force producers to maintain parallel product grades, complicating inventory and batch release protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isooctyl Chloride Market |
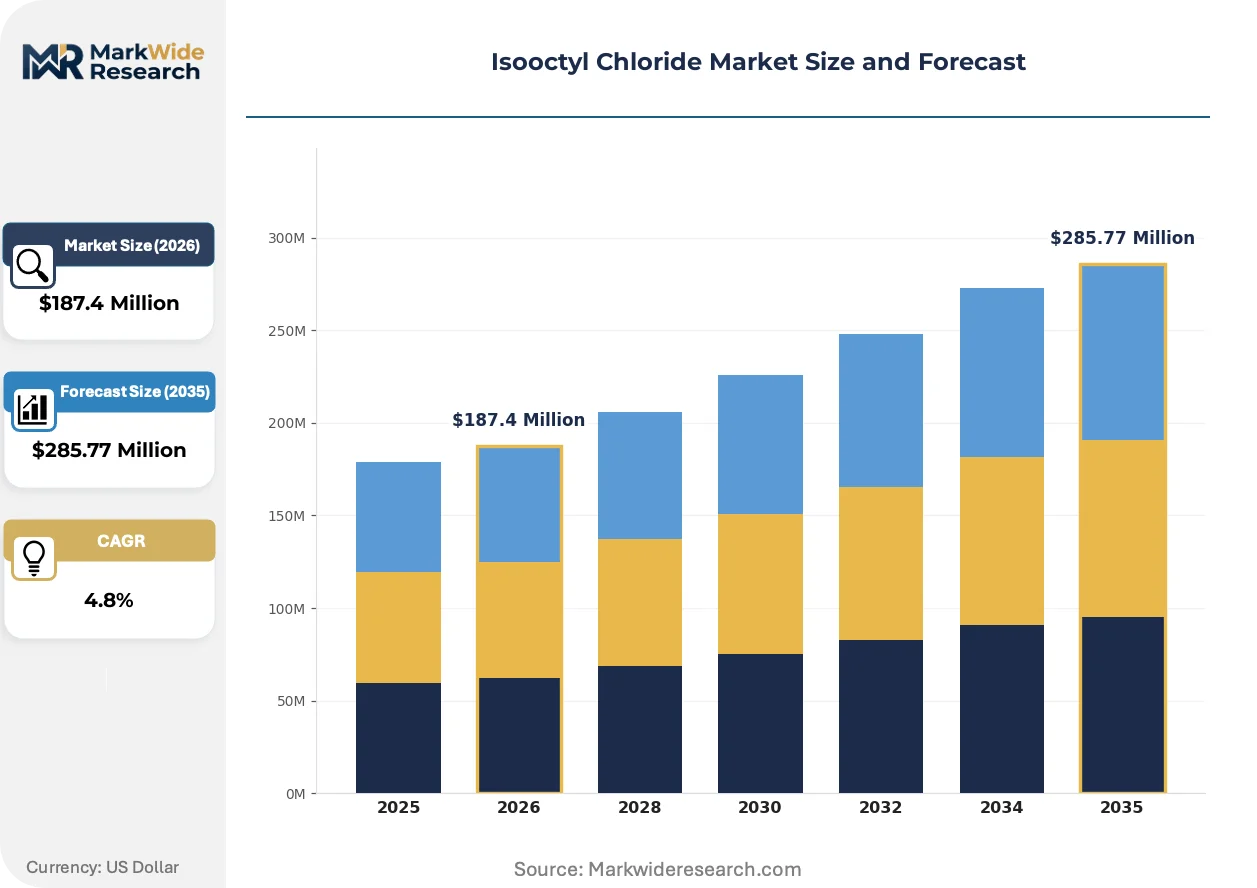
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent, Surfactant, Intermediate, Plasticizer Application: Coating, Adhesives, Sealants, Lubricants End User: Chemical Industry, Automotive, Construction, Pharmaceuticals Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | BASF SE, Dow Chemical Company, DuPont, CABB Chemicals, Eastman Chemical Company, INEOS, LG Chem Ltd, Merck, OXEA GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isooctyl Chloride Market Evolving Landscape
Reactive distillation and continuous chlorination process architectures are compressing unit capital intensity while tightening product specifications, enabling mid-scale producers to challenge integrated petrochemical incumbents on specialty grade delivery.
Membrane-based HCl recovery systems are modularizing chlor-alkali integration for merchant isooctyl chloride producers. Mid-tier European and Chinese operators are adopting skid-mounted recovery units to bypass captive chlorine infrastructure requirements. This technology is modularizing competitive entry economics, allowing regional specialists to achieve emission compliance without billion-dollar integrated site investments.
REACH authorization list expansion under ECHA sunset date pressure is accelerating substitution documentation requirements for chlorinated intermediates. Coatings formulators in Germany and Benelux are pre-qualifying alternative supply chains ahead of 2026-2028 review windows. The adhesives segment is most exposed, with major tape manufacturers already diversifying solvent portfolios to hedge authorization denial risks.
Direct supplier relationships are displacing distributor intermediation in North American specialty coatings procurement. Large formulators in Ohio and Texas are contracting chlorinated solvent volumes through long-term offtake agreements indexed to ethylene feedstock benchmarks. This pattern is most visible in automotive refinish and industrial maintenance coatings, where procurement teams prioritize supply security over transactional flexibility.
Isooctyl Chloride Market Segmentation
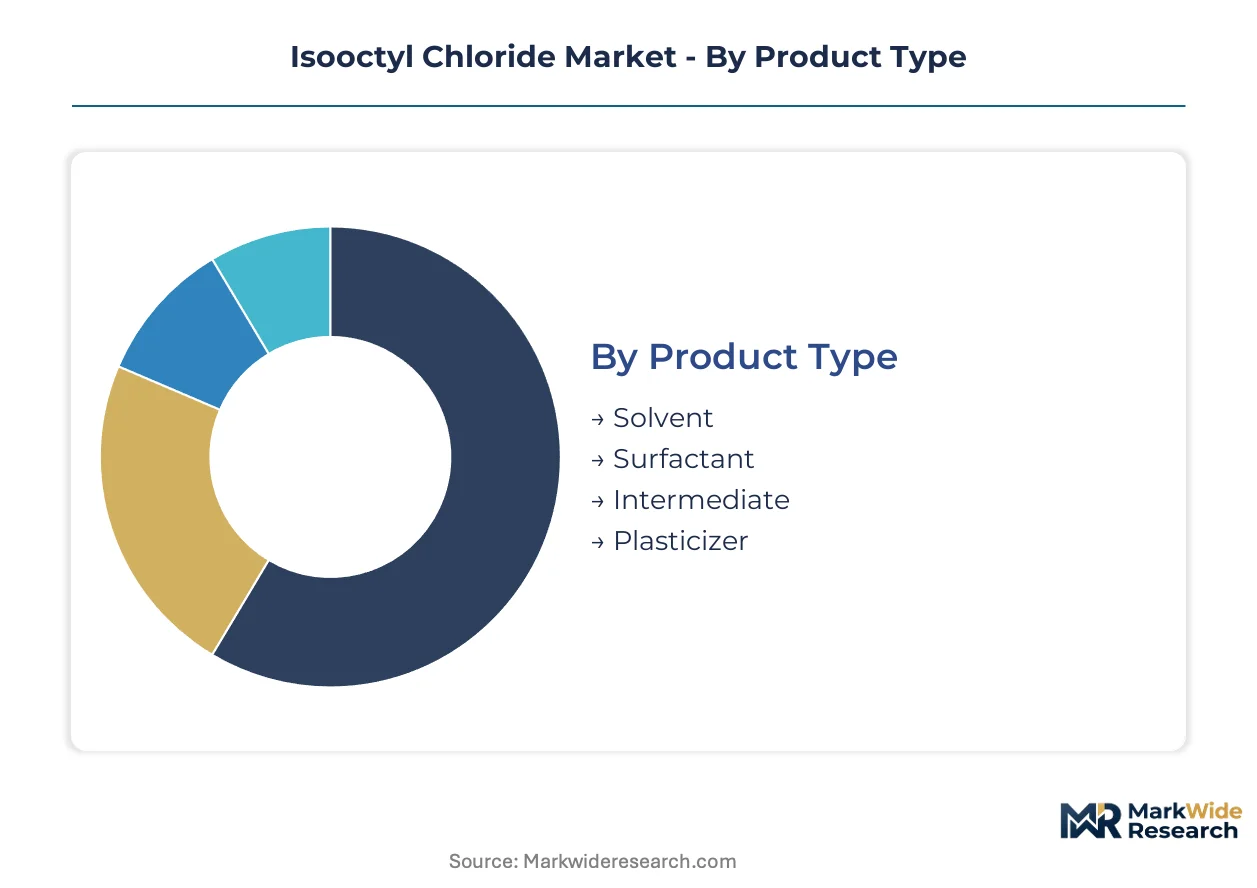
Segmentation in isooctyl chloride reveals divergent margin profiles across product grades and end-use channels. Buyers prioritize purity thresholds, regulatory certification, and supply security over price alone, fragmenting procurement strategies across application-specific tiers.
Product Type:
Buyers differentiate by functional specification and downstream conversion economics, with premium grades commanding qualification-based premiums.
- Intermediate:Branched-chain alkyl chloride feedstock converted to plasticizer alcohols and surfactant precursors through hydrolysis or amination routes. Volume concentrates in China where captive chlorination units serve domestic plasticizer synthesis, driven by import substitution mandates under MEE emission caps.
- Solvent:High-purity grades for electronics cleaning and specialty coatings applications requiring sub-ppm moisture and acid specifications. Demand clusters in German and Japanese semiconductor fabrication facilities, constrained by REACH authorization timelines and ECHA sunset date pressures.
- Surfactant:Chlorinated precursor for quaternary ammonium and betaine derivatives in personal care and industrial cleaning.
- Plasticizer:Direct precursor to isooctyl phthalate and adipate esters for flexible PVC compounding.
Volume sits with Intermediate; growth tilts toward Solvent.
Application:
End-use margins vary by regulatory exposure and substitution vulnerability, with VOC-driven reformulation reshaping demand trajectories.
- Coating:Solvent-borne automotive refinish and industrial maintenance formulations requiring controlled evaporation rates and resin compatibility. Procurement in Ohio and Texas shifts toward direct supplier contracts indexed to ethylene benchmarks, driven by supply security priorities among large formulators.
- Adhesives:Sealant and tape manufacturing substituting isooctyl chloride for restricted aromatics under tightening EPA and state-level VOC rules. German and Benelux tape manufacturers pre-qualify alternative supply chains ahead of REACH authorization reviews, expanding addressable demand fastest.
- Sealants:Construction-grade formulations for joint filling and weatherproofing applications.
- Lubricants:Additive intermediate and synthetic base oil modifier for high-temperature stability.
Coating holds volume concentration; adhesives gain share fastest on substitution momentum.
End User:
Customer scale and integration depth determine pricing power, with merchant buyers facing tighter qualification burdens than captive producers.
- Chemical Industry:Integrated plasticizer and surfactant manufacturers consuming bulk intermediate grades. BASF SE and Dow Chemical Company anchor demand through captive C4 chemistry streams, while Chinese domestic producers scale backward-integrated chlorination to reduce import dependency.
- Automotive:OEM coatings and underbody sealant formulators requiring consistent batch certification. Procurement teams in Detroit and Stuttgart prioritize long-term offtake agreements over spot purchasing, reflecting just-in-time manufacturing constraints.
- Construction:Adhesive and sealant compounders serving infrastructure and residential building markets.
- Pharmaceuticals:Specialty solvent applications in API synthesis and extraction processes.
Chemical Industry dominates volume flows; automotive offers premium pricing stability.
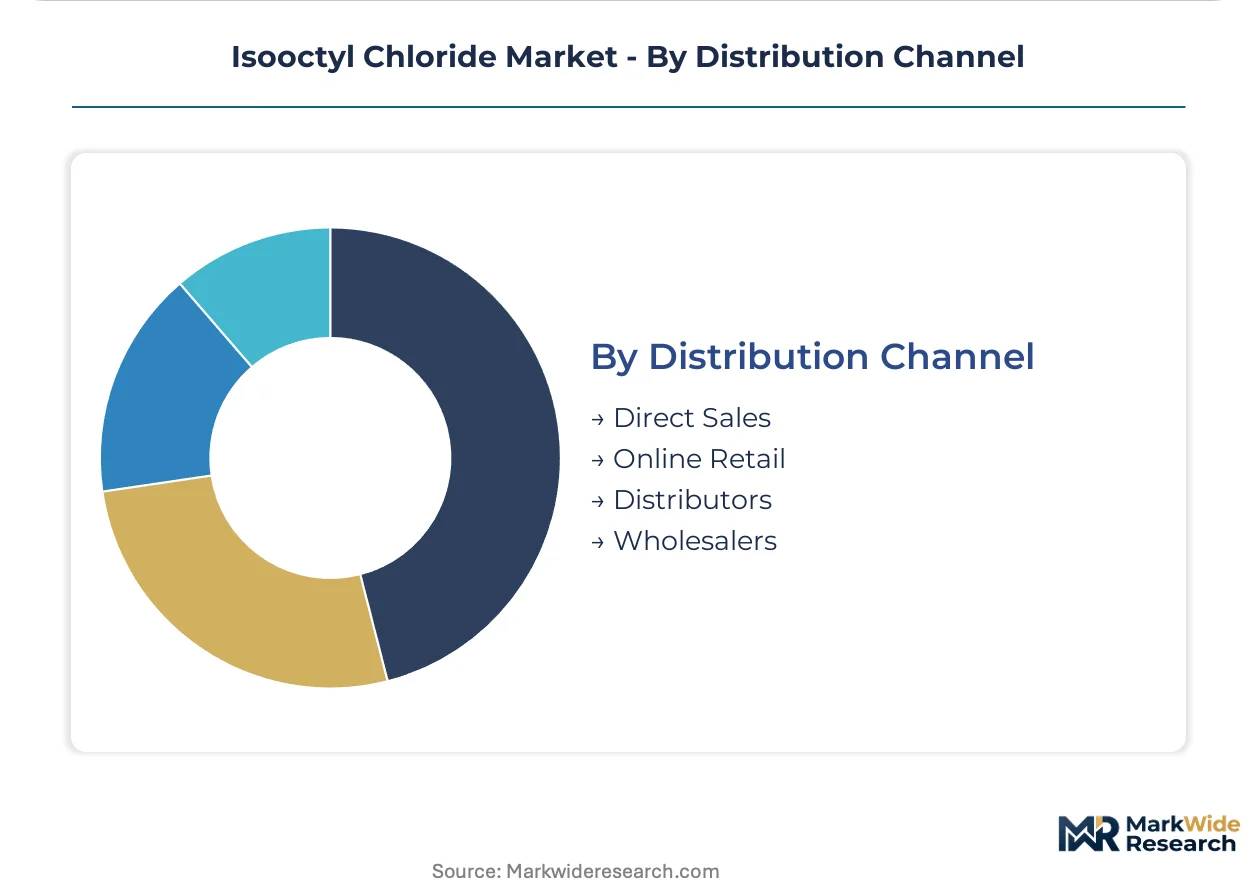
Distribution Channel:
Channel selection reflects buyer scale and regulatory documentation requirements, with large accounts bypassing intermediaries.
- Direct Sales:Long-term contracts between chlorinated solvent producers and specialty coatings formulators. Large Ohio and Texas-based manufacturers displace distributor intermediation through ethylene-indexed offtake agreements, securing supply priority during feedstock cycle tightness.
- Distributors:Regional chemical distributors serving mid-tier formulators with smaller volume requirements and broader product baskets.
- Online Retail:E-procurement platforms for laboratory and pilot-scale quantities.
- Wholesalers:Bulk handlers serving construction and industrial maintenance channels with lower specification grades.
Direct sales capture volume concentration; distributor relationships retain relevance for fragmented mid-tier accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
C4 olefin availability along the US Gulf Coast and Rhine-Ruhr corridor anchors chlorination capacity for isooctyl chloride production. Merchant supply concentrates near integrated chlor-alkali infrastructure, while captive consumption scales fastest in China's Yangtze River Delta chemical clusters.
United States
Specialty coatings formulators in Ohio and Texas drive solvent-grade procurement through direct supplier contracts. EPA oversight under the Toxic Substances Control Act tightens purity documentation requirements for commercial volumes. Gulf Coast chlor-alkali networks near Houston and Lake Charles sustain backward-integrated chlorination economics for plasticizer intermediate flows.
Germany
Semiconductor and display manufacturers in Dresden and Munich qualify high-purity solvent grades for precision electronics cleaning. REACH registration mandates and ECHA substance evaluation updates demand sustained toxicological dossier maintenance. The Rhine-Ruhr chemical corridor around Leverkusen and Ludwigshafen hosts integrated C4 chemistry streams serving captive intermediate demand.
China
Domestic chemical producers in Jiangsu and Zhejiang provinces scale captive chlorination units to feed downstream plasticizer synthesis. MEE emission caps on chlorinated solvent production favor integrated producers with waste-gas recovery systems. The Yangtze River Delta around Shanghai and Ningbo concentrates capacity buildouts targeting import substitution.
India
PLI scheme incentives attract chlorinated intermediate investments for domestic coatings and adhesive supply chains. BIS standard harmonization accelerates qualification protocols for specialty chemical manufacturing. Gujarat and Maharashtra industrial corridors near Vadodara and Mumbai anchor merchant production scaling for regional formulator procurement.
Japan
Electronics cleaning applications in Osaka and Nagoya sustain premium pricing for sub-ppm moisture specification grades. METI industrial chemical regulations align with REACH-equivalent substance safety requirements. The Kansai manufacturing belt maintains long-term offtake relationships with German and US solvent suppliers.
Isooctyl Chloride Market Competitive Landscape
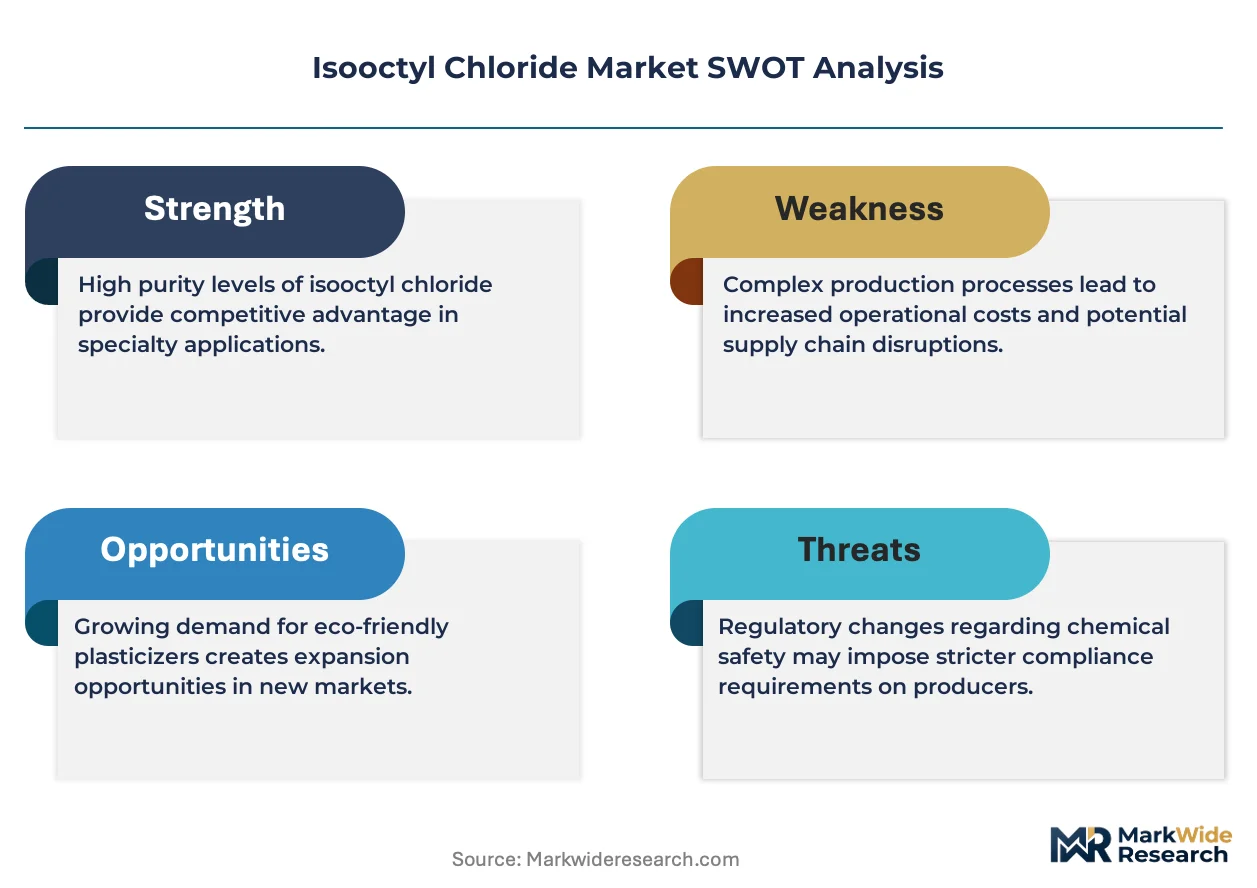
Established producers occupy the standard tier; emerging entrants pursue modular HCl recovery and regional specialty grade positioning. The vendor base stratifies across integrated petrochemical incumbents with captive C4 streams, merchant chlorinators dependent on spot olefin supply, and mid-tier regional specialists leveraging continuous process architectures. Three archetypes dominate: Gulf Coast and Rhine-Ruhr integrated operators, Chinese domestic captives with MEE-compliant recovery systems, and European merchant producers competing on REACH-certified specialty grades. Capacity expansion and strategic partnerships represent the dominant competitive vectors, with brownfield chlorination timelines constrained by process safety engineering scarcity.
Among integrated chemical conglomerates, BASF SE and Dow Chemical Company exemplify the captive-production archetype through C4 chemistry integration and Gulf Coast chlor-alkali anchoring respectively. INEOS occupies a position within European chlorinated solvent networks competing on scale across merchant intermediate supply. These three entities represent the structural concentration of supply-side capability, with their positioning reflecting the feedstock-access and regulatory-compliance barriers that constrain new entrant economics.
| Leading Market Players |
|---|
| BASF SE |
| Dow Chemical Company |
| DuPont |
| CABB Chemicals |
| Eastman Chemical Company |
| INEOS |
| LG Chem Ltd |
| Merck |
| OXEA GmbH |
| Others |
Value Network & Pricing Analysis
Continuous chlorination process architectures are compressing capital intensity for mid-scale producers while simultaneously fragmenting supply concentration away from integrated petrochemical incumbents toward regional specialists with modular HCl recovery systems. This technology transition simultaneously lowers entry barriers and intensifies price competition across intermediate grades, while REACH certification burdens sustain premium pricing for solvent-tier qualifications in European electronics cleaning applications.
Pricing Analysis
Service bundling separates REACH-certified solvent grades with full toxicological dossier maintenance from unbundled intermediate grades sold on spot olefin indices. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, purity specification, and volume commitment scale. Cost compression in standard intermediate grades is intensifying because Chinese captive producers are flooding regional supply with MEE-compliant output. Merchant buyers in coatings applications exhibit highest price sensitivity; semiconductor fabricators in Dresden and Osaka demonstrate lowest sensitivity due to qualification lock-in effects.
Supply Chain Analysis
Direct-to-specialty-formulator channels handle hyperscale buyer demand in Ohio and Texas, while regional distributors serve fragmented mid-tier adhesive compounders. Supply concentrates in the United States, Germany, and China, with C4 olefin availability anchoring chlorination economics along the Gulf Coast and Rhine-Ruhr corridor. Production draws from isooctene feedstocks, chlorine supply from integrated chlor-alkali networks, and hydrochlorination catalyst systems. Single-source vulnerability runs through European chlorinated solvent infrastructure controlled by INEOS and integrated German operators. Distribution runs through long-term offtake agreements indexed to ethylene benchmarks for large accounts, spot market transactions for merchant buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The isooctyl chloride market sits in a technology-transition phase as membrane-based HCl recovery modularizes competitive entry and displaces legacy billion-dollar integrated site economics. Continuous process architectures are replacing batch chlorination, enabling mid-scale regional specialists to challenge incumbent cost structures.
For Market Incumbents: Lock in captive C4 chemistry streams through backward integration into isooctene supply or long-term feedstock offtakes with Gulf Coast and Rhine-Ruhr olefin producers. Invest in REACH dossier maintenance and extended one-generation reproductive toxicity studies to defend authorization status against ECHA sunset date pressure. Prioritize waste-gas recovery system deployment to maintain MEE compliance access in China and pre-empt tightening EPA emission standards.
For New Entrants and Emerging Players: Capture specialty solvent grade positioning in Indian coatings and adhesive supply chains where PLI scheme incentives and BIS harmonization are accelerating qualification protocols. Target electronics cleaning applications in Japanese semiconductor fabrication facilities demanding sub-ppm moisture specifications with limited qualified supplier bases. Pursue direct supplier relationships with large Ohio and Texas formulators through ethylene-indexed long-term contracts.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated chemical conglomerates seeking captive intermediate supply security. Five-to-ten year viability hinges on sustained REACH authorization and MEE emission cap compliance rather than commodity cost position. Monitor ECHA substance evaluation updates and REACH authorization list expansion as inflection indicators for substitution risk in adhesives and coatings segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into C4 Olefin Supply | BASF and Dow anchor cost position through captive isooctene streams. |
| Membrane-Based HCl Recovery Deployment | Mid-tier European and Chinese operators bypass integrated chlorine infrastructure requirements. |
| REACH Dossier Maintenance Investment | Sustained toxicological spending secures EU market access against ECHA sunset dates. |
| Direct Supplier Relationship Formation | Large Ohio and Texas formulators displace distributor intermediation for supply security. |
| Specialty Grade Certification in Electronics Cleaning | Sub-ppm moisture specifications command pricing premiums in Dresden and Osaka fabs. |
Research Methodology
Independent corroboration across plant managers at chlorination facilities, procurement leads at downstream coatings and adhesive formulators, distribution channel partners in European solvent networks, and technical R&D directors at specialty chemical manufacturers underwrites the qualitative findings. Secondary validation draws from customs and trade data, Cefic chlorinated solvent reports, SEC 10-K filings of integrated chemical producers, and EPA TSCA regulatory filings. Bottom-up capacity and demand modeling triangulates against top-down macroeconomic and olefin cycle indicators.
Rate-of-change decomposition separates volume growth into end-use substitution effects, regulatory-driven reformulation, and captive production scaling across the analysis window. Segmentation dimensions include product grade tier, end-use industry channel, geographic production hub, and certification status. CAGRs derive from weighted average of demand elasticity estimates and supply expansion timelines. Industry-specific forecast inputs incorporate ethylene cycle positioning and REACH authorization timeline assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA regulatory decisions, MEE emission cap enforcement intensity, and bio-based plasticizer alcohol substitution rates. Forecasts reflect assumptions about sustained semiconductor fabrication demand, continued VOC regulation tightening, and stable chlor-alkali infrastructure economics. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Global Oxidized Polyethylene Wax Market
Oleochemicals
Ethylhexyl Pelargonate Market
Oleochemicals
Carbolic Oil Market
Oleochemicals
Sodium Stearoyl Lactylate Market
Oleochemicals
Partially Hydrogenated Oil Market
Oleochemicals
Isopropyl Esters Market
Oleochemicals
Allyl Caproate Market
Oleochemicals
Glycerol Esters of Wood Rosins Market
Oleochemicals
Europe Wax Market
Oleochemicals
Medium-Chain Triglycerides (MCT) Powder Market
Oleochemicals
Squalane Market
Oleochemicals
Asia-Pacific Algae Omega-3 Ingredient Market
Oleochemicals
Mixed Acetic and Tartaric Acid Esters of Mono and Diglycerides of Fatty Acids Market
Oleochemicals
Isostearic Acid Market
Oleochemicals
Higher Olefins Market
Oleochemicals
Asia-Pacific Wax Market