
 Global Welding Powder Market | 2026-2036
Global Welding Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Global Welding Powder Market Outlook
Market Context
Automotive lightweighting is decoupling from traditional steel-intensive joining methods as aluminum and titanium alloy demand surges across electric vehicle platforms. H.C. Starck leverages its refractory metal expertise to dominate high-performance aerospace powder grades. Shanghai Zhongzhou Special Alloy Materials anchors Chinese supply through integrated ferroalloy production. AMG Superalloys UK competes on nickel-based superalloy powders for turbine repair applications.
Technical Definition and Segmentation
Welding powder comprises atomized metallic particles with controlled particle size distribution, typically 45-150 microns, engineered to create metallurgically sound deposits during fusion-based joining processes. The material functions as consumable filler or surfacing medium across arc, laser, and plasma transfer systems. Ferrous powders occupy the largest volume share due to structural steel fabrication scale, while alloy grades command premium positioning in aerospace end-use. Gas Metal Arc technology leads technology adoption in automated production environments, though Gas Tungsten Arc powders sustain higher margin pools in precision manual applications.
Regulatory Environment
EPA emissions thresholds and OSHA hexavalent chromium exposure limits shape North American product formulation requirements, while REACH substance restrictions in Europe drive substitution away from certain alloying elements. China's GB standards and MEE environmental enforcement tighten domestic manufacturing compliance burdens. Stakeholders must monitor evolving alloy composition restrictions across multiple jurisdictions to anticipate reformulation costs and qualification timelines.
Market Dynamics
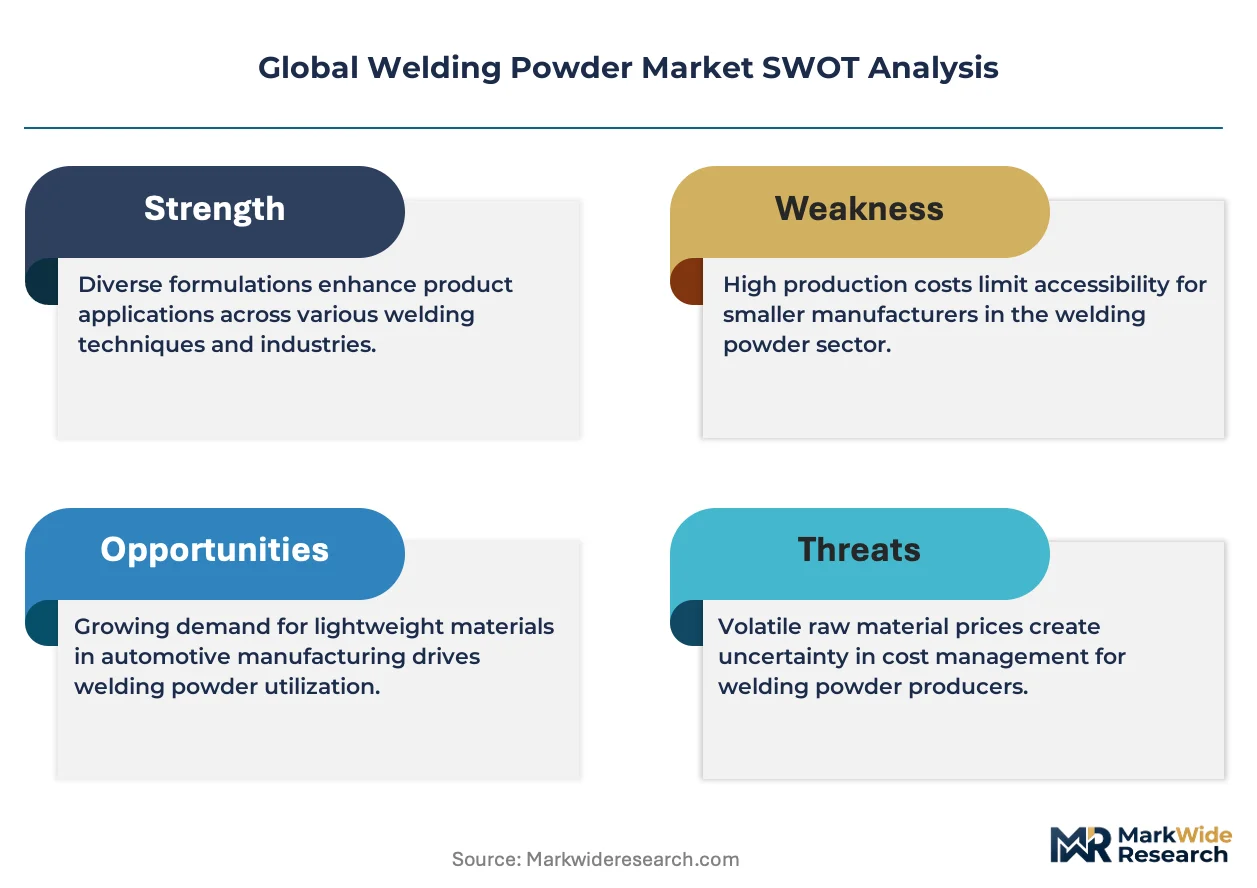
Automotive lightweighting programs are forcing a structural shift from conventional steel wire consumables toward aluminum and titanium alloy welding powders, compressing qualification timelines and reformulation cycles across the supply base.
Growth Catalysts
- Electric Vehicle Platform Expansion:Aluminum-intensive battery enclosures and body-in-white structures across EV architectures are consuming high-purity alloy powders at volumes that legacy steel filler metals cannot satisfy.
- REACH Substance Restrictions:European ECHA mandates on hexavalent chromium and nickel compound classifications are accelerating substitution toward cobalt-reduced and chromium-free powder formulations.
- Shipbuilding Cluster Concentration:China's state-directed maritime infrastructure buildouts in Jiangsu and Zhejiang provinces are anchoring regional demand for high-deposition-rate ferrous powders.
Market Restraints
- Sponge Titanium Price Volatility:Titanium alloy powder production remains hostage to Kroll process sponge pricing, with Ukrainian and Russian feedstock disruptions amplifying quarterly cost swings.
- Atomization Capacity Concentration:Premium inert gas atomization capacity clusters in Germany, Japan, and the United States, creating single-source vulnerabilities for aerospace-grade powder procurement.
- Plasma Transfer Arc Limitations:PTA surfacing systems face deposition rate ceilings that constrain productivity in heavy equipment repair applications relative to laser cladding alternatives.
Strategic Opportunities
- India Infrastructure Buildout:The country's National Infrastructure Pipeline and domestic manufacturing incentives under PLI schemes are creating virgin demand for structural steel fabrication consumables.
- Laser-Hybrid Arc Convergence:Shipyards in South Korea and Japan are piloting hybrid processes combining laser depth penetration with GMAW deposition efficiency, requiring tailored powder chemistries.
- EPA Greenhouse Gas Standards:Proposed tightening of industrial emissions thresholds is incentivizing low-fume, low-spatter powder formulations that reduce post-weld cleanup and ventilation energy.
Industry Challenges
- Welding Engineer Talent Scarcity:Qualified metallurgists capable of qualifying new alloy chemistries across multiple WPS parameters are retiring faster than apprenticeship programs replenish them.
- Multi-Jurisdiction Certification Burden:Aerospace powder suppliers must maintain parallel AS9100, NADCAP, and customer-specific approvals, with each recertification consuming 12-18 month cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Welding Powder Market |
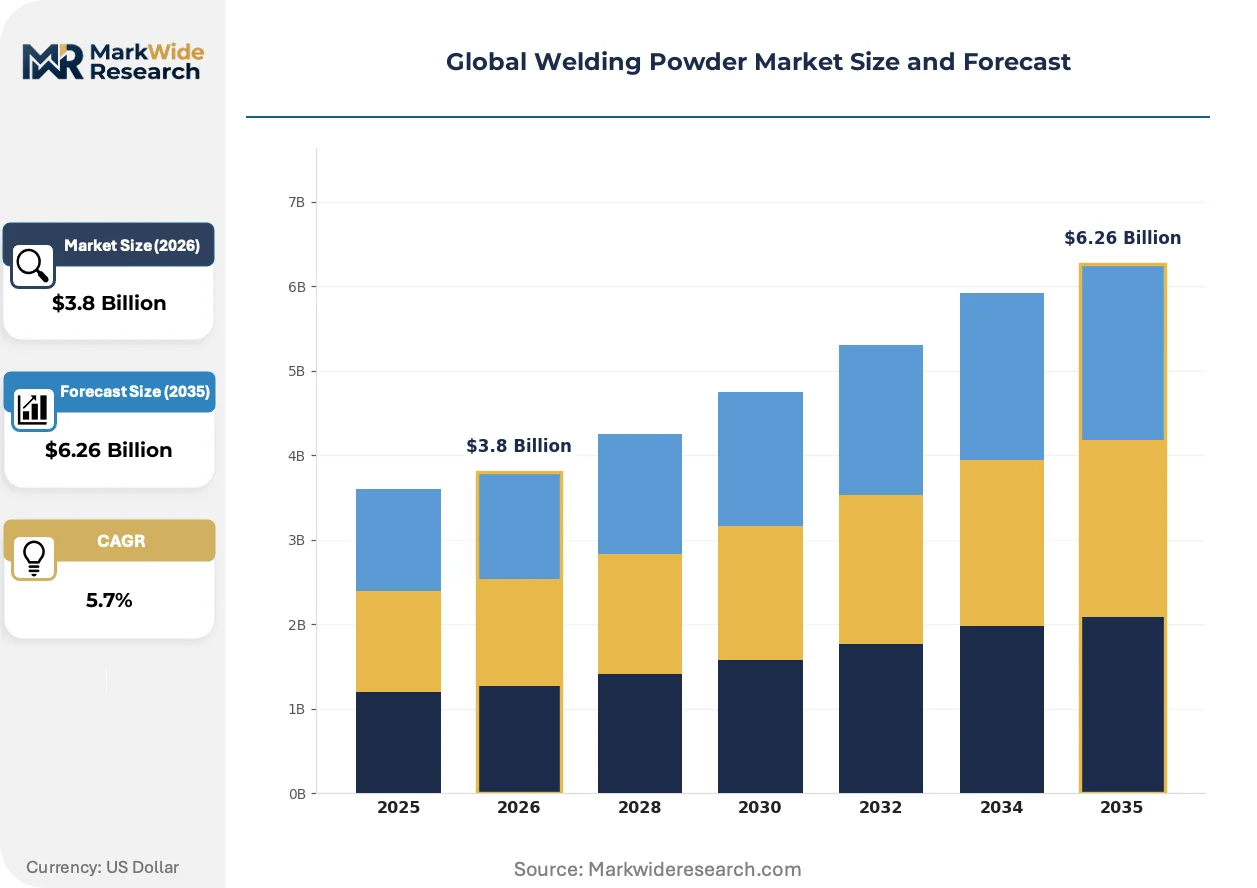
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ferrous, Non-Ferrous, Stainless Steel, Alloy Technology: Gas Metal Arc, Flux-Cored Arc, Gas Tungsten Arc, Submerged Arc End User: Aerospace, Construction, Automotive, Fabrication Form: Powder, Granules, Pellets, Slurry |
| Companies Covered | Harris, GENSA Group, NiGK Corporation, H.C. Starck, AMG Superalloys UK, Shanghai Zhongzhou Special Alloy Materials, Tongling Xinxin Welding Materials, Pometon Powder, Grecian Magnesite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Welding Powder Market Strategic Shifts
Digital traceability systems and closed-loop atomization controls are compressing the gap between powder production and deposition qualification, collapsing traditional feedback cycles from months to weeks.
Plasma rotating electrode atomization is decentralizing premium powder production away from centralized merchant suppliers. Tier-one aerospace contractors in France and the United Kingdom are installing captive PREP units to secure nickel superalloy supply chains. This technology is decentralizing procurement leverage from incumbent German and Japanese atomization houses toward end-user controlled vertical supply.
REACH Annex XIV authorization requirements are forcing systematic substitution of cobalt and nickel classifications in high-temperature alloy powders. ECHA's 2024-2025 sunset date evaluations are pressuring formulators to validate alternative hardening mechanisms. European turbine repair shops are most affected, stockpiling legacy chemistries while qualifying chromium-molybdenum replacements.
Consolidated procurement by Chinese state shipyards is compressing supplier margins and standardizing powder specifications across previously fragmented buyer pools. Yangzijiang Shipbuilding and China State Shipbuilding Corporation are mandating unified chemical certification protocols. This concentration is most visible in Jiangsu province, where local powder blenders are absorbing qualification costs to maintain yard-approved status.
Global Welding Powder Market Segmentation
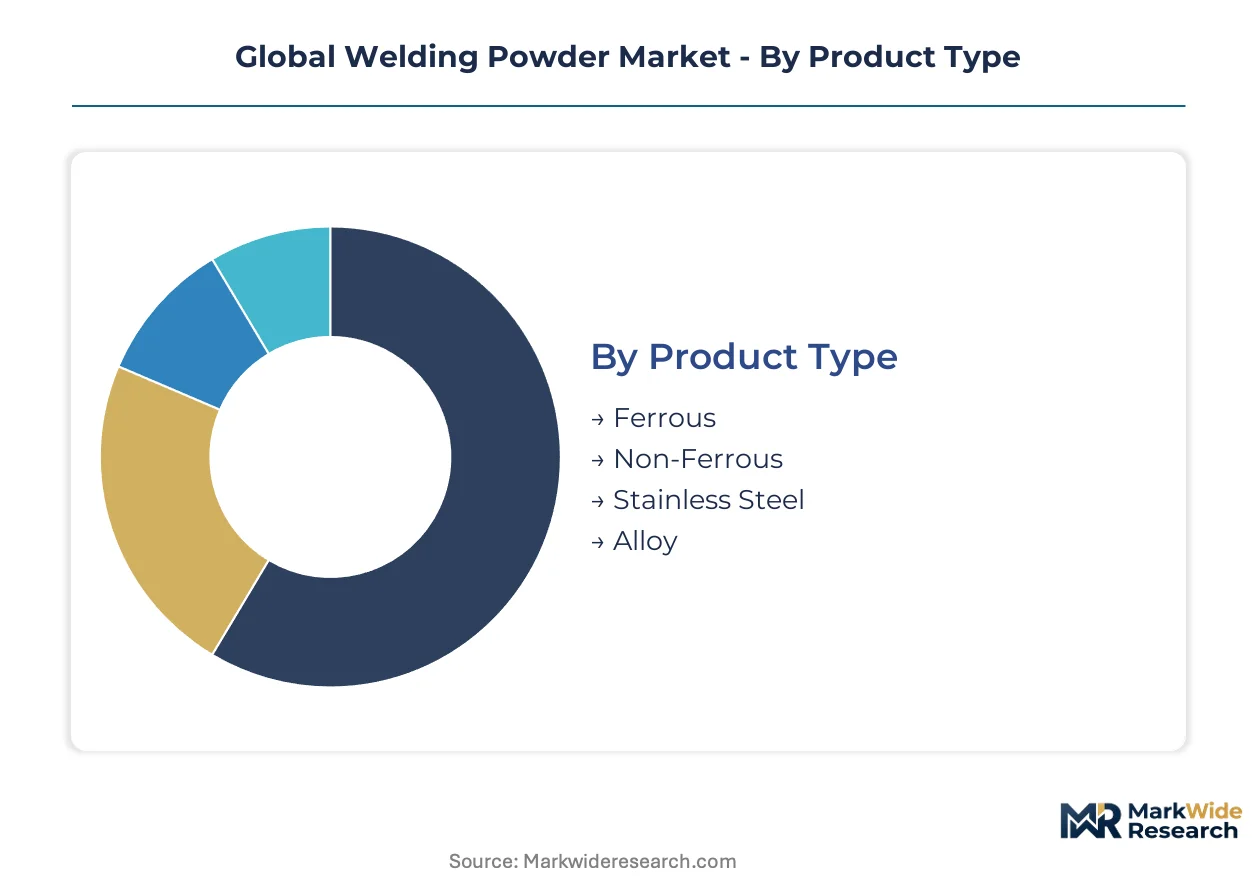
Welding powder segmentation reflects divergent buyer priorities across deposition rate requirements, metallurgical precision, and regulatory compliance burdens. Material chemistry and particle morphology dictate process compatibility and end-use qualification timelines.
Product Type:
Buyers differentiate primarily by base metal chemistry and the performance premiums commanded by specialized alloy formulations.
- Ferrous:Carbon and low-alloy steel powders dominate structural fabrication volumes, with particle size distributions optimized for high-deposition-rate submerged arc operations. Shipyards in China's Jiangsu province consume bulk ferrous grades for hull construction, though margin compression from state-directed procurement limits supplier profitability.
- Alloy:Nickel-based superalloy and cobalt-bearing formulations serve turbine repair and aerospace surfacing applications requiring creep resistance and thermal fatigue performance. PREP atomization capacity expansion in France and the United Kingdom is reshaping supply security for these premium grades.
- Non-Ferrous:Aluminum and titanium alloy powders address automotive lightweighting and corrosion-resistant chemical processing equipment.
- Stainless Steel:Austenitic and duplex grades satisfy food processing, pharmaceutical, and marine environment specifications.
Volume sits with Ferrous; growth tilts toward Alloy.
Technology:
Process selection determines deposition efficiency, heat input control, and the automation compatibility that separates mass fabrication from precision repair.
- Gas Metal Arc:Continuous wire-fed processes with external shielding gas dominate automated production environments, consuming aluminum and steel powders at rates exceeding manual alternatives. South Korean shipyards are piloting laser-hybrid GMAW configurations demanding tailored powder chemistries.
- Gas Tungsten Arc:Non-consumable tungsten electrode processes sustain premium positioning in manual precision applications, particularly aerospace component repair where heat-affected zone control is critical. Qualified welder scarcity constrains capacity expansion for this higher-margin segment.
- Flux-Cored Arc:Tubular wire constructions with internal flux enable all-position welding and deeper penetration in structural steel.
- Submerged Arc:Granular flux blankets protect the weld pool in flat-position heavy plate fabrication, anchoring demand for coarse ferrous powder grades.
Gas Metal Arc commands current throughput; Gas Tungsten Arc captures expanding value pools.
End User:
Industry verticals impose distinct certification regimes, deposition volume profiles, and metallurgical performance thresholds.
- Automotive:Electric vehicle platform architectures are displacing steel-intensive joining with aluminum battery enclosures and body-in-white structures. Tesla, BYD, and Volkswagen Group procurement teams are compressing powder qualification cycles from 18 months to under 12.
- Aerospace:Turbine blade repair and engine component surfacing demand AS9100-certified nickel superalloy powders with full chemical and mechanical traceability. NADCAP accreditation requirements extend supplier onboarding timelines.
- Construction:Infrastructure steel fabrication consumes standardized ferrous grades with minimal alloy premiums.
- Fabrication:General job shops source across multiple chemistries based on contract-specific welding procedure specifications.
Construction absorbs the largest tonnage; Automotive generates the steepest expansion trajectory.
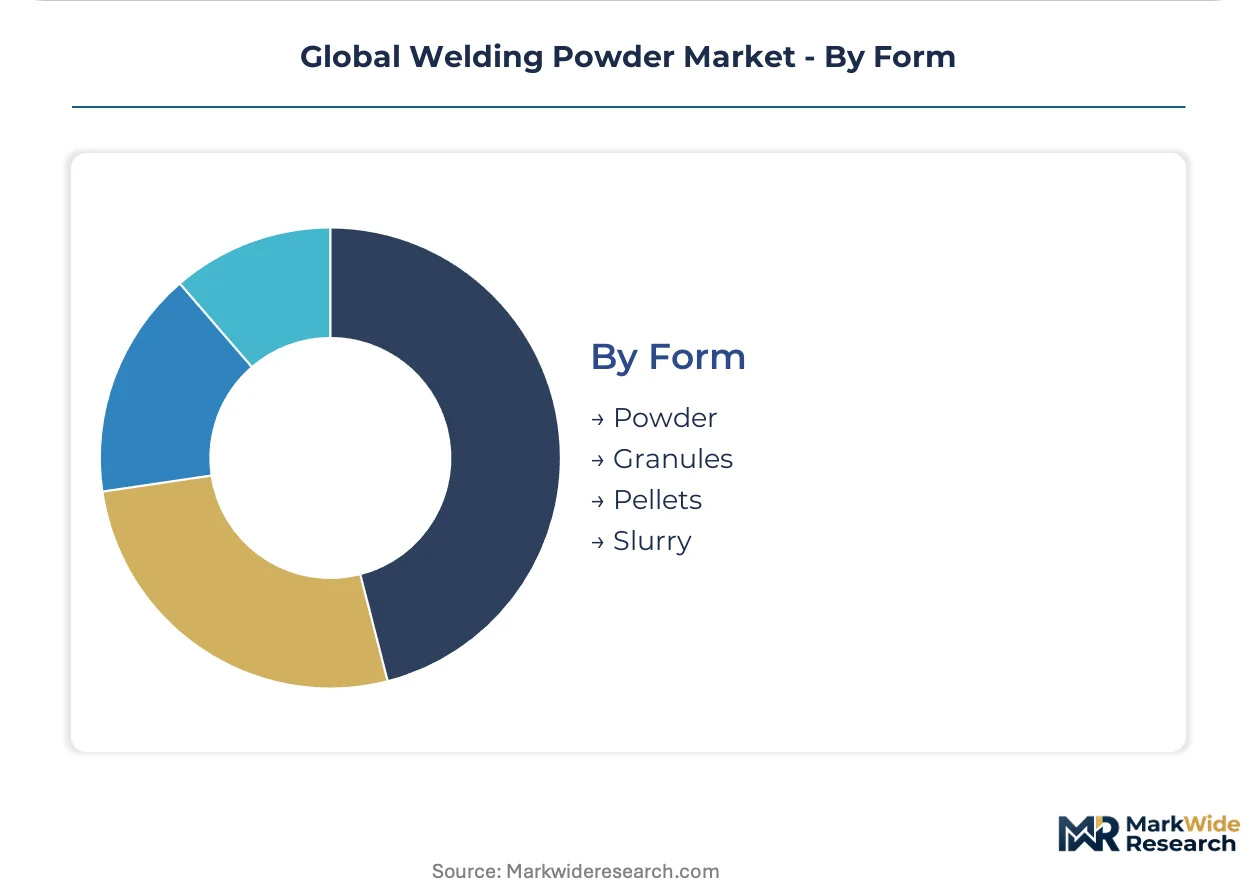
Form:
Physical presentation governs feeding system compatibility, atmospheric exposure risk, and deposition consistency.
- Powder:Fine atomized particles in the 45-150 micron range enable precise feed rate control in laser and plasma transfer systems. Inert gas atomization capacity concentration in Germany and Japan creates procurement vulnerabilities for aerospace-qualified material.
- Granules:Coarser agglomerated particles serve submerged arc flux blankets and bulk surfacing operations where deposition rate outweighs precision.
- Pellets:Compacted forms reduce atmospheric oxidation during extended storage and improve flow characteristics in automated feeding systems.
- Slurry:Liquid-suspended particles enable specialized surfacing and additive manufacturing feedstock applications.
Granules dominate tonnage throughput; Powder is climbing the fastest in value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Jiangsu Free Trade Zone anchors welding powder concentration through shipbuilding incentives and bonded warehousing for atomized alloy feedstock. German industrial clusters absorb premium aerospace grades. Indian infrastructure buildouts and Japanese precision manufacturing sustain divergent demand vectors.
China
Jiangsu and Zhejiang province shipyards consume bulk ferrous powders for hull construction under state-directed maritime infrastructure programs. MEE environmental enforcement tightens atomization facility compliance burdens. Yangzijiang Shipbuilding in Taizang mandates unified chemical certification protocols that compress supplier margins.
Germany
Automotive lightweighting programs in Baden-Württemberg drive aluminum and titanium alloy powder demand for EV battery enclosures. REACH Annex XIV authorization requirements pressure cobalt-reduced formulation adoption. Inert gas atomization capacity in North Rhine-Westphalia concentrates aerospace-grade supply security.
United States
Tesla and legacy automakers in Michigan and California compress powder qualification cycles for aluminum-intensive body-in-white structures. EPA emissions thresholds and OSHA hexavalent chromium exposure limits reshape product formulations. Aerospace contractors in the Pacific Northwest maintain parallel AS9100 and NADCAP accreditation requirements.
India
The National Infrastructure Pipeline and PLI manufacturing incentives generate structural steel fabrication demand across Maharashtra and Gujarat. BIS standards tighten domestic consumable quality benchmarks. Fabrication clusters in Haryana absorb standardized ferrous grades for bridge and highway construction.
Japan
Precision turbine repair shops in Nagoya and Osaka sustain Gas Tungsten Arc powder consumption for heat-affected zone control. METI industrial policy supports nickel superalloy qualification timelines. Shipyards in Kobe pilot laser-hybrid arc configurations requiring tailored chemistry development.
Global Welding Powder Market Competitive Environment
Top-tier vendors anchor premium alloy supply through captive atomization capacity, while mid-scale blenders compete on qualification speed and regional logistics. The vendor base stratifies across aerospace-certified specialists, integrated ferroalloy producers, and merchant powder distributors. Refractory metal expertise and nickel superalloy formulation capability separate pricing tiers. Competitive moves concentrate on backward integration into sponge titanium supply and geographic expansion through joint ventures in Chinese shipbuilding clusters.
Within the premium-tier vector, H.C. Starck and AMG Superalloys UK occupy positions defined by refractory metal and superalloy specialization. Shanghai Zhongzhou Special Alloy Materials anchors Chinese supply through integrated ferroalloy production. These three exemplify the archetype divergence between European aerospace qualification depth and Asian volume-scale integration.
| Leading Market Players |
|---|
| Harris |
| GENSA Group |
| NiGK Corporation |
| H.C. Starck |
| AMG Superalloys UK |
| Shanghai Zhongzhou Special Alloy Materials |
| Tongling Xinxin Welding Materials |
| Pometon Powder |
| Grecian Magnesite |
| Others |
Value Chain & Pricing Dynamics
Plasma rotating electrode atomization technology is decentralizing premium powder production from centralized merchant suppliers toward captive aerospace installations, simultaneously collapsing lead-time premiums and eroding traditional atomization house pricing power while concentrating input cost exposure among sponge titanium and nickel feedstock processors.
Pricing Analysis
Short lead-time premiums for aerospace-qualified nickel superalloy powders command substantial markups over standard inventory positions, while spot ferrous grades trade at discounts reflecting Chinese state shipyard procurement concentration. Three-tier pricing structure across AS9100-certified premium, industrial-standard mid-grade, and bulk economy ferrous levels separates qualification depth from volume scale. Pricing pressure stems from Yangzijiang Shipbuilding's unified chemical certification mandates compressing supplier margins in Jiangsu province. Chinese state-directed buyers exhibit highest price sensitivity, whereas NADCAP-accredited aerospace repair shops demonstrate lowest elasticity due to qualification switching costs.
Supply Chain Analysis
Sponge titanium supply rests on Ukrainian and Russian Kroll process feedstock, with inert gas atomization capacity clustering in Germany, Japan, and the United States. Premium nickel superalloy powder production draws from electrolytic nickel cathodes and cobalt metal intermediates sourced through concentrated trading houses. Single-source vulnerability pervades aerospace-grade inert gas atomization, where German and Japanese merchant houses control qualification-critical capacity. Distribution runs through direct mill relationships for bulk ferrous grades and specialized distributors for certified aerospace material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where REACH Annex XIV authorization requirements and parallel AS9100-NADCAP accreditation burdens create substantial barrier-to-entry moats favoring incumbents with established qualification portfolios.
For Market Incumbents: To counter plasma rotating electrode atomization decentralization threatening merchant atomization revenue, secure captive sponge titanium supply through backward integration into Kroll process feedstock or long-term offtake agreements with Ukrainian and Russian processors. Expand inert gas atomization capacity in Germany and Japan to maintain aerospace qualification concentration against emerging PREP installations in France and the United Kingdom. For New Entrants and Emerging Players: Indian structural steel fabrication job shops present the most penetrable buyer archetype, with National Infrastructure Pipeline project demand outpacing qualified domestic powder supply. Target Maharashtra and Gujarat fabrication clusters with BIS-certified ferrous grades priced below established import channels. Accelerate qualification speed by pre-certifying to Chinese GB standards for eventual Yangzijiang Shipbuilding supplier status. For Investors and Strategic Acquirers: Exit pathways concentrate in aerospace-qualified specialty alloy producers with established NADCAP accreditation and captive atomization assets. Long-term viability favors refractory metal and nickel superalloy formulators over commodity ferrous blenders facing Chinese state procurement margin compression. Watch ECHA sunset date enforcement intensity as inflection indicator for cobalt-reduced formulation substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sponge Titanium | Captive Kroll process feedstock secures aerospace powder cost stability against Ukrainian supply disruption. |
| PREP Atomization Capacity Installation | Captive plasma rotating electrode production in France and United Kingdom reduces German merchant dependence. |
| REACH Annex XIV Substitution R&D | Cobalt-reduced nickel superalloy validation ahead of ECHA sunset dates protects European turbine repair access. |
| Indian Joint Venture Formation | Local ferrous powder blending in Maharashtra accelerates National Infrastructure Pipeline contract capture. |
| Laser-Hybrid Arc Chemistry Development | Tailored aluminum powder formulations for South Korean shipyard pilot programs open premium deposition technology segment. |
Study Parameters
Multi-period observation of atomization capacity utilization rates, sponge titanium price indices, and aerospace qualification backlog durations anchored the trend analysis, supplemented by interviews with welding consumables procurement managers at Tier 1 automotive suppliers, NADCAP-accredited powder metallurgy specialists, shipyard welding engineers in Jiangsu province, and commercial directors at inert gas atomization houses. Secondary validation drew from customs trade data, ECHA authorization timelines, SEC filings by listed specialty materials producers, and AS9100 registrar accreditation databases. Bottom-up segment sizing triangulated against top-down end-use consumption estimates.
Segment-weighting across product type, technology, end user, and form dimensions calibrated volume and value outputs across the projection horizon. Material chemistry splits between ferrous, alloy, non-ferrous, and stainless steel categories combined with process technology adoption curves for Gas Metal Arc, Gas Tungsten Arc, Flux-Cored Arc, and Submerged Arc systems. CAGRs were derived from regression analysis against automotive production forecasts, shipbuilding orderbook data, and infrastructure investment pipelines. Industry-specific inputs included electric vehicle platform aluminum content trajectories and REACH substance restriction implementation schedules.
Revisions become necessary when ECHA accelerates cobalt or nickel compound sunset dates, Ukrainian sponge titanium supply sustains prolonged disruption, or Chinese state shipyard procurement consolidation extends unified certification mandates beyond Jiangsu province. A small set of regulatory enforcement intensity, critical mineral supply stability, and state-directed buyer concentration triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Reconditioned Steel Drums Market
Metals
Metal Finishing Market
Metals
Global Stainless Steel Lashing Wire Market
Metals
Aluminum Tubes Market
Metals
Aluminum Ingots Market
Metals
Galvanized Steel Coil Market
Metals
Copper Smelting Market
Metals
Galvanizing Market
Metals
North America Aluminium Powder Market
Metals
Global Tantalum Market
Metals
GCC Aluminium Cans Market
Metals
Welding Materials Market
Metals
Electrodeposited Copper Foil Market
Metals
Ferrosilicon Magnesium Market
Metals
Electrolytic Iron Market
Metals
Lithium Foil Market