
 Aluminum Ingots Market | 2026-2036
Aluminum Ingots Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Ingots Market Outlook
The aluminum ingots market is recalibrating around a widening gap between premium aerospace-grade material and commodity construction-grade supply. Alcoa Corporation leverages its upstream bauxite-to-ingot integration to command premium pricing in high-purity segments. Norsk Hydro ASA anchors its position through hydropower-smelting technology that lowers carbon intensity for European automotive clients. China Hongqiao Group Limited dominates volume production through captive alumina refining and massive foundry scale in Shandong Province.
Aluminum ingots are solid cast blocks of refined aluminum metal, typically produced through electrolytic reduction of alumina in Hall-Héroult cells and subsequently remelted or alloyed for downstream fabrication; they serve as the foundational feedstock for extrusion, rolling, and casting operations across transportation and packaging industries. Primary ingots sustain margin concentration among integrated smelters with captive energy assets, while secondary ingots from scrap recovery are gaining structural share as circular-economy mandates tighten virgin-metal quotas. Aerospace grade commands the steepest certification barriers and longest qualification cycles, insulating incumbent suppliers from commodity price volatility.
The EPA enforces emissions thresholds for U.S. smelters under the Clean Air Act, while REACH and the EU Carbon Border Adjustment Mechanism impose traceability and carbon-content declarations on ingot imports into Europe. China's MEE enforces dual carbon goals that cap smelter capacity expansion and redirect investment toward secondary recovery. Stakeholders must monitor how divergent carbon-accounting rules reshape cross-border arbitrage and supplier qualification timelines.
Market Dynamics
Carbon-border compliance costs are fragmenting aluminum ingot trade flows, forcing smelters to reconfigure energy sourcing and certification systems ahead of phased-in tariffs.
Growth Catalysts
- EU Carbon Border Adjustment Mechanism:Importers into Europe must document embedded emissions, creating premium demand for low-carbon primary and secondary ingots from hydropower-fed smelters.
- Automotive lightweighting mandates:NHTSA fuel-economy standards and parallel EU CO2 fleet targets are expanding alloy ingot orders for electric vehicle body-in-white and battery enclosure castings.
- Secondary recovery infrastructure:China's dual carbon goals under MEE are redirecting capital from greenfield smelters toward scrap-fed remelting capacity, structurally lifting recycled ingot supply.
Market Restraints
- Alumina price volatility:Bauxite refining disruptions in Guinea and Australia transmit directly to smelter feedstock costs, compressing margins for non-integrated producers.
- Energy cost divergence:European smelters face natural gas and power price premiums against Middle Eastern and Canadian competitors with captive gas or hydro assets.
- REACH traceability burdens:ECHA substance-of-very-high-concern declarations add documentation costs and qualification delays for alloy additives in precision casting grades.
Strategic Opportunities
- India domestic procurement scaling:Construction and packaging demand in Gujarat and Maharashtra is outpacing local smelter capacity, opening import substitution and joint-venture foundry slots.
- Aerospace alloy qualification:Boeing and Airbus supplier consolidation is creating entry points for certified secondary feedstock in non-critical structural components.
- ISO 14064 carbon accounting:Third-party verification of smelter emissions is becoming a procurement gate, rewarding early adopters with long-term automotive supply agreements.
Industry Challenges
- Smelter engineer scarcity:Hall-Héroult cell operation and potline maintenance expertise is concentrating among retiring workforces in Russia and Canada, constraining capacity restart timelines.
- Alloy certification cycles:Aerospace-grade ingot qualification spans 18-36 months of testing, freezing supplier rosters and delaying revenue recognition for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Ingots Market |
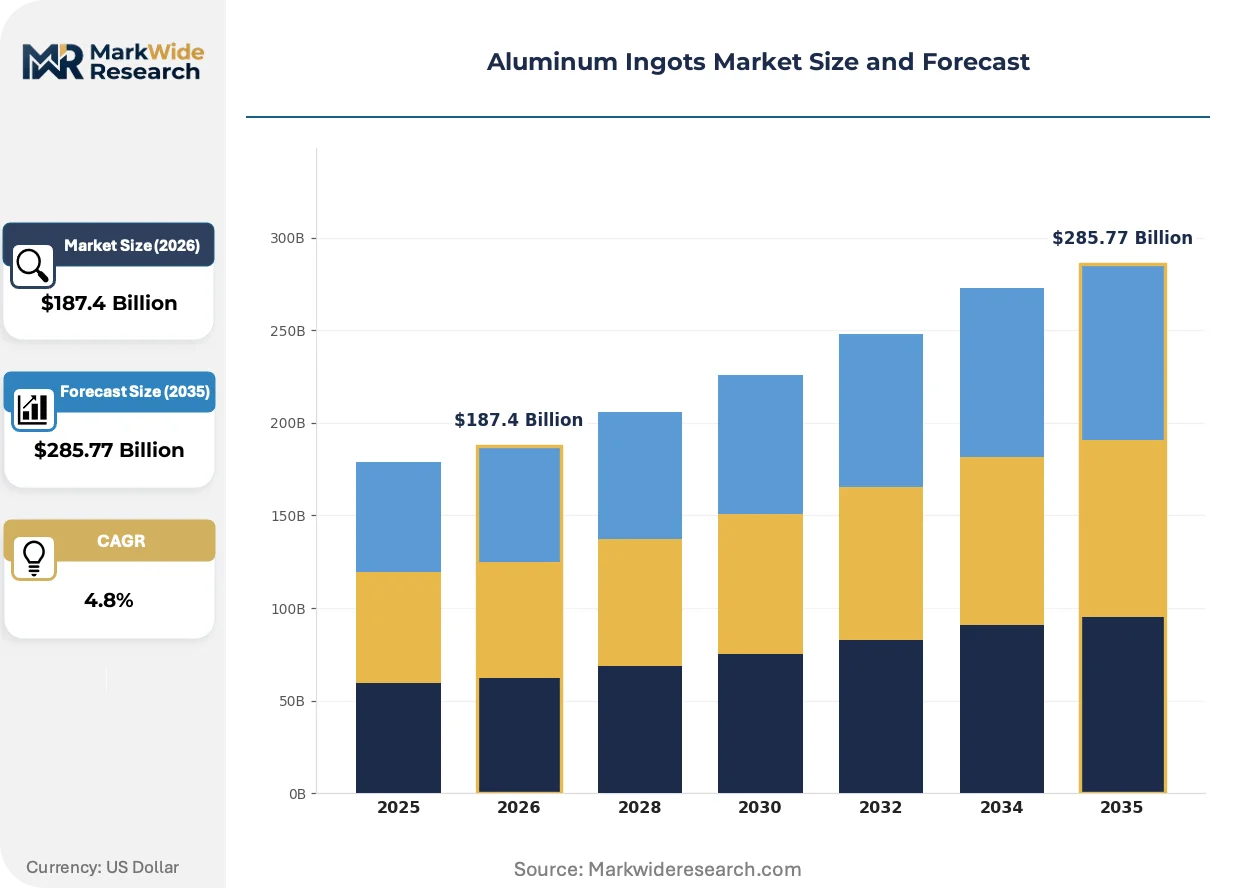
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primary Ingots, Secondary Ingots, Alloy Ingots, Foundry Ingots End User: Aerospace, Automotive, Construction, Packaging Grade: Commercial Grade, High Purity Grade, Aerospace Grade, Automotive Grade Form: Cast, Rolled, Extruded, Forged |
| Companies Covered | Alcoa Corporation, Rio Tinto Group, United Company RUSAL, China Hongqiao Group Limited, Norsk Hydro ASA, Dubai Aluminium Company Limited, Hindalco Industries, Bahrain Aluminium Company, Constellium SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Ingots Market Strategic Shifts
Smelting technology and carbon-accounting protocols are converging to redefine competitive advantage around energy provenance rather than scale alone.
Inert anode technology is decentralizing primary aluminum production by eliminating carbon anode consumption and enabling modular, lower-capex cell designs. Rio Tinto and Alcoa pilot installations in Quebec and Norway are validating oxygen-only emissions profiles that bypass carbon-capture infrastructure. This architecture collapses the minimum efficient scale for smelter entry, allowing renewable-rich jurisdictions to attract capacity without billion-dollar integrated complexes.
REACH authorization requirements for chromium and nickel compounds in high-strength alloys are tightening formulation flexibility for European automotive casters. ECHA sunset dates for specific substance uses are forcing alloy redesigns and supplier requalification across transmission-housing and suspension-component supply chains. German and Czech foundries are accelerating trials of boron-modified alternatives to preserve die-cast process windows.
Automotive OEMs are consolidating aluminum ingot purchasing through direct mill relationships, bypassing traditional merchant traders and regional distributors. Tier-1 casters in Michigan and Bavaria are negotiating multi-year tolling arrangements that embed carbon-intensity clauses and scrap-return obligations. This channel compression is most advanced in battery-electric vehicle programs where traceability requirements exceed commodity-grade documentation standards.
Aluminum Ingots Market Segmentation
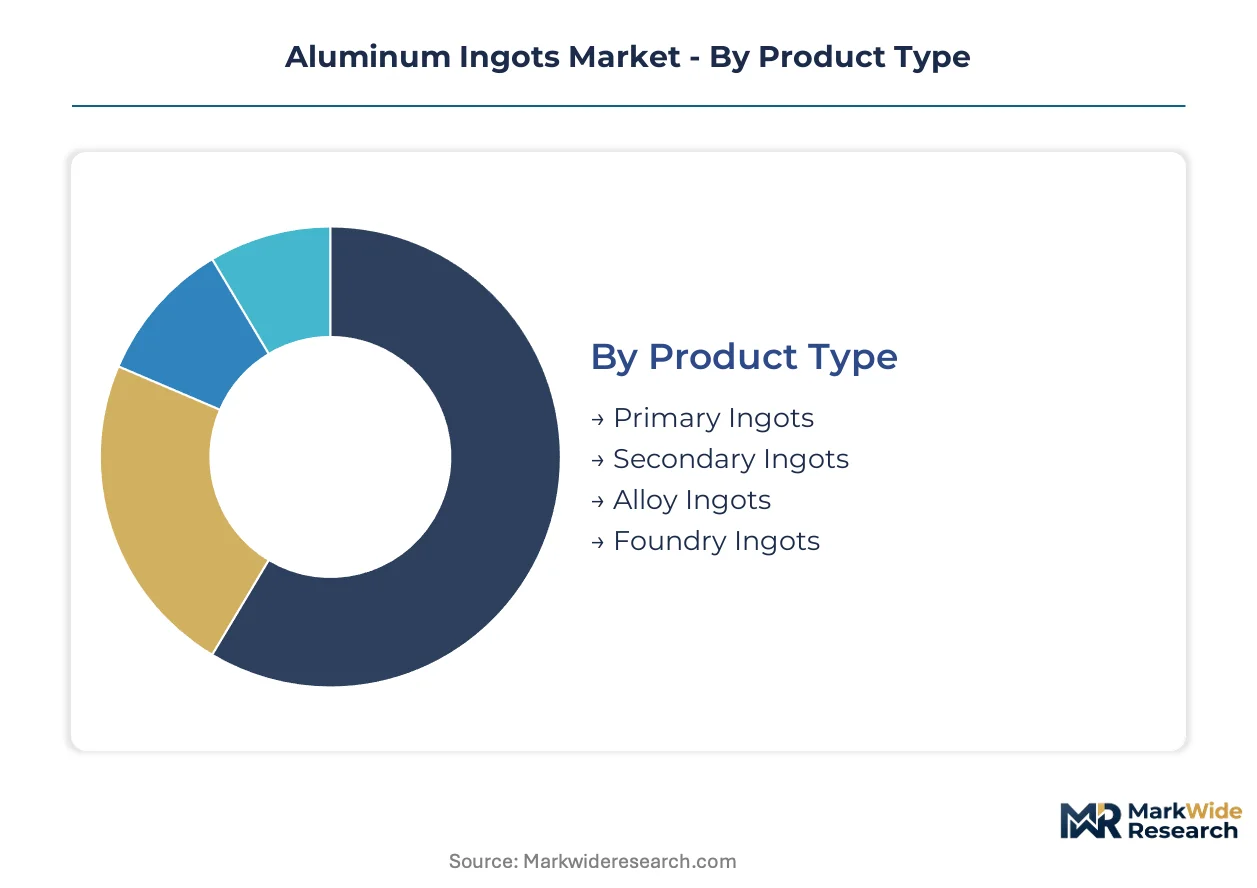
Aluminum ingot buyers segment supply by carbon intensity, alloy specification, and qualification tier. Procurement teams weight energy provenance against mechanical performance requirements when matching feedstock to end-use applications.
Product Type:
Buyers differentiate primarily by feedstock origin and carbon footprint liability.
- Primary Ingots:Electrolytically refined from alumina via Hall-Héroult reduction, these ingots carry embedded emissions from smelter power sourcing. EU Carbon Border Adjustment Mechanism documentation requirements are redirecting European automotive procurement toward hydropower-fed Canadian and Norwegian supply.
- Secondary Ingots:Remelted from post-consumer and industrial scrap streams, these ingots command premium pricing in markets with virgin-metal quotas. China's MEE dual carbon goals are accelerating scrap-fed capacity expansion in Shandong and Henan provinces.
- Alloy Ingots:Pre-formulated with silicon, magnesium, or copper additions for downstream casting efficiency.
- Foundry Ingots:Sized and shaped for direct furnace charging in sand and die-casting operations.
Primary ingots lead volumes today; secondary ingots are gaining share fastest.
End User:
Application-specific certification barriers create divergent margin profiles across demand verticals.
- Aerospace:Stringent AMS and ASTM specifications govern ingot chemistry and inclusion content. Boeing and Airbus qualification cycles spanning 18-36 months insulate incumbent suppliers from commodity price pressure.
- Automotive:NHTSA fuel-economy mandates and EU CO2 fleet targets are expanding alloy ingot orders for electric vehicle body-in-white and battery enclosure castings. OEMs embed carbon-intensity clauses in multi-year tolling agreements.
- Construction:Structural extrusion and facade system demand concentrates in India's Gujarat and Maharashtra corridors.
- Packaging:Thin-gauge rolling stock for beverage cans and foil applications prioritizes formability over strength.
Automotive procurement leads volume concentration; aerospace commands the steepest price premiums.
Grade:
Mechanical property thresholds and traceability requirements stratify pricing tiers.
- Commercial Grade:General-purpose ingots with 99.5-99.7% aluminum content serve construction and commodity packaging applications where specification tolerance is widest.
- High Purity Grade:99.9%+ aluminum content supports electrical conductor and specialty chemical applications. Smelters with captive bauxite-to-ingot integration command premium positioning in this tier.
- Aerospace Grade:Tight chemistry controls and ultrasonic cleanliness certification support airframe and engine component casting.
- Automotive Grade:Controlled silicon and magnesium ranges optimize die-cast fluidity and heat-treat response for powertrain housings.
Commercial grade dominates tonnage; high purity grade is climbing the fastest.
Form:
Downstream processing compatibility determines ingot geometry selection.
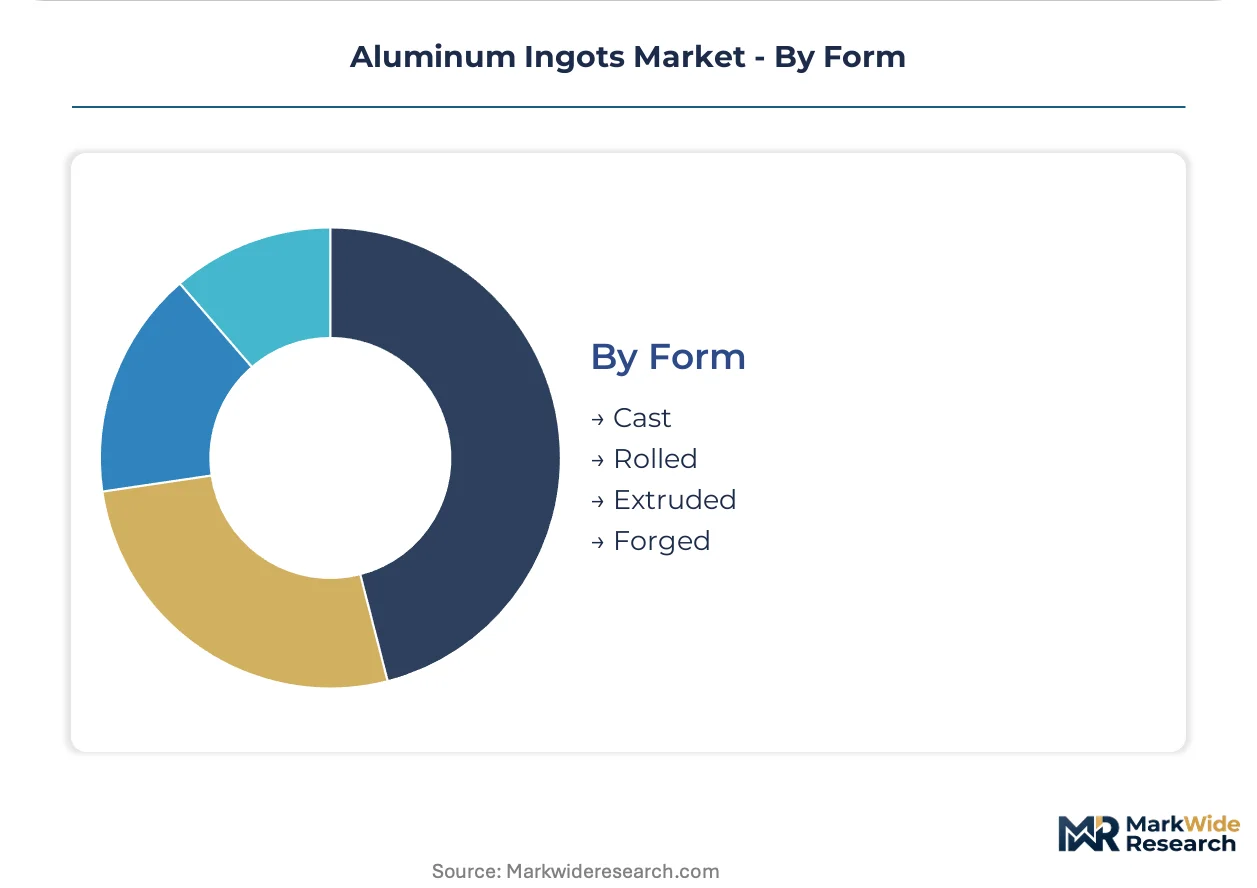
- Cast:Standard sow and T-bar shapes feed remelting furnaces across extrusion, rolling, and foundry operations. Cast ingots remain the default feedstock for integrated smelter-to-fabricator supply chains.
- Rolled:Continuous cast slab formats bypass ingot remelting for direct hot-band entry, compressing energy intensity in packaging sheet production.
- Extruded:Billet forms with controlled grain structure feed press operations for architectural and transportation profiles.
- Forged:Upset-forged preforms reduce machining waste in high-strength suspension and airframe component manufacturing.
Cast forms anchor current supply; rolled formats are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smelter engineering talent concentrates in Quebec's Saguenay Valley and Russia's Krasnoyarsk region, anchoring primary production capacity that shapes trade flows. These workforce clusters sustain operational expertise across aging potline infrastructure while newer jurisdictions compete for technology transfer.
China
Construction and packaging demand in Shandong and Henan provinces is outpacing domestic smelter capacity. The MEE enforces dual carbon goals that cap greenfield primary expansion and redirect investment toward scrap-fed remelting. Yunnan's hydropower-rich valleys are attracting relocated capacity from coal-dependent northern provinces.
United States
Automotive OEMs in Michigan and Ohio are expanding alloy ingot orders for electric vehicle battery enclosures and body-in-white castings. The EPA enforces Clean Air Act emissions thresholds that constrain restart timelines for idled smelter capacity. Kentucky's aluminum corridor hosts integrated rolling and extrusion complexes serving southeastern automotive assembly plants.
India
Construction sector procurement in Gujarat and Maharashtra is scaling faster than local smelter output. The Bureau of Indian Standards certifies ingot grades for structural extrusion applications. Odisha's bauxite belt feeds captive alumina refineries that supply smelters in Jharsuguda and Korba.
Germany
Automotive casters in Bavaria and North Rhine-Westphalia are negotiating tolling agreements with embedded carbon-intensity clauses. The EU Carbon Border Adjustment Mechanism imposes traceability documentation on imported ingot. The KBA enforces vehicle fleet CO2 targets that expand lightweight alloy demand from foundries in Neckarsulm and Dingolfing.
Norway
Hydropower-smelting technology in the Nordland and Søral regions commands premium positioning for European automotive clients. Norsk Hydro ASA anchors capacity that delivers low-carbon primary ingots qualifying for CBAM-compliant procurement. The country's renewable energy surplus sustains cost advantages against natural gas-dependent continental competitors.
Aluminum Ingots Market Competitive Environment
Capital-heavy producers compete with asset-light traders across a market structure consolidating around integrated upstream control. The vendor base stratifies into three tiers: captive energy smelters commanding premium pricing, merchant producers exposed to alumina cost volatility, and scrap-fed secondary specialists capturing circular-economy mandates. Dominant competitive moves include backward integration into bauxite refining and strategic partnerships embedding carbon-accounting clauses into long-term supply agreements.
Among North American integrated producers, Alcoa Corporation exemplifies the upstream-integrated archetype through its bauxite-to-ingot positioning. Rio Tinto Group represents the diversified mining conglomerate model with smelting assets spanning hydropower-rich jurisdictions. China Hongqiao Group Limited anchors the scale-driven Asian producer tier through massive foundry operations in Shandong Province.
| Leading Market Players |
|---|
| Alcoa Corporation |
| Rio Tinto Group |
| United Company RUSAL |
| China Hongqiao Group Limited |
| Norsk Hydro ASA |
| Dubai Aluminium Company Limited |
| Hindalco Industries |
| Bahrain Aluminium Company |
| Constellium SE |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed producers and captive-energy smelters anchor supply discipline across the aluminum ingots market, translating stranded hydropower assets into pricing power that merchant competitors cannot replicate. This ownership pattern concentrates margin capture among integrated upstream operators while forcing non-integrated players toward spot-market exposure.
Pricing Analysis
Long-term contract pricing dominates high-volume automotive procurement, separating bundled carbon-accounting and scrap-return obligations from unbundled commodity spot transactions. Price differentiation rests on energy provenance certification and alloy qualification tier, with hydropower-fed primary ingots commanding premiums against coal-dependent supply. Cost compression in commercial-grade construction feedstock is intensifying because Indian import substitution is expanding local smelter capacity. Automotive OEMs exhibit the lowest price sensitivity due to embedded carbon-intensity clauses, while commodity packaging buyers remain most responsive to spot-price movements.
Supply Chain Analysis
Dual-sourcing mandates from European automotive OEMs are fragmenting traditional single-supplier relationships and accelerating qualification of secondary feedstock streams. Geographic concentration centers on China, Canada, and Norway, with bauxite refining in Guinea and Australia feeding smelter networks. Supply chains draw from alumina, metallurgical coke, and hydropower or natural gas inputs. Single-source vulnerability around Hall-Héroult cell engineering expertise in Quebec and Krasnoyarsk constrains capacity restart timelines. Distribution runs through integrated smelter-to-fabricator tolling arrangements and merchant traders serving spot-demand pockets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aluminum ingots market functions as a stable compounder, with automotive lightweighting mandates and circular-economy regulations delivering predictable demand expansion across replacement and growth cycles.
For Market Incumbents: Anticipate margin compression from Chinese scrap-fed capacity expansion by securing captive bauxite refining and hydropower smelting positions in Canada or Norway. Deepen automotive tolling relationships through ISO 14064 carbon-accounting certification that locks in multi-year supply agreements ahead of EU Carbon Border Adjustment Mechanism phase-in. Prioritize aerospace alloy qualification investments to insulate revenue from commodity volatility. For New Entrants and Emerging Players: Launch via scrap-fed secondary ingot production targeting India's Gujarat and Maharashtra construction corridors, where domestic smelter capacity lags demand growth. Exploit white-space in certified secondary aerospace feedstock for non-critical structural components, where Boeing and Airbus supplier consolidation is relaxing incumbent lock-in. Pursue joint-venture foundry slots with Odisha-based alumina refineries to secure backward integration without greenfield smelter capex. For Investors and Strategic Acquirers: Valuations sit cheapest among merchant producers exposed to alumina cost volatility and natural gas price premiums, creating acquisition entry points before energy transition repricing. Long-term viability favors integrated upstream operators with captive hydropower and bauxite reserves across the coming decade. Watch for inflection in EU Carbon Border Adjustment Mechanism enforcement stringency, which would accelerate premium pricing for low-carbon primary and secondary ingots.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Refining | Captive alumina supply insulates Alcoa and Rio Tinto from Guinea disruption risk. |
| Hydropower Smelting Capacity Expansion | Norsk Hydro's Nordland operations qualify for EU CBAM-compliant automotive procurement. |
| Scrap-Fed Secondary Remelting Buildout | China's MEE dual carbon goals redirect capital toward circular-economy ingot supply. |
| Aerospace Alloy Qualification Investment | Boeing and Airbus certification cycles protect incumbent suppliers from price erosion. |
| Long-term Tolling Agreement with Carbon Clauses | German automotive casters embed traceability requirements exceeding commodity standards. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining executive interviews with smelter operations directors, automotive Tier 1 procurement leads, aerospace casting engineers, and commodity traders. Secondary validation draws from customs trade data, SEC 10-K filings, EPA emissions disclosures, and ECHA REACH substance registrations. Bottom-up capacity and demand modeling triangulates against top-down macroeconomic drivers.
Granularity-level modeling distinguishes primary, secondary, alloy, and foundry ingot categories across commercial, high-purity, aerospace, and automotive grades. End-use segmentation captures transportation, construction, packaging, and electrical applications. Regional clusters differentiate hydropower-rich jurisdictions from coal-dependent production zones. CAGRs derive from volume-demand elasticity against fuel-economy regulations and carbon-border compliance costs. Forecast inputs incorporate smelter restart timelines, aerospace qualification cycles, and scrap-recovery infrastructure buildout.
Forecast precision tightens around the base case; tail outcomes carry wider variance under alumina supply disruption or accelerated EU Carbon Border Adjustment Mechanism phase-in. Deviation in Chinese dual carbon policy enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Ferro Aluminum Market
Metals
Zinc Ingots Market
Metals
High Purity Pig Iron Market
Metals
Metal Alloys Market
Metals
High Magnetic Induction Grain-Oriented Silicon Steel Market
Metals
Global Nickel Alloy Welding Consumables Market
Metals
Global Copper Cathode Market
Metals
Steel Ingots Market
Metals
Hafnium Foil Market
Metals
Steel Wire Market
Metals
Barium Market
Metals
Global Bronze Market
Metals
Global Electrolytic Copper Foil Market
Metals
Global Copper Market
Metals
GCC Aluminium Powder Market
Metals
US and Mexico Stainless Steel Market