
 Aluminum Smelting Market | 2026-2036
Aluminum Smelting Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Smelting Market Analysis
Automotive OEMs is collapsing the historical buyer mix that favored construction and packaging offtake. Rusal leverages Siberian hydropower assets to sustain low-carbon primary output. Alcoa Corporation anchors North American supply through integrated bauxite-to-smelter operations. Norsk Hydro ASA differentiates via certified low-carbon Hydro REDUXA product lines serving European automotive contracts.
Aluminum smelting converts alumina into metallic aluminum through Hall-Héroult electrolysis in reduction cells operating at approximately 950°C with cryolite electrolyte, yielding 99.5-99.9% purity metal for structural, electrical, and thermal applications. Primary aluminum commands the largest value pool given energy intensity and capital requirements, while secondary aluminum is expanding fastest as scrap collection infrastructure matures and EU ETS carbon costs widen the cost gap against carbon-intensive primary production. Electrolytic technology dominates installed capacity, though vertical shaft methods retain niche positions in specific regional energy configurations.
EPA rules on per- and polyfluoroalkyl substances constrain anode manufacturing inputs in the United States, while the EU's Carbon Border Adjustment Mechanism reshapes import competitiveness for Middle Eastern and Russian metal. China's MEE enforces dual carbon emissions caps that force capacity relocations to provinces with cleaner power grids. Stakeholders must track regulatory divergence between carbon-pricing jurisdictions and monitor smelter power sourcing as the decisive cost and compliance variable.
Market Dynamics
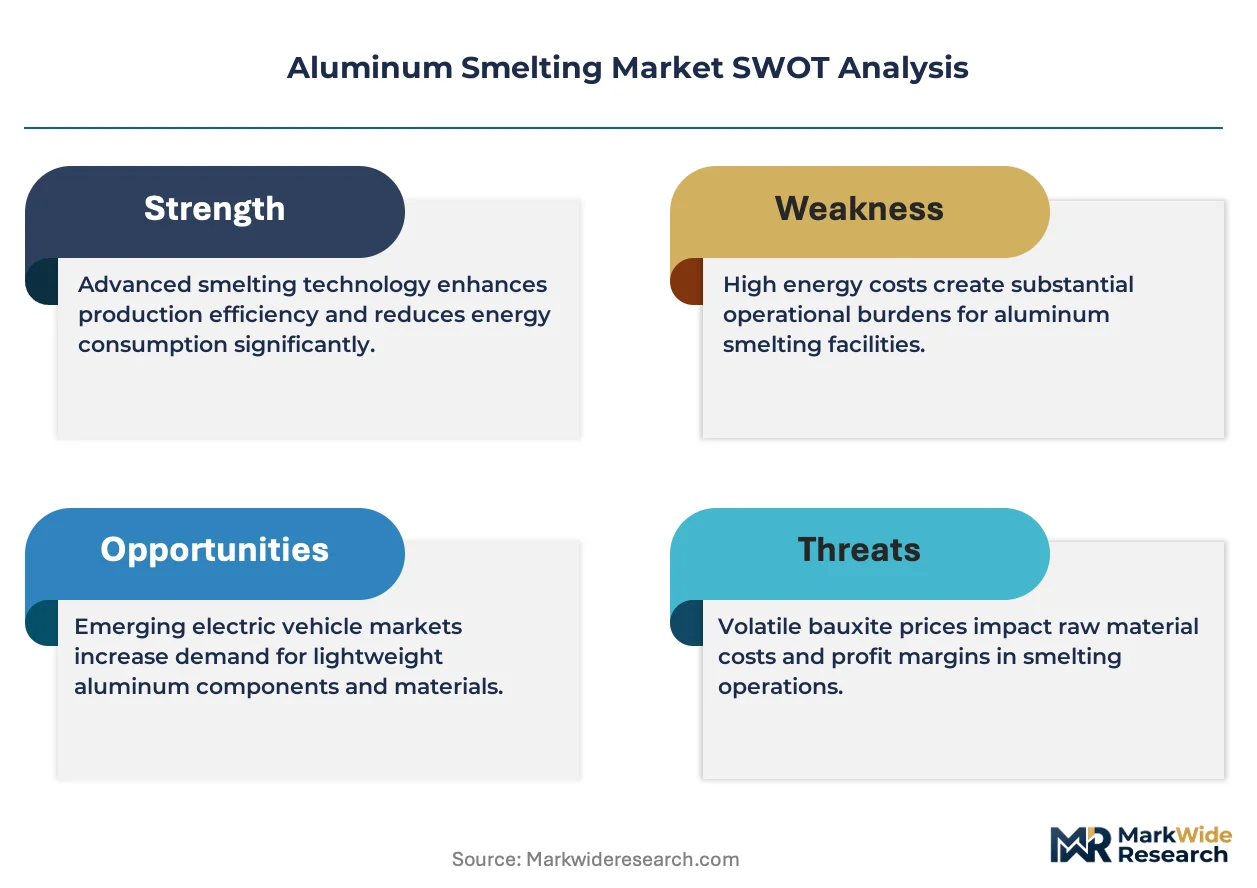
Electrolytic smelters face a structural squeeze as carbon pricing mechanisms spread across jurisdictions, forcing power-sourcing decisions to dominate both opex and compliance strategy for producers.
Growth Catalysts
- Automotive lightweighting mandates:OEMs are expanding aluminum content in electric vehicle platforms to reduce curb weight and extend range, redirecting offtake from traditional construction and packaging buyers.
- EU Carbon Border Adjustment Mechanism:The CBAM is tightening emissions benchmarks for imported primary metal, creating competitive advantage for smelters with verified low-carbon power sourcing.
- Middle East gas reserves:Emirates Global Aluminium and regional peers leverage stranded natural gas for energy-intensive electrolytic production, concentrating new capacity in the Gulf.
Market Restraints
- Alumina input volatility:Bauxite refining capacity concentrates in Guinea and Australia, exposing smelters to freight cost spikes and geopolitical supply interruptions.
- Power cost divergence:Smelters in China face MEE dual carbon caps forcing relocations to cleaner grids, while European producers absorb EU ETS carbon costs that widen against Middle Eastern gas-powered competitors.
- Silicon carbide anode limits:EPA rules on per- and polyfluoroalkyl substances constrain anode manufacturing inputs in the United States, raising compliance costs for domestic producers.
Strategic Opportunities
- Scrap-fed secondary expansion:EU ETS carbon costs are widening the cost gap against carbon-intensive primary production, accelerating investment in scrap collection and remelt infrastructure.
- Hydropower-certified branding:Norsk Hydro's REDUXA product lines demonstrate how certified low-carbon metal commands premium positioning in European automotive contracts.
- Inert anode commercialization:Elimination of carbon anode consumption would remove CO2 emissions from the reduction process entirely, though technical durability challenges persist.
Industry Challenges
- Electrolytic cell rebuild cycles:Hall-Héroult reduction cells require capital-intensive relining every 5-7 years, demanding precise timing against aluminum price cycles to avoid margin compression.
- Power purchase agreement renegotiation:Long-term offtake contracts with utilities face restructuring as grid decarbonization mandates and renewable intermittency complicate baseload supply guarantees for 24/7 smelter operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Smelting Market |
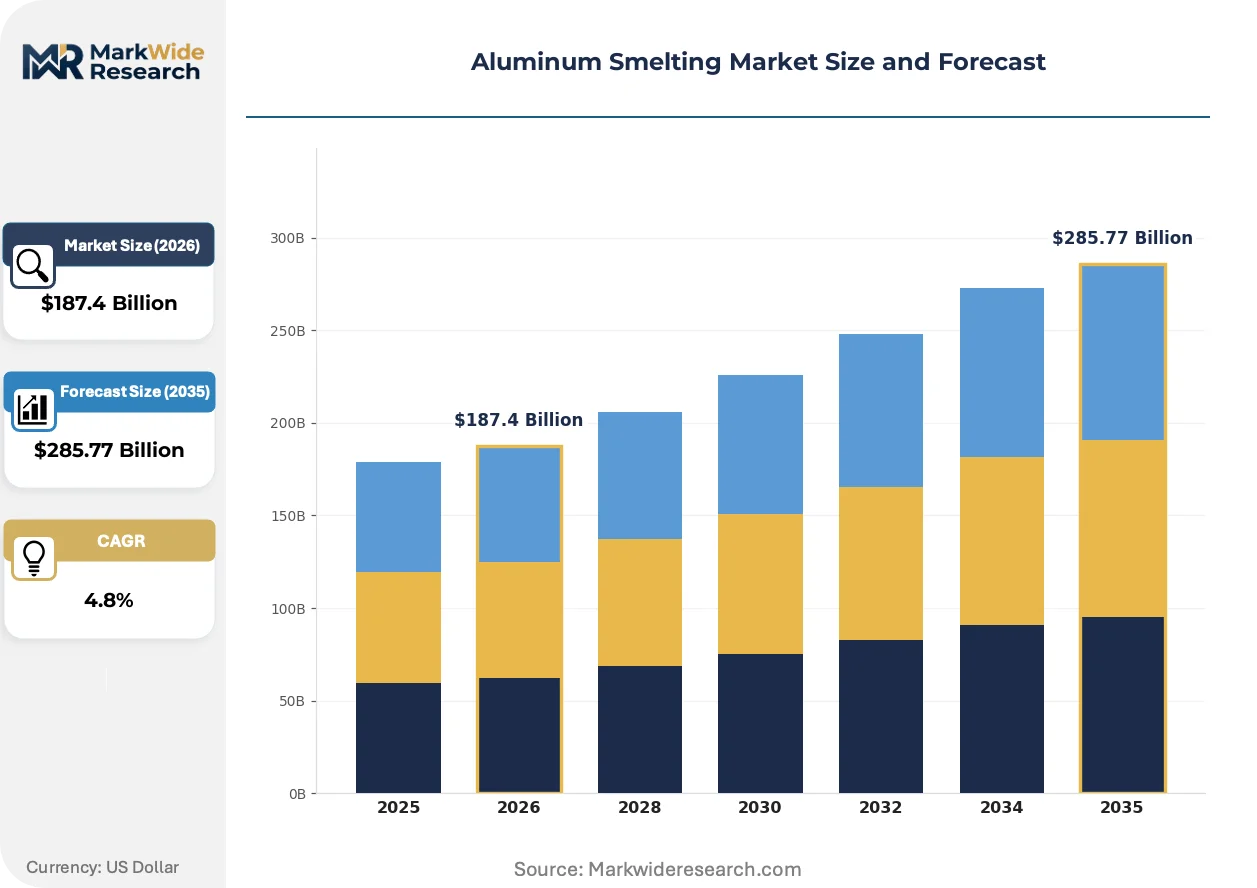
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electrolytic, Vertical Shaft, Horizontal Shaft, Ingot Casting Product Type: Primary Aluminum, Secondary Aluminum, Alloyed Aluminum, Pure Aluminum End User: Aerospace, Transportation, Construction, Consumer Goods Distribution Channel: Direct Sales, Online Sales, Distributors, Wholesalers |
| Companies Covered | Rusal, Aluminium Corporation of China, China Hongqiao Group, Hindalco Industries, Emirates Global Aluminium, Alcoa Corporation, Norsk Hydro ASA, Century Aluminum Company, Rio Tinto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Smelting Market Emerging Trajectories
Smelter technology and buyer requirements are diverging sharply as carbon accounting becomes a primary sorting mechanism for metal procurement and contract terms.
Neural network-based cell control systems are miniaturizing the operational variance in Hall-Héroult electrolysis. Aluminum producers in Iceland and Norway deploy machine-learning algorithms to optimize alumina feeding and thermal balance in real time. This compression of process variability is reducing anode effects and power consumption per tonne of output.
China's MEE enforces dual carbon emissions caps that force capacity relocations to provinces with cleaner power grids. The policy is accelerating smelter closures in coal-dependent Shandong and Henan while permitting new builds in Yunnan and Sichuan where hydropower dominates. Producers are responding with joint ventures to secure captive renewable supply.
Automotive OEMs now require mass-balance carbon certificates for aluminum sheet and extrusion supply. Tier-1 suppliers in Germany and Japan are consolidating purchase orders toward smelters with verified below-4-tonne-CO2-per-tonne-Al footprints. This certification-driven preference shift is fragmenting the historical commodity pricing structure for primary metal.
Aluminum Smelting Market Segmentation
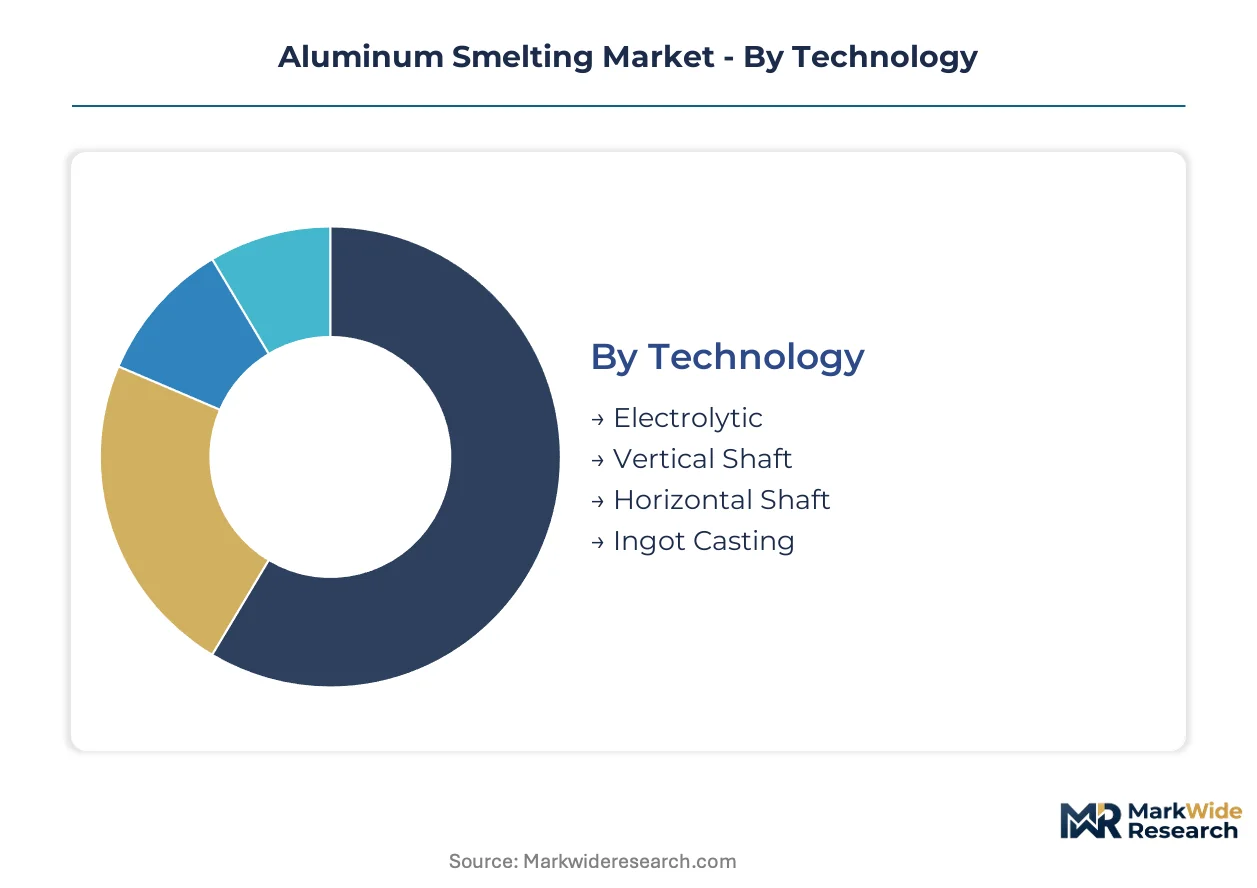
Channel configuration and technology choice determine margin capture in aluminum smelting. Buyers in automotive and aerospace now sort supply by carbon intensity rather than commodity grade alone.
Technology:
Direct sales channels dominate high-volume electrolytic output to automotive OEMs, while distributors handle smaller lot sizes for specialty vertical shaft producers.
- Electrolytic:Hall-Héroult cells operating at approximately 950°C with cryolite electrolyte yield 99.5-99.9% purity metal. Demand concentrates with Emirates Global Aluminium and other Gulf producers leveraging stranded gas for 24/7 baseload operations as EU CBAM tightens emissions benchmarks for imports.
- Vertical Shaft:Thermal reduction methods using alternative reductants serve niche regional energy configurations where grid electricity is unreliable or prohibitively expensive. Chinese MEE dual carbon caps are accelerating closures of shaft capacity in coal-dependent provinces.
- Horizontal Shaft:Modified thermal designs retain limited installed base in specific bauxite-rich regions with captive fuel supply.
- Ingot Casting:Solidification and alloying operations downstream of primary reduction feed remelt and secondary scrap recovery channels.
Electrolytic capacity dominates installed base. Inert anode development is where expansion concentrates for zero-carbon primary production.
Product Type:
Margin structures diverge sharply between carbon-intensive primary and scrap-fed secondary as EU ETS costs widen the cost gap.
- Primary Aluminum:Electrolytic reduction of alumina commands the largest value pool given energy intensity and capital requirements. Norsk Hydro's REDUXA-certified lines demonstrate premium positioning for below-4-tonne-CO2-per-tonne-Al footprints in European automotive contracts.
- Secondary Aluminum:Scrap collection and remelt operations expand most quickly as infrastructure matures and carbon pricing favors recycled feedstock. Germany and Japan tier-1 suppliers consolidate purchase orders toward verified low-carbon sources.
- Alloyed Aluminum:Silicon, magnesium, and copper additions tailor mechanical properties for aerospace and transportation specifications.
- Pure Aluminum:High-conductivity grades serve electrical transmission and specialized thermal applications with tight impurity tolerances.
Primary aluminum anchors current revenue. Secondary recovery is climbing the fastest as regulatory pressure reshapes input economics.
End User:
Automotive lightweighting mandates are collapsing the historical buyer mix that favored construction and packaging offtake.
- Transportation:Electric vehicle platforms expand aluminum content to reduce curb weight and extend range. OEMs now require mass-balance carbon certificates for sheet and extrusion supply, fragmenting historical commodity pricing structures.
- Construction:Structural extrusions and building envelope systems face demand pressure as automotive buyers outbid for limited low-carbon primary tonnage.
- Aerospace:High-strength alloy specifications for airframe and engine components command stringent certification and traceability requirements.
- Consumer Goods:Packaging, electronics housings, and durables absorb price-sensitive secondary and standard-grade primary output.
Transportation applications concentrate growth investment. Construction offtake is losing share to automotive procurement competition.
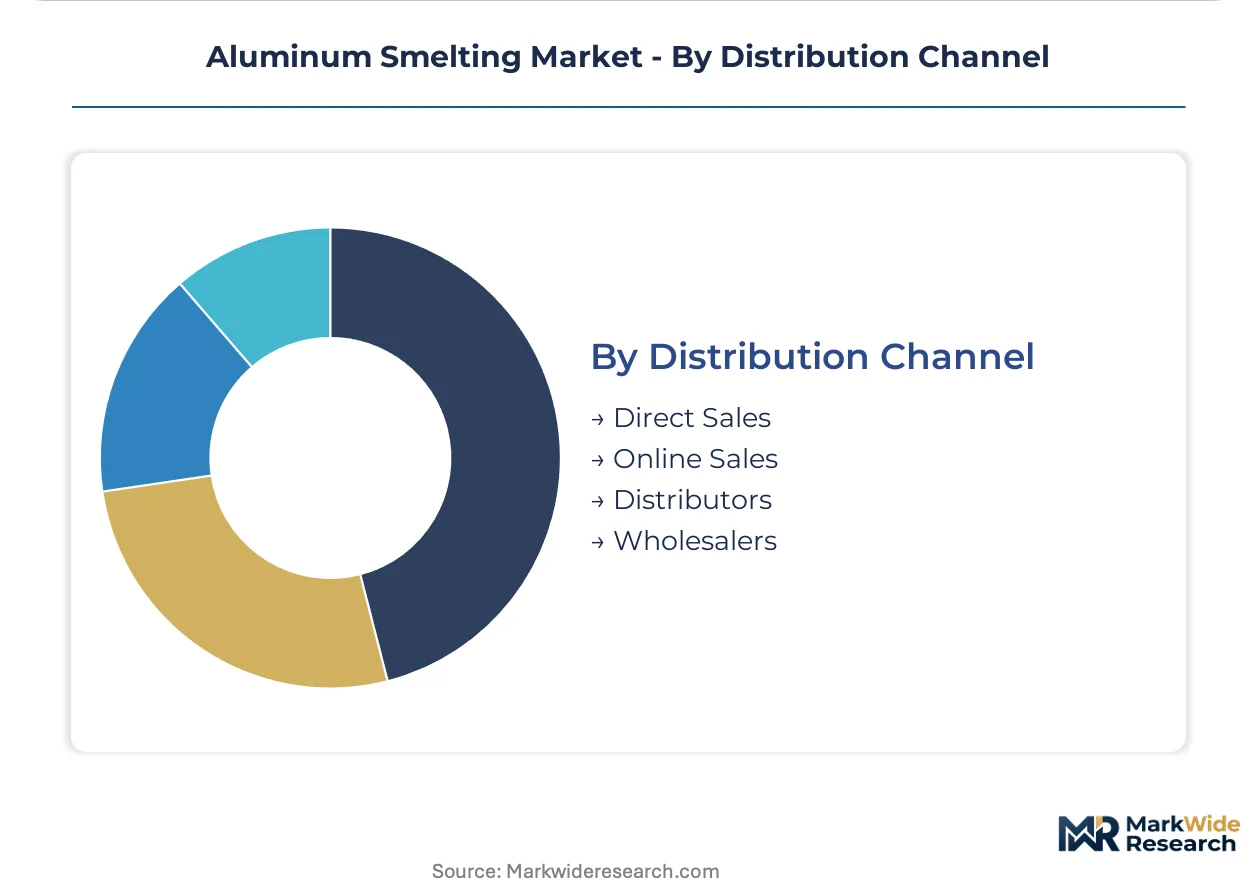
Distribution Channel:
Long-term offtake contracts face restructuring as grid decarbonization mandates complicate baseload supply guarantees.
- Direct Sales:Smelters contract directly with automotive OEMs and aerospace primes for certified low-carbon tonnage with embedded carbon accounting.
- Distributors:Regional metal service centers inventory standard grades for construction and industrial fabrication customers with shorter lead time requirements.
- Wholesalers:Volume aggregators handle commodity-grade primary and secondary for price-sensitive buyers without certification requirements.
- Online Sales:Digital platforms emerge for spot market transactions and scrap trading as price transparency improves.
Direct sales channels dominate premium certified volumes. Distributor networks handle the residual commodity tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian smelters export low-carbon primary metal to European automotive manufacturers seeking mass-balance carbon certificates under tightening EU CBAM benchmarks.
China
Electric vehicle manufacturers in Shanghai and Shenzhen are absorbing record aluminum tonnage for lightweight battery enclosures. The MEE enforces dual carbon emissions caps that force smelter relocations from coal-heavy Shandong to hydropower-rich Yunnan. New capacity concentrates in Sichuan's industrial corridor near the Jinsha River cascade.
United States
Domestic automotive OEMs in Michigan and Ohio require certified low-carbon sheet for electric truck platforms. EPA rules on per- and polyfluoroalkyl substances constrain anode manufacturing inputs, raising compliance costs for domestic producers. Century Aluminum operates integrated facilities in Kentucky and South Carolina serving regional automotive clusters.
Norway
European automotive tier-1 suppliers consolidate purchase orders toward verified below-4-tonne-CO2-per-tonne-Al footprints. Norsk Hydro ASA leverages hydropower assets to produce REDUXA-certified lines for German OEM contracts. Smelter capacity clusters along western fjords where renewable baseload powers 24/7 electrolytic operations.
United Arab Emirates
Gulf producers leverage stranded natural gas reserves for energy-intensive electrolytic production at globally competitive power costs. Emirates Global Aluminium anchors regional capacity expansion as EU CBAM tightens emissions benchmarks for imported primary metal. New smelter investment concentrates in Abu Dhabi and Dubai industrial zones.
Iceland
Machine-learning algorithms optimize alumina feeding and thermal balance in real-time cell control systems. Renewable geothermal and hydropower resources attract carbon-conscious European buyers seeking mass-balance certificates. Smelter operations cluster near Reykjanes Peninsula energy fields serving specialty aerospace and automotive contracts.
Aluminum Smelting Market Vendor Landscape
Listed leaders compete with private specialists across power-sourcing strategies and carbon-certification positioning. The vendor base concentrates around integrated bauxite-to-smelter operators, hydropower-dependent low-carbon specialists, and gas-powered Gulf producers. Three archetypes dominate: vertically integrated majors with captive raw material supply, renewable-powered premium-positioned smelters, and cost-optimized gas-based producers. Competitive moves center on securing long-term renewable power purchase agreements and acquiring scrap collection infrastructure for secondary expansion.
Within the integrated major tier, Rusal and Alcoa Corporation exemplify divergent geographic and energy strategies. Rusal anchors low-carbon output through Siberian hydropower assets serving European automotive contracts. Alcoa Corporation occupies a position across North American bauxite-to-smelter operations. Among Gulf-based producers, Emirates Global Aluminium represents the cost-optimized gas-powered archetype concentrating new capacity in the Middle East.
| Leading Market Players |
|---|
| Rusal |
| Aluminium Corporation of China |
| China Hongqiao Group |
| Hindalco Industries |
| Emirates Global Aluminium |
| Alcoa Corporation |
| Norsk Hydro ASA |
| Century Aluminum Company |
| Rio Tinto |
| Others |
Supply Flow & Price Mechanics
Capacity utilization rates above 90% at Gulf smelters compress marginal cost curves and establish regional price floors that European gas-powered competitors cannot match under EU ETS carbon costs. This scale asymmetry concentrates pricing power with Emirates Global Aluminium and regional peers while forcing higher-cost Chinese coal-dependent capacity toward idling or relocation.
Pricing Analysis
Electrolytic Hall-Héroult technology commands premium positioning over vertical shaft methods as automotive OEMs require mass-balance carbon certificates. Three-tier pricing structure across certified low-carbon, standard primary, and secondary scrap-fed grades separates Norsk Hydro REDUXA lines from commodity tonnage. Cost compression in standard primary is intensifying because EU CBAM tightens emissions benchmarks for imported metal. Construction buyers exhibit highest price sensitivity while automotive OEMs absorb premiums for verified below-4-tonne-CO2-per-tonne-Al footprints.
Supply Chain Analysis
Guinea and Australia anchor bauxite refining capacity feeding global alumina supply chains. Smelter operations draw from cryolite electrolyte inputs, carbon anode consumables, and baseload power contracts. Single-source vulnerability concentrates in Guinean bauxite corridors exposed to freight cost spikes and geopolitical interruption. Distribution runs through direct long-term offtake contracts with automotive OEMs and aerospace primes for certified volumes, with regional metal service centers handling residual commodity tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aluminum smelting operates through a cyclical recovery phase as automotive lightweighting mandates absorb record tonnage for electric vehicle platforms and restock depleted inventory channels.
For Market Incumbents: Compound hydropower certification advantages into long-term automotive supply agreements before EU CBAM fully phases in. Defend position by acquiring scrap collection infrastructure in Germany and Japan as EU ETS carbon costs widen the cost gap against primary production. Prioritize power purchase agreement renegotiation to secure renewable baseload supply guarantees for 24/7 electrolytic operations.
For New Entrants and Emerging Players: Differentiate on stranded gas economics in Middle Eastern industrial zones where Emirates Global Aluminium has validated the cost-optimized producer archetype. Target secondary aluminum remelt capacity in European markets where carbon pricing favors recycled feedstock. Enter through joint ventures securing captive renewable supply in Yunnan and Sichuan provinces under China's MEE dual carbon caps.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hydropower-dependent low-carbon specialists with verified automotive contracts over undifferentiated commodity producers. Long-term viability hinges on power-sourcing strategy rather than scale alone. Watch inert anode commercialization timelines as the inflection indicator for zero-carbon primary production economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Power Purchase Agreement | Secures baseload supply for 24/7 electrolytic operations under tightening EU ETS benchmarks. |
| Scrap Collection Infrastructure Acquisition | Captures secondary aluminum growth as carbon pricing favors recycled feedstock in European markets. |
| Inert Anode Technology Development | Eliminates CO2 emissions from reduction process entirely, though technical durability challenges persist. |
| Mass-Balance Carbon Certification | Unlocks premium positioning with German and Japanese tier-1 automotive suppliers requiring verified footprints. |
| Joint Venture for Captive Renewables | Accelerates smelter relocation to Yunnan and Sichuan hydropower corridors under China's MEE enforcement. |
Methodological Framework
Initial hypotheses were tested against primary input from smelter operations directors, automotive procurement leads at OEMs, power utility contract managers, and scrap collection infrastructure operators and refined through secondary validation. Primary fieldwork combined structured interviews with plant managers at electrolytic facilities and procurement directors at tier-1 aluminum suppliers. Secondary sources encompassed customs and trade data from bauxite-exporting jurisdictions, SEC filings from integrated aluminum majors, IEA power market reports, and EU ETS carbon price registries. Bottom-up capacity and utilization estimates were triangulated against top-down demand modeling from automotive production databases.
Variance decomposition separated volume drivers from price realization effects across the projection horizon. The analytical framework modeled segmentation across technology type, product grade tier, end-use industry, and regional power sourcing configuration. CAGRs were derived from installed capacity trajectories, demand elasticity estimates from automotive lightweighting mandates, and carbon cost pass-through assumptions. Forecast inputs incorporated MEE dual carbon cap enforcement timelines, EU CBAM phase-in schedules, and inert anode development milestones.
Material uncertainties — alumina input volatility, power contract renegotiation outcomes, and regulatory divergence between carbon-pricing jurisdictions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding technology adoption curves and policy implementation fidelity. Recalibration cycles align with material shifts in carbon border adjustment mechanisms and commercial inert anode deployment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Motor Lamination Material Market
Metals
Copper and Copper Alloy Scrap and Recycling Market
Metals
Steel Ingots Market
Metals
Steel Sheet for Home Appliances Market
Metals
316 Stainless Steel Container Market
Metals
Bearing Steel Market
Metals
Global Flat Carbon Steel Market
Metals
Shipbuilding Steel Plate Market
Metals
Global Steel Market
Metals
Qatar Metalworking Market
Metals
Steel Drums and Ibcs Market
Metals
Global Stretch Spring Wire Market
Metals
Global Welding Powder Market
Metals
Platinum Group Metals Market
Metals
Steel Drums Market
Metals
US Copper Scrap Market