
 Ferric Sulfate Market | 2026-2036
Ferric Sulfate Market Size, Share, and Industry Trends Forecast 2026-2036
Ferric Sulfate Market Analysis
High-purity liquid-grade specifications is redrawing competitive boundaries in ferric sulfate supply. Kemira Oyj leverages its integrated chlorine-alkali backbone to control feedstock costs across Nordic and North American delivery corridors. Tessenderlo Group anchors European municipal demand through dedicated wastewater chemistry service teams. Hunan Yide Chemical Co., Ltd. dominates spot pricing in Asia-Pacific bulk procurement cycles with captive sulfuric acid supply.
Ferric sulfate is an iron(III) salt with the formula Fe₂(SO₄)₃, typically manufactured through the oxidation of ferrous sulfate or direct reaction of sulfuric acid with iron oxide feedstocks, yielding a coagulant effective across pH ranges from 4 to 11. Its primary commercial purpose centers on destabilizing colloidal suspensions in water and wastewater matrices, enabling solids separation through flocculation and sedimentation. Water treatment applications command the deepest volume pools, while wastewater treatment segments generate premium pricing through customized dosing protocols for nutrient removal. Municipal end users sustain the most predictable offtake rhythms, whereas mining companies concentrate demand seasonally around tailings pond commissioning cycles.
The US EPA enforces Drinking Water Treatment Rules and NPDES permit conditions that directly specify ferric sulfate dosing for arsenic and phosphorus control, shaping product certification requirements for suppliers seeking municipal qualification. China's MEE implements GB 8978 integrated wastewater discharge standards that tighten ferric sulfate performance thresholds for industrial facilities in the Yangtze and Pearl River basins. REACH registration obligations in Europe constrain non-European producers from spot market participation without full substance dossiers. Stakeholders must monitor how evolving PFAS destruction regulations redirect municipal coagulant selection toward ferric sulfate alternatives capable of handling emerging contaminant loads.
Market Dynamics
China's MEE enforcement of GB 8978 discharge standards is compressing supplier margins while simultaneously expanding addressable volume in industrial wastewater treatment across the Yangtze River basin.
Growth Catalysts
- US EPA NPDES permit tightening:Municipal utilities in Ohio and Pennsylvania face phosphorus discharge limits below 0.1 mg/L, mandating ferric sulfate upgrades at over 200 facilities.
- Arsenic remediation protocols:Bangladesh's Department of Environment is deploying ferric sulfate coagulation for groundwater remediation in 61 priority districts.
- Semiconductor fabrication expansion:Ultra-high-purity liquid grades are penetrating wafer fabrication effluent treatment lines in Taiwan and South Korea.
Market Restraints
- Sulfuric acid feedstock volatility:Smelter acid supply disruptions in Chile and Peru transmit directly to ferric sulfate production cost structures.
- REACH registration barriers:Non-European producers lacking full substance dossiers cannot access spot procurement cycles in German or French municipal tenders.
- Aluminum sulfate substitution:Paper mills in Brazil and Indonesia are reverting to alum for sizing applications where pH buffering permits.
Strategic Opportunities
- PFAS destruction co-treatment:US EPA emerging contaminant mandates are redirecting municipal coagulant selection toward ferric sulfate for combined phosphorus-PFAS removal trains.
- Direct-to-utility digital procurement:Nordic municipalities are piloting algorithmic dosing contracts that bypass traditional distributor markups.
- Lithium brine processing:Chilean salar operators are testing ferric sulfate for magnesium impurity precipitation in battery-grade lithium carbonate circuits.
Industry Challenges
- Analytical chemist scarcity:Municipal labs lack personnel to validate ferric sulfate performance under variable raw water quality conditions.
- Legacy ferric chloride infrastructure:Conversion to sulfate chemistry requires tank farm replacement and polymer compatibility testing at water treatment plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ferric Sulfate Market |
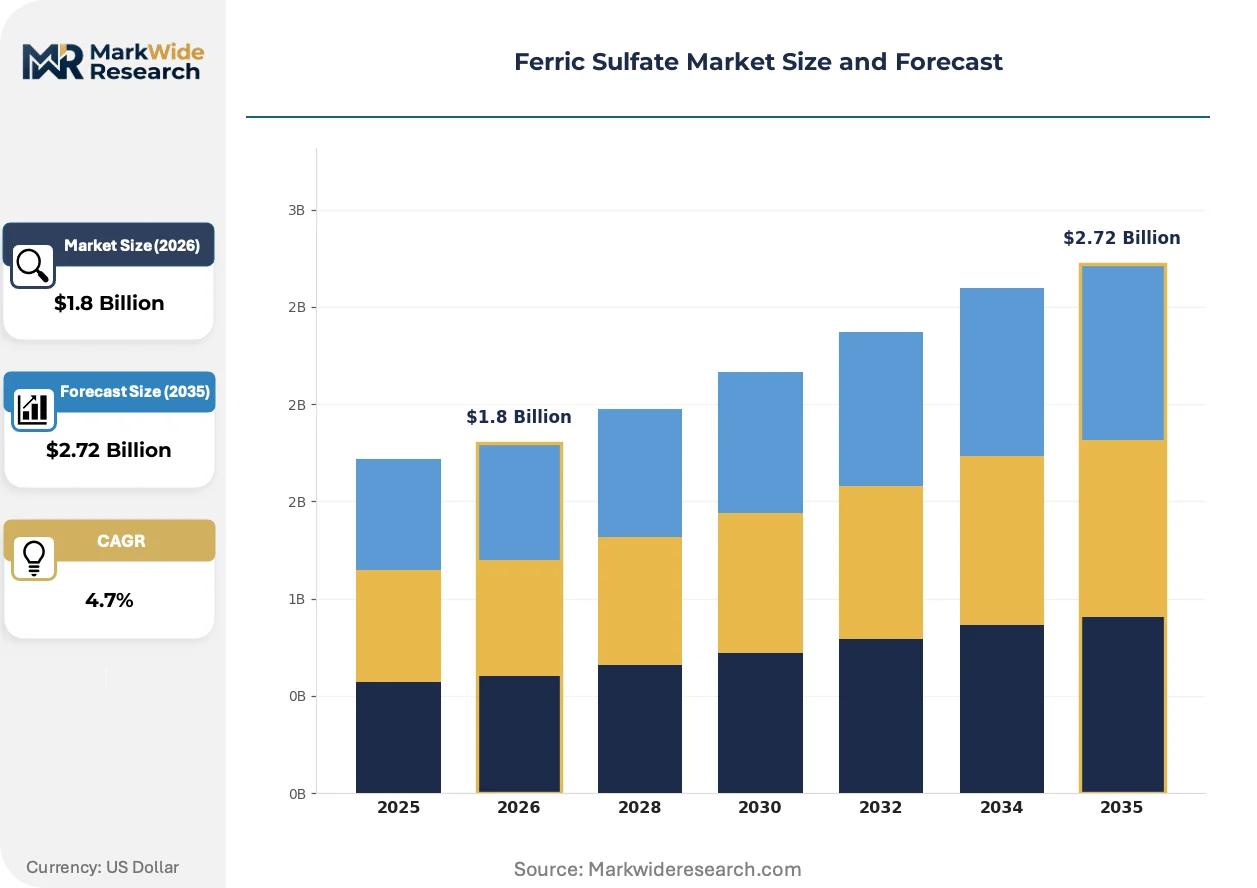
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Water Treatment, Wastewater Treatment, Paper Manufacturing, Mining Product Type: Granular, Liquid, Powder, Solution End User: Municipalities, Industrial Facilities, Chemical Manufacturers, Mining Companies Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Tessenderlo Group, Hunan Yide Chemical Co., Ltd., Kemira Oyj, Altivia Chemicals LLC, Chemtrade Logistics Inc., Pencco Inc., Chemifloc Limited, Airedale Chemical, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ferric Sulfate Market Emerging Trajectories
Continuous oxidation reactor technology is compressing production energy intensity while enabling on-site generation at large municipal facilities.
Membrane electrolysis-based ferric sulfate synthesis is miniaturizing. This electrochemical route eliminates sulfuric acid dependency and generates chlorine as a co-product. Dutch and Singaporean utilities are piloting 50-ton-per-day containerized units for decentralized water treatment. The technology is compressing freight costs and supply security premiums in island and remote municipal markets.
EU F-Gas Regulation phase-down schedules are indirectly elevating ferric sulfate preference in cooling tower blowdown treatment. Operators previously dependent on synthetic polymers face formulation discontinuations. German chemical parks are retrofitting coagulation trains to handle higher ferric sulfate dosing without pH depression.
Specification-driven purchasing is fragmenting buyer segments. Mining companies now contract for seasonal spot volumes with penalty clauses for delivery delays during tailings dam commissioning. Japanese electronics manufacturers demand Certificate of Analysis traceability to iron oxide mine origin. This behavioral shift is compressing commodity-grade pricing power while expanding premium tiers for documented supply chain transparency.
Ferric Sulfate Market Segmentation
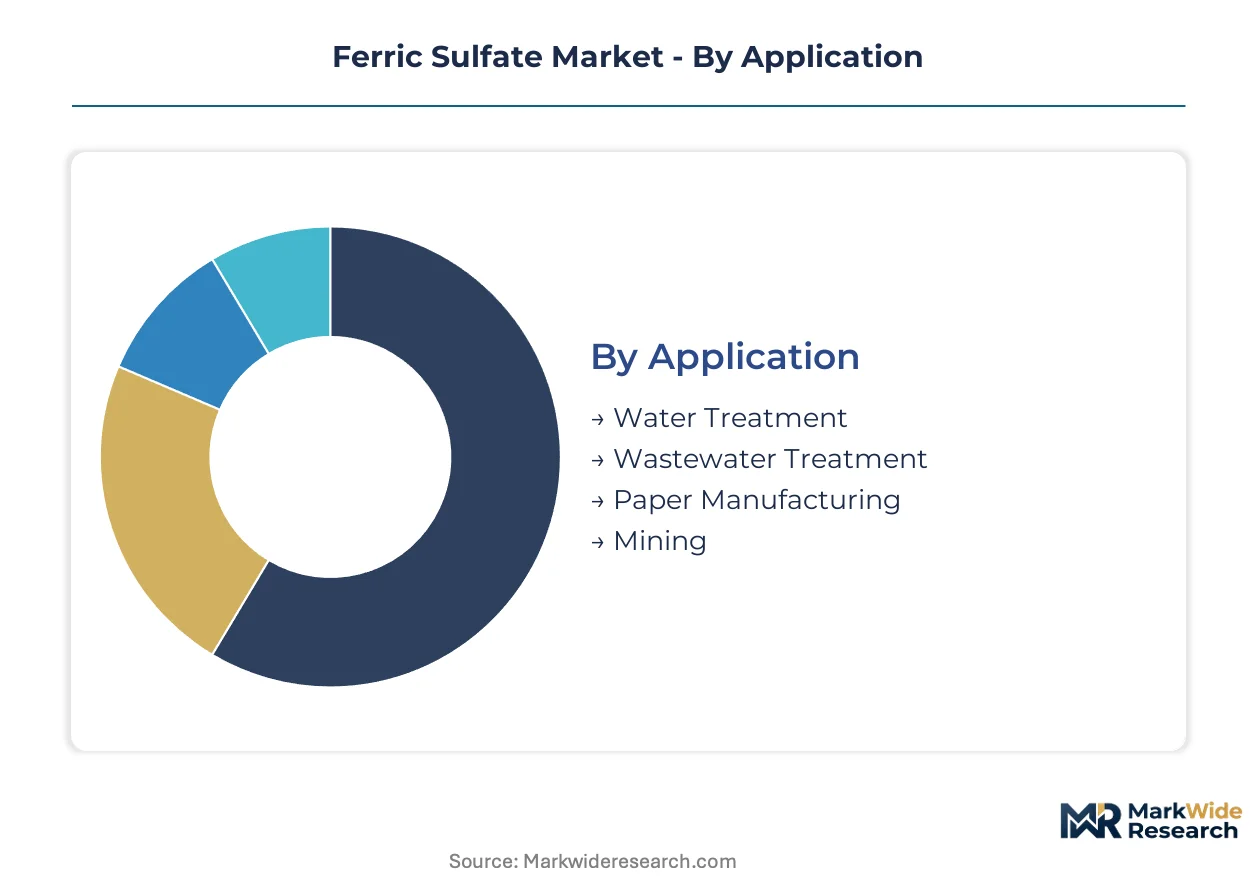
Segmentation in ferric sulfate procurement reflects divergent regulatory pressure points across municipal and industrial discharge regimes. Specification tiers separate commodity bulk buyers from facilities facing contaminant-specific permit conditions.
Application:
US EPA NPDES phosphorus limits and China's GB 8978 discharge standards are fragmenting demand by contaminant removal obligation rather than treatment stage alone.
- Water Treatment:Liquid-grade ferric sulfate dominates surface water clarification for arsenic and turbidity control under US EPA Drinking Water Treatment Rules. Municipal utilities in Bangladesh and Vietnam are expanding coagulation capacity for groundwater arsenic remediation.
- Wastewater Treatment:Nutrient removal trains in Ohio, Pennsylvania, and the Yangtze River basin mandate ferric sulfate dosing below 0.1 mg/L phosphorus discharge thresholds. Premium pricing attaches to customized dosing protocols for combined phosphorus-PFAS removal.
- Paper Manufacturing:Sizing applications favor aluminum sulfate where pH buffering permits; ferric sulfate retains share in effluent color removal.
- Mining:Tailings pond commissioning drives seasonal demand concentration around dam construction cycles in Chilean and Australian operations.
Established volume favors Water Treatment; emerging adoption favors Wastewater Treatment.
Product Type:
Freight economics and on-site storage constraints are concentrating procurement toward forms that minimize handling cost per active iron unit.
- Liquid:High-purity liquid grades penetrate semiconductor fabrication effluent treatment in Taiwan and South Korea, with membrane electrolysis enabling containerized on-site generation at Singaporean and Dutch utilities.
- Granular:Bulk rail and barge shipment to North American municipal facilities minimizes per-ton freight burden for high-volume consumers.
- Powder:Dust control requirements limit adoption to paper mill and chemical manufacturer sites with enclosed handling systems.
- Solution:Intermediate concentration blends serve industrial facilities lacking bulk tank farm infrastructure.
Freight-sensitive buyers gravitate toward Liquid; capital-constrained facilities default toward Solution.
End User:
Contract structure and certification burden separate municipal qualification pathways from industrial spot procurement.
- Municipalities:Multi-year framework agreements with Certificate of Analysis requirements and full supply chain traceability dominate OECD procurement. REACH registration obligations constrain non-European suppliers from German and French tenders.
- Industrial Facilities:Metal plating and textile operations in China's Pearl River basin face tightening MEE enforcement, compressing supplier margins while expanding addressable volume.
- Chemical Manufacturers:Captive sulfuric acid integration enables backward integration into ferric sulfate production for internal consumption.
- Mining Companies:Seasonal spot contracting with penalty clauses for delivery delays during tailings dam commissioning concentrates pricing power with suppliers holding inventory flexibility.
Contract predictability favors Municipalities; margin volatility favors Mining Companies.
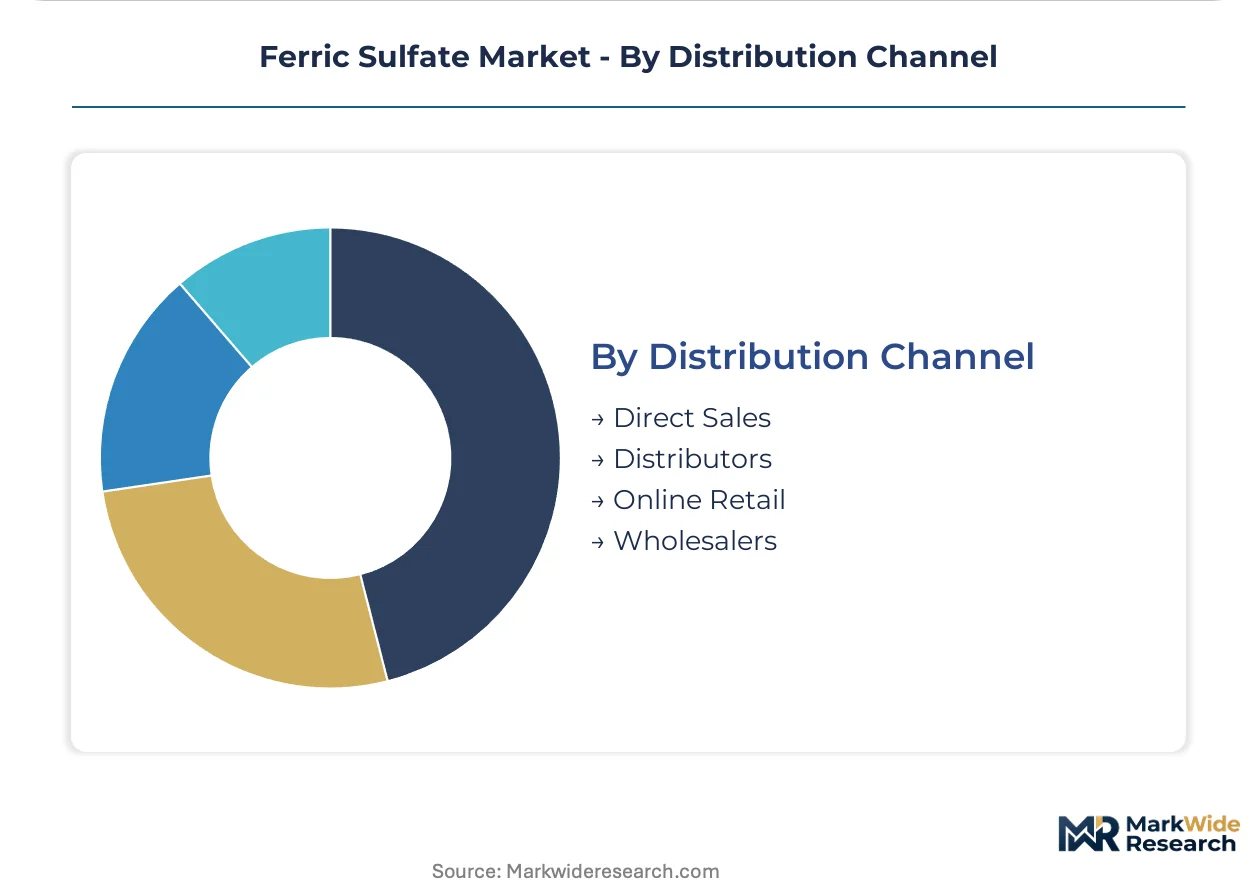
Distribution Channel:
Digital procurement pilots and algorithmic dosing contracts are compressing traditional distributor markups in Nordic municipal markets.
- Direct Sales:Large municipal utilities and mining companies negotiate volume commitments bypassing distributor margins, with technical service bundled into pricing.
- Distributors:Regional chemical distributors retain share in fragmented industrial markets requiring just-in-time delivery and local inventory.
- Online Retail:Small-scale water treatment operators and research facilities procure laboratory and pilot-scale quantities through specialized chemical marketplaces.
- Wholesalers:Bulk aggregation for paper manufacturing and textile clusters in Indonesia and Brazil.
Scale economies favor Direct Sales; fragmentation favors Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in ferric sulfate concentrate around sulfuric acid feedstock availability and municipal procurement sophistication. Nordic producers supply North American utilities through long-term contracts, while Chinese manufacturers dominate spot pricing in Asia-Pacific bulk cycles.
United States
Ohio and Pennsylvania utilities face EPA NPDES phosphorus limits below 0.1 mg/L, compelling ferric sulfate upgrades at over 200 facilities. The EPA Drinking Water Treatment Rules mandate arsenic control specifications that shape supplier certification requirements. Municipal procurement clusters in the Great Lakes region concentrate multi-year framework agreements with full supply chain traceability obligations.
China
Provincial environmental bureaus enforce GB 8978 discharge standards on metal plating and textile operations across the Yangtze and Pearl River basins. The MEE tightens enforcement quarterly, compressing supplier margins while expanding industrial wastewater volume. Hunan-based chemical manufacturers leverage captive sulfuric acid supply to dominate spot pricing in bulk procurement cycles.
Germany
REACH registration obligations constrain non-European producers from German municipal tenders, protecting domestic supplier positions. The EU F-Gas Regulation phase-down elevates ferric sulfate preference in cooling tower blowdown treatment as synthetic polymer formulations discontinue. Chemical parks in the Rhine-Ruhr region retrofit coagulation trains for higher ferric sulfate dosing without pH depression.
Netherlands
Dutch utilities pilot membrane electrolysis-based ferric sulfate synthesis in 50-ton-per-day containerized units for decentralized water treatment. The technology eliminates sulfuric acid dependency and generates chlorine as co-product. Rotterdam-area facilities compress freight costs and supply security premiums through on-site generation.
Bangladesh
The Department of Environment deploys ferric sulfate coagulation for groundwater arsenic remediation across 61 priority districts. Development finance institutions fund municipal treatment capacity expansion in rural sub-districts. Dhaka-based procurement offices coordinate bulk import contracts with Nordic and Middle Eastern suppliers.
Ferric Sulfate Market Vendor Landscape
Listed leaders compete with private specialists across feedstock integration and municipal qualification pathways. The vendor base separates into sulfuric acid-integrated producers, municipal service bundlers, and regional spot suppliers. Three archetypes dominate: chlorine-alkali backbone operators controlling feedstock costs, wastewater chemistry service teams anchoring European municipal demand, and captive acid suppliers dominating Asia-Pacific bulk cycles. Competitive moves concentrate on backward integration into sulfuric acid supply and digital procurement platform development.
Within the integrated chemical backbone tier, Kemira Oyj and Tessenderlo Group exemplify divergent geographic anchoring strategies. Hunan Yide Chemical Co., Ltd. occupies a position representing captive feedstock advantage in spot-driven procurement environments. These three entities illustrate how feedstock control, service bundling, and regional scale respectively define sustainable positioning.
| Leading Market Players |
|---|
| Tessenderlo Group |
| Hunan Yide Chemical Co., Ltd. |
| Kemira Oyj |
| Altivia Chemicals LLC |
| Chemtrade Logistics Inc. |
| Pencco Inc. |
| Chemifloc Limited |
| Airedale Chemical |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between Nordic producers and North American municipal utilities lock in both sulfuric acid feedstock access and price visibility across multi-year procurement cycles. These contracts insulate buyers from spot volatility while anchoring supplier margins through volume commitments.
Pricing Analysis
Industrial OEM buyers anchor commodity-grade ferric sulfate pricing through high-volume, low-margin contracts that compress spot premiums. Pricing stratifies across high-purity liquid grades for semiconductor fabrication, standard municipal liquid specifications, and economy granular forms for mining tailings applications. Cost compression in the standard tier is intensifying because captive sulfuric acid producers in China flood Asia-Pacific spot markets. Municipal utilities show least price sensitivity due to regulatory compliance mandates, while paper manufacturers exhibit highest sensitivity and revert to aluminum sulfate where pH conditions permit.
Supply Chain Analysis
Strait of Malacca transit underwrites sulfuric acid feedstock flows from Middle Eastern smelters to Asian ferric sulfate manufacturers. Production concentrates in China, Finland, and the United States, with each hub drawing from distinct sulfuric acid supply bases—captive smelter acid in China, chlorine-alkali integration in Finland, and merchant acid markets in the United States. The supply chain rests on sulfuric acid price volatility as its primary structural risk, with Chilean and Peruvian smelter disruptions transmitting directly to production economics. Distribution runs through regional chemical distributors for fragmented industrial accounts, while direct sales dominate large municipal and mining contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane electrolysis-based ferric sulfate synthesis represents a technological inflection that disrupts traditional sulfuric acid-dependent production economics and enables decentralized, on-site generation at municipal scale.
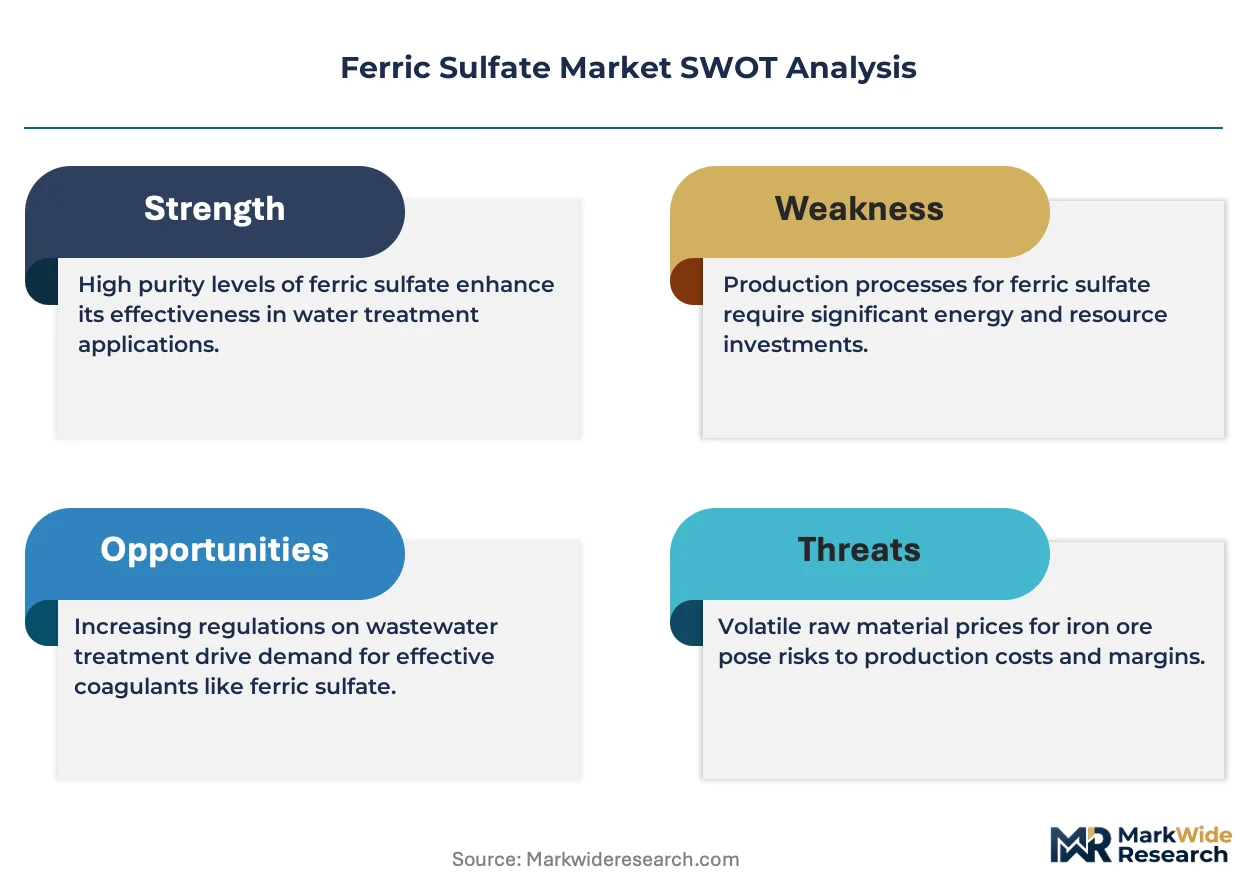
For Market Incumbents: Shield municipal qualification positions by accelerating REACH dossier completion for European market access and investing in membrane electrolysis pilot capacity before technology diffusion erodes sulfuric acid integration advantages. Aluminum sulfate substitution in paper applications and Chinese spot-price competition constitute immediate margin threats; backward integration into chlorine-alkali feedstocks offers the most durable defensive lever. For New Entrants and Emerging Players: Lead with containerized, membrane electrolysis-based production systems targeting island and remote municipal markets where freight costs and supply security premiums concentrate willingness-to-pay. Bangladesh's arsenic remediation program and Vietnam's groundwater treatment expansion represent the most penetrable geographies lacking established supplier relationships. A direct-to-utility digital procurement platform bypassing traditional distributor markups offers the clearest go-to-market angle. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors asset-light, electrochemical process innovators over legacy sulfuric acid-integrated producers. Five-to-ten year viability favors firms with demonstrated membrane electrolysis scale-up and municipal qualification pathways. Acquisition targets should show captive feedstock positions or proven on-site generation deployment; the signal to watch is EPA PFAS destruction mandate implementation accelerating ferric sulfate preference over alternative coagulants.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Electrolysis Scale-Up | Enables sulfuric acid-independent production with chlorine co-generation at Dutch and Singaporean utilities. |
| REACH Dossier Completion | Unlocks German and French municipal tenders currently closed to non-European producers lacking full substance registration. |
| Digital Procurement Platform | Nordic algorithmic dosing contracts demonstrate path to bypass distributor markups in fragmented municipal markets. |
| Backward Integration into Sulfuric Acid | Hunan-based captive acid supply anchors margin control in Asia-Pacific spot procurement cycles. |
| PFAS Co-Treatment Certification | US EPA emerging contaminant mandates redirect municipal selection toward ferric sulfate for combined removal trains. |
Methodological Framework
A standing panel of municipal water treatment plant managers, industrial wastewater facility engineers, chemical distribution procurement leads, and membrane electrolysis technology developers provided ongoing calibration across primary interview rounds. Secondary validation drew from US EPA NPDES permit filings, China MEE discharge standard enforcement bulletins, EU ECHA REACH registration databases, and customs trade flow records. Bottom-up volume estimates by application and grade tier were triangulated against top-down producer capacity assessments.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across application type, product form, end-user contract structure, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating municipal capital expenditure cycles, industrial discharge enforcement intensity, and technology substitution elasticities. Key inputs included EPA phosphorus limit implementation schedules and MEE quarterly enforcement tightening patterns.
Underlying assumptions cover sustained regulatory enforcement of phosphorus and arsenic discharge limits, with deviation risk concentrated in sulfuric acid feedstock supply disruptions and accelerated aluminum sulfate substitution in paper applications. Practitioners should keep alternative scenarios live as membrane electrolysis technology cost curves and PFAS destruction regulatory scope evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Ground Calcium Carbonate Market
Bulk Chemicals
Propionic Acid Market
Bulk Chemicals
Sodium Sulfide Market
Bulk Chemicals
Diisopropylbenzene Market
Bulk Chemicals
Asia Pacific Dry PVC Compound Market
Bulk Chemicals
Global Plastics Market
Bulk Chemicals
Precipitated Barium Sulphate Market
Bulk Chemicals
Cresylic Acid Market
Bulk Chemicals
Methyl Mercaptan Market
Bulk Chemicals
Magnesium Chloride Market
Bulk Chemicals
Antimony Trioxide Market
Bulk Chemicals
Middle East Formaldehyde Market
Bulk Chemicals
Bulk Molding Compounds Market
Bulk Chemicals
Zinc Carbonate Market
Bulk Chemicals
Phosphorus and Derivatives Market
Bulk Chemicals
Encapsulated Sodium Bicarbonate Market