
 7075 T6 Aluminum Market | 2026-2036
7075 T6 Aluminum Market Size, Share, and Industry Trends Forecast 2026-2036
7075 T6 Aluminum Market Insights
China is narrowing its dependence on imported high-strength aluminum billet through domestic T6 tempering investments. Kaiser Aluminum leverages captive aerospace forging relationships across North American defense programs. Hindalco Industries anchors South Asian supply for aircraft structural extrusions.
7075 T6 aluminum designates a precipitation-hardened alloy containing zinc, magnesium, and copper as principal alloying elements, with T6 indicating solution heat treatment followed by artificial aging to achieve tensile strengths exceeding 570 MPa for critical load-bearing structures. Aerospace applications dominate volume consumption due to airframe weight reduction mandates, while defense hardware procurement sustains premium pricing for certified plate and bar stock. Extruded forms lead commercial shipments, though forged components capture disproportionate margin pools in military landing gear and wing spar assemblies.
FAA airworthiness directives and EASA certification standards govern material qualification for commercial aviation, compelling producers to maintain Nadcap-accredited heat treatment records. China's NMPA and GB/T standards enforce parallel traceability for civil aircraft programs, creating dual-compliance burdens for multinational suppliers. Stakeholders must monitor evolving alloy substitution pressures from carbon fiber composites in next-generation airframe designs.
Market Dynamics
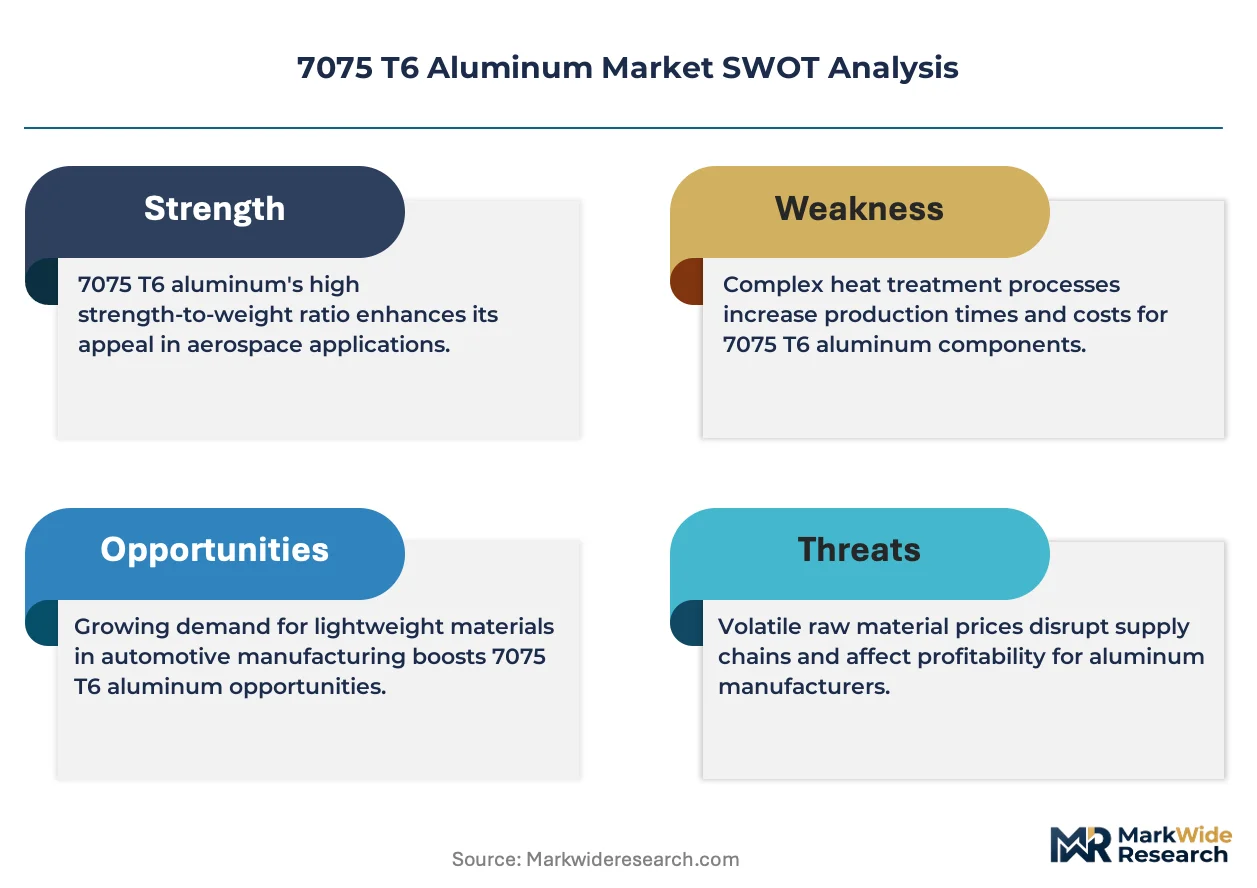
Aerospace airframe weight reduction mandates are compressing design cycles and forcing mill producers to accelerate T6 tempering throughput while maintaining Nadcap heat treatment traceability.
Growth Catalysts
- FAA Airworthiness Directives:Certification requirements for commercial aviation sustain premium demand for certified plate and bar stock with documented heat treatment records.
- Defense Hardware Procurement:Military landing gear and wing spar assembly programs lock in long-term contracts for forged 7075 T6 components.
- China's NMPA Civil Aircraft Programs:Parallel GB/T standards enforcement creates dual-compliance demand that expands qualified supplier rosters.
Market Restraints
- Zinc Input Volatility:Principal alloying element price swings compress margin predictability for precipitation-hardened alloy production.
- Carbon Fiber Substitution Pressure:Composite airframe designs in next-generation commercial programs threaten structural aluminum volume in wing boxes.
- Dual-Certification Burden:EASA and FAA parallel qualification requirements extend material approval timelines for multinational suppliers.
Strategic Opportunities
- Urban Air Mobility Airframes:Electric vertical take-off and landing vehicle manufacturers require certified high-strength extrusions for lightweight structural members.
- India's PLI Scheme for Aerospace:Domestic aircraft structural extrusion incentives attract capacity investment for regional supply base development.
- Scrap Closed-Loop Integration:Aerospace forging relationships enable captive recycling streams that reduce virgin billet dependence.
Industry Challenges
- Nadcap Heat Treatment Auditor Scarcity:Accredited technician pipelines constrain throughput expansion for aerospace-qualified mills.
- Legacy ERP Integration:Digital traceability requirements for GB/T and FAA dual compliance force expensive MES overlay deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 7075 T6 Aluminum Market |
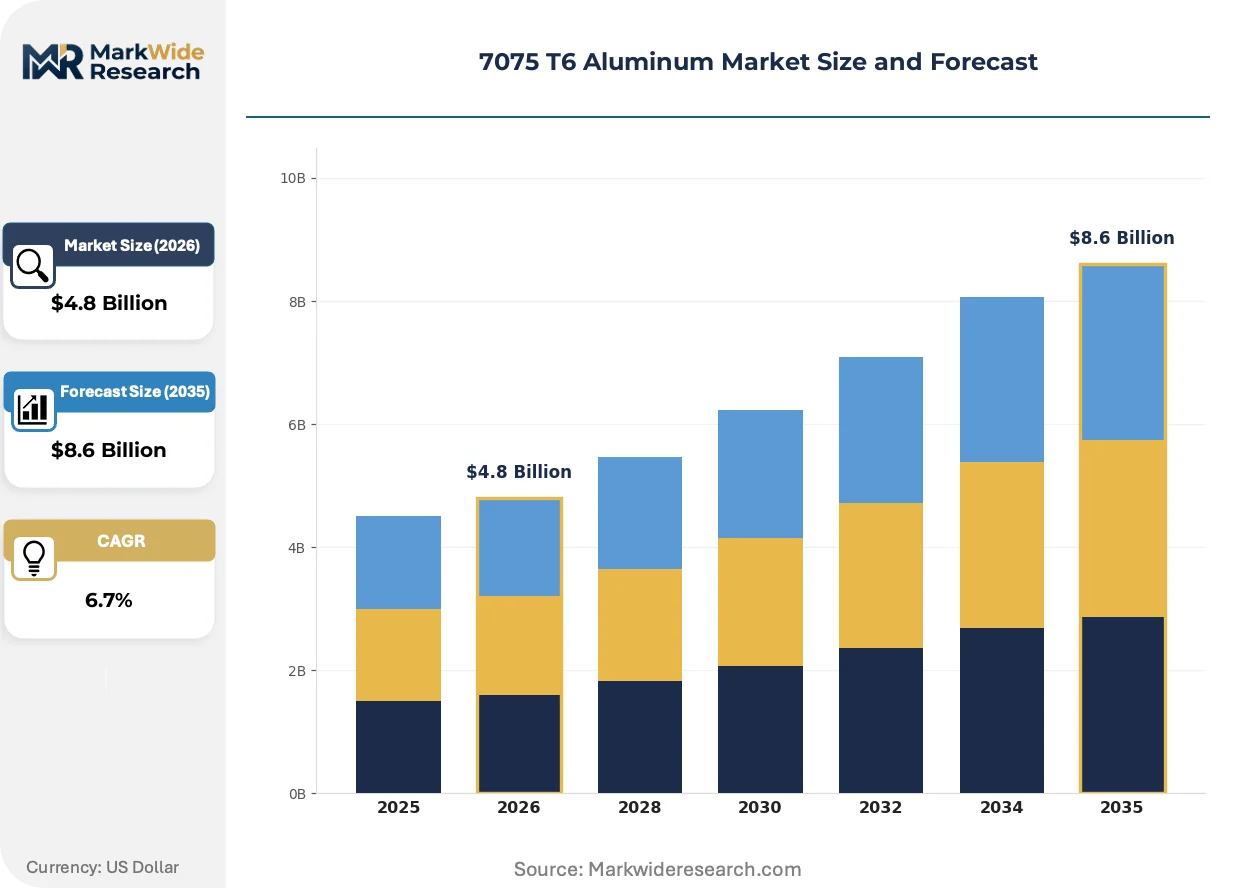
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheets, Plates, Bars, Rods, Foils Application: Aerospace, Sports Equipment, Marine Components, Electrical Equipment, Defense Hardware Form: Extruded, Rolled, Cast, Forged, Machined End User Industry: Aircraft Manufacturers, Shipbuilders, Electronics Producers, Military Suppliers, Recreational Goods |
| Companies Covered | Alcoa Corporation, Kaiser Aluminum, Novelis, Constellium, Emirates Global Aluminium, Hindalco Industries, Aluminum Corporation of China, China Hongqiao Group, Norsk Hydro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
7075 T6 Aluminum Market Trends and Innovations
Continuous T6 tempering line automation and digital twin process control are compressing lead times while tightening mechanical property variance bands for critical load-bearing applications.
Direct-chill casting combined with inline homogenization is rendering obsolete batch furnace approaches for aerospace billet production. Tier 1 forging houses in Germany and Japan are adopting these integrated lines to meet airframe OEM compressed development cycles. The technology is rendering obsolete traditional two-step processing that required separate solution heat treatment and artificial aging stages.
China's GB/T 3880 series updates and NMPA civil aircraft material qualification protocols now mandate blockchain-anchored heat treatment records. This regulatory shift forces multinational suppliers to deploy parallel traceability systems for domestic and export production streams. European mills serving COMAC programs are responding by localizing T6 processing capacity within mainland facilities.
Airframe OEMs are consolidating supplier rosters around vertically integrated mills capable of extrusion, forging, and heat treatment under single Nadcap accreditation. Long-term offtake agreements with minimum volume guarantees are replacing spot market purchases for certified 7075 T6 plate. This concentration is most visible in United States defense programs where Lockheed Martin and Boeing have reduced qualified billet sources to three primary mills since 2022.
7075 T6 Aluminum Market Segmentation
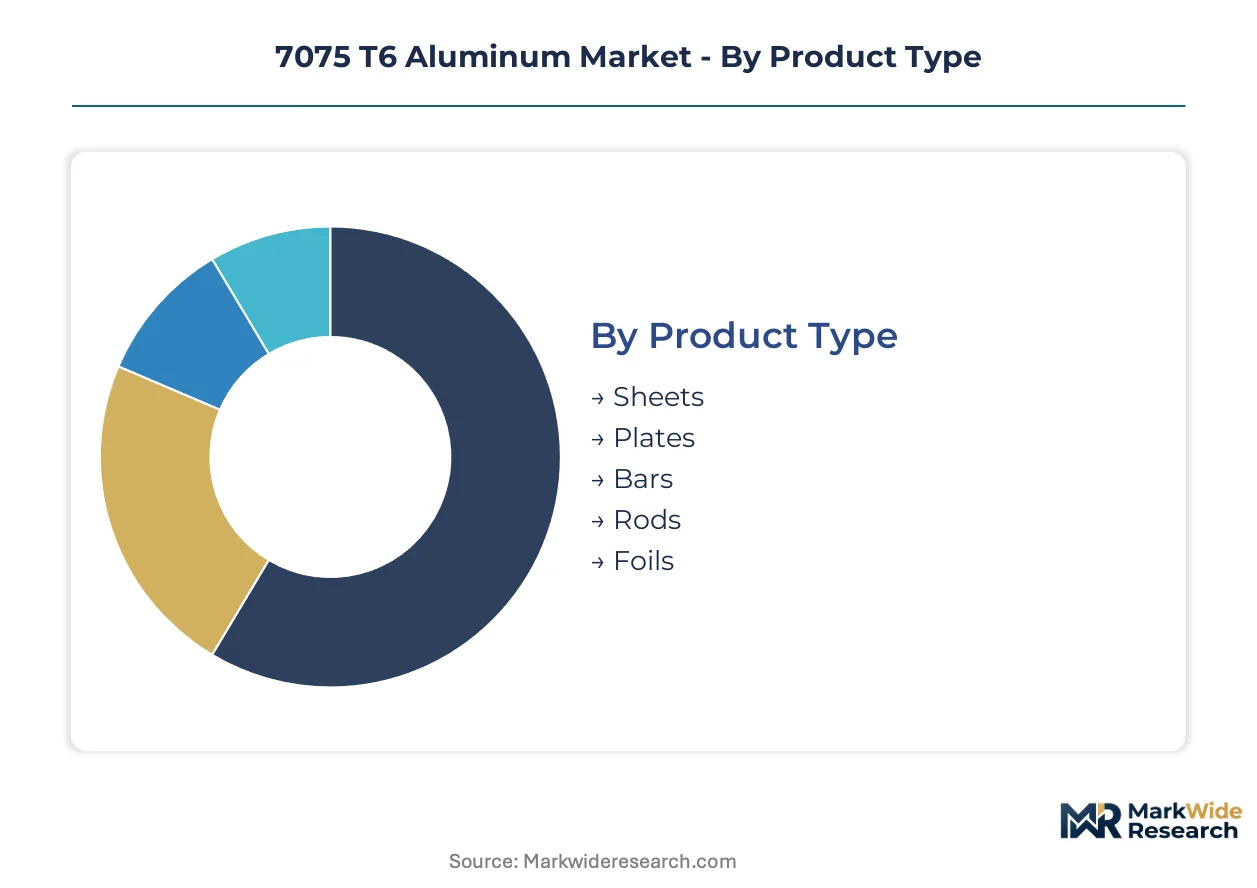
7075 T6 aluminum demand fragments across product geometries and certification grades that dictate heat treatment protocols. Each segment carries distinct Nadcap audit burdens and end-use qualification timelines that reshape supplier economics.
Product Type:
After-sales service intensity varies sharply across product geometries, with aerospace plate requiring decades of heat treatment record retention versus commodity rod.
- Sheets:Thin-gauge flat-rolled product specified for aircraft skin panels and structural fairings. Boeing and Airbus fuselage programs in the United States and Germany concentrate demand, though carbon fiber substitution in next-generation wing boxes constrains volume expansion.
- Plates:Thick-section material exceeding 6mm thickness used for bulkheads, wing ribs, and landing gear trunnions. Defense procurement in the United States and civil aircraft qualification in China drive premium pricing for certified plate with documented solution heat treatment cycles.
- Bars:Longitudinal stock for machining into structural fittings and control linkages.
- Rods:Round cross-section material deployed in tension members and fastener blanks.
- Foils:Ultra-thin gauge below 0.2mm serving specialized electrical shielding and honeycomb core bonding layers.
By volume, plates lead. By growth pace, sheets are climbing fastest as urban air mobility airframes scale.
Application:
Application-driven cost tiers separate aerospace-certified material from commercial-grade supply, with certification burden determining margin capture.
- Aerospace:Airframe structures, landing gear, and control surfaces requiring FAA or EASA material qualification. Germany, Japan, and the United States concentrate OEM demand, while China's COMAC programs expand qualified supplier rosters through NMPA certification protocols.
- Sports Equipment:Bicycle frames, climbing hardware, and competitive archery equipment leveraging strength-to-weight ratios. Japanese and Italian manufacturers drive premium extrusion demand for performance cycling components.
- Marine Components:Hull structures and mast fittings for high-performance sailing vessels.
- Electrical Equipment:Bus bars and heat sinks exploiting thermal conductivity alongside mechanical strength.
- Defense Hardware:Armored vehicle structures and weapons systems subject to ITAR-controlled supply chains.
Aerospace commands the highest revenue share. Defense hardware is expanding most quickly amid rearmament programs across NATO members.
Form:
Form selection dictates capital intensity, with forging presses and continuous extrusion lines representing divergent equipment commitments.
- Extruded:Longitudinal profiles produced by forcing billet through shaped dies, dominating commercial shipment volumes. Kaiser Aluminum and Hindalco Industries anchor North American and South Asian supply for aircraft structural extrusions.
- Rolled:Flat products reduced through sequential mill passes, capturing plate and sheet categories.
- Cast:Near-net-shape components solidified in molds for subsequent T6 tempering.
- Forged:Compressively worked material for critical load-bearing applications including wing spars and landing gear.
- Machined:Finish-machined components delivered to final dimensional tolerances.
Extruded forms ship the most tonnage. Forged components gain share fastest as airframe OEMs consolidate around vertically integrated suppliers.
End User Industry:
Customer-type concentration shapes contract structures, with aircraft manufacturers locking in multi-year offtake agreements unlike fragmented recreational goods.
- Aircraft Manufacturers:Boeing, Airbus, and COMAC driving qualified material demand with Nadcap-accredited supplier requirements. Tier 1 forging houses in Germany and Japan are adopting integrated continuous T6 tempering lines to meet compressed OEM development cycles.
- Shipbuilders:Naval and commercial vessel constructors specifying high-strength alloys for weight-critical superstructures.
- Electronics Producers:Thermal management and structural chassis applications in telecommunications infrastructure.
- Military Suppliers:Prime contractors and subcontractors subject to defense procurement regulations.
- Recreational Goods:Dispersed manufacturers of sporting equipment with lower certification barriers.
Aircraft manufacturers absorb the largest volume. Military suppliers are climbing fastest amid procurement acceleration in the United States and European NATO members.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA airworthiness directives anchor demand concentration in the United States, while EASA certification standards and China's NMPA protocols create parallel compliance corridors that reshape supplier geography.
United States
Boeing and Lockheed Martin drive certified plate consumption for commercial and defense airframes. FAA mandates documented Nadcap heat treatment records for all structural alloys. Kaiser Aluminum anchors supply from its Tennessee and Washington operations, serving long-term defense procurement contracts.
Germany
Airbus fuselage programs and Tier 1 forging houses compress development cycles for T6 tempering throughput. EASA qualification requirements parallel FAA standards for multinational suppliers. Bavarian and North Rhine-Westphalian mills adopt continuous tempering lines to meet OEM delivery windows.
China
COMAC civil aircraft expansion and NMPA certification protocols tighten material traceability for domestic programs. GB/T 3880 series updates mandate blockchain-anchored heat treatment records. Yangtze River Delta and Shandong Peninsula facilities localize T6 processing capacity for export and domestic streams.
Japan
Mitsubishi Heavy Industries and Subaru anchor aerospace structural extrusion demand for regional jet programs. METI industrial standards align with JIS certification for high-strength alloys. Nagoya and Osaka industrial clusters concentrate precision forging capacity for wing spar assemblies.
India
Hindalco Industries scales aircraft structural extrusion capacity under PLI scheme incentives for aerospace manufacturing. DGFT import substitution policies narrow dependence on high-strength billet imports. Gujarat and Maharashtra host emerging forging and extrusion complexes serving South Asian supply chains.
7075 T6 Aluminum Market Competitive Landscape
Capability concentration sits with vertically integrated mills possessing Nadcap-accredited heat treatment and forging capacity; scale advantage sits with diversified aluminum producers serving multiple alloy grades. The vendor base stratifies into three tiers: aerospace-certified specialists, diversified industrial mills, and regional extrusion houses. Consolidation pressures favor backward integration into billet casting and captive recycling streams. Long-term offtake agreements with minimum volume guarantees displace spot market purchases.
Among North American aerospace specialists, Kaiser Aluminum exemplifies the certified-tier archetype through captive forging relationships. Alcoa Corporation and Constellium occupy positions bridging industrial scale with aerospace qualification depth. Emirates Global Aluminium and Hindalco Industries represent the geographic diversification vector, anchoring supply from Middle Eastern and South Asian production bases respectively.
| Leading Market Players |
|---|
| Alcoa Corporation |
| Kaiser Aluminum |
| Novelis |
| Constellium |
| Emirates Global Aluminium |
| Hindalco Industries |
| Aluminum Corporation of China |
| China Hongqiao Group |
| Norsk Hydro |
| Others |
Pricing and Supply Chain Analysis
Zinc concentrate supply from Australian and Peruvian mining operations anchors raw material costs for precipitation-hardened alloy production, with downstream margin pools concentrating in Nadcap-accredited heat treatment and forging tiers where certification scarcity sustains premium capture.
Pricing Analysis
North American certified plate commands price spreads over Asian commercial-grade extrusions, reflecting FAA and EASA qualification burdens. Three-tier pricing structure across aerospace-certified, industrial-grade, and commodity spot levels separates margin capture. Pricing pressure stems from carbon fiber substitution in next-generation wing boxes. Recreational goods manufacturers exhibit highest price sensitivity; defense procurement programs demonstrate lowest.
Supply Chain Analysis
Contract manufacturing concentration rests with Tier 1 forging houses in Germany, Japan, and the United States holding Nadcap-accredited capacity. Billet casting draws from primary aluminum smelters in Canada, Russia, and the Middle East. Zinc and magnesium alloying elements introduce commodity price volatility risk. Distribution runs through long-term offtake agreements with airframe OEMs rather than spot market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense procurement acceleration and commercial aviation order backlogs position this market in cyclical recovery, with airframe OEM consolidation around qualified suppliers reinforcing contract visibility.
For Market Incumbents: Insulate margin pools through captive recycling streams that reduce virgin zinc billet exposure. Secure Nadcap auditor pipelines against accreditation bottlenecks. Carbon fiber substitution in wing box applications threatens structural aluminum volume; backward integration into continuous T6 tempering lines preserves throughput advantage. For New Entrants and Emerging Players: Establish a beachhead in urban air mobility extrusion demand where certification barriers remain lower than commercial aviation. India's PLI scheme incentives for aerospace manufacturing offer penetrable geographic entry. Target aftermarket service intensity for legacy aircraft heat treatment record retention. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated mills possessing Nadcap-accredited forging and heat treatment under single accreditation. Long-term viability over a multi-year horizon hinges on defense procurement continuity. Watch COMAC supplier roster expansion as inflection signal for Chinese domestic qualification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Nadcap Accreditation Investment | FAA and EASA qualification requirements lock in premium pricing for certified plate and bar stock. |
| Continuous T6 Tempering Line Deployment | Inline homogenization compresses lead times for Boeing and Airbus compressed development cycles. |
| Scrap Closed-Loop Integration | Aerospace forging relationships enable captive recycling streams reducing virgin billet dependence. |
| Blockchain-Anchored Traceability System | China's GB/T 3880 updates mandate parallel record systems for domestic and export production streams. |
| Urban Air Mobility Supply Agreement | Electric vertical take-off vehicle manufacturers require certified high-strength extrusions for structural members. |
Research Methodology
Operator-level perspectives from aerospace procurement managers, heat treatment technicians, Tier 1 forging house operations directors, and Nadcap accreditation auditors anchored the qualitative base. Secondary validation drew from FAA airworthiness directives, EASA certification standards, COMAC supplier qualification documents, and customs trade data for aluminum alloy shipments. Bottom-up alloy consumption estimates triangulated against top-down airframe production forecasts.
Scenario-bracketing framed volume projections across the analysis window, with segmentation dimensions spanning product geometry, certification grade, end-use application, and regional regulatory cluster. CAGRs derived from airframe OEM delivery schedules and defense procurement pipeline visibility. Zinc price volatility bands and carbon fiber substitution curves served as industry-specific demand modifiers.
Stress conditions across zinc input costs, Nadcap auditor availability, and COMAC supplier roster expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding defense procurement continuity and airframe weight reduction mandate persistence. Quarterly review of urban air mobility order flow and China's NMPA certification queue depth is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Precious Metal Market
Metals
Stainless Steel Panels Market
Metals
Zinc Dust Market
Metals
Rare Earth Metals Market
Metals
Carbotanium Market
Metals
Metal Recycling Market
Metals
Steel Drums Market
Metals
Titanium Sponge Market
Metals
GCC Aluminium Powder Market
Metals
Aluminum Welding Market
Metals
High Purity Base Metals Market
Metals
Aluminum Wire Market
Metals
Aluminium Conductors Market
Metals
Recycled Metal Market
Metals
Bearing Steel Market
Metals
Weathering Steel Market