
 Merchant Bar Quality (MBQ) Steel Market | 2026-2036
Merchant Bar Quality (MBQ) Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Merchant Bar Quality (MBQ) Steel Market Insights
Maintenance-service contracts for rebar threading and on-site bending equipment are decoupling capital sales from recurring revenue streams across the merchant bar value chain. ArcelorMittal leverages its European service-center network to bundle fabrication support with tonnage commitments. Nucor Corporation anchors its southeastern US position through direct mill-to-job-site logistics programs that bypass traditional distributor tiers. POSCO competes in premium-grade segments with heat-treatable bar products certified for offshore platform applications.
Merchant Bar Quality steel denotes long-product rounds, flats, angles, channels, and squares produced to ASTM A36, A529, or equivalent specifications with controlled chemistry and dimensional tolerances for secondary forming rather than direct structural loading. Hot rolled steel dominates volume flows through infrastructure projects and heavy equipment channels, while cold rolled and annealed variants command margin premiums in precision fabrication workshops requiring tight bend radii and uniform surface finish. Galvanized steel is expanding fastest in coastal construction hardware and shipbuilding end-user industries where atmospheric corrosion resistance reduces lifecycle maintenance costs.
ASTM International sets mechanical property baselines that govern US procurement specifications for federal and state infrastructure contracts, while China's SAMR enforces GB/T 700 and GB/T 1591 standards that restrict uncertified mill access to domestic project bids. India's BIS marking requirement under the Steel Quality Control Order creates compliance barriers for imported merchant bar products entering fabrication workshops and power plant construction sites. Stakeholders must monitor how carbon-border adjustment mechanisms and evolving scrap-content thresholds reshape sourcing economics for electric-arc-furnace versus blast-furnace route producers.
Market Dynamics
China's SAMR enforcement of GB/T 1591 certification requirements is forcing long-product mills to upgrade melt-shop controls and reshape sourcing economics for electric-arc-furnace route producers competing against blast-furnace incumbents.
Growth Catalysts
- Infrastructure Absorption:Bridge decking and structural framing projects across Vietnam, Indonesia, and the Philippines are pulling merchant bar tonnages into fabrication workshops clustered near port facilities.
- REACH Compliance Spillover:European fabricators importing MBQ steel for machinery frames now require mill certificates documenting scrap content and carbon intensity, extending supply-chain visibility upstream.
- Heat-Treatable Bar Certification:Offshore platform specifications for quenched-and-tempered rounds are opening premium segments where chemistry control and ultrasonic testing justify margin premiums.
Market Restraints
- Scrap Price Volatility:Electric-arc-furnace producers face margin compression when shredded auto scrap and busheling prices spike, locking in raw material exposure that blast-furnace route competitors avoid through iron ore contracts.
- BIS Marking Barriers:India's Steel Quality Control Order restricts uncertified mill access to power plant construction and fabrication workshop bids, creating compliance costs for imported merchant bar.
- Substitution Pressure:Hollow structural sections and cold-formed steel framing are displacing traditional angle and channel configurations in low-rise commercial construction.
Strategic Opportunities
- Western India Corridor:Fabrication workshops from Gujarat through Maharashtra lack sufficient domestic MBQ capacity, creating white space for service-center investments with direct mill-to-job-site logistics.
- Galvanized Coastal Hardware:Atmospheric corrosion resistance specifications for shipbuilding and marine construction are expanding zinc-coated bar and angle demand.
- Maintenance-Service Unbundling:Rebar threading and on-site bending equipment contracts are decoupling capital sales from recurring revenue streams across the value chain.
Industry Challenges
- Dimensional Tolerance Expertise:Precision fabrication workshops require operators capable of interpreting ASTM A36 and A529 chemistry certificates and managing tight bend radii specifications.
- Certification Timeline Compression:GB standards tightening and carbon-border adjustment mechanisms are compressing the window for mills to achieve dual certification for domestic and export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Merchant Bar Quality (MBQ) Steel Market |
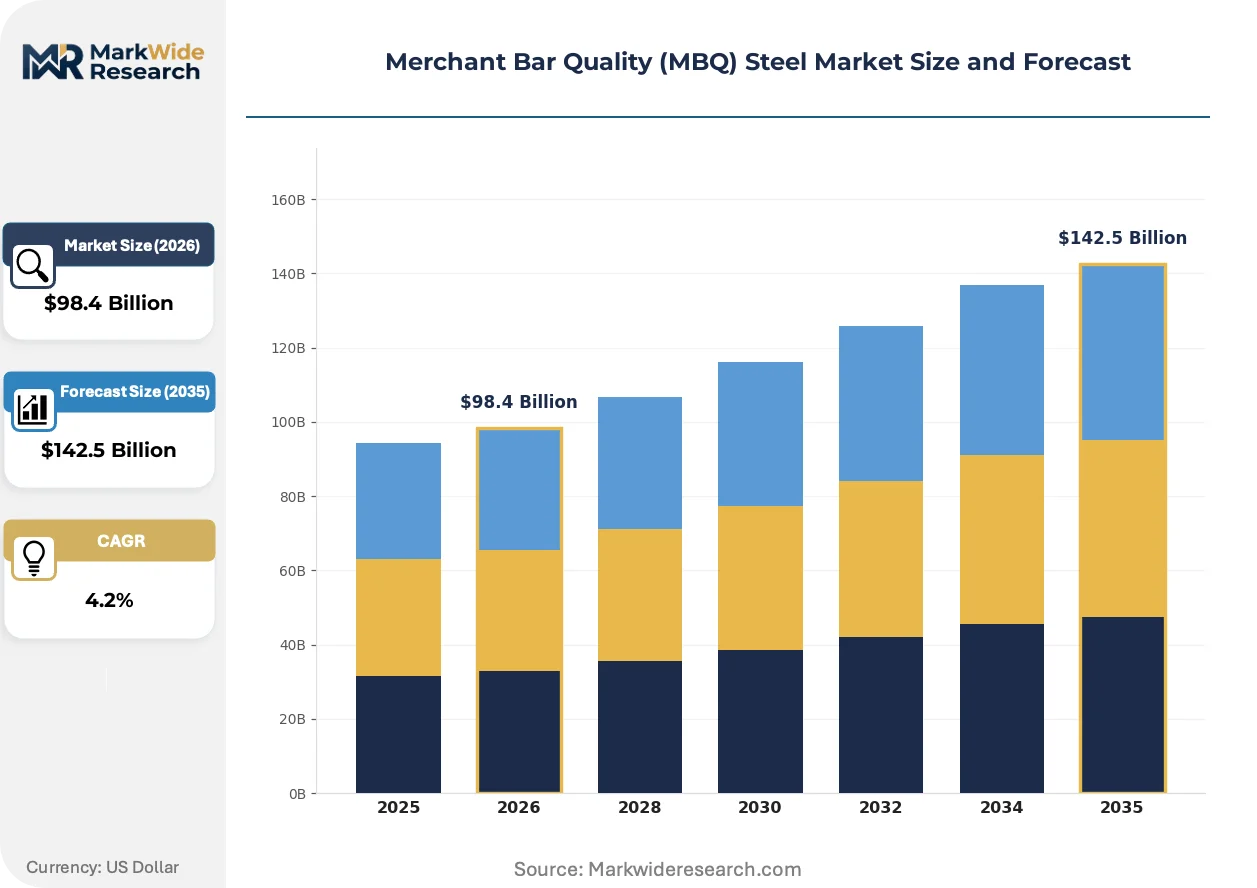
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $142.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Rolled Steel, Cold Rolled Steel, Galvanized Steel, Annealed Steel Application: Infrastructure Projects, Heavy Equipment, Fabricated Components, Construction Hardware End User Industry: Shipbuilding, Machinery Manufacturing, Power Plants, Fabrication Workshops Distribution Channel: Direct Sales, Steel Distributors, Online Platforms, Local Dealers |
| Companies Covered | Tata Steel, Gerdau S.A., ArcelorMittal, Steel Dynamics, Inc., POSCO, Nucor Corporation, Nippon Steel Corporation, JSW Steel, China Baowu Steel Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Merchant Bar Quality (MBQ) Steel Market Trends and Innovations
Digital melt-shop controls and secondary metallurgy investments are converging with tightening certification requirements to reshape competitive positioning among long-product producers.
Advanced ladle refining and vacuum degassing systems are converging with online hydrogen measurement probes to enable real-time chemistry adjustment during continuous casting. Offshore platform fabricators in the North Sea and Gulf of Mexico are specifying these heat-treatable grades for riser and conductor guide applications. The technology is converging with premium pricing structures that reward mills capable of certifying low hydrogen and sulfur levels without offline retesting delays.
China's SAMR enforcement of GB/T 700 and GB/T 1591 standards is restricting uncertified mill participation in state-backed infrastructure tenders. Long-product producers must now document carbon equivalency and through-thickness ductility to qualify for bridge and high-rise contracts. Domestic mills with existing laboratory accreditation are absorbing market share from smaller competitors facing retrofit costs.
Direct mill-to-job-site logistics programs are bypassing traditional distributor tiers in the southeastern United States. Heavy equipment manufacturers and construction contractors are consolidating purchase orders into tonnage commitments that bundle fabrication support with scheduled delivery windows. This pattern is most visible in states with active port expansion and industrial park development.
Merchant Bar Quality (MBQ) Steel Market Segmentation
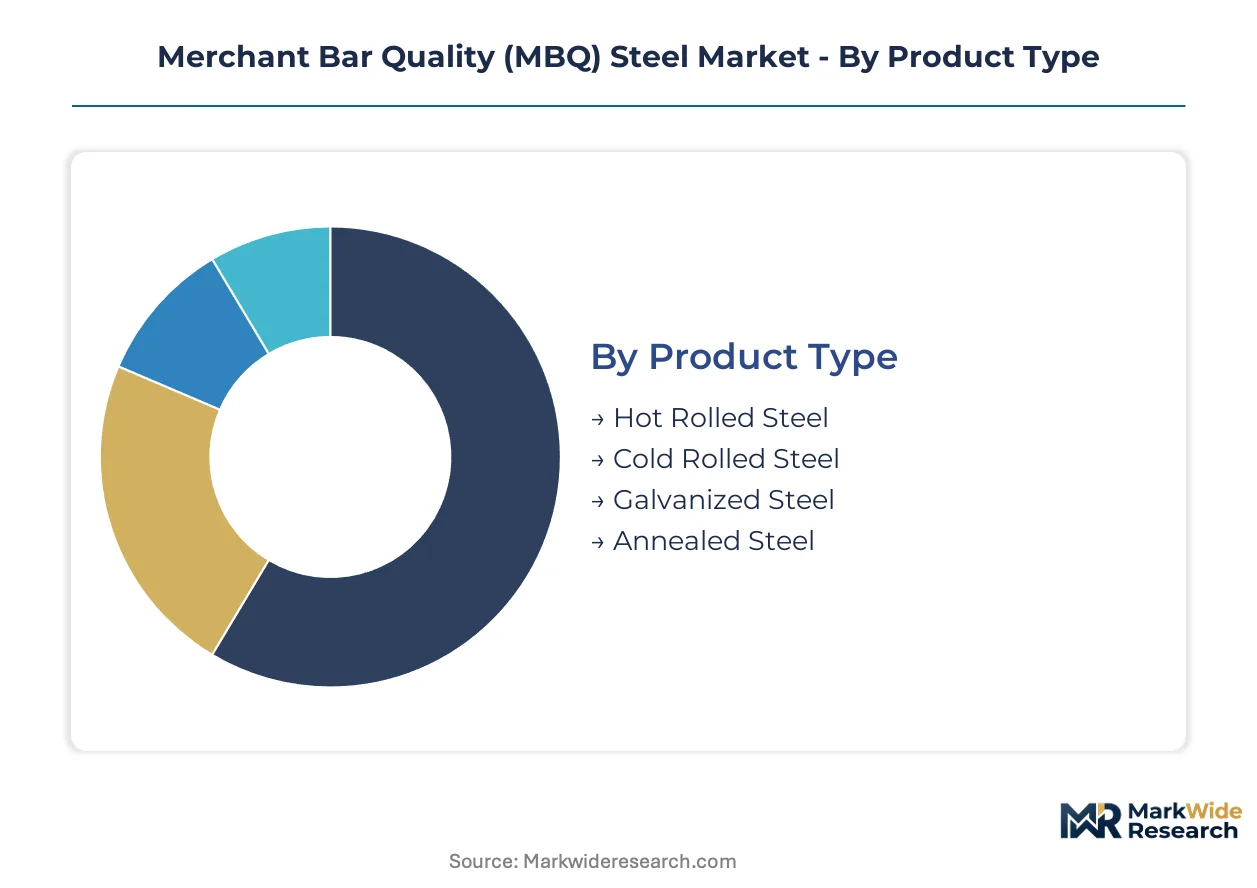
Merchant Bar Quality steel segments reflect divergent metallurgical processing routes and procurement pathways. Specification tiers separate volume infrastructure flows from precision fabrication requirements. Distribution channel choices increasingly bundle logistics capabilities with metallurgical certification support.
Product Type:
Hot rolled and cold rolled specifications anchor the technology axis, with surface finish and dimensional tolerance defining application boundaries.
- Hot Rolled Steel:Mill scale surfaces and wider dimensional tolerances suit structural framing and heavy equipment channels where subsequent welding or machining removes surface irregularities. Bridge decking projects across Vietnam and Indonesia absorb substantial tonnages through fabrication workshops clustered near port facilities.
- Cold Rolled Steel:Tighter thickness control and improved surface finish enable precision bending operations with minimal springback. Machinery manufacturers in India's western corridor specify these grades for components requiring tight bend radii and uniform aesthetic surfaces.
- Galvanized Steel:Zinc coating thicknesses of 85-275 g/m² deliver atmospheric corrosion resistance for coastal construction hardware and shipbuilding applications where lifecycle maintenance cost reduction justifies material premiums.
- Annealed Steel:Spheroidized microstructures from controlled thermal cycles improve formability in cold heading and severe forming operations for specialized fastener production.
Mature deployment sits with hot rolled grades across infrastructure channels. Newer deployment is concentrated in galvanized specifications for marine and coastal corrosion environments.
Application:
End-use concentration patterns reveal how procurement specifications fragment across project types and equipment categories.
- Infrastructure Projects:Federal and state procurement specifications governed by ASTM International standards require certified mechanical properties and traceable heat numbers for bridge decking and structural framing. Southeast Asian governments are absorbing larger tonnages through state-backed tenders with tightening certification windows.
- Heavy Equipment:Frame rails, booms, and undercarriage components demand controlled carbon equivalency for weldability alongside through-thickness ductility for fatigue resistance. OEMs are consolidating purchase orders into tonnage commitments that bundle fabrication support with scheduled delivery windows.
- Fabricated Components:Secondary forming operations including punching, shearing, and thermal cutting require chemistry control to prevent edge cracking and distortion during processing.
- Construction Hardware:Angles, channels, and flats for commercial building framing face substitution pressure from hollow structural sections and cold-formed steel in low-rise applications.
Volume concentration remains with infrastructure and heavy equipment. Margin expansion is climbing the fastest in fabricated components requiring certification documentation for export markets.
End User Industry:
Customer technical requirements diverge sharply between marine specifications and land-based fabrication standards.
- Shipbuilding:Classification society rules from Lloyd's Register and DNV specify minimum yield strengths and impact toughness at sub-zero temperatures for hull structural applications. Offshore platform fabricators in the North Sea and Gulf of Mexico are specifying heat-treatable grades for riser and conductor guide applications.
- Machinery Manufacturing:Precision fabrication workshops require operators capable of interpreting ASTM A36 and A529 chemistry certificates and managing tight bend radii specifications for OEM component supply.
- Power Plants:India's BIS marking requirement under the Steel Quality Control Order restricts uncertified mill access to boiler structural and auxiliary framing bids.
- Fabrication Workshops:Clustered near port facilities from Gujarat through Maharashtra, these operators lack sufficient domestic MBQ capacity and require service-center investments with direct mill-to-job-site logistics.
Certification intensity peaks with shipbuilding classification requirements. Procurement flexibility is expanding most quickly in fabrication workshops adopting digital mill certificate verification systems.
Distribution Channel:
Channel economics reflect inventory carrying costs against technical service requirements and logistics coordination complexity.
- Direct Sales:Mill-to-job-site programs bypass traditional distributor tiers in the southeastern United States where heavy equipment manufacturers consolidate purchase orders into scheduled delivery windows.
- Steel Distributors:Service-center networks bundle fabrication support with tonnage commitments, offering plasma cutting, shearing, and first-stage processing for customers lacking in-house capabilities.
- Online Platforms:Digital procurement interfaces are emerging for standardized grades with immediate availability and documented certification, though complex technical specifications still require direct mill consultation.
- Local Dealers:Geographic proximity to job sites enables just-in-time delivery for maintenance and repair operations with lower inventory carrying costs than centralized distribution.
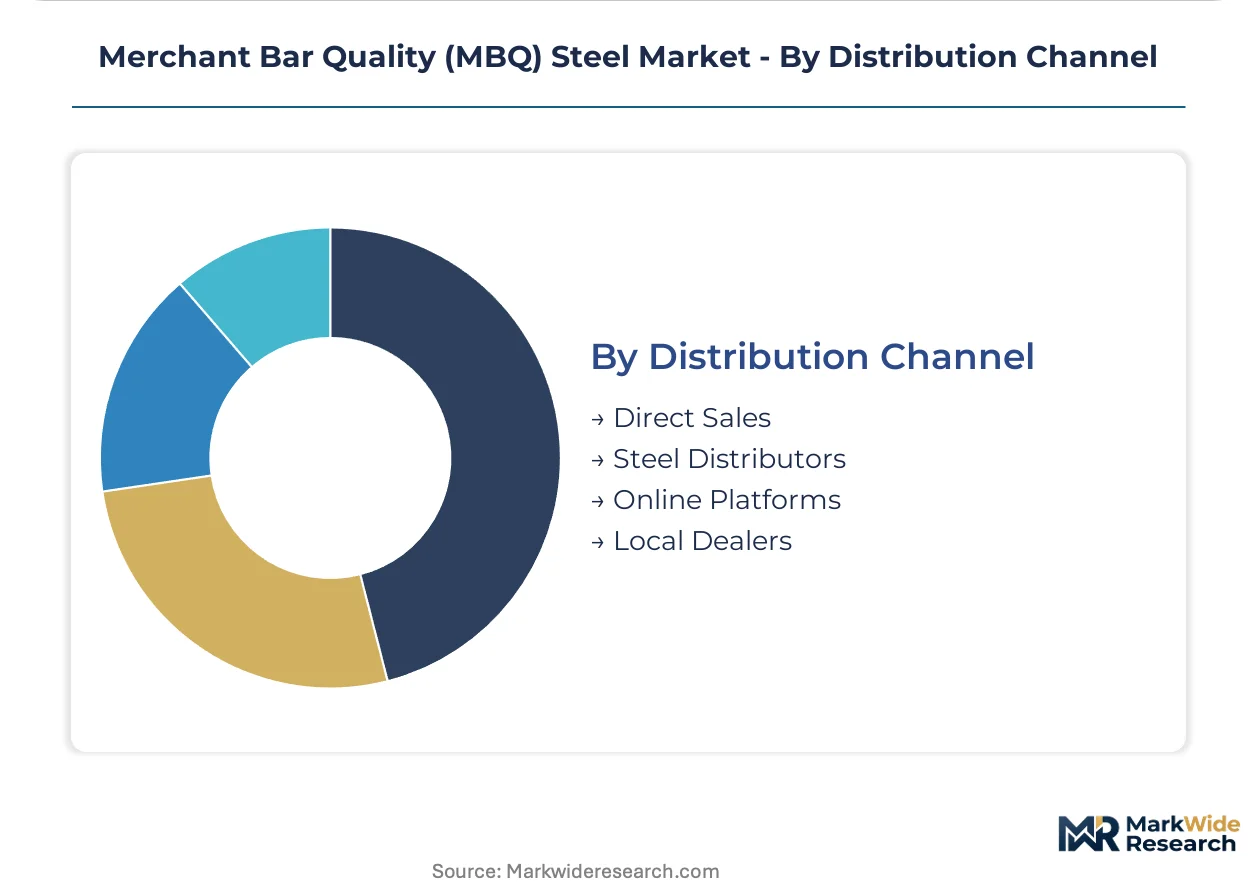
Established volume flows through steel distributors with processing capabilities. Channel experimentation is gaining share fastest in direct sales programs linking electric-arc-furnace producers to consolidated end-user accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's blast-furnace capacity outstrips domestic MBQ consumption, forcing surplus tonnage toward Southeast Asian infrastructure tenders. India's electric-arc-furnace sector cannot match western corridor fabrication demand, opening import dependency. United States coastal mills serve heavy equipment OEMs through direct logistics programs that bypass distributor markups.
China
Bridge decking and high-rise structural framing absorb the majority of domestic hot rolled bar production. SAMR enforcement of GB/T 1591 certification requirements restricts uncertified mill participation in state-backed tenders. Mills in Hebei and Jiangsu provinces are upgrading ladle refining systems to document carbon equivalency and through-thickness ductility.
India
Fabrication workshops from Gujarat through Maharashtra cluster near Mumbai and Mundra port facilities, consuming angles and channels for power plant construction. BIS marking requirements under the Steel Quality Control Order block uncertified imports from competing suppliers. Domestic electric-arc-furnace producers in Raigarh and Bellary lack sufficient MBQ capacity to serve this western corridor concentration.
United States
Heavy equipment manufacturers in Alabama and Georgia consolidate purchase orders into tonnage commitments with scheduled delivery windows. ASTM International standards govern federal and state infrastructure procurement specifications. Southeastern mills are deploying direct mill-to-job-site logistics programs that eliminate traditional steel distributor tiers.
Vietnam
State-backed port expansion and industrial park development are pulling merchant bar tonnages into fabrication workshops near Hai Phong and Ho Chi Minh City. Government infrastructure tenders specify ASTM-equivalent mechanical properties with traceable heat numbers. Japanese and South Korean mill suppliers are capturing share through bundled fabrication support services.
Germany
Machinery manufacturers in Baden-Württemberg and North Rhine-Westphalia require cold rolled grades with tight bend radii specifications. REACH compliance documentation now extends to scrap content and carbon intensity declarations for imported MBQ steel. Service-center networks in the Ruhr region bundle plasma cutting and certification support with tonnage commitments.
Merchant Bar Quality (MBQ) Steel Market Competitive Landscape
Top-tier vendors anchor integrated blast-furnace and electric-arc-furnace production, while regional mini-mill operators compete on logistics proximity and rapid order turnaround. The competitive map separates global-scale producers with captive raw material access from national champions serving protected domestic infrastructure tenders. Three archetypes dominate: integrated steelmakers with service-center networks, electric-arc-furnace specialists with scrap-flexibility advantages, and state-linked producers with preferential access to domestic project pipelines. Capacity expansion in premium heat-treatable grades and strategic partnerships for offshore platform certification represent the dominant competitive vectors.
Among the integrated steelmaker tier, ArcelorMittal and POSCO exemplify scale-driven positioning with metallurgical certification depth for demanding applications. Nucor Corporation anchors the electric-arc-furnace specialist archetype with southeastern US logistics integration. Tata Steel and JSW Steel occupy positions within the Asia-Pacific infrastructure supply base, while China Baowu Steel Group represents state-linked production capacity with domestic tender preferential access.
| Leading Market Players |
|---|
| Tata Steel |
| Gerdau S.A. |
| ArcelorMittal |
| Steel Dynamics, Inc. |
| POSCO |
| Nucor Corporation |
| Nippon Steel Corporation |
| JSW Steel |
| China Baowu Steel Group |
| Others |
Pricing and Supply Chain Analysis
Heavy equipment OEMs consolidating purchase orders into tonnage commitments command pricing leverage through scheduled delivery windows and bundled fabrication support. Their procurement scale compresses margins for electric-arc-furnace producers exposed to shredded auto scrap volatility.
Pricing Analysis
Cost-down pressure on standard-grade hot rolled bar accelerates because blast-furnace incumbents in China absorb iron ore contract stability while electric-arc-furnace competitors face busheling price spikes. Three-tier pricing structure across heat-treatable premium, certified standard, and uncertified economy levels separates offshore platform specifications from infrastructure-grade material. Price differentiation rests on GB/T 1591 certification documentation and carbon-intensity declarations for European REACH compliance. Government procurement programs show lowest price sensitivity due to specification rigidity, while fabrication workshops clustered near Indian port facilities negotiate hardest on per-ton logistics premiums.
Supply Chain Analysis
GB/T 1591 and ASTM International certification gating restricts uncertified mill participation in state-backed tenders, concentrating qualified supply among Hebei and Jiangsu province producers in China plus southeastern US electric-arc-furnace operators. Raw material flows draw from Australian iron ore contracts, shredded North American auto scrap, and Indonesian nickel for corrosion-resistant grades. Single-source vulnerability intensifies around ladle refining system suppliers capable of real-time hydrogen measurement. Distribution runs through service-center networks bundling plasma cutting with certification support, though direct mill-to-job-site programs are bypassing traditional tiers in Alabama and Georgia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital melt-shop controls and online hydrogen measurement probes are displacing legacy offline retesting protocols, compressing certification timelines and reshaping capital allocation priorities.
For Market Incumbents: Lock in western India corridor fabrication workshop relationships through direct mill-to-job-site logistics before domestic electric-arc-furnace capacity expands in Raigarh and Bellary. Deepen backward integration into shredded scrap collection networks to buffer margin compression from busheling price volatility. Prioritize ladle refining upgrades to capture heat-treatable bar premiums from North Sea offshore platform specifications. For New Entrants and Emerging Players: Enter via galvanized coastal hardware segments in Vietnam and Indonesia where atmospheric corrosion resistance specifications outpace domestic zinc-coating capacity. Target fabrication workshops near Hai Phong and Ho Chi Minh City lacking sufficient MBQ supply. Lead with bundled maintenance-service contracts for rebar threading equipment that decouple capital sales from recurring revenue streams. For Investors and Strategic Acquirers: The window for entry favors electric-arc-furnace specialists with scrap-flexibility advantages and existing laboratory accreditation for dual GB/ASTM certification. Long-term viability hinges on carbon-border adjustment mechanism positioning and green steel premium capture. Watch for inflection when India's Steel Quality Control Order tightens BIS marking enforcement against uncertified imports.| Strategic Initiative | Industry Significance |
|---|---|
| Ladle Refining System Upgrade | Hebei province mills achieve GB/T 1591 certification for bridge decking tenders. |
| Direct Mill-to-Job-Site Logistics | Nucor Corporation eliminates distributor markups in Alabama heavy equipment supply. |
| Heat-Treatable Bar Certification | POSCO captures premium segments for Gulf of Mexico riser applications. |
| Scrap Collection Network Expansion | Electric-arc-furnace producers buffer margin exposure to busheling price spikes. |
| Maintenance-Service Unbundling | ArcelorMittal decouples capital equipment sales from recurring threading contracts. |
Research Methodology
Document review covered customs trade data, SEC steel producer filings, and BIS certification registries, complemented by interviews with melt-shop operations directors, fabrication workshop procurement managers, and heavy equipment OEM supply chain leads. Primary fieldwork across Hebei, Jiangsu, Maharashtra, and southeastern US production clusters validated capacity utilization assumptions. Secondary sources included SAMR GB standard enforcement notices, ASTM International specification updates, and ECHA REACH compliance guidance. Bottom-up shipment data triangulated against top-down infrastructure tender absorption estimates.
Historical volume trajectories cross-referenced against panel input from long-product mill executives and service-center operators informed the analytical framework. Segmentation modeling spanned product type, application, end user industry, and distribution channel dimensions across the projection horizon. CAGRs derived from curve-fitting approaches applied to certified-grade premium expansion and galvanized coastal hardware penetration. Scrap price volatility indices and carbon-border adjustment mechanism phase-in schedules served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt GB standards tightening or Indonesian nickel export restrictions. Model assumptions reflect documented certification timelines, melt-shop upgrade capex cycles, and infrastructure tender award patterns. A model refresh is warranted upon material change in India's BIS marking enforcement intensity or European carbon-border adjustment mechanism scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Galvanized Steel Market
Metals
Brazing Strips Market
Metals
Global Wire Rods Market
Metals
Asia-Pacific Aluminum Casting Market
Metals
Global Chromium Market
Metals
Global Stainless Steel Lashing Wire Market
Metals
Cerium Market
Metals
Metal Finishing Market
Metals
High Purity Pig Iron Market
Metals
Cold Drawn Wire Market
Metals
Aluminum Ingots Market
Metals
Cobalt Market
Metals
Europe Aluminium Cans Market
Metals
Zinc Plating Market
Metals
High Purity Tungsten Market
Metals
Bismuth Market