
 Asia-Pacific Metal Finishing Market | 2026-2036
Asia-Pacific Metal Finishing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Metal Finishing Market Outlook
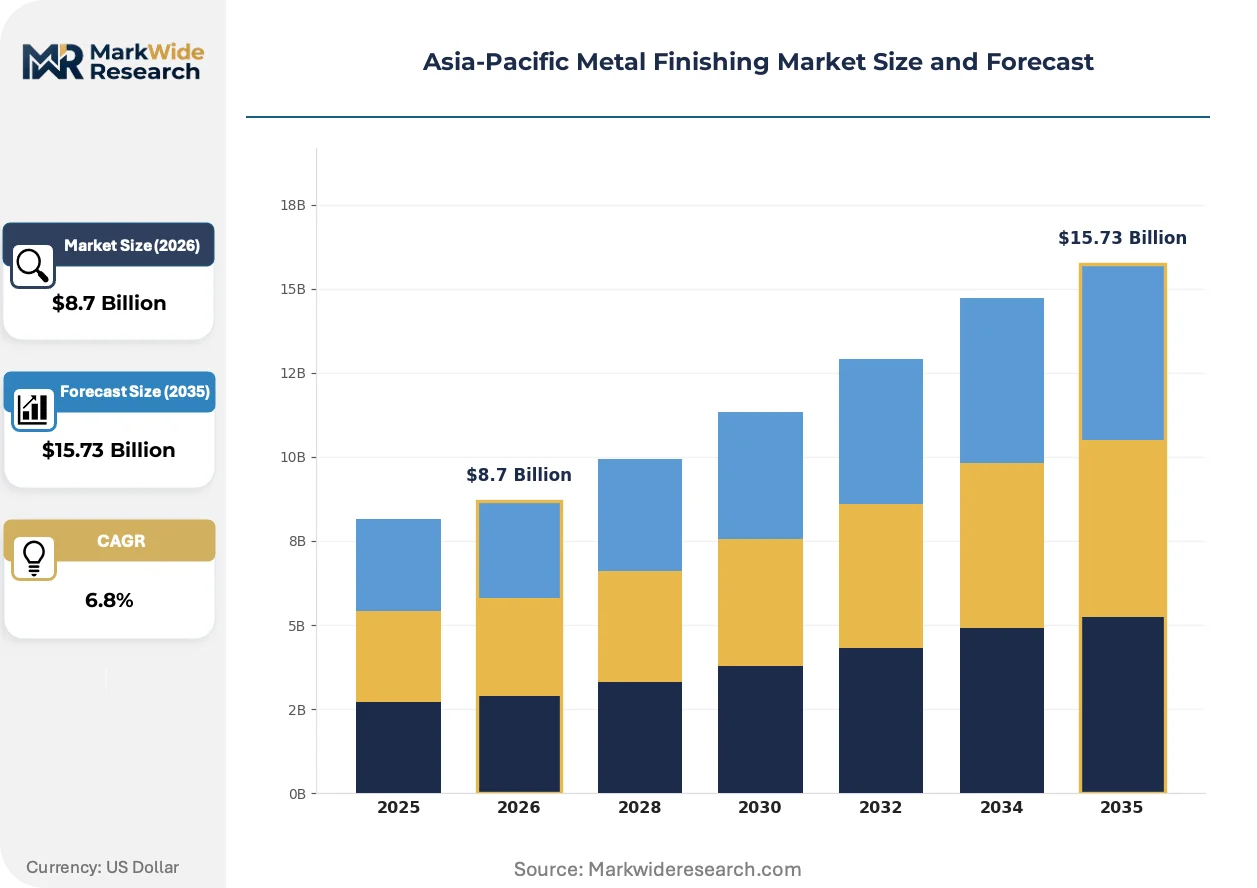
China's GB 21900 standards on electroplating wastewater discharge is broadening the cost-of-entry calculus for metal finishing operations across the Asia-Pacific region. Henkel AG & Co. KGAA leverages its chemical formulation portfolio to serve automotive OEMs transitioning to compliant surface treatments. C. Uyemura & Co. Ltd anchors its position through captive R&D on trivalent chromium chemistries tailored to East Asian regulatory thresholds. Grauer & Weil India Ltd dominates the Indian subcontinent with an extensive distribution network for plating chemicals and equipment.
Asia-Pacific metal finishing encompasses chemical and electrochemical processes that modify surface properties—hardness, corrosion resistance, electrical conductivity, or aesthetic appearance—through controlled deposition, conversion, or coating layers typically measured in micrometers. Electroplating deposits metallic coatings via electrolytic reduction, while anodizing builds protective oxide layers on aluminum substrates through controlled electrochemical oxidation. Electroplating retains the largest revenue share due to its entrenched use in automotive fasteners and electronics connectors, yet powder coating is expanding fastest as VOC regulations tighten across Southeast Asian manufacturing zones. Physical vapor deposition commands premium pricing in aerospace blade and turbine applications where thermal barrier performance justifies capital-intensive equipment.
Japan's METI enforces JIS H 0400 standards that dictate plating thickness tolerances for precision components exported to integrated supply chains. India's BIS certification mandates for electroplated household articles create compliance gateways that filter out informal operators. Australia's TGA and South Korea's MFDS both regulate nickel release from consumer goods, extending quality requirements beyond traditional industrial buyers. Stakeholders must weigh capital allocation between upgrading wastewater infrastructure and migrating to dry-coating alternatives as regulatory baselines continue shifting across the region's fragmented enforcement landscape.
Market Dynamics
China's GB 21900 wastewater discharge standards are forcing electroplating facilities across the Asia-Pacific region into costly compliance retrofits, compressing margins for small-scale operators while advantaging chemical suppliers with turnkey trivalent chromium formulations. This regulatory pressure is redrawing competitive boundaries between wet-process incumbents and dry-coating challengers.
Growth Catalysts
- Automotive corrosion mandates:OEMs in India and China are expanding surface treatment capacity to meet stricter fastener durability specifications for export vehicles.
- Trivalent chromium transition:China's MEE enforcement of heavy metal discharge limits is accelerating replacement of hexavalent processes in supplier parks.
- Electronics miniaturization:Connector manufacturers in South Korea and Taiwan are adopting electroless nickel-phosphorus for high-density interconnect reliability.
Market Restraints
- Hexavalent chromium phase-out costs:Conversion of plating lines to trivalent chemistries requires capital outlays that filter out informal operators in India and Southeast Asia.
- Precious metal price volatility:Palladium and rhodium cost swings in electroplating baths compress margin predictability for job shops serving automotive tier-2 suppliers.
- Substitution by powder coating:VOC regulations in Thailand and Vietnam are pushing appliance manufacturers toward dry-finishing alternatives for non-critical components.
Strategic Opportunities
- Vietnam manufacturing expansion:Supplier parks near Hanoi and Ho Chi Minh City lack captive metal finishing capacity, creating white space for electroplating joint ventures.
- Physical vapor deposition growth:Aerospace blade coatings for maintenance-repair-overhaul facilities in Singapore and Australia command premium pricing due to thermal barrier performance requirements.
- India PLI scheme leverage:Production-linked incentives for automotive and electronics manufacturing are pulling captive plating investments into the Pune-Chennai corridor.
Industry Challenges
- Process chemist shortage:Trivalent chromium bath management requires specialized expertise that outpaces vocational training output in China's Pearl River Delta.
- Wastewater infrastructure capex:Zero-liquid-discharge systems for electroplating effluent recovery demand capital commitments that strain small and mid-scale job shop balance sheets.
- JIS H 0400 certification timelines:Japanese automotive tier-1 suppliers impose lengthy qualification periods on plating thickness tolerance compliance for precision component exports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Metal Finishing Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electroplating, Anodizing, Electropolishing, Powder Coating Application: Aerospace, Automotive, Construction, Consumer Goods Technology: Physical Vapor Deposition, Chemical Vapor Deposition, Traditional Finishing, Advanced Coating End User: Manufacturers, OEMs, Service Providers, Industrial Users |
| Companies Covered | C. Uyemura & Co. Ltd, OC Oerlikon Management AG, Honeywell International Inc., Linde plc, Grauer & Weil India Ltd, Quaker Chemical Corporation, Henkel AG & Co. KGAA, Atotech, Elementis plc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Metal Finishing Market Strategic Shifts
Surface treatment technologies across the Asia-Pacific region are fragmenting along regulatory fault lines, with wet-process incumbents defending automotive and electronics strongholds while dry-coating alternatives capture appliance and architectural applications. This bifurcation is compressing the addressable market for traditional electroplating in VOC-sensitive jurisdictions.
Electroless nickel-phosphorus deposition is converging with printed circuit board manufacturing in Taiwan and South Korea, where high-density interconnect designs demand uniform coating thickness on complex via geometries. Semiconductor packaging houses are adopting these chemistries at pilot scale for flip-chip under-bump metallization. The technology is converging with advanced substrate fabrication, enabling thinner dielectric layers that compress signal path lengths in next-generation devices.
Japan's METI has tightened JIS H 0400 plating thickness tolerances for precision components exported to integrated automotive supply chains, forcing job shops into statistical process control investments. The industrial consequence is a filtering of informal operators unable to document Cpk values above 1.33. Connector manufacturers serving Toyota and Honda supply networks are most affected, responding with inline X-ray fluorescence inspection systems that add fifteen to twenty percent to process overhead.
Buyer concentration among automotive OEMs in China and India is compressing plating chemical procurement cycles, with annual supplier performance scorecards replacing multi-year framework agreements. Tier-1 fastener manufacturers are consolidating vendor panels from twelve suppliers to three qualified partners. This pattern is most visible in India's Pune-Chennai manufacturing corridor, where Maruti Suzuki and Hyundai Motor India have imposed vendor reduction mandates that favor chemical suppliers with captive technical service teams.
Asia-Pacific Metal Finishing Market Segmentation
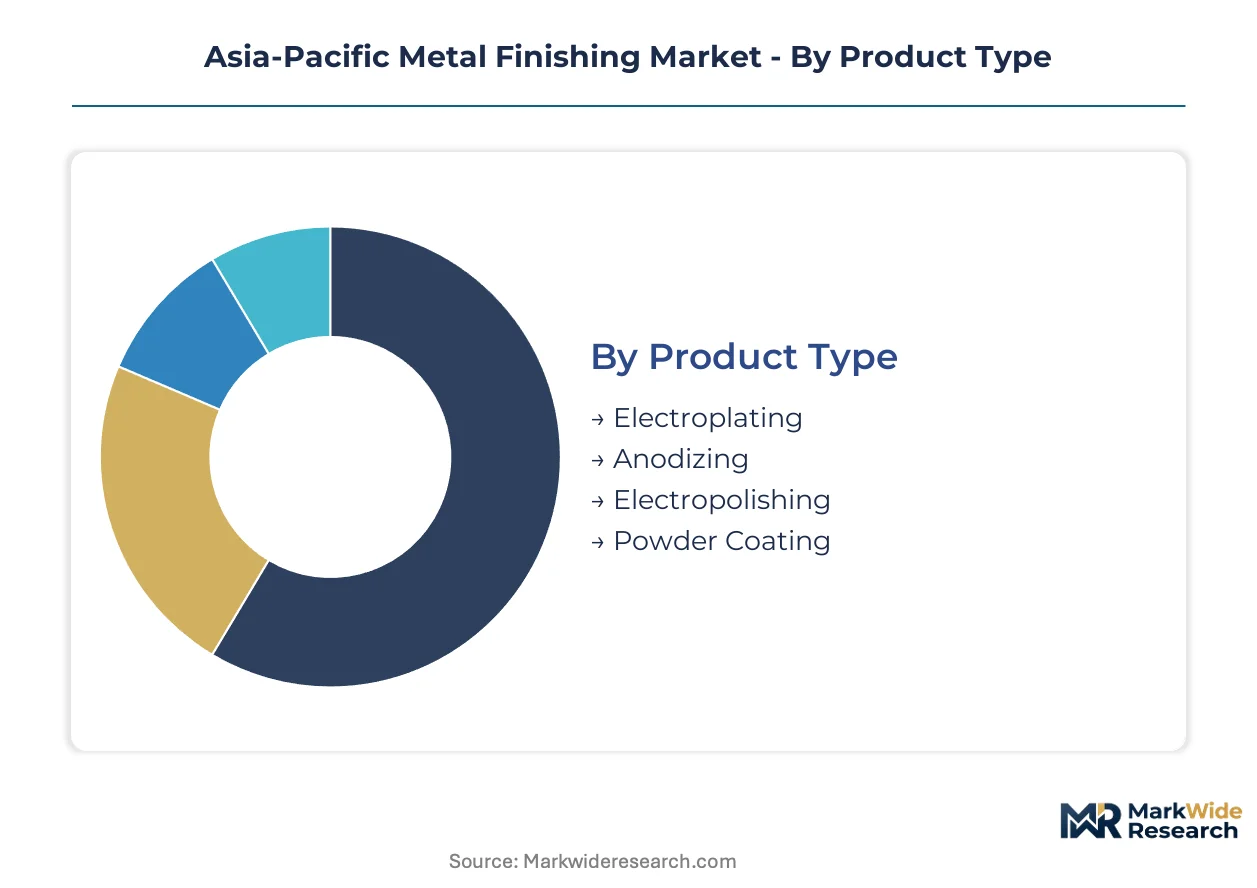
Asia-Pacific metal finishing technologies fragment along regulatory compliance lines, with wet-process incumbents defending automotive and electronics strongholds while dry-coating alternatives capture appliance applications. Segment boundaries blur where trivalent chromium mandates force plating line conversions and powder coating gains share in VOC-sensitive manufacturing zones.
Product Type:
Upgrade cycles across plating facilities favor technologies that minimize wastewater discharge while preserving corrosion performance specifications.
- Electroplating:Electrolytic reduction deposits metallic coatings measured in micrometers onto conductive substrates. China's MEE enforcement of GB 21900 heavy metal limits is forcing supplier parks in the Pearl River Delta toward trivalent chromium bath conversions.
- Powder Coating:Thermoset or thermoplastic powders applied electrostatically and cured thermally produce VOC-free finishes. Thailand's tightening air quality regulations are pulling appliance manufacturers away from liquid coatings in Bangkok industrial estates.
- Anodizing:Controlled electrochemical oxidation builds protective oxide layers on aluminum, prevalent in Japan's precision component exports.
- Electropolishing:Reverse electroplating smooths metal surfaces through selective dissolution, serving medical device manufacturers in South Korea.
Electroplating sits at the top of the volume ranking, with powder coating climbing the fastest.
Application:
Cost tier differentiation separates premium corrosion specifications from commodity aesthetic finishes across the region's manufacturing bases.
- Automotive:Fastener durability mandates from China and India OEMs drive surface treatment capacity expansion. Maruti Suzuki and Hyundai Motor India supplier scorecards now require documented plating thickness compliance for export vehicle programs.
- Aerospace:Thermal barrier coatings on turbine blades command premium pricing in Singapore and Australia maintenance-repair-overhaul facilities. Physical vapor deposition systems justify capital intensity through performance specifications that wet processes cannot match.
- Construction:Architectural aluminum anodizing serves commercial building facades across Australia's urban centers.
- Consumer Goods:India's BIS certification for electroplated household articles filters informal operators from formal supply chains.
Automotive commands the largest revenue base, with aerospace expanding most quickly.
Technology:
Customer type concentration among Japanese automotive tier-1 suppliers imposes lengthy qualification timelines that filter technology providers.
- Traditional Finishing:Hexavalent chromium electroplating and conventional anodizing retain entrenched positions in cost-sensitive supply chains. Conversion capital requirements are compressing margins for small-scale job shops across India and Southeast Asia.
- Physical Vapor Deposition:Vacuum deposition of thin films delivers thermal barrier performance for aerospace rotating components. Singapore's MRO facilities source these coatings for regional airline engine overhaul programs.
- Chemical Vapor Deposition:Gas-phase precursor reactions produce ceramic coatings for semiconductor manufacturing equipment in Taiwan.
- Advanced Coating:Nanostructured and composite formulations target next-generation electronics interconnect reliability in South Korea.
Traditional Finishing retains the largest installed base, with Physical Vapor Deposition gaining share fastest.
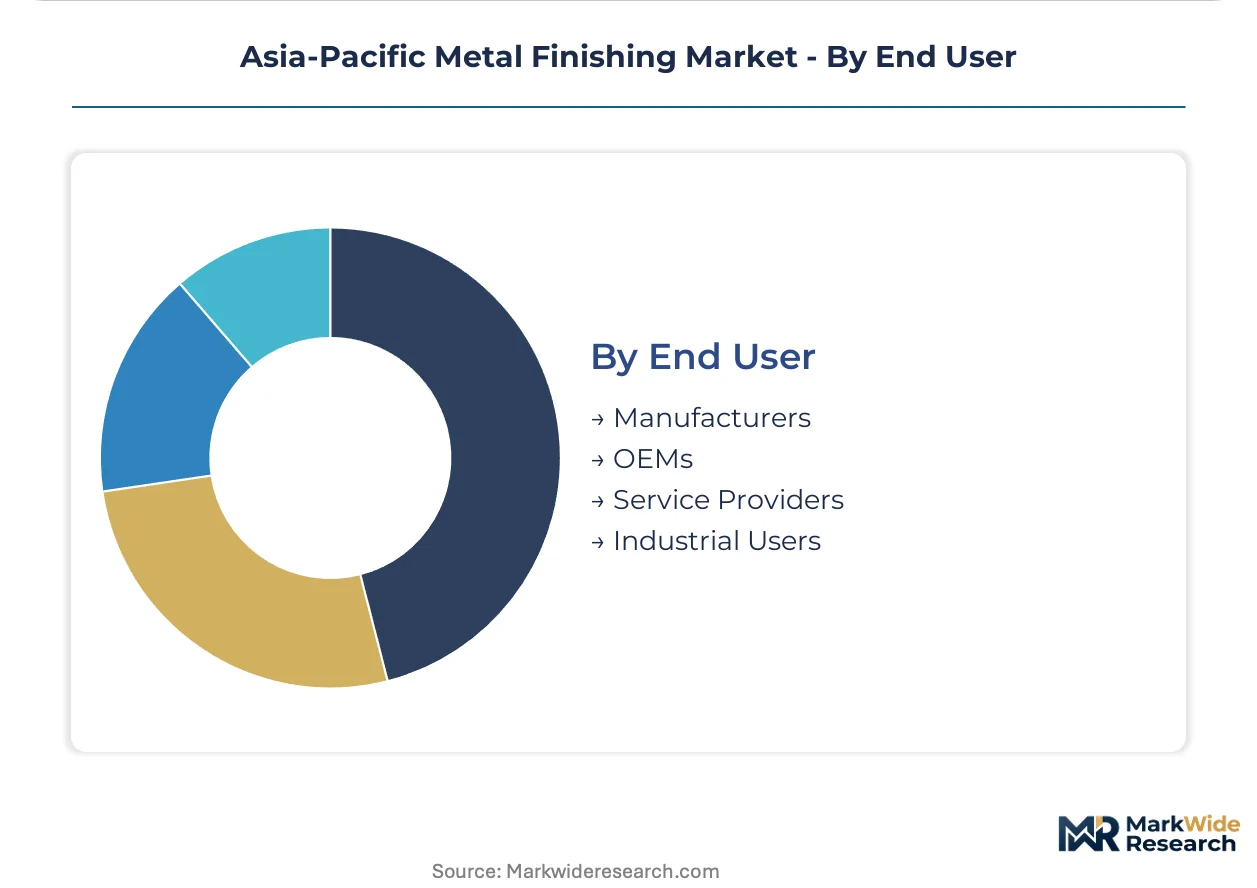
End User:
Supply concentration in India's Pune-Chennai corridor is pulling captive plating investments away from fragmented job shop networks.
- OEMs:Automotive original equipment manufacturers consolidate vendor panels from twelve suppliers to three qualified partners. Annual performance scorecards have replaced multi-year framework agreements across China and India procurement organizations.
- Manufacturers:Tier-1 fastener producers in Japan's automotive supply chains invest in inline X-ray fluorescence inspection to meet JIS H 0400 plating thickness tolerances.
- Service Providers:Independent plating job shops face wastewater infrastructure capex demands that strain balance sheets in China's manufacturing zones.
- Industrial Users:Heavy equipment and machinery producers source surface treatments through arm's-length contracts in Australia's mining supply chains.
OEMs dominate procurement volume, with Manufacturers expanding their captive capacity most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled process chemists cluster in China's Pearl River Delta and Japan's Kansai industrial belt, anchoring wet-process technical capability across the region. These talent concentrations shape where trivalent chromium conversion expertise concentrates and which supplier parks can support precision automotive plating.
China
Automotive OEMs in the Yangtze River Delta and Pearl River Delta are expanding captive plating capacity for export vehicle programs. MEE enforcement of GB 21900 wastewater discharge standards is forcing electroplating facilities into costly zero-liquid-discharge retrofits. Supplier parks in Dongguan and Suzhou are consolidating from fragmented job shop networks toward qualified chemical partners with turnkey compliance solutions.
India
Two-wheeler and passenger vehicle manufacturers are pulling surface treatment investments into the Pune-Chennai manufacturing corridor. BIS certification mandates for electroplated household articles filter informal operators from formal supply chains. Maruti Suzuki and Hyundai Motor India have imposed vendor reduction mandates that favor plating chemical suppliers with captive technical service teams in Maharashtra and Tamil Nadu.
Japan
Precision component exporters serving Toyota and Honda supply networks face tightened JIS H 0400 plating thickness tolerances. METI standards dictate qualification timelines that filter out job shops lacking statistical process control documentation. Kansai-based connector manufacturers are investing in inline X-ray fluorescence inspection systems to meet Cpk thresholds above 1.33 for automotive tier-1 contracts.
South Korea
Electronics miniaturization is driving electroless nickel-phosphorus adoption for high-density interconnect reliability. MFDS regulates nickel release from consumer goods, extending quality requirements beyond traditional industrial buyers. Semiconductor packaging houses in Gyeonggi Province are piloting these chemistries for flip-chip under-bump metallization in advanced substrate fabrication.
Vietnam
Supplier parks near Hanoi and Ho Chi Minh City lack captive metal finishing capacity, creating white space for electroplating joint ventures. Tightening air quality regulations are pulling appliance manufacturers toward powder coating alternatives for non-critical components. Japanese and Korean automotive tier-1 suppliers are evaluating local plating partnerships to support expanding assembly operations in northern industrial zones.
Asia-Pacific Metal Finishing Market Competitive Environment
The competitive structure tilts toward chemical formulation specialists with turnkey regulatory compliance capabilities. Wet-process incumbents defend automotive and electronics strongholds while dry-coating challengers capture appliance and architectural applications. Three archetypes dominate: multinational chemical suppliers with regional technical service networks, captive R&D specialists in trivalent chromium chemistries, and India-focused distributors with extensive plating equipment and chemical portfolios. Consolidation moves center on vendor panel reductions by automotive OEMs and chemical suppliers acquiring wastewater treatment technology to offer integrated compliance packages.
Among Japan-based specialists, C. Uyemura & Co. Ltd occupies a position exemplifying captive R&D investment in trivalent chromium formulations tailored to East Asian regulatory thresholds. Henkel AG & Co. KGAA, a German AG, represents the multinational chemical supplier archetype with regional technical service networks supporting automotive OEM transitions. Grauer & Weil India Ltd, an India-based Ltd, anchors the subcontinent distribution archetype with extensive plating chemical and equipment reach across the Pune-Chennai corridor. These three illustrate how geographic origin and corporate structure map to distinct competitive positioning in a market fragmenting along regulatory compliance lines.
| Leading Market Players |
|---|
| C. Uyemura & Co. Ltd |
| OC Oerlikon Management AG |
| Honeywell International Inc. |
| Linde plc |
| Grauer & Weil India Ltd |
| Quaker Chemical Corporation |
| Henkel AG & Co. KGAA |
| Atotech |
| Elementis plc |
| Others |
Value Chain & Pricing Dynamics
Palladium and rhodium spot price indices cascade through electroplating bath chemistry costs, compressing margins for Indian and Southeast Asian job shops while rewarding Chinese chemical suppliers with captive metal sourcing and turnkey trivalent chromium formulations. This raw-material volatility stratifies the market into bundled compliance-service providers commanding premium positioning versus unbundled commodity operators facing relentless cost pressure.
Pricing Analysis
Bundled wastewater compliance and chemical management services versus unbundled commodity chemical supply defines the pricing architecture across Asia-Pacific metal finishing. Three-tier pricing structure across premium certified, standard compliant, and economy unregulated levels separates Henkel-grade technical partnerships from Grauer & Weil distribution plays. Pricing pressure stems from MEE enforcement of GB 21900 discharge standards forcing zero-liquid-discharge capex into supplier cost bases. Tier-2 automotive fastener manufacturers in India's Pune corridor exhibit highest price sensitivity, while Japanese precision component exporters serving Toyota supply networks accept premium positioning for JIS H 0400 certification documentation.
Supply Chain Analysis
Skilled process chemist availability concentrates in China's Pearl River Delta and Japan's Kansai industrial belt, anchoring wet-process technical capability and shaping where plating line conversions can execute. China, Japan, and South Korea dominate specialty chemical formulation supply, drawing from nickel sulfate, chromium compounds, and proprietary organic additive packages. Single-source vulnerability runs through palladium and rhodium feedstock dependencies tied to South African and Russian mining concentration. Distribution runs through qualified chemical partners with captive technical service teams rather than arm's-length commodity traders, reflecting the complexity of bath management and regulatory compliance integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific metal finishing functions as a geographic-arbitrage play where Vietnam's supplier park vacuum and China's regulatory compliance cost inflation create divergent entry economics for capital deployment.
For Market Incumbents: Cement market position through backward integration into wastewater treatment technology and captive trivalent chromium R&D capacity. Henkel AG & Co. KGAA's regional technical service network model offers a template for defending against dry-coating substitution in appliance applications. Lock in automotive OEM vendor panel consolidation through multi-year chemical management contracts with embedded compliance guarantees. For New Entrants and Emerging Players: Direct-to-OEM digital procurement platforms offer a route around entrenched distributor relationships in India's fragmented job shop landscape. Target Vietnam's Hanoi and Ho Chi Minh City supplier parks where captive plating capacity gaps create white space for electroplating joint ventures with Japanese automotive tier-1 suppliers. Lead with electroless nickel-phosphorus technical service capabilities to penetrate South Korean electronics packaging houses piloting flip-chip under-bump metallization. For Investors and Strategic Acquirers: Asymmetric upside sits with India-focused plating chemical distributors possessing deep Pune-Chennai corridor relationships and BIS certification navigation expertise. The five-to-ten-year viability window favors acquisitions of regional wastewater treatment technology providers that enable integrated compliance-service bundling. Watch MEE enforcement intensity in China's Pearl River Delta as the inflection signal for trivalent chromium conversion capex cycles and associated chemical supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wastewater Treatment | Captive zero-liquid-discharge capability locks in automotive OEM compliance contracts against commodity chemical rivals. |
| Trivalent Chromium Chemistry Joint Venture | Local formulation partnerships with C. Uyemura & Co. Ltd accelerate GB 21900 compliance timelines for Chinese supplier parks. |
| Electroless Nickel-Phosphorus Capacity Expansion | Gyeonggi Province positioning captures semiconductor packaging demand for flip-chip under-bump metallization pilots. |
| Vendor Panel Consolidation Response | Technical service team density in Maharashtra and Tamil Nadu secures Maruti Suzuki and Hyundai Motor India qualification. |
| Powder Coating Line Diversification | Bangkok industrial estate positioning captures Thai appliance manufacturer VOC regulation migration away from liquid coatings. |
Study Parameters
Multiple input streams — primary interviews with plating chemical plant managers, automotive OEM procurement leads, and wastewater treatment engineering directors; secondary validation through customs trade data, SEC chemical company filings, and MEE regulatory enforcement disclosures — were reconciled through bottom-up plating facility capacity modeling and top-down automotive production correlation. Technical R&D directors at trivalent chromium specialists and distribution channel partners across India's Pune-Chennai corridor provided operational ground-truth.
Data-stream reconciliation anchored volume projections to automotive fastener demand curves, electronics connector miniaturization trends, and aerospace MRO thermal barrier coating replacement cycles across the projection horizon. Segmentation dimensions modeled include process technology type, application vertical, regulatory compliance tier, and regional manufacturing cluster concentration. CAGRs derived from slope-consistency checks against historical plating chemical consumption patterns and forward capacity announcement tracking.
The model assumes a particular technology adoption path; alternative pathways for hexavalent chromium phase-out acceleration or dry-coating substitution breakthroughs would alter the outlook. Forecasts embed assumptions regarding MEE enforcement continuity, palladium price regime stability, and Japanese automotive supply chain qualification timeline rigidity. Material deviation in GB 21900 inspection intensity or Vietnam supplier park development velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Copper Cathode Market
Metals
North America and Europe Metal Powder Market
Metals
Lanthanum Market
Metals
Metal Casting Market
Metals
Aluminum Flat-Rolled Products Market
Metals
Global Precious Metal Market
Metals
Trivalent Chromium Finishing Market
Metals
Aluminum Tubes Market
Metals
Metal Finishing Market
Metals
China Copper Market
Metals
Vietnam Aluminum Market
Metals
Saudi Arabia Aluminum Market
Metals
North America Aluminum Market
Metals
Global Vanadium Market
Metals
Metal Recycling Market
Metals
Finished Steel Products Market