
 Palladium Market | 2026-2036
Palladium Market Size, Share, and Industry Trends Forecast 2026-2036
Palladium Market Analysis
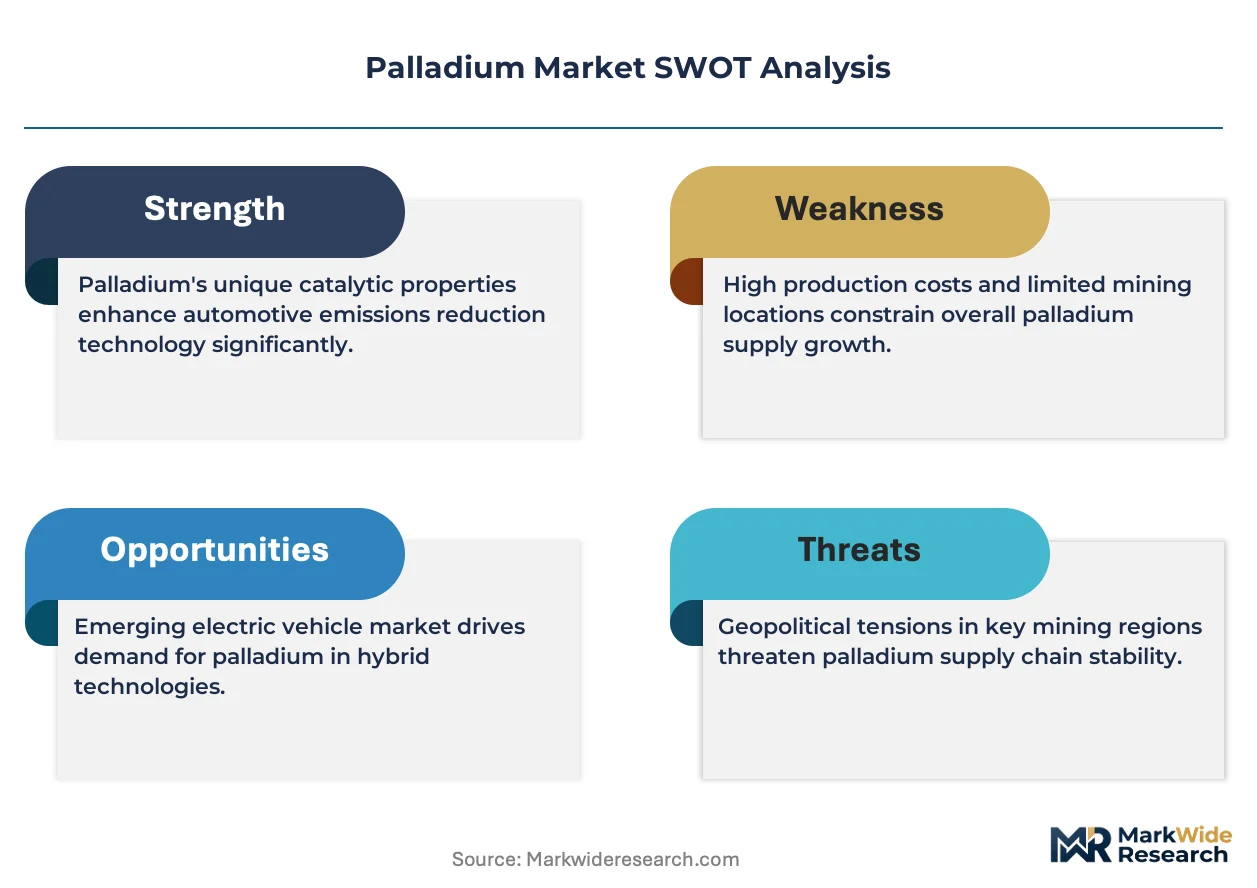
Project finance for junior mining ventures is fragmenting competitive access to palladium reserves. Sibanye Stillwater leverages its integrated processing infrastructure across North American platinum group metal deposits. Anglo American Platinum anchors global supply through mechanized operations in South Africa's Bushveld Complex. Platinum Group Metals specializes in advanced exploration targeting large-scale palladium-dominant resources.
Palladium is a lustrous, silvery-white platinum group metal with atomic number 46, melting point 1,555°C, and exceptional catalytic activity for oxidation reactions; manufacturers primarily deploy it in automotive catalytic converters to transform harmful exhaust gases into less toxic emissions. Automotive catalysts dominate end-user consumption as gasoline vehicles retain palladium-heavy formulations despite ongoing platinum substitution research. High purity grades command premium positioning in electronics applications where sputtering targets and plating chemistries demand minimal contaminant levels. Powder and sponge forms serve distinct industrial channels, with sponge preferred for catalyst manufacturing and powder directed toward chemical process and dental alloy applications.
EPA tailpipe standards, Euro 7 emissions frameworks, and China's MEE vehicle emission rules directly determine palladium loading requirements per catalyst unit. REACH compliance in Europe and evolving GB standards in China constrain processing chemistries and recycling protocols across the value chain. Stakeholders must monitor regulatory calibration timelines and substitution technology maturation to align inventory positions with shifting metal intensity trajectories.
Market Dynamics
Automotive emission mandates are compressing palladium substitution timelines as gasoline catalyst loadings rise to meet Euro 7 and China's MEE Phase 6b standards, forcing supply chains to absorb metal price volatility without passing full costs downstream.
Growth Catalysts
- Euro 7 Emissions Framework:The European Union's tightened nitrogen oxide limits for gasoline vehicles mandate higher palladium loadings per catalyst unit, directly expanding metal intensity across the continent's passenger car fleet.
- China Vehicle Fleet Expansion:The country's expanding middle-class vehicle ownership combined with MEE enforcement tightening creates concentrated demand growth for palladium-heavy three-way catalysts in the world's largest automotive market.
- Platinum Substitution Lag:Technical barriers to platinum-for-palladium substitution in gasoline engines preserve incumbent formulations, extending the runway for palladium-dominant catalyst designs.
Market Restraints
- South African Supply Concentration:The Bushveld Complex hosts mechanized platinum group metal operations that concentrate primary supply in a single geographic jurisdiction exposed to electricity grid instability and labor action.
- Platinum Cost Arbitrage:Persistent price differentials between platinum and palladium incentivize automakers to accelerate substitution research, threatening long-term demand structural integrity.
- REACH Processing Constraints:European chemical registration requirements constrain recycling protocol flexibility, elevating compliance costs for secondary metal recovery operations.
Strategic Opportunities
- Hydrogen Fuel Cell Membranes:Emerging proton exchange membrane electrolyzer deployments utilize palladium-containing catalyst layers, opening industrial demand channels beyond automotive applications.
- Urban Air Mobility:Advanced aerial vehicle propulsion systems require compact emission control solutions where palladium's catalytic efficiency supports miniaturized reactor designs.
- India BS-VII Preparation:The country's upcoming emission standard alignment creates forward demand visibility for catalyst manufacturers positioning ahead of regulatory implementation.
Industry Challenges
- PGM Assay Precision:Recycling operations face technical complexity in separating palladium from platinum and rhodium in spent catalyst feedstock, requiring capital-intensive analytical infrastructure.
- Smelter Bottleneck Access:Junior miners confront limited toll processing capacity at integrated refineries, constraining project finance viability for greenfield palladium-dominant deposits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Palladium Market |
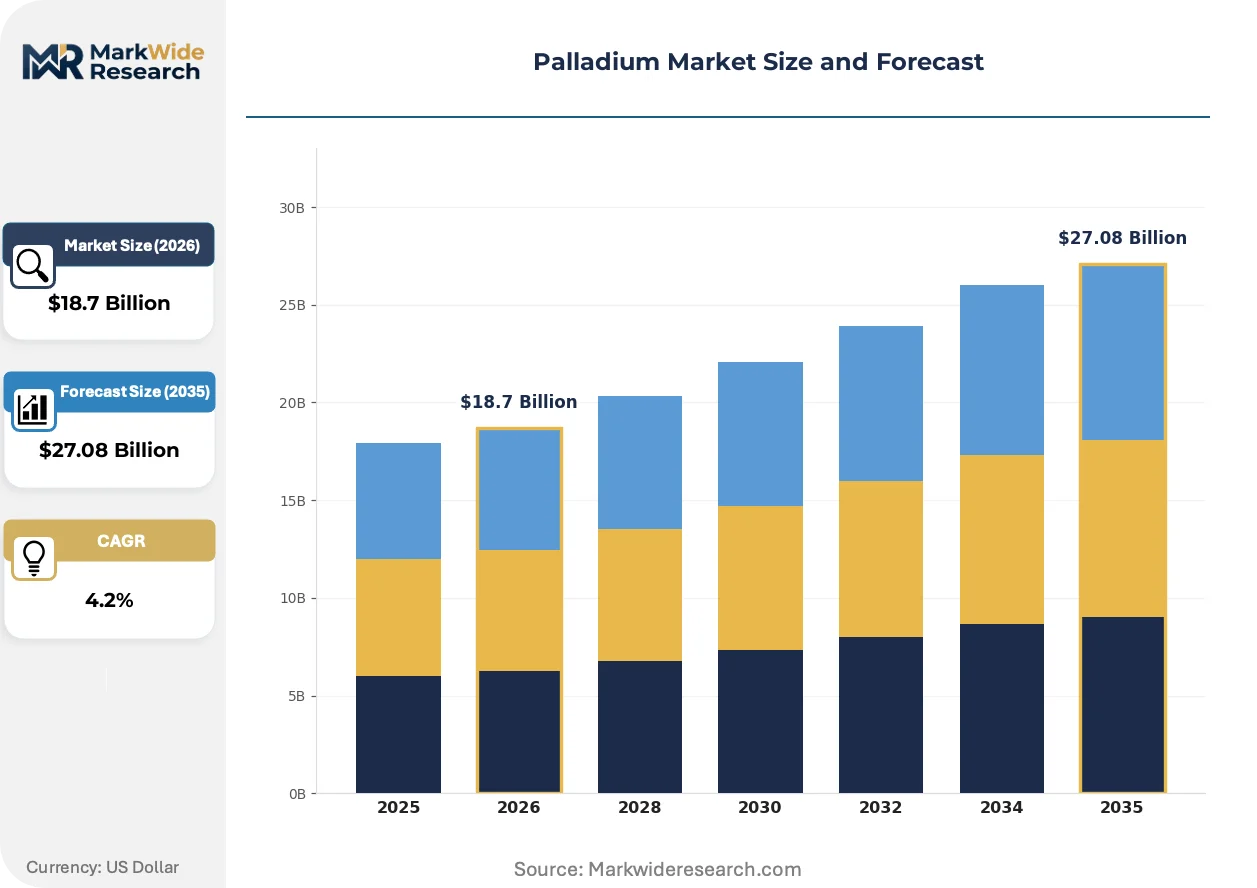
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coins, Bars, Sheets, Powder End User: Automotive Catalysts, Electronics, Jewelry, Dental Applications Form: Sponge, Ingot, Wire, Foil Purity: Low Purity, Standard Purity, High Purity, Ultra High Purity |
| Companies Covered | Platinum Group Metals, Zimplats Holdings, Sibanye Stillwater, Eastern Platinum, Solitario Exploration & Royalty, Anglo American Platinum, New Age Metals, Venus Metals Corp., Ivanhoe Mines, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Palladium Market Emerging Trajectories
Digital process control and materials informatics are compressing catalyst development cycles, while regulatory calibration in major economies forces simultaneous adaptation across formulation chemistry and supply chain transparency.
Computational catalyst design platforms are virtualizing traditional wet-laboratory screening protocols. Automotive suppliers including tier-one catalyst manufacturers deploy machine learning models to predict palladium dispersion optimization on washcoat substrates. This technology is virtualizing months of empirical testing into simulation-driven parameter sweeps, collapsing development timelines for emission-compliant formulations.
China's MEE vehicle emission rules are tightening enforcement timelines ahead of original schedules. Provincial environmental bureaus now mandate real-world driving emission monitoring through onboard diagnostic data transmission. Light-duty gasoline vehicle producers in Shanghai and Beijing are responding by locking palladium loading specifications earlier in model-year planning cycles.
Automotive procurement departments are consolidating catalyst supply agreements into multi-year metal-price-hedged contracts. Tier-one suppliers face compressed switching timelines as OEMs demand fixed-price coverage through 2028 model years. This pattern is most visible in German and Japanese automaker supply chains, where just-in-sequence manufacturing tolerates minimal formulation disruption.
Palladium Market Segmentation
Palladium market segmentation reveals distinct demand profiles across physical forms, purity grades, and end-use applications. Each dimension carries specific technical specifications that govern procurement patterns and pricing structures.
Product Type:
Physical configuration determines storage logistics, liquidity profiles, and premium structures across investment and industrial channels.
- Coins:Government-minted palladium coins carry sovereign guarantees and standardized weights, attracting retail investors seeking portable store-of-value instruments. Canadian Maple Leaf and American Eagle programs anchor North American retail demand through recognized assay certification.
- Bars:Cast and minted bars in 1-ounce to 1-kilogram denominations dominate institutional holdings. Swiss refiners and London Bullion Market Association-accredited fabricators supply allocated and unallocated pool positions for exchange-traded product backing.
- Sheets:Rolled palladium sheets serve specialized industrial applications requiring precise thickness control for electrical contact manufacturing and laboratory equipment fabrication.
- Powder:Atomized and chemically reduced powders enable additive manufacturing feedstock and catalyst precursor production for chemical process industries.
Coins command the established base. The steepest expansion runs through powder as industrial additive applications mature.
End User:
Application intensity varies dramatically across sectors, with automotive consumption dwarfing all other demand channels by order of magnitude.
- Automotive Catalysts:Three-way catalytic converters in gasoline vehicles consume the overwhelming majority of annual palladium offtake. EPA, Euro 7, and China's MEE emission standards directly determine loading specifications per vehicle platform.
- Electronics:Multi-layer ceramic capacitors, connector plating, and semiconductor packaging utilize high-purity palladium for conductivity and corrosion resistance. Japanese and South Korean electronics manufacturers concentrate procurement for consumer device production.
- Jewelry:Palladium-white gold alloys and pure palladium settings offer hypoallergenic alternatives to nickel-based white metals. Chinese and Indian jewelry fabricators drive regional demand cycles tied to wedding season purchasing patterns.
- Dental Applications:Palladium-silver and palladium-gold alloys provide biocompatible restorative materials with adjustable hardness characteristics for crown and bridge prosthetics.
Automotive catalysts absorb the volume base. Electronics applications are climbing the fastest as miniaturization demands intensify.
Form:
Processing state dictates downstream manufacturing compatibility and working characteristics for distinct industrial workflows.
- Sponge:Porous, high-surface-area metal produced through chemical reduction serves as the primary feedstock for catalyst manufacturing. Sponge dissolves readily in nitric acid for plating bath preparation and chemical synthesis.
- Ingot:Cast rectangular blocks facilitate vacuum remelting and alloy formulation for aerospace and medical device specifications requiring precise composition control.
- Wire:Drawn filament in diameters from 0.025mm to 3mm enables electrical contact springs, thermocouple elements, and surgical instrument components.
- Foil:Cold-rolled thin sheet below 0.1mm thickness supports hydrogen purification membranes, fuel cell bipolar plate coatings, and specialized laboratory apparatus.
Sponge anchors catalyst supply chains. Foil applications are expanding most quickly around hydrogen economy infrastructure deployment.
Purity:
Grade specification separates commodity industrial consumption from premium-priced precision applications where trace element control determines performance.
- Low Purity:Material at 95-99% palladium content, often recovered from secondary sources, satisfies cost-sensitive chemical process applications where absolute purity is non-critical.
- Standard Purity:99.5% minimum material meets general industrial catalyst manufacturing and mainstream electroplating requirements without premium assay certification.
- High Purity:99.95% material with controlled impurity profiles supports semiconductor sputtering targets, medical device alloys, and aerospace specifications demanding documented trace element limits.
- Ultra High Purity:99.999% and above material, produced through repeated zone refining and vacuum distillation, commands substantial premiums for research applications, specialized optical coatings, and quantum technology components.
Standard purity grades dominate volume throughput. Ultra high purity is gaining share fastest around advanced materials research funding expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-setting power in palladium concentrates in South African mining jurisdictions while Chinese automotive demand determines volume absorption rates. This asymmetry shapes procurement strategies and inventory positioning across the value chain.
China
Shanghai and Beijing automotive clusters drive palladium consumption through gasoline vehicle production for domestic and export markets. MEE Phase 6b enforcement tightens real-world emission monitoring through onboard diagnostic data transmission. Provincial environmental bureaus in these municipalities mandate earlier catalyst specification locking in model-year planning cycles.
South Africa
The Bushveld Complex concentrates primary palladium supply through mechanized platinum group metal operations. Electricity grid instability and labor action exposure create supply interruption risk for global automotive supply chains. Rustenburg and Limpopo mining districts host the bulk of mechanized extraction capacity.
United States
Domestic automotive manufacturing in Michigan and Ohio sustains palladium demand through three-way catalyst production for gasoline light-duty vehicles. EPA tailpipe standards determine loading specifications per vehicle platform. Stillwater mining operations in Montana provide North American primary supply diversification.
Germany
Premium automotive manufacturers in Stuttgart and Munich anchor European palladium consumption through high-performance gasoline engine production. Euro 7 emissions framework mandates elevated nitrogen oxide limits requiring higher per-unit catalyst loadings. German automaker procurement departments consolidate multi-year metal-price-hedged supply agreements.
Japan
Electronics manufacturers in Tokyo and Osaka consume high-purity palladium for multi-layer ceramic capacitors and semiconductor packaging applications. METI industrial policy supports advanced materials research funding. Japanese tier-one catalyst suppliers deploy machine learning models for palladium dispersion optimization.
Palladium Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in mining and refining. The palladium market exhibits consolidated upstream supply with fragmented midstream processing and concentrated downstream automotive offtake. Three archetypes dominate: diversified mining majors with Bushveld Complex exposure, North American integrated processors with captive smelter capacity, and junior exploration companies targeting palladium-dominant greenfield deposits. Competitive moves center on backward integration into refining infrastructure and strategic toll-processing partnerships to secure smelter bottleneck access.
Among diversified mining majors, Anglo American Platinum and Sibanye Stillwater exemplify integrated supply chain control through mechanized Bushveld operations and North American processing infrastructure respectively. Platinum Group Metals occupies a position within the advanced exploration tier targeting large-scale palladium-dominant resources. These three companies represent distinct strategic postures: established volume security, regional supply diversification, and resource base expansion.
| Leading Market Players |
|---|
| Platinum Group Metals |
| Zimplats Holdings |
| Sibanye Stillwater |
| Eastern Platinum |
| Solitario Exploration & Royalty |
| Anglo American Platinum |
| New Age Metals |
| Venus Metals Corp. |
| Ivanhoe Mines |
| Others |
Supply Flow & Price Mechanics
Durban-Richards Bay freight corridors channel Bushveld Complex concentrates to global refiners, with rail cost volatility amplifying South African supply premiums while Chinese automotive buyers absorb differentiated pricing across sponge purity grades.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with pricing stratifying across high-purity sputtering targets, standard sponge for catalyst manufacturing, and lower-grade recycled feedstock. Price differentiation centers on MEE compliance certification and volume scale commitments to tier-one suppliers. Cost compression in standard sponge tiers is intensifying because Chinese smelters are expanding toll-processing capacity. Aftermarket catalyst recyclers exhibit highest price sensitivity; semiconductor sputtering target purchasers show least elasticity due to trace-element specification rigidity.
Supply Chain Analysis
Export-control regimes on advanced PGM assay instrumentation limit technology transfer to Russian and Iranian refining operations, constraining secondary supply channel expansion. Primary extraction concentrates in South Africa, Russia, and Zimbabwe; downstream sponge conversion centers on China, Germany, and Japan. The supply chain draws from nickel-copper co-product ores, alluvial deposits, and spent automotive catalyst feedstock. Single-source vulnerability concentrates at Stillwater smelter bottlenecks for North American juniors. Distribution runs through LBMA-accredited vault networks for investment products and just-in-sequence pipeline deliveries for automotive catalyst manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as hydrogen fuel cell membrane deployments create industrial demand channels beyond mature automotive catalyst applications.
For Market Incumbents: Insulate processing margins through captive smelter capacity expansion in North American jurisdictions, offsetting Bushveld electricity grid instability exposure. Secure backward integration into recycling infrastructure before REACH compliance costs escalate for secondary metal recovery. Platinum substitution acceleration represents the core threat to long-term demand structural integrity. For New Entrants and Emerging Players: Palladium-dominant greenfield deposits in Montana and Ontario represent the most penetrable entry point, given toll-processing agreement scarcity elsewhere. Hydrogen economy foil applications for proton exchange membrane electrolyzers offer uncaptured white-space demand. Pursue offtake partnerships with Japanese tier-one catalyst suppliers deploying machine learning formulation optimization. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors junior explorers with advanced palladium-dominant resource definitions and secured processing pathways. Five-to-ten year viability hinges on automotive emission standard stringency persistence against battery electric vehicle penetration. Monitor EPA tailpipe calibration timelines and Euro 7 implementation enforcement as primary inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycling Infrastructure | REACH compliance constraints elevate secondary metal recovery margins for European operators. |
| Long-term Supply Agreement | German automaker procurement departments lock multi-year metal-price-hedged catalyst contracts through 2028 model years. |
| Capacity Expansion | Stillwater processing infrastructure additions diversify North American supply away from Bushveld concentration risk. |
| Joint Venture | Junior miners partner with integrated refiners to secure smelter bottleneck access for greenfield project finance. |
| Technology Licensing | Machine learning catalyst design platforms virtualize palladium dispersion optimization for tier-one suppliers. |
Methodological Framework
A spread of perspectives from Bushveld Complex mine planners, automotive catalyst procurement directors, LBMA refinery operators, and hydrogen fuel cell membrane researchers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against customs trade data, SEC 10-K filings from listed PGM producers, vehicle production databases, and MEE enforcement bulletins. Bottom-up segment sizing and top-down macroeconomic cross-checks established analytical triangulation.
Demand-supply balance modeling across the projection horizon incorporated vehicle fleet expansion trajectories, emission standard loading specifications, and substitution technology maturation curves. Segmentation dimensions included physical form, purity grade, end-use application, and regional regulatory cluster. CAGRs were derived from metal intensity projections per catalyst unit and fleet composition shifts. Hydrogen economy infrastructure deployment schedules and urban air mobility propulsion requirements informed alternative demand channel estimates.
Practitioners should monitor platinum-for-palladium substitution breakthroughs, battery electric vehicle penetration rates, and Bushveld electricity grid stability indicators for early signals. Forecasts reflect assumptions about sustained automotive catalyst demand and hydrogen economy foil application scaling. Material shifts in EPA or Euro 7 regulatory calibration, or step-change advances in platinum gasoline catalyst viability, would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Tinplate Market
Metals
Cobalt Market
Metals
Global Flat Carbon Steel Market
Metals
Beryllium Copper for Telecommunication Market
Metals
Steel Ingots Market
Metals
United States Aluminum Extrusion Market
Metals
Aluminum Ingots Market
Metals
Copper Wire Market
Metals
Rubidium Market
Metals
Rare Earth Metals Market
Metals
Copper Azoles Market
Metals
Huntite Market
Metals
Molybdenum Market
Metals
Stainless Steel Foil Market
Metals
Global Precious Metal Market
Metals
Recycled Metal Market