
 Ferro Aluminum Market | 2026-2036
Ferro Aluminum Market Size, Share, and Industry Trends Forecast 2026-2036
Ferro Aluminum Market Foresight
Multi-source procurement among steelmakers and foundries is pivoting toward tighter qualification of ferro aluminum suppliers. Alcoa Corporation leverages its captive bauxite and alumina positions to control feedstock costs across North American alloy operations. Rusal anchors its ferro aluminum output to Siberian hydropower, sustaining cost advantages in energy-intensive smelting. Vedanta Resources Limited competes through integrated aluminum-to-alloy circuits at its Indian operations, reducing tolling dependencies.
Ferro aluminum denotes iron-aluminum alloys typically containing 30-40% aluminum by weight, produced via aluminothermic reduction or electric furnace smelting for use as deoxidizers and grain refiners in steel and cast iron production. The alloy's primary purpose centers on improving castability, tensile strength, and corrosion resistance in finished metal products. Ferro-Silicon-Aluminum formulations dominate volume flows into foundry applications, where the silicon addition enhances fluidity in complex castings. Aerospace and automotive applications represent the fastest-growing demand pools, driven by lightweighting mandates and thermal management requirements in powertrain and airframe assemblies. Direct sales channels capture premium-margin alloy contracts from large OEMs and tier-one metalworking firms, while wholesale distribution serves fragmented foundry customers across emerging industrial clusters.
EPA emissions standards in the United States and EU Green Deal carbon border adjustments are tightening allowable carbon intensities for imported ferro alloys, compelling producers to document smelter energy sources. China's MEE enforces dual carbon compliance timelines that favor hydropower-based and recycled-content alloy production over coal-dependent routes. India's BIS certification requirements for ferro alloys used in infrastructure-grade steel create non-tariff barriers that reward domestic producers with approved laboratory testing. Stakeholders must monitor evolving carbon accounting rules and regional certification reciprocity agreements to secure long-term alloy supply positions.
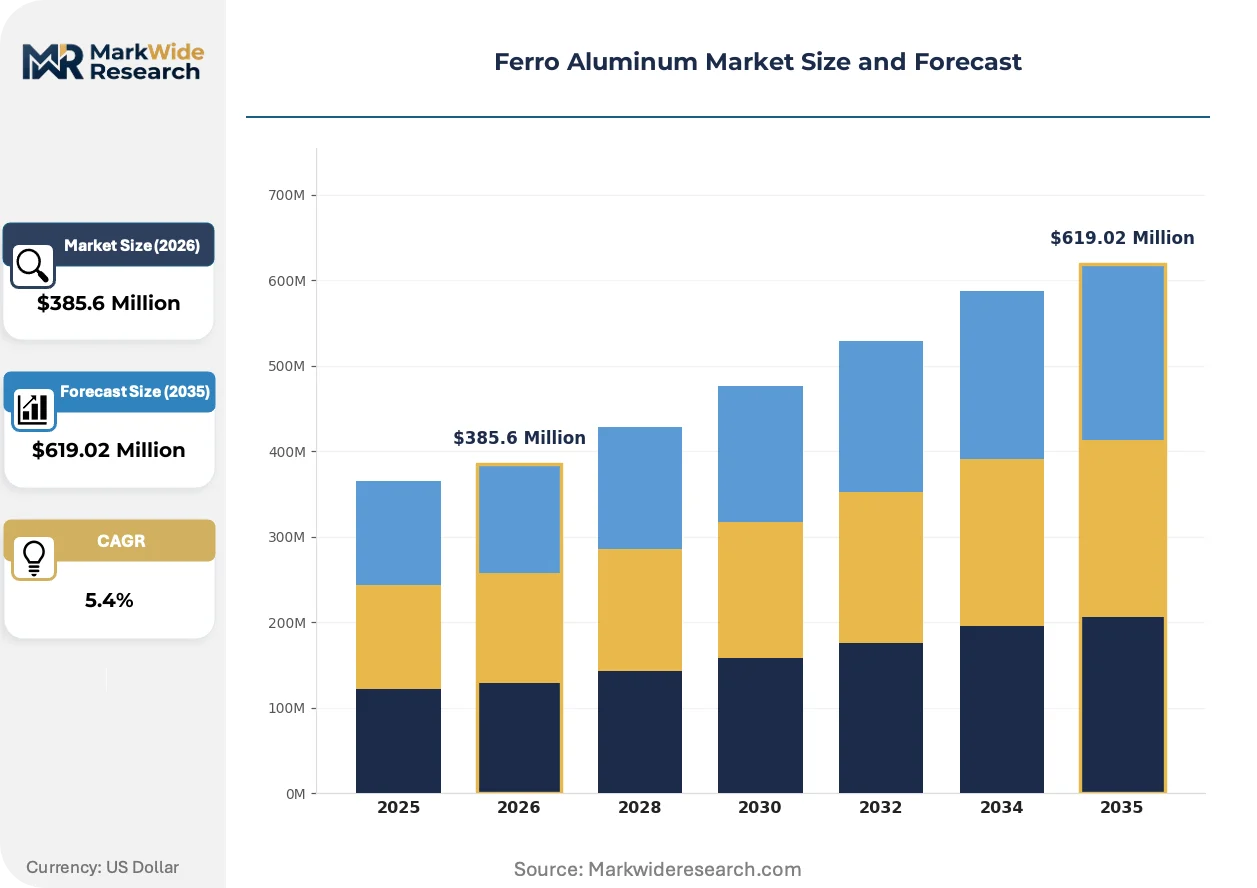
Market Dynamics
Automotive OEMs in Europe and China's dual carbon mandates are restructuring ferro aluminum procurement, forcing smelters to document energy provenance and alloy carbon intensity while foundries consolidate supplier lists to qualified low-carbon sources.
Growth Catalysts
- EU Green Deal carbon border adjustments:Import tariffs on high-carbon ferro alloys are redirecting European automotive procurement toward hydropower-certified suppliers, accelerating qualification timelines for low-emission smelters.
- India's western industrial corridor:Foundry clusters in Gujarat and Maharashtra serving domestic auto and electrical equipment makers are concentrating demand for standardized ferro aluminum grades, creating volume pull for domestic producers.
- Aluminothermic reduction efficiency gains:Process heat recovery systems are lowering unit energy consumption in alloy production, improving margins for electric furnace operators competing against coal-dependent Chinese supply.
Market Restraints
- Alumina feedstock volatility:Bauxite supply disruptions from Guinea and Indonesia are transmitting price shocks to ferro aluminum cost structures, compressing margins for non-integrated producers.
- Siberian hydropower concentration:Rusal's dominance in low-carbon smelting creates geographic supply risk, with European buyers exposed to sanctions-related logistics disruptions.
- Ferro-silicon substitution:Silicon-based deoxidizers are capturing share in lower-specification steel applications, limiting ferro aluminum volume growth in commodity-grade foundry markets.
Strategic Opportunities
- India BIS certification expansion:Infrastructure-grade steel mandates are creating non-tariff barriers that reward domestic alloy producers with approved laboratory testing, locking out unqualified imports.
- Aerospace thermal management applications:Powertrain and airframe assemblies requiring precise grain refinement represent an emerging premium segment for high-purity ferro aluminum formulations.
- Direct OEM contracting channels:Tier-one metalworking firms are bypassing wholesale distributors to secure long-term alloy supply agreements with carbon disclosure requirements.
Industry Challenges
- Carbon accounting skill gaps:Smelters lack in-house expertise to document Scope 2 emissions per EU Green Deal and China MEE reporting standards, delaying market access.
- Electric furnace capex intensity:Conversion from coal-powered to hydropower-based smelting requires capital deployment that stranded asset risk discourages.
- Recycled-content certification complexity:Post-consumer aluminum traceability systems remain underdeveloped, complicating compliance with China's dual carbon recycled-content targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ferro Aluminum Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $619.02 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ferro-Silicon-Aluminum, Ferro-Aluminum-Manganese, Alloyed Ferro Aluminum, Miscellaneous Ferro Aluminum Application: Aerospace, Automotive, Construction, Electrical End User: Manufacturers, OEMs, Metalworking Industry, Foundries Distribution Channel: Wholesale, Direct Sales, Retail, Online Platforms |
| Companies Covered | Alcoa Corporation, Rusal, Glencore plc, Rio Tinto, Hindalco Industries, Vedanta Resources Limited, Norsk Hydro ASA, China Hongqiao Group, South32, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ferro Aluminum Market Shifts & Advancements
Smelting technology and procurement transparency requirements are restructuring how ferro aluminum flows from producer to end-use, with energy provenance displacing price as the primary qualification criterion.
Inert anode technology for aluminum smelting is electrifying carbon-free primary metal production, with pilot deployments at European and North American sites accelerating. Aerospace and automotive OEMs are prioritizing these inputs for structural lightweighting programs. The technology is compressing the carbon intensity gap between primary and recycled aluminum alloys, reshaping feedstock sourcing for ferro aluminum producers.
China's MEE enforcement of dual carbon compliance timelines is tightening emissions standards for coal-dependent alloy routes, favoring hydropower-based and recycled-content production. Smelters in Yunnan and Sichuan provinces are capturing market share from Shanxi and Shandong coal-based competitors. The policy shift is fragmenting Chinese export supply into carbon-tiered categories with diverging European market access.
Foundry procurement teams are consolidating supplier panels from fragmented wholesale channels toward direct mill relationships with documented energy sources. Tier-one automotive metalworkers in Germany and Japan are displacing spot-market purchasing with multi-year alloy contracts containing carbon-intensity clauses. This concentration is most visible in India's western industrial corridor, where domestic foundry clusters now mandate BIS-certified supply with smelter energy disclosure.
Ferro Aluminum Market Segmentation
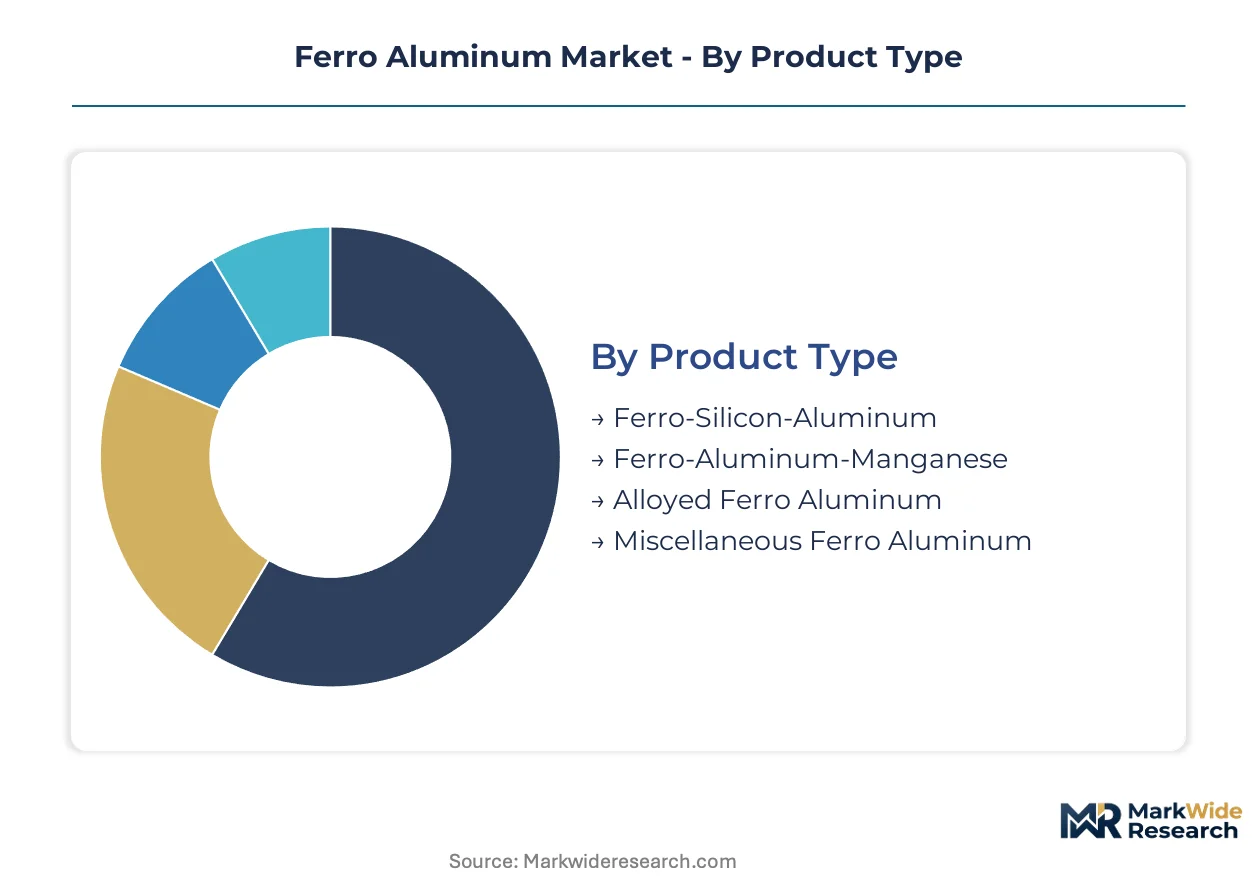
Ferro aluminum alloys vary sharply in aluminum content, silicon ratios, and grain-refining potency, creating distinct procurement tiers across steelmaking and foundry operations. Specification mismatches between supplier capabilities and end-use thermal requirements drive qualification failures and contract losses.
Product Type:
Aluminum-to-iron ratios and additive elements define alloy performance in deoxidation and grain refinement cycles.
- Ferro-Silicon-Aluminum:This alloy combines 30-40% aluminum with 15-25% silicon to enhance fluidity in complex iron castings. Foundry clusters in India's western industrial corridor specify this grade for automotive transmission housings and electrical motor frames, with BIS certification requirements tightening supplier qualification.
- Ferro-Aluminum-Manganese:Manganese additions improve tensile strength and wear resistance in structural steel applications. European automotive OEMs procure this formulation for lightweight chassis components, driven by EU Green Deal carbon border adjustments that favor documented low-carbon smelter sources.
- Alloyed Ferro Aluminum:Custom compositions with chromium, titanium, or vanadium additions target aerospace thermal management specifications.
- Miscellaneous Ferro Aluminum:Niche formulations including low-aluminum variants serve specialty deoxidation requirements in stainless steel production.
Ferro-Silicon-Aluminum leads on scale; Ferro-Aluminum-Manganese leads on momentum.
Application:
End-use thermal and mechanical requirements dictate alloy purity thresholds and carbon-intensity documentation burdens.
- Automotive:Powertrain lightweighting mandates and crashworthiness specifications consume high-purity ferro aluminum for engine blocks and suspension arms. German and Japanese tier-one metalworkers now require smelter energy disclosure in multi-year supply contracts.
- Aerospace:Airframe assemblies and turbine housings demand precise grain refinement with trace-element control. This segment expands most quickly as OEMs prioritize inert anode aluminum inputs for structural components.
- Construction:Rebar and structural steel deoxidation uses standard-grade alloys with less stringent carbon accounting.
- Electrical:Transformer housings and motor frames in India's western corridor specify silicon-enhanced grades for castability.
Automotive commands volume concentration; Aerospace commands premium expansion.
End User:
Procurement scale and technical capability separate direct mill relationships from wholesale-dependent buyers.
- OEMs:Tier-one automotive and aerospace assemblers negotiate multi-year contracts with carbon-intensity clauses, bypassing distribution layers to lock qualified smelter capacity.
- Foundries:Fragmented operations across emerging industrial clusters depend on wholesale distributors for standardized grades, though India's BIS certification requirements are consolidating supplier panels.
- Manufacturers:Steel mills with in-house metallurgical laboratories qualify alloys directly for deoxidization protocols.
- Metalworking Industry:Tier-two fabricators and job shops purchase spot-market volumes with limited specification negotiation.
OEMs lead on contract value; Foundries lead on transaction frequency.
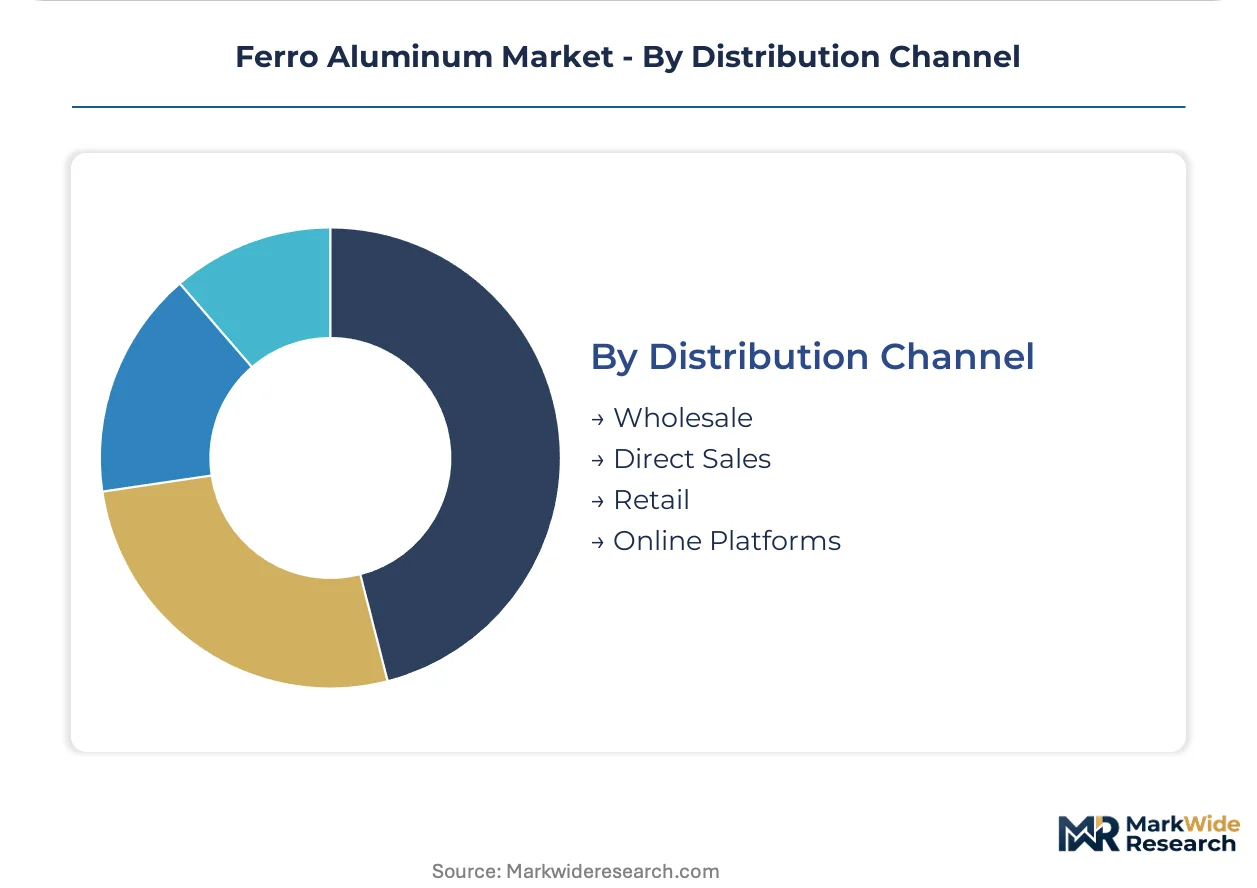
Distribution Channel:
Channel selection reflects buyer scale, specification complexity, and carbon documentation requirements.
- Direct Sales:Large-volume contracts from qualified smelters to automotive OEMs and tier-one metalworkers include energy provenance documentation and multi-year price mechanisms.
- Wholesale:Distributors serve fragmented foundry demand across India's western industrial corridor, consolidating small-lot orders into mill-direct volumes.
- Retail:Local metal traders supply emergency and spot requirements for maintenance-grade alloys.
- Online Platforms:Digital procurement channels emerge for standardized grades with transparent carbon-tiered pricing.
Direct Sales leads on margin capture; Wholesale leads on geographic reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting ferro aluminum production toward jurisdictions with favorable energy costs and lower carbon-compliance burdens, reshaping trade flows and smelter investment patterns.
China
MEE enforcement of dual carbon timelines is fragmenting domestic supply into carbon-tiered categories. Smelters in Yunnan and Sichuan provinces leverage hydropower advantages to capture share from coal-dependent competitors in Shanxi and Shandong. The Pearl River Delta and Yangtze River Delta clusters now export differentiated alloy grades with diverging European market access.
India
BIS certification requirements for infrastructure-grade steel are creating non-tariff barriers that reward domestic producers with approved laboratory testing. Foundry clusters in Gujarat and Maharashtra concentrate demand for standardized ferro aluminum grades serving automotive transmission housings and electrical motor frames. Vedanta Resources Limited operates integrated aluminum-to-alloy circuits reducing tolling dependencies.
Germany
EU Green Deal carbon border adjustments redirect automotive procurement toward hydropower-certified suppliers. Tier-one metalworkers in Bavaria and Baden-Württemberg negotiate multi-year contracts with carbon-intensity clauses. The KBA enforces documentation standards that accelerate qualification timelines for low-emission smelters supplying lightweight chassis components.
United States
EPA emissions standards tighten allowable carbon intensities for imported ferro alloys, compelling producers to document smelter energy sources. Alcoa Corporation leverages captive bauxite and alumina positions to control feedstock costs across North American alloy operations. The Southeast industrial corridor concentrates foundry demand from domestic auto and electrical equipment makers.
Russia
Rusal anchors ferro aluminum output to Siberian hydropower, sustaining cost advantages in energy-intensive smelting. European buyers face sanctions-related logistics disruptions despite preferring low-carbon supply. The geographic concentration creates supply risk for automotive OEMs seeking documented energy provenance.
Ferro Aluminum Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue carbon-certified specialty formulations and direct OEM contracting channels. The vendor base stratifies across integrated miners with captive feedstock, regional smelters with energy-cost advantages, and trading houses with distribution reach. Three archetypes dominate: upstream-integrated majors controlling bauxite-to-alloy value chains; hydropower-anchored smelters leveraging clean energy credentials; and foundry-focused distributors serving fragmented demand. Competitive moves center on backward integration into alumina refining and strategic partnerships with automotive OEMs for multi-year supply agreements.
Among upstream-integrated majors, Alcoa Corporation and Rio Tinto exemplify the feedstock-control archetype through their bauxite and alumina positions. Rusal occupies a distinctive position as the hydropower-anchored smelter archetype, with Siberian energy assets supporting low-carbon output claims. Vedanta Resources Limited represents the emerging-market integrated model, with Indian operations spanning aluminum smelting through alloy production. These three companies anchor the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| Alcoa Corporation |
| Rusal |
| Glencore plc |
| Rio Tinto |
| Hindalco Industries |
| Vedanta Resources Limited |
| Norsk Hydro ASA |
| China Hongqiao Group |
| South32 |
| Others |
Supply & Pricing Matrix
Captive bauxite-to-alloy integration at Alcoa Corporation and Vedanta Resources Limited anchors supply positions while compressing tolling margins for non-integrated competitors. This upstream control translates into pricing power over ferro aluminum formulations, particularly where EU Green Deal carbon border adjustments and China's MEE dual carbon enforcement create tiered market access based on documented energy provenance.
Pricing Analysis
Distributor margins in wholesale channels serving India's western foundry clusters absorb 8-12 percentage points above direct mill pricing to automotive OEMs. Contract-based long-term offtake dominates tier-one procurement, with carbon-intensity certification and volume scale as the primary price differentiation drivers. Cost compression in standard-grade ferro-silicon-aluminum is intensifying because silicon-based deoxidizers capture share in commodity steel applications. Foundries remain most price-sensitive, while aerospace OEMs accept premiums for trace-element-controlled formulations.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German and Japanese automotive metalworkers, bypassing wholesale layers entirely. Supply concentrates in China, India, and Russia, with raw material dependencies on Guinean bauxite, Indonesian alumina, and Siberian hydropower. Tariff exposure from EU carbon border adjustments creates structural risk for coal-dependent Chinese exporters. Distribution runs through three distinct tiers: mill-direct contracts, regional distributors consolidating small-lot orders, and local metal traders for emergency spot requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Siberian hydropower-cost structures and European carbon-compliance premiums, rewarding positioning across energy-provenance tiers.
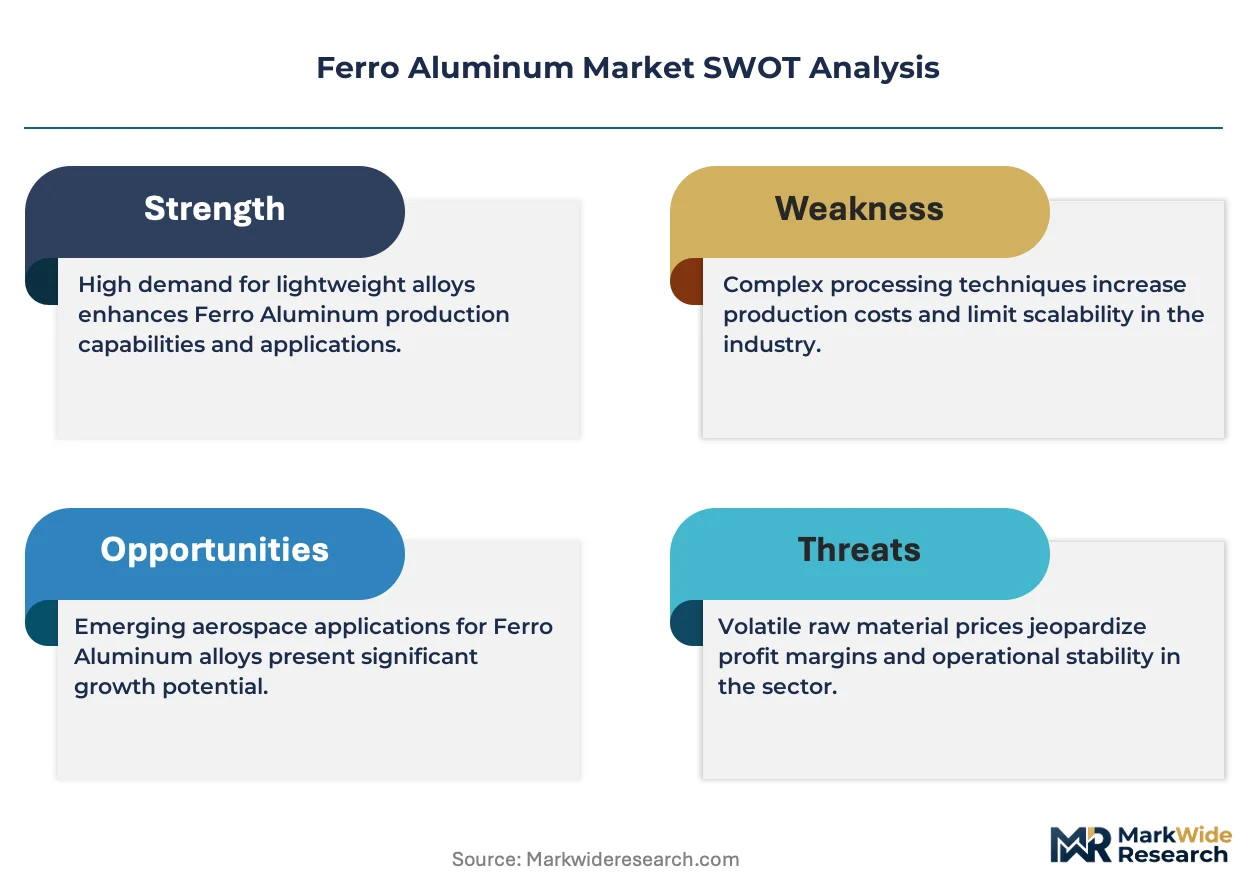
For Market Incumbents: Hedge against alumina feedstock volatility through backward integration into bauxite refining or captive supply agreements with Guinean and Australian miners. Lock qualified smelter capacity through multi-year OEM contracts containing carbon-intensity clauses before EU Green Deal enforcement tightens. Certification investment in BIS-approved laboratory testing secures access to India's infrastructure-grade steel market.
For New Entrants and Emerging Players: The 15-20% price-point gap between hydropower-certified premium grades and coal-based economy formulations creates entry space for mid-tier producers with documented clean energy transitions. Target India's western industrial corridor foundry clusters, where BIS certification requirements are consolidating supplier panels and displacing unqualified imports. Go-to-market through direct mill relationships with carbon disclosure documentation rather than wholesale distribution.
For Investors and Strategic Acquirers: Roll-up economics work for hydropower-anchored regional smelters because carbon-accounting skill scarcity and electric furnace capex intensity prevent greenfield competition. Platform consolidation across Yunnan and Sichuan province assets captures structural advantage as China's MEE enforcement fragments domestic supply. Watch for EU carbon border adjustment implementation timing as the inflection signal for premium-tier demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Refining | Captive alumina supply insulates Alcoa and Vedanta from Guinean export disruptions. |
| Hydropower Certification Program | Rusal's Siberian energy documentation secures EU automotive procurement despite logistics risks. |
| BIS Laboratory Accreditation | Domestic Indian producers lock out unqualified imports from infrastructure steel applications. |
| Long-term OEM Supply Agreement | German tier-one metalworkers bypass wholesale channels with carbon-intensity contract clauses. |
| Electric Furnace Capacity Conversion | Process heat recovery systems improve margins against coal-dependent Chinese competitors. |
Research Methodology
Direct dialogue with ferro aluminum plant managers, automotive OEM procurement leads, foundry technical directors, and distribution channel partners grounded qualitative findings in operational reality. Secondary validation drew from customs and trade data, SEC 10-K filings of integrated miners, BIS certification registries, and EU carbon border adjustment documentation. Bottom-up alloy production estimates and top-down steel consumption models were triangulated against smelter capacity disclosures.
Market size and growth trajectory outputs across the projection horizon reflect segmented modeling by aluminum-to-iron ratio grade, end-use application, and regional regulatory cluster. CAGRs were derived from production capacity expansion schedules, OEM lightweighting program timelines, and carbon policy implementation trajectories. Forecast inputs included bauxite supply disruption probabilities, hydropower availability curves, and foundry cluster demand concentration patterns.
Caveats apply where alumina price spikes, sanctions-related logistics disruptions, or recycled-content certification breakthroughs could materially shift the outlook. Forecasts reflect documented assumptions about MEE enforcement timelines and EU carbon border adjustment scope. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Ferrite Market
Metals
Metallurgical Silicon Market
Metals
Silver Nitrate Market
Metals
North America Aluminum Market
Metals
High-End Copper Foil Market
Metals
Beryllium Copper for Telecommunication Market
Metals
Titanium Mill Products Market
Metals
Clutch Spring Wires Market
Metals
Europe Aluminum Extrusion Market
Metals
316 Stainless Steel Container Market
Metals
Silver Cyanide Market
Metals
Neodymium Market
Metals
Grain Oriented Electrical Steel Market
Metals
Copper Foil Market
Metals
Electrolytic Manganese Metal Market
Metals
North America Electrical Steel Market