
 Magnetic Shielding Sheets Market | 2026-2036
Magnetic Shielding Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetic Shielding Sheets Market Analytics
Specialized metallurgical engineering talent is rotating toward rare-earth alloy formulation and precision rolling capabilities, tightening labor availability for conventional shielding production. Magnetic Shield Corporation leverages captive annealing expertise to sustain premium-grade mu-metal output for defense and medical OEMs. TDK anchors Asian supply networks through integrated ferrite and nanocrystalline sheet operations. Vacuumschmelze competes on ultra-high-permeability cobalt-iron alloys, dominating European aerospace qualification programs.
Magnetic shielding sheets are thin-gauge ferromagnetic or conductive laminates, typically manufactured through cold rolling, hydrogen annealing, and surface oxidation control to achieve permeability values exceeding 80,000. These components attenuate electromagnetic interference by redirecting magnetic flux lines away from sensitive instrumentation in MRI suites, satellite payloads, and EV power electronics. Nickel-based alloys command the widest specification coverage across medical and aerospace end users, while custom-shaped form factors capture the fastest expansion as OEMs integrate shielding into compact device architectures. Copper and aluminum segments occupy cost-driven volume tiers in consumer electronics and standard communication enclosures where moderate attenuation satisfies operational requirements.
FDA device electromagnetic compatibility standards and EU MDR conformity requirements shape material traceability and lot certification protocols for medical-grade shielding suppliers. EPA hazardous air pollutant rules and OSHA workplace exposure limits govern foundry and annealing operations, elevating capital intensity for domestic North American production. Stakeholders must monitor evolving IEC electromagnetic compatibility test standards and NHTSA vehicle-level immunity specifications to anticipate qualification burdens before design-in commitments solidify.
Market Dynamics
Specialized metallurgical engineering talent is rotating toward rare-earth alloy formulation and precision rolling capabilities, tightening labor availability for conventional shielding production and compressing lead times for high-permeability material qualification.
Growth Catalysts
- EU F-Gas Regulation:REACH compliance requirements are reshaping material selection criteria for European manufacturers, accelerating procurement of hydrogen-annealed nickel-iron alloys that eliminate fluorinated process gases.
- Electromagnetic interference mitigation:FDA electromagnetic compatibility standards for diagnostic imaging equipment are tightening shielding performance thresholds in MRI suite construction across North American hospital networks.
- Germany's industrial corridor:Precision engineering clusters in Bavaria and Baden-Württemberg anchor OEM supply agreements for next-generation diagnostic hardware, concentrating demand for custom-shaped mu-metal form factors.
Market Restraints
- Nickel price volatility:LME nickel contract fluctuations transmit directly into input cost structures for 80%+ nickel alloy formulations, compressing margin buffers for non-integrated processors.
- Annealing capacity concentration:Hydrogen annealing furnace availability clusters in Germany, Japan, and the United States, creating geographic chokepoints for premium-grade material output.
- Amorphous metal substitution:Nanocrystalline ribbon products from integrated ferrite operations are capturing moderate-frequency shielding applications below 100 kHz.
Strategic Opportunities
- EV power electronics:NHTSA vehicle-level immunity specifications are mandating onboard shielding for 800-volt architectures, opening specification windows for cobalt-iron laminates in traction inverter housings.
- India PLI scheme:Production-linked incentives for electronics manufacturing are attracting magnetic component assembly investments in Tamil Nadu and Karnataka, creating localized demand for standard-grade shielding sheet.
- IEC 61000-4-8 convergence:Harmonized power-frequency magnetic field immunity testing across medical and industrial equipment categories is unifying qualification protocols and reducing certification duplication costs.
Industry Challenges
- Hydrogen annealing expertise scarcity:Retiring furnace operators in traditional manufacturing regions are constraining throughput expansion for ultra-high-permeability material grades.
- Lot certification timeline compression:FDA and EU MDR traceability requirements are extending material qualification cycles from 12 weeks to 20+ weeks for medical-grade shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetic Shielding Sheets Market |
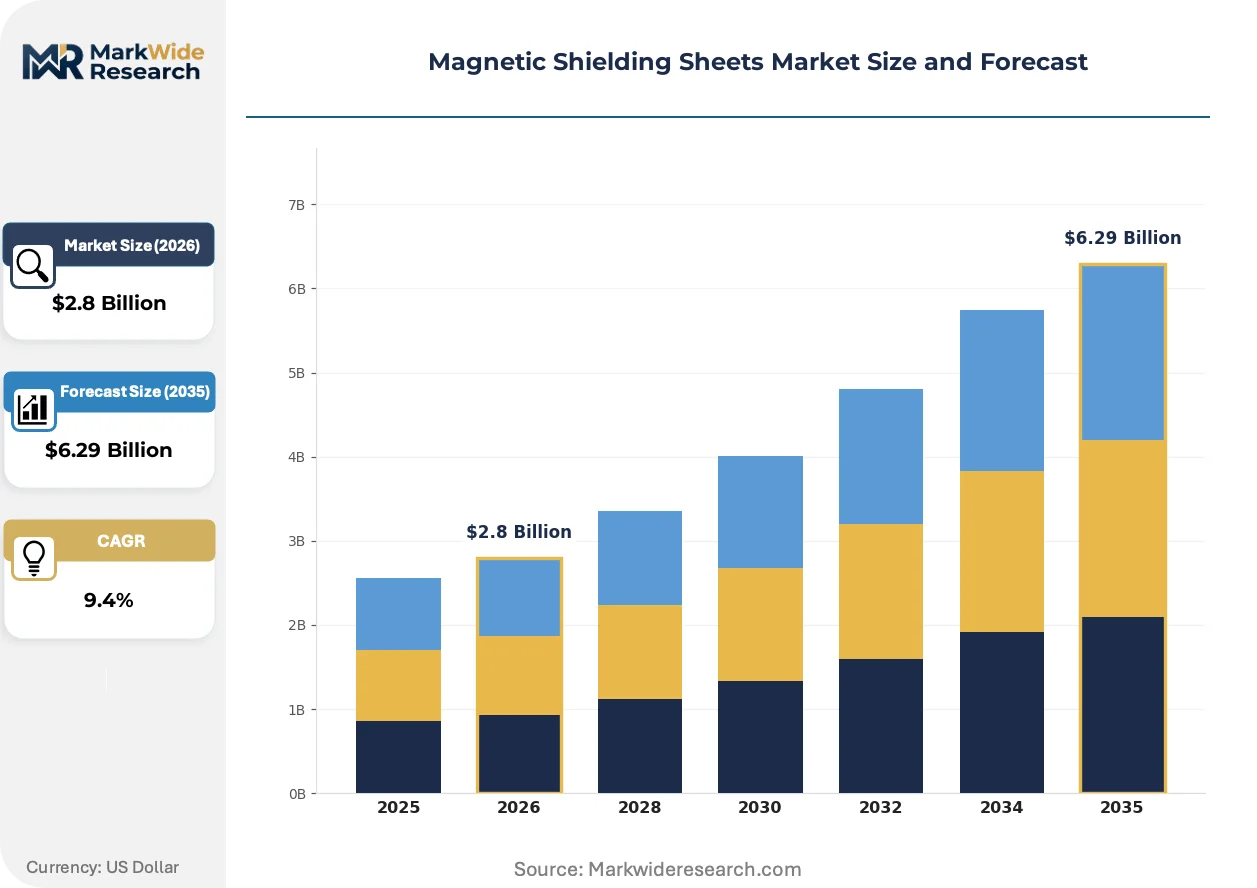
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Copper, Steel, Aluminum, Nickel End User: Electronics, Aerospace, Automotive, Medical Devices Application: Operational Equipment, Consumer Electronics, Communication Systems, Power Supply Units Form: Sheet, Foil, Tape, Custom Shapes |
| Companies Covered | Magnetic Shield Corporation, MuShield Company, 3M, Amuneal Manufacturing, Hitachi Metals, TDK, Vacuumschmelze, Magnetic Shields, Minoru, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetic Shielding Sheets Market Evolving Landscape
Material scientists and process engineers are converging on thinner-gauge, higher-permeability solutions that integrate directly into compact device architectures rather than retrofitting external enclosures.
Multilayer nanocrystalline-amorphous composites are achieving permeability values exceeding 100,000 while maintaining mechanical flexibility for complex geometries. Satellite payload manufacturers and implantable medical device OEMs are specifying these laminates for weight-critical applications. The technology is miniaturing shielding enclosures from centimeter-scale housings to millimeter-scale integrated packages.
EPA hazardous air pollutant rules governing foundry emissions are elevating capital intensity for domestic North American hydrogen annealing operations. Compliance investments are diverting expansion capital toward emission control retrofits rather than greenfield capacity. Medical-grade suppliers with existing EPA Title V permits are consolidating qualification advantages over new market entrants.
Buyers in aerospace and defense segments are unbundling material supply from fabrication services, contracting directly with alloy producers for certified sheet stock while retaining specialized forming partners. This disintermediation is compressing channel margins for traditional distributor-fabricator intermediaries. German and Japanese OEMs are pioneering direct mill relationships that specify surface oxidation control parameters at the rolling stage rather than post-processing.
Magnetic Shielding Sheets Market Segmentation
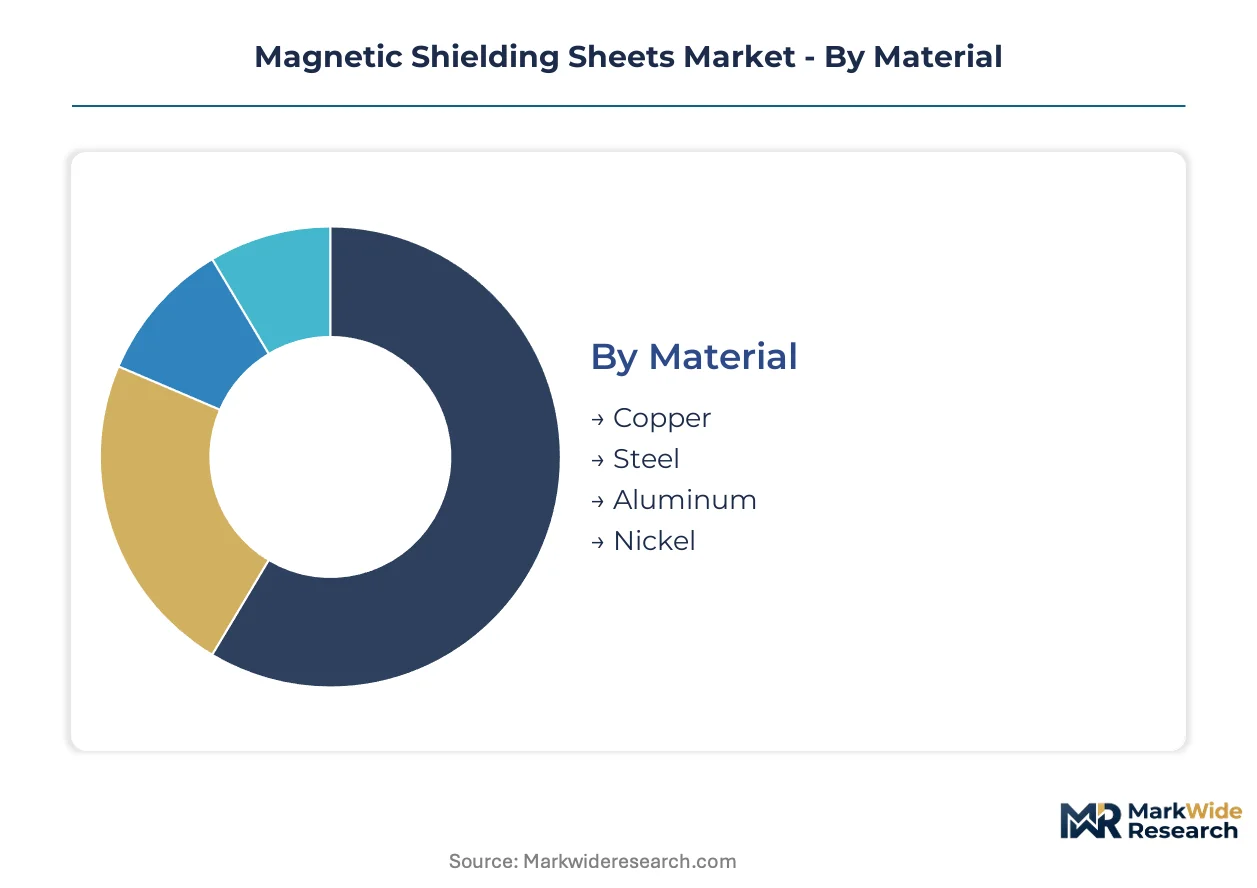
Magnetic shielding sheets fragment across material chemistry, end-use performance thresholds, and geometric form factors. Procurement patterns diverge sharply between domestic specification-grade supply and export-oriented volume tiers.
Material:
Domestic production concentrates on nickel-iron and specialty cobalt alloys serving FDA-regulated medical device manufacturers, while copper and aluminum volumes flow primarily toward Asian export markets for consumer electronics.
- Nickel:High-permeability nickel-iron alloys, typically 80%+ nickel content with hydrogen annealing, achieve permeability values exceeding 80,000 for MRI suite shielding. Bavarian precision engineering clusters in Germany anchor procurement for diagnostic imaging OEMs facing tightened EU MDR conformity requirements.
- Copper:Oxygen-free copper laminates provide broadband electromagnetic interference attenuation across radio frequency ranges. Tamil Nadu and Karnataka electronics manufacturing corridors under India's PLI scheme drive volume demand for standard-grade sheet stock in smartphone and tablet enclosures.
- Steel:Cold-rolled low-carbon steel offers cost-positioned shielding for industrial enclosures where moderate permeability satisfies operational requirements.
- Aluminum:Lightweight aluminum sheets serve aerospace weight-critical applications and automotive 800-volt traction inverter housings subject to NHTSA vehicle-level immunity specifications.
Nickel commands the established base. The steepest expansion runs through aluminum.
End User:
Customer segmentation reflects divergent certification burdens, with medical and aerospace buyers demanding lot-level traceability while automotive and electronics procurement prioritizes scale economies.
- Medical Devices:MRI manufacturers and implantable device OEMs specify ultra-high-permeability mu-metal for electromagnetic compatibility compliance under FDA device standards. Hydrogen annealing expertise scarcity in traditional manufacturing regions constrains qualified supplier expansion.
- Electronics:Consumer device manufacturers integrate thin-gauge shielding directly into compact architectures. Surface-mount compatible form factors are displacing external enclosure retrofit approaches.
- Aerospace:Satellite payload manufacturers specify multilayer nanocrystalline composites for weight-critical shielding applications. Direct mill relationships specify surface oxidation control parameters at rolling stage.
- Automotive:EV power electronics shielding demand concentrates in 800-volt traction inverter housings. NHTSA immunity specifications mandate onboard attenuation for high-voltage architectures.
Medical Devices commands the established base. Electronics shows the steepest climb.
Application:
Application segmentation tracks frequency domain requirements, with power-frequency shielding diverging from radio-frequency and microwave attenuation specifications.
- Communication Systems:Base station and satellite ground equipment demand broadband shielding across 100 kHz to 6 GHz ranges. IEC 61000-4-8 harmonized testing protocols reduce certification duplication across medical and industrial categories.
- Power Supply Units:Switching power supplies require attenuation of conducted and radiated emissions at fundamental and harmonic frequencies. Custom-shaped form factors integrate shielding into compact converter architectures.
- Operational Equipment:Industrial control systems specify moderate-permeability solutions for factory automation electromagnetic compatibility.
- Consumer Electronics:Smartphones, tablets, and wearables drive volume demand for sub-millimeter gauge laminates with mechanical flexibility for complex geometries.
Communication Systems commands the established base. Consumer Electronics gains share fastest.
Form:
Form factor segmentation reflects manufacturing integration depth, with raw sheet supply separating from value-added fabrication services.
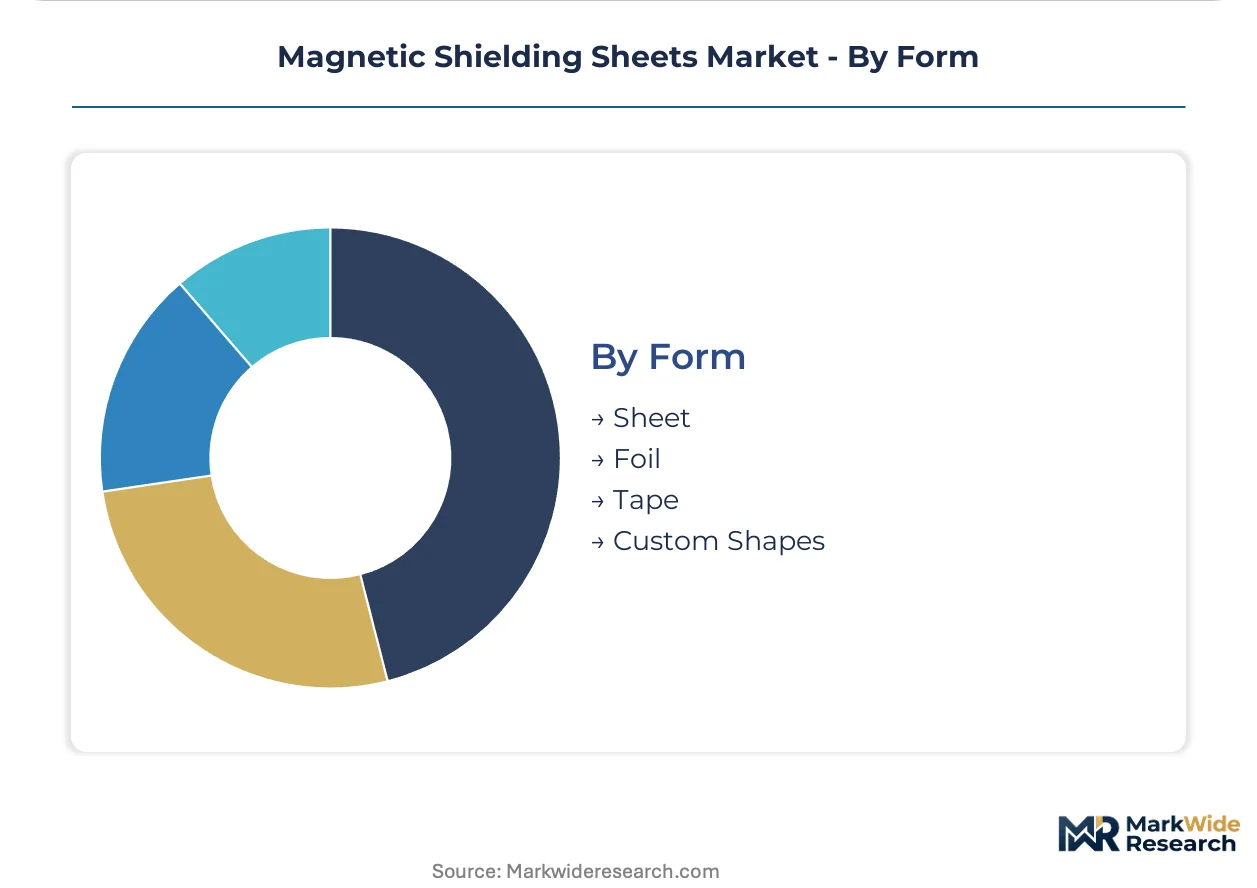
- Custom Shapes:Stamped, drawn, and CNC-formed components integrate directly into device architectures rather than retrofitting external enclosures. German and Japanese OEMs pioneer direct mill relationships specifying form factor at alloy production stage.
- Sheet:Standard-width cold-rolled sheet serves fabrication shops and distributor-fabricator intermediaries facing margin compression from buyer disintermediation.
- Foil:Sub-100 micron gauge foil enables multilayer composite construction and weight-critical satellite applications.
- Tape:Adhesive-backed tape formats serve field installation and repair applications with moderate performance requirements.
Sheet commands the established base. Custom Shapes expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes magnetic shielding sheets predominantly for precision medical and aerospace qualification programs, while the United States channels demand toward defense and FDA-regulated device manufacturing, and Asian markets prioritize volume-scale electronics integration.
United States
Defense procurement and medical device OEMs drive specification-grade demand for hydrogen-annealed nickel-iron alloys. FDA electromagnetic compatibility standards and EPA Title V permits govern domestic production, consolidating qualification advantages for incumbent suppliers. Greater Boston and Pacific Northwest precision engineering clusters anchor OEM supply agreements for next-generation diagnostic hardware.
Germany
Precision engineering clusters in Bavaria and Baden-Württemberg concentrate European demand for ultra-high-permeability mu-metal form factors. EU F-Gas Regulation and REACH compliance requirements are reshaping material selection criteria, accelerating procurement of alloys that eliminate fluorinated process gases. Hydrogen annealing furnace availability clusters in industrial corridors, creating geographic chokepoints for premium-grade material output.
Japan
Integrated ferrite and nanocrystalline sheet operations serve domestic electronics and automotive OEMs. METI industrial standards and JIS certification protocols shape material traceability requirements for medical-grade shipments. Kanto and Kansai manufacturing belts anchor supply networks for compact device architectures in consumer electronics.
China
Electronics manufacturing scale and EV power electronics expansion drive volume demand for standard-grade shielding sheet. MIIT electromagnetic compatibility regulations and GB standards govern domestic equipment qualification. Yangtze River Delta and Pearl River Delta industrial zones concentrate fabrication capacity for export-oriented consumer device manufacturers.
India
Production-linked incentives for electronics manufacturing are attracting magnetic component assembly investments. BIS standards and CDSCO medical device regulations shape import substitution strategies for diagnostic imaging equipment. Tamil Nadu and Karnataka electronics manufacturing corridors under the PLI scheme drive localized demand for standard-grade sheet stock.
Magnetic Shielding Sheets Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive annealing capabilities and alloy formulation expertise separating premium-grade suppliers from volume-oriented processors. The structure concentrates qualification advantages among incumbent players with existing EPA permits and hydrogen furnace access. Two strategic archetypes dominate: integrated alloy producers with backward control over melting and rolling operations, and specialized fabricators focusing on custom-shaped form factors for device integration. Competitive moves center on direct mill relationships that disintermediate traditional distributors, and capacity investments in nanocrystalline composite technologies for weight-critical applications.
Among the integrated alloy producers, Magnetic Shield Corporation and Vacuumschmelze occupy positions exemplifying captive annealing expertise and ultra-high-permeability cobalt-iron specialization respectively. TDK represents the Asian integrated model, anchoring supply networks through diversified magnetic materials operations. These three entities illustrate how geographic clustering of hydrogen annealing capacity in Germany, Japan, and the United States translates into sustained competitive positioning for specification-grade segments.
| Leading Market Players |
|---|
| Magnetic Shield Corporation |
| MuShield Company |
| 3M |
| Amuneal Manufacturing |
| Hitachi Metals |
| TDK |
| Vacuumschmelze |
| Magnetic Shields |
| Minoru |
| Others |
Value Network & Pricing Analysis
Nanocrystalline ribbon substitution for conventional mu-metal in moderate-frequency applications below 100 kHz is simultaneously redrawing procurement geography toward integrated Asian ferrite operations and compressing margin buffers for non-integrated European and North American processors dependent on discrete hydrogen annealing steps.
Pricing Analysis
Long-term offtake contracts dominate specification-grade procurement for FDA-regulated medical device OEMs, while spot-market transactions govern standard-grade electronics volumes. Three-tier pricing structure across premium, standard, and economy levels separates hydrogen-annealed nickel-iron alloys with full lot traceability from cold-rolled steel and aluminum alternatives. Cost compression in the standard tier intensifies because nickel price volatility transmits directly into 80%+ nickel alloy formulations. Electronics manufacturers in Tamil Nadu and Karnataka exhibit the highest price sensitivity, whereas Bavarian precision engineering clusters for diagnostic imaging equipment absorb premium tier premiums without volume elasticity.
Supply Chain Analysis
Strategic stockpiling of certified sheet stock prevails among aerospace and medical device OEMs facing 20+ week lot certification timelines, while just-in-time inventory governs consumer electronics procurement. Geographic supply concentration clusters in Germany, Japan, and the United States for hydrogen-annealed premium grades, with China and India anchoring volume-tier fabrication. Raw material dependencies center on LME-traded nickel, cobalt for high-temperature alloys, and rare-earth elements for nanocrystalline formulations. Single-source vulnerability in hydrogen annealing furnace availability creates chokepoints for ultra-high-permeability material output. Distribution runs through direct mill relationships that disintermediate traditional distributor-fabricator intermediaries, particularly for German and Japanese OEMs specifying surface oxidation control at the rolling stage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnetic shielding sheets sit at an early-cycle expansion phase where NHTSA vehicle-level immunity specifications for 800-volt EV architectures are creating specification windows faster than incumbent capacity can qualify.
For Market Incumbents: Shield premium-grade positioning by deepening captive hydrogen annealing expertise as retiring furnace operators constrain competitor expansion, while securing EPA Title V permit advantages that block new entrant qualification for medical-grade shipments. Prioritize backward integration into cobalt-iron alloy melting to defend margin position against nickel price volatility. For New Entrants and Emerging Players: Custom-shaped form factor fabrication services represent the most penetrable white-space where integrated alloy producers under-serve device-integrated shielding demand, particularly for satellite payload manufacturers and implantable medical device OEMs specifying multilayer nanocrystalline composites. Target Tamil Nadu and Karnataka electronics corridors under India's PLI scheme with standard-grade sheet stock positioned for localized magnetic component assembly. For Investors and Strategic Acquirers: The market sits at a qualification-constrained expansion phase that favors incumbent alloy producers with existing EPA permits and hydrogen furnace access over greenfield entrants facing 20+ week certification timelines. Acquisition targets should display captive annealing capabilities and established aerospace or medical OEM qualification programs. Watch IEC 61000-4-8 harmonization progress as the signal for certification burden reduction that could accelerate design-in velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Annealing Capacity Expansion | Captive furnace investments in Germany and the United States consolidate premium-grade supply advantages as operator scarcity tightens. |
| Direct Mill Relationship Formation | Bypassing distributor-fabricator intermediaries allows German and Japanese OEMs to specify surface oxidation parameters at rolling stage. |
| Nanocrystalline Composite Development | Multilayer laminates exceeding 100,000 permeability capture satellite and implantable device specifications from conventional mu-metal. |
| Cobalt-Iron Alloy Backward Integration | Upstream control over melting operations insulates margin buffers from LME nickel contract fluctuations in 80%+ nickel formulations. |
| EPA Title V Permit Acquisition | Existing emission control authorizations block new entrant qualification for FDA-regulated medical-grade shielding shipments. |
Research Methodology
Desk research of trade association filings, customs records, and electromagnetic compatibility test standards preceded structured interviews with hydrogen annealing furnace operators, precision engineering procurement managers at Bavarian diagnostic imaging OEMs, biomedical engineers specifying MRI suite shielding, and magnetic materials R&D directors at integrated alloy producers. Primary fieldwork combined with secondary validation from SEC filings, JIS certification databases, and EU MDR conformity assessment documentation enabled bottom-up and top-down triangulation across material chemistry, end-use performance thresholds, and geometric form factor segments.
Variance decomposition across the projection horizon isolates volume drivers by material tier, end-use certification burden, and regional regulatory cluster. The analytical framework models nickel-iron, cobalt-iron, copper, aluminum, and steel chemistries against medical device, electronics, aerospace, and automotive end users, with form factor segmentation tracking raw sheet, custom shapes, foil, and tape. CAGRs derive from segment-level growth rate reconciliation against macroeconomic anchors and technology substitution curves, with nanocrystalline ribbon penetration and EV power electronics shielding adoption serving as key industry-specific forecast inputs.
Underlying assumptions cover sustained nickel price volatility, hydrogen annealing capacity constraints, and IEC standard harmonization timelines, with deviation risk concentrated in amorphous metal substitution rates and EPA enforcement intensity. Forecasts reflect these conditions without scenario weighting. Revision becomes warranted when nanocrystalline composite permeability values exceed 150,000 in commercial production or when NHTSA expands immunity specifications beyond 800-volt architectures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Cubic Boron Nitrates Market
Advanced Materials
North America Plasma Powder Market
Advanced Materials
APAC Advanced Building Materials Market
Advanced Materials
Advanced Carbon Materials Market
Advanced Materials
Lithium Tantalate Crystal Market
Advanced Materials
Vacuum Insulation Panels Market
Advanced Materials
Natural Single Crystal Diamond Market
Advanced Materials
Flexible Bio-Foams Market
Advanced Materials
Advanced Sports Materials Market
Advanced Materials
Global Synthetic Diamond Market
Advanced Materials
Cold Plasma Market
Advanced Materials
Rigid Foam Market
Advanced Materials
Global Graphene Market
Advanced Materials
Cathode Materials Market
Advanced Materials
Europe Blanket Aerogel Market
Advanced Materials
Global Diamond-Like Carbon (DLC) Market