
 Global Copper Sputtering Target Market | 2026-2036
Global Copper Sputtering Target Market Size, Share, and Industry Trends Forecast 2026-2036
Global Copper Sputtering Target Market Analysis
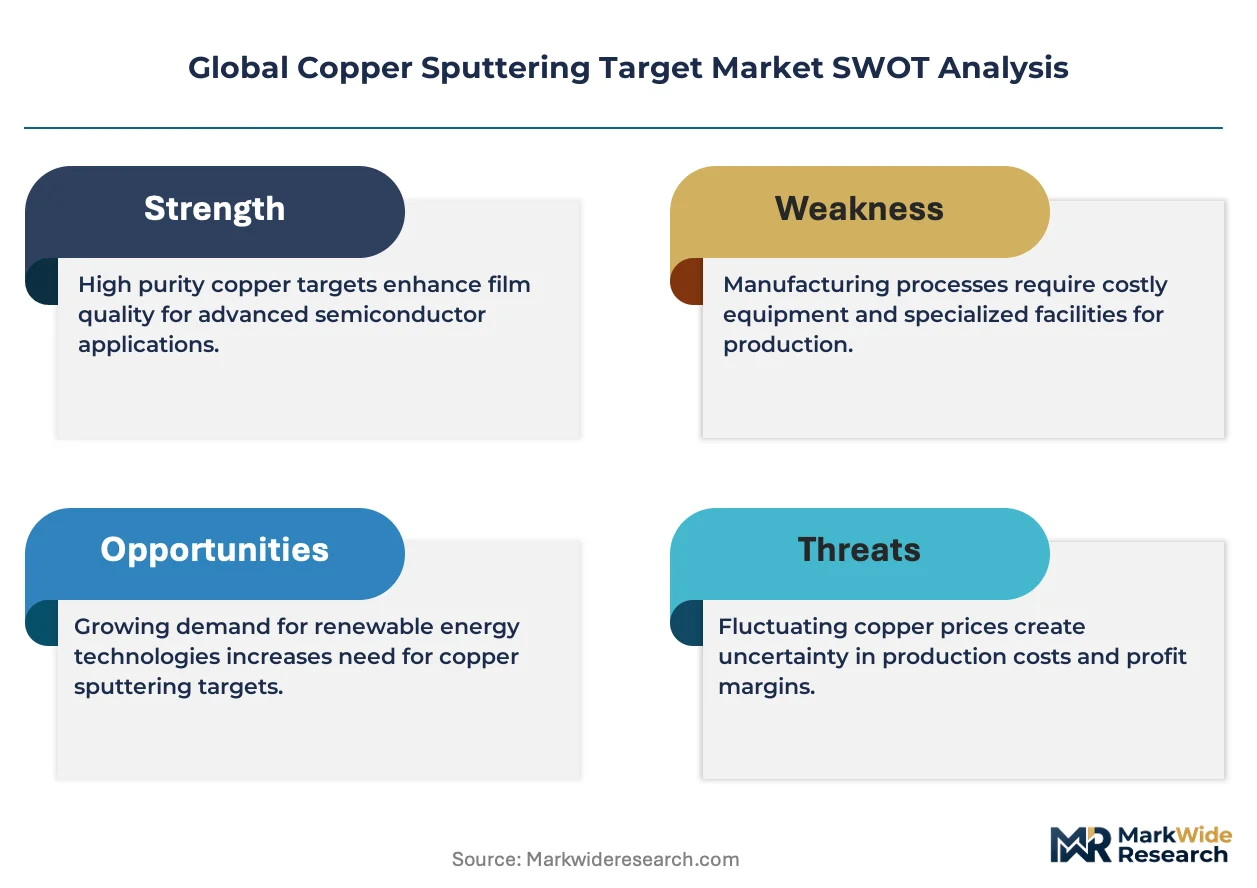
Aluminum interconnect metallization is decoupling from sub-7nm logic designs as copper damascene processes claim dominant cost-performance profiles at advanced nodes. JX Nippon Mining & Metals leverages captive copper refining and electron-beam melting capacity to anchor supply for Japanese and Taiwanese semiconductor fabs. Plansee differentiates through hot isostatic pressing expertise that yields grain structures optimized for uniform erosion during long sputtering campaigns. Honeywell Electronic Materials controls distribution channels spanning North American defense and aerospace coating applications where trace-element certification carries premium value.
A copper sputtering target is a machined disc or rectangular plate of high-purity copper, typically 99.999% or higher, designed for physical vapor deposition systems where energetic ion bombardment ejects copper atoms onto a substrate surface to form conductive thin films. These targets operate at power densities up to 50 kW/m² and require controlled grain orientation to minimize particle generation during erosion. High-purity copper targets dominate current revenue as logic foundries demand six-nines material for barrier-seed layer stacks in dual-damascene architectures. Sputtering technology leads installation base but co-sputtering configurations are expanding fastest as multi-material stacks for advanced packaging require simultaneous copper-tantalum or copper-manganese deposition from a single chamber.
FDA oversight of medical device coatings and EPA hazardous air pollutant standards for metalworking operations shape manufacturing compliance burdens in the United States, while REACH registration and RoHS substance restrictions govern European target import and alloy formulation. China's SAMR enforces GB standards for electronic materials purity that foreign suppliers must meet for domestic fab qualification. Stakeholders must monitor how tightening purity specifications interact with energy-intensive refining processes as regional carbon accounting frameworks mature.
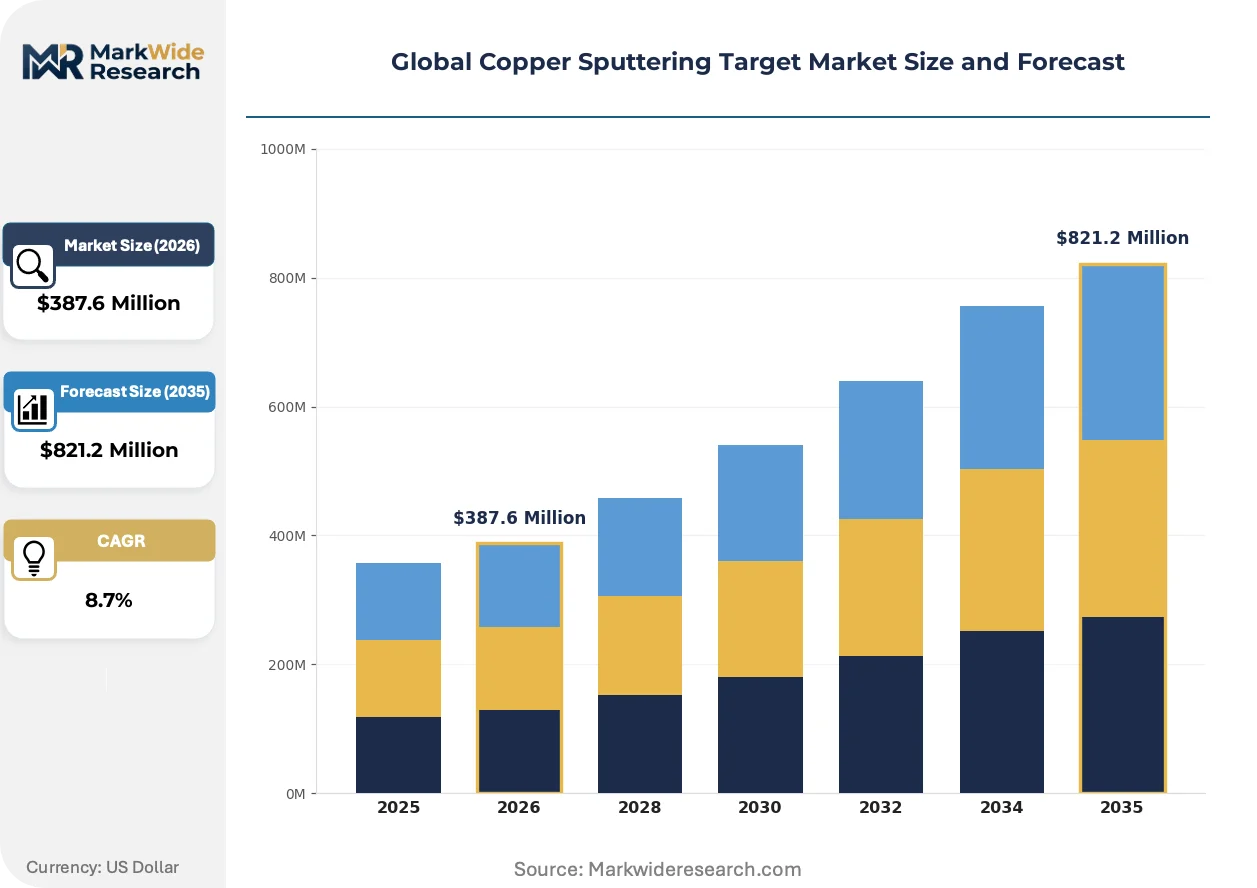
Market Dynamics
Copper interconnect metallization is consolidating dominance at sub-7nm logic nodes as aluminum damascene processes lose cost-performance viability, forcing foundries to lock ultra-high-purity copper supply chains years ahead of volume ramps.
Growth Catalysts
- Advanced node logic expansion:Taiwan Semiconductor Manufacturing and Samsung Foundry are scaling copper dual-damascene deposition for 3nm and 2nm process technologies, pulling six-nines purity targets into long-term supply agreements.
- REACH substance restrictions:ECHA registration requirements for high-purity metals are tightening trace-element documentation standards, elevating certified suppliers above uncertified competitors in European fab qualification.
- High-bandwidth memory stacking:Through-silicon via metallization for HBM3E and HBM4 architectures is accelerating copper seed layer consumption in Korean and Japanese memory fabs.
Market Restraints
- Electron-beam melting capacity concentration:Ultra-high-purity copper refining infrastructure clusters in Japan and Germany, creating single-source vulnerability for foundries outside these geographies.
- Energy cost volatility:Vacuum arc remelting and hot isostatic pressing operations consume 15-20 MWh per tonne of finished target, exposing margins to European and Chinese electricity price swings.
- Cobalt interconnect substitution:IBM and Intel have demonstrated cobalt liners at 5nm nodes that reduce copper electromigration failure rates, threatening copper volume at future technology generations.
Strategic Opportunities
- Indian semiconductor manufacturing:Micron Technology's Gujarat assembly and test facility and Tata Electronics' planned Assam fab are creating first-mover qualification opportunities for copper target suppliers before domestic refining capacity matures.
- Co-sputtering chamber architectures:Simultaneous copper-tantalum deposition from single-source targets is enabling advanced packaging redistribution layers for chiplet-based designs in Taiwanese OSAT facilities.
- China's dual carbon goals:SAMR carbon intensity benchmarks for electronic materials production are incentivizing foreign suppliers with verified low-carbon refining to displace domestic high-emission competitors.
Industry Challenges
- Grain orientation engineering talent scarcity:Hot isostatic pressing technicians capable of optimizing {100} fiber textures for uniform target erosion command premium compensation in Japanese and Austrian metallurgy clusters.
- Fab qualification timeline compression:Leading-edge foundries now demand 18-month target validation cycles versus 36 months historically, compressing R&D amortization for new alloy formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Copper Sputtering Target Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Purity Copper, Copper Alloys, Bonded Targets, Rotatable Targets Technology: Physical Vapor Deposition, Sputtering, Co-sputtering, Atomic Layer Deposition End User: Semiconductors, Electronics, Solar Cells, Thin Film Coatings Application: Chip Manufacturing, Display Production, Optical Coatings, Research & Development |
| Companies Covered | Praxair, The Kurt J. Lesker Company, JX Nippon Mining & Metals, Mitsubishi Materials, American Elements, Tosoh, Honeywell Electronic Materials, Plansee, KFMI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Copper Sputtering Target Market Emerging Trajectories
Physical vapor deposition equipment is evolving toward multi-material chambers that compress process steps, while regulatory carbon accounting and buyer consolidation are rewriting supplier qualification protocols across East Asian foundry clusters.
Single-crystal copper target technology is converging with advanced packaging requirements. Chip-scale redistribution layers demand atomically smooth copper films with minimized surface roughness. Taiwanese OSATs are piloting single-crystal targets for fan-out panel-level packaging. This convergence is compressing the viable supplier base to electron-beam melting specialists with crystallographic control capabilities.
China's GB standards for electronic materials purity are tightening heavy metal contamination thresholds under SAMR enforcement. Foreign target manufacturers must now submit third-party assay documentation for 35 trace elements to qualify for domestic fab supply. Korean and Japanese suppliers are responding by pre-certifying production lots at independent Shanghai laboratories before shipment.
Foundry procurement departments are consolidating qualified supplier lists to dual-source architectures from historical three-to-four source models. TSMC and Intel Foundry Services are compressing vendor panels to reduce qualification overhead and secure volume pricing leverage. This concentration is most visible in Arizona and Dresden greenfield fabs where single-source risk is being managed through geographic dual-siting rather than vendor multiplication.
Global Copper Sputtering Target Market Segmentation
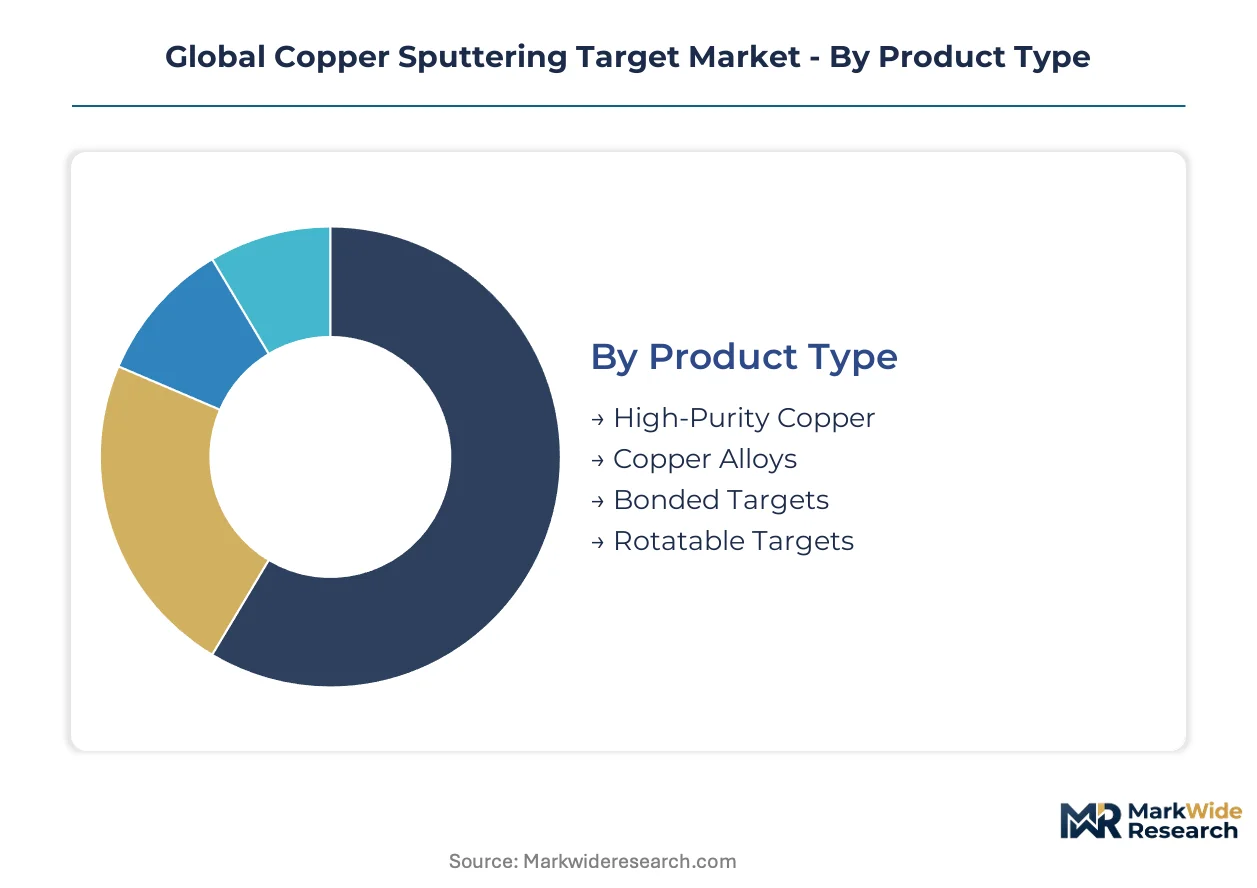
Copper sputtering target segmentation reflects divergent capital requirements across purity grades and deposition technologies. Foundry procurement teams weight segment selection against node-specific metallization roadmaps and chamber configuration constraints.
Product Type:
Capital intensity escalates sharply with purity thresholds, electron-beam melting infrastructure, and bonding layer complexity.
- High-Purity Copper:Six-nines material refined through vacuum arc remelting and electron-beam melting commands the steepest upfront equipment investment. Taiwan Semiconductor Manufacturing and Samsung Foundry lock multi-year supply agreements for this grade to secure 3nm and 2nm node ramps.
- Copper Alloys:Copper-manganese and copper-tantalum formulations require precision casting control for homogeneous distribution. Korean memory fabs driving HBM3E through-silicon via metallization are pulling alloy targets into qualification cycles.
- Bonded Targets:Backing plate integration via explosive bonding or diffusion bonding adds process steps without purity escalation.
- Rotatable Targets:Cylindrical geometries suit in-line coating systems for architectural glass and display manufacturing.
High-purity copper absorbs the bulk of installed capacity; copper alloys are expanding most quickly.
Technology:
Process architecture determines chamber retrofit costs and target utilization rates across deposition campaigns.
- Physical Vapor Deposition:The foundational installation base spans planar magnetron and ionized PVD configurations. Taiwanese OSATs operating legacy 200mm lines maintain steady consumption for mature node redistribution layers.
- Sputtering:DC magnetron sputtering dominates logic fab barrier-seed deposition with established target erosion protocols. Arizona and Dresden greenfield fabs specify sputtering chambers for copper damascene process integration.
- Co-sputtering:Simultaneous multi-material deposition from angled cathodes enables advanced packaging metallization stacks.
- Atomic Layer Deposition:Self-limiting surface reactions require precursor compatibility rather than bulk target supply.
Sputtering retains the deepest installed base; co-sputtering is gaining share fastest in packaging applications.
End User:
Customer concentration and qualification timelines vary dramatically across device categories and production scales.
- Semiconductors:Leading-edge logic and memory fabs impose 18-month qualification cycles and six-nines purity mandates. Japanese and Korean electron-beam melting specialists anchor supply for this segment.
- Electronics:Printed circuit board and connector metallization operates at lower purity thresholds with compressed procurement cycles.
- Solar Cells:CIGS and cadmium telluride photovoltaic manufacturing consumes copper targets for back contact deposition.
- Thin Film Coatings:Decorative and functional surface treatments for automotive and architectural applications prioritize cost over trace-element control.
Semiconductors command the dominant revenue share; solar cells are climbing the fastest as photovoltaic manufacturing scales.
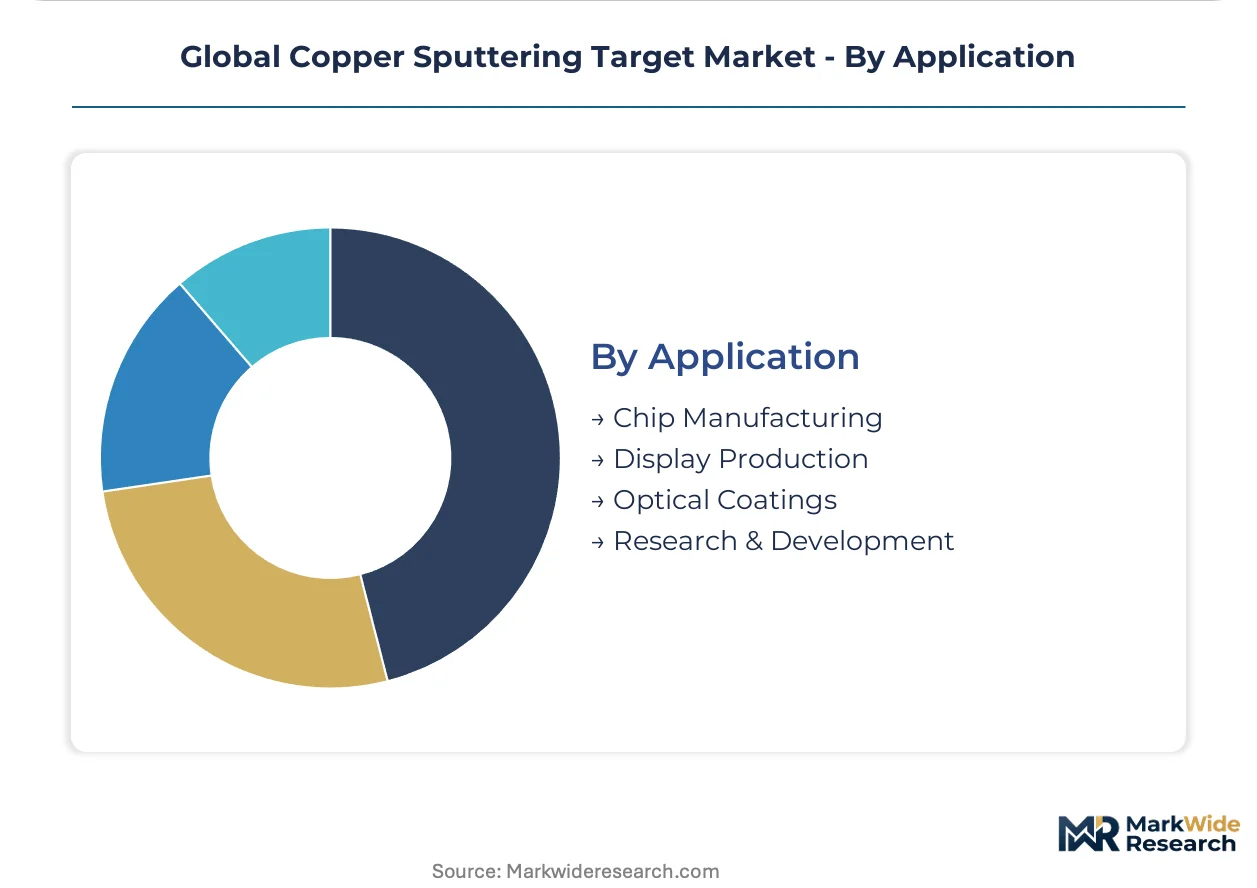
Application:
Technical specifications and volume profiles diverge between high-unit-value chip production and scale-driven display manufacturing.
- Chip Manufacturing:Dual-damascene interconnect stacks require atomically controlled copper grain orientation to minimize electromigration failure. Intel Foundry Services and TSMC specify target suppliers with documented crystallographic texture engineering.
- Display Production:Gen 10.5 and larger substrate sizes drive rotatable target adoption for uniform film thickness across meter-scale glass panels.
- Optical Coatings:Precision optics for aerospace and defense applications demand trace-element certification under ITAR and EAR regulations.
- Research & Development:Academic and national laboratory procurement operates at small volumes with broad alloy exploration requirements.
Chip manufacturing concentrates the highest-value demand; display production is expanding most rapidly on volume metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry demand concentrates in East Asian manufacturing clusters, while equipment qualification cycles and carbon accounting frameworks reshape supplier access across North American and European greenfield expansions.
United States
Intel Foundry Services and TSMC Arizona are scaling copper damascene capacity for advanced node production. EPA hazardous air pollutant standards govern metalworking emissions from target fabrication facilities. Greater Phoenix anchors the Southwest semiconductor corridor where sputtering equipment installation is accelerating ahead of 2025 production ramps.
Taiwan
TSMC and United Microelectronics drive six-nines purity consumption through long-term supply agreements with Japanese refiners. The island's environmental regulator enforces industrial emissions controls on vacuum metallurgy operations. Hsinchu Science Park concentrates electron-beam melting qualification facilities serving the world's densest logic foundry cluster.
South Korea
Samsung Foundry and SK Hynix are expanding copper seed layer deposition for HBM3E through-silicon via architectures. MFDS oversight of manufacturing quality systems extends to sputtering target documentation requirements. Yongin and Pyeongtaek host memory fab complexes pulling ultra-high-purity copper into 3D stacking processes.
Japan
JX Nippon Mining & Metals and Mitsubishi Materials leverage captive refining infrastructure for Taiwanese and Korean fab supply. METI industrial standards govern trace-element certification protocols for electronic materials export. Kitakyushu and Saitama prefectures concentrate vacuum arc remelting capacity with documented crystallographic texture engineering capabilities.
China
Yangtze Memory Technologies and SMIC are qualifying domestic target suppliers under SAMR GB standards for 35-trace-element documentation. Dual carbon goals are tightening energy-intensity benchmarks for electron-beam melting operations. Shanghai and Hefei foundry clusters are pre-certifying production lots at independent assay laboratories before volume ramp decisions.
Global Copper Sputtering Target Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with captive refining operations conferring supply security advantages in semiconductor-qualified tiers. The structure concentrates around electron-beam melting capacity holders and hot isostatic pressing specialists. Three archetypes dominate: integrated mining-metals conglomerates with upstream copper control, dedicated electronic materials fabricators with qualification track records, and diversified industrial gas or coating equipment suppliers leveraging distribution scale. Competitive moves center on backward integration into refining capacity and geographic dual-siting to manage single-source risk in Arizona and Dresden greenfield fabs.
Among Japanese mining-metals conglomerates, JX Nippon Mining & Metals and Mitsubishi Materials exemplify the integrated archetype with captive copper refining and electron-beam melting infrastructure. Plansee represents the European hot isostatic pressing specialist tier with grain structure optimization capabilities. Honeywell Electronic Materials occupies a position bridging industrial scale with defense-aerospace certification requirements. These three anchors illustrate how qualification depth, geographic proximity to foundry clusters, and documented crystallographic control separate premium-tier suppliers from commodity fabricators.
| Leading Market Players |
|---|
| Praxair |
| The Kurt J. Lesker Company |
| JX Nippon Mining & Metals |
| Mitsubishi Materials |
| American Elements |
| Tosoh |
| Honeywell Electronic Materials |
| Plansee |
| KFMI |
| Others |
Supply Flow & Price Mechanics
Electron-beam melting infrastructure scarcity in Japan and Germany simultaneously elevates production costs and concentrates supply leverage among incumbent refiners serving Taiwanese and Korean foundries. This technological bottleneck forces buyers into long-term offtake contracts that lock pricing premiums years ahead of volume ramps, while energy-intensive vacuum metallurgy operations expose margins to electricity price volatility across European and Chinese manufacturing zones.
Pricing Analysis
Volume-margins split sharply between semiconductor-qualified six-nines purity and industrial-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels separates electron-beam melted targets with crystallographic documentation from vacuum arc remelted products and basic cast material. Cost compression in the premium tier is intensifying because foundries are consolidating vendor panels to dual-source architectures, squeezing supplier pricing leverage. Memory fabs exhibit the highest price sensitivity due to cyclical DRAM pricing, while aerospace-defense buyers accept substantial premiums for ITAR-traceable certification.
Supply Chain Analysis
Hot isostatic pressing technician scarcity in Japanese and Austrian metallurgy clusters constrains finished target output regardless of raw copper availability. Supply concentrates in Japan, Germany, and Taiwan, where captive refining and grain orientation engineering capabilities anchor the qualified supplier base. Raw material flows draw from Chilean copper concentrate, Japanese electron-beam melting capacity, and Taiwanese bonding fabrication. Single-source vulnerability pervades the ultra-high-purity tier where JX Nippon Mining & Metals and Mitsubishi Materials control electron-beam infrastructure. Distribution runs through direct mill-to-fab contracts for semiconductor tiers and regional distributor networks for industrial applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electron-beam melting capacity scarcity props pricing premiums across the forecast horizon, constraining volume growth to qualified infrastructure holders and forcing buyers into early commitment strategies.
For Market Incumbents: Cement supply security through backward integration into captive copper refining or binding long-term concentrate offtake with Chilean and Australian miners. Lock grain orientation engineering talent through apprenticeship pipelines in Saitama and Kitakyushu prefectures to defend against Austrian and German competitors poaching technicians. Cobalt interconnect substitution at Intel and IBM represents the primary technology threat requiring R&D hedging in alternative barrier-seed formulations. For New Entrants and Emerging Players: Capture qualification windows at Micron Technology's Gujarat facility and Tata Electronics' Assam fab before domestic Indian refining capacity matures. Target solar cell and display manufacturing segments where five-nines purity suffices and eighteen-month semiconductor fab qualification cycles do not apply. Lead with co-sputtering target configurations for advanced packaging redistribution layers, where technical differentiation commands faster adoption than commodity copper replacement. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated mining-metals conglomerates seeking semiconductor-qualified tier access or by PVD equipment manufacturers pursuing captive target supply. Long-term viability hinges on electron-beam melting asset ownership or exclusive hot isostatic pressing partnerships with documented crystallographic control. Watch for Intel Foundry Services and TSMC compressing vendor panels to single-source-per-geography models as the inflection signal for supplier consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Refining | Captive six-nines material supply secures TSMC and Samsung Foundry qualification slots against Japanese incumbents. |
| Hot Isostatic Pressing Capacity Expansion | Grain texture engineering scale-up enables uniform erosion performance for long sputtering campaigns at Arizona fabs. |
| Co-Sputtering Target Development | Simultaneous copper-tantalum deposition configurations capture advanced packaging growth at Taiwanese OSAT facilities. |
| Carbon-Intensity Certification Program | Verified low-carbon refining documentation displaces high-emission domestic competitors under China's SAMR benchmarks. |
| Geographic Dual-Siting Partnership | Arizona-Dresden production pairing satisfies Intel Foundry Services single-source risk management requirements. |
Methodological Framework
Independent corroboration across semiconductor fab procurement executives, electron-beam melting plant managers, and PVD equipment engineering directors underwrites the qualitative findings in this study. Primary interviews with foundry supply chain strategists, hot isostatic pressing technicians, and raw materials procurement leads at copper concentrate traders were validated against secondary sources including SEC filings from target manufacturers, customs trade data for high-purity copper imports, and SAMR GB standard documentation. Bottom-up target consumption estimates by fab node and top-down market sizing by purity grade were triangulated to constrain projection variance.
Rate-of-change decomposition across the analysis window separates volume growth from purity-grade mix shifts and pricing trajectory components. Segmentation modeling incorporates product type, deposition technology, end-use sector, and application layer dimensions alongside regional regulatory cluster effects. CAGRs were derived from installed PVD equipment base expansion, node transition timelines, and foundry capex disclosure patterns. Forecast inputs include electron-beam melting capacity utilization rates and REACH substance restriction implementation schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to cobalt interconnect substitution viability and regional electricity price trajectories. Projections reflect assumptions regarding foundry vendor panel consolidation rates and carbon accounting framework maturation. Material deviation in Intel or TSMC qualification timeline compression or SAMR enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Wear Steel Plate Market
Metals
Finished Steel Products Market
Metals
Copper Powder Market
Metals
Silver Sulphate Market
Metals
Beryllium Copper Plate Market
Metals
Global Metal and Metal Manufactured Products Market
Metals
Iron and Steel Market
Metals
Europe Aluminum Extrusion Market
Metals
Silver-Platinum Paste Market
Metals
India Special Steel Market
Metals
Tungsten Metal Powder Market
Metals
Rhodium Market
Metals
Bearing Steel Market
Metals
Cold Drawn Wire Market
Metals
Ferrosilicon Magnesium Market
Metals
Motor Lamination Material Market