
 Lithium Tungstate Market | 2026-2036
Lithium Tungstate Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Tungstate Market Insights
Specialty ceramics buyers are collapsing orders from legacy glass-coating suppliers as electronics OEMs redirect lithium tungstate volumes toward high-frequency substrate applications. Ganfeng Lithium leverages captive brine assets to secure upstream lithium feedstock for tungstate synthesis. Albemarle anchors North American supply through its Kings Mountain processing complex. Tianqi Lithium competes on cost at the spodumene conversion stage, though tungsten sourcing remains a bottleneck.
Lithium tungstate (Li2WO4) is an inorganic salt synthesized from lithium carbonate or hydroxide and tungstic acid, typically yielding a white crystalline powder with melting point near 720°C and high piezoelectric coupling coefficients. Electronics applications dominate offtake, where Li2WO4 serves as a precursor for surface acoustic wave filters and optical modulators in 5G infrastructure. The ceramics segment sustains premium pricing through aerospace thermal-barrier specifications, while catalyst-grade Li2WO3 occupies a narrower volume niche in petrochemical desulfurization. Glass manufacturers face margin compression as display panel makers shift to organic alternatives, reducing lithium tungstate incorporation in melting formulations.
REACH registration requirements in Europe compel importers to document tungsten substance dossiers, elevating compliance costs for non-EU refiners. China's SAMR enforces GB standards on battery-grade lithium salts that indirectly constrain tungstate purity benchmarks for electronics customers. South Korea's MFDS maintains pharmaceutical-grade lithium specifications that some producers exploit as a quality signaling mechanism. Stakeholders must monitor tungsten concentrate export licensing shifts in Vietnam and Rwanda, as these jurisdictions increasingly control global intermediate supply.
Market Dynamics
Electronics OEMs are consolidating lithium tungstate procurement around high-frequency substrate specifications, redirecting volumes away from legacy glass-coating applications and compressing supplier margins across intermediate processing tiers.
Growth Catalysts
- 5G infrastructure deployment:Surface acoustic wave filter manufacturers in South Korea and Taiwan are expanding Li2WO4 offtake for base station components. Base station rollouts accelerate substrate precursor demand.
- China's dual carbon goals:Stricter MEE emissions standards are forcing tungsten refinery consolidation, inadvertently concentrating high-purity output for electronics-grade tungstate synthesis.
- REACH registration:European importers must document tungsten substance dossiers, creating compliance moats for established refiners with existing registration portfolios.
Market Restraints
- Tungsten concentrate volatility:Export licensing shifts in Vietnam and Rwanda constrain intermediate supply predictability for non-integrated processors.
- Glass substitution:Display panel makers are shifting to organic melting alternatives, eroding lithium tungstate incorporation in traditional glass formulations.
- GB standard convergence:China's SAMR battery-grade lithium salt specifications indirectly elevate tungstate purity benchmarks, raising conversion costs for smaller refiners.
Strategic Opportunities
- Aerospace thermal barriers:Specialty ceramics specifications sustain premium pricing tiers for high-melting-point Li2WO4 in turbine coatings.
- Petrochemical desulfurization:Catalyst-grade lithium tungstate occupies a narrow but defensible niche with long-term offtake contracts.
- Captive brine integration:Upstream lithium asset holders can backward integrate into tungstate synthesis, bypassing carbonate spot market exposure.
Industry Challenges
- Piezoelectric coupling optimization:Electronics customers demand tighter coefficient tolerances, requiring recalibration of synthesis protocols and quality systems.
- MFDS pharmaceutical-grade crossover:Some producers exploit South Korean pharmaceutical lithium specifications as quality signaling, complicating positioning for pure industrial-grade suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Tungstate Market |
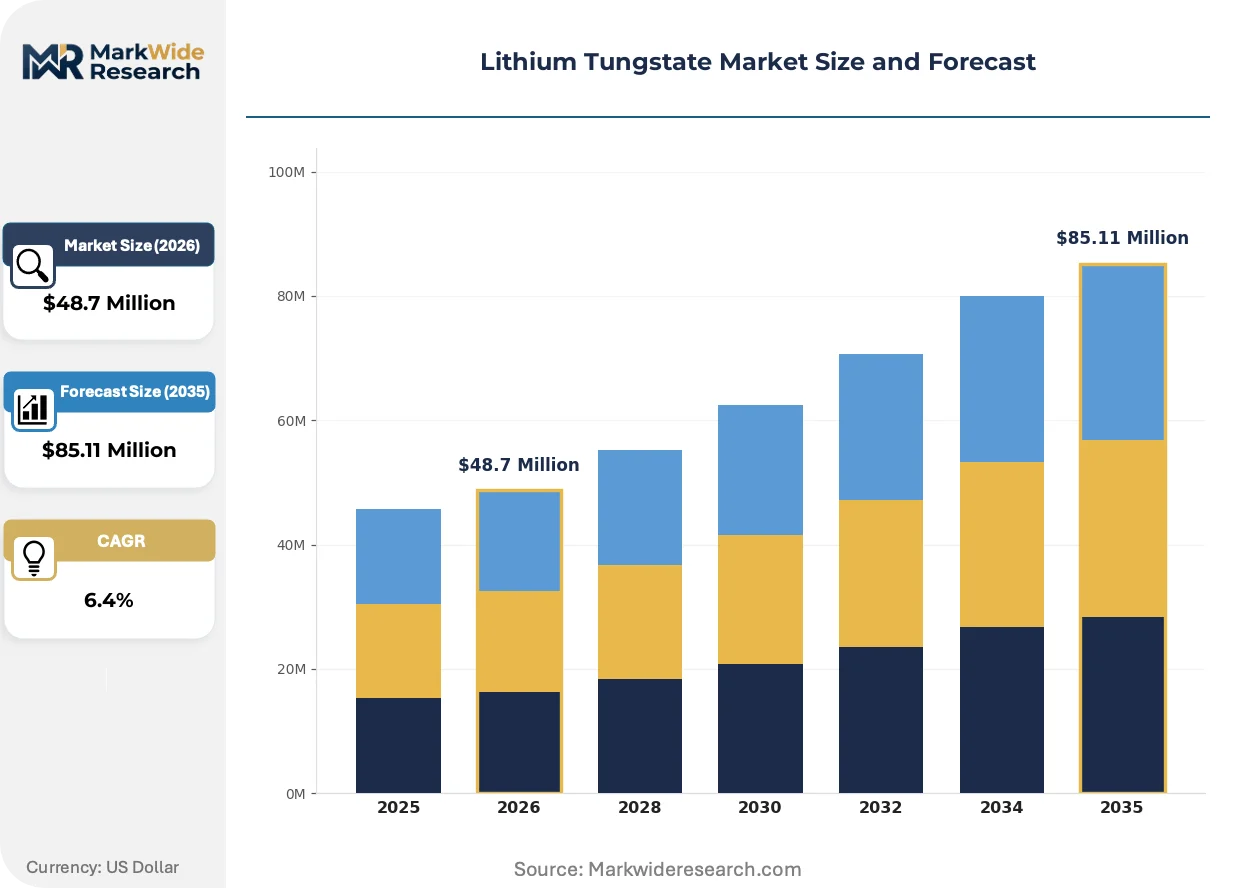
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $85.11 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Li2WO4, Li4W2O9, Li2WO3, Others Application: Electronics, Ceramics, Glass, Catalysts End User: Manufacturers, Exporters, Research Institutions, Utilities Distribution Channel: Online, Offline, Distributors, Resellers |
| Companies Covered | Albemarle, Sociedad Química y Minera de Chile, Ganfeng Lithium, Tianqi Lithium, Rio Tinto, Mineral Resources, Almonty Industries, Allied Critical Metals, Guardian Metal Resources, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Tungstate Market Trends and Innovations
Process intensification and regulatory convergence are compressing the viable supplier set while opening specification-driven premium tiers for qualified producers.
Solid-state synthesis routes for lithium tungstate precursors are fragmenting the incumbent wet-chemical process base. Japanese ceramics manufacturers are piloting continuous-flow reactors that reduce thermal cycling energy by half. The shift is fragmenting equipment supplier relationships and favoring reactor engineering specialists over traditional crystallization equipment vendors.
REACH substance dossier requirements are elevating documentation burdens for European importers. Non-EU refiners face elevated compliance costs that compress their addressable market to price-insensitive electronics tiers. German and French chemical distributors are responding by consolidating sourcing around pre-registered Asian suppliers with existing ECHA portfolios.
Specification-driven procurement is compressing supplier qualification timelines for electronics OEMs. Long-term agreements with tungsten concentrate offtake rights are displacing spot market purchasing in South Korean display clusters. The pattern is most visible in Seoul-Incheon semiconductor fabrication corridors where substrate precursor inventories are managed through vendor-managed inventory programs.
Lithium Tungstate Market Segmentation
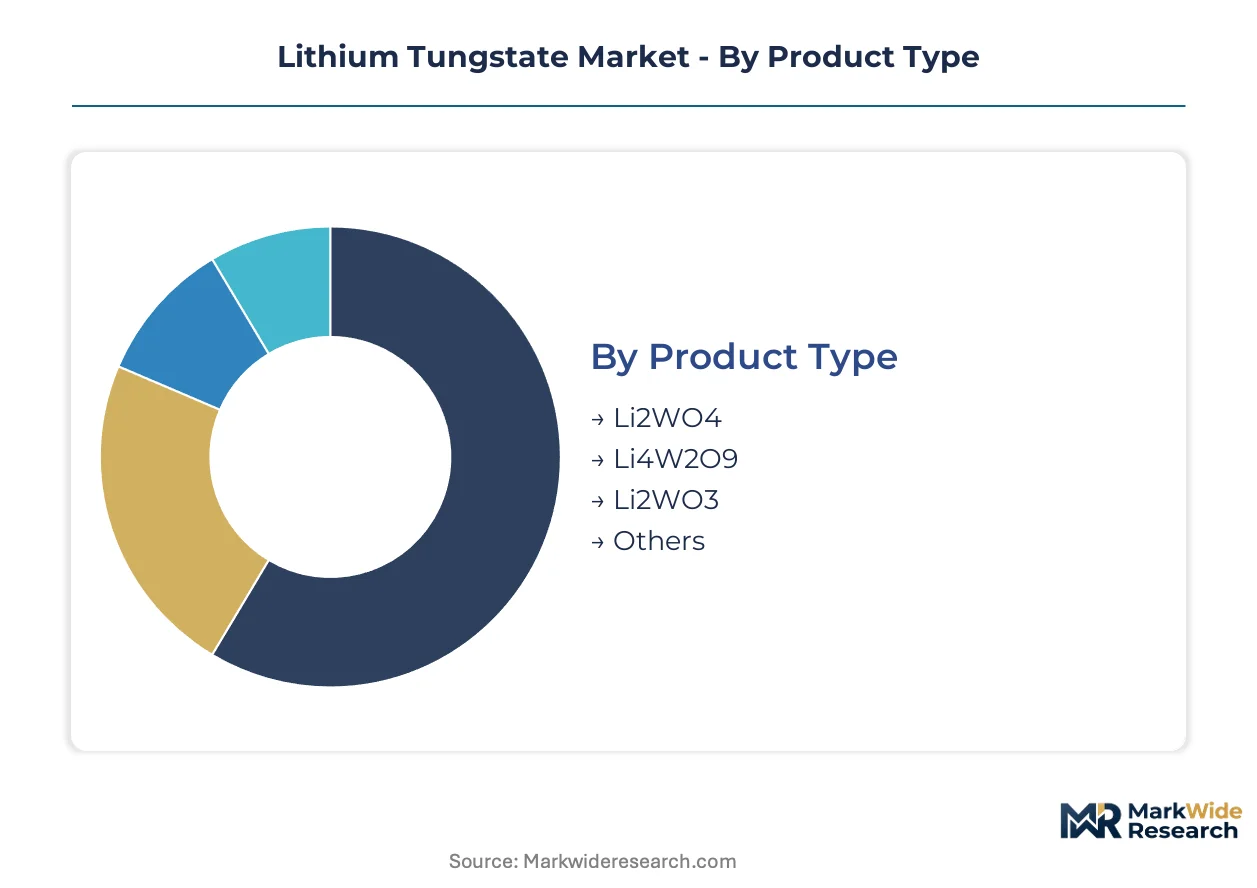
Lithium tungstate procurement patterns diverge sharply across product grades and customer types. Specification tolerances for piezoelectric coupling coefficients fragment the supplier base, while end-user scale determines whether buyers negotiate direct contracts or accept distributor markups.
Product Type:
Premium margins concentrate in high-purity Li2WO4 for electronics substrates, while intermediate grades compete on conversion efficiency for ceramics and catalyst applications.
- Li2WO4:The standard lithium tungstate salt delivers melting points near 720°C with piezoelectric coupling coefficients optimized for surface acoustic wave filters. South Korean 5G base station manufacturers in Seoul-Incheon corridors specify this grade for optical modulator substrates, with SAMR's GB purity benchmarks elevating qualification thresholds for non-integrated refiners.
- Li4W2O9:This tungstate variant offers modified thermal expansion coefficients suited to aerospace thermal barrier coatings. Specialty ceramics buyers in Japan's turbine supply chain specify Li4W2O9 for premium-priced melting formulations, though volume remains constrained by narrow aerospace qualification pathways.
- Li2WO3:Catalyst-grade specification serving petrochemical desulfurization units with long-term offtake contracts.
- Others:Experimental stoichiometries and custom synthesis products for research institutions and battery prototyping labs.
The dominant share belongs to Li2WO4, while Li4W2O9 is closing the gap fastest in contract value terms.
Application:
Customer technical requirements split the market between precision-driven electronics tiers and cost-sensitive industrial formulations.
- Electronics:Surface acoustic wave filter precursors and optical modulator substrates for 5G infrastructure command specification premiums. Taiwanese and South Korean OEMs consolidate procurement around high-frequency substrate tolerances, with REACH dossier requirements filtering out non-registered Asian suppliers from European electronics tiers.
- Ceramics:Aerospace thermal barrier specifications sustain premium pricing through melting point and coefficient requirements. Japanese ceramics manufacturers pilot solid-state synthesis routes that reduce energy intensity, fragmenting equipment supplier relationships toward reactor engineering specialists.
- Glass:Traditional melting formulation demand erodes as display panel makers shift to organic alternatives.
- Catalysts:Petrochemical desulfurization niche with stable but limited volume growth.
Electronics captures the largest revenue pool, though ceramics maintains the highest margin per kilogram.
End User:
Procurement scale determines channel access, with integrated manufacturers bypassing spot markets while research buyers absorb distributor premiums.
- Manufacturers:Electronics OEMs and ceramics processors with captive synthesis capability or direct tungsten concentrate offtake rights. South Korean display clusters manage substrate precursor inventories through vendor-managed inventory programs, compressing supplier qualification timelines.
- Exporters:German and French chemical distributors consolidating sourcing around pre-registered Asian suppliers with existing ECHA portfolios.
- Research Institutions:Small-batch buyers for piezoelectric material prototyping and next-generation battery chemistry development.
- Utilities:Niche demand for thermal management applications in power generation infrastructure.
Manufacturers command pricing leverage through volume concentration, while exporters are expanding most quickly as REACH compliance moats deepen.
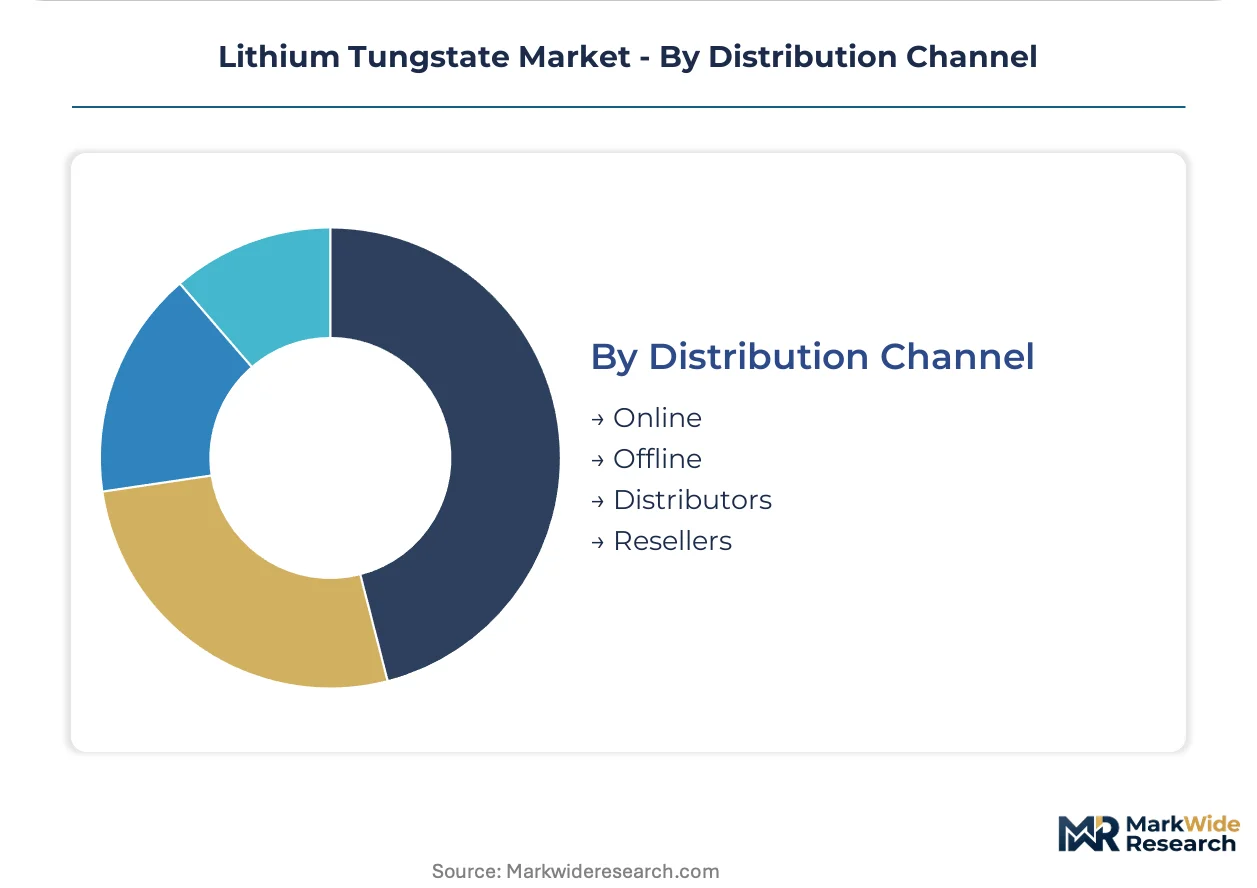
Distribution Channel:
Documentation burdens and specification complexity favor relationship-based channels over transactional platforms.
- Online:Limited to standard-grade Li2WO4 with documented certificates of analysis for qualified buyers.
- Offline:Direct sales relationships dominate electronics-grade procurement, with technical service agreements covering synthesis protocol calibration.
- Distributors:European chemical distributors absorb REACH registration complexity for non-integrated refiners, capturing margin through compliance intermediation.
- Resellers:Spot market access for smaller ceramics processors without direct refinery relationships.
Offline channels retain the dominant transaction value, though distributors are gaining share fastest in cross-border European procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports refined tungstate intermediates to South Korean electronics corridors, while Vietnamese concentrate flows feed Japanese ceramics manufacturers. This trade architecture concentrates procurement leverage in East Asian fabrication clusters.
China
Electronics-grade tungstate synthesis and tungsten concentrate refining dominate output. SAMR enforces GB standards on battery-grade lithium salts that indirectly elevate purity benchmarks for downstream tungstate customers. Yangtze River Delta refineries in Jiangsu and Zhejiang provinces consolidate high-purity output as MEE emissions standards force smaller operators offline.
South Korea
Surface acoustic wave filter manufacturers in Seoul-Incheon corridors drive substrate precursor demand for 5G base station components. MFDS maintains pharmaceutical-grade lithium specifications that some producers exploit as quality signaling mechanisms. Display and semiconductor fabrication clusters manage lithium tungstate inventories through vendor-managed inventory programs with qualified refiners.
Japan
Aerospace thermal barrier ceramics and piezoelectric material prototyping sustain premium-grade offtake. METI oversees industrial chemical standards that align with JIS certification requirements for specialty ceramics feedstock. Nagoya-area turbine supply chain manufacturers pilot solid-state synthesis routes that reduce thermal cycling energy intensity.
Germany
Chemical distributors absorb REACH registration complexity for cross-border European procurement. ECHA substance dossier requirements elevate documentation burdens for non-EU tungstate importers. Frankfurt and Hamburg distribution hubs consolidate sourcing around pre-registered Asian suppliers with existing registration portfolios.
United States
Aerospace ceramics and research institution demand anchors North American offtake. EPA oversees industrial chemical emissions standards affecting tungsten processing facility permitting. Kings Mountain processing complex in North Carolina anchors domestic lithium salt supply for tungstate synthesis.
Lithium Tungstate Market Competitive Landscape
Player mix skews toward integrated lithium majors with captive brine or spodumene assets. Market structure concentrates around three strategic archetypes: upstream-integrated lithium producers backward into tungstate synthesis, independent tungsten refiners without lithium integration, and specialty chemical distributors mediating REACH compliance. Dominant competitive moves include long-term tungsten concentrate offtake agreements and synthesis protocol licensing to secure electronics-grade qualification.
Among lithium-integrated producers, Albemarle, Ganfeng Lithium, and Tianqi Lithium exemplify the upstream-control archetype. Albemarle anchors North American supply through its Kings Mountain processing complex. Ganfeng Lithium leverages captive brine assets to secure upstream lithium feedstock. Tianqi Lithium competes on cost at the spodumene conversion stage, though tungsten sourcing remains a constraint for all three. These companies occupy positions that downstream electronics OEMs must negotiate for qualified tungstate volumes.
| Leading Market Players |
|---|
| Albemarle |
| Sociedad Química y Minera de Chile |
| Ganfeng Lithium |
| Tianqi Lithium |
| Rio Tinto |
| Mineral Resources |
| Almonty Industries |
| Allied Critical Metals |
| Guardian Metal Resources |
| Others |
Pricing and Supply Chain Analysis
REACH substance dossier requirements gate both supply qualification and price differentiation simultaneously, compressing non-EU refiners into premium electronics tiers while elevating compliance costs that European distributors capture as intermediation margin.
Pricing Analysis
Prior-generation glass-coating specifications trade at commodity benchmarks while current-generation electronics-grade Li2WO4 commands specification premiums, and next-generation solid-state synthesis routes threaten to reset cost baselines entirely. Three-tier pricing structure across premium, standard, and economy levels separates SAMR-certified electronics grades from industrial ceramics formulations and residual glass-melting volumes. Pricing pressure stems from display panel makers abandoning lithium tungstate for organic alternatives, eroding absorption capacity in the economy tier. Research institutions exhibit highest price sensitivity due to small-batch procurement scale, while South Korean 5G base station manufacturers absorb premiums for optical modulator substrate qualification.
Supply Chain Analysis
China and Vietnam anchor tungsten concentrate extraction and intermediate refining, while South Korea and Taiwan concentrate downstream substrate fabrication for surface acoustic wave filters. The chain draws from lithium carbonate or hydroxide feedstock, tungstic acid precursors, and high-purity process chemicals, with tungsten sourcing remaining the critical chokepoint for non-integrated producers. Single-source vulnerability concentrates in Vietnamese export licensing shifts, which have disrupted concentrate flows to Japanese ceramics manufacturers without warning. Distribution runs through vendor-managed inventory programs in Seoul-Incheon corridors for qualified electronics OEMs, while European procurement channels through REACH-registered distributors in Frankfurt and Hamburg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lithium tungstate market tracks a cyclical recovery anchored to 5G infrastructure deployment waves, with base station rollouts creating predictable demand pulses that favor contracted supply relationships over spot market exposure.
For Market Incumbents: Shield qualified electronics-grade positions by securing long-term tungsten concentrate offtake rights in Vietnam and Rwanda before export licensing tightens further. Lock in vendor-managed inventory programs with South Korean display clusters to compress supplier qualification timelines for emerging competitors. Prioritize synthesis protocol licensing to Japanese ceramics manufacturers piloting solid-state routes, converting equipment relationships into captive feedstock demand.
For New Entrants and Emerging Players: Differentiate on REACH registration arbitrage by pre-positioning ECHA dossiers for European electronics tiers that incumbent Asian refiners have neglected. Target the aerospace thermal barrier segment in Japan's Nagoya-area turbine supply chain, where narrow qualification pathways sustain premium pricing and incumbent capacity constraints create absorption gaps. Lead with technical service agreements covering piezoelectric coupling coefficient calibration rather than commodity volume positioning.
For Investors and Strategic Acquirers: Carve-out targets emerge from integrated lithium majors seeking to monetize non-core tungstate synthesis units as they refocus on battery-grade carbonate and hydroxide production. Five-to-ten-year viability hinges on tungsten concentrate access rather than lithium feedstock control, inverting traditional battery materials valuation frameworks. Monitor Vietnamese Ministry of Industry and Trade export licensing announcements as the critical inflection signal for intermediate supply predictability.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Tungsten Concentrate Offtake Agreement | Secures intermediate supply predictability against Vietnamese and Rwandan export licensing volatility. |
| REACH Registration Portfolio Expansion | Elevates compliance moats for European electronics tiers while compressing non-registered competitor addressable markets. |
| Solid-state Synthesis Route Licensing | Captures Japanese ceramics manufacturer energy efficiency gains as captive equipment relationships. |
| Vendor-Managed Inventory Program Implementation | Locks South Korean display clusters into contracted precursor supply with compressed qualification timelines. |
| Aerospace Thermal Barrier Specification Qualification | Opens premium-priced ceramics tier through JIS-certified melting formulations for turbine coatings. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, including electronics OEM procurement directors, ceramics plant managers, tungsten refinery technical leads, and European chemical distribution channel partners. Secondary validation drew from ECHA substance dossier filings, Chinese MEE emissions compliance disclosures, South Korean MFDS pharmaceutical-grade specifications, and customs trade data tracking tungsten concentrate flows. Bottom-up volume estimates from end-use application sizing were triangulated against top-down refinery capacity assessments across the analysis window.
Across the modeling period, segmentation dimensions included product grade tier, end-use application, and regional regulatory cluster alignment. CAGRs were derived from elasticity-weighted demand projections for 5G infrastructure deployment, aerospace thermal barrier replacement cycles, and petrochemical catalyst refresh schedules. Industry-specific forecast inputs incorporated SAMR GB standard convergence timelines and Japanese METI solid-state synthesis pilot outcomes.
The analysis sits within stated boundaries; outcomes outside sustained 5G base station rollout velocity or abrupt tungsten concentrate trade policy shifts would require recalibration. Forecasts reflect documented assumptions around electronics-grade purity benchmark stability and ceramics qualification pathway duration. Recalibration cycles align with material shifts in Vietnamese export licensing regimes and Chinese MEE emissions enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Beryllium Copper Billet Market
Metals
Silver-Platinum Paste Market
Metals
Battery Metals Market
Metals
Gold Smelting Market
Metals
Aluminium Rolled Products Market
Metals
Copper Powder Market
Metals
Chrome Metal Powder Market
Metals
Copper Azoles Market
Metals
US and Mexico Stainless Steel Market
Metals
Precious Metals Wire Market
Metals
Titanium Mill Products Market
Metals
Tungsten Metal Powder Market
Metals
Hafnium Foil Market
Metals
Stainless Steel Sheet Market
Metals
Global Duplex Stainless Steel Market
Metals
Global Aluminum Market