
 Global Chromium Market | 2026-2036
Global Chromium Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chromium Market Analysis
Market Overview
High-carbon ferrochrome grade differentiation is collapsing as stainless steel mills consolidate procurement around unified charge specifications. Glencore leverages its integrated mining-smelting footprint in South Africa to control feedstock costs across the value chain. Samancor Chrome anchors regional supply through its Western Chrome Mines and Rustenburg operations. Outokumpu Oyj competes in European specialty grades with tight sulfur and phosphorus tolerances for aerospace bar stock.
Segmentation Analysis
Chromium is a hard, lustrous transition metal with atomic number 24, occurring primarily in chromite ore (FeCr₂O₄) and refined into ferrochrome, metal, or chemical compounds for corrosion resistance and high-temperature stability. Ferrochrome dominates value flows as the essential input for austenitic and ferritic stainless steel melt shops, while chromium compounds serve pigment, tanning, and plating baths with tighter environmental compliance burdens. Stainless steel application demand leads volume but faces margin compression from nickel price volatility, whereas aerospace end-user specifications for superalloy-grade metal capture premium pricing through NADCAP-qualified supply chains.
Regulatory Environment
China's MIIT enforces GB/T 5683 ferrochrome standards that restrict silicon and carbon banding for electric furnace feed, while South Africa's Department of Mineral Resources and Energy monitors mining charter compliance for chromite extraction licenses. REACH registration in Europe governs hexavalent chromium compound imports, forcing coating and plating formulators toward trivalent substitution or closed-loop recovery systems. Stakeholders must track how carbon border adjustment mechanisms and evolving alloy scrap recycling economics reshape primary versus secondary chromium unit economics.
Market Dynamics
China's MIIT ferrochrome purity mandates are compressing grade spreads and forcing stainless steel mills to consolidate procurement specifications around unified charge chemistry, collapsing traditional high-carbon versus charge-grade price differentials.
Growth Catalysts
- MIIT GB/T 5683 enforcement:Tighter silicon and carbon banding requirements are accelerating furnace feed standardization across Chinese stainless steel melt shops.
- Aerospace superalloy specifications:NADCAP-qualified supply chains for bar stock and turbine components are pulling premium-grade chromium metal demand from engine OEMs.
- Bushveld Complex concentration:South Africa's chromite reserve dominance anchors smelter economics across three continents through integrated mining-smelting footprints.
Market Restraints
- Power cost volatility:South African smelters face Eskom tariff instability that directly erodes ferrochrome conversion margins.
- REACH hexavalent restrictions:ECHA registration burdens on chromium VI compounds are forcing European plating formulators toward costlier trivalent substitution or closed-loop recovery.
- Nickel price transmission:Stainless steel margin compression from nickel volatility constrains alloy procurement budgets and ferrochrome pass-through pricing.
Strategic Opportunities
- India stainless steel expansion:PLI scheme incentives for domestic melt shop capacity are creating new ferrochrome demand nodes outside traditional Chinese procurement.
- Scrap recycling economics:Carbon border adjustment mechanisms are reshaping primary versus secondary chromium unit economics in favor of alloy recovery circuits.
- Trivalent plating chemistry:Environmental compliance tailwinds in Europe and North America are opening formulation markets for hexavalent-free coating technologies.
Industry Challenges
- Pyrometallurgical engineering scarcity:Smelter design and furnace optimization expertise is concentrating among retiring specialists without sufficient knowledge transfer pipelines.
- Chromite beneficiation capex cycles:UG2 reef processing upgrades require sustained capital commitment amid uncertain ferrochrome price floors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chromium Market |
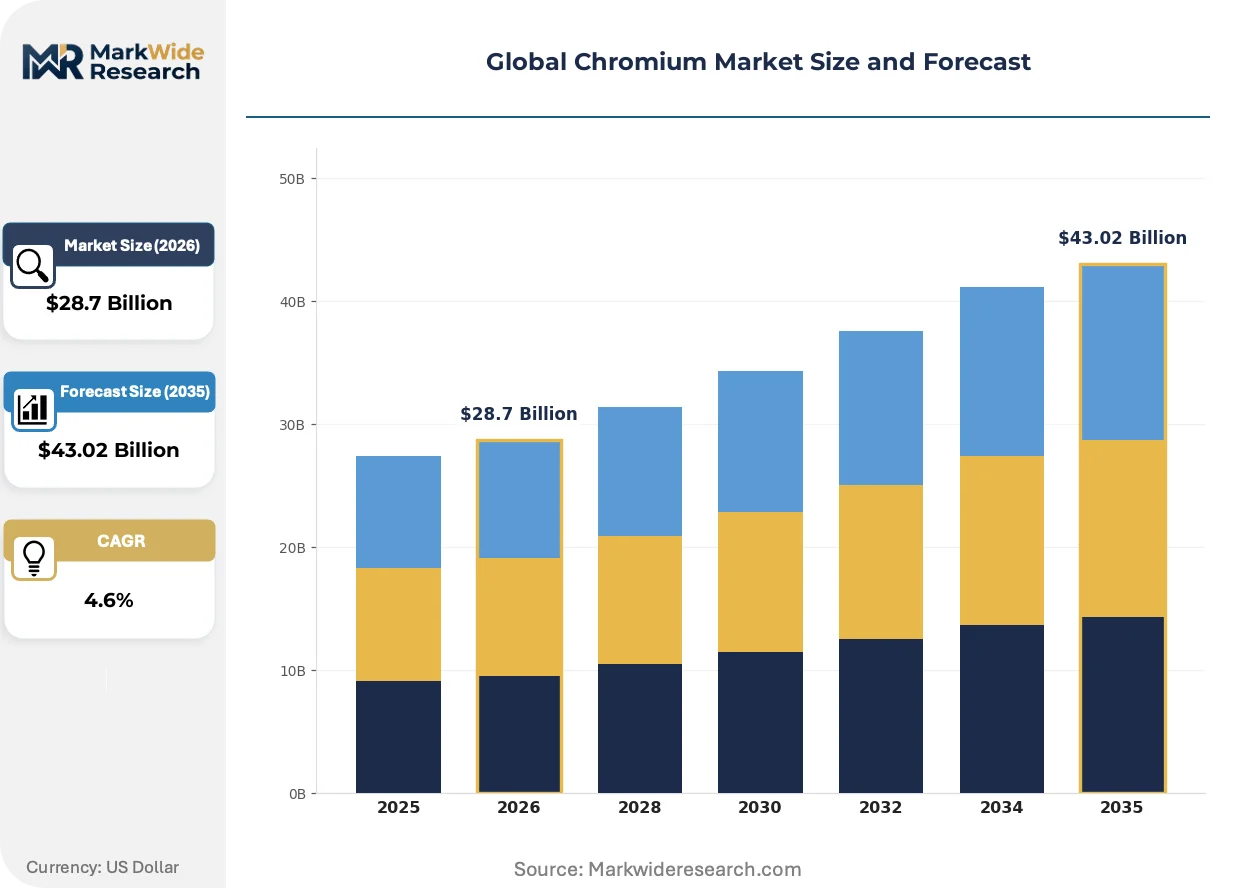
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $43.02 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chromium Metal, Chromium Alloys, Chromium Compounds, Ferrochrome Application: Stainless Steel, Coatings, Refractories, Chemical Processing End User: Aerospace, Automotive, Construction, Electronics Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Glencore, Samancor Chrome, Assmang Proprietary Limited, Kermas Investment Group, Tata Steel Mining Ltd., Afarak Group PLC, Eurasian Resources Group, Outokumpu Oyj, Tharisa Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chromium Market Emerging Trajectories
Smelting technology and environmental compliance frameworks are actively restructuring how chromium units flow from mine to melt shop, with furnace economics and regulatory chemistry dominating competitive positioning.
Submerged arc furnace (SAF) technology with enhanced pre-reduction stages is decomposing the traditional cost advantage of integrated mining-smelting operations by enabling competitive ferrochrome production from lower-grade chromite fines. Indonesian and Indian entrants are adopting this configuration to bypass Bushveld concentrate dependence. The technology is decomposing historical geographic moats around South African supply.
REACH authorization requirements for chromium trioxide in functional and decorative plating are forcing European surface treatment specialists to accelerate trivalent process validation or invest in closed-loop hexavalent recovery. Decorative automotive trim and aerospace component categories face the steepest compliance timelines. German and French plating clusters are consolidating around shared wastewater treatment infrastructure to amortize recovery capital.
Stainless steel mill procurement is compressing supplier panels from fragmented traders toward direct long-term offtake with integrated producers capable of certified carbon footprint disclosure. Chinese and Indonesian melt shops are leading this consolidation, displacing spot-market ferrochrome purchases. The shift is most visible in Tsingshan and Delong vertical integration strategies that internalize chromite-to-slabs within single ownership structures.
Global Chromium Market Segmentation
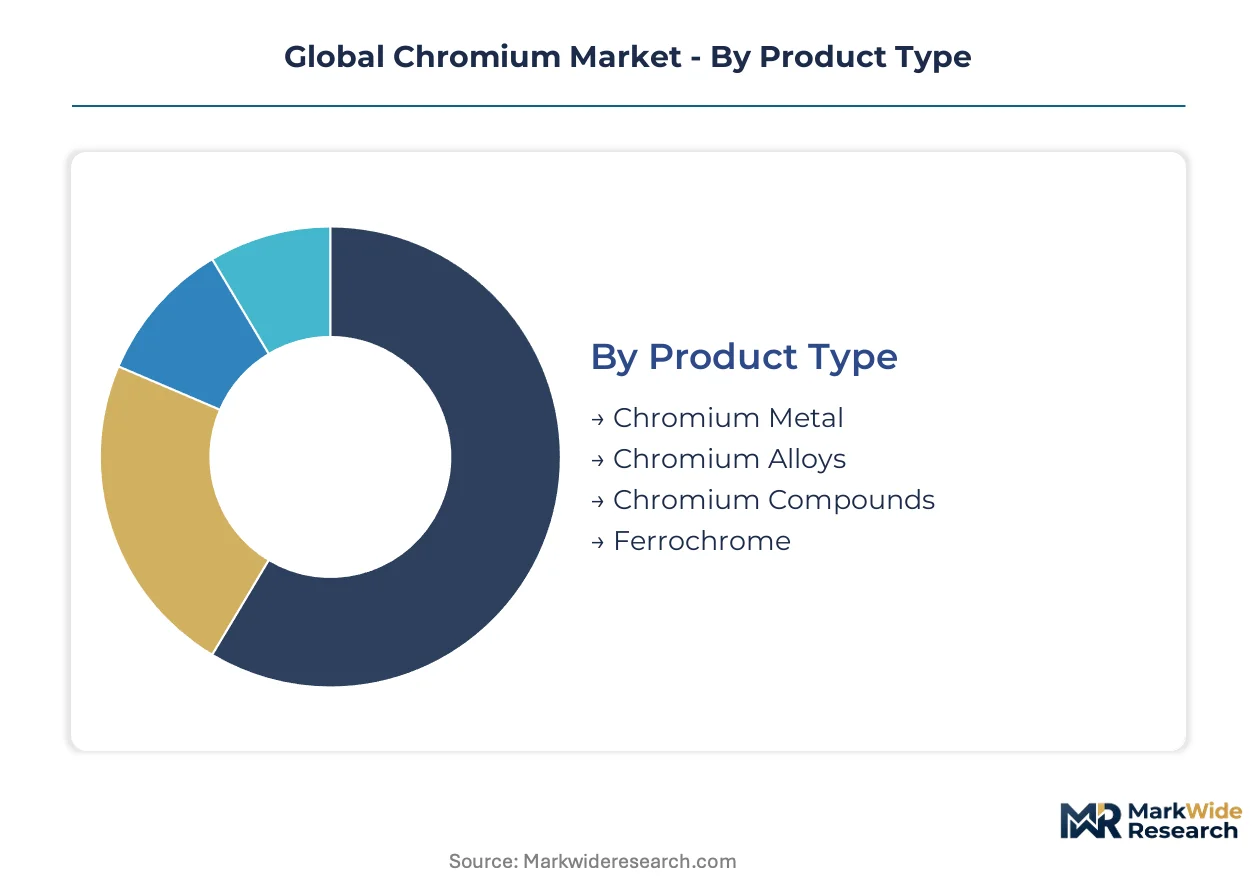
Chromium market segmentation reflects divergent purity requirements and regulatory burdens across metallurgical and chemical applications. Product specifications vary sharply between stainless steel feedstock and surface treatment compounds, with REACH and GB standards forcing distinct compliance investments.
Product Type:
Regulatory differentiation separates metallurgical grades governed by GB/T 5683 and ECHA chemical registrations from industrial specifications.
- Ferrochrome:An iron-chromium alloy containing 50-70% chromium content, produced via submerged arc furnace reduction of chromite ore. Chinese stainless steel melt shops in Jiangsu and Shanxi provinces concentrate procurement around unified charge specifications as MIIT tightens silicon and carbon banding requirements.
- Chromium Compounds:Processed derivatives including chromium trioxide and chromic acid serving plating, pigment, and tanning applications. European formulators in Germany's Rhine-Ruhr plating cluster face REACH authorization deadlines forcing trivalent substitution or closed-loop hexavalent recovery systems.
- Chromium Alloys:Nickel-chromium and cobalt-chromium superalloys for high-temperature service.
- Chromium Metal:Electrolytically refined material for aerospace bar stock and superalloy master melts.
Ferrochrome handles the majority of throughput; chromium compounds are gaining share fastest on environmental compliance tailwinds.
Application:
Cost tier stratification separates commodity metallurgical demand from specialty surface treatment and refractory applications.
- Stainless Steel:Austenitic and ferritic melt shop consumption of ferrochrome as the primary corrosion-resistance input. Indonesian integrated producers at Morowali Industrial Park and Chinese mills in Fujian province are consolidating procurement around direct long-term offtake rather than spot-market purchases.
- Coatings:Functional and decorative plating baths using hexavalent or trivalent chromium chemistry. Automotive trim suppliers in Stuttgart and aerospace component finishers in Toulouse face the steepest REACH compliance timelines for chromium trioxide authorization.
- Refractories:Magnesia-chrome brick for cement and non-ferrous smelting linings.
- Chemical Processing:Catalyst supports and oxidation reagents for petrochemical intermediates.
Stainless steel commands the volume base; coatings represent the steepest expansion trajectory on regulatory substitution economics.
End User:
Customer type determines specification stringency, with NADCAP-qualified supply chains demanding certified material provenance.
- Aerospace:Turbine blade and combustion hardware manufacturers requiring superalloy-grade chromium metal with tight sulfur and phosphorus tolerances. Engine OEMs in Connecticut and Arizona pull material through qualified bar stock suppliers with full heat and melt documentation.
- Automotive:Exhaust system catalyst substrates and decorative trim plating. German premium manufacturers and Japanese tier-one suppliers are accelerating trivalent process validation ahead of hexavalent phase-out deadlines.
- Construction:Architectural stainless steel cladding and structural fasteners.
- Electronics:Hard disk drive substrates and connector plating.
Aerospace absorbs the highest purity premiums; automotive is climbing the fastest on plating chemistry conversion.
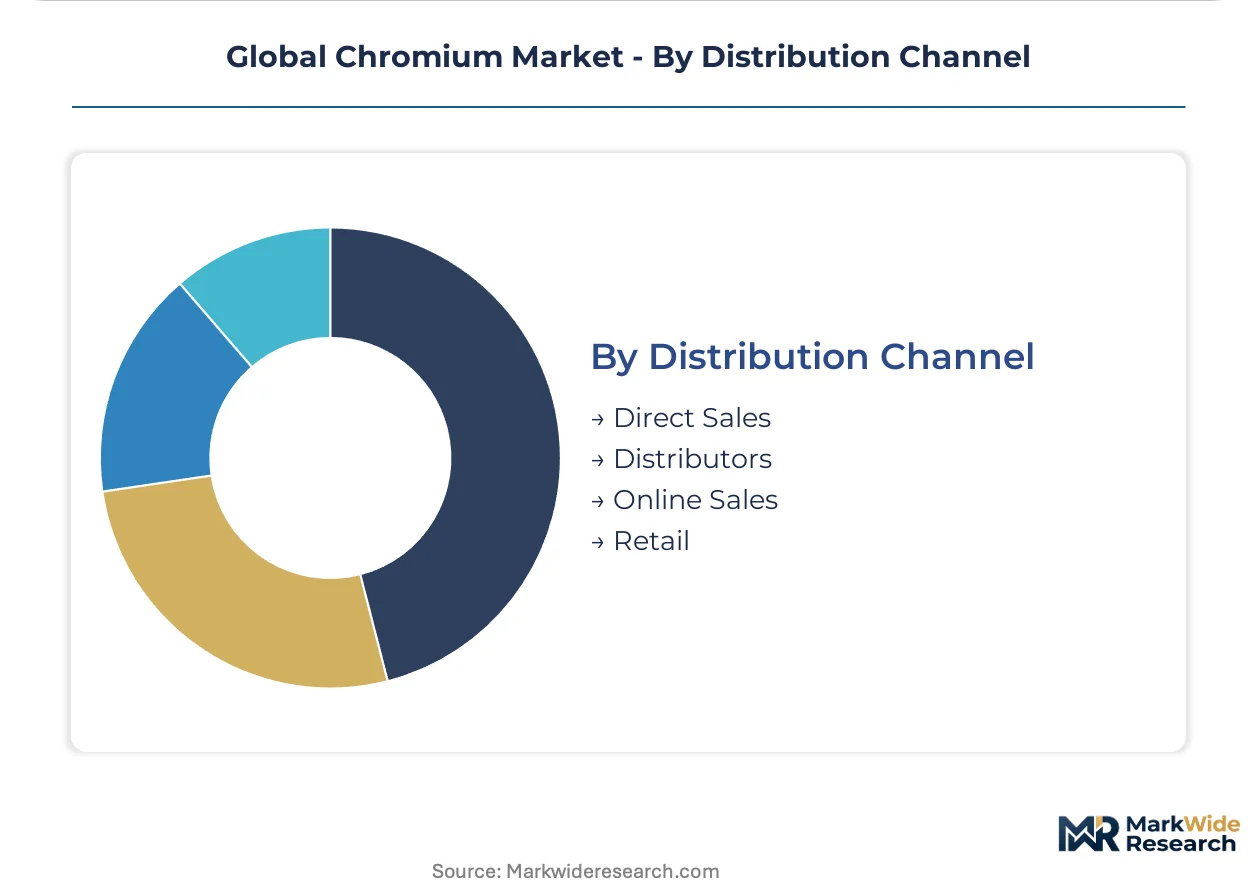
Distribution Channel:
Supply concentration shapes channel economics, with integrated producers bypassing traditional trader intermediaries.
- Direct Sales:Long-term offtake contracts between chromite mine-smelter operations and stainless steel melt shops. South African producers in the Bushveld Complex ship directly to Tsingshan and Delong facilities in Indonesia and China under multi-year supply agreements with carbon footprint disclosure requirements.
- Distributors:Regional stockholders serving fragmented plating shops and specialty alloy consumers.
- Online Sales:Digital procurement platforms for standardized ferrochrome grades.
- Retail:Small-lot chemical compound sales for laboratory and artisanal plating.
Direct sales handles the majority of ferrochrome tonnage; online platforms are expanding most quickly on spot-price transparency tools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chromium trade flows reveal stark asymmetries between ore-exporting jurisdictions and stainless steel manufacturing centers. Import dependency in East Asian melt shops contrasts with South Africa's chromite surplus position.
China
Jiangsu and Shanxi provinces host the world's largest stainless steel melt shop concentration, absorbing ferrochrome shipments under MIIT's tightening GB/T 5683 purity mandates. The regulator's silicon and carbon banding restrictions are compressing traditional grade spreads and forcing procurement consolidation around unified charge specifications. Tsingshan and Delong operations in Fujian and Guangdong internalize chromite-to-slab production within captive vertical structures.
South Africa
The Bushveld Complex anchors global chromite reserves, with Rustenburg and Limpopo smelters feeding export markets across three continents. The Department of Mineral Resources and Energy monitors mining charter compliance for extraction licenses while Eskom tariff volatility erodes ferrochrome conversion margins. Western Chrome Mines and Eastern Limb operations maintain integrated mining-smelting footprints that control feedstock costs.
India
Odisha and Karnataka states concentrate domestic ferrochrome capacity serving emerging stainless steel demand. PLI scheme incentives for melt shop capacity expansion are creating new procurement nodes outside traditional Chinese channels. Jindal Stainless and Aperam operations in Haryana and Maharashtra are consolidating direct offtake relationships with chromite suppliers.
Indonesia
Morowali Industrial Park hosts integrated nickel-chrome-stainless production complexes that bypass traditional ferrochrome spot markets. The Ministry of Industry's downstream metal processing incentives attract Chinese capital for captive smelter construction. Sulawesi operations leverage enhanced pre-reduction furnace technology to process lower-grade chromite fines competitively.
Finland
Tornio smelters specialize in European aerospace-grade ferrochrome with tight sulfur and phosphorus tolerances for superalloy applications. ECHA REACH registration requirements govern chemical compound imports, forcing plating formulators toward trivalent substitution. Outokumpu operations supply NADCAP-qualified bar stock producers in Connecticut and Arizona through certified material provenance chains.
Global Chromium Market Vendor Landscape
Listed leaders compete with private specialists across integrated mining-smelting footprints and merchant trading positions. The vendor base clusters around three archetypes: Bushveld-based chromite miners with captive smelters, European specialty alloy producers serving aerospace specifications, and Asian integrated stainless steel groups internalizing ferrochrome supply. Competitive moves center on backward integration into chromite mining and long-term offtake contracting with carbon footprint disclosure requirements.
Within the integrated mining-smelting tier, Glencore and Samancor Chrome exemplify South African chromite dominance through Bushveld Complex operations. Outokumpu Oyj occupies a position among European specialty producers serving aerospace superalloy specifications with tight impurity tolerances.
| Leading Market Players |
|---|
| Glencore |
| Samancor Chrome |
| Assmang Proprietary Limited |
| Kermas Investment Group |
| Tata Steel Mining Ltd. |
| Afarak Group PLC |
| Eurasian Resources Group |
| Outokumpu Oyj |
| Tharisa Plc |
| Others |
Supply Flow & Price Mechanics
Trivalent chromium chemistry substitution for hexavalent plating baths is simultaneously shifting supply geography toward European formulators and compressing premium pricing tiers as REACH compliance costs standardize across the coatings segment. This regulatory-driven input swap redraws procurement maps while eroding historical price premiums tied to hazardous material handling.
Pricing Analysis
Industrial OEM buyers anchor ferrochrome pricing around long-term offtake contracts with carbon footprint disclosure requirements. Three-tier pricing structure across NADCAP-certified aerospace grades, unified charge specifications for stainless steel melt shops, and merchant spot grades separates premium sulfur-controlled metal from standard ferrochrome. Pricing pressure stems from nickel price volatility transmitting into stainless steel mill procurement budgets. Merchant traders face the steepest price sensitivity; integrated mine-smelter operations command leverage through captive chromite supply.
Supply Chain Analysis
South Africa and Indonesia anchor global ferrochrome production through Bushveld Complex mining-smelting integration and Morowali Industrial Park captive operations. Chromite ore, metallurgical coke, and electrical power constitute the critical input trinity. Single-source vulnerability concentrates in South African chromite reserves exposed to Eskom tariff instability. Distribution runs through direct long-term contracts between integrated producers and stainless steel melt shops, displacing fragmented spot-market intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global chromium demand is accelerating on dual carbon goals and stainless steel capacity expansion, with MIIT GB/T 5683 enforcement acting as the decisive regulatory inflection compressing grade spreads and consolidating procurement channels.
For Market Incumbents: Fortify backward integration into Bushveld chromite mining to secure feedstock cost control against Indonesian enhanced pre-reduction furnace entrants. Prioritize NADCAP certification investment for aerospace superalloy metal streams as engine OEMs tighten provenance requirements. Channel control through direct long-term offtake contracts with Tsingshan and Delong operations displaces spot-market exposure. For New Entrants and Emerging Players: Lead with trivalent chromium compound formulation for European automotive plating shops facing REACH authorization deadlines. India's PLI-scheme stainless steel expansion offers the most penetrable demand node outside Chinese procurement concentration. Go-to-market positioning should emphasize closed-loop hexavalent recovery systems for German and French plating cluster shared infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward integrated mining-smelting archetypes with Bushveld Complex chromite licenses and captive power arrangements. Long-term viability across the projection horizon hinges on carbon border adjustment mechanism positioning and alloy scrap recycling circuit economics. The signal to watch is Indonesian Morowali ferrochrome output growth as a proxy for Chinese vertical integration displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chromite Mining | Glencore and Samancor-style Bushveld operations control feedstock costs across volatile ferrochrome price cycles. |
| NADCAP Certification Investment | Aerospace bar stock suppliers in Connecticut and Arizona demand certified sulfur and phosphorus tolerances for turbine components. |
| Enhanced Pre-reduction Furnace Deployment | Indonesian and Indian entrants bypass South African concentrate dependence through competitive lower-grade chromite processing. |
| Trivalent Plating Chemistry Validation | European automotive trim suppliers in Stuttgart accelerate formulation shifts ahead of ECHA chromium trioxide authorization deadlines. |
| Closed-loop Hexavalent Recovery Systems | German and French plating clusters consolidate around shared wastewater infrastructure to amortize compliance capital. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across stainless steel melt shop procurement directors, ferrochrome smelter operations managers, aerospace superalloy metallurgists, and European plating formulators. Secondary validation drew from customs trade data, SEC mining sector filings, ECHA REACH registration databases, and MIIT GB standard publications. Bottom-up ferrochrome shipment analysis and top-down stainless steel production triangulation anchored volume estimates.
Across the analysis window, projections incorporate grade-tier segmentation by carbon and silicon content, end-use splits between stainless steel feedstock and chemical compounds, and regional production hub clustering around South African, Indonesian, Chinese, and Indian smelter capacity. CAGRs were derived from alloy demand elasticity modeling against stainless steel output forecasts and aerospace superalloy build rates. Power cost volatility indices and chromite ore grade degradation curves fed scenario sensitivities.
The analysis sits within stated boundaries; outcomes outside sustained MIIT enforcement intensity, Eskom tariff stability, or Indonesian downstream investment flows would require recalibration. Forecasts reflect documented assumptions on stainless steel mill procurement consolidation trajectories and REACH authorization timeline adherence. Recalibration cycles align with material shifts in carbon border adjustment mechanism implementation and alloy scrap recycling economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Iron and Steel Market
Metals
Asia-Pacific Metallurgical Grade Fluorspar Market
Metals
Magnesium Metal Market
Metals
Nickel Foam Market
Metals
Global Tool Steel Market
Metals
Copper Powder Market
Metals
Neodymium Market
Metals
HSLA Steel Plate Market
Metals
Global Stainless Steel Lashing Wire Market
Metals
Amorphous Metal Cores Market
Metals
Aluminum Wire Market
Metals
Global Wire Rods Market
Metals
Metal Forging Market
Metals
Lithium Foil Market
Metals
Copper Clad Aluminum Wire Market
Metals
Metallic Rope Cords Market