
 Construction Helmet Market | 2026-2036
Construction Helmet Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Helmet Market Analysis
A shift from single-source to multi-source helmet procurement is realigning supply relationships across major construction programs. MSA Safety leverages its established testing infrastructure to sustain institutional contracts in North American energy infrastructure. Honeywell International anchors its position through integrated distribution networks serving federal and state-level projects. Delta Plus Group competes by specializing in modular suspension systems that adapt to regional fit requirements.
Construction helmets are engineered protective headgear, typically fabricated from high-density polyethylene or polycarbonate shells with adjustable suspension assemblies, designed to absorb impact energy and deflect penetrating objects at industrial worksites. Hard hats constitute the dominant product category due to universal adoption across building trades, while full brim helmets command premium positioning in utility and oil field applications where extended coverage against sun and debris provides measurable functional value. High-density polyethylene leads material selection for cost-sensitive volume procurement, whereas polycarbonate concentrates in specifications demanding superior impact resistance and electrical insulation ratings.
OSHA mandates under 29 CFR 1910.135 govern workplace head protection standards across United States jurisdictions, while the EU's PPE Regulation 2016/425 enforces CE marking and module B+C2 conformity procedures for market access. BIS certification requirements under IS 2925 are tightening import pathways into India's domestic supply chain. Stakeholders must monitor evolving harmonization between ANSI Z89.1 and EN 397 testing protocols as cross-border project standards converge.
Market Dynamics
OSHA's 2024 enforcement surge on construction sites is accelerating replacement cycles for certified head protection, compressing the interval between mandatory helmet upgrades from five years to three in high-risk classifications.
Growth Catalysts
- India's BIS IS 2925 Certification Mandate:Labor inspectors in Mumbai, Delhi, and Bangalore corridors are confiscating uncertified imports at worksite checkpoints, forcing contractors toward compliant domestic and imported suppliers.
- High-Density Polyethylene Cost Efficiency:Shell fabricators serving Southeast Asian infrastructure megaprojects are securing volume contracts that undercut polycarbonate alternatives by forty percent at procurement scale.
- Utility Sector Full Brim Specifications:Oil field operators in Texas and Alberta are specifying extended-coverage helmets for twelve-hour shift rotations, creating premium tier demand distinct from standard construction procurement.
Market Restraints
- Polycarbonate Resin Price Volatility:Electrical-grade helmet manufacturers face margin compression when benzene feedstock costs spike, forcing pass-through clauses that alienate price-locked municipal buyers.
- China Suspension Component Concentration:Four Zhejiang and Guangdong suppliers control seventy percent of global ratchet adjustment mechanism production, exposing downstream assemblers to single-source risk.
- EU PPE Regulation Module B+C2 Friction:Third-party conformity assessment delays of fourteen to eighteen weeks are blocking Southeast Asian exporters from spot-contract opportunities in German and French public works.
Strategic Opportunities
- Indonesia's Trans-Java Toll Road Program:State-owned contractor Waskita Karya specifications for ten thousand unit helmet orders per segment present white-space entry for certified suppliers outside the incumbent Japanese trading house network.
- ANSI Z89.1-EN 397 Harmonization:Dual-certified helmet designs eliminate retooling costs for suppliers serving cross-border North American and European infrastructure joint ventures.
- Direct-to-Site E-Procurement Platforms:Amazon Business and specialized industrial marketplaces are disintermediating traditional safety distributor markups for mid-sized contractor accounts in the US Southwest.
Industry Challenges
- Industrial Hygienist Certification Bottlenecks:OSHA-authorized trainers capable of conducting 29 CFR 1910.135 fit testing are scarce in Appalachian and Mountain West construction corridors, delaying project start dates.
- Legacy Suspension Inventory Stranding:Contractors holding pre-2019 four-point suspension stock face write-downs as six-point systems become default in union-negotiated safety protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Helmet Market |
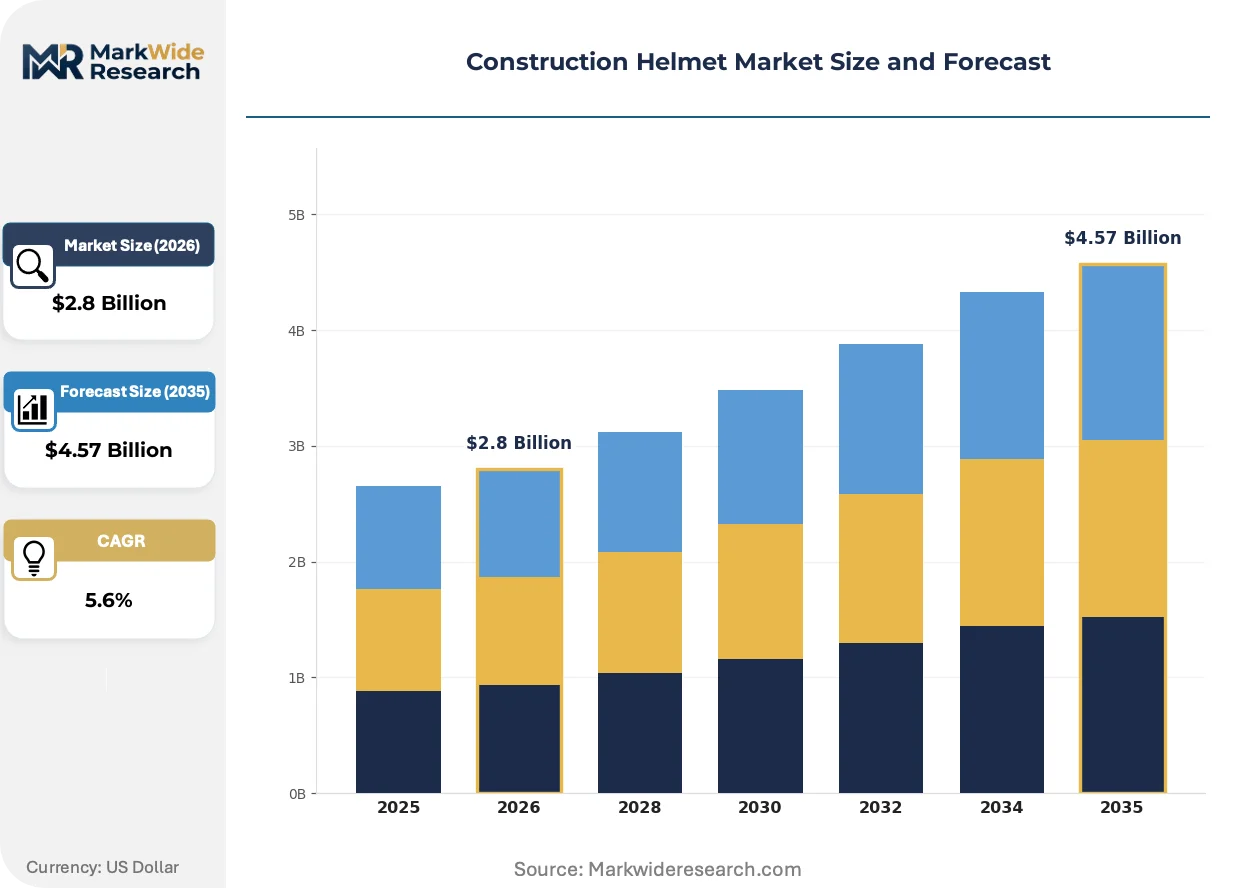
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.57 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Hats, Bump Caps, Full Brim Helmets, Half Shell Helmets Material: Polycarbonate, Fiberglass, High-Density Polyethylene, Steel Feature: Ventilation, Adjustable Suspension, Impact Resistance, Electrical Insulation End User: Construction Workers, Oil & Gas Personnel, Mining Operators, Emergency Responders |
| Companies Covered | uvex group, JSP Limited, MSA Safety, Centurion Safety Products Ltd., Bullard, Honeywell International, Delta Plus Group, Pyramex Safety Products, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Helmet Market Emerging Trajectories
Sensor-embedded helmet architectures are migrating from pilot programs to specification documents, with impact detection and proximity alert systems becoming bid requirements on federally funded infrastructure projects.
Polycarbonate-nylon hybrid shell construction is modularizing field repair and component replacement protocols. Utility fleet managers in the US Southeast are specifying snap-in brow pad and suspension assemblies that reduce technician downtime from forty-five minutes to under ten. This architecture is modularizing aftermarket service revenue models away from unit replacement toward component subscription programs.
The EU's PPE Regulation 2016/425 amendment tightening Module D audit frequencies is compressing manufacturer quality system documentation cycles. Notified bodies in Germany and Italy are demanding batch-specific test records for imported suspension webbing, forcing Asian suppliers to deploy in-house ISO 17025 laboratories. Full brim helmet categories face the steepest compliance cost escalation due to extended surface area testing protocols.
Consolidated procurement through general contractor safety programs is displacing trade-level purchasing autonomy. Skanska and Bechtel master service agreements now mandate single-source helmet standardization across electrical, concrete, and steel subcontractor tiers, most visible on data center and semiconductor fab projects in Arizona and Ohio. This concentration is compressing brand diversity at the worksite level while expanding volume commitment leverage for prime contractors.
Construction Helmet Market Segmentation
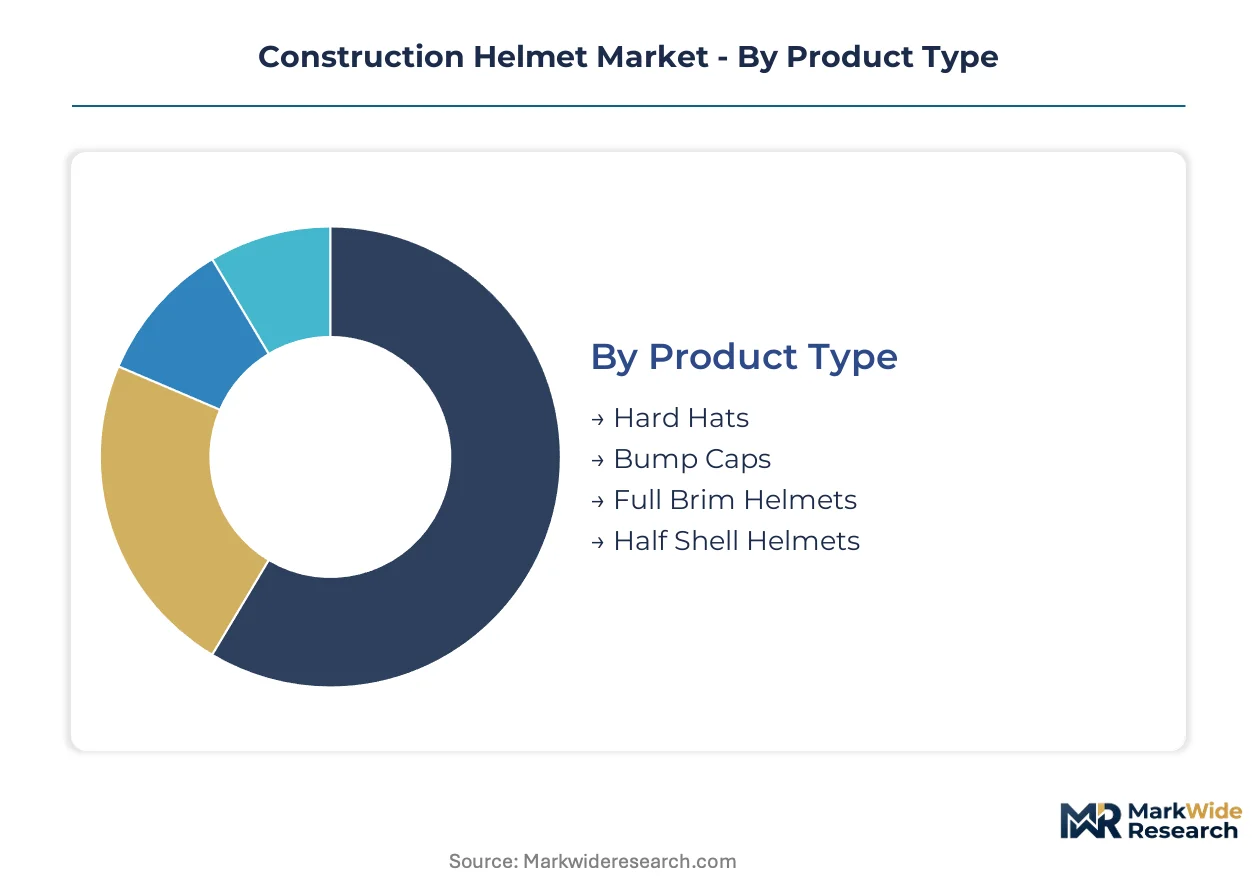
Construction helmet procurement stratifies across performance tiers that trade off unit cost against regulatory compliance depth. Specification divergence between commodity infrastructure builds and precision industrial sites creates parallel demand tracks that suppliers must serve through differentiated product architectures.
Product Type:
Customization intensity spans from universal-fit hard hats to task-engineered brim configurations that demand suspension redesign.
- Hard Hats:Molded HDPE or polycarbonate shells with four-point or six-point suspension assemblies dominate volume procurement across building trades. Demand concentrates in India's urban construction corridors as BIS IS 2925 enforcement intensifies and labor inspectors confiscate uncertified imports at Mumbai and Delhi worksite checkpoints.
- Full Brim Helmets:Extended peripheral coverage fabricated from polycarbonate or fiberglass composites protects against solar exposure and debris deflection during extended shifts. Oil field operators in Texas and Alberta specify these for twelve-hour rotations, creating premium tier demand distinct from standard construction procurement with measurable functional value in utility and energy infrastructure applications.
- Bump Caps:Lightweight polyethylene shells with minimal suspension for low-impact protection in confined mechanical spaces.
- Half Shell Helmets:Reduced-coverage designs for overhead clearance constraints in tunneling and shipyard environments.
Most installed capacity flows through Hard Hats. Expansion is steepest in Full Brim Helmets.
Material:
Cost tier stratification separates commodity thermoplastics from engineered composites in electrical and high-impact specifications.
- High-Density Polyethylene:Injection-molded shells serve cost-sensitive volume procurement with adequate impact absorption for general construction. Shell fabricators serving Southeast Asian infrastructure megaprojects secure contracts that undercut polycarbonate alternatives by forty percent at procurement scale.
- Polycarbonate:Superior impact resistance and electrical insulation ratings concentrate in specifications demanding ANSI Z89.1 Class E compliance and EN 397 voltage protection. Electrical-grade manufacturers face margin compression when benzene feedstock costs spike, forcing pass-through clauses that alienate price-locked municipal buyers.
- Fiberglass:Thermoset composite shells for extreme temperature and chemical exposure in foundry and smelter operations.
- Steel:Legacy metal shells retained in specific mining jurisdictions with projectile penetration hazards.
Procurement volume concentrates in High-Density Polyethylene. Value expansion tracks Polycarbonate.
Feature:
Functional add-ons migrate from optional accessories to bid-mandated specifications on federally funded infrastructure projects.
- Impact Resistance:Engineered shell geometry and suspension travel distance govern energy absorption metrics under ANSI Z89.1 and EN 397 drop testing protocols. OSHA's 2024 enforcement surge accelerates replacement cycles for certified head protection, compressing the interval between mandatory helmet upgrades from five years to three in high-risk classifications.
- Adjustable Suspension:Ratchet and pin-lock mechanisms enable field fit customization across diverse head geometries. Four Zhejiang and Guangdong suppliers control seventy percent of global ratchet adjustment mechanism production, exposing downstream assemblers to single-source risk.
- Ventilation:Molded air channels and removable crown pads for thermal management in humid climates.
- Electrical Insulation:Dielectric shell materials and suspension isolation for live electrical work environments.
Baseline specifications center on Impact Resistance. Feature differentiation is accelerating fastest in Adjustable Suspension.
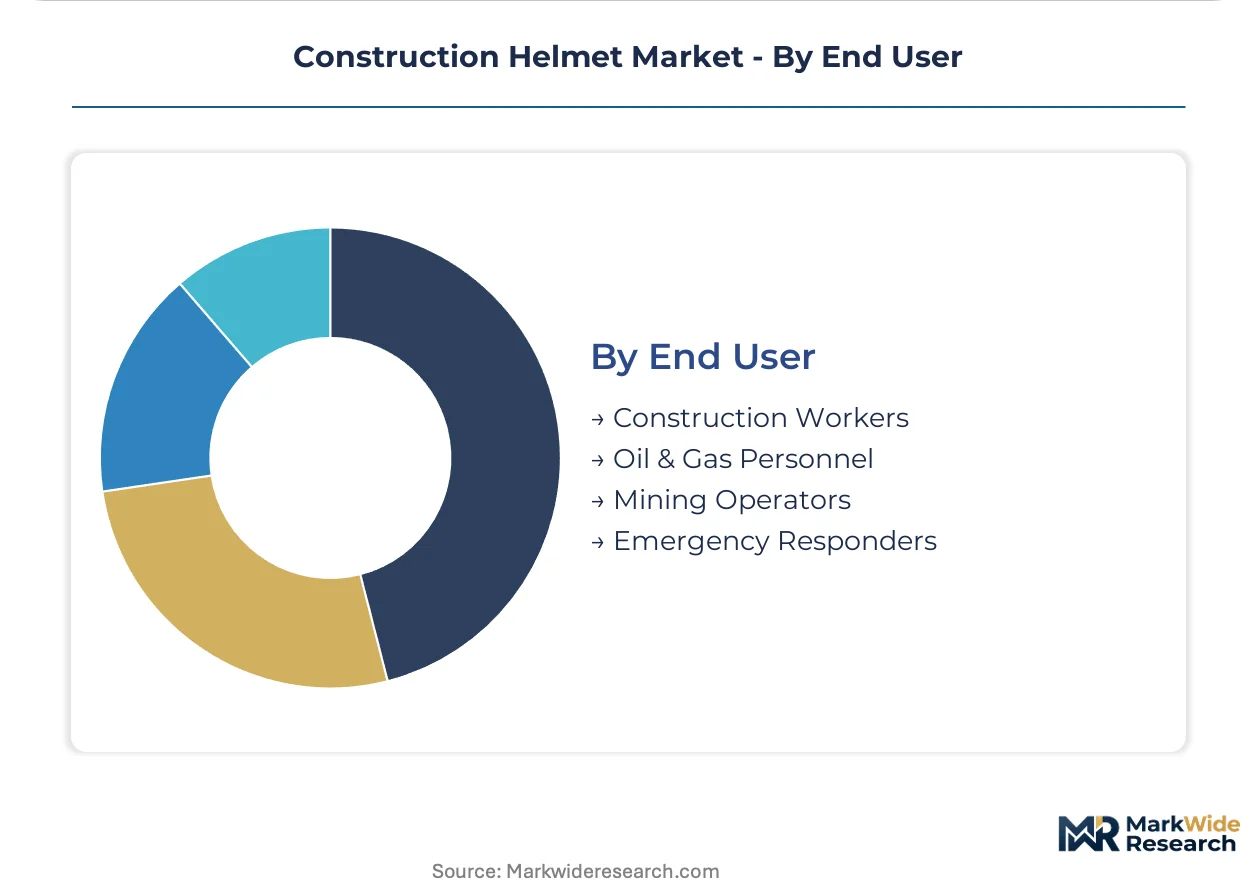
End User:
Customer type determines certification depth, replacement frequency, and procurement channel structure.
- Construction Workers:General building trades drive standardized hard hat procurement through general contractor safety programs. Skanska and Bechtel master service agreements mandate single-source helmet standardization across electrical, concrete, and steel subcontractor tiers, compressing brand diversity at the worksite level while expanding volume commitment leverage for prime contractors.
- Oil & Gas Personnel:Offshore and onshore energy operations specify full brim configurations with flame-resistant accessories and integrated communications mounts. State-owned contractor Waskita Karya specifications for ten thousand unit helmet orders per segment on Indonesia's Trans-Java Toll Road Program present white-space entry for certified suppliers.
- Mining Operators:Underground and open-pit extraction sites demand enhanced penetration resistance and integrated lighting systems.
- Emergency Responders:Search and rescue teams require helmet-mounted camera compatibility and rapid donning features.
Volume concentration sits with Construction Workers. Procurement sophistication is climbing fastest among Oil & Gas Personnel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's urban construction corridors command procurement volume concentration as labor safety enforcement intensifies across Mumbai, Delhi, and Bangalore worksites. Infrastructure megaprojects across Southeast Asia are expanding certified head protection procurement volumes. Regulatory tightening in the EU and US is reshaping import pathways and replacement cycles.
United States
OSHA's 2024 enforcement surge on construction sites accelerates replacement cycles for certified head protection. The agency's 29 CFR 1910.135 mandates compress mandatory helmet upgrades from five years to three in high-risk classifications. Oil field operators in Texas specify full brim configurations for twelve-hour shift rotations, creating premium tier demand distinct from standard building trades procurement.
India
BIS certification requirements under IS 2925 are tightening import pathways into India's domestic supply chain. Labor inspectors in Mumbai, Delhi, and Bangalore corridors confiscate uncertified imports at worksite checkpoints, forcing contractors toward compliant domestic and imported suppliers. Urban construction corridors in Maharashtra and Karnataka drive volume concentration as infrastructure investment scales.
Germany
The EU's PPE Regulation 2016/425 enforces CE marking and module B+C2 conformity procedures for market access. Third-party conformity assessment delays of fourteen to eighteen weeks block Southeast Asian exporters from spot-contract opportunities in German public works. Notified bodies in Germany demand batch-specific test records for imported suspension webbing, forcing Asian suppliers to deploy in-house ISO 17025 laboratories.
Indonesia
State-owned contractor Waskita Karya specifications for ten thousand unit helmet orders per segment present white-space entry for certified suppliers. The Trans-Java Toll Road Program generates sustained procurement volume across multiple construction phases. Domestic safety equipment distributors are expanding inventory positions to capture recurring replacement demand from project consortiums.
United Arab Emirates
Megaproject construction in Dubai and Abu Dhabi drives specification-grade helmet procurement for expatriate labor forces. Federal safety authority inspections are aligning site-level requirements with Gulf Cooperation Council harmonization initiatives. Specialized distributors serving oil field and utility infrastructure segments are expanding premium-tier product portfolios.
Construction Helmet Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue sensor-embedded architectures and modular suspension systems. The vendor base stratifies across three tiers: multinational safety conglomerates with institutional contracting infrastructure, regional specialists with certified manufacturing for single-market regulatory compliance, and component suppliers concentrated in Zhejiang and Guangdong for ratchet adjustment mechanisms. Consolidation pressure is mounting as general contractor master service agreements mandate single-source standardization. Strategic moves center on dual-certification design investments and direct-to-site e-procurement platform partnerships.
Within the multinational tier, MSA Safety and Honeywell International anchor institutional contracting positions through established testing infrastructure and integrated distribution networks. Delta Plus Group occupies a specialist position in modular suspension systems that adapt to regional fit requirements. Among diversified industrial manufacturers, 3M Company and uvex group represent the convergence of personal protective equipment portfolios with construction sector applications. These named entities exemplify competitive archetypes rather than exhaustive market coverage.
| Leading Market Players |
|---|
| uvex group |
| JSP Limited |
| MSA Safety |
| Centurion Safety Products Ltd. |
| Bullard |
| Honeywell International |
| Delta Plus Group |
| Pyramex Safety Products |
| 3M Company |
| Others |
Supply Flow & Price Mechanics
General contractor master service agreements concentrate procurement leverage among a shrinking pool of prime contractors, compressing supplier margins while rewarding volume commitment with preferential pricing tiers. This buyer consolidation feeds directly into supply chain restructuring as assemblers seek captive control over critical suspension components.
Pricing Analysis
Input-cost pass-through from benzene feedstock volatility governs polycarbonate helmet pricing, forcing electrical-grade manufacturers to embed escalation clauses that municipal buyers resist. Three-tier pricing structure across premium full-brim, standard hard hat, and economy HDPE levels separates oil field operators from general construction trades from cost-sensitive infrastructure megaprojects. Price differentiation rests on certification depth—dual ANSI Z89.1-EN 397 compliance commands measurable premiums over single-standard alternatives. Cost compression in the polycarbonate tier is intensifying because electrical insulation specifications face substitution pressure from hybrid shell architectures. Municipal procurement teams exhibit highest price sensitivity, while utility fleet managers prioritize lifecycle cost over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from Skanska and Bechtel master service agreements are forcing helmet assemblers to qualify secondary ratchet mechanism suppliers beyond the dominant Zhejiang and Guangdong concentration. Manufacturing gravity centers on China for suspension components, India for molded HDPE shells serving domestic BIS IS 2925 compliance, and Germany for polycarbonate electrical-grade fabrication. Raw material dependencies span high-density polyethylene resin, polycarbonate granules, and nylon suspension webbing. Single-source vulnerability in ratchet adjustment mechanisms exposes downstream assemblers to production disruption. Distribution runs through industrial safety distributors and emerging direct-to-site e-procurement platforms serving mid-sized contractor accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in sensor-embedded premium tiers and modular component subscription models, with cost-down drivers from snap-in suspension architectures enabling field repair economics that displace full-unit replacement cycles.
For Market Incumbents: Hedge against polycarbonate resin volatility by securing backward integration into HDPE shell production or hybrid material R&D. Dual-certification design investment protects against ANSI Z89.1-EN 397 harmonization delays that could strand single-standard inventory. Channel control through exclusive distributor relationships defends position against Amazon Business disintermediation in the US Southwest contractor segment. For New Entrants and Emerging Players: BIS IS 2925 in India opens a window for certified suppliers to capture procurement volume as labor inspectors confiscate uncertified imports at Mumbai and Delhi worksite checkpoints. Indonesia's Trans-Java Toll Road Program presents the most penetrable geography, with Waskita Karya specifications for ten thousand unit orders per segment creating white-space outside incumbent Japanese trading house networks. Direct-to-site e-procurement platform partnerships offer the fastest go-to-market angle for mid-sized contractor accounts. For Investors and Strategic Acquirers: Safety equipment conglomerates with institutional contracting infrastructure are the most active acquirer in this space, seeking sensor-embedded technology capabilities and modular suspension IP. Acquisition target archetypes include regional specialists with certified manufacturing for single-market regulatory compliance and ISO 17025 laboratory assets. The signal to watch is OSHA enforcement intensity in Appalachian and Mountain West corridors, where industrial hygienist certification bottlenecks delay project starts and concentrate demand among qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Design Investment | Eliminates retooling costs for suppliers serving cross-border North American and European infrastructure joint ventures. |
| Backward Integration into Suspension Components | Reduces single-source risk from Zhejiang and Guangdong ratchet mechanism concentration. |
| ISO 17025 Laboratory Deployment | Satisfies German and Italian notified body demands for batch-specific suspension webbing test records. |
| Direct-to-Site E-Procurement Partnership | Captures mid-sized contractor accounts disintermediated from traditional safety distributor markups. |
| Sensor-Embedded Architecture Development | Meets federally funded infrastructure project bid requirements for impact detection and proximity alert systems. |
Methodological Framework
Direct dialogue with safety equipment procurement managers, industrial hygienists, helmet assemblers, and notified body auditors grounds qualitative findings in operational reality. Secondary validation draws from OSHA enforcement records, BIS certification registries, EU PPE Regulation Module B+C2 conformity assessment databases, and customs trade data for HDPE and polycarbonate resin flows. Bottom-up unit shipment estimates triangulate against top-down construction spending allocation models.
Segment-level projections across product type, material grade, feature configuration, and end-user vertical populate the analytical framework throughout the forecast period. CAGRs derive from regression analysis against construction output indices, infrastructure investment pipelines, and regulatory enforcement intensity metrics. Model inputs incorporate BIS IS 2925 compliance transition timelines, ANSI Z89.1-EN 397 harmonization progress, and sensor-embedded specification adoption curves on federally funded projects.
Revisions become necessary when OSHA enforcement intensity shifts, benzene feedstock costs spike beyond historical bands, or EU PPE Regulation Module D audit frequencies tighten further. Deviation in China's suspension component export availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Self-Pierce Riveting (SPR) Equipment Market
Construction Equipment
GCC Crane Market
Construction Equipment
Solar Pile Driving Equipment Market
Construction Equipment
Self-Driving Dumpers Machine Market
Construction Equipment
Jackhammer Market
Construction Equipment
Europe Welding Equipment Market
Construction Equipment
Global CNC Tool and Cutter Grinding Machine Market
Construction Equipment
Stud Welding Guns Market
Construction Equipment
Asia Pacific Construction Equipment Market
Construction Equipment
Global Skid Steer Attachments Market
Construction Equipment
TBR Hydraulic Curing Press Market
Construction Equipment
Global Crane Market
Construction Equipment
Mobile Asphalt Plant Market
Construction Equipment
Fogging Machine Market
Construction Equipment
Hydraulic Shearing Machine Market
Construction Equipment
Industrial Ovens Market