
 United States Crane Market | 2026-2036
United States Crane Market Size, Share, and Industry Trends Forecast 2026-2036
United States Crane Market Intelligence
Modular crane configuration—where manufacturers bundle base machines with interchangeable boom sections, counterweight kits, and telematics packages—is hardening as the dominant procurement format. Terex Corporation leverages this architecture across its mobile crane lines to reduce field assembly time for rental fleet operators. The Manitowoc Company anchors its competitive stance through in-house boom fabrication and integrated control systems that sustain premium positioning in tower crane categories. Columbus McKinnon Corporation specializes in overhead lifting equipment and occupies a distinct niche below the heavy-lift threshold where larger manufacturers compete less aggressively.
A crane is a powered lifting machine utilizing wire ropes, sheaves, hydraulic cylinders, or electric motors to raise and lower loads, with load capacities spanning from under one ton to over 5,000 tons depending on configuration. Mobile cranes dominate unit volume in the United States owing to versatility across dispersed job sites, while crawler cranes command the highest average selling prices due to specialized heavy-lift applications in energy infrastructure. Tower cranes concentrate margin pools in urban vertical construction, particularly where super-tall building codes require precision placement at significant heights. Electric and hybrid technological features are gaining specification share as project owners impose emissions constraints on equipment fleets.
OSHA crane operator certification requirements and FAA coordination protocols for tower crane operations near airports shape equipment deployment timelines and site selection across metropolitan areas. EPA Tier 4 Final emissions standards for off-road diesel engines influence powertrain design decisions and fleet replacement cycles for mobile and crawler units. Stakeholders must monitor evolving state-level clean construction rules in California and New York, where air quality mandates are tightening fastest, and weigh the capital trade-offs between conventional diesel platforms and emerging electric alternatives before committing to multi-year fleet investments.
Market Dynamics
Modular crane configuration and emissions-driven powertrain substitution are compressing procurement cycles across United States rental fleets and project owners. Equipment lessors now bundle telematics, boom sections, and counterweight kits as standardized packages, while EPA Tier 4 Final standards accelerate diesel-to-electric conversion timelines in metropolitan construction zones.
Growth Catalysts
- Infrastructure Investment and Jobs Act:Federal bridge and port modernization mandates are tightening equipment specifications and extending crane deployment durations at federally funded sites.
- Data center construction clusters:Northern Virginia and Texas hyperscale facility buildouts are absorbing crawler and tower crane capacity at unprecedented density.
- Hybrid powertrain adoption:Electric and hybrid technological features are gaining specification share as project owners impose emissions constraints on equipment fleets.
Market Restraints
- Specialized steel input volatility:High-strength boom steel and precision-machined hydraulic components face concentrated supply from domestic foundries with limited surge capacity.
- OSHA certification friction:Crane operator certification requirements and FAA coordination protocols for tower crane operations near airports extend deployment timelines and constrain site selection flexibility.
- Used equipment substitution:Secondary markets for late-model diesel crawler cranes offer cost-competitive alternatives to new electric platforms for non-metropolitan projects.
Strategic Opportunities
- Gulf Coast petrochemical corridor:Heavy-lift demand for ethylene cracker and LNG export terminal expansions remains underpenetrated by electric crane offerings due to load requirements.
- Telematics-as-a-service bundling:Equipment manufacturers can unbundle predictive maintenance and fleet optimization software as standalone recurring revenue streams.
- California clean construction mandates:State-level air quality rules are tightening fastest in Los Angeles and San Francisco metro areas, creating first-mover advantage for zero-emission crane platforms.
Industry Challenges
- Certified operator scarcity:OSHA crane operator certification pipelines cannot match retirement outflows and new project ramp rates, particularly for tower crane specialists.
- Multi-year fleet capital intensity:The capital trade-off between conventional diesel platforms and emerging electric alternatives requires precise timing before committing to replacement cycles.
- Telematics integration complexity:Legacy fleet management systems resist seamless integration with new IoT-enabled crane monitoring architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Crane Market |
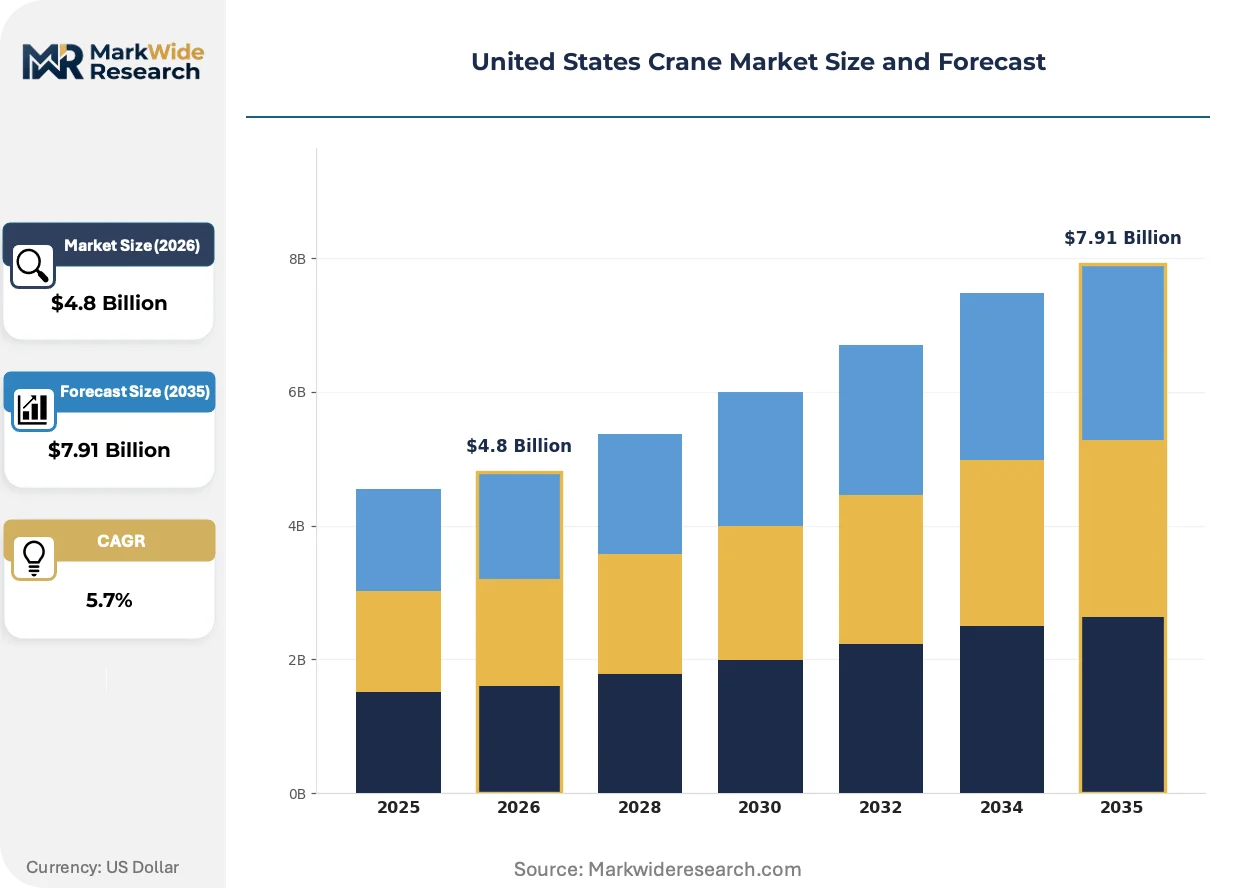
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Crane, Tower Crane, Loader Crane, Crawler Crane End User: Construction, Oil & Gas, Mining, Shipping Deployment: Onsite, Offsite, Rental, Sale Technological Feature: Hydraulic, Electric, Telescopic, Conventional |
| Companies Covered | Terex Corporation, The Manitowoc Company, Inc., Columbus McKinnon Corporation, Konecranes, Inc., American Crane & Equipment Corporation, Gorbel Inc., Ingersoll Rand Inc., Manitex International Inc., Broderson Manufacturing Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Crane Market Strategic Shifts & Innovations
Electrification architectures and predictive maintenance platforms are restructuring competitive advantage around total cost of ownership rather than upfront equipment price. Manufacturers and rental operators are racing to embed software-defined capabilities that extend asset utilization rates and reduce unplanned downtime.
Telematics-enabled condition monitoring is consolidating fleet management practices across United States rental operators. Sensors embedded in boom structures, winch systems, and outriggers transmit real-time load stress and fatigue data to centralized platforms. Major equipment lessors are mandating these systems for inclusion in new procurement contracts. The technology is consolidating vendor relationships toward integrated hardware-software suppliers capable of delivering unified fleet visibility.
EPA Tier 4 Final emissions standards are compressing diesel engine design margins and accelerating electric alternative development. Off-road diesel powertrains now require exhaust after-treatment systems that add weight, maintenance burden, and thermal management complexity. Mobile and crawler crane segments are most affected, with manufacturers expanding battery-electric and hybrid product lines to maintain metropolitan market access.
Rental fleet operators are unbundling maintenance contracts and demanding usage-based service pricing. Traditional fixed-fee service agreements are giving way to per-lift-hour or per-ton-mile pricing models tied to actual equipment utilization. This shift is most visible in Texas and Florida construction markets, where project volatility makes fixed-cost service commitments economically unattractive for contractors managing variable workloads.
United States Crane Market Segmentation
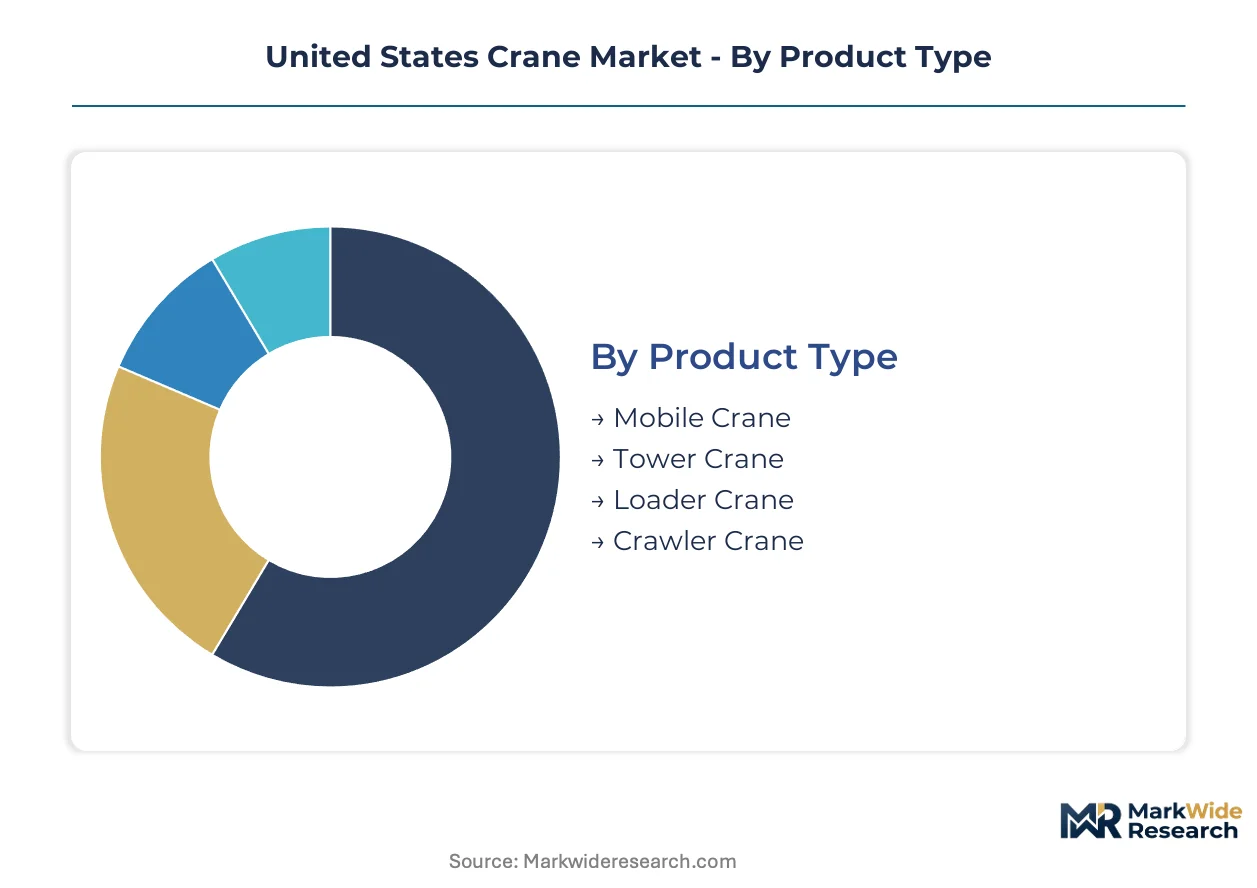
Crane procurement decisions in the United States hinge on load specifications, site mobility constraints, and emissions compliance timelines. Segmentation reveals where capital concentrates and which technology trajectories are displacing incumbent platforms.
Product Type:
Buyers prioritize lifting capacity against transport logistics and assembly time when selecting crane architecture.
- Mobile Crane:Truck-mounted or all-terrain configurations deploy rapidly across dispersed job sites without dedicated transport fleets. Demand clusters in Texas and Florida construction markets where project volatility favors equipment that relocates within hours rather than days. Rental fleet operators specify mobile units most heavily where utilization rates fluctuate seasonally.
- Tower Crane:Fixed-base vertical lifting systems dominate urban super-tall construction through precision placement at significant heights. Northern Virginia data center buildouts and Manhattan residential towers absorb capacity fastest, though FAA coordination protocols near airports constrain site selection flexibility.
- Loader Crane:Articulating boom systems mounted on commercial vehicles handle lighter loads with rapid cycling. Waste management and utility maintenance fleets in the Southeast specify these for material handling at distributed facilities.
- Crawler Crane:Tracked undercarriages distribute massive loads across soft ground without outrigger preparation. Gulf Coast petrochemical expansions and LNG export terminals in Texas and Louisiana drive specification for ethylene cracker module installation.
Mobile cranes lead on scale; tower cranes lead on momentum.
End User:
Application-specific duty cycles and regulatory exposure shape equipment procurement across verticals.
- Construction:General building contractors represent the volume anchor, with demand bifurcating between metropolitan vertical projects and horizontal infrastructure. Federal bridge modernization under the Infrastructure Investment and Jobs Act extends deployment durations at federally funded sites.
- Oil & Gas:Upstream and midstream operators require heavy-lift capacity for refinery turnaround and pipeline compressor station work. The Permian Basin and Gulf Coast corridor concentrate crawler crane utilization for module-heavy facility construction.
- Mining:Surface extraction operations specify rough-terrain mobile units for maintenance and infrastructure tasks. Copper and aggregate operations in Arizona and Nevada drive replacement cycles tied to commodity price recoveries.
- Shipping:Port terminal operators and inland waterway barge handlers utilize specialized gantry and floating crane configurations. Charleston and Houston port expansions under federal modernization mandates tighten equipment specifications.
Construction dominates absolute volume; oil and gas commands premium pricing per lift-hour.
Deployment:
Capital availability and project duration uncertainty determine ownership versus access models.
- Onsite:Long-duration projects with predictable utilization curves favor dedicated equipment stationed permanently. Data center campuses in Northern Virginia and hyperscale facilities in Texas deploy tower cranes onsite for 18-36 month construction windows.
- Offsite:Modular construction yards and prefabrication facilities position cranes at manufacturing nodes rather than final installation sites. California factory-built housing producers utilize this model to circumvent metropolitan emissions restrictions.
- Rental:Equipment lessors now bundle telematics, boom sections, and counterweight kits as standardized packages. Texas and Florida contractors managing variable workloads prefer per-lift-hour pricing over fixed-cost service commitments.
- Sale:Fleet operators with stable utilization profiles and in-house maintenance capabilities purchase assets outright. Secondary markets for late-model diesel crawler cranes offer cost-competitive alternatives to new electric platforms for non-metropolitan projects.
Rental leads on transaction volume; onsite leads on contract duration.
Technological Feature:
Emissions compliance deadlines and total cost of ownership calculations are restructuring specification priorities.
- Hydraulic:Fluid power systems deliver precise load control through variable displacement pumps and closed-loop circuits. Legacy fleet dominance persists in oil and gas applications where electrification load requirements remain unmet.
- Electric:Battery-electric and grid-connected architectures eliminate tailpipe emissions at point of use. Los Angeles and San Francisco metro areas under California clean construction mandates create first-mover advantage for zero-emission platforms.
- Telescopic:Nested boom sections extend reach without disassembly, compressing mobilization timelines. All-terrain mobile cranes deploy this architecture for rapid response to emergency infrastructure repairs.
- Conventional:Mechanical and early-hybrid systems without advanced telematics integration occupy price-sensitive segments. Used equipment substitution pressures this category as Tier 4 Final compliance costs accumulate.
Hydraulic leads on installed base; electric leads on specification growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States crane industry traces its modern scale to post-World War II infrastructure expansion, when federal highway programs and port modernization created sustained equipment demand that concentrated manufacturing in the Upper Midwest and Gulf Coast.
Texas
Hyperscale data center construction in Dallas-Fort Worth and Austin absorbs crawler crane capacity at unprecedented density. EPA Tier 4 Final emissions standards accelerate diesel-to-electric conversion timelines in Houston metropolitan construction zones. The Gulf Coast petrochemical corridor from Baytown to Beaumont drives heavy-lift specification for ethylene cracker module installation.
California
Los Angeles and San Francisco metro areas under state clean construction mandates create first-mover advantage for zero-emission crane platforms. CARB regulations tighten fastest in Southern California air basins, compressing procurement cycles for electric alternatives. Factory-built housing producers in the Central Valley utilize offsite modular construction to circumvent metropolitan emissions restrictions.
Virginia
Northern Virginia data center buildouts deploy tower cranes onsite for 18-36 month construction windows. FAA coordination protocols near Dulles International Airport constrain site selection flexibility and extend deployment timelines. Loudoun County and Prince William County anchor the nation's densest concentration of hyperscale facility construction.
Florida
Seasonal construction volatility favors rental fleet operators specifying mobile units with rapid relocation capability. Miami-Dade and Broward County building codes for hurricane resistance tighten equipment specifications for high-rise vertical construction. Tampa and Orlando infrastructure projects absorb rough-terrain mobile cranes for bridge and highway work.
Louisiana
LNG export terminal expansions along the Mississippi River delta drive crawler crane utilization for module-heavy facility construction. OSHA crane operator certification requirements shape equipment deployment timelines across Baton Rouge and Lake Charles industrial corridors. Port of New Orleans modernization under federal infrastructure mandates tightens gantry crane specifications.
United States Crane Market Key Industry Players
Premium-margin players sit above commodity-margin players across technology integration and aftermarket service depth, with tiered competition separating integrated manufacturers from component specialists and regional fabricators. The vendor base spans three strategic archetypes: diversified industrial conglomerates with captive crane divisions, pure-play lifting equipment specialists with in-house fabrication, and niche regional assemblers serving price-sensitive segments. Dominant competitive moves include portfolio diversification into telematics-enabled service contracts and backward integration into precision-machined hydraulic components.
Within the pure-play specialist tier, Terex Corporation and The Manitowoc Company, Inc. exemplify divergent strategic positions—Terex leverages modular architecture across mobile crane lines while Manitowoc anchors premium positioning through integrated control systems in tower crane categories. Columbus McKinnon Corporation occupies a distinct niche below the heavy-lift threshold where larger manufacturers compete less aggressively.
| Leading Market Players |
|---|
| Terex Corporation |
| The Manitowoc Company, Inc. |
| Columbus McKinnon Corporation |
| Konecranes, Inc. |
| American Crane & Equipment Corporation |
| Gorbel Inc. |
| Ingersoll Rand Inc. |
| Manitex International Inc. |
| Broderson Manufacturing Corporation |
| Others |
Cost & Logistics Intelligence
High-strength steel price indices cascade through crane manufacturing supply chains, compressing margins on premium crawler units while amplifying cost advantages for manufacturers with captive foundry operations. Equipment lessors absorb volatility through usage-based pricing models that transfer input cost risk to project owners.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates integrated telematics platforms from conventional hydraulic systems and refurbished legacy fleets. Price differentiation hinges on EPA Tier 4 Final compliance certification and bundled predictive maintenance contracts. Pricing pressure stems from secondary market substitution for late-model diesel crawlers in non-metropolitan oil and gas corridors. Price-sensitive independent contractors in Texas and Florida favor rental per-lift-hour models over capital-intensive ownership.
Supply Chain Analysis
Refurbishment flows for boom sections and hydraulic components create secondary supply channels that compete with OEM replacement parts. Domestic foundries in Ohio and Pennsylvania supply high-strength alloy steel, while precision-machined hydraulic valves draw from German and Japanese specialty manufacturers. Single-source vulnerability concentrates in rare-earth magnets for electric powertrain motors. Distribution runs through manufacturer-direct sales for large crawler units and regional rental fleet networks for mobile cranes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
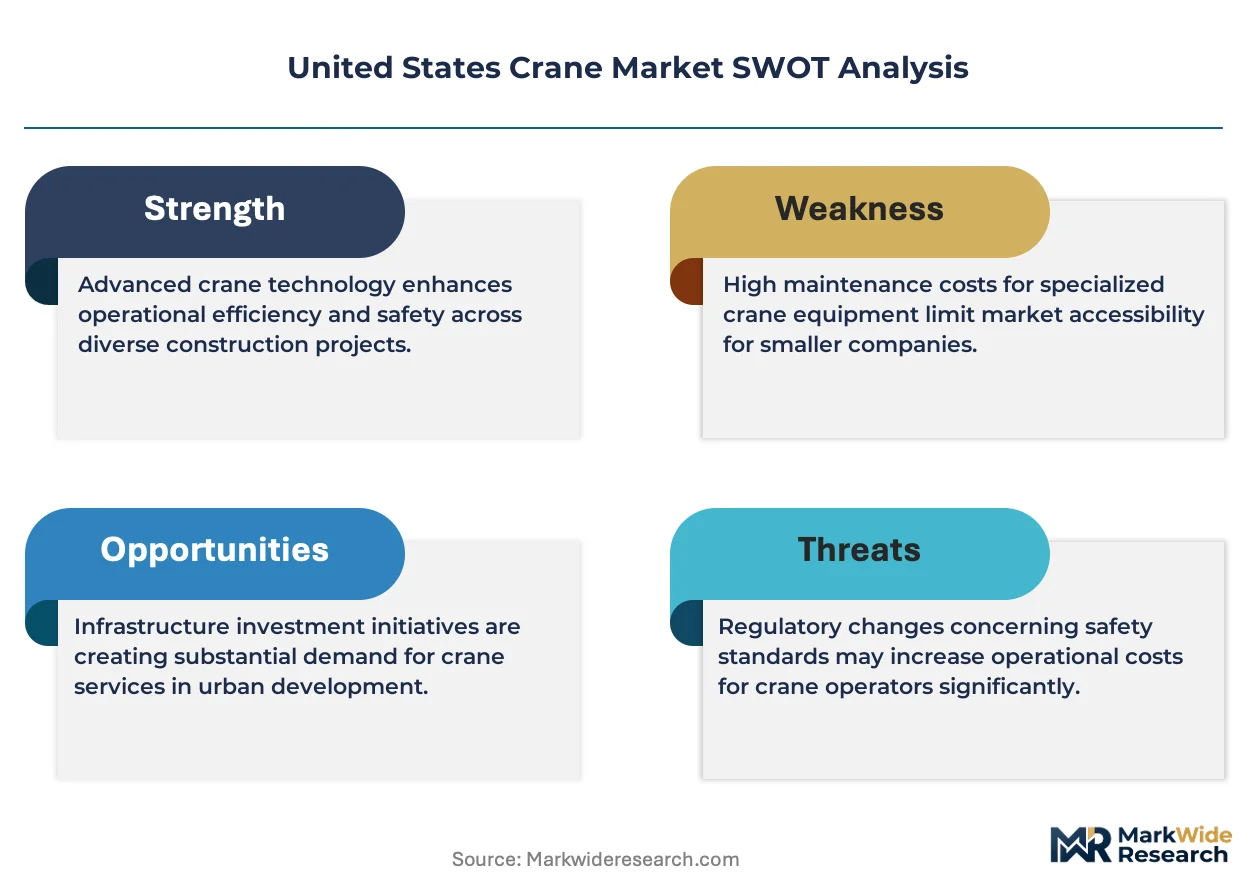
The United States crane market functions as a regulatory compounder where EPA Tier 4 Final emissions deadlines and state-level clean construction mandates accelerate fleet replacement cycles regardless of macroeconomic conditions.
For Market Incumbents: Anchor defensive positioning through backward integration into boom fabrication and captive hydraulic component production. Threat substitution from Chinese electric crane platforms intensifies in California metro areas under CARB regulations. Certification investment in OSHA operator training pipelines secures deployment timeline advantages at federally funded infrastructure sites. For New Entrants and Emerging Players: Capture white-space opportunity in zero-emission tower crane platforms for Northern Virginia data center clusters where FAA coordination protocols constrain incumbent expansion. Gulf Coast petrochemical heavy-lift applications remain underpenetrated by electric alternatives due to load requirements. Go-to-market leverage through telematics-as-a-service bundling unburdens capital-constrained contractors from upfront software licensing. For Investors and Strategic Acquirers: Asymmetric upside sits with regional rental fleet operators possessing dense metropolitan yard networks and established OSHA certification pipelines. Long-term viability favors asset-light platforms with usage-based pricing flexibility over capital-heavy manufacturing. Monitor California Air Resources Board rulemaking timelines as inflection signals for electric platform adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Embedded IoT sensors in boom structures transmit real-time fatigue data to centralized fleet management systems. |
| Electric Powertrain Development | Battery-electric architectures maintain metropolitan market access under tightening EPA Tier 4 Final standards. |
| Modular Configuration Standardization | Interchangeable boom sections and counterweight kits compress field assembly time for rental operators. |
| Predictive Maintenance Service Launch | Usage-based pricing models tied to per-lift-hour utilization replace fixed-fee service agreements in volatile markets. |
| Regional Rental Fleet Expansion | Dense yard networks in Texas and Florida capture seasonal construction volatility through rapid relocation capability. |
Research Approach
Direct dialogue with crane fleet operators, plant maintenance directors, OEM procurement teams, and aftermarket service heads grounded qualitative demand assessment. Secondary validation drew from EPA regulatory filings, OSHA certification databases, EIA infrastructure spending disclosures, and SEC equipment manufacturer filings. Bottom-up unit demand triangulation across product type and end-use segments reconciled with top-down macroeconomic indicators.
Bottom-up modeling aggregated deployment data by crane architecture, powertrain technology, and ownership model across the analysis window. Segmentation dimensions included lifting capacity tier, emissions compliance status, and metropolitan versus non-metropolitan deployment geography. CAGRs derived from regression analysis against construction spending indices and federal infrastructure appropriation schedules. Forecast inputs incorporated data center construction pipeline disclosures and petrochemical facility expansion timelines.
Underlying measurement precision varies by segment; rental transaction volume and mobile crane deployment carry tighter precision than emerging electric platform adoption curves. Forecasts reflect assumptions regarding regulatory enforcement consistency and commodity price stability. Practitioners should monitor Infrastructure Investment and Jobs Act disbursement velocity and state-level clean construction rulemaking for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Field Marking Equipment Market
Construction Equipment
Asia Pacific Construction Equipment Market
Construction Equipment
Inflatable Ramps Market
Construction Equipment
Crane Aftermarket Market
Construction Equipment
Welding and Cutting Equipment Market
Construction Equipment
Track Mounted Gangway Market
Construction Equipment
Sweden Construction Equipment Market
Construction Equipment
Industrial Steam Washer Market
Construction Equipment
Plastic Molding Machine Market
Construction Equipment
Concrete NDT Testing Equipment Market
Construction Equipment
Hydraulic Press Machine Market
Construction Equipment
Shot Peening Machine Market
Construction Equipment
Used Construction Equipment Market
Construction Equipment
Static Crane Market
Construction Equipment
Industrial Agitators Market
Construction Equipment
US Welding Consumables Market