
 Portable Loading Ramps Market | 2026-2036
Portable Loading Ramps Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Loading Ramps Market Analytics
Maintenance-service bundling is repositioning how portable loading ramp vendors capture lifetime value from fleet operators. Copperloy leverages its in-house fabrication capabilities to control lead times on custom-capacity orders. Bluff Manufacturing anchors its market presence through a national dealer network serving regional warehouse operators. DOCKZILLA CO. specializes in modular dock-to-ground systems that reduce installation downtime for logistics hubs.
Portable loading ramps are mobile inclined surfaces engineered to bridge height differentials between loading docks and transport vehicles, typically fabricated from aluminum or steel alloys with serrated tread surfaces achieving coefficients of friction above 0.6 for wet-condition traction. These devices enable safe material transfer in facilities lacking permanent dock infrastructure, with rated capacities spanning from light-duty consumer applications to industrial loads exceeding 10,000 pounds. Heavy-duty steel ramps command the largest revenue share among product types due to their durability in construction environments, while aluminum variants represent the fastest-expanding material category as operators prioritize corrosion resistance and manual repositionability. The 1501-2500 lbs weight capacity tier captures concentrated margin pools from mid-size logistics fleets seeking versatile equipment across mixed vehicle heights.
OSHA General Industry Standards and ANSI MH30.1 specifications govern ramp slope maximums, guardrail requirements, and load-testing protocols for workplace deployment in the United States. The Department of Transportation's Federal Motor Carrier Safety Administration indirectly shapes demand through hours-of-service regulations that pressure dock efficiency and turnaround speed. Stakeholders must monitor evolving state-level warehouse safety enforcement intensity as California and Texas expand inspector staffing for material handling equipment compliance audits.
Market Dynamics
OSHA workplace safety mandates and ANSI MH30.1 specifications are tightening compliance requirements for material handling equipment, forcing fleet operators toward certified ramp configurations and documented load-testing protocols.
Growth Catalysts
- E-commerce logistics expansion:Online retail fulfillment networks are scaling last-mile delivery infrastructure, driving replacement cycles for portable loading equipment across regional distribution hubs.
- ANSI MH30.1 specifications:Updated load-testing protocols and guardrail requirements are compelling facilities to upgrade non-compliant legacy ramps, creating pull-through demand for certified replacements.
- Aluminum alloy adoption:Corrosion-resistant materials with manual repositionability are capturing preference from mid-size logistics fleets seeking versatile equipment across mixed vehicle heights.
Market Restraints
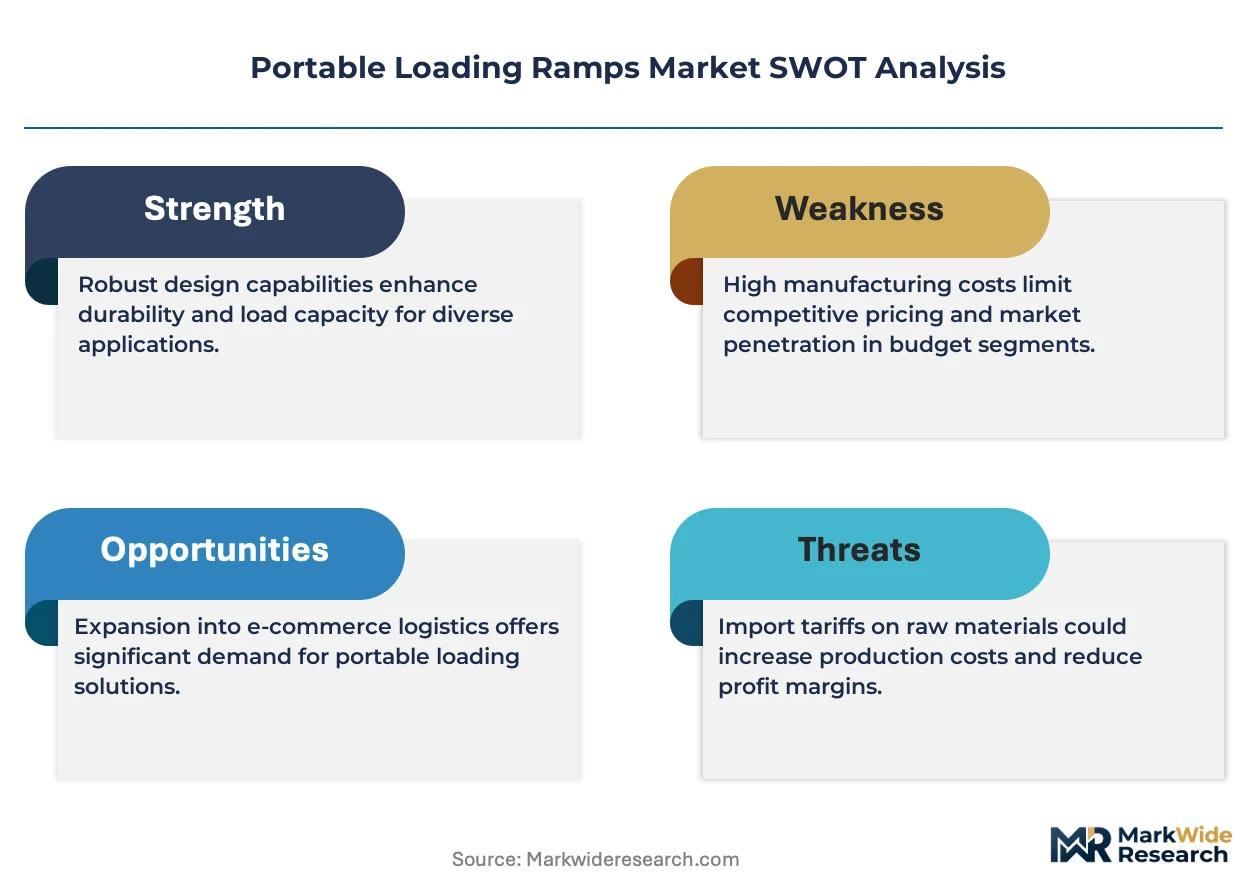
- Steel price volatility:Input cost swings for heavy-duty steel alloys compress margins on industrial-grade ramp fabrication, particularly affecting construction-environment deployments.
- Fabrication capacity concentration:In-house production capabilities for custom-capacity orders cluster among a limited supplier base, extending lead times during demand surges.
- Permanent dock infrastructure substitution:Warehouse automation investments in fixed loading systems reduce addressable market for portable alternatives in greenfield facilities.
Strategic Opportunities
- Modular dock-to-ground systems:Logistics hubs are prioritizing installation-speed solutions that minimize operational downtime during equipment deployment.
- Maintenance-service bundling:Lifetime value capture through scheduled inspection contracts and certified repair networks creates recurring revenue streams beyond initial equipment sales.
- State-level enforcement expansion:California and Texas are augmenting inspector staffing for material handling equipment compliance audits, accelerating replacement demand.
Industry Challenges
- Welding certification scarcity:Qualified aluminum and steel fabrication technicians are in short supply, constraining production scale-up for custom-capacity orders.
- Multi-standard compliance complexity:Facilities operating across state lines must reconcile varying interpretations of OSHA General Industry Standards with local amendments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Loading Ramps Market |
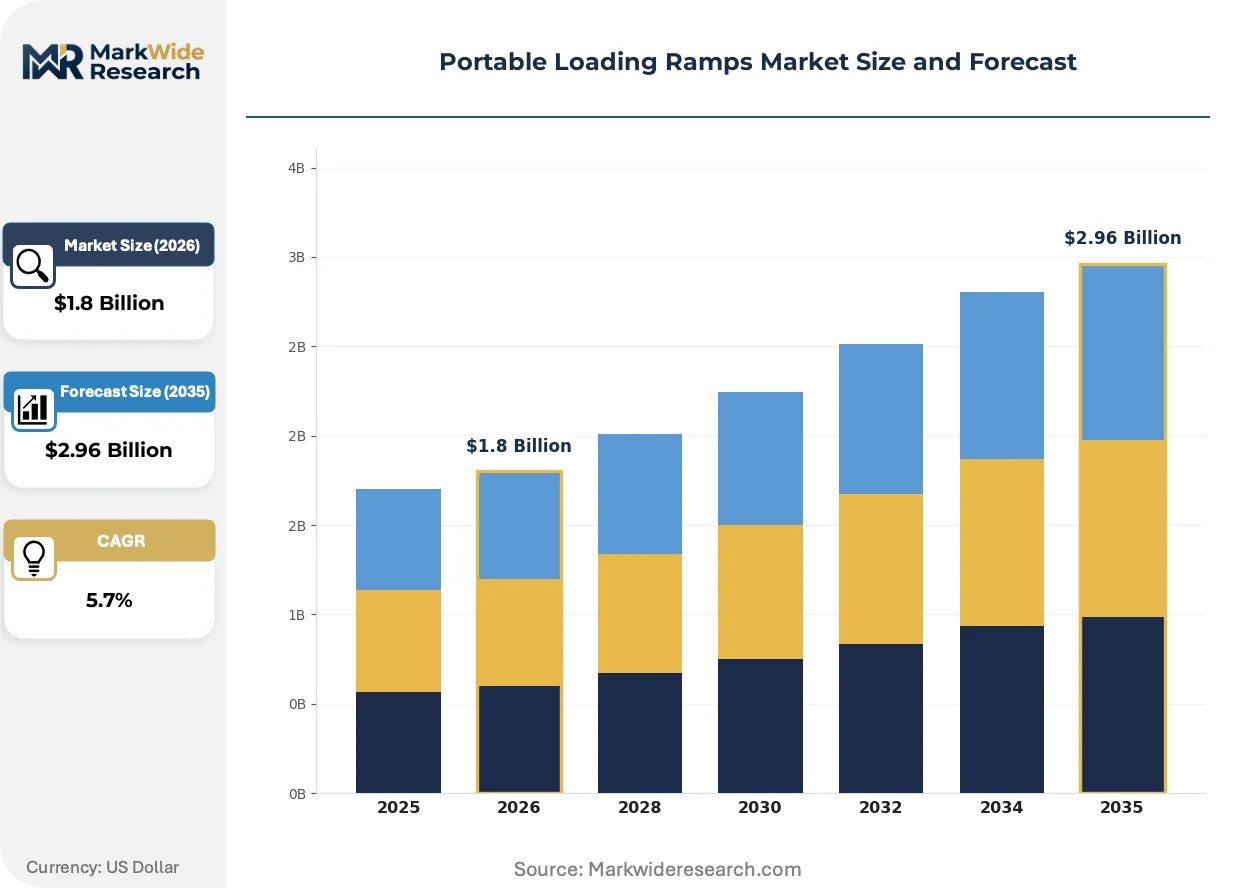
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foldable Ramps,Bi-Fold Ramps,Tri-Fold Ramps,Heavy-Duty Ramps Material: Aluminum,Steel,Plastic,Composite End User: Construction Industry,Warehouse Operators,Logistics Companies,Delivery Services Weight Capacity: Up to 750 lbs,751-1500 lbs,1501-2500 lbs,Over 2500 lbs |
| Companies Covered | Bluff Manufacturing, Dura-Ramp, Handi-Ramp, Vestil Manufacturing Corporation, Copperloy, Marshall Industrial Inc., DOCKZILLA CO., Discount Ramps, Quality Material Handling, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Loading Ramps Market Evolving Landscape
Material substitution and regulatory harmonization are compressing product lifecycles while reshaping how fleet operators evaluate total cost of ownership for portable loading infrastructure.
Advanced aluminum-magnesium alloys are absorbing market share from traditional steel fabrication in corrosive environments. Food processing and cold-chain logistics operators are specifying these materials for washdown compatibility and manual repositionability. This substitution is absorbing margin pressure from steel price volatility while enabling lighter-duty fleet configurations.
OSHA General Industry Standards are harmonizing with state-level warehouse safety amendments, creating unified compliance baselines. The Department of Transportation's Federal Motor Carrier Safety Administration hours-of-service regulations are amplifying dock efficiency pressures. Heavy-duty steel ramp categories face accelerated inspection cycles as enforcement intensity rises in high-volume logistics corridors.
Fleet operators are consolidating vendor relationships around national service networks. Regional warehouse operators previously sourcing through fragmented dealer channels are migrating toward direct manufacturer partnerships with embedded maintenance contracts. This concentration is most visible in the United States, where multi-site logistics operators prioritize standardized equipment configurations across state boundaries.
Portable Loading Ramps Market Segmentation
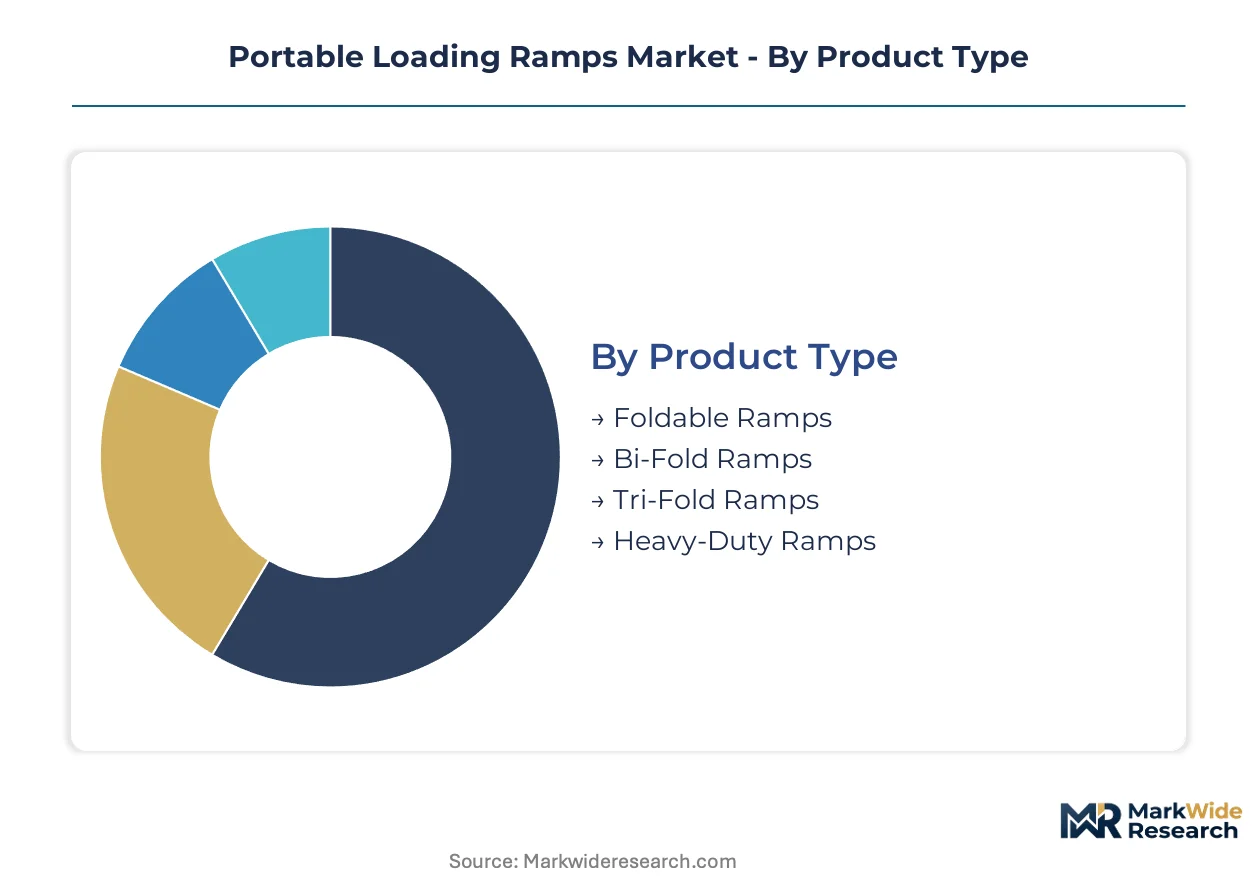
Portable loading ramp procurement decisions pivot on load specifications, deployment frequency, and environmental exposure. Fleet operators balance upfront capital outlays against lifecycle maintenance burdens when selecting across material grades and capacity tiers.
Product Type:
Application intensity and storage constraints drive product type selection, with operators matching fold geometry to vehicle access patterns and warehouse footprints.
- Heavy-Duty Ramps:Fabricated from structural steel with reinforced side rails and serrated tread surfaces rated for industrial loads exceeding 10,000 pounds. Construction contractors in Texas and California specify these for equipment loading onto flatbeds, compelled by state-level OSHA enforcement intensity and documented load-testing protocols.
- Foldable Ramps:Hinged aluminum platforms collapse to compact dimensions for fleet vehicles with limited cargo space. Last-mile delivery operators across the United States favor these for mixed vehicle heights, prioritizing manual repositionability over fixed installations.
- Bi-Fold Ramps:Two-section hinges enable mid-length folding for moderate-load applications.
- Tri-Fold Ramps:Three-section compression delivers the smallest stowed footprint for consumer and light commercial use.
Heavy-Duty Ramps lead on scale; Foldable Ramps lead on momentum.
Material:
Corrosion exposure and manual handling requirements split procurement between weight-optimized and durability-focused specifications.
- Aluminum:Advanced aluminum-magnesium alloys deliver corrosion resistance and manual repositionability for washdown environments. Food processing and cold-chain logistics operators in the United States are specifying these materials, displacing steel in corrosive deployment contexts.
- Steel:Heavy-duty steel alloys command the largest revenue share due to durability in construction environments. Fabrication capacity for custom-capacity orders concentrates among limited suppliers, extending lead times during demand surges.
- Plastic:Molded polymer construction serves light-duty consumer applications with minimal load requirements.
- Composite:Fiber-reinforced materials blend weight reduction with structural rigidity for specialized industrial applications.
Steel dominates current revenue; aluminum is expanding most quickly.
End User:
Operational scale and compliance exposure differentiate procurement patterns across user categories.
- Logistics Companies:Multi-site operators consolidate vendor relationships around national service networks with embedded maintenance contracts. These fleets prioritize standardized equipment configurations across state boundaries to simplify OSHA compliance documentation.
- Warehouse Operators:Regional distribution hubs drive replacement cycles for portable loading equipment as e-commerce fulfillment networks scale. ANSI MH30.1 specification updates compel upgrades from non-compliant legacy ramps.
- Construction Industry:Heavy equipment loading demands steel fabrication with reinforced capacity ratings.
- Delivery Services:Last-mile operators specify lightweight aluminum variants for frequent repositioning across mixed vehicle fleets.
Logistics Companies lead on scale; Warehouse Operators lead on momentum.
Weight Capacity:
Fleet composition and cargo diversity determine capacity tier selection, with mid-range specifications capturing versatile deployment economics.
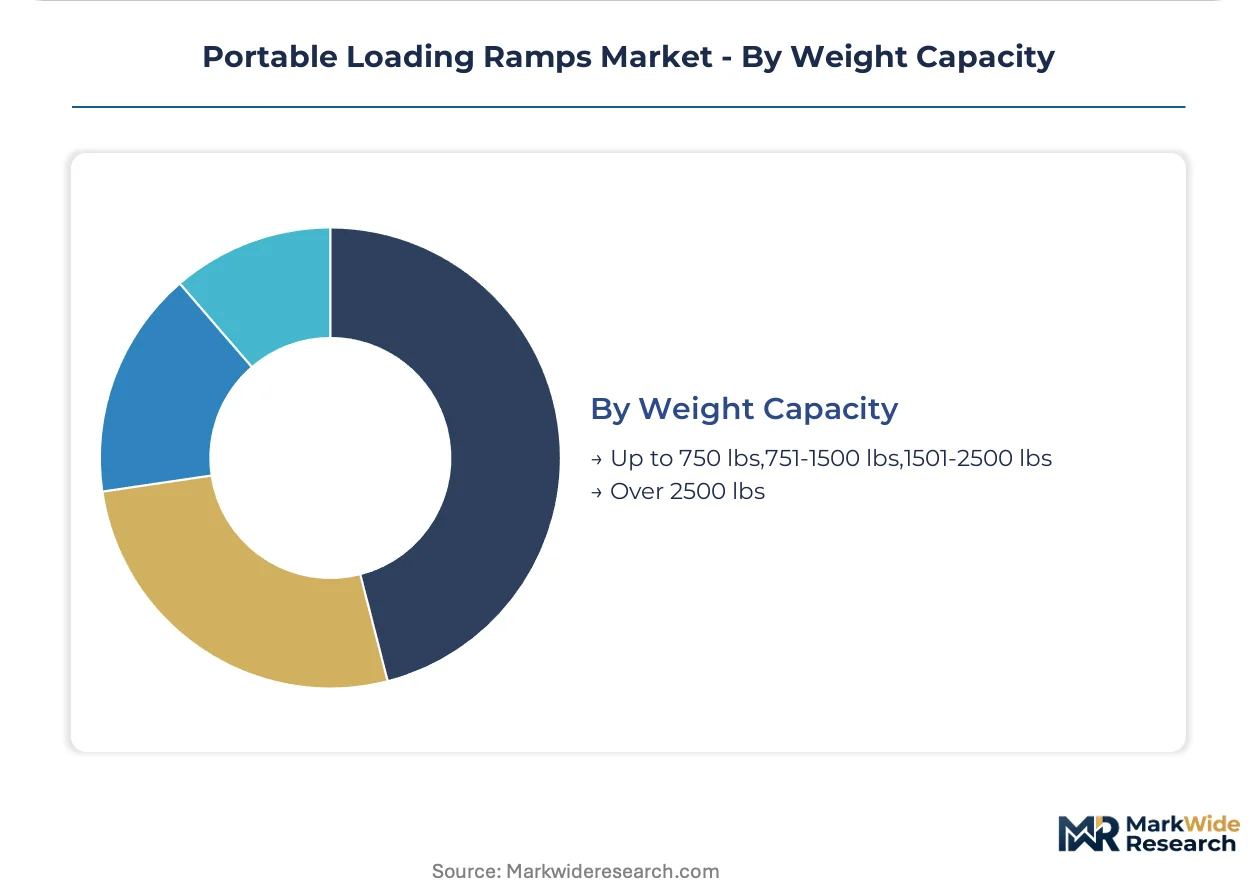
- 1501-2500 lbs:This tier concentrates margin pools from mid-size logistics fleets seeking versatile equipment across mixed vehicle heights. Regional warehouse operators in the United States specify these capacities for standard pallet loads and light machinery.
- Over 2500 lbs:Industrial-grade configurations serve construction equipment and heavy machinery loading. Steel price volatility compresses margins on these fabrications, particularly affecting construction-environment deployments.
- Up to 750 lbs:Consumer and light commercial applications including recreational vehicle and mobility equipment access.
- 751-1500 lbs:Light commercial fleets and small delivery operators utilize these for standard package handling.
1501-2500 lbs leads on scale; Over 2500 lbs leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States demand for portable loading ramps outpaces Canadian procurement volumes by a factor of nearly five to one, reflecting divergent warehouse automation trajectories and enforcement intensities across North American logistics corridors.
United States
E-commerce fulfillment networks and last-mile delivery infrastructure drive replacement cycles for portable loading equipment. OSHA General Industry Standards and ANSI MH30.1 specifications mandate documented load-testing protocols and guardrail requirements. Texas and California logistics hubs concentrate procurement activity as state-level warehouse safety enforcement expands inspector staffing for material handling equipment compliance audits.
Germany
Industrial machinery exports and automotive component logistics sustain demand for heavy-duty steel ramp configurations. CE marking requirements and EU machinery directives govern workplace deployment standards for mobile loading equipment. The Ruhr industrial corridor and Bavarian manufacturing clusters anchor fabrication capacity for custom-capacity orders serving mixed vehicle fleet operators.
China
Domestic e-commerce platform expansion and cross-border logistics infrastructure construction accelerate aluminum alloy ramp adoption. GB standards issued by SAMR establish structural safety baselines for material handling equipment in warehouse environments. Yangtze River Delta distribution hubs prioritize corrosion-resistant materials for high-humidity deployment contexts in Shanghai and surrounding port cities.
Japan
Compact warehouse footprints and automated storage system integration favor foldable aluminum ramp configurations for space-constrained facilities. METI industrial safety guidelines and JIS standards regulate slope maximums and load ratings for mobile loading infrastructure. The Kanto region around Tokyo concentrates procurement from third-party logistics operators serving dense urban delivery networks.
India
Rapid warehouse construction for organized retail and pharmaceutical cold-chain expansion drives initial equipment procurement across tier-1 and tier-2 cities. BIS certification requirements for material handling equipment are tightening import standards and domestic fabrication quality benchmarks. Maharashtra and Karnataka industrial zones concentrate demand from emerging logistics parks serving Mumbai and Bangalore metropolitan distribution networks.
Portable Loading Ramps Market Competitive Landscape
Top-tier vendors anchor national service networks with embedded maintenance contracts, while mid-tier fabricators compete on custom-capacity lead times and regional dealer coverage. The vendor base clusters around three strategic archetypes: integrated manufacturers controlling in-house fabrication, modular system specialists prioritizing installation speed, and maintenance-service bundlers capturing lifetime value through inspection contracts. Dominant competitive moves include geographic expansion through dealer network density and backward integration into aluminum and steel alloy supply chains.
Within the integrated manufacturing tier, Copperloy and Bluff Manufacturing exemplify contrasting approaches to market presence. Copperloy anchors its position through captive fabrication capabilities that compress lead times on non-standard capacity orders. Bluff Manufacturing occupies a position defined by national dealer network coverage serving regional warehouse operators across multiple state jurisdictions. DOCKZILLA CO. represents the modular system specialist archetype, with its company name signaling concentration on dock-to-ground configurations that minimize operational downtime during equipment deployment.
| Leading Market Players |
|---|
| Bluff Manufacturing |
| Dura-Ramp |
| Handi-Ramp |
| Vestil Manufacturing Corporation |
| Copperloy |
| Marshall Industrial Inc. |
| DOCKZILLA CO. |
| Discount Ramps |
| Quality Material Handling |
| Others |
Value Network & Pricing Analysis
Aluminum-magnesium alloy adoption across mid-size logistics fleets is compressing fabrication cost curves while redistributing supplier power toward mills with captive smelting capacity. This material transition simultaneously erodes steel-dependent fabricators' pricing leverage and rewards operators controlling upstream alloy supply.
Pricing Analysis
Capacity additions in China and domestic U.S. aluminum rolling mills are reshaping price floors for corrosion-resistant ramp configurations. Three-tier pricing structure across premium certified, standard ANSI-compliant, and economy non-certified levels separates fleet operators by compliance exposure. Cost compression in heavy-duty steel categories is intensifying because of volatile scrap and alloy input markets. Regional warehouse operators exhibit highest price sensitivity, while multi-site logistics companies prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Domestic-content mandates in U.S. federal procurement and India's PLI scheme for material handling equipment are reshaping sourcing patterns for public-sector and export-bound orders. Fabrication capacity clusters in the United States, China, and Germany, with each hub serving distinct regulatory certification requirements. Production draws from structural steel billets, aluminum-magnesium alloy sheet, and serrated tread surfacing materials. Single-source vulnerability concentrates in specialized welding certification labor pools. Distribution runs through national dealer networks for regional coverage and direct manufacturer partnerships for large fleet accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in maintenance-service bundling and aluminum alloy premium tiers, as fleet operators shift procurement evaluation from upfront capital outlays toward lifecycle cost optimization.
For Market Incumbents: Cement national service network density before state-level OSHA enforcement expansion accelerates replacement demand. Backward integration into aluminum alloy supply chains secures margin capture from material substitution trends. Threat from modular dock-to-ground specialists demands response through embedded inspection contract offerings. Certification investment in ANSI MH30.1 testing protocols creates differentiation against non-compliant imports. For New Entrants and Emerging Players: Regional dealer networks represent the most penetrable channel structure for mid-size logistics fleet access. White-space exists in cold-chain logistics aluminum configurations for food processing operators seeking washdown compatibility. Secondary opportunities concentrate in Texas and California state-level compliance audit acceleration. Go-to-market execution should anchor on maintenance-service bundling to capture recurring revenue streams beyond equipment sales. For Investors and Strategic Acquirers: Roll-up economics work for regional fabricators with captive welding certification programs because compliance documentation requirements are consolidating procurement around certified suppliers. Five-to-ten year viability hinges on aluminum alloy processing capabilities and national service network scale. Acquisition targets should demonstrate embedded maintenance contract penetration above fleet-average levels. Signal to watch is state-level inspector staffing announcements in high-volume logistics corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Alloy Supply | Captive smelting partnerships with Chinese and U.S. mills secure margin protection from price volatility. |
| Maintenance-Service Bundling Expansion | Scheduled inspection contracts with ANSI-certified technicians create recurring revenue from fleet operators. |
| Modular Dock-to-Ground System Development | Installation-speed solutions reduce operational downtime for logistics hubs during equipment deployment. |
| Welding Certification Program Investment | Qualified aluminum and steel fabrication technicians constrain competitor scale-up for custom-capacity orders. |
| State-Level Compliance Audit Positioning | California and Texas inspector staffing expansion accelerates certified replacement ramp demand. |
Research Methodology
Multiple input streams — fleet operator procurement interviews, OEM fabrication facility assessments, and aftermarket service provider consultations — were reconciled against trade data and regulatory filing analysis. Primary fieldwork engaged maintenance directors at regional distribution hubs, plant engineers at aluminum and steel fabrication facilities, and national dealer network managers. Secondary validation drew from OSHA enforcement records, ANSI standards documentation, U.S. Census trade data, and state-level warehouse safety audit reports. Bottom-up equipment shipment tallies and top-down logistics infrastructure investment flows were cross-referenced for triangulation.
Historical capacity utilization patterns were cross-referenced against industry panel input on replacement cycle timing and fleet expansion intentions. Segmentation modeling spanned material grade, weight capacity tier, fold geometry, and end-user operational scale. CAGRs were derived from shipment volume trajectories and average selling price movements across the analysis window. Forecast inputs included e-commerce fulfillment network buildout schedules and state-level enforcement staffing projections.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to steel price volatility and aluminum alloy availability. Projections reflect assumptions on OSHA enforcement intensity trajectories and ANSI specification adoption timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Japan Conveyor Belt Market
Material Handling Equipment
Dewatering Screen Market
Material Handling Equipment
Pharmaceutical Material Handling Equipment Market
Material Handling Equipment
US and Mexico Metal Stamping Market
Material Handling Equipment
Latin America Conveyors Market
Material Handling Equipment
Global Lifting Columns Market
Material Handling Equipment
Rail Mounted Gantry Crane Market
Material Handling Equipment
Enclosed Belt Conveyors Market
Material Handling Equipment
Manual Lifting Light Tower Market
Material Handling Equipment
Pick and Carry (PNC) Crane Market
Material Handling Equipment
Vibrating Conveyor Market
Material Handling Equipment
Cam and Groove Fittings Market
Material Handling Equipment
Asia-Pacific Forklift Rental Market
Material Handling Equipment
Rubber Tyre Gantry Crane Market
Material Handling Equipment
Floor Scrubber Machine Market
Material Handling Equipment
Global Rolling Mill Rolls Market