
 US Rental Equipment Market | 2026-2036
US Rental Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
US Rental Equipment Market Outlook
Steel-reinforced composite booms is consolidating market share against traditional aluminum lift structures in access equipment fleets. United Rentals leverages its national branch density to sustain same-day availability across metropolitan construction corridors. Sunbelt Rentals anchors its southeastern footprint with climate-resistant fleet configurations. Herc Rentals differentiates through telematics-integrated fleet management systems that track utilization rates in real time.
US rental equipment encompasses machinery and tools leased temporarily to commercial and industrial users, with hydraulic systems rated from 1,500 to 5,000 PSI and diesel or electric power trains governed by EPA Tier 4 Final emissions thresholds. Construction Equipment commands the largest revenue pool due to high unit values and replacement cycles tied to infrastructure project timelines. Material Handling is expanding fastest as e-commerce fulfillment centers and warehousing developers seek flexible forklift and conveyor capacity without capital commitment. Short-Term Rental generates premium margins during seasonal demand spikes, while Long-Term Rental contracts stabilize fleet utilization for multi-year infrastructure engagements.
OSHA mandates fall protection and operator certification standards that elevate compliance costs for rental providers maintaining aerial work platforms. EPA Tier 4 Final and emerging CARB zero-emission rules for off-road equipment are accelerating electric fleet conversions in California and neighboring states. The Department of Transportation infrastructure funding mechanisms are channeling equipment demand toward bridge and highway rehabilitation segments. Stakeholders must weigh electrification capital requirements against diesel residual values as regulatory timelines compress.
Market Dynamics
Construction project volatility is compressing equipment ownership cycles and forcing contractors toward rental models that transfer utilization risk to fleet operators. This structural shift intensifies as infrastructure spending concentrates in high-growth metropolitan corridors.
Growth Catalysts
- EPA Tier 4 Final Emissions Standards:Diesel engine compliance costs push smaller contractors away from ownership. Rental providers absorb capital burdens while maintaining compliant fleets.
- E-commerce Fulfillment Expansion:Warehousing developers in California and Texas demand flexible material handling capacity. Short-term forklift and conveyor rentals align with seasonal inventory surges.
- Steel-Reinforced Composite Booms:Lighter access equipment reduces transport costs and extends reach specifications. Fleet operators refresh aerial platform inventories to capture premium rental rates.
Market Restraints
- Steel and Hydraulic Component Volatility:Input price swings compress rental rate margins. Fleet operators delay expansion cycles when commodity indexes spike.
- California CARB Zero-Emission Mandates:Accelerated electrification timelines strand diesel asset values. Rental providers face write-downs on Tier 4 Final equipment before depreciation cycles complete.
- Skilled Operator Certification Bottlenecks:OSHA aerial platform certification requirements limit labor pool depth. Equipment sits idle when qualified operators are unavailable.
Strategic Opportunities
- Texas Infrastructure Corridors:Highway rehabilitation and energy construction create sustained multi-year demand. Long-term rental contracts stabilize fleet utilization in Houston and Dallas-Fort Worth markets.
- Telematics-Integrated Fleet Management:Real-time utilization tracking enables dynamic pricing models. Rental providers optimize asset deployment across metropolitan branch networks.
- Florida Climate-Resistant Configurations:Salt-air corrosion specifications differentiate southeastern fleets. Specialized equipment commands premium rates in coastal construction zones.
Industry Challenges
- Electric Fleet Capital Intensity:Battery-powered equipment requires charging infrastructure investments. Branch locations must retrofit electrical systems to support overnight fleet charging.
- Multi-State Compliance Fragmentation:California CARB rules diverge from federal EPA timelines. Rental providers operating across state lines maintain dual certification inventories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Rental Equipment Market |
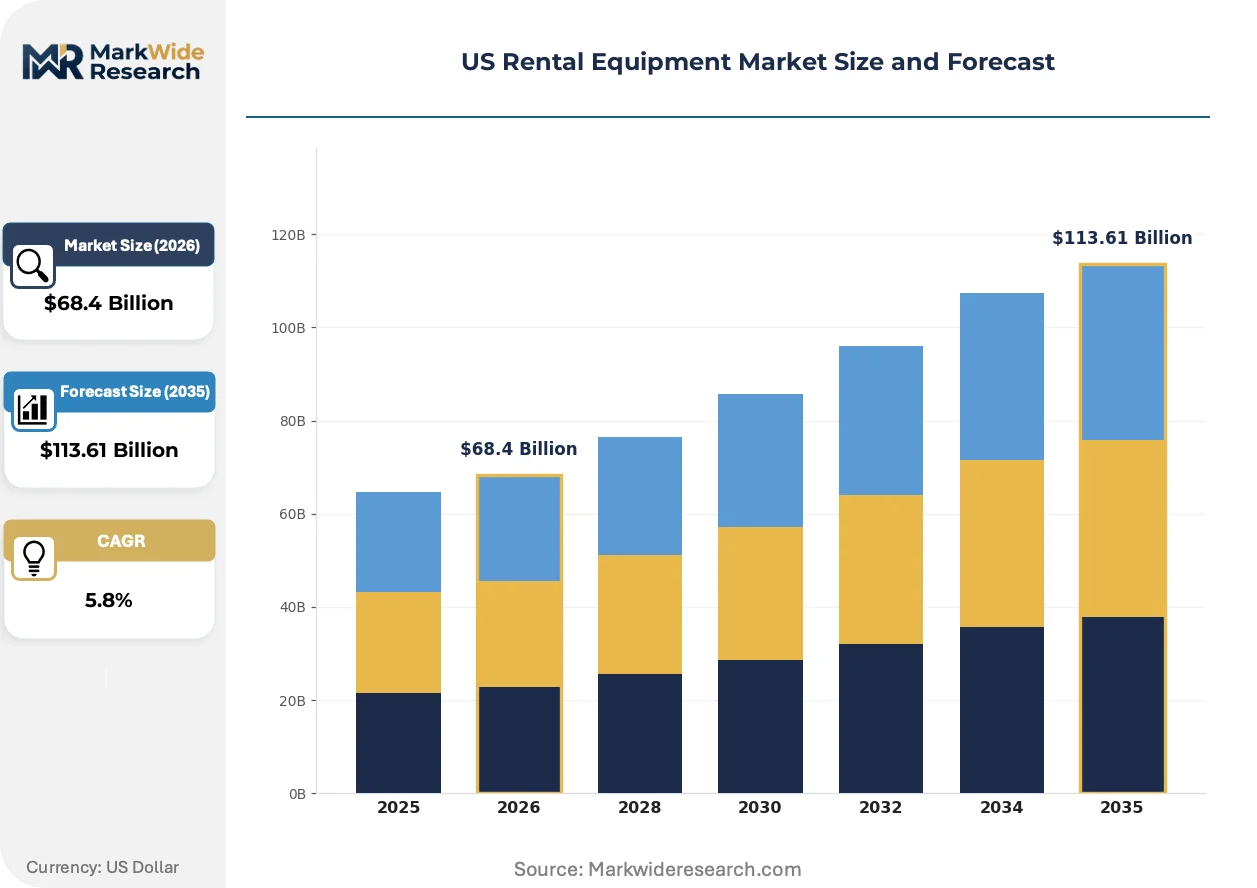
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Construction Equipment, Material Handling, Earthmoving, Access Equipment End User: Construction Firms, Industrial Companies, Event Organizers, Government Agencies Service Type: Short-Term Rental, Long-Term Rental, Lease-to-Own, Equipment Sales Delivery Model: On-Site Delivery, Pickup Services, Drop-Off, Local Warehousing |
| Companies Covered | United Rentals, Sunbelt Rentals, Herc Rentals, H&E Equipment Services, Sunstate Equipment, Neff Rental, Ahern Rentals, Maxim Crane Works, EquipmentShare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Rental Equipment Market Strategic Shifts
Equipment connectivity and powertrain electrification are compressing traditional rental models. Fleet operators now compete on data transparency and emissions compliance rather than asset scale alone.
Telematics platforms embedded in aerial work platforms and earthmoving equipment transmit utilization metrics, fault codes, and geolocation data to rental provider dashboards. Construction contractors in Texas and Florida demand real-time visibility into equipment location and availability. This transparency is rewriting contract structures, with usage-based pricing displacing flat daily rates in competitive metropolitan markets.
OSHA fall protection mandates and EPA Tier 4 Final enforcement tighten simultaneously, elevating compliance documentation requirements. Rental providers must maintain operator certification records, inspection logs, and emissions test results for every unit in service. California's CARB zero-emission trajectory accelerates electric fleet conversions, with Los Angeles and San Francisco construction corridors showing earliest adoption of battery-powered excavators and lifts.
Contractors increasingly unbundle equipment sourcing from maintenance and operator provision. Traditional full-service rental packages fragment into bare equipment leases with separate technician and operator contracts. This unbundling is most pronounced in Florida's commercial development sector, where specialized trades contractors prefer direct control over labor allocation while outsourcing capital-intensive machinery.
US Rental Equipment Market Segmentation
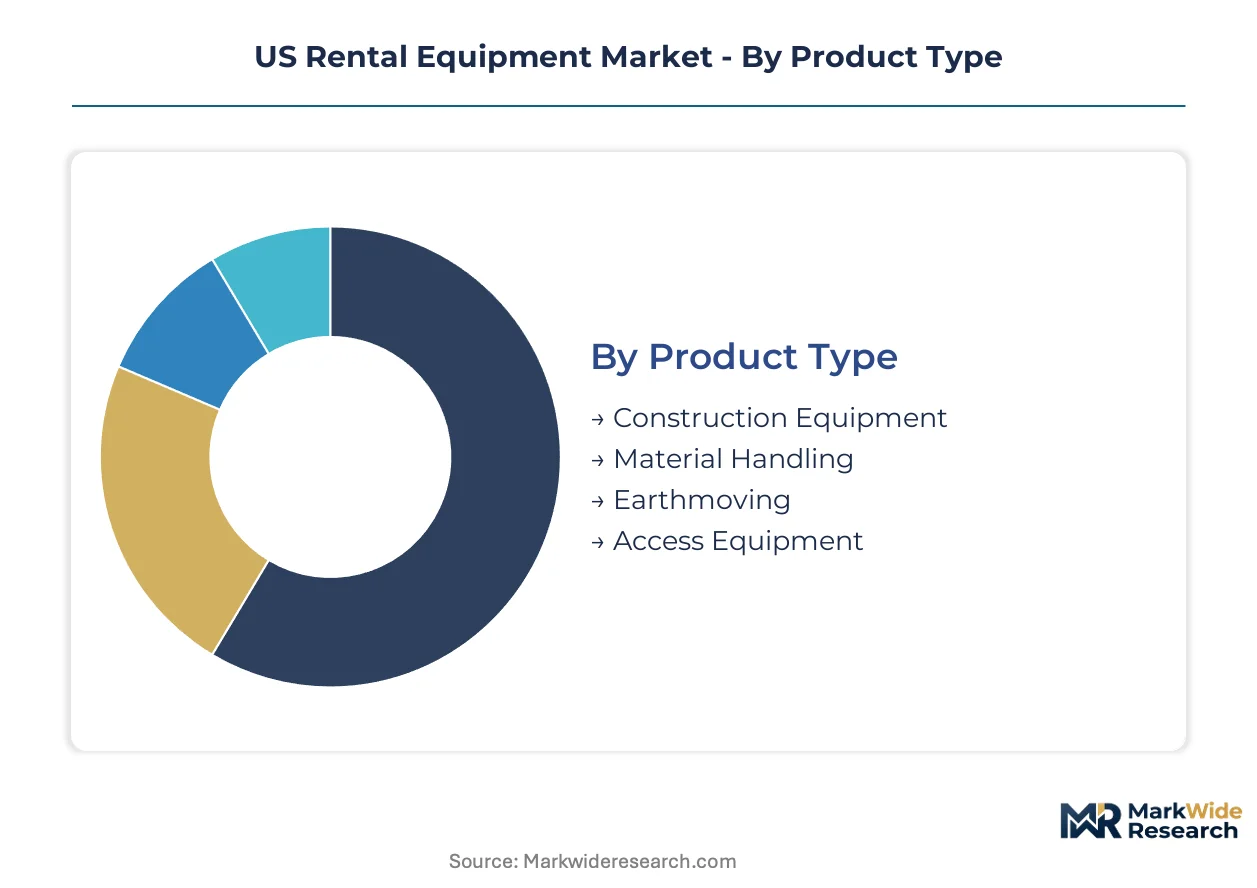
Segmentation in the US rental equipment market reflects how contractors balance capital flexibility against project duration and asset specificity. Fleet operators structure pricing and availability around these decision points, with regulatory compliance costs and utilization transparency reshaping traditional category boundaries.
Product Type:
Capital intensity and replacement cycles drive contractor selection between owned and rented assets across equipment categories.
- Construction Equipment:Heavy machinery including excavators, loaders, and compaction equipment with hydraulic systems rated 3,000–5,000 PSI. Demand concentrates in Texas highway rehabilitation corridors where Department of Transportation funding sustains multi-year project pipelines.
- Material Handling:Forklifts, pallet jacks, and conveyor systems with electric powertrains gaining share under CARB zero-emission mandates. California and Texas warehousing developers deploy these for seasonal e-commerce fulfillment surges without capital commitment.
- Earthmoving:Bulldozers and scrapers governed by EPA Tier 4 Final diesel emissions thresholds.
- Access Equipment:Aerial work platforms with steel-reinforced composite booms displacing aluminum structures in fleet refreshes.
Construction Equipment leads on scale; Material Handling leads on momentum.
End User:
Risk transfer preferences and compliance burden tolerance separate customer groups in contract negotiations.
- Construction Firms:General and specialty contractors facing project volatility compress ownership cycles. These firms dominate rental volume in Florida commercial development zones where climate-resistant fleet specifications command premium rates.
- Industrial Companies:Manufacturing and logistics operators seeking flexible capacity for facility expansions or maintenance turnarounds. Demand clusters in California distribution corridors where OSHA aerial platform certification requirements limit qualified operator availability.
- Event Organizers:Temporary infrastructure providers requiring rapid deployment and removal capabilities.
- Government Agencies:Municipal and federal entities with procurement constraints favoring long-term rental over capital appropriations.
Construction Firms anchor volume concentration; Industrial Companies show steepest expansion trajectory.
Service Type:
Duration and ownership intent determine pricing structures and fleet deployment strategies.
- Short-Term Rental:Daily to monthly contracts capturing premium margins during seasonal demand spikes. Hurricane recovery in Florida and wildfire reconstruction in California generate acute demand for immediate equipment availability.
- Long-Term Rental:Multi-year agreements stabilizing utilization rates for fleet operators. Texas infrastructure corridors sustain these contracts through sustained highway and energy construction activity.
- Lease-to-Own:Structured purchase pathways for contractors testing equipment before capital commitment.
- Equipment Sales:Disposal channel for depreciated fleet assets, increasingly pressured by diesel residual value uncertainty under electrification mandates.
Long-Term Rental provides utilization stability; Short-Term Rental generates margin expansion.
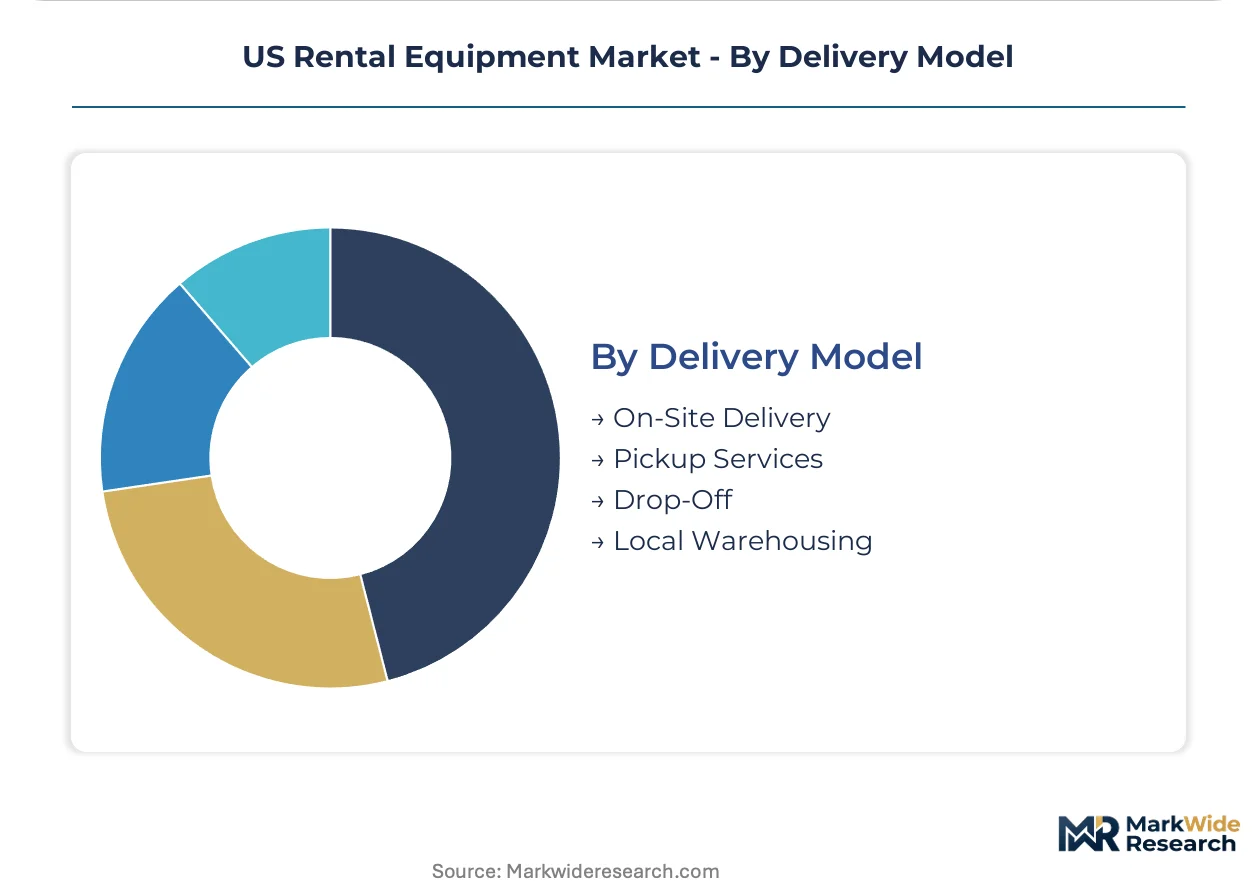
Delivery Model:
Logistics configuration shapes competitive differentiation in metropolitan density corridors.
- On-Site Delivery:Transport to project locations with operator provision. This model dominates Texas and Florida metropolitan construction zones where same-day availability determines contract awards.
- Local Warehousing:Proximity-based inventory positioning enabling rapid pickup. California operators leverage this to minimize transport emissions under CARB compliance tracking.
- Pickup Services:Customer-arranged collection from branch locations.
- Drop-Off:Scheduled return logistics with inspection and maintenance handoff.
On-Site Delivery commands rate premiums; Local Warehousing enables density economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas metropolitan construction corridors anchor equipment rental demand through sustained infrastructure rehabilitation and energy sector expansion. Federal Department of Transportation funding channels multi-year highway projects across Houston and Dallas-Fort Worth, while EPA Tier 4 Final compliance costs concentrate rental adoption among mid-sized contractors.
Texas
Highway rehabilitation and petrochemical construction sustain the nation's densest rental equipment utilization. Department of Transportation infrastructure allocations fund bridge and corridor projects across Houston and Dallas-Fort Worth metropolitan zones. Fleet operators deploy long-term rental contracts to capture stabilized utilization rates through multi-year project timelines.
California
Warehousing developers for e-commerce fulfillment centers drive material handling equipment demand across Inland Empire and Central Valley distribution nodes. CARB zero-emission mandates for off-road equipment accelerate electric forklift and aerial platform conversions ahead of federal EPA timelines. Los Angeles and San Francisco construction corridors show earliest battery-powered excavator adoption.
Florida
Commercial development and hurricane recovery cycles generate acute short-term rental spikes across Miami, Orlando, and Tampa metropolitan areas. Climate-resistant fleet specifications with salt-air corrosion protection command premium rates in coastal construction zones. OSHA aerial platform certification requirements limit qualified operator availability during peak demand periods.
Southeast
Georgia and Carolinas manufacturing reshoring initiatives expand industrial facility construction requiring flexible material handling capacity. Sunbelt Rentals anchors southeastern branch density with rapid-deployment configurations for commercial and industrial end users. Atlanta and Charlotte logistics corridors concentrate forklift rental demand from third-party fulfillment operators.
Midwest
Illinois and Ohio infrastructure maintenance backlogs sustain earthmoving and compaction equipment rentals across Chicago and Cleveland metropolitan networks. Seasonal freeze-thaw cycles compress construction windows and intensify short-term rental utilization during viable work periods. Fleet operators balance diesel asset residual values against electrification capital requirements.
US Rental Equipment Market Competitive Environment
Capacity expansion dominates the current landscape as national operators extend branch density to capture same-day availability premiums. The market structures around three tiers: national fleet networks with metropolitan coverage, regional specialists with climate or sector configurations, and technology-integrated platforms competing on utilization transparency. Strategic archetypes include scale-driven national coverage, geography-specialized fleet positioning, and telematics-enabled dynamic pricing. M&A consolidation and electric fleet conversion accelerate competitive differentiation.
Among national-scale operators, United Rentals and Sunbelt Rentals exemplify branch-density strategies, while Herc Rentals occupies a position within the telematics-integrated tier. United Rentals leverages metropolitan corridor positioning for same-day availability. Sunbelt Rentals anchors southeastern markets with climate-adapted configurations. Herc Rentals represents real-time utilization tracking as a competitive vector. Regional specialists including H&E Equipment Services and Sunstate Equipment concentrate geographic presence against national coverage models. EquipmentShare and similar technology-forward platforms compete on data transparency rather than asset scale alone.
| Leading Market Players |
|---|
| United Rentals |
| Sunbelt Rentals |
| Herc Rentals |
| H&E Equipment Services |
| Sunstate Equipment |
| Neff Rental |
| Ahern Rentals |
| Maxim Crane Works |
| EquipmentShare |
| Others |
Value Chain & Pricing Dynamics
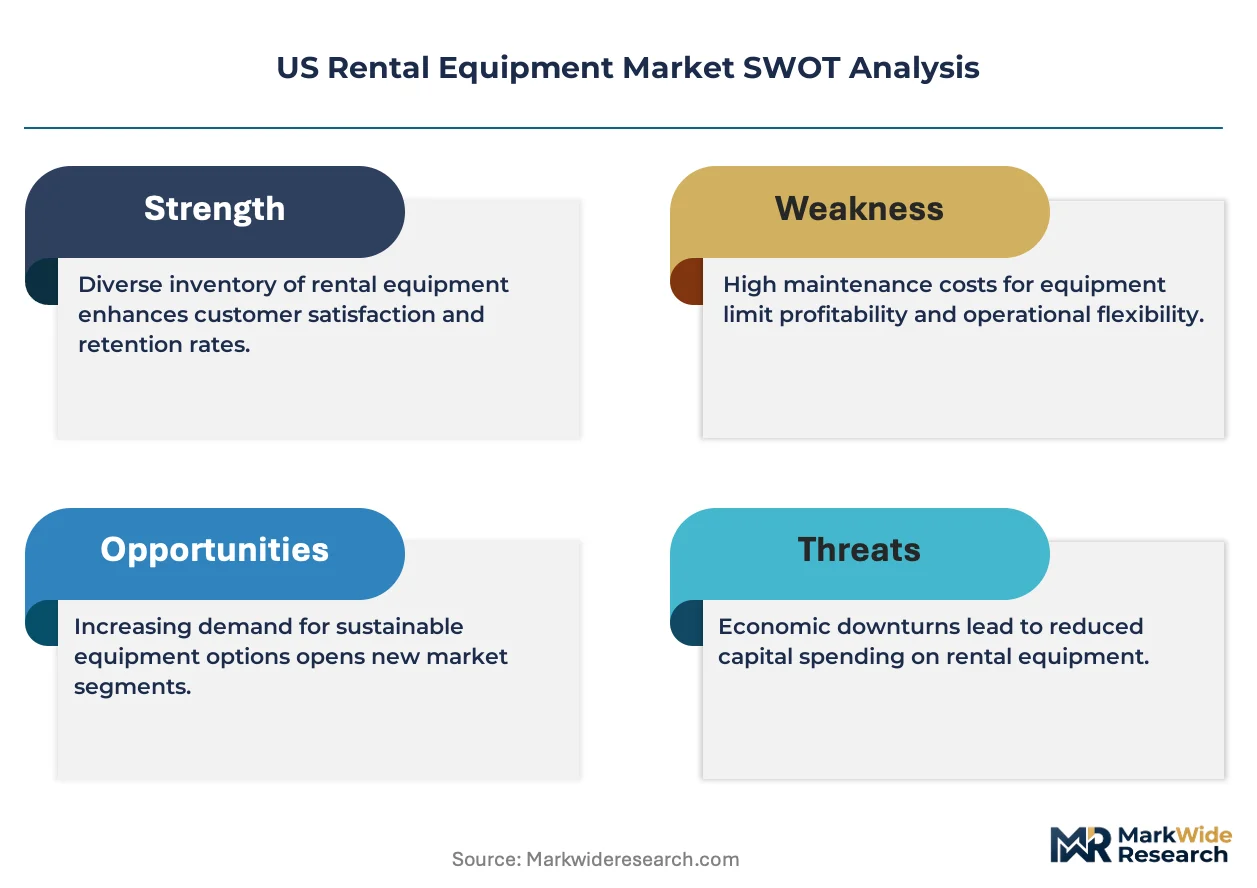
Steel and hydraulic component volatility cascades through rental rate structures as fleet operators absorb commodity index spikes or pass them downstream to contractors. Input cost pass-through mechanisms differentiate pricing tiers, with premium fleet configurations insulating margins while standard equipment segments absorb compression.
Pricing Analysis
Input-cost pass-through operates through daily rate adjustments tied to steel futures and hydraulic fluid indexes. Three-tier pricing structure across premium, standard, and economy levels separates climate-resistant fleet specifications from baseline configurations. Price differentiation centers on telematics integration and CARB compliance certification. Margins are tightening due to electrification capital requirements and stranded diesel asset risks. Small contractors in the Midwest show highest price sensitivity, while Texas infrastructure developers prioritize availability over rate negotiations.
Supply Chain Analysis
Single-source vulnerability sits with Japanese hydraulic component manufacturers and Chinese steel suppliers for boom fabrication. Manufacturing concentration in Mexico and South Korea feeds assembly operations in Texas and California. Raw material dependencies include high-strength steel plate, hydraulic cylinders, and EPA-certified diesel engines. Tariff exposure on Chinese steel inputs threatens margin stability for fleet refresh cycles. Distribution runs through metropolitan branch networks with same-day delivery guarantees commanding rate premiums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in US rental equipment rests on telematics-enabled utilization optimization and premium-tier fleet differentiation that captures compliance-driven contractor demand.
For Market Incumbents: To counter electric fleet conversion costs and CARB regulatory compression, national operators should deepen backward integration into battery charging infrastructure and acquire regional specialists in Texas and Florida corridors. Priority levers include climate-resistant fleet certification and telematics platform standardization across branch networks. For New Entrants and Emerging Players: Telematics-first asset-light platforms offer entry points into underserved metropolitan construction zones. White-space targets include mid-sized contractors in Georgia and Carolinas manufacturing reshoring corridors and specialized access equipment for hurricane recovery cycles. Go-to-market positioning should emphasize real-time availability transparency over asset scale. For Investors and Strategic Acquirers: Roll-up economics work for regional fleet operators with dense metropolitan branch networks because infrastructure spending concentration creates localized moats. Long-term viability favors platforms with electrification-ready infrastructure and multi-state compliance capabilities. Acquisition targets should demonstrate sustained utilization rates above industry medians. The signal to watch is CARB zero-emission mandate acceleration in neighboring states beyond California.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Conversion | Battery-powered equipment captures CARB-compliant demand in California construction corridors. |
| Telematics Platform Integration | Real-time utilization data enables dynamic pricing and same-day availability guarantees. |
| Climate-Resistant Fleet Certification | Salt-air corrosion specifications command premium rates in Florida coastal zones. |
| Metropolitan Branch Density Expansion | Proximity positioning captures infrastructure project volatility in Texas and California. |
| Operator Certification Programs | OSHA-compliant training pools reduce equipment idle time during peak demand periods. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged fleet operations directors, construction procurement managers, OSHA compliance officers, and telematics platform engineers across Texas, California, and Florida markets. Secondary validation drew from EPA enforcement databases, Department of Transportation infrastructure allocation records, CARB regulatory filings, and equipment utilization benchmarks. Bottom-up branch-level capacity estimates triangulated against top-down market size reconstructions.
Comparable-period anchoring linked forward projections to historical utilization cycles and fleet refresh patterns across the analysis window. Segmentation dimensions modeled include equipment category, powertrain architecture, contract duration tier, and metropolitan density cluster. CAGRs derived from regression-weighted equipment deployment trajectories. Industry-specific inputs incorporated infrastructure spending authorization timelines and electrification capital cost curves.
The model holds under sustained infrastructure funding and gradual regulatory phase-in; deviation in accelerated CARB mandates or steel tariff escalation would shift fleet conversion economics. Forecasts reflect documented assumptions about contractor risk-transfer preferences and equipment residual value curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Global Cone Crusher Market
Construction Equipment
Drone-Based Solutions in Construction Market
Construction Equipment
Garage Equipment Market
Construction Equipment
Pressure Vessel Market
Construction Equipment
Global Welding Market
Construction Equipment
Earthmoving Equipment Market
Construction Equipment
South Korea Heavy Construction Equipment Rental Market
Construction Equipment
Rotary Dryers Market
Construction Equipment
Laser Cladding Equipment Market
Construction Equipment
Welding and Cutting Equipment Market
Construction Equipment
Global Dragline Excavator Market
Construction Equipment
Global Construction Dumper Market
Construction Equipment
Shot Peening Machine Market
Construction Equipment
Concrete Grinder Market
Construction Equipment
Track Laying Equipment Market
Construction Equipment
Refurbished Construction Equipment Market