
 Line Boring Machine Market | 2026-2036
Line Boring Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Line Boring Machine Market Outlook
Modular product bundling is pivoting how buyers evaluate line boring systems, with suppliers now packaging portable units with digital alignment kits and training modules rather than selling bare machines. DMG MORI leverages its integrated automation portfolio to anchor premium positioning in stationary systems. Doosan Machine Tools sustains manufacturing scale advantages across heavy-duty configurations. Climax Portable Machining specializes in compact, field-deployable units that dominate offshore and remote maintenance segments.
A line boring machine is a precision metalworking device that enlarges or finishes existing holes in large structural components, typically achieving bore tolerances within 0.001 inches using single-point cutting tools rotated on a horizontal or vertical axis. Its primary purpose is restoring dimensional accuracy to worn bearing housings, cylinder bores, and pin bores in heavy machinery frames that cannot be transported to fixed machining centers. Portable units command the fastest-growing demand pool as on-site repair eliminates disassembly and transport costs for mining and construction equipment. Electric technology leads the installed base for indoor manufacturing environments, while hydraulic systems retain dominance in construction and mining applications where power infrastructure is absent. The machinery application segment carries the deepest margin pool due to recurring aftermarket demand from equipment rebuild programs.
FDA oversight of medical device manufacturing indirectly shapes demand for precision boring in orthopedic implant tooling, while OSHA machine guarding standards affect portable unit design for US field crews. ISO 9001 and EU machinery directives enforce traceable calibration protocols that filter out uncertified suppliers across European procurement channels. Stakeholders must monitor how CE marking evolution under the EU machinery regulation affects retrofit eligibility for legacy boring systems imported into European job shops.
Market Dynamics
Modular product bundling is compressing traditional equipment-only sales models as suppliers package portable line boring units with digital alignment systems and certified training modules to capture recurring service revenue.
Growth Catalysts
- EU Machinery Directive compliance mandates:CE marking requirements for portable boring equipment are filtering uncertified suppliers from European procurement channels, concentrating demand among ISO 9001-certified vendors.
- Aerospace engine refurbishment cycles:Precision boring capacity expansion for turbine component restoration is pulling specialized stationary systems into MRO facilities across Germany and France.
- Field-deployable hydraulic technology:Mining and construction equipment operators in remote sites are eliminating transport costs through on-site bore restoration using self-powered portable units.
Market Restraints
- Specialized alloy input volatility:Tool steel and tungsten carbide pricing swings compress margin predictability for cutting tool suppliers serving the aftermarket.
- German supplier concentration:Stuttgart-Munich industrial corridor dominance creates single-source vulnerability for precision spindle components and calibration services.
- Dimensional accuracy ceilings:Current portable unit designs struggle to achieve sub-0.0005 inch tolerances required for semiconductor manufacturing equipment frames.
Strategic Opportunities
- India PLI scheme for heavy machinery:Domestic manufacturing incentives are opening procurement channels for cost-optimized portable boring systems in mining equipment rebuild programs.
- Digital twin convergence with bore measurement:Real-time dimensional feedback loops are enabling predictive maintenance contracts that bundle hardware with continuous calibration services.
- OSHA silica exposure rules:Tighter workplace safety enforcement is accelerating replacement of legacy dry-cutting portable units with enclosed wet-cutting systems in US construction fleets.
Industry Challenges
- Precision metrology skill scarcity:Field technicians capable of operating laser alignment systems alongside portable boring equipment command premium wages and extended recruitment cycles.
- Multi-standard certification timelines:Simultaneous ISO 9001, CE marking, and OSHA compliance pathways stretch product launch schedules for new portable unit introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Line Boring Machine Market |
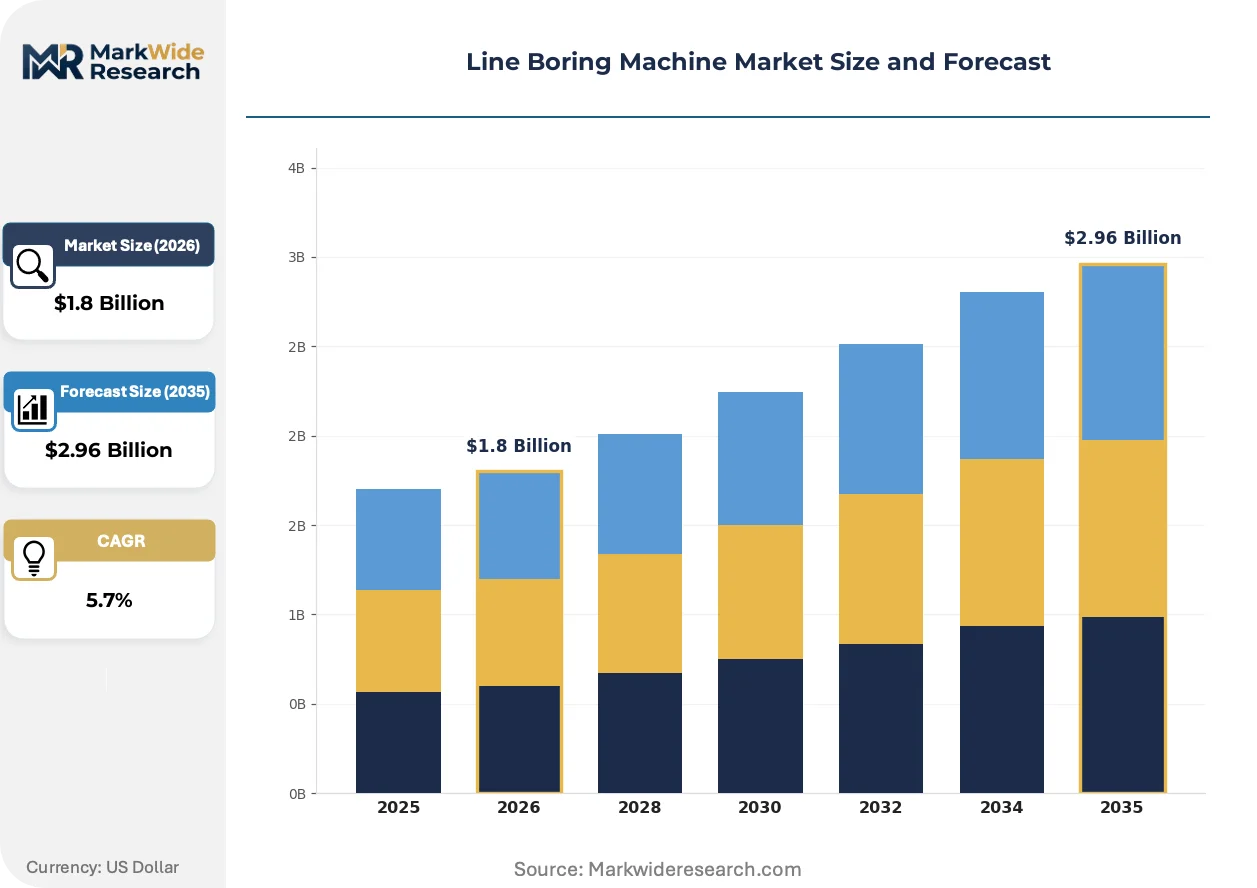
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Stationary, Heavy-Duty, Multi-Function End User: Manufacturing, Construction, Mining, Aerospace Application: Piping, Machinery, Automotive, Equipment Maintenance Technology: Hydraulic, Pneumatic, Electric, Magnetic |
| Companies Covered | DMG MORI, Doosan Machine Tools, Climax Portable Machining, ROMI Lazzati, Fives Group, International Revere Machining, Mazak Corporation, Shanghai Shenji International, Dalian Haidi Machinery Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Line Boring Machine Market Strategic Shifts
Digital integration and regulatory tightening are fundamentally restructuring how line boring equipment is specified, sold, and serviced across industrial end-uses.
Brushless electric spindle technology is electrifying portable line boring applications previously dominated by hydraulic power trains. Underground mining operators in Australia and Canada are adopting battery-electric units to eliminate diesel particulate exposure in confined shafts. The shift is compressing maintenance intervals while enabling real-time torque monitoring through integrated sensor arrays.
REACH substance restrictions on chromium plating are forcing cutting tool suppliers to accelerate tungsten-carbide and ceramic insert development for bore finishing operations. European job shops face retrofit deadlines for legacy equipment with hexavalent chromium components. Tooling manufacturers with pre-certified alternative coatings are capturing specification priority in German automotive rebuild programs.
Buyer preference is hardening around total-cost-of-ownership models that unbundle equipment purchase from per-bore service contracts. Mining contractors in South Africa and Chile are shifting from capital expenditure approvals to operational leasing structures with guaranteed dimensional accuracy clauses. Equipment financiers are responding with residual value guarantees tied to ISO calibration traceability.
Line Boring Machine Market Segmentation
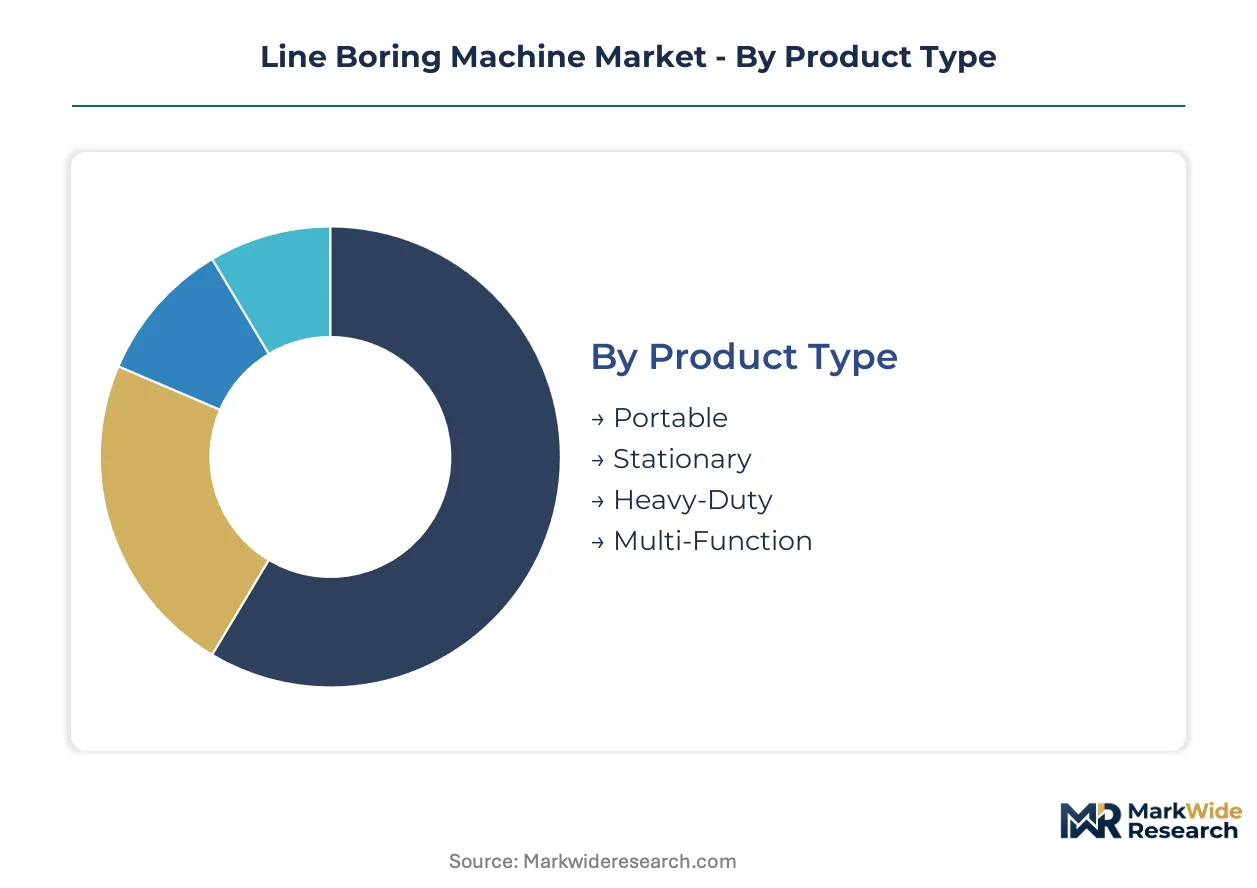
Line boring equipment specification varies sharply across operating environments, from confined underground shafts to climate-controlled aerospace facilities. Procurement decisions hinge on power availability, transport constraints, and dimensional tolerance requirements rather than unit cost alone.
Product Type:
Supply concentration in portable systems is reshaping how manufacturers allocate engineering resources between field-deployable and fixed-installation platforms.
- Portable:Compact, self-contained units mount directly onto workpieces using bolt-hole or clamp fixtures, enabling on-site bore restoration without component disassembly. Mining contractors in Australia and Chile are eliminating transport costs through field-deployable hydraulic and battery-electric configurations.
- Stationary:Fixed-base machines with rigid column-and-bed construction achieve sub-0.001 inch tolerances for turbine component refurbishment. German aerospace MRO facilities in Stuttgart and Munich anchor demand for precision spindle systems with integrated laser alignment.
- Heavy-Duty:Extended-bed machines handle structural frames exceeding 10 meters in length for construction equipment remanufacturing.
- Multi-Function:Modular platforms combine boring, facing, and welding preparation in single setups for offshore platform maintenance.
Today's leader: Portable. Tomorrow's challenger: Multi-Function.
End User:
Customer type determines pricing tolerance and aftermarket attachment rates across replacement part and calibration service streams.
- Mining:Equipment rebuild programs in remote sites drive demand for self-powered portable units with hydraulic or battery-electric power trains. South African and Chilean contractors are shifting from capital expenditure to operational leasing with guaranteed dimensional accuracy clauses.
- Aerospace:Engine component refurbishment cycles require stationary systems achieving turbine blade housing tolerances within 0.0005 inches. French and German MRO facilities are expanding precision boring capacity for narrow-body engine programs.
- Manufacturing:Automotive and heavy machinery OEMs in Germany's industrial corridor cluster procurement around ISO 9001-certified vendors with traceable calibration protocols.
- Construction:Equipment fleets in North America face OSHA silica exposure rule compliance deadlines, accelerating replacement of dry-cutting legacy units with enclosed wet-cutting systems.
Mining commands the steepest expansion trajectory through operational leasing adoption. Aerospace maintains the deepest margin pool via specialized calibration services.
Application:
Volume concentration in machinery maintenance is compressing sales cycles for new equipment versus recurring aftermarket tooling and service contracts.
- Machinery:Bearing housing and pin bore restoration in heavy equipment frames generates recurring demand for cutting tool inserts and spindle rebuild services. German automotive rebuild programs are specifying pre-certified tungsten-carbide tooling to meet REACH substance restrictions on chromium plating.
- Equipment Maintenance:On-site repair contracts for mining and construction fleets bundle portable boring units with per-bore service guarantees and residual value financing tied to ISO calibration traceability.
- Piping:Pipeline flange facing and valve bore finishing in oil and gas infrastructure.
- Automotive:Engine block cylinder boring for remanufacturing operations.
Machinery dominates current procurement volume. Equipment Maintenance is climbing the fastest through outcome-based contracting models.
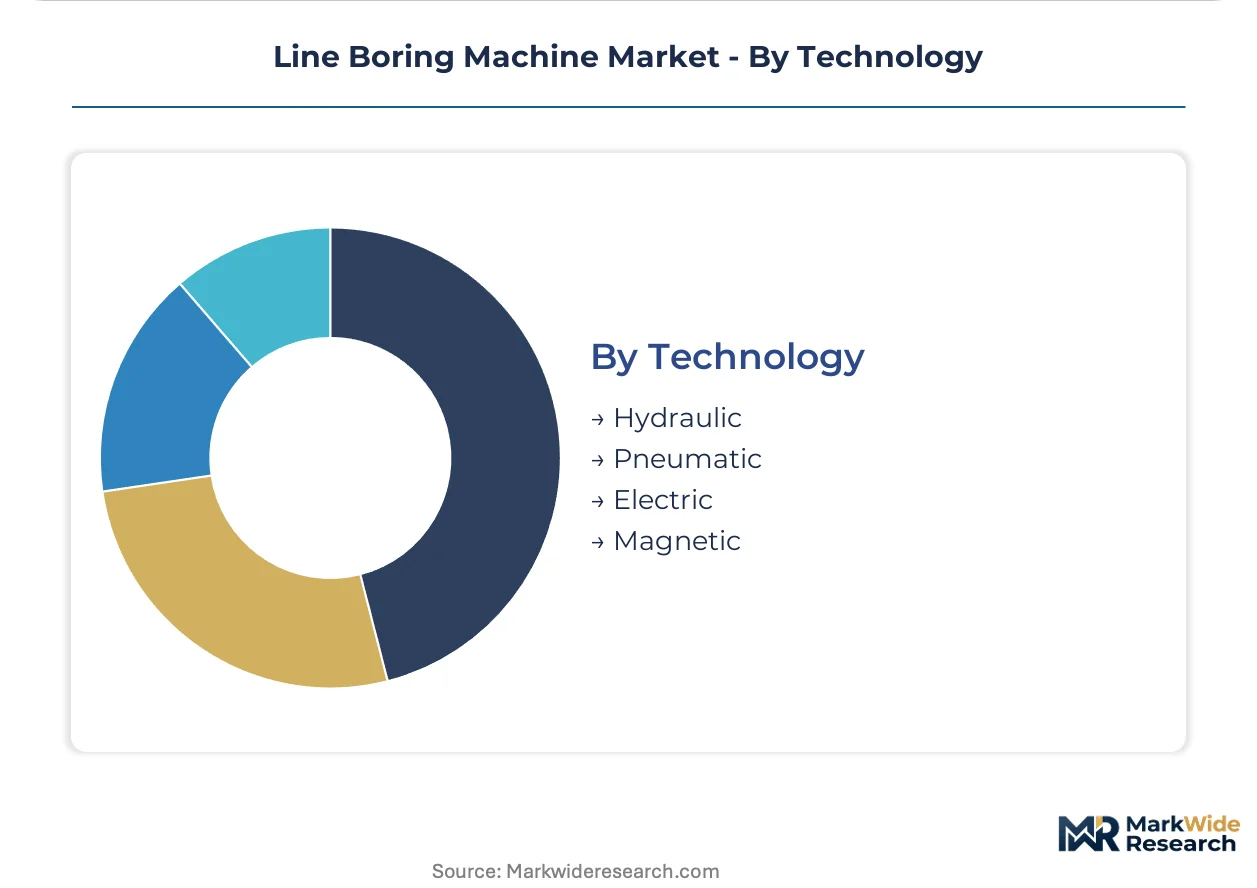
Technology:
Power train selection tracks infrastructure availability and emissions constraints across underground, offshore, and indoor operating environments.
- Electric:Brushless spindle systems with integrated torque monitoring are displacing hydraulic power trains in underground mining applications. Australian operators are adopting battery-electric units to eliminate diesel particulate exposure in confined shafts while compressing maintenance intervals.
- Hydraulic:Self-powered units retain dominance in construction and mining sites lacking grid infrastructure, particularly in remote African and South American operations.
- Pneumatic:Compressed-air systems serve explosive atmospheres in petrochemical maintenance where electrical ignition risks are prohibited.
- Magnetic:Electromagnetic base mounting enables rapid repositioning on ferrous structures for shipboard and offshore platform applications.
Electric is gaining share fastest through battery integration and real-time sensor feedback. Hydraulic defends installed base through infrastructure-independent deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered precision boring equipment during the post-war industrial reconstruction, establishing Stuttgart and Munich as the twin anchors of European machine tool engineering. This historical foundation shaped procurement patterns that now concentrate demand in specific industrial corridors across multiple continents.
Germany
Stuttgart and Munich anchor the densest cluster of automotive and heavy machinery OEMs, driving specification authority for ISO 9001-certified portable boring systems. CE marking requirements under EU machinery directives filter procurement toward vendors with traceable calibration protocols. Baden-Württemberg's precision engineering ecosystem supplies specialized spindle components that German rebuild programs specify exclusively.
United States
OSHA silica exposure enforcement is accelerating fleet replacement of dry-cutting portable units with enclosed wet-cutting systems across construction equipment operators. The Midwest industrial belt concentrates heavy machinery remanufacturing activity that consumes stationary boring capacity for frame restoration. Texas and Louisiana offshore maintenance contractors specify multi-function platforms combining boring with flange facing for platform integrity programs.
China
Domestic mining equipment rebuild programs in Shanxi and Inner Mongolia are absorbing cost-optimized portable boring configurations from state-supported manufacturing zones. MIIT industrial upgrading guidelines are pressuring job shops toward certified equipment that satisfies export market traceability requirements. Yangtze River Delta machinery clusters are developing captive boring capacity to reduce dependence on German spindle imports.
Australia
Underground mining operators in Western Australia and Queensland are adopting battery-electric portable units to eliminate diesel particulate exposure in confined shafts. The country's national workplace safety regulator enforces ventilation standards that favor enclosed cutting systems in subterranean operations. Perth-based equipment lessors are structuring operational contracts with guaranteed dimensional accuracy clauses for remote site deployment.
India
PLI scheme incentives for heavy machinery domestic manufacturing are opening procurement channels for portable boring systems in mining equipment rebuild programs. Maharashtra and Karnataka industrial corridors are attracting component suppliers seeking proximity to OEM assembly operations. Domestic fabricators in Pune and Bangalore are qualifying for ISO certification to access European automotive supply chain specifications.
Line Boring Machine Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification depth and aftermarket service attachment. The vendor base stratifies between integrated automation portfolios, scale-driven manufacturing operations, and compact field-deployable specialists. Three archetypes dominate: diversified machine tool conglomerates with captive boring divisions, pure-play portable equipment fabricators, and regional machinery builders serving cost-sensitive mining markets. Competitive moves concentrate on bundling digital alignment systems with hardware sales and securing residual value financing partnerships for operational leasing structures.
Within the diversified conglomerate tier, DMG MORI and Doosan Machine Tools occupy positions anchoring premium stationary system supply through integrated automation portfolios. Among field-deployable specialists, Climax Portable Machining exemplifies the compact unit archetype serving offshore and remote maintenance segments. Shanghai Shenji International and Dalian Haidi Machinery Co., Ltd represent Chinese fabricators targeting cost-optimized configurations for domestic mining rebuild programs.
| Leading Market Players |
|---|
| DMG MORI |
| Doosan Machine Tools |
| Climax Portable Machining |
| ROMI Lazzati |
| Fives Group |
| International Revere Machining |
| Mazak Corporation |
| Shanghai Shenji International |
| Dalian Haidi Machinery Co., Ltd |
| Others |
Value Chain & Pricing Dynamics
Precision metrology technicians in Germany's Stuttgart-Munich corridor command wage premiums that compress margin spreads between premium ISO 9001-certified systems and economy-grade portable units. Labor-cost differentials between Baden-Württemberg's engineering clusters and emerging manufacturing zones in India and China directly shape three-tier pricing stratification across certification grades.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates equipment procurement, with ISO 9001 certification depth and bundled digital alignment services as primary differentiation drivers. Cost compression in economy tiers intensifies as Chinese fabricators scale battery-electric portable configurations for domestic mining rebuild programs. Mining contractors in South Africa and Chile exhibit highest price sensitivity through operational leasing adoption, while German aerospace MRO facilities show lowest sensitivity due to specialized calibration service dependencies.
Supply Chain Analysis
Workforce availability constraints in Germany's precision engineering corridor and China's Yangtze River Delta machinery clusters concentrate high-grade spindle component supply. Tool steel and tungsten carbide cutting inserts draw from specialized metallurgical suppliers in Japan and Austria. Single-source vulnerability around German spindle manufacturers creates structural risk for European rebuild programs. Distribution runs through OEM-direct channels for stationary systems and equipment lessor networks for field-deployable portable units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential in this market rests on battery-electric technology cost-down curves and premium-tier shift toward outcome-based service contracts with guaranteed dimensional accuracy clauses.
For Market Incumbents: Cement certification moats by accelerating CE marking compliance for legacy portable unit retrofits before EU machinery regulation evolution hardens eligibility windows. Deepen backward integration into tungsten carbide cutting tool production to offset REACH substance restriction impacts on chromium plating alternatives. Defend against Chinese cost-optimized entrants by anchoring premium positioning through captive calibration service networks.
For New Entrants and Emerging Players: Capture operational leasing white space in Australian and Chilean mining markets where guaranteed dimensional accuracy clauses are displacing capital expenditure approvals. India's PLI scheme for heavy machinery domestic manufacturing represents the most penetrable geography for cost-optimized portable boring system introduction. Lead with battery-electric configurations targeting underground ventilation compliance requirements.
For Investors and Strategic Acquirers: Diversified machine tool conglomerates with captive boring divisions are the most active acquirers in this space, seeking field-deployable technology to complement stationary system portfolios. Target acquisition archetype: compact portable specialists with pre-certified tungsten-carbide tooling pipelines and established equipment lessor financing partnerships. Watch battery-electric adoption rates in Australian underground mining as inflection signal for technology displacement timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Electric Product Line Expansion | Australian underground mining ventilation standards favor enclosed cutting systems eliminating diesel particulate exposure. |
| Backward Integration into Cutting Tool Manufacturing | REACH substance restrictions on chromium plating accelerate tungsten-carbide and ceramic insert development pipelines. |
| Operational Leasing Structure Launch | South African and Chilean mining contractors shift from capital expenditure to per-bore service guarantees with residual value financing. |
| Digital Twin Integration with Bore Measurement | Real-time dimensional feedback loops enable predictive maintenance contracts bundling hardware with continuous calibration services. |
| CE Marking Pre-Certification Investment | EU machinery directive evolution filters procurement toward vendors with traceable calibration protocols and retrofit eligibility. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with maintenance directors at mining contractors, plant engineers at German automotive OEMs, aftermarket service heads at heavy machinery rebuild programs, and procurement teams at aerospace MRO facilities with secondary validation against SEC 10-K filings, customs and trade data for machine tool imports, ISO certification registries, and EU machinery directive compliance databases. Bottom-up equipment shipment tracking and top-down end-use demand estimation were triangulated against calibration service revenue disclosures.
Segment-weighting approaches modeled portable, stationary, heavy-duty, and multi-function product categories alongside electric, hydraulic, pneumatic, and magnetic technology splits across mining, aerospace, manufacturing, and construction end-use verticals. CAGRs were derived from equipment replacement cycle analysis and operational leasing adoption curves. Forecast inputs incorporated battery-electric technology cost trajectories and REACH substance restriction compliance timelines.
Raw material input volatility, regulatory certification pathway delays, and workforce skill scarcity are the dominant revision risks that could compress or extend projected expansion trajectories. Forecasts reflect assumptions around technology substitution rates and leasing structure penetration. Material deviation in tungsten carbide pricing, CE marking enforcement intensity, or precision metrology technician availability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
China Construction Equipment Market
Construction Equipment
Solar Pile Driving Equipment Market
Construction Equipment
Truck Mounted Concrete Mixer Market
Construction Equipment
Laser Cladding Systems Market
Construction Equipment
Crane Rail Market
Construction Equipment
Hoist and Winches Market
Construction Equipment
Ceramic Tile Printing Machine Market
Construction Equipment
Case Erectors Market
Construction Equipment
Compact Electric Construction Equipment Market
Construction Equipment
Welding Fume Extraction Equipment Market
Construction Equipment
Cranes Rental Market
Construction Equipment
Inflatable Ramps Market
Construction Equipment
Mobile Elevating Work Platform (MEWP) Market
Construction Equipment
Snow Clearing Vehicles Market
Construction Equipment
Global Light Towers Market
Construction Equipment
Global Construction Industry Core Drill Market