
 North America Crane Rental Market | 2026-2036
North America Crane Rental Market Size, Share, and Industry Trends Forecast 2026-2036
North America Crane Rental Market Outlook
Modular fleet bundling is decoupling crane rentals from standalone equipment contracts across North America. United Rentals leverages its national branch density to anchor multi-project logistics for infrastructure contractors. Maxim Crane Works sustains Gulf Coast market presence through specialized crawler and heavy-lift configurations. Bigge Crane and Rigging Co. differentiates via engineered lifting plans that integrate transportation and rigging services.
North America crane rental encompasses the short-term and long-term provision of mobile and fixed lifting equipment with rated capacities from under 25 tons to over 1,000 tons, typically configured with telescopic booms, lattice structures, or tower mast assemblies for vertical material handling. The primary purpose is to supply construction, energy, and industrial clients with flexible lifting capacity without capital ownership burden. Rough terrain and all terrain mobile cranes dominate rental revenue due to versatility across dispersed job sites, while tower cranes concentrate margin pools in urban high-rise construction. Crawler crane demand is accelerating fastest among energy sector clients, particularly for wind turbine component installation and refinery turnaround projects.
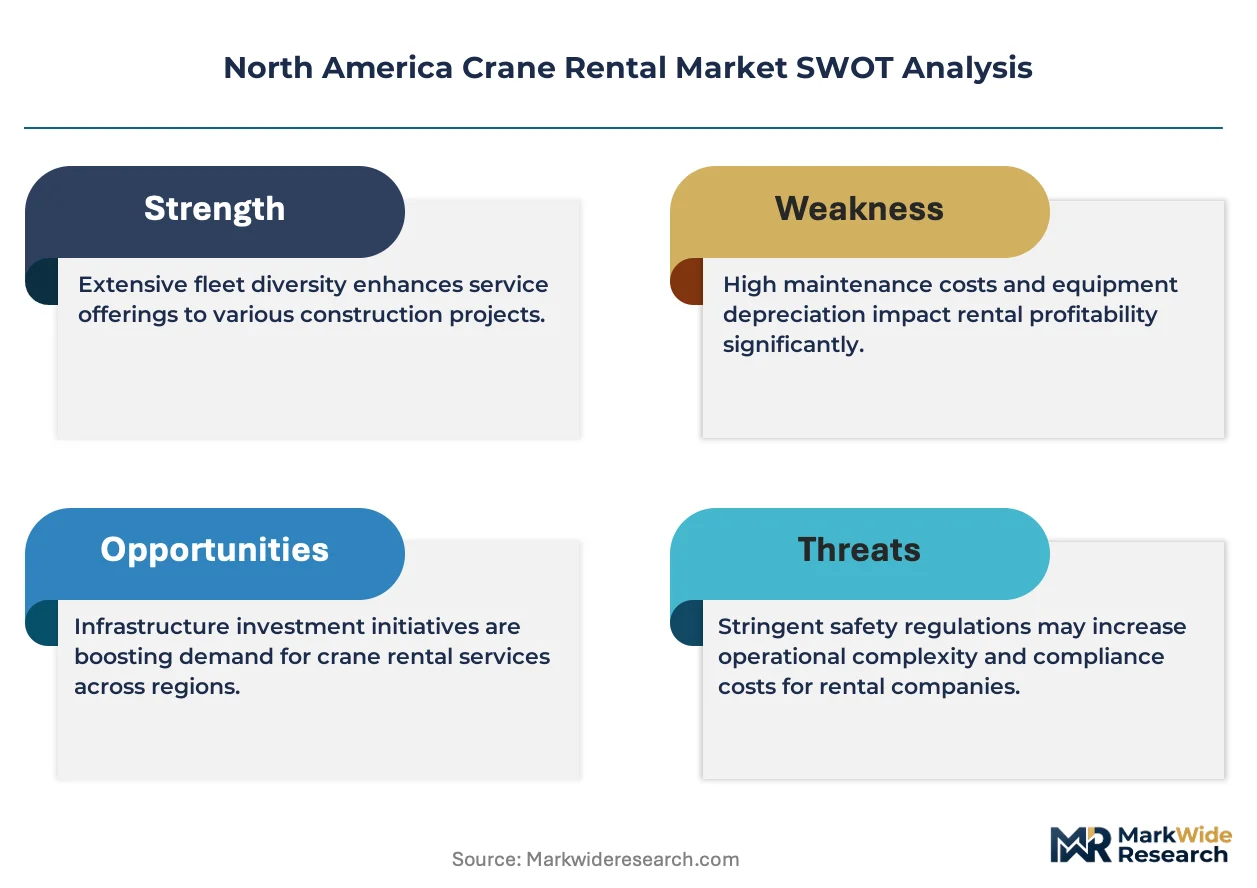
OSHA crane operator certification standards and provincial occupational safety regulations in Ontario and Alberta shape equipment specifications and training service bundling across the market. FCC coordination requirements for telecommunications infrastructure lifts add compliance layers for urban tower crane deployment. Stakeholders must monitor evolving carbon disclosure rules and electrification mandates that could redefine fleet composition and rental pricing structures.
Market Dynamics
Modular fleet bundling is decoupling crane rentals from standalone equipment contracts across North America. United Rentals leverages its national branch density to anchor multi-project logistics for infrastructure contractors. Maxim Crane Works sustains Gulf Coast market presence through specialized crawler and heavy-lift configurations. Bigge Crane and Rigging Co. differentiates via engineered lifting plans that integrate transportation and rigging services.
Growth Catalysts
- Data center construction:Hyperscale facility builds across Texas and Virginia are accelerating crawler crane deployment for cooling tower and generator lifts.
- OSHA certification mandates:Tightened operator qualification standards are expanding training service bundling alongside equipment contracts.
- Petrochemical turnaround cycles:Scheduled maintenance along the Gulf Coast corridor drives peak rental utilization for heavy-lift crawler configurations.
Market Restraints
- Steel price volatility:Fluctuations in high-grade structural steel input costs compress fleet replacement margins for rental providers.
- Specialized operator scarcity:Certified crane operators concentrate in Texas, Louisiana, and Alberta, creating regional supply bottlenecks during peak demand windows.
- Telecom lift coordination:FCC frequency coordination requirements add compliance layers and timeline friction for urban tower crane deployment.
Strategic Opportunities
- Wind turbine installation:Crawler crane demand for nacelle and blade lifts is expanding across the Great Plains and Texas wind corridors.
- Electrification mandates:Provincial carbon disclosure rules in Ontario and Alberta are creating early-mover advantages for hybrid and electric fleet segments.
- Modular logistics integration:Bundling transportation, rigging, and lift planning into single-source contracts opens margin pools beyond equipment rental alone.
Industry Challenges
- Certification timeline compression:OSHA crane operator recertification cycles and provincial lifting standard updates in Ontario strain training infrastructure capacity.
- Fleet reconfiguration capex:Electrification and telematics upgrades demand capital deployment before carbon pricing mechanisms mature.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Crane Rental Market |
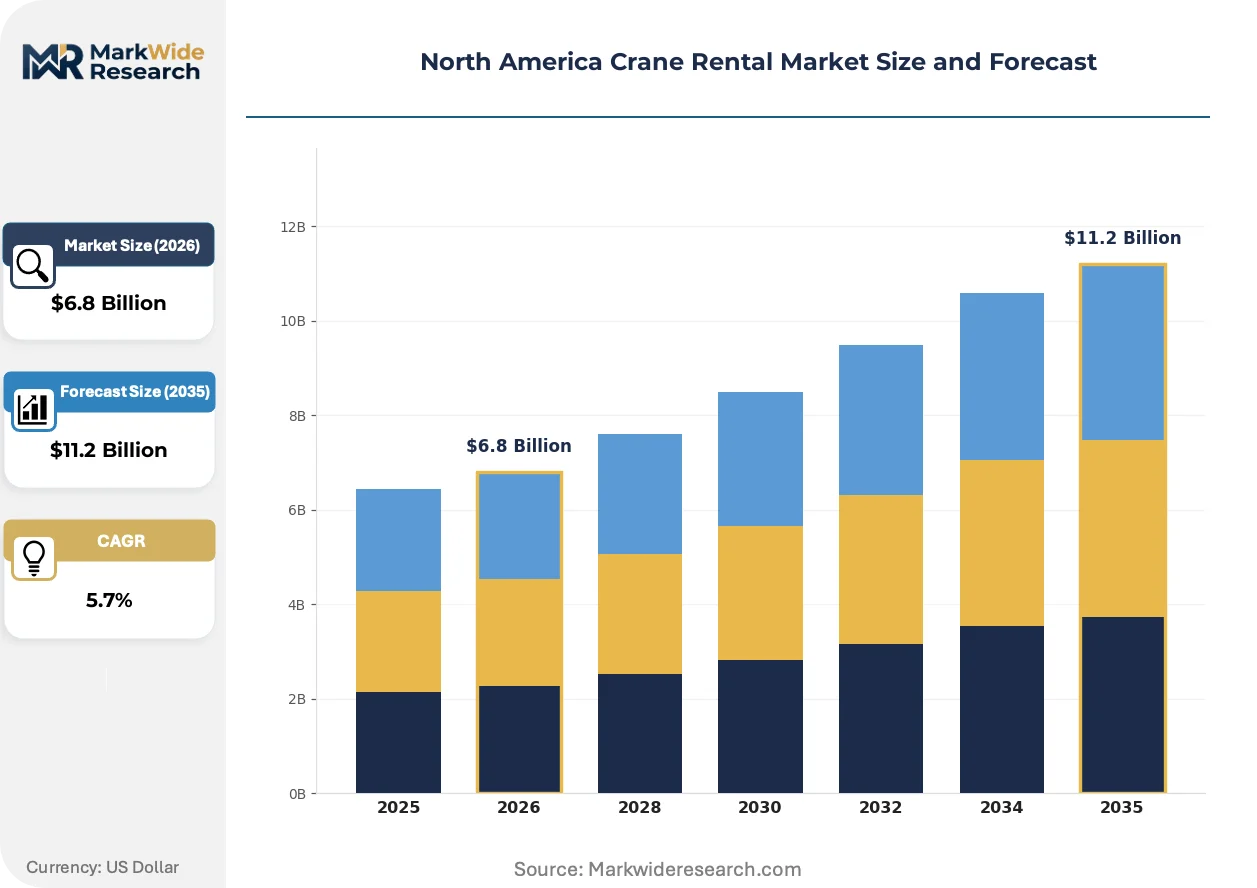
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rough Terrain, All Terrain, Tower, Crawler End User: Construction, Shipping, Energy, Telecommunications Deployment: On-site, Off-site, Leasing, Long-term Service Type: Inspection, Maintenance, Operator Training, Transportation |
| Companies Covered | United Rentals, Maxim Crane Works, ALL Erection & Crane Rental Corp., Sunbelt Rentals, Herc Rentals, Bigge Crane and Rigging Co., H&E Equipment Services, AmQuip Crane Rental, Buckner HeavyLift Cranes, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Crane Rental Market Strategic Shifts
Telematics-enabled fleet management is absorbing operational decision-making from site supervisors to centralized logistics platforms. Rental providers now capture utilization data, maintenance triggers, and operator performance metrics in real time.
Telematics integration is absorbing traditional dispatch and maintenance scheduling functions into predictive algorithms. Major infrastructure contractors across Texas and Virginia are adopting platform-managed crane allocation. This compression of operational layers is absorbing margin from manual coordination into software-enabled fleet optimization.
OSHA crane operator certification standards are tightening practical examination requirements and recertification frequency. The industrial consequence is expanded training service bundling and extended onboarding timelines for new operators. Energy sector clients in the Gulf Coast petrochemical corridor are responding by locking multi-year operator commitments into rental contracts.
Project bundling is consolidating discrete equipment rentals into single-source logistics contracts. Infrastructure contractors are displacing standalone crane rentals with integrated lift-planning and transportation packages. This shift is most visible in data center construction across Northern Virginia and wind farm development throughout the Great Plains.
North America Crane Rental Market Segmentation
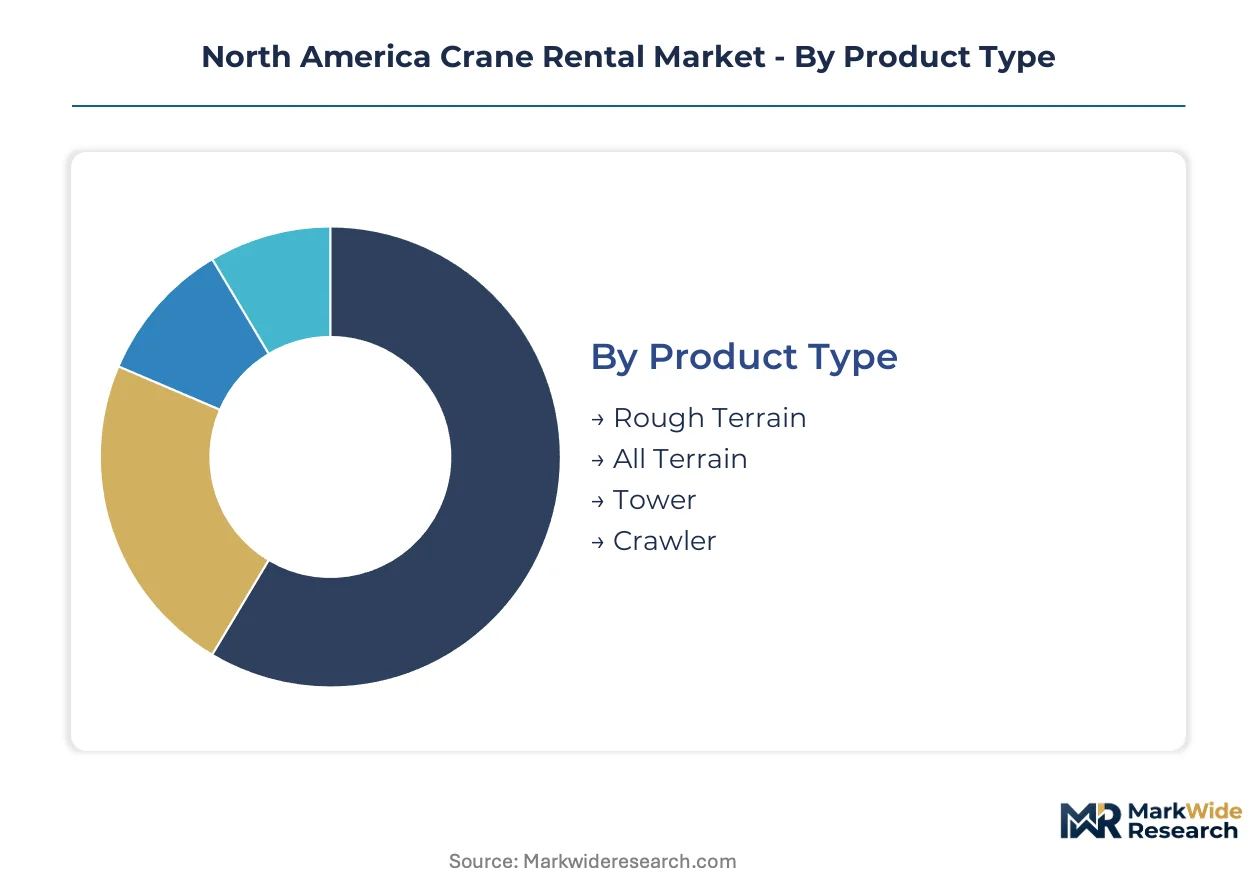
Crane rental segmentation in North America reflects divergent capital intensity and mobility requirements across energy infrastructure, urban construction, and industrial logistics. Equipment configuration and service bundling decisions hinge on project duration, site access constraints, and regulatory compliance burdens.
Product Type:
Rough terrain and all terrain units anchor standardized rental portfolios, while crawler and tower configurations demand deeper customization around lift engineering and site preparation.
- Rough Terrain:Compact outrigger-based designs with four-wheel drive and crab-steering capability navigate unpaved construction sites across Texas and Alberta. Demand concentrates in petrochemical turnaround projects along the Gulf Coast, where rapid mobilization between process units compresses rental windows and rewards fleet proximity.
- All Terrain:Highway-legal carrier configurations with multi-axle suspensions combine on-road transit speed with off-road lifting capacity. Data center construction in Northern Virginia and Dallas-Fort Worth drives deployment for cooling tower and electrical substation lifts, where roadability between dispersed building pads reduces transport costs.
- Tower:Fixed mast assemblies with climbing mechanisms serve vertical construction in dense urban cores.
- Crawler:Tracked undercarriages distribute heavy loads across soft ground conditions for wind turbine component installation.
Most installed capacity flows through rough terrain and all terrain segments. Expansion is steepest in crawler configurations.
End User:
Customer archetypes span asset-light project contractors to capital-intensive owner-operators, with procurement sophistication varying sharply across construction, energy, and telecommunications verticals.
- Construction:General and specialty contractors source mobile cranes for commercial, industrial, and residential verticals, with rental duration averaging days to months. OSHA certification mandates and provincial safety standards in Ontario shape operator qualification requirements and training service attachment rates.
- Energy:Refinery operators and wind farm developers lock multi-year crawler commitments for scheduled turnarounds and turbine installation campaigns. FCC coordination requirements for telecom infrastructure lifts add compliance layers for urban tower crane deployment in this segment's distributed generation assets.
- Shipping:Port authorities and intermodal terminals lease heavy-lift capacity for container handling and vessel loading.
- Telecommunications:Tower companies and wireless carriers rent specialized units for antenna installation and network densification.
Construction channels the highest rental transaction volume. Energy exhibits the steepest contract value escalation.
Deployment:
Duration and location flexibility define procurement economics, with short-term mobility premiums contrasting against long-term site anchoring efficiencies.
- On-site:Equipment remains dedicated to single project locations for continuous operational availability. Petrochemical turnarounds along the Gulf Coast corridor drive peak utilization, where crane standby costs during process unit shutdowns justify dedicated fleet placement.
- Off-site:Yard-based staging with transport to multiple job sites optimizes fleet turns across dispersed contractor portfolios. United Rentals leverages national branch density to anchor multi-project logistics for infrastructure contractors seeking rapid equipment repositioning.
- Leasing:Medium-term contracts with purchase options serve capital-constrained contractors.
- Long-term:Multi-year agreements with embedded maintenance and operator provisions lock capacity for recurring industrial campaigns.
On-site deployment captures the majority of revenue ton-miles. Off-site models are expanding most quickly in data center construction.
Service Type:
Ancillary revenue streams separate equipment-only providers from integrated lifting solution vendors, with compliance-driven services commanding premium attachment.
- Inspection:Pre-lift structural assessments and periodic compliance verification satisfy OSHA and provincial occupational safety requirements. Ontario and Alberta regulators mandate documented inspection protocols for tower crane deployment in urban construction zones.
- Maintenance:Scheduled service intervals and breakdown response minimize downtime penalties in critical path construction schedules. Telematics-enabled fleet management absorbs operational decision-making from site supervisors to centralized logistics platforms, triggering predictive maintenance dispatch.
- Operator Training:Certification preparation and recertification programs address specialized operator scarcity in Texas, Louisiana, and Alberta.
- Transportation:Heavy-haul permitting and route planning integrate with lift engineering for crawler and tower configurations.
Inspection and maintenance services generate the highest attachment rates. Operator training is climbing the fastest as OSHA tightens practical examination requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Crane rental operations in North America trace their modern scale to post-war infrastructure buildouts across the United States and Canada, with the Gulf Coast petrochemical corridor establishing the continent's first heavy-lift rental density.
United States
Data center construction across Northern Virginia and Dallas-Fort Worth accelerates all-terrain crane deployment for cooling tower installation. OSHA crane operator certification standards mandate practical examination recertification every five years, compressing available labor pools during peak construction windows. The Texas Gulf Coast petrochemical corridor sustains the continent's highest crawler crane utilization rates through scheduled turnaround maintenance cycles.
Canada
Wind turbine installation campaigns across Ontario and Alberta drive specialized crawler crane demand for nacelle and blade lifts. Provincial occupational safety regulators in Ontario enforce documented inspection protocols for tower crane deployment in urban construction zones. The oil sands extraction region around Fort McMurray anchors heavy-lift rental commitments for modular facility construction and maintenance.
Mexico
Nearshoring manufacturing expansion across Nuevo León and Baja California generates rough terrain crane demand for industrial facility construction. Mexican federal labor law aligns with North American trade agreement provisions on equipment safety standards, though enforcement capacity varies by state. The Mexico City metropolitan area concentrates tower crane deployment for commercial high-rise development and transit infrastructure expansion.
North America Crane Rental Market Competitive Environment
Premium-margin players sit above commodity-margin players across service bundling depth, with integrated logistics providers commanding rate premiums over equipment-only rental houses. The North American market exhibits tiered consolidation, where national branch networks coexist with regional specialists anchored in specific industrial corridors. Three archetypes dominate: scale-driven multi-service platforms, Gulf Coast heavy-lift specialists, and engineered-lift solution providers. Competitive dynamics center on fleet telematics integration and multi-project logistics contracts that lock contractor relationships across sequential infrastructure builds.
Within the national platform tier, United Rentals exemplifies branch-density scale, while Maxim Crane Works occupies a position as a Gulf Coast heavy-lift specialist. Bigge Crane and Rigging Co. anchors the engineered-solutions archetype through integrated transportation and rigging service bundling.
| Leading Market Players |
|---|
| United Rentals |
| Maxim Crane Works |
| ALL Erection & Crane Rental Corp. |
| Sunbelt Rentals |
| Herc Rentals |
| Bigge Crane and Rigging Co. |
| H&E Equipment Services |
| AmQuip Crane Rental |
| Buckner HeavyLift Cranes |
| Others |
Value Chain & Pricing Dynamics
High-grade structural steel price indices cascade through crane rental supply chains into three-tier pricing stratification across premium, standard, and economy fleet segments. Steel input volatility compresses replacement margins for rental providers while concentrating pricing power with integrated operators who source components through captive fabrication relationships.
Pricing Analysis
Project-based rental contracts with duration-scaled rate cards dominate the North American market. Price differentiation hinges on certification tier—OSHA-compliant operator bundles command premiums over bare equipment rentals—and geographic delivery radius from branch depots. Pricing pressure stems from steel cost compression in crawler crane configurations, where high-tonnage lattice boom fabrications absorb material volatility most acutely. General construction contractors exhibit highest price sensitivity, while Gulf Coast petrochemical operators lock multi-year commitments with lowest elasticity.
Supply Chain Analysis
Regional distribution centers in Texas, Louisiana, and Alberta anchor hub-and-spoke fleet repositioning across the North American market. Manufacturing concentration rests on Germany, Japan, and the United States for precision hydraulic components and high-tensile steel fabrications. Single-source vulnerability runs through specialized crawler undercarriage assemblies sourced from limited Tier 1 suppliers. Distribution runs through national branch networks with yard-based staging, supplemented by heavy-haul partners for oversized component transport.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North American crane rental market functions as a regulatory compounder, with OSHA recertification mandates and provincial safety standards in Ontario and Alberta perpetually expanding addressable demand for bundled training services.
For Market Incumbents: Acquire telematics-enabled fleet management platforms to absorb dispatch and maintenance scheduling from manual coordination. Defend against modular logistics integrators by anchoring multi-project contracts across sequential infrastructure builds in Texas and Virginia data center corridors. Prioritize backward integration into operator training infrastructure to capture recertification revenue streams.
For New Entrants and Emerging Players: Enter via hybrid and electric crane segments where provincial carbon disclosure rules in Ontario and Alberta create first-mover positioning before compliance mandates mature. Target wind turbine installation campaigns across the Great Plains and Texas corridors, where crawler crane demand outstacks specialized supply. Lead with single-source logistics bundling that combines transportation, rigging, and lift engineering.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional heavy-lift specialists anchored in Gulf Coast petrochemical corridors, where turnaround cycle predictability generates contract visibility across multi-year horizons. Monitor OSHA recertification timeline compression as the inflection signal—training infrastructure bottlenecks will accelerate consolidation of operator provisioning capabilities into rental platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Absorbs dispatch functions into predictive algorithms for Texas and Virginia infrastructure contractors. |
| Operator Training Infrastructure Acquisition | Captures OSHA recertification revenue streams as practical examination requirements tighten. |
| Hybrid Fleet Segment Buildout | Positions early-mover advantage under Ontario and Alberta carbon disclosure mandates. |
| Gulf Coast Heavy-Lift Specialization | Locks multi-year crawler commitments through petrochemical turnaround cycle predictability. |
| Modular Logistics Contracting | Displaces standalone equipment rentals with integrated lift-planning and transportation packages. |
Study Parameters
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market through structured interviews with fleet operations directors, construction procurement managers, petrochemical maintenance planners, and crane operator training providers. Secondary validation draws from OSHA regulatory filings, provincial occupational safety records in Ontario and Alberta, customs data on crane component imports, and SEC disclosures from listed rental providers. Bottom-up equipment unit economics triangulate against top-down construction spending forecasts.
Granularity extends to product type, end-use vertical, deployment duration, and service attachment rates across the projection horizon. Modeled dimensions include rough terrain, all terrain, crawler, and tower configurations; construction, energy, shipping, and telecommunications end-users; on-site, off-site, leasing, and long-term deployment structures; and inspection, maintenance, operator training, and transportation service tiers. CAGRs derive from segment-level demand elasticity analysis against infrastructure investment cycles and regulatory compliance timelines.
Inputs from regulatory agencies and rental operator disclosures were available through the study window; gaps in real-time fleet utilization telemetry introduce uncertainty bands around capacity utilization assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Vertical Machining Centers Market
Construction Equipment
Boom Lifts Market
Construction Equipment
Europe Multi Attachment Loaders Market
Construction Equipment
Bucket Elevator Market
Construction Equipment
Bale Openers Market
Construction Equipment
Plasma Welding Machine Market
Construction Equipment
Separation Machinery Market
Construction Equipment
Winch Market
Construction Equipment
Mexico Heavy Construction Equipment Rental Market
Construction Equipment
Powered Screed Market
Construction Equipment
Snow Removal Equipment Market
Construction Equipment
Piling Machine Market
Construction Equipment
Cement and Mortar Testing Equipment Market
Construction Equipment
Cold Forming Equipment Market
Construction Equipment
Jackhammer Market
Construction Equipment
Europe Used Construction Machinery Market