
 GCC Construction Equipment/Machinery Rental Market | 2026-2036
GCC Construction Equipment/Machinery Rental Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Construction Equipment/Machinery Rental Market Foresight
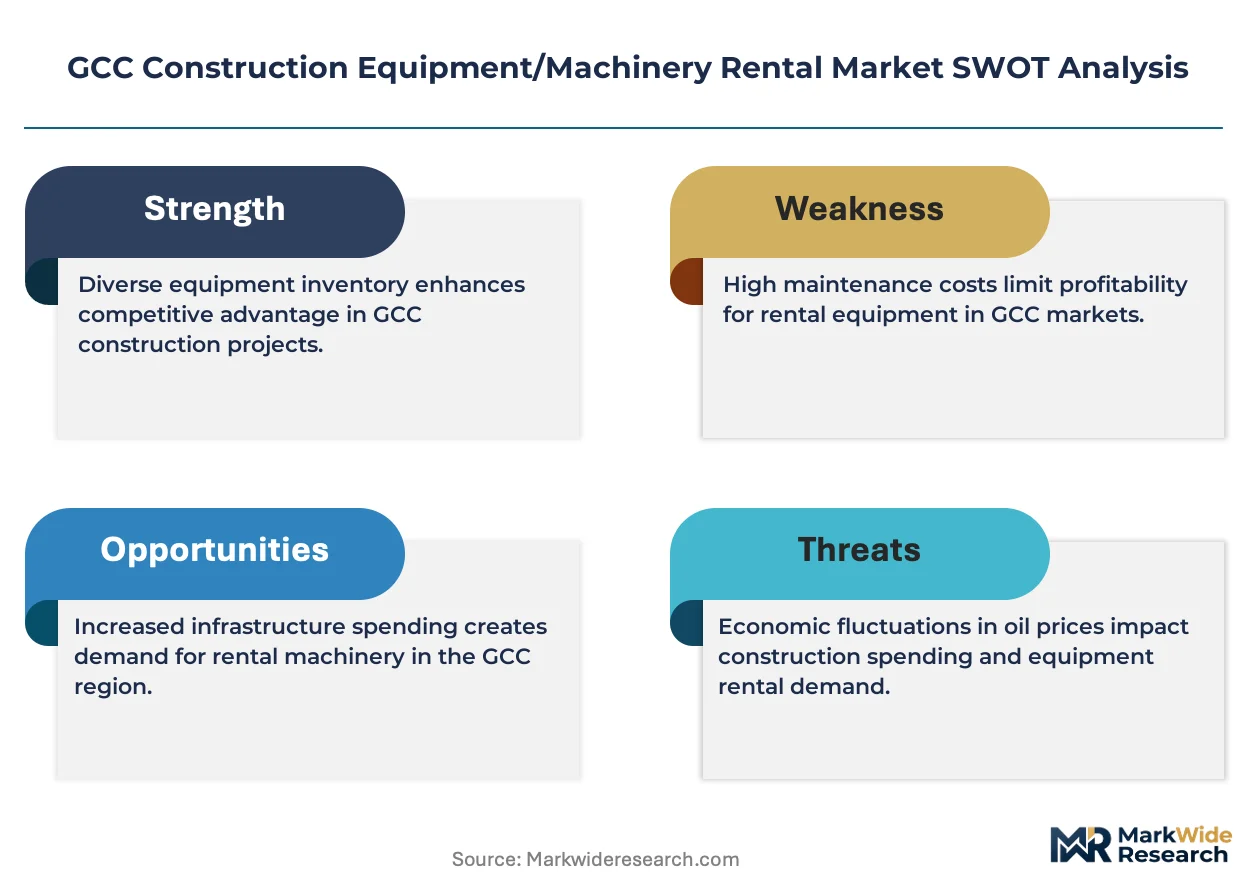
Equipment distribution channels across the GCC is narrowing as rental firms consolidate fleet procurement relationships directly with OEMs and authorized dealers. Byrne Equipment Rental leverages its UAE-based logistics network to sustain same-day deployment capabilities across the Emirates. Zahid Tractor and Heavy Machinery Company anchors its position through deep Caterpillar dealership ties and aftermarket service infrastructure. Al Faris Group specializes in heavy-lift crane logistics, dominating niche segments where technical certification requirements limit competitor entry.
Construction equipment and machinery rental denotes the short-to-medium term leasing of earthmoving, lifting, and material handling assets to contractors and project developers, with fleet units typically rated by load capacity, boom reach, or engine horsepower and maintained under manufacturer service protocols to ensure operational uptime across desert and coastal environments. The application dimension shows infrastructure projects and oil and gas facilities commanding the largest equipment deployment volumes, reflecting state-backed capital allocation patterns across the Gulf. Within equipment type, excavators and cranes represent the most contested categories, while GPS-enabled technology segments attract premium rental rates due to fuel optimization and theft prevention functionalities.
Gulf national regulators including Saudi Arabia's Saudi Standards, Metrology and Quality Organization and the UAE's Emirates Authority for Standardization and Metrology enforce equipment safety and emissions compliance frameworks that shape fleet renewal cycles and import specifications. The Saudi Building Code and Qatar Construction Specifications impose operator certification and inspection protocols that rental providers must integrate into service contracts. Stakeholders should monitor how carbon-neutrality commitments across GCC national visions redirect procurement criteria toward electric and hybrid equipment categories.
Market Dynamics
Fleet telematics integration is compressing rental contract durations across the GCC as contractors demand real-time utilization data and predictive maintenance guarantees from equipment providers. This technological imperative is forcing rental firms to restructure service-level agreements around uptime metrics rather than simple hourly rates.
Growth Catalysts
- NEOM and Red Sea Project pipelines:Saudi Arabia's giga-project portfolio is absorbing crawler cranes and earthmoving fleets at volumes that sustain premium rental rates and accelerate fleet renewal cycles among national providers.
- Emirates Authority for Standardization and Metrology emissions protocols:The UAE's phased diesel particulate filter mandates are pushing contractors toward rental models that externalize compliance upgrade costs to fleet owners.
- Modular construction methods:Prefabricated building systems across Qatar's Lusail Development and Dubai South are driving demand for all-terrain mobile cranes with precision load-moment indicators.
Market Restraints
- Steel and hydraulic component import dependency:GCC rental fleets rely on East Asian supply chains for boom sections and valve assemblies, exposing operators to container freight volatility and extended replacement part lead times.
- Saudi Standards, Metrology and Quality Organization certification bottlenecks:Equipment type-approval timelines for non-Caterpillar and non-Komatsu OEMs stretch 8-14 months, constraining fleet diversification strategies.
- Used equipment re-export channels:Depreciated GCC fleet units flood African and South Asian secondary markets, compressing residual values and elevating lessor risk premiums for long-dated contracts.
Strategic Opportunities
- Oman and Kuwait infrastructure gaps:These markets exhibit 40-60% lower equipment rental penetration than the UAE and Saudi Arabia, presenting first-mover expansion potential for logistics-capable operators.
- Grid-connected electric excavator pilots:Dubai Electricity and Water Authority charging infrastructure investments are enabling battery-powered fleet trials at Al Maktoum International Airport construction zones.
- Saudi Vision 2030 localization incentives:The National Industrial Development Center's equipment manufacturing joint-venture subsidies are attracting rental firms to establish in-country assembly partnerships for mid-size loader production.
Industry Challenges
- Crane operator certification scarcity:Qatar Construction Specifications mandate EU-recognized CPCS or NCCCO credentials that regional training centers cannot supply at scale, inflating wage premiums and project delay risks.
- Legacy fleet telematics retrofit complexity:Pre-2018 diesel units lack CAN bus architectures compatible with GPS fuel monitoring platforms, forcing rental providers to maintain parallel maintenance tracking systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Construction Equipment/Machinery Rental Market |
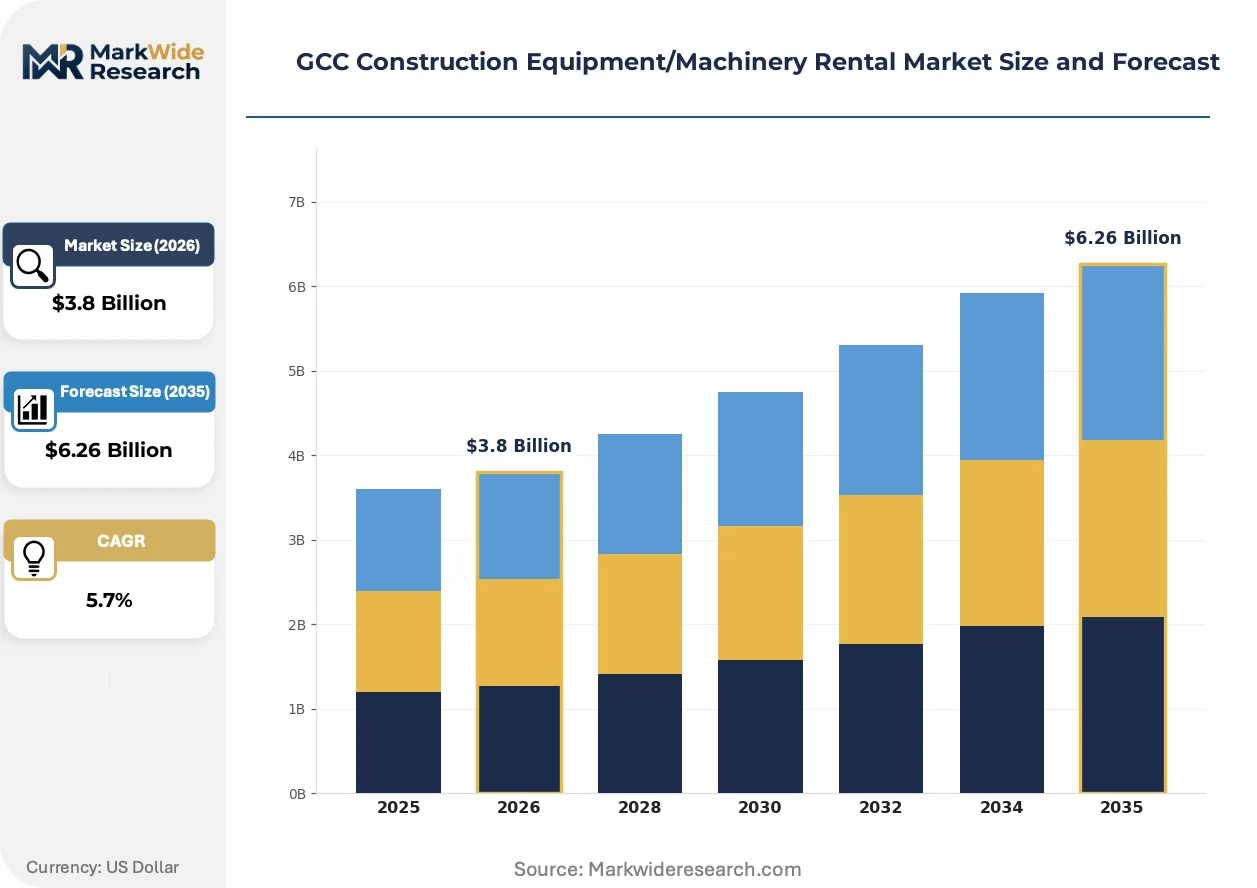
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Excavators, Cranes, Bulldozers, Forklifts, Loaders Technology: Hydraulic, Diesel Engine, Electric, Pneumatic, GPS Enabled Application: Infrastructure Projects, Oil & Gas Facilities, Commercial Buildings, Residential Complexes, Transportation Networks End User: Construction Firms, Engineering Consultants, Equipment Leasing Companies, Civil Contractors, Project Developers |
| Companies Covered | Byrne Equipment Rental, Zahid Tractor and Heavy Machinery Company, Al Faris Group, Hertz Dayim Equipment Rental Co., Johnson Arabia LLC, Bin Quraya, Mohamed Abdulrahman Al-Bahar LLC, Abdullah H. Al Shuwayer Company, Arabian Machinery & Heavy Equipment Co. (AMHEC), Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Construction Equipment/Machinery Rental Market Shifts & Advancements
Equipment intelligence layers are redefining competitive differentiation as rental contracts migrate from asset-access models to productivity-guarantee structures. This shift elevates data analytics capabilities above fleet scale as the primary vendor selection criterion.
Telematics platforms is hybridizing operational visibility with predictive maintenance algorithms across GCC rental fleets. Major contractors on Saudi giga-projects now mandate ISO 15143-3 telematics data feeds as standard contract terms. This convergence is compressing response times for hydraulic fault remediation from 48 hours to sub-6-hour windows.
Saudi Arabia's Saudi Building Code amendments are mandating real-time load monitoring for cranes above 50-ton capacity across all government-funded projects. The regulation forces rental providers to retrofit older lattice boom units with wireless load cells or retire them from state contract eligibility. Contractors in Riyadh and Jeddah corridors are accelerating compliance spending to maintain project bidding qualifications.
Equipment-as-a-service contracting is displacing traditional dry-hire arrangements across UAE commercial construction. Contractors now demand bundled fuel, maintenance, and operator provision within single monthly rates. This preference is most pronounced in Dubai's Expo District legacy developments, where fixed-cost budgeting priorities override asset ownership preferences among mid-tier general contractors.
GCC Construction Equipment/Machinery Rental Market Segmentation
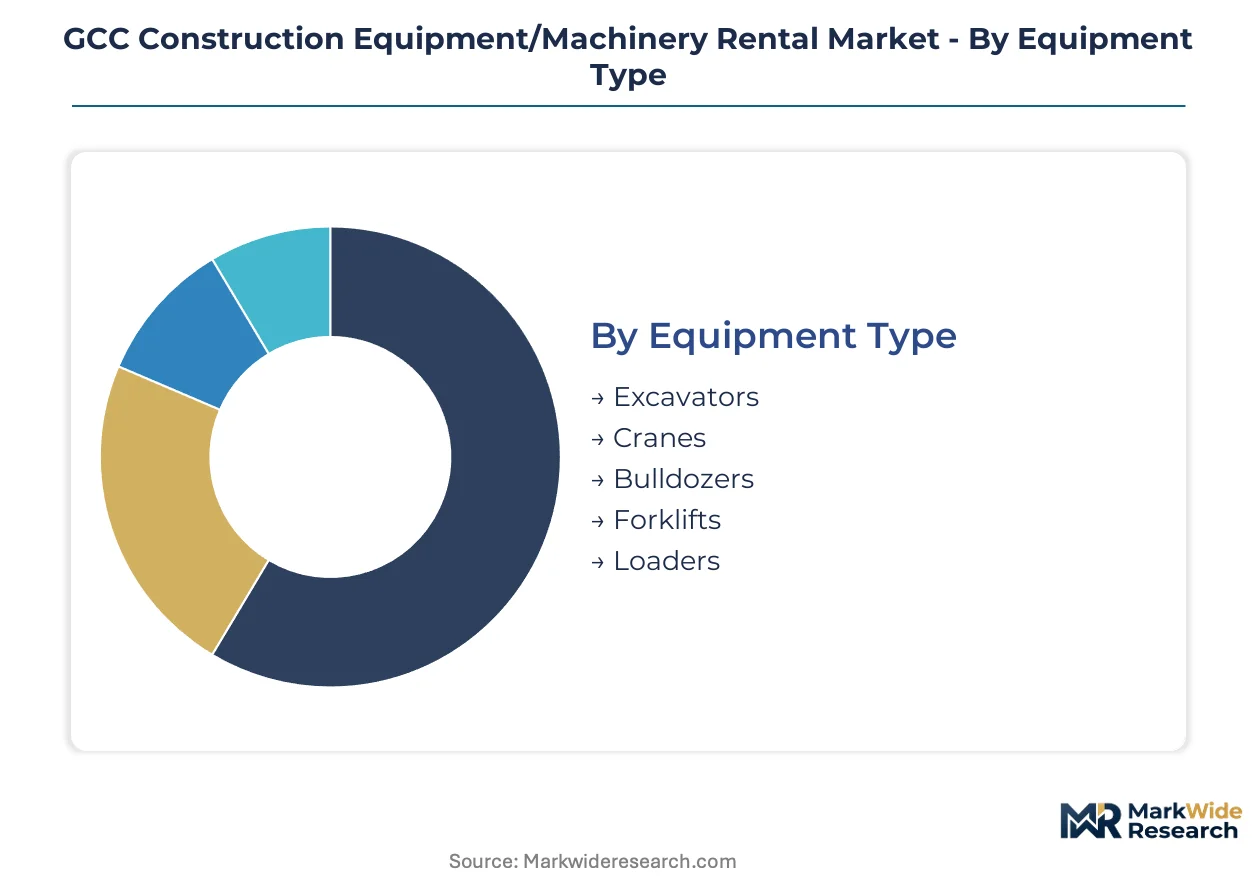
Segmentation in the GCC equipment rental market reveals how fleet composition, technology integration, and end-user contracting structures determine utilization rates and margin profiles across desert construction corridors. Rental providers configure mixed-asset portfolios to match the project duration and technical certification requirements dominant in each application vertical.
Equipment Type:
Cycle times vary dramatically by equipment category, with high-utilization earthmovers turning over every 18-24 months while specialized heavy-lift assets depreciate across 7-10 year holding periods.
- Excavators:Tracked and wheeled variants with bucket capacities from 1.5 to 40 cubic meters dominate Saudi giga-project earthworks. NEOM and Red Sea Project contractors specify mid-size hydraulic excavators with reinforced undercarriages for abrasive desert terrain, compressing maintenance intervals and accelerating replacement demand.
- Cranes:Lattice boom crawler and all-terrain mobile units command premium daily rates tied to operator certification scarcity. Qatar's Lusail Development and Dubai South modular construction zones absorb telescopic and tower crane fleets where precision load-moment indicators have become mandatory under amended building codes.
- Bulldozers:Heavy dozers with rippers and blade configurations serve site preparation and road grading across UAE transportation network buildouts.
- Forklifts:Warehouse and material handling fleets rotate through shorter-term contracts in commercial building logistics.
- Loaders:Wheel loaders with high-lift arms support aggregate handling and batch plant operations in Riyadh and Jeddah construction corridors.
Excavators dominate installed base. Cranes are where expansion concentrates.
Technology:
Cost tiers separate legacy mechanical systems from connected fleets, with GPS-enabled and electric categories commanding 15-25% rate premiums over conventional diesel equivalents.
- GPS Enabled:Telematics-integrated units with ISO 15143-3 data feeds deliver real-time fuel consumption and theft prevention. Dubai Electricity and Water Authority charging infrastructure pilots at Al Maktoum International Airport construction zones validate battery-powered fleet economics, while Saudi contractors now mandate predictive maintenance guarantees as standard contract terms.
- Electric:Grid-connected excavators and compact loaders eliminate diesel particulate filter compliance costs under UAE phased emissions mandates. Battery-powered units face range and charging infrastructure constraints but attract state-backed giga-project procurement preferences aligned with carbon-neutrality commitments.
- Hydraulic:Conventional fluid-power systems remain standard for heavy-lift crane categories where electrification torque requirements exceed current battery densities.
- Diesel Engine:Pre-2018 fleet units lacking CAN bus architectures face telematics retrofit complexity and parallel maintenance tracking burdens.
- Pneumatic:Compressed-air systems serve niche demolition and tunneling applications with lower penetration in GCC rental portfolios.
Diesel Engine units retain largest fleet share. GPS Enabled technology is gaining share fastest.
Application:
Volume concentration tracks state capital allocation, with infrastructure and hydrocarbon facilities absorbing 60-70% of deployed fleet hours against shorter-cycle commercial and residential projects.
- Infrastructure Projects:Roads, bridges, utilities, and water treatment facilities sustain multi-year equipment attachments. Saudi Vision 2030 giga-projects generate continuous demand for earthmoving and piling equipment with 85-90% utilization rates.
- Oil & Gas Facilities:Refinery expansions and offshore platform maintenance require explosion-proof certified cranes and specialized lifting gear. Aramco and ADNOC contracting standards impose vendor qualification barriers that concentrate rental relationships with established fleet operators.
- Commercial Buildings:High-rise office and retail developments in Dubai and Abu Dhabi corridors drive tower crane and concrete pumping demand.
- Residential Complexes:Mid-density housing projects utilize smaller excavators and material handlers on shorter-term dry-hire arrangements.
- Transportation Networks:Metro extensions and airport expansions across Doha, Riyadh, and Kuwait City specify precision grading and tunnel boring support equipment.
Infrastructure Projects anchor fleet deployment. Oil & Gas Facilities show steepest expansion trajectory.
End User:
Customer type determines contract structure complexity, with construction firms and civil contractors driving equipment-as-a-service bundling while leasing companies and consultants influence specification standards.
- Construction Firms:Tier-1 general contractors on Saudi giga-projects and UAE commercial developments demand bundled fuel, maintenance, and operator provision within fixed monthly rates. This preference displaces traditional dry-hire arrangements and elevates vendor data analytics capabilities above fleet scale in selection criteria.
- Civil Contractors:Road, bridge, and utility specialists maintain long-term relationships with rental providers for recurring earthmoving and compaction equipment needs.
- Equipment Leasing Companies:Financial lessors focus on residual value management and secondary market re-export channels for depreciated fleet units.
- Engineering Consultants:Technical advisors specify equipment performance standards and telematics compliance without direct rental contracting authority.
- Project Developers:Master developers coordinate multi-contractor equipment scheduling across phased construction programs.
Construction Firms generate highest contract volume. Civil Contractors offer most predictable renewal patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The King Fahd Causeway and Qatar-Bahrain Causeway anchor Bahrain's strategic position as a Gulf logistics intermediary, while the Riyadh-Dammam railway corridor underwrites Saudi Arabia's equipment mobility infrastructure. These transport arteries concentrate rental fleet deployment patterns across the six GCC states.
Saudi Arabia
NEOM's linear city development and Red Sea Project tourism zones absorb crawler cranes and earthmoving fleets at sustained volumes. The Saudi Building Code amendments mandate real-time load monitoring for cranes above 50-ton capacity, forcing fleet retrofits. Riyadh and Jeddah construction corridors exhibit the densest equipment rental penetration outside the UAE.
United Arab Emirates
Dubai Metro extensions and Al Maktoum International Airport buildouts drive precision grading equipment demand. The Emirates Authority for Standardization and Metrology enforces phased diesel particulate filter mandates that push contractors toward rental models externalizing compliance costs. Dubai and Abu Dhabi corridors concentrate the highest rental equipment density in the GCC.
Qatar
Lusail Development and FIFA World Cup legacy infrastructure sustain multi-year crane and concrete pumping contracts. Qatar Construction Specifications impose EU-recognized CPCS or NCCCO operator credentials that regional training centers cannot supply at scale. Doha metro expansion zones absorb tunnel boring support equipment on fixed monthly rate contracts.
Oman
Duqm Special Economic Zone port and refinery projects generate demand for heavy-lift and material handling fleets. The country's national standardization body enforces equipment safety protocols aligned with GCC technical regulations. Muscat-Sohar industrial corridor exhibits 40-60% lower rental penetration than UAE benchmarks, presenting expansion headroom.
Kuwait
Silk City and Boubyan Island development schemes drive earthmoving and piling equipment attachments. The Public Authority for Industry oversees equipment import specifications and type-approval timelines. Kuwait City construction zones show concentrated demand for mid-size hydraulic excavators on shorter-term dry-hire arrangements.
GCC Construction Equipment/Machinery Rental Market Competitive Landscape
On the supply side, the industry is consolidating around fleet-scale operators with integrated logistics networks and OEM dealership relationships. Three archetypes dominate: UAE-based logistics-integrated providers with same-day deployment capabilities, Caterpillar-anchored dealers leveraging aftermarket service infrastructure, and heavy-lift specialists commanding niche segments through technical certification barriers. Competitive moves concentrate on fleet telematics integration and geographic expansion into underpenetrated Oman and Kuwait markets.
Within the logistics-integrated tier, Byrne Equipment Rental exemplifies UAE-based operators sustaining rapid deployment capabilities across Emirates corridors. Zahid Tractor and Heavy Machinery Company anchors the OEM-dealer archetype through deep Caterpillar ties. Al Faris Group occupies the heavy-lift specialist position where crane operator certification scarcity limits competitor entry. These three represent distinct strategic positions rather than direct substitution alternatives.
| Leading Market Players |
|---|
| Byrne Equipment Rental |
| Zahid Tractor and Heavy Machinery Company |
| Al Faris Group |
| Hertz Dayim Equipment Rental Co. |
| Johnson Arabia LLC |
| Bin Quraya |
| Mohamed Abdulrahman Al-Bahar LLC |
| Abdullah H. Al Shuwayer Company |
| Arabian Machinery & Heavy Equipment Co. (AMHEC) |
| Others |
Supply & Pricing Matrix
East Asian steel mills and hydraulic component foundries anchor upstream supply for GCC rental fleets, concentrating margin capture in boom sections and valve assemblies while downstream pricing power fragments across dispersed contractor bases. This upstream concentration forces rental operators to absorb freight volatility through inventory carrying costs rather than pass-through mechanisms.
Pricing Analysis
Volume-discount tiering structures separate national fleet operators from regional specialists, with three-tier pricing across premium telematics-enabled units, standard diesel fleets, and economy-grade legacy equipment. Price differentiation hinges on ISO 15143-3 certification status and bundled service-attach density. Cost compression in economy tiers is intensifying because used equipment re-export channels compress residual values. Mid-tier civil contractors exhibit highest price sensitivity, while Aramco and ADNOC contractors prioritize uptime guarantees over rate negotiation.
Supply Chain Analysis
Export-control regimes on precision GPS modules and encrypted telematics chipsets limit technology flows into GCC assembly operations, extending lead times for connected fleet retrofits. Manufacturing concentrates in Japan, South Korea, and Germany for hydraulic systems, with China dominating steel boom fabrication. Raw material dependencies span high-tensile steel plate, synthetic hydraulic fluids, and rare-earth magnet components for electric drivetrains. Single-source vulnerability runs through East Asian container freight corridors. Distribution runs through OEM-authorized dealer networks rather than open wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC equipment rental market functions as a service-attach opportunity where predictive maintenance contracts and telematics data subscriptions expand faster than base hardware rental rates. Recurring revenue layers now determine enterprise valuation multiples.
For Market Incumbents: Pre-empt telematics platform consolidation by acquiring regional software integrators before Caterpillar and Komatsu bundle proprietary solutions. Defend fleet utilization rates through backward integration into in-country assembly partnerships under Saudi Vision 2030 localization incentives. Certification bottlenecks at Saudi Standards, Metrology and Quality Organization threaten market access for non-aligned operators. For New Entrants and Emerging Players: Establish a beachhead in Oman's Duqm Special Economic Zone and Kuwait's Silk City corridor where rental penetration trails UAE benchmarks by 40-60%. Target heavy-lift crane categories where Qatar Construction Specifications mandate EU-recognized credentials that constrain supply. Lead with equipment-as-a-service bundling to displace dry-hire incumbents. For Investors and Strategic Acquirers: Capital is best deployed toward logistics-integrated mid-cap operators with same-day deployment capabilities and established OEM dealership relationships. Long-term viability favors fleet-scale positions over asset-light intermediaries. Watch for Saudi Building Code amendments mandating real-time load monitoring as inflection indicators for compliance-driven replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Telematics Integration | ISO 15143-3 data feeds now anchor contractor selection criteria across Saudi giga-projects. |
| Geographic Expansion into Oman and Kuwait | Underpenetrated corridors offer first-mover logistics network establishment ahead of infrastructure buildouts. |
| Electric Equipment Pilot Programs | Dubai Electricity and Water Authority charging infrastructure validates battery-powered fleet economics at Al Maktoum. |
| Localization Joint Ventures | National Industrial Development Center subsidies enable in-country assembly partnerships for mid-size loader production. |
| Operator Certification Infrastructure | EU-recognized CPCS and NCCCO credential programs address Qatar's crane operator scarcity premium. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from listed OEMs, and Emirates Authority for Standardization and Metrology regulatory bulletins. Fleet operations directors, maintenance supervisors at Saudi giga-projects, procurement leads at Aramco and ADNOC, and aftermarket service heads at Caterpillar dealerships provided structured interviews. Bottom-up equipment utilization rates triangulate against top-down construction spending forecasts.
Forecast inputs include equipment type segmentation, technology tier adoption curves, and application vertical demand intensity across the projection horizon. The analytical framework models earthmoving, lifting, and material handling categories with GPS-enabled, electric, and conventional diesel technology splits. CAGRs derive from fleet replacement cycles, giga-project pipeline visibility, and regulatory compliance phase-in schedules. Saudi Vision 2030 capital allocation patterns and UAE emissions mandate timelines anchor forward projections.
Stress conditions across steel price volatility, container freight rate spikes, and certification approval delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about state-backed infrastructure commitment continuity and OEM supply chain stability. Material shifts in GCC national carbon-neutrality target acceleration or East Asian export control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Extrusion Machinery Market
Construction Equipment
North America Drilling Market
Construction Equipment
Cement Consistency Meter Market
Construction Equipment
Cementing Accessories Market
Construction Equipment
Hybrid Excavator Market
Construction Equipment
Hydraulic Press Machine Market
Construction Equipment
Global Desktop CNC Machines Market
Construction Equipment
Laser Cladding Equipment Market
Construction Equipment
Crossover Ladder Market
Construction Equipment
Fogging Machine Market
Construction Equipment
GCC Crane Market
Construction Equipment
Asia-Pacific Mobile Light Tower Market
Construction Equipment
Vertical Machining Centers Market
Construction Equipment
Stud Welding Machine Market
Construction Equipment
Grout Bags Market
Construction Equipment
Construction Lasers Market