
 Rolling Mill Machine Market | 2026-2036
Rolling Mill Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Rolling Mill Machine Market Analytics
Chinese steel equipment makers is expanding domestic forging capacity for wide-strip mills. SMS Group GmbH leverages deep engineering heritage in hot rolling lines for integrated steelworks. Danieli anchors its position through continuous casting and rolling integration. Primetals Technologies Ltd. competes on digital twin deployment across electromechanical mill upgrades.
A rolling mill machine is a mechanical system that reduces metal stock thickness through compressive forces applied by rotating cylindrical rolls, typically achieving gauge tolerances within hundredths of a millimeter. The equipment serves primary metalworking and steel production facilities that require uniform sheet, plate, or structural section output. Hot rolling commands the largest installed base due to its role in primary steelmaking, while cold rolling captures margin concentration from automotive surface-quality requirements. Electromechanical technology is displacing legacy hydraulic systems where energy recovery and precision control justify capital replacement cycles.
China's MIIT enforces GB energy-efficiency standards that compel mill retrofit or retirement of outdated mechanical drives. The EU F-Gas Regulation and REACH framework constrain hydraulic fluid chemistry and emissions profiles for equipment sold into European steelworks. India's BIS certification mandates structural steel conformity for infrastructure-grade rolled products. Stakeholders must weigh regulatory compliance timelines against the extended depreciation cycles typical of mill capital equipment.
Market Dynamics
Electromechanical drive retrofits are displacing hydraulic systems across aging installed bases, forcing capital allocation decisions between full replacement and incremental upgrade paths. Steel producers face compressed payback thresholds as energy recovery systems reshape operating cost structures.
Growth Catalysts
- India PLI Scheme for Specialty Steel:Domestic producers are qualifying for production-linked incentives by expanding wide-strip and plate mill capacity, directly lifting equipment orders from domestic and international suppliers.
- Automotive Surface-Quality Mandates:Cold rolling lines serving EV chassis and battery enclosure grades command premium specifications, sustaining investment in precision gauge control systems.
- China's Dual Carbon Goals:MIIT enforcement of GB energy-efficiency standards is accelerating retirement of mechanical drive mills in Hebei and Shandong provinces, creating replacement demand.
Market Restraints
- Specialty Alloy Input Volatility:Roll manufacturing depends on forged steel and tungsten carbide feedstock subject to spot price swings, compressing OEM margins on fixed-price contracts.
- Supplier Concentration in Drive Systems:High-torque electromechanical motors and variable frequency drives concentrate among German and Japanese component houses, exposing mill builders to single-source risk.
- REACH Hydraulic Fluid Constraints:The EU F-Gas Regulation and ECHA restrictions on mineral oil formulations complicate aftermarket service for legacy hydraulic mills still operational across European steelworks.
Strategic Opportunities
- Southeast Asia Greenfield Capacity:Vietnam and Indonesia are licensing integrated steelworks with domestic rolling capacity, opening first-mover positioning for equipment vendors outside established Chinese supply relationships.
- Digital Twin Integration:Convergence of physics-based modeling with real-time sensor telemetry enables predictive roll wear scheduling, creating recurring software revenue streams alongside hardware sales.
- Scrap-Based EAF Rolling Lines:Mini-mill configurations serving rebar and structural sections are expanding in Turkey and Egypt, requiring compact roughing and intermediate mill packages distinct from integrated works specifications.
Industry Challenges
- Control Systems Integration:Retrofitting electromechanical drives into 1970s-era mill housings demands scarce automation engineering talent capable of bridging mechanical and digital architectures.
- BIS Certification Timelines:India's structural steel conformity assessment for infrastructure grades extends equipment qualification cycles, delaying revenue recognition for suppliers targeting NHAI and state highway projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rolling Mill Machine Market |
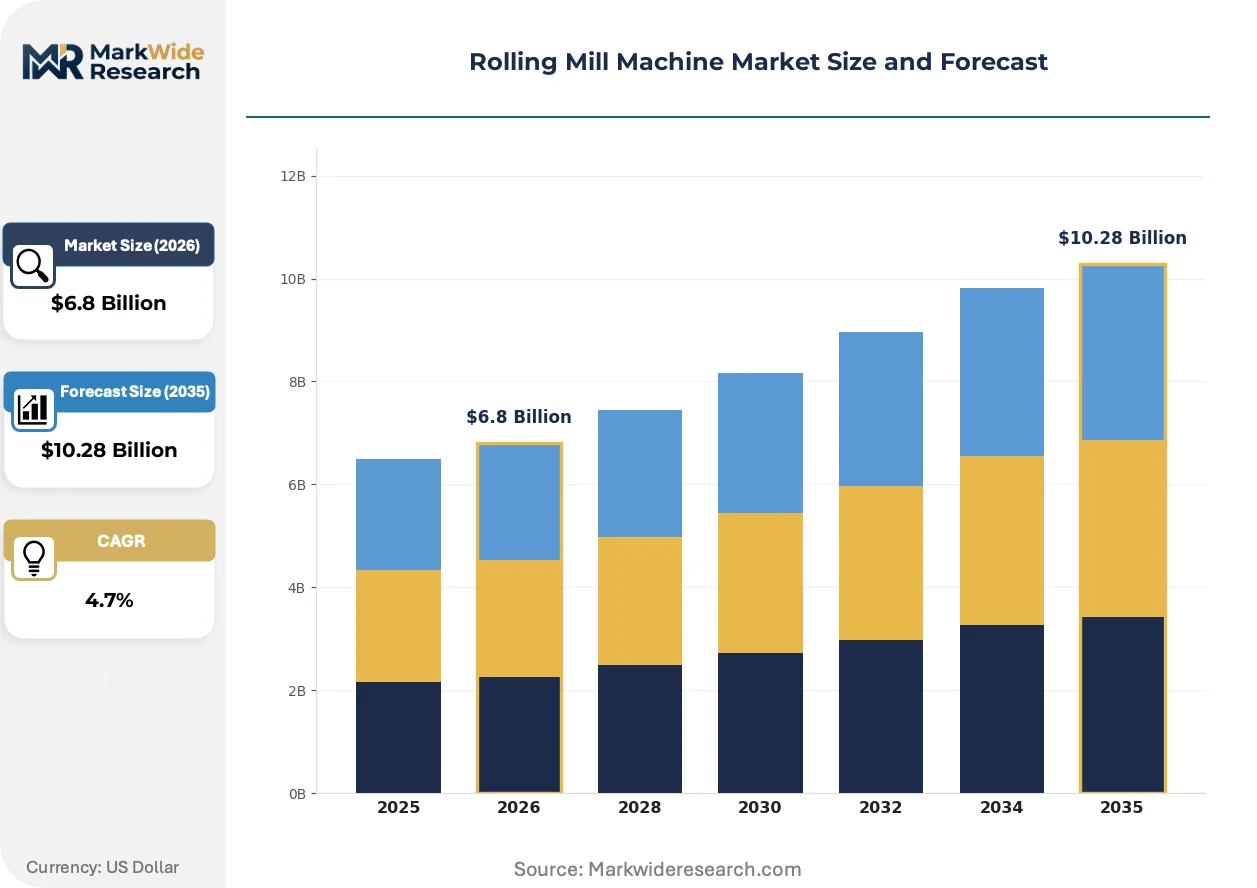
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Rolling, Cold Rolling, Plate Mill, Wire Rod Mill End User: Construction, Automotive, Aerospace, Manufacturing Technology: Mechanical, Hydraulic, Electromechanical, Automation Application: Metalworking, Steel Production, Sheet Metal, Structural Components |
| Companies Covered | SMS Group GmbH, Primetals Technologies Ltd., Danieli, Andritz AG, Mitsubishi Heavy Industries Ltd., ABB Ltd., Fives Group, ThyssenKrupp AG, Tenova S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rolling Mill Machine Market Evolving Landscape
Artificial intelligence and edge computing are penetrating mill control architectures, compressing the gap between process modeling and real-time roll gap adjustment. Equipment vendors are repositioning around data monetization rather than pure hardware margins.
Model-predictive control systems using neural network training on historical rolling force data are consolidating supplier competitive positions around software-embedded hardware bundles. Tier-one automotive steel buyers in Germany and Japan are mandating these systems for surface defect prevention. The technology is consolidating mid-tier mill builders who lack in-house algorithm development capabilities into licensing relationships with specialized controls houses.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in mill hydraulic cooling circuits, compelling redesign of thermal management subsystems. European steelworks in Belgium and northern Italy face accelerated compliance deadlines for existing wide-strip installations. Cold rolling specialists serving automotive exposed panels are responding with air-oil mist cooling retrofits that eliminate refrigerant dependency entirely.
Steel buyers are unbundling after-sales service contracts from original equipment procurement, driving third-party maintenance houses to acquire rolling expertise. Independent service providers in Pittsburgh and Duisburg are hiring retired mill operators to compete on roll change and gauge calibration. This pattern is most visible in North American specialty steel, where fragmented buyer structures resist long-term OEM service lock-in.
Rolling Mill Machine Market Segmentation
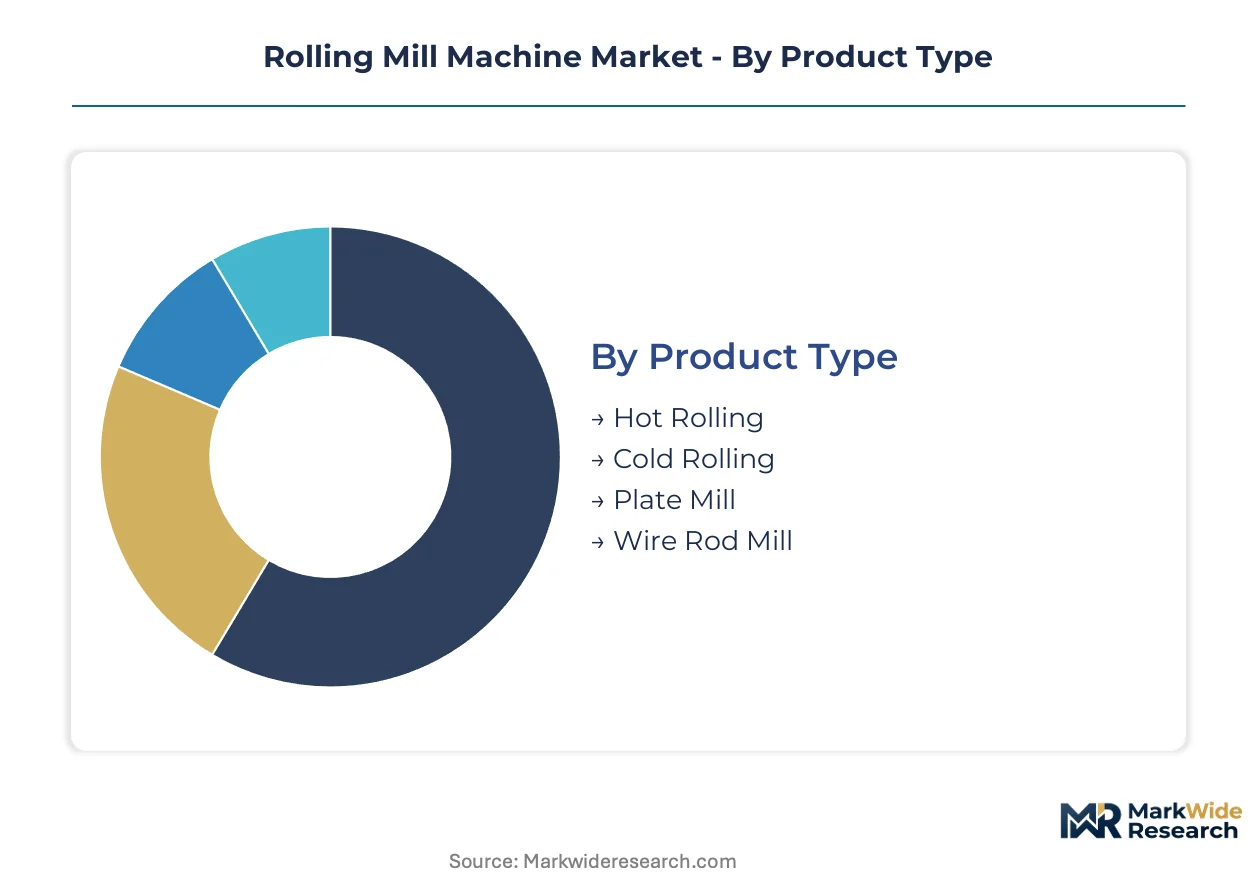
Rolling mill machine segmentation reveals how capital allocation priorities diverge across steelmaking value chains. Equipment specification varies sharply between integrated works requiring heavy-gauge capacity and mini-mills serving niche dimensional tolerances.
Product Type:
Standardization dominates high-volume installations while specialty mills demand extensive mechanical customization for unique gauge profiles.
- Hot Rolling:These mills process steel above recrystallization temperature, achieving thickness reduction through multi-stand continuous configurations. Demand concentrates in Hebei province where MIIT-mandated efficiency retrofits are replacing mechanical drive systems with electromechanical alternatives. China's state-backed infrastructure sustain heavy plate consumption through state-owned steelworks.
- Cold Rolling:Operating below recrystallization temperature, these lines deliver surface finishes within micrometer tolerances for automotive exposed panels. German and Japanese tier-one automotive steel buyers mandate model-predictive control systems for defect prevention, compressing supplier qualification timelines.
- Plate Mill:Specialized for thick-section structural and shipbuilding grades requiring width exceeding 3,000 millimeters.
- Wire Rod Mill:Compact configurations serving rebar and construction mesh markets with high-speed coil output.
Leading the category by volume: Hot Rolling. Growing fastest: Cold Rolling.
End User:
Margin concentration shifts toward precision-dependent sectors where specification tolerance justifies premium equipment configurations.
- Automotive:EV chassis and battery enclosure grades command surface-quality mandates that sustain investment in precision gauge control systems. Cold rolling lines serving this segment require neural network-trained predictive systems for real-time roll gap adjustment.
- Construction:India's NHAI and state highway projects drive structural steel conformity requirements under BIS certification, extending equipment qualification cycles for infrastructure-grade rolled products.
- Aerospace:Titanium and specialty alloy rolling demands vacuum-chamber and isothermal mill configurations with extreme temperature control.
- Manufacturing:General industrial applications span appliance-grade sheet to precision strip for electronics substrates.
Highest margin capture: Automotive. Steepest expansion trajectory: Construction.
Technology:
Energy recovery economics are forcing capital replacement cycles across aging installed bases.
- Electromechanical:Variable frequency drives with regenerative braking displace legacy systems where precision control and energy recovery justify capital outlay. German and Japanese component houses concentrate high-torque motor supply, exposing mill builders to single-source risk.
- Hydraulic:Legacy installations face REACH fluid constraints and EU F-Gas Regulation compliance deadlines for cooling circuit redesign.
- Mechanical:Conventional drive systems dominate developing-market greenfield projects with lower capital intensity requirements.
- Automation:Edge computing and sensor telemetry enable predictive roll wear scheduling, creating recurring software revenue streams alongside hardware sales.
Widest installed base: Hydraulic. Fastest displacement rate: Electromechanical.
Application:
Process integration requirements vary from standalone mini-mills to fully integrated steelworks with continuous casting linkages.
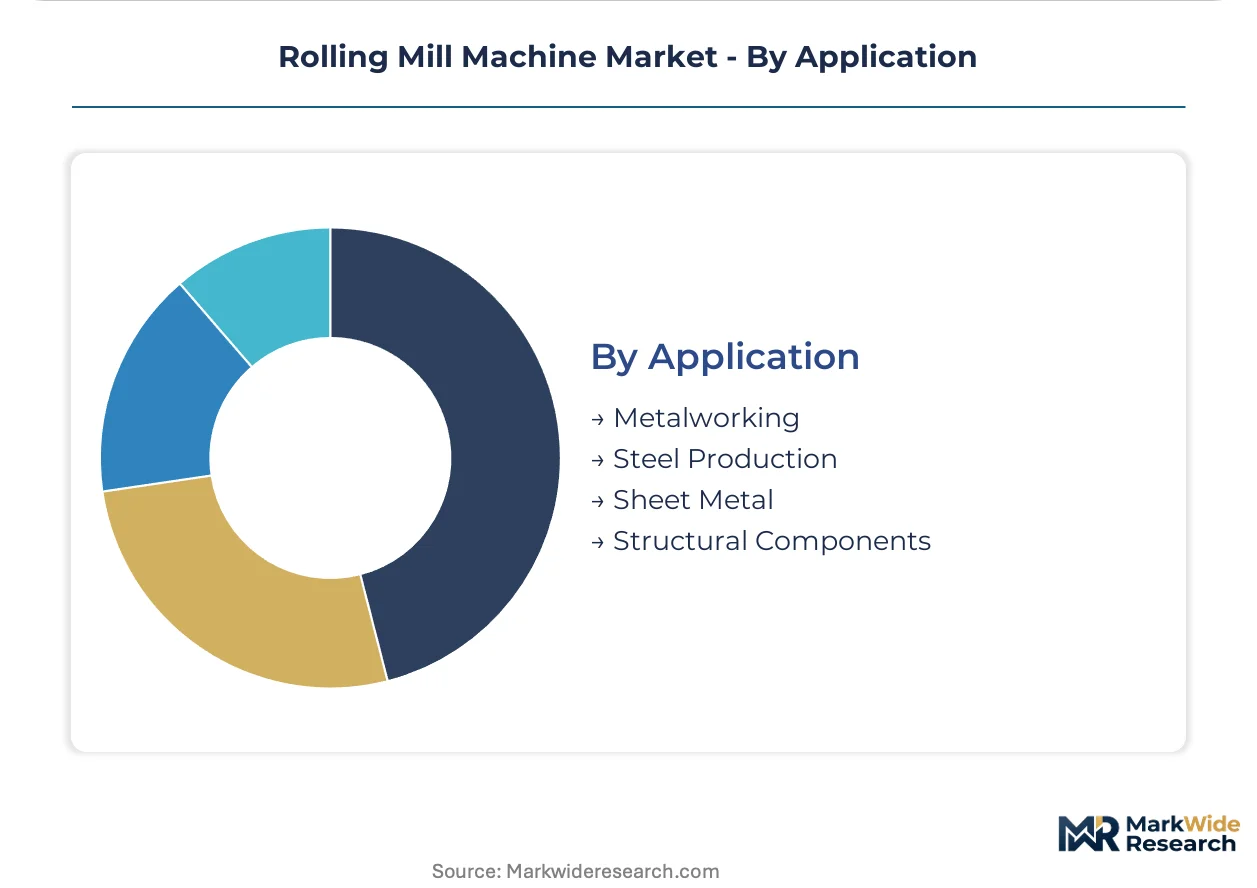
- Steel Production:Integrated works in Vietnam and Indonesia are licensing domestic rolling capacity, opening first-mover positioning for equipment vendors outside established Chinese supply relationships.
- Sheet Metal:Automotive and appliance grades demand tandem cold mill configurations with automatic gauge control and shape metering systems.
- Metalworking:Non-ferrous rolling for copper and aluminum requires specialized roll materials and cooling protocols distinct from steel processing.
- Structural Components:Beam, channel, and angle production serves construction markets with lower surface finish requirements but strict dimensional tolerances.
Dominant revenue share: Steel Production. Gaining share fastest: Sheet Metal.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iron ore deposits in Western Australia and the Pilbara region anchor steelmaking feedstock flows that shape rolling mill demand across Asia-Pacific manufacturing belts.
China
Hebei and Shandong provinces host the densest concentration of wide-strip capacity where MIIT enforces GB energy-efficiency standards. The dual carbon goals accelerate retirement of mechanical drive mills. Tangshan steel clusters are retrofitting electromechanical systems under state-mandated efficiency timelines.
India
The PLI scheme for specialty steel is expanding wide-strip and plate mill orders across domestic producers. BIS certification mandates structural steel conformity for infrastructure-grade rolled products. Odisha and Jharkhand steel corridors are scaling capacity to serve NHAI highway projects.
Germany
Automotive surface-quality mandates from tier-one steel buyers sustain investment in precision cold rolling lines. The EU F-Gas Regulation and REACH framework constrain hydraulic fluid chemistry for equipment compliance. Ruhr industrial belt steelworks are deploying model-predictive control systems for defect prevention.
United States
Mini-mill configurations serving rebar and structural sections are expanding across electric arc furnace operators. EPA emissions standards and state-level decarbonization targets shape equipment replacement cycles. Pittsburgh specialty steel clusters resist long-term OEM service lock-in through independent maintenance providers.
Japan
Tier-one automotive steel buyers mandate neural network-trained predictive systems for real-time roll gap adjustment. METI industrial efficiency guidelines drive electromechanical retrofits in aging integrated works. Chubu and Kansai manufacturing belts concentrate precision cold rolling capacity for exposed panel grades.
Rolling Mill Machine Market Competitive Landscape
Global majors compete with regional champions across engineering heritage and digital integration depth. The vendor base organizes around three tiers: full-line integrators with continuous casting linkages, electromechanical drive specialists, and automation-focused controls houses. Strategic moves concentrate on M&A for digital twin capabilities and geographic expansion through licensing partnerships in Southeast Asian greenfield projects.
Within the full-line integrator tier, SMS Group GmbH and Danieli exemplify engineering-intensive positioning through hot rolling heritage and casting-rolling integration. Primetals Technologies Ltd. occupies a distinct position around digital twin deployment for electromechanical upgrades. These three anchors illustrate how competitive positioning increasingly separates hardware margins from recurring software revenue streams.
| Leading Market Players |
|---|
| SMS Group GmbH |
| Primetals Technologies Ltd. |
| Danieli |
| Andritz AG |
| Mitsubishi Heavy Industries Ltd. |
| ABB Ltd. |
| Fives Group |
| ThyssenKrupp AG |
| Tenova S.p.A. |
| Others |
Value Network & Pricing Analysis
Electromechanical drive retrofits across aging Hebei and Shandong steel clusters simultaneously compress operating costs and concentrate procurement leverage among German and Japanese motor suppliers. This technology transition reshapes capital equipment economics by elevating precision-control premiums while squeezing legacy hydraulic service margins.
Pricing Analysis
After-sales service unbundling from original equipment procurement now dominates contract structures across North American specialty steel and European wide-strip installations. Three-tier pricing structure across premium, standard, and economy levels separates digital twin-embedded bundles from bare mechanical configurations, with tier-one automotive buyers in Germany and Japan mandating neural network-trained predictive systems for defect prevention. Cost compression in economy-tier hydraulic retrofits is intensifying because REACH fluid constraints and EU F-Gas Regulation compliance deadlines accelerate obsolescence. Mini-mill operators in Turkey and Egypt exhibit highest price sensitivity due to scrap-fed EAF economics, while integrated works in Vietnam and Indonesia absorb premium electromechanical packages for greenfield licensing requirements.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese component houses for high-torque electromechanical motors and variable frequency drives, exposing mill builders to concentrated supply risk. Forged steel and tungsten carbide roll manufacturing draws from China, Germany, and Japan, with specialty alloy feedstock subject to spot price volatility that compresses OEM margins on fixed-price contracts. Tariff exposure on precision control electronics imported into Southeast Asian greenfield projects compounds procurement uncertainty. Distribution runs through OEM-direct channels for integrated works and third-party maintenance houses for fragmented North American specialty steel buyers resisting long-term service lock-in.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around software-embedded hardware bundles as algorithm development capabilities force mid-tier mill builders into licensing relationships with specialized controls houses. Regulatory compliance timelines against extended depreciation cycles squeeze capital-constrained regional players.
For Market Incumbents: Anticipate margin compression from independent service providers in Pittsburgh and Duisburg hiring retired mill operators to compete on roll change and gauge calibration. Defend position through backward integration into predictive roll wear software development and captive supply of high-torque motor assemblies. Prioritize BIS certification pre-qualification for India's NHAI and state highway project pipelines. For New Entrants and Emerging Players: The premium-to-economy price-point gap in cold rolling lines for automotive exposed panels offers white-space entry for compact mill configurations serving EV chassis and battery enclosure grades. Target scrap-based EAF rolling line packages distinct from integrated works specifications in Turkey and Egypt. Pursue licensing partnerships with Vietnamese and Indonesian integrated steelworks as first-mover positioning outside established Chinese supply relationships. For Investors and Strategic Acquirers: Re-rating potential sits with automation-focused controls houses given tier-one automotive mandates for model-predictive control systems across Germany and Japan. Long-term viability favors vendors capturing recurring software revenue streams alongside hardware sales rather than pure mechanical builders. Watch for inflection when steel buyers unbundle after-sales contracts at scale, signaling third-party maintenance house acquisition appetite.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Physics-based modeling with sensor telemetry enables predictive roll wear scheduling for recurring software revenue. |
| Backward Integration into Drive Systems | Captive production of high-torque motors mitigates single-source vulnerability to German and Japanese component houses. |
| Greenfield Licensing Partnerships | Southeast Asian steelworks in Vietnam and Indonesia open first-mover positioning outside Chinese supply relationships. |
| Air-Oil Mist Cooling Retrofits | Elimination of hydrofluorocarbon refrigerant dependency satisfies EU F-Gas Regulation compliance for Belgian and Italian mills. |
| BIS Certification Pre-Qualification | Structural steel conformity assessment streamlines equipment qualification for India's NHAI highway project pipelines. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with maintenance directors at integrated steelworks, plant engineers at mini-mill operators, OEM procurement teams, and aftermarket service heads combined with MIIT efficiency standard disclosures, EU ECHA restriction databases, and Indian BIS certification registries. Bottom-up equipment order tracking and top-down steel capacity expansion projections were triangulated for cross-validation.
Segment-level granularity modeled hot rolling, cold rolling, plate mill, and wire rod mill configurations across electromechanical, hydraulic, mechanical, and automation technology tiers. End-use segmentation captured automotive, construction, aerospace, and manufacturing demand patterns. Geographic disaggregation tracked country-specific regulatory enforcement timelines and greenfield licensing activity. CAGRs were derived from installed base replacement cycles and capacity expansion announcements across the analysis window. Forecast inputs incorporated energy recovery economics, roll material spot price indices, and automotive surface-quality mandate diffusion rates.
Inputs from steelworks maintenance records and component supplier order books were available through the study window; gaps in real-time electromechanical retrofit deployment rates introduce uncertainty bands around displacement speed assumptions. Forecasts reflect documented regulatory compliance deadlines and capital depreciation schedules. Commodity price volatility in specialty alloy feedstock, tariff regime shifts on precision electronics, and automotive demand cyclicality could revise trajectory assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
East Africa Elevator and Escalator Market
Material Handling Equipment
Industrial Hose Assemblies Market
Material Handling Equipment
Europe Conveyors Market
Material Handling Equipment
Conveyors and Belt Loaders Market
Material Handling Equipment
Robotic Palletizers and De-Palletizers Market
Material Handling Equipment
Belt Weigh Feeder Market
Material Handling Equipment
Elevator Component Market
Material Handling Equipment
Resistance Welding Products Market
Material Handling Equipment
Firewood Processors Market
Material Handling Equipment
Jaw Crushers Market
Material Handling Equipment
Portable Loading Ramps Market
Material Handling Equipment
Copper and Aluminum Welding Bar Market
Material Handling Equipment
Global Linear Guide Market
Material Handling Equipment
Forklift Tire Market
Material Handling Equipment
Floor Scrubber Machine Market
Material Handling Equipment
Level Loader Market