
 Suction Excavator Market | 2026-2036
Suction Excavator Market Size, Share, and Industry Trends Forecast 2026-2036
Suction Excavator Market Analysis
German equipment engineering is shifting toward higher-capacity vacuum systems for urban utility networks. Vac-Con leverages vertical integration in blower manufacturing to control component quality. Vermeer Corporation anchors North American distribution through dealer density in the Midwest and Sun Belt. Kaiser AG specializes in compact chassis configurations tailored to narrow European streets.
A suction excavator deploys high-velocity air or water streams to loosen soil while a vacuum system conveys debris into a sealed tank, typically operating at airflow rates exceeding 15,000 cubic feet per minute and vacuum levels reaching 28 inches of mercury for non-destructive excavation around buried infrastructure. The equipment serves primarily to expose utilities without mechanical contact, eliminating strike damage to gas lines, fiber optic cables, and electrical conduits. Hydraulic systems occupy the largest installed base among product types due to proven power density in heavy-duty construction applications, while electric variants are gaining traction fastest in European municipalities with carbon reduction mandates. Contractors dominate end user demand volume, though rental services are expanding fleet share as project-based procurement replaces capital ownership.
OSHA excavation safety standards and EPA emissions regulations in the United States shape equipment specifications, compelling manufacturers to integrate Tier 4 Final engines and certified protective systems. The EU Green Deal and F-Gas Regulation in Europe are accelerating electric drivetrain development and refrigerant transitions in auxiliary climate systems. Stakeholders must monitor how municipal procurement codes evolve to prioritize low-emission equipment in urban contracts.
Market Dynamics
Municipal fleet procurement in Germany and the United Kingdom is pivoting toward electric suction excavators as urban emission zones tighten and underground utility density accelerates damage-risk premiums for mechanical excavation methods.
Growth Catalysts
- EU Green Deal carbon mandates:Western European cities now embed low-emission equipment requirements into municipal tender documents, redirecting capital toward electric drivetrain configurations.
- OSHA excavation safety standards:Underground damage prevention protocols in the United States are compelling contractors to replace backhoes with non-destructive vacuum systems for utility exposure work.
- Fiber optic cable deployment:Telecommunications infrastructure rollouts across urban cores are generating sustained demand for precision excavation around delicate buried networks.
Market Restraints
- High-pressure blower supply concentration:Specialized vacuum blower manufacturing clusters in Germany and Italy create single-source vulnerability for chassis integrators elsewhere.
- Battery energy density limitations:Electric suction excavators face operational range constraints on all-day municipal shifts, compressing addressable use cases.
- REACH compliance costs:European chemical registration requirements for hydraulic fluids and refrigerants inflate auxiliary system engineering expenses.
Strategic Opportunities
- India smart city infrastructure:Urban utility modernization programs in Mumbai and Delhi present untapped demand for compact chassis configurations suited to narrow colonial-era street grids.
- CSRD disclosure requirements:Corporate sustainability reporting mandates are pushing rental fleet operators to upgrade toward measurable emission-reduction equipment.
- Telematics-integrated predictive maintenance:Convergence of IoT sensors and vacuum system diagnostics enables outcome-based service contracts displacing traditional break-fix arrangements.
Industry Challenges
- Certified vacuum technician scarcity:Specialized training for high-velocity airflow system maintenance lags fleet expansion in North American rental channels.
- Tier 4 Final engine integration complexity:Emissions after-treatment systems for hydraulic variants require reconfigured chassis packaging, extending product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Suction Excavator Market |
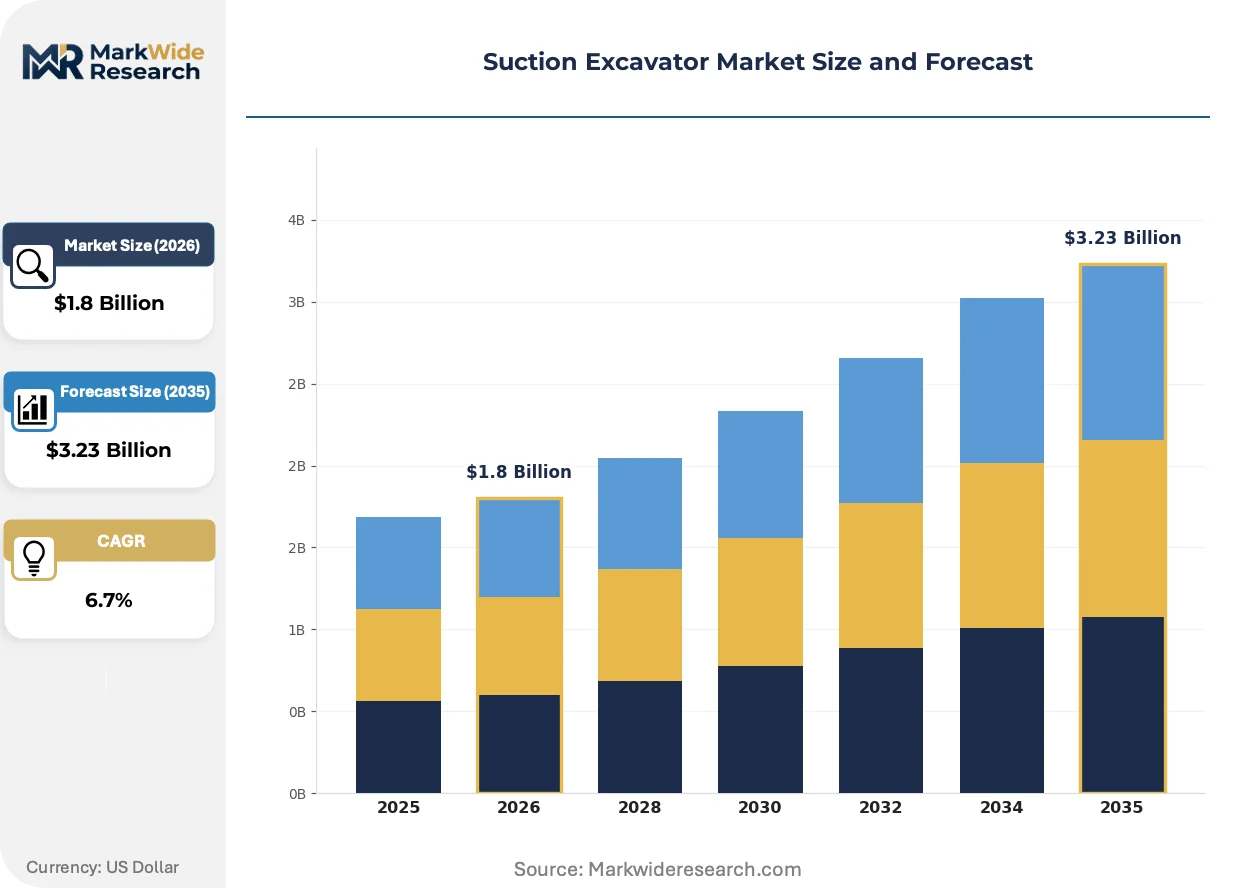
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Construction, Utility Installation, Road Maintenance, Environmental Cleaning Product Type: Hydraulic, Pneumatic, Electric, Compact End User: Municipalities, Contractors, Rental Services, Oil & Gas Technology: Vacuum, Water Jet, Hybrid, Traditional |
| Companies Covered | Vac-Con, Vermeer Corporation, Ditch Witch, Vactor Manufacturing, Federal Signal, GapVax, Vacall Industries, Kaiser AG, Super Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Suction Excavator Market Emerging Trajectories
Equipment specification is splitting along operational intensity lines, with electric systems capturing municipal maintenance cycles while hydraulic platforms retain dominance in emergency response and heavy soil conditions.
High-capacity lithium-ion battery packs are expanding into suction excavator prime mover applications, replacing diesel gensets in continuous-duty urban utility work. German municipal fleets in Stuttgart and Munich are deploying these configurations for scheduled maintenance windows. The technology is expanding into rental fleet procurement criteria as emission-zone compliance becomes a contract eligibility gate.
F-Gas Regulation refrigerant phase-down schedules are forcing auxiliary climate system redesigns across European-manufactured equipment. Compressor manufacturers must validate alternative working fluids without sacrificing vacuum pump thermal management. Compact chassis specialists in Switzerland and Austria are accelerating R-513A and R-1234yf transitions ahead of 2027 quota reductions.
Rental channel consolidation is compressing equipment procurement decision cycles, with national fleet managers centralizing specification authority previously held by regional branches. Independent dealers in the US Sun Belt are losing configuration influence to corporate procurement teams. This concentration is most visible in Texas and Florida, where hurricane-response fleet standardization now overrides local preference for hydraulic versus electric platforms.
Suction Excavator Market Segmentation
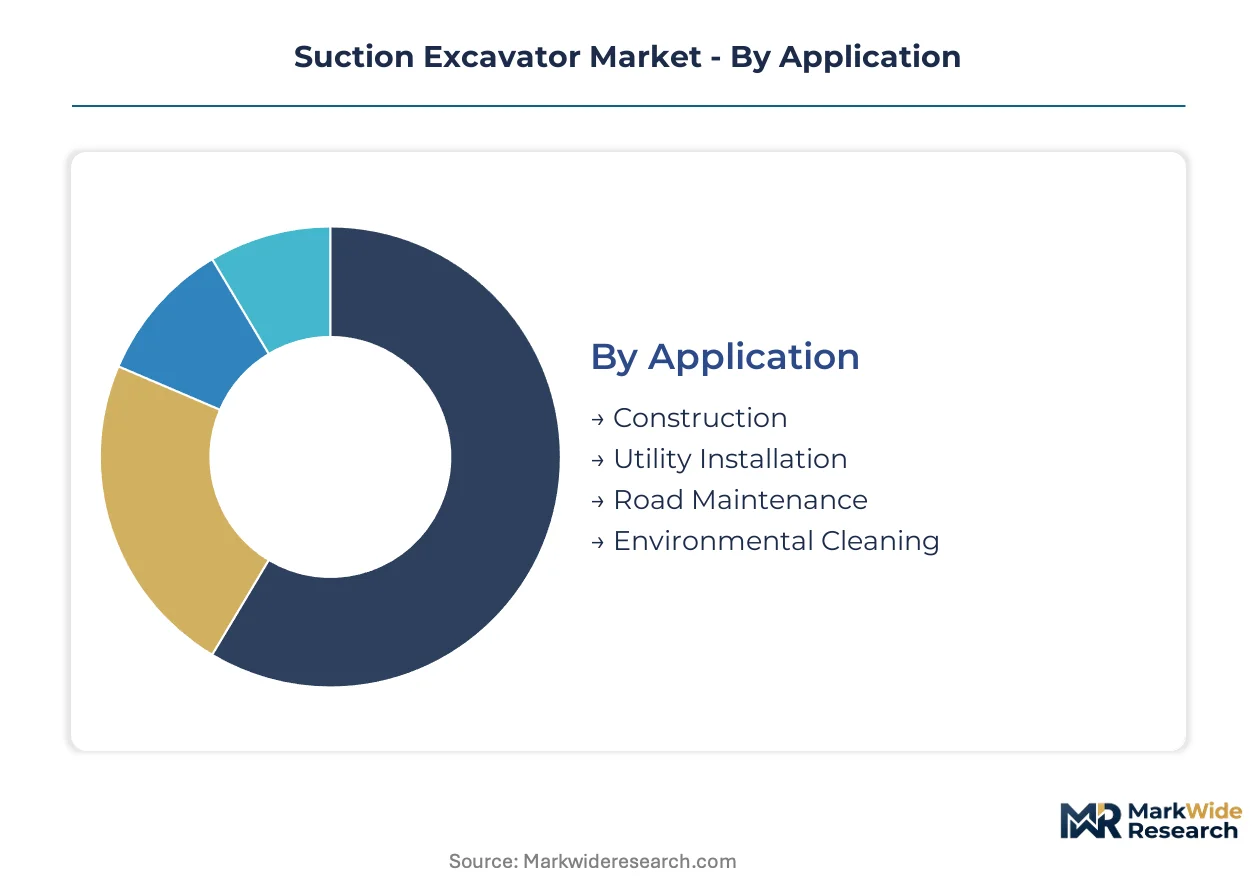
Suction excavator demand fragments across operational intensity levels, with specification diverging sharply between scheduled urban maintenance and emergency response scenarios. Procurement patterns within each segment reveal distinct equipment lifecycles, financing structures, and regulatory compliance thresholds that reshape vendor positioning.
Application:
Supply concentration among German blower manufacturers directly shapes which application segments gain priority access to high-performance vacuum systems during capacity-constrained periods.
- Construction:Heavy-duty soil removal around commercial foundations and structural footings demands airflow rates exceeding 18,000 cubic feet per minute. Contractors in Texas and Florida hurricane-response zones specify hydraulic platforms for all-day operation in compacted clay conditions.
- Utility Installation:Precision exposure of gas lines and fiber optic cables without mechanical contact drives specification toward compact electric configurations. Stuttgart and Munich municipal fleets deploy these systems for scheduled maintenance windows within tightening emission zones.
- Road Maintenance:Pothole repair and drainage clearing in narrow European street grids favors compact chassis with sub-7.5 ton gross vehicle weight ratings.
- Environmental Cleaning:Contaminated soil removal and spill response applications require sealed tank systems with hazardous material certification.
Today's leader: Construction. Tomorrow's challenger: Utility Installation.
Product Type:
Cost tier separation between hydraulic and electric platforms widens as battery pack scale economies advance, compressing mid-range specification space.
- Hydraulic:Diesel-powered systems with Tier 4 Final after-treatment retain dominance in emergency response and heavy soil conditions. The installed base across North American rental channels remains weighted toward this configuration despite emission compliance complexity.
- Electric:Lithium-ion prime mover systems are climbing the fastest in Western European municipal procurement, with battery energy density limitations constraining operational range on extended shifts. EU Green Deal carbon mandates embed low-emission requirements into tender documents.
- Pneumatic:Compressed air-driven units serve confined space applications where combustion risk prohibits internal combustion engines.
- Compact:Narrow chassis configurations tailored to colonial-era street grids in Mumbai and Delhi address smart city infrastructure modernization programs.
Today's leader: Hydraulic. Tomorrow's challenger: Electric.
End User:
Customer type determines financing structure, with rental services compressing procurement decision cycles through centralized fleet management.
- Municipalities:Scheduled maintenance cycles and emission-zone compliance requirements drive specification toward electric drivetrains with telematics integration. German and United Kingdom fleet expansion for utility installation work concentrates demand in compact configurations.
- Contractors:Project-based procurement patterns favor hydraulic platforms for operational flexibility across variable soil conditions. OSHA excavation safety standards compel vacuum system adoption for utility exposure work.
- Rental Services:National fleet managers in Texas and Florida now override regional branch preferences for hurricane-response standardization.
- Oil & Gas:Pipeline maintenance and facility decommissioning applications require explosion-proof configurations for hazardous area classification.
Today's leader: Contractors. Tomorrow's challenger: Rental Services.
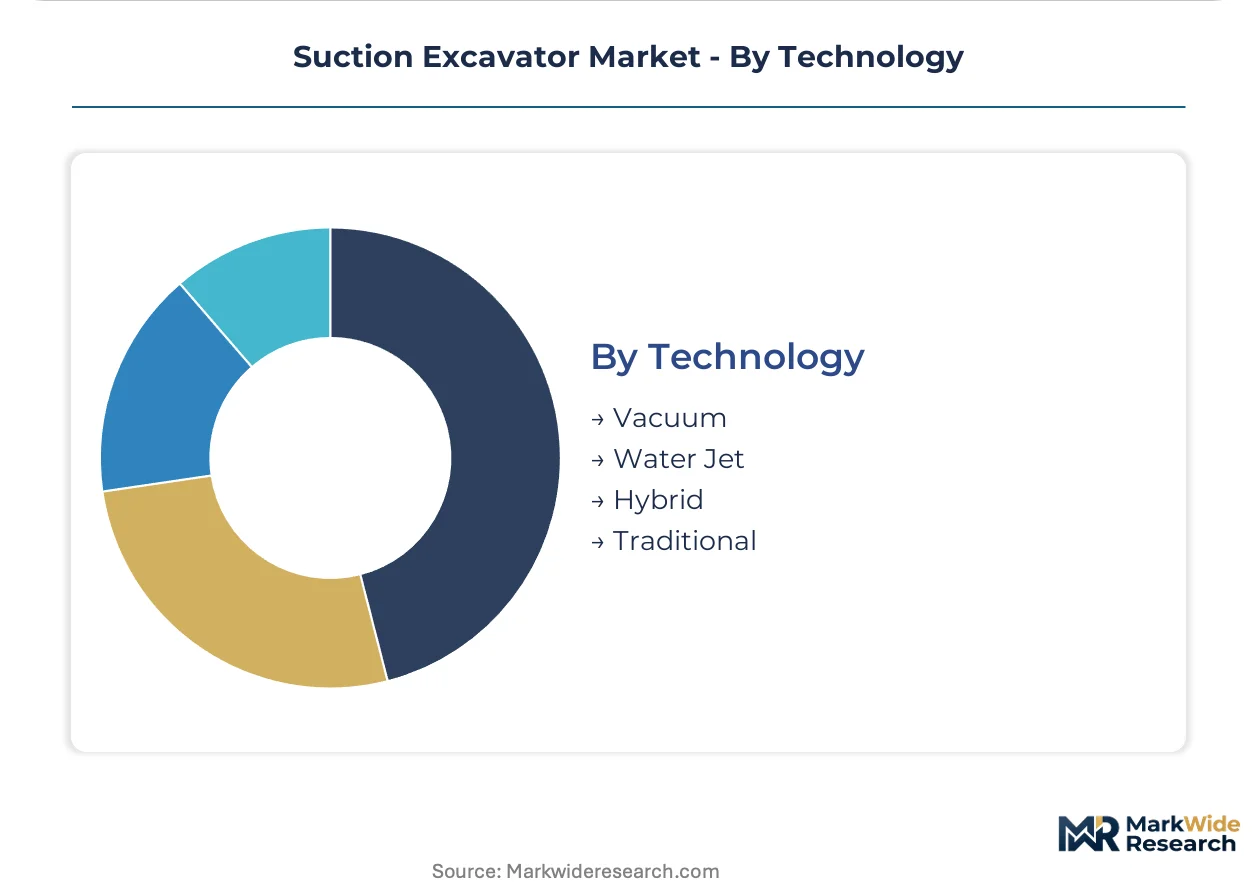
Technology:
Volume concentration in vacuum-based systems creates margin pressure on hybrid and water jet alternatives seeking differentiation.
- Vacuum:High-velocity airflow systems operating at 28 inches of mercury vacuum levels constitute the dominant installed base. F-Gas Regulation refrigerant phase-down schedules force auxiliary climate system redesigns across European-manufactured equipment.
- Water Jet:Pressurized water stream loosening serves cohesive soil conditions where air displacement proves insufficient. Water recovery and treatment requirements inflate operational complexity.
- Hybrid:Dual-mode systems switching between vacuum and water jet operation address variable subsurface conditions without equipment changeout.
- Traditional:Mechanical excavation methods face replacement pressure from OSHA underground damage prevention protocols and utility strike risk premiums.
Today's leader: Vacuum. Tomorrow's challenger: Hybrid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands higher specification standards than the United States, where OSHA-driven safety compliance accelerates fleet turnover without matching European emission stringency.
Germany
Municipal fleets in Stuttgart and Munich drive electric suction excavator procurement for scheduled utility maintenance within tightening urban emission zones. The EU Green Deal embeds low-emipment equipment requirements into federal tender documents, redirecting capital toward lithium-ion drivetrains. Baden-Württemberg engineering clusters specialize in high-capacity vacuum blower systems for chassis integrators.
United States
Contractors across Texas and Florida hurricane-response zones specify hydraulic platforms for all-day operation in compacted clay conditions. OSHA excavation safety standards compel vacuum system adoption for utility exposure work, replacing mechanical digging methods. Midwest dealer density anchors North American distribution networks for rental channel consolidation.
United Kingdom
Urban utility density in London and Birmingham accelerates damage-risk premiums for mechanical excavation, redirecting municipal investment toward compact electric configurations. The CSRD disclosure requirements push rental fleet operators toward measurable emission-reduction equipment upgrades. Scottish infrastructure programs test narrow chassis systems for colonial-era street grid compatibility.
India
Smart city modernization in Mumbai and Delhi generates demand for compact chassis configurations suited to narrow street grids and dense buried infrastructure. The country's national urban development regulator prioritizes non-destructive excavation methods for fiber optic cable deployment. Maharashtra and Gujarat municipal corporations pilot vacuum systems for utility installation in high-congestion corridors.
Switzerland
Alpine tunnel maintenance and precision utility work in Zurich and Geneva favor compact electric systems with sub-7.5 ton gross vehicle weight ratings. The F-Gas Regulation accelerates R-513A refrigerant transitions in auxiliary climate systems ahead of quota reductions. Swiss manufacturing clusters specialize in narrow chassis engineering for constrained European urban cores.
Suction Excavator Market Vendor Landscape
German producers anchor the high-specification tier; North American specialists hold volume positions in rental channel distribution. Market structure concentrates around blower manufacturing expertise and chassis integration capability, with three strategic archetypes dominating: vertically integrated vacuum system manufacturers, compact chassis specialists, and rental fleet service providers. Competitive moves center on electric drivetrain development partnerships and telematics-integrated predictive maintenance service contracts.
Within the integrated manufacturing tier, Vac-Con exemplifies upstream control over blower component quality, while Vermeer Corporation occupies a position in North American distribution density. Kaiser AG represents the compact chassis specialization for narrow European street applications. These three anchors illustrate how geographic origin and structural configuration shape competitive positioning without requiring uniform strategic approaches across product categories.
| Leading Market Players |
|---|
| Vac-Con |
| Vermeer Corporation |
| Ditch Witch |
| Vactor Manufacturing |
| Federal Signal |
| GapVax |
| Vacall Industries |
| Kaiser AG |
| Super Products |
| Others |
Supply Flow & Price Mechanics
EU Green Deal carbon mandates gate qualified supply and premium-tier pricing access by restricting municipal tender eligibility to electric drivetrain configurations certified for urban emission zones. German and Swiss manufacturers command pricing power through captive vacuum blower production, while chassis integrators elsewhere absorb margin compression from single-source component dependencies.
Pricing Analysis
Capacity additions in Baden-Württemberg and Bavaria are reshaping price floors for high-capacity vacuum systems as localized blower manufacturing expands. Three-tier pricing structure across premium, standard, and economy levels separates Tier 4 Final hydraulic platforms from lithium-ion electric configurations and compact pneumatic units. Price differentiation hinges on certification grade for F-Gas Regulation compliance and after-sales service bundling. Cost compression in mid-range hydraulic tiers is intensifying because rental channel consolidation centralizes procurement authority. Municipal fleet managers exhibit lowest price sensitivity due to emission-zone compliance mandates, while independent contractors in North American Sun Belt markets show highest sensitivity to upfront capital outlays.
Supply Chain Analysis
Certified vacuum technician scarcity in German and Italian manufacturing clusters constrains output scaling for chassis integrators in North America and India. Component manufacturing concentrates in Germany, Italy, and Switzerland, with high-pressure blowers, lithium-ion battery packs, and compact chassis frames as critical inputs. Single-source vulnerability in specialized blower engineering creates supply chain risk for equipment assemblers outside Western Europe. Distribution runs through rental fleet operators and municipal procurement departments, with national fleet managers in Texas and Florida overriding regional branch preferences for hurricane-response standardization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU emission stringency creates premium pricing in Stuttgart and Munich while OSHA-driven safety compliance in Texas and Florida sustains volume demand without matching carbon mandates.
For Market Incumbents: To counter battery energy density limitations compressing electric platform addressable use cases, deepen backward integration into blower manufacturing to control component quality and certification timelines. Prioritize capacity addition in Switzerland for compact chassis configurations serving narrow European street grids, anchoring premium positioning through F-Gas Regulation pre-compliance. For New Entrants and Emerging Players: Capture utility installation demand in Mumbai and Delhi smart city corridors where colonial-era street grids favor sub-7.5 ton gross vehicle weight configurations underserved by incumbent chassis specialists. Deploy telematics-integrated predictive maintenance as a service-layer wedge, displacing traditional break-fix arrangements in North American rental channels. For Investors and Strategic Acquirers: Roll-up economics work for regional rental fleet operators because CSRD disclosure requirements force emission-reduction equipment upgrades across fragmented municipal customer bases. Five-to-ten year viability rests on consolidation of procurement authority previously held by branch-level decision makers. Watch for Tier 4 Final engine integration complexity extending product development cycles as an inflection signal for distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Drivetrain Partnership | Battery supply agreements with Stuttgart engineering clusters accelerate EU Green Deal compliance timelines. |
| Telematics Platform Integration | IoT sensor convergence enables outcome-based service contracts displacing traditional maintenance arrangements. |
| Compact Chassis Manufacturing Scale-Up | Sub-7.5 ton configurations address Mumbai and Delhi smart city infrastructure modernization programs. |
| Backward Integration into Blower Production | In-house vacuum system manufacturing reduces single-source vulnerability from German and Italian supply concentration. |
| CSRD-Aligned Fleet Upgrade Program | Measurable emission-reduction equipment positioning captures rental channel consolidation procurement authority. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with municipal fleet managers, rental service procurement heads, OEM chassis integrators, and vacuum system maintenance technicians with secondary validation from customs trade data, EU tender documentation databases, OSHA compliance filings, and SEC equipment manufacturer disclosures. Bottom-up equipment shipment tracking and top-down municipal capital expenditure analysis provided triangulation across modeling approaches.
Comparable historical reference periods anchored growth trajectory assumptions across the projection horizon, with segmentation modeling across product type, application intensity, end-user financing structure, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis, fleet expansion patterns, and emission mandate implementation timelines. Forecast inputs incorporated battery energy density improvement curves and F-Gas Regulation phase-down schedules affecting auxiliary climate system specifications.
Underlying measurement precision varies by segment; electric drivetrain adoption rates in German municipal fleets carry tighter precision than emerging market penetration assumptions. Forecasts reflect documented assumptions regarding OSHA enforcement intensity and EU Green Deal tender compliance thresholds. Material deviation in battery cost reduction curves or REACH hydraulic fluid registration timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Construction Camera [Time Lapse Camera] Market
Construction Equipment
Excavation Equipment Market
Construction Equipment
Gear Grinding Machine Market
Construction Equipment
Hybrid Construction Equipment Market
Construction Equipment
Middle East and Africa Construction Equipment Market
Construction Equipment
Heavy Construction Equipment Market
Construction Equipment
Dust Suppression Fog Cannon Market
Construction Equipment
South Korea Heavy Construction Equipment Rental Market
Construction Equipment
Cold Planers Market
Construction Equipment
Asia Pacific Construction Equipment Rental Market
Construction Equipment
Tunnel Boring Machines Market
Construction Equipment
Skid Steer Loader Market
Construction Equipment
Rotomolding Market
Construction Equipment
Fixed Crane Market
Construction Equipment
North America and Europe Snow Blowers Market
Construction Equipment
Concrete Chain Saw Market