
 Asia-Pacific Completion Equipment and Services Market | 2026-2036
Asia-Pacific Completion Equipment and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Completion Equipment and Services Market Outlook
Higher-pressure rating specifications for subsea completions is rotating procurement standards across the Asia-Pacific basin. Schlumberger Ltd anchors its regional position through integrated project management capabilities across deepwater fields off Australia and Malaysia. Halliburton Company leverages localized manufacturing partnerships to sustain cost competitiveness in Indonesia's maturing offshore blocks. Baker Hughes Company differentiates through advanced metallurgy R&D for high-temperature reservoirs in the Gulf of Thailand.
Completion equipment and services encompass the engineered systems and specialized operations required to prepare a drilled well for hydrocarbon production, including packers rated for specific pressure differentials, perforating guns designed for precise tunnel geometry, and intelligent completion technologies that enable real-time zonal control. These systems serve the fundamental purpose of establishing safe, efficient flow paths from reservoir to surface while enabling operators to monitor and manage production across multiple zones. Packers and intelligent completion systems command the strongest margin pools as operators prioritize reservoir management precision over commodity hardware. Tubing and cementing services remain volume-heavy segments where scale and logistics execution determine competitive outcomes.
China's NMPA enforces equipment certification standards that constrain market access for uncertified completion hardware, while Australia's NOPSEMA offshore safety framework elevates technical documentation requirements for subsea installations. India's CEA and petroleum ministry directives on domestic content thresholds shape procurement patterns for state-affiliated exploration companies. Stakeholders must weigh regulatory compliance investments against the margin compression risk in standardized service segments.
Market Dynamics
Higher-pressure subsea completion specifications are rotating procurement standards across Asia-Pacific basins as operators push equipment ratings beyond 15,000 psi to access deeper reservoirs. This technical escalation is compressing margins for standardized hardware while concentrating value in specialized metallurgy and intelligent monitoring systems.
Growth Catalysts
- Australia's offshore safety framework:NOPSEMA's elevated technical documentation requirements for subsea installations are forcing operators to upgrade completion hardware, creating replacement demand across mature Bass Strait fields.
- Deepwater expansion in Malaysia and Indonesia:National oil companies are awarding integrated service contracts for high-pressure high-temperature wells, pulling advanced completion technologies into Southeast Asian waters.
- China's dual carbon mandates:Beijing's emissions targets are accelerating gas field development, requiring certified completion equipment for sour service environments in Sichuan and South China Sea blocks.
Market Restraints
- Specialized alloy supply concentration:Super duplex stainless steel and Inconel sourcing remains concentrated among Japanese and European mills, exposing contractors to nickel price volatility and extended lead times.
- NMPA certification friction:China's national medical products administration extends equipment approval timelines by 12-18 months for uncertified foreign packer and perforating gun manufacturers.
- Subsea installation vessel scarcity:Heavy-lift capability for deepwater tree installations concentrates among Singapore and South Korean yards, creating queue bottlenecks during campaign windows.
Strategic Opportunities
- India's domestic content thresholds:CEA and petroleum ministry directives on local value-add create openings for joint ventures with Indian fabrication yards serving ONGC and Oil India deepwater programs.
- Intelligent completion convergence:Integration of fiber-optic sensing with remotely operated zonal control valves enables real-time reservoir management in Australia's remote offshore basins.
- Vietnam's emerging blocks:Underexplored Cuu Long and Nam Con Son basins offer first-mover positioning for contractors willing to pre-position equipment ahead of licensing rounds.
Industry Challenges
- High-temperature metallurgy expertise gap:Gulf of Thailand operators struggle to source completion engineers with experience above 350°F reservoir conditions, slowing project execution.
- Legacy wellhead integration complexity:Brownfield tiebacks in Indonesia's mature Mahakam block require custom adapter systems that extend engineering cycles and compress project returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Completion Equipment and Services Market |
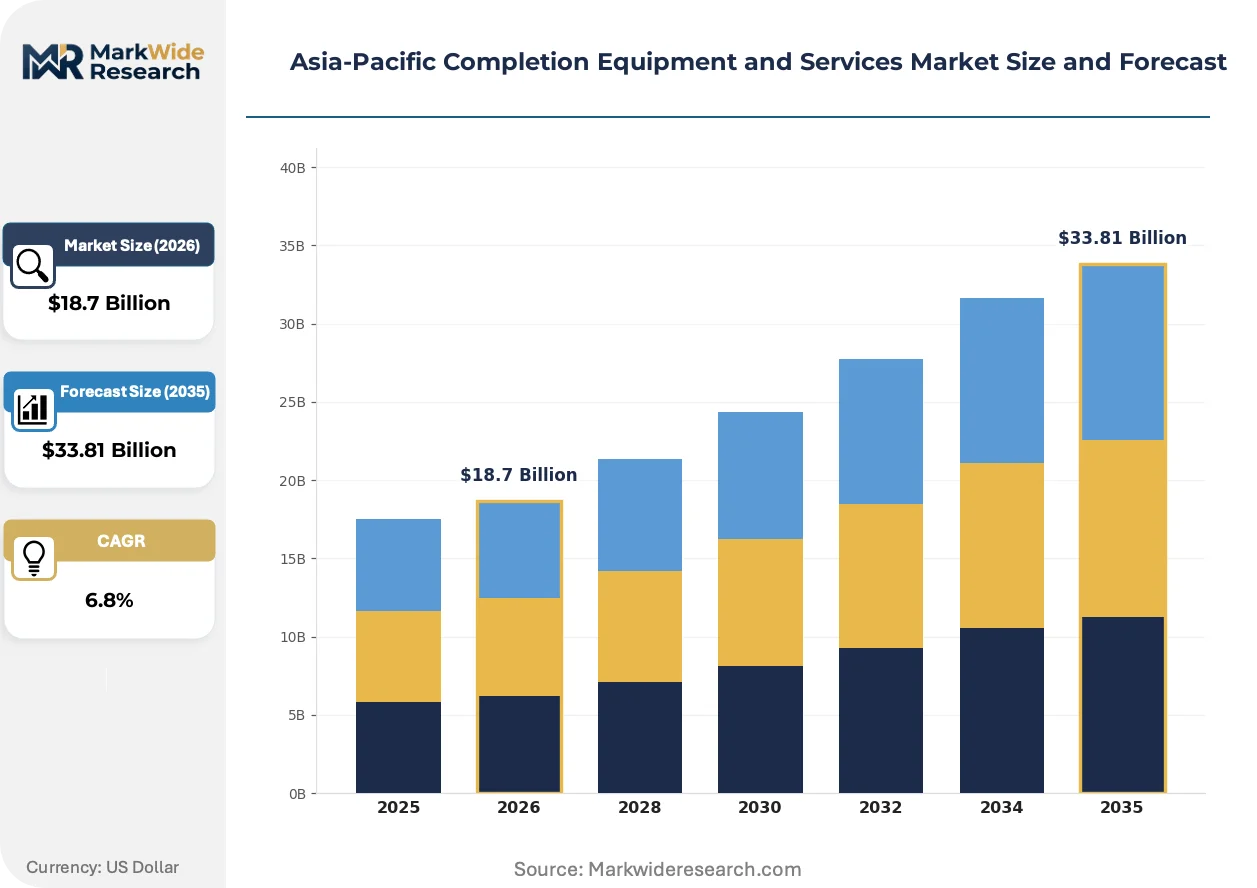
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Packers, Tubing, Perforating Systems, Valves Service Type: Well Testing, Completion Installation, Coiled Tubing, Cementing Services End User: Exploration Companies, Oil & Gas Producers, Service Providers, Government Agencies Technology: Smart Wells, Intelligent Completion, Hydraulic Systems, Offshore Technologies |
| Companies Covered | Schlumberger Ltd, Halliburton Company, Baker Hughes Company, Weatherford International plc, China Oilfield Services Ltd, National Oilwell Varco, TechnipFMC, OEG Offshore, Oceaneering International, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Completion Equipment and Services Market Strategic Shifts
Digitalization of reservoir monitoring is decomposing traditional service boundaries between completion hardware and production optimization software. Operators now demand integrated packages that combine physical packer systems with real-time analytics, forcing contractors to restructure technical capabilities and partnership networks.
Modular subsea tree architectures are decomposing conventional integrated system procurement. Australian independents now specify plug-and-play wellhead modules that separate production, injection, and monitoring functions, enabling phased field development and reducing initial capital exposure. Suppliers must reconfigure manufacturing lines to produce interchangeable cartridge assemblies rather than monolithic assemblies.
China's NMPA equipment certification requirements are tightening product standards across the region. Foreign completion hardware manufacturers must submit extensive metallurgical testing documentation and maintain local quality representatives, raising compliance costs but creating competitive moats for certified suppliers. Australian and Malaysian operators increasingly specify NMPA-equivalent documentation even where not legally required, harmonizing procurement standards upward.
Integrated service contracting is displacing discrete equipment purchasing in Southeast Asian deepwater projects. National oil companies in Malaysia and Indonesia now bundle engineering, procurement, and installation under single-source agreements, compressing the vendor base and favoring contractors with project management capabilities over pure equipment manufacturers. This concentration is most visible in Sarawak's gas development campaigns where lump-sum turnkey contracts dominate.
Asia-Pacific Completion Equipment and Services Market Segmentation
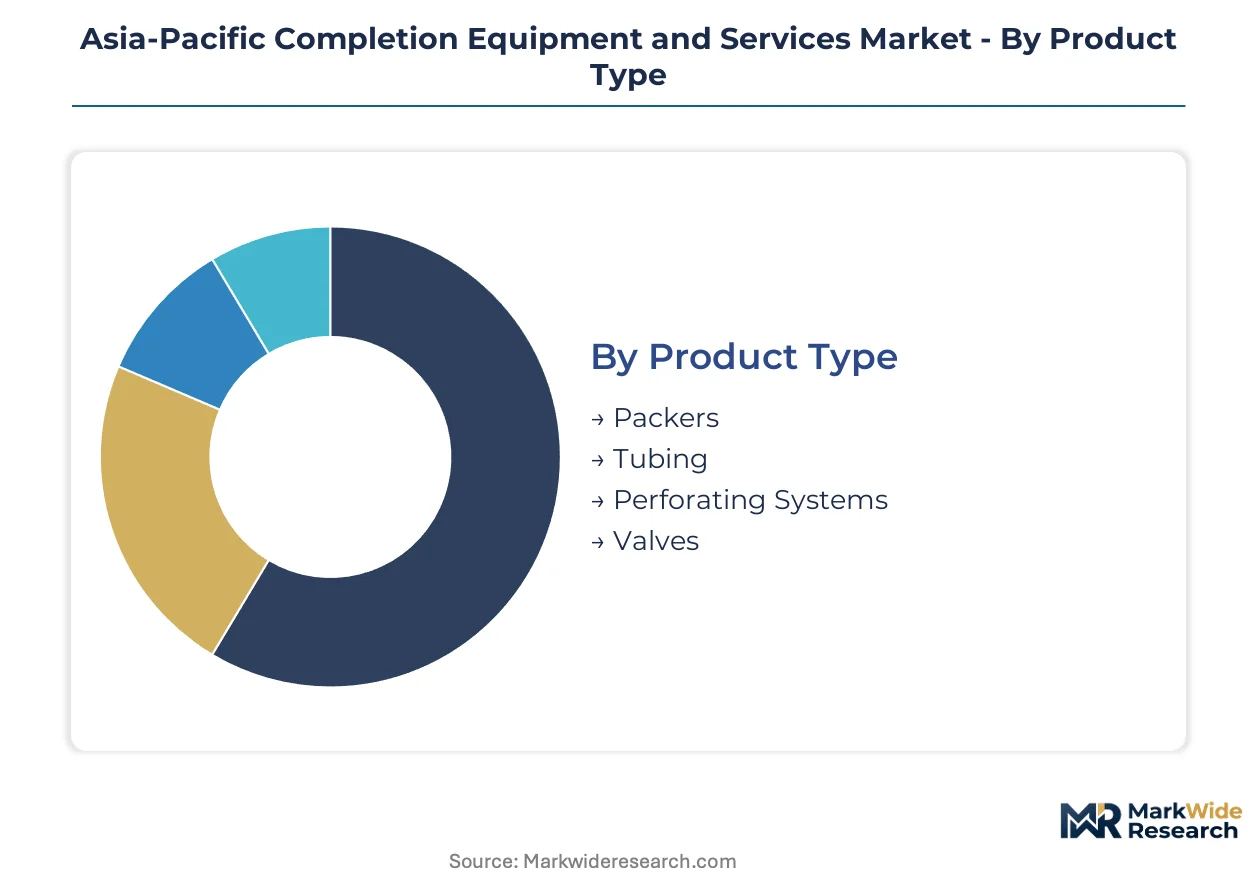
Completion equipment and services segmentation in Asia-Pacific reflects divergent procurement pressures across regulatory regimes. NMPA certification requirements in China, NOPSEMA documentation standards in Australia, and CEA domestic content rules in India each reshape how vendors configure product portfolios and service bundles.
Product Type:
Regulatory differentiation across Asia-Pacific basins elevates certain hardware categories above commodity status. NMPA and NOPSEMA documentation requirements disproportionately burden packer and valve systems, while tubing faces lighter compliance loads.
- Packers:Sealing devices engineered for specific pressure differentials and temperature envelopes, manufactured from super duplex stainless steel or Inconel alloys. Demand concentrates in Australia's Bass Strait fields where NOPSEMA mandates replacement of legacy subsea installations, though Japanese and European mill sourcing creates nickel price exposure for contractors.
- Valves:Zonal isolation and flow control mechanisms including remotely operated subsea gate valves and surface safety valves. Malaysian and Indonesian deepwater projects specify 15,000+ psi ratings, pulling advanced metallurgy R&D into Southeast Asian procurement standards.
- Tubing:Conduit systems connecting reservoir to surface facilities, available in carbon steel and corrosion-resistant alloy grades. Sichuan basin sour service environments drive certified material specifications under China's dual carbon mandates.
- Perforating Systems:Shaped charge assemblies for precise tunnel geometry creation through casing and cement. Mahakam block brownfield tiebacks require custom adapter integration with legacy wellheads.
Established volume favors tubing; emerging adoption favors intelligent packer systems with real-time monitoring capabilities.
Service Type:
Service bundling patterns track offshore project complexity and vessel availability constraints. Heavy-lift installation vessel scarcity in Singapore and South Korean yards shapes how operators structure completion campaigns.
- Completion Installation:Integrated engineering, procurement, and installation of subsea trees, wellheads, and production control systems. Sarawak gas development campaigns favor lump-sum turnkey contracts that compress the vendor base.
- Cementing Services:Annular isolation and zonal barrier placement using specialized slurry formulations. Gulf of Thailand high-temperature reservoirs above 350°F strain regional technical expertise pools.
- Well Testing:Reservoir characterization through controlled flow measurement and pressure transient analysis. Australia's remote offshore basins drive demand for portable testing packages.
- Coiled Tubing:Continuous conduit intervention for wellbore cleanout, stimulation, and plug setting. Indonesia's maturing offshore blocks sustain volume through workover campaigns.
Discrete service purchasing dominates cementing; integrated contracting is displacing standalone installation procurement in deepwater.
End User:
Customer type determines pricing leverage and contract structure across Asia-Pacific markets. State-affiliated exploration companies operate under distinct procurement frameworks compared with international independents.
- Oil & Gas Producers:Operating companies holding production licenses and reservoir development rights. Australian independents specify modular subsea tree architectures that separate production, injection, and monitoring functions.
- Exploration Companies:License holders focused on frontier basin appraisal and greenfield discovery. Vietnam's Cuu Long and Nam Con Son basins attract first-mover positioning from contractors pre-positioning equipment.
- Service Providers:Contract drilling and field service companies subcontracting completion activities. Localized manufacturing partnerships in Indonesia sustain cost competitiveness for Halliburton's regional operations.
- Government Agencies:National oil companies and petroleum ministry directorates setting procurement policy. India's CEA and petroleum ministry domestic content thresholds shape ONGC and Oil India deepwater programs.
International producers drive specification intensity; government agencies drive localization requirements.
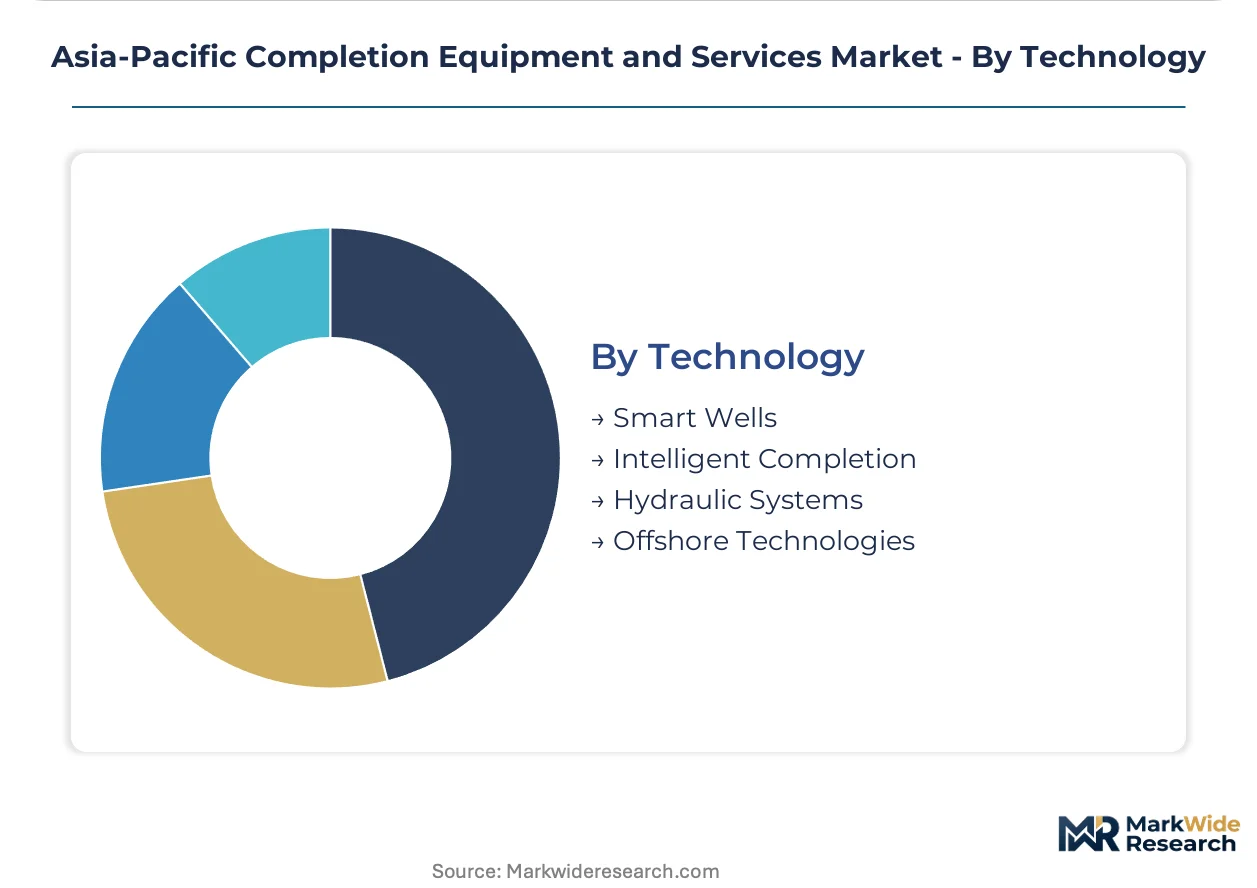
Technology:
Technology segmentation captures the convergence of physical hardware and digital capability. Fiber-optic sensing integration with zonal control valves decomposes traditional service boundaries.
- Intelligent Completion:Systems combining downhole sensors, remotely operated valves, and surface control infrastructure for real-time reservoir management. Australia's remote offshore basins favor this technology where platform access is limited.
- Smart Wells:Instrumented completions with permanent downhole monitoring and autonomous flow optimization. Malaysia's national oil company bundles these under integrated service contracts.
- Offshore Technologies:Subsea-specific hardware including subsea trees, manifolds, and tieback systems. Queue bottlenecks at Singapore and South Korean heavy-lift yards constrain campaign timing.
- Hydraulic Systems:Pressure-actuated completion tools including setting tools and circulating devices. Standardized hardware faces margin compression as operators prioritize intelligent alternatives.
Hydraulic systems anchor current installed base; intelligent completion is climbing the fastest as operators demand production optimization software integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's heavy-lift yards export subsea installation capacity to Australian and Malaysian operators, creating a regional service corridor that shapes campaign timing across Southeast Asian waters.
Australia
Bass Strait field replacement demand and remote offshore basin development drive specification intensity for intelligent completion systems. NOPSEMA's technical documentation requirements force hardware upgrades across mature installations. Perth anchors engineering design activity for subsea projects spanning the North West Shelf and Browse Basin.
China
Sichuan basin sour service environments and South China Sea gas field development accelerate certified equipment procurement. NMPA equipment certification extends approval timelines for foreign packer manufacturers. Shenzhen and Shanghai host quality representative offices serving dual carbon mandate compliance.
Malaysia
Deepwater high-pressure high-temperature well campaigns pull advanced metallurgy into Sarawak gas developments. Petronas awards integrated service contracts bundling engineering and installation. Kuala Lumpur concentrates project management capabilities for lump-sum turnkey structures.
Indonesia
Mahakam block brownfield tiebacks and maturing offshore workover campaigns sustain coiled tubing volume. Localized manufacturing partnerships reduce cost exposure in standardized segments. Jakarta and Balikpapan coordinate fabrication logistics for Java Sea and Kalimantan operations.
India
ONGC and Oil India deepwater programs create joint venture openings with domestic fabrication yards. CEA domestic content thresholds reshape procurement patterns for state-affiliated explorers. Mumbai and Visakhapatnam cluster subsea engineering capabilities serving east coast basins.
Asia-Pacific Completion Equipment and Services Market Competitive Environment
Listed leaders compete with private specialists across integrated service contracting, creating a tiered structure where scale and certification credentials determine access to national oil company frameworks. The vendor base concentrates around project management capabilities in deepwater and manufacturing partnerships in maturing basins. Three archetypes dominate: integrated technology providers, regional fabrication specialists, and equipment-certification-focused compliance players. M&A activity targets intelligent completion software assets, while strategic partnerships localize manufacturing to meet domestic content requirements.
Within the integrated service tier, Schlumberger Ltd and Halliburton Company represent archetypes of project management capability across Australian and Malaysian deepwater fields. Baker Hughes Company occupies a position emphasizing metallurgy specialization for high-temperature reservoirs. Weatherford International plc exemplifies the regional specialist model through localized execution networks. These three named entities anchor the competitive structure without exhausting its diversity.
| Leading Market Players |
|---|
| Schlumberger Ltd |
| Halliburton Company |
| Baker Hughes Company |
| Weatherford International plc |
| China Oilfield Services Ltd |
| National Oilwell Varco |
| TechnipFMC |
| OEG Offshore |
| Oceaneering International |
| Others |
Value Chain & Pricing Dynamics
Lump-sum turnkey contracts for Sarawak gas developments lock in supply access for heavy-lift installation capacity while capping price exposure for Malaysian national oil companies across campaign windows. This contracting architecture concentrates procurement power among integrated service providers who can reserve queue positions at Singapore and South Korean yards, compressing margins for equipment-only vendors unable to bundle installation.
Pricing Analysis
Next-generation intelligent completion systems command substantial premiums over hydraulic-actuated hardware, while prior-generation packer technologies face acute price erosion in standardized segments. Three-tier pricing structure across NMPA-certified premium, NOPSEMA-compliant standard, and economy-grade hydraulic tiers reflects documentation burden differentials. Cost compression in commodity tubing and cementing services is intensifying because Indonesian manufacturing partnerships enable localized cost structures. Exploration companies pre-positioning for Vietnam licensing rounds exhibit highest price sensitivity; Australian independents specifying modular subsea architectures show lowest.
Supply Chain Analysis
Strategic stockpiling of super duplex stainless steel and Inconel alloys dominates procurement behavior among Japanese and European mill customers, insulating against nickel price volatility that would disrupt campaign timing. Super duplex stainless steel and Inconel sourcing draws from concentrated Japanese and European mill bases, with titanium alloys for high-temperature valves increasingly sourced from Russian and Chinese suppliers. Single-source vulnerability around heavy-lift installation vessels at Singapore and South Korean yards creates queue bottlenecks during concentrated campaign windows. Distribution runs through engineering-procurement-installation contractors who bundle hardware with project management capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital platform convergence between physical completion hardware and production optimization software creates ecosystem lock-in effects, with fiber-optic sensing integration establishing interoperability standards that reshape competitive boundaries across Asia-Pacific basins.
For Market Incumbents: Consolidate project management capabilities around deepwater integrated service contracts in Malaysia and Indonesia, where Petronas bundling trends compress the vendor base. Acquire intelligent completion software assets to defend against pure-play digital entrants. Secure backward integration into super duplex alloy sourcing through offtake agreements with Japanese mills, mitigating nickel price volatility exposure that erodes lump-sum contract margins. For New Entrants and Emerging Players: Lead with NMPA certification investment as competitive moat for packer and valve entry into China's Sichuan basin sour service environments. Vietnam's Cuu Long and Nam Con Son basins represent the most penetrable geography for first-mover equipment pre-positioning ahead of licensing rounds. Partner with Indian fabrication yards to satisfy CEA domestic content thresholds for ONGC deepwater programs, converting compliance burden into channel access. For Investors and Strategic Acquirers: Capital is best deployed toward intelligent completion software specialists with fiber-optic sensing integration capabilities, as physical hardware margins compress and data-layer value concentrates. The 5-10 year viability window favors platforms combining downhole monitoring with surface analytics over pure equipment manufacturers. Watch for Petronas integrated contract award velocity as inflection indicator for vendor base consolidation pace across Southeast Asian deepwater.| Strategic Initiative | Industry Significance |
|---|---|
| Intelligent Completion Software Acquisition | Captures data-layer value as fiber-optic sensing displaces hydraulic actuation in Australian offshore basins. |
| NMPA Certification Investment | Creates regulatory moat for packer entry into China's dual carbon-mandated gas field developments. |
| Indian Fabrication Joint Venture | Converts CEA domestic content thresholds into channel access for ONGC deepwater program participation. |
| Super Duplex Alloy Offtake Agreement | Secures Japanese mill capacity against nickel volatility eroding lump-sum turnkey contract margins. |
| Vietnam Equipment Pre-positioning | Establishes first-mover presence in Cuu Long and Nam Con Son basins ahead of licensing rounds. |
Study Parameters
Initial hypotheses were tested against primary input from drilling contractors, subsea project managers, procurement leads at national oil companies, and metallurgical engineers at alloy mills, then refined through secondary validation. Completion equipment executives at integrated service providers, regulatory affairs specialists navigating NMPA and NOPSEMA frameworks, and fabrication yard operations heads in Singapore and South Korea contributed operational perspective. Secondary sources included customs trade data for alloy imports, petroleum ministry procurement disclosures, subsea installation vessel utilization databases, and SEC filings from listed service contractors. Bottom-up equipment demand estimates were triangulated against top-down exploration and production capex allocations.
Variance decomposition across pressure rating tiers, technology generations, and regulatory compliance clusters shaped the analytical framework over the projection horizon. Segmentation dimensions modeled encompass product type, service bundling structure, end-user procurement framework, and technology integration level, with country-specific regulatory regime as an additional industry-specific dimension. CAGRs were derived from equipment replacement cycles in mature Bass Strait fields, greenfield development timelines in Malaysian deepwater, and certification pipeline velocities for NMPA compliance. Forecast inputs included vessel queue bottlenecks at Singapore yards and nickel price volatility indices affecting alloy procurement.
The analysis sits within stated boundaries; outcomes outside sustained dual carbon mandate enforcement in China, continued Petronas integrated contracting preference, or stable heavy-lift vessel availability would require recalibration. Forecasts reflect documented assumptions about regulatory harmonization trends and national oil company procurement centralization. Revision becomes warranted when NMPA certification timeline extensions or subsea installation vessel capacity constraints cross thresholds that alter campaign economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
India Crane Market
Construction Equipment
Solid Control Equipment Market
Construction Equipment
Global Dragline Excavator Market
Construction Equipment
Global Wheel Trenchers Market
Construction Equipment
Welding and Cutting Equipment Market
Construction Equipment
Asia Pacific Construction Equipment Rental Market
Construction Equipment
Global Hydraulic Hammer Market
Construction Equipment
North America Crane Rental Market
Construction Equipment
Hydraulic Shearing Machine Market
Construction Equipment
Truck Crane Market
Construction Equipment
Rubber Track Pads for Construction Machinery Market
Construction Equipment
Asia-Pacific Mobile Light Tower Market
Construction Equipment
Hydraulic Intensifiers Market
Construction Equipment
India Construction Equipment Rental Market
Construction Equipment
United States Crane Market
Construction Equipment
Automatic Clay Brick Making Machine Market