
 Gear Honing Machines Market | 2026-2036
Gear Honing Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Gear Honing Machines Market Foresight
Premium CNC gear honing capability is decoupling from commodity manual finishing on price, throughput, and tolerance repeatability. KAPP NILES Group leverages its grinding-honing integration to dominate high-precision aerospace contracts. Liebherr Group anchors its position through captive gear production for wind turbine and construction equipment drivetrains. Gleason Corporation differentiates via its closed-loop measurement systems that reduce post-process inspection cycles.
Gear honing machines remove stock from hardened gear tooth flanks using abrasive stones mounted on a honing tool, achieving ISO 1328 grade 4-6 tolerances with surface finishes below Ra 0.4 micrometers to reduce noise and extend fatigue life in power transmission systems. Horizontal configurations lead in automotive volume applications where long shafts require through-pass processing, while CNC technology captures the fastest expansion as multi-axis interpolation replaces mechanical indexers for spiral bevel and helical gear forms. Abrasive technology remains the mature revenue base, though hybrid electrochemical-abrasive systems are emerging where heat-resistant superalloy gears demand minimal thermal damage layers.
ISO 6336 and AGMA 2001-D04 standards dictate allowable tooth bending stress and contact patterns that honing must preserve, while EPA Tier 4 and Euro 7 emissions frameworks indirectly tighten gear mesh efficiency requirements for engine and transmission builders. FDA medical device quality system regulations shape honing protocols for surgical robot and imaging equipment gear trains. Stakeholders should monitor how NIST advanced manufacturing grants and EU Green Deal industrial funding redirect capital toward energy-efficient machine tool platforms.
Market Dynamics
Precision tolerance compression from electric drivetrain manufacturers is forcing honing equipment suppliers to decouple mechanical indexers from multi-axis CNC architectures, fundamentally restructuring capital allocation toward closed-loop measurement integration.
Growth Catalysts
- EPA Tier 4 and Euro 7 emissions frameworks:Tighter gear mesh efficiency mandates push engine and transmission builders toward ISO 1328 grade 4-6 honing tolerances to minimize frictional losses.
- Electric vehicle drivetrain expansion:Automotive OEMs require precision-finished gears for high-speed reduction stages in battery-electric powertrains, concentrating demand around Stuttgart and Munich machine tool clusters.
- Hybrid electrochemical-abrasive technology:Heat-resistant superalloy gears for aerospace applications demand minimal thermal damage layers, opening adoption paths beyond conventional abrasive systems.
Market Restraints
- Abrasive stone supply concentration:Premium synthetic diamond and CBN honing stone production clusters in limited geographic basins create input cost volatility for machine builders.
- ISO 6336 compliance friction:Tooth bending stress preservation requirements during honing extend process validation timelines for new machine installations.
- Grinding substitution threat:Continuous generating grinding technology achieves comparable surface finishes for certain helical gear forms at higher material removal rates.
Strategic Opportunities
- Wind turbine drivetrain expansion:Captive gear production for multi-megawatt turbine gearboxes creates dedicated honing capacity demand outside automotive cyclicality.
- NIST advanced manufacturing grants:Federal funding redirects capital toward energy-efficient machine tool platforms with regenerative drives and reduced idle power consumption.
- Surgical robot gear trains:FDA medical device quality system regulations shape honing protocols for miniature precision gears in imaging and robotic surgery equipment.
Industry Challenges
- Multi-axis CNC programming expertise gap:Spiral bevel and helical form interpolation requires specialized CAM competency scarce in traditional mechanical indexer operator pools.
- AGMA 2001-D04 certification timelines:Contact pattern validation protocols extend post-installation acceptance testing, compressing effective equipment utilization windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gear Honing Machines Market |
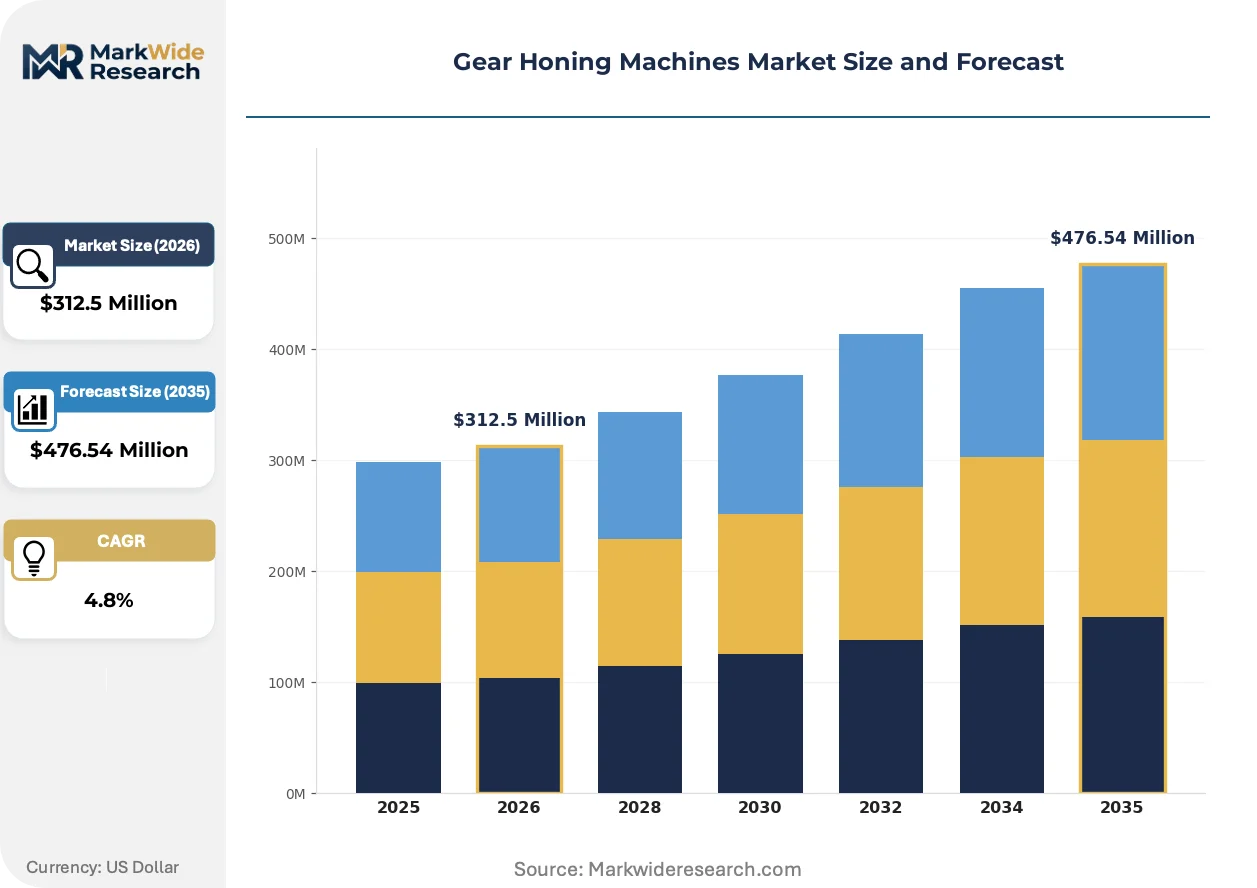
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $476.54 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal, Vertical, CNC, Manual Application: Aerospace, Automotive, Industrial Machinery, Marine Technology: Conventional, Abrasive, Electrochemical, Hybrid End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Retailers |
| Companies Covered | KAPP NILES Group, Liebherr Group, Gehring Technologies GmbH, delapena Group Ltd., Mitsubishi Heavy Industries Machine Tool Co., Ltd., Gleason Corporation, Reishauer AG, Sunnen Products Co., EMAG GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gear Honing Machines Market Shifts & Advancements
Closed-loop metrology integration is compressing post-process inspection cycles while hybrid process technologies expand addressable material sets beyond hardened steels into nickel-based superalloys and powder metallurgy components.
Adaptive process control software with real-time acoustic emission monitoring is automating tool wear compensation during long-batch automotive shaft production. Tier 1 suppliers in Germany are deploying these systems across horizontal through-pass configurations to eliminate manual offset adjustments between shifts. This automation is compressing operator-to-machine ratios and enabling unattended night-shift production of transmission gears.
EU Green Deal industrial funding is redirecting capital toward regenerative drive systems and minimum quantity lubrication architectures that reduce honing fluid consumption by sixty percent or more. Machine tool builders must now document carbon footprint per finished gear across the full equipment lifecycle to qualify for public procurement tenders. German and Italian OEMs are responding fastest, integrating energy monitoring dashboards as standard configuration rather than optional add-on modules.
After-sales service unbundling is fragmenting traditional full-service contracts into discrete performance-based modules for abrasive logistics, predictive maintenance analytics, and remote spindle diagnostics. Wind turbine operators in Denmark and Spain are piloting subscription models for honing stone replenishment tied to actual cutting hours rather than calendar-based replacement schedules. This consumption-pattern shift transfers inventory carrying costs from end-users to equipment vendors while locking in long-term consumable revenue streams.
Gear Honing Machines Market Segmentation
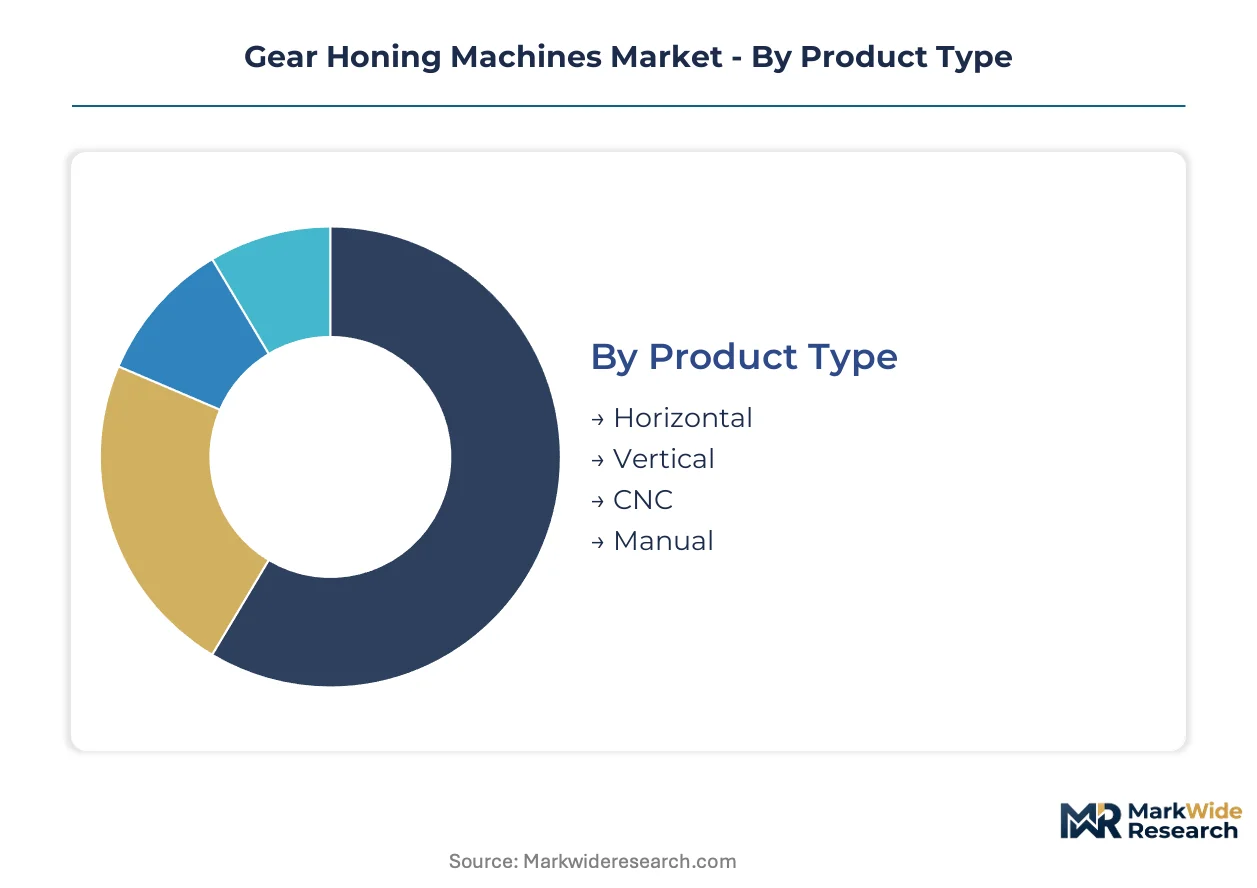
Gear honing machine segmentation reveals divergent capital allocation patterns across precision tiers. Volume manufacturers prioritize throughput-optimized horizontal configurations for automotive shaft production, while aerospace contractors specify CNC multi-axis platforms for spiral bevel forms demanding ISO 1328 grade 4 tolerances.
Product Type:
Horizontal platforms dominate automotive volume production, while CNC architectures capture premium precision contracts.
- Horizontal:Through-pass configurations process long transmission shafts in continuous flow. Automotive OEMs around Stuttgart deploy these systems for high-volume battery-electric drivetrain gears.
- CNC:Multi-axis interpolation replaces mechanical indexers for helical and spiral bevel forms. Aerospace manufacturers specify these platforms for nickel-based superalloy gears requiring minimal thermal damage layers.
- Vertical:Compact footprints suit job-shop environments with mixed batch sizes.
- Manual:Entry-level systems serve developing market repair facilities and prototype shops.
Today's leader: Horizontal. Tomorrow's challenger: CNC.
Application:
End-use concentration splits between cyclical automotive volume and resilient industrial machinery replacement cycles.
- Automotive:Battery-electric drivetrains demand precision-finished reduction gears for high-speed motor interfaces. EPA Tier 4 and Euro 7 efficiency mandates push transmission builders toward tighter mesh tolerances.
- Aerospace:Heat-resistant superalloy gears for turbine power transmission require hybrid electrochemical-abrasive processing to preserve fatigue life.
- Industrial Machinery:Wind turbine multi-megawatt gearboxes create dedicated honing capacity outside automotive demand swings.
- Marine:Large-module propulsion gears favor robust vertical platforms with extended stone life.
Automotive commands current installed base. Aerospace offers steepest expansion trajectory.
Technology:
Process maturity curves separate established abrasive systems from emerging hybrid architectures.
- Abrasive:Synthetic diamond and CBN stone systems achieve Ra 0.4 micrometer finishes on hardened steels. Supply concentration in limited geographic basins creates input cost volatility.
- Hybrid:Electrochemical-abrasive combinations minimize thermal damage layers in Inconel and Rene alloys. Medical device gear trains for surgical robots drive FDA-validated protocol development.
- Conventional:Mechanical indexer platforms persist in cost-sensitive repair applications.
- Electrochemical:Standalone chemistries serve specialized deburring without stock removal.
Abrasive technology anchors revenue. Hybrid systems gain share fastest.
End User:
Procurement authority concentrates with OEMs specifying closed-loop metrology, while Tier-1 suppliers optimize for throughput.
- OEMs:Captive gear production for wind turbines and construction equipment anchors dedicated honing capacity. Liebherr Group exemplifies vertical integration into precision finishing.
- Tier-1 Suppliers:Automotive transmission specialists deploy adaptive process control with acoustic emission monitoring for unattended night-shift production.
- Aftermarket Providers:Repair and remanufacturing services favor flexible manual and vertical platforms.
- Retailers:Distributor networks supply abrasive stones and consumables to fragmented job-shop bases.
OEMs set technology specifications. Tier-1 suppliers determine volume allocation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision machining talent pools in southern Germany and industrial heartlands across Japan anchor the highest-density gear honing machine deployment worldwide. These concentrations of skilled technicians and application engineers sustain demand for multi-axis CNC platforms and closed-loop metrology systems.
Germany
Machine tool clusters around Stuttgart and Munich serve premium-tier automotive suppliers building battery-electric drivetrains. The EU Green Deal industrial funding redirects capital toward regenerative drive systems with documented carbon footprints per finished gear. Bavaria's captive gear production for wind turbine gearboxes creates dedicated honing capacity outside automotive cyclicality.
United States
NIST advanced manufacturing grants accelerate adoption of energy-efficient platforms with reduced idle power consumption. EPA Tier 4 emissions frameworks tighten gear mesh efficiency mandates for engine builders across the Midwest industrial corridor. Michigan and Ohio transmission specialists deploy adaptive process control with acoustic emission monitoring for unattended production.
Japan
METI industrial policy supports precision finishing technology for surgical robot gear trains under FDA-validated protocols. Chubu region machine tool builders concentrate on hybrid electrochemical-abrasive systems for heat-resistant superalloy processing. Nagoya-based aerospace contractors specify minimal thermal damage layer preservation for turbine power transmission gears.
China
MIIT dual carbon goals push domestic machine tool builders toward minimum quantity lubrication architectures cutting fluid consumption. Yangtze River Delta automotive OEMs expand precision-finished gear adoption for high-speed electric vehicle reduction stages. Shanghai and Suzhou clusters import European CNC honing platforms for ISO 1328 grade 4-6 tolerance compliance.
Italy
Emilia-Romagna machine tool manufacturers integrate energy monitoring dashboards as standard configuration for EU public procurement qualification. Lombardy gear producers serving industrial machinery replacement cycles favor flexible vertical platforms for mixed batch sizes. Italian OEMs respond fastest to carbon footprint documentation requirements across full equipment lifecycles.
Gear Honing Machines Market Competitive Landscape
Top-tier vendors anchor the premium precision tier, while mid-scale fabricators compete on throughput-optimized horizontal configurations. The vendor base stratifies across grinding-honing integration specialists, captive gear production operators, and closed-loop metrology system providers. Strategic archetypes include aerospace-focused hybrid technology developers, automotive volume suppliers with acoustic emission automation, and wind turbine captive producers. Competitive moves concentrate on M&A for abrasive technology access and strategic partnerships for electrochemical process licensing.
Within the grinding-honing integration archetype, KAPP NILES Group and Gleason Corporation exemplify platforms combining finishing and measurement in single workflows. Liebherr Group occupies a distinct position through captive gear production for wind turbine and construction equipment drivetrains, representing vertical control over precision finishing capacity. Japanese fabricators including Mitsubishi Heavy Industries Machine Tool Co., Ltd. and Reishauer AG sit within the multi-axis CNC specialization tier serving aerospace superalloy applications.
| Leading Market Players |
|---|
| KAPP NILES Group |
| Liebherr Group |
| Gehring Technologies GmbH |
| delapena Group Ltd. |
| Mitsubishi Heavy Industries Machine Tool Co., Ltd. |
| Gleason Corporation |
| Reishauer AG |
| Sunnen Products Co. |
| EMAG GmbH & Co. KG |
| Others |
Supply & Pricing Matrix
Automotive OEMs and Tier 1 transmission specialists concentrate procurement authority for multi-axis CNC platforms, anchoring contract-based long-term offtake pricing with performance-based after-sales modules unbundled from base equipment sales.
Pricing Analysis
Full-service contract unbundling into discrete performance modules for abrasive logistics and predictive maintenance is reshaping revenue recognition across the vendor base. Price differentiation rests on ISO 1328 certification grade and closed-loop metrology integration, with aerospace contractors least sensitive and developing-market repair facilities most cost-constrained. Pricing pressure stems from continuous generating grinding substitution for certain helical gear forms, compressing margins on standard abrasive platforms.
Supply Chain Analysis
EU Green Deal industrial funding and EPA emissions frameworks are gating qualification for public procurement tenders, forcing documentation of carbon footprint per finished gear across full equipment lifecycles. Synthetic diamond and CBN honing stone production draws from concentrated geographic basins in Germany, Japan, and the United States, creating input cost volatility. Single-source vulnerability in premium abrasive supply feeds from limited superabrasive synthesis capacity. Distribution runs through captive gear production networks and Tier 1 supplier clusters anchored around Stuttgart, Munich, and Nagoya.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in gear honing machines flows from adaptive process control automation compressing operator-to-machine ratios and hybrid electrochemical-abrasive platforms commanding premium positioning for superalloy applications.
For Market Incumbents: Lock in long-term consumable revenue streams through subscription-based honing stone replenishment tied to actual cutting hours rather than calendar schedules. Deepen backward integration into abrasive technology through selective acquisition of synthetic diamond and CBN stone producers, defending against input cost volatility and grinding substitution threats.
For New Entrants and Emerging Players: Tier 1 automotive suppliers in China's Yangtze River Delta represent the most penetrable channel partner type for horizontal through-pass configurations serving battery-electric drivetrain expansion. Target FDA-validated protocol development for surgical robot gear trains as a white-space entry point, leveraging METI industrial policy alignment in Japan for technology licensing partnerships.
For Investors and Strategic Acquirers: Machine tool builders with grinding-honing integration capability are the most active acquirer in this space, consolidating closed-loop metrology and multi-axis CNC competency. Acquisition targets with hybrid electrochemical process patents offer the strongest long-term viability as aerospace superalloy demand accelerates. Monitor NIST advanced manufacturing grant disbursement velocity as an inflection indicator for capital redirection toward energy-efficient platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Metrology Integration | Compresses post-process inspection cycles for ISO 1328 grade 4-6 compliance. |
| Hybrid Electrochemical-Abrasive Licensing | Opens nickel-based superalloy processing for aerospace turbine power transmission. |
| Adaptive Process Control Deployment | Enables unattended night-shift production via acoustic emission monitoring automation. |
| Regenerative Drive System Integration | Qualifies equipment for EU Green Deal public procurement tender requirements. |
| Subscription-Based Consumable Models | Transfers inventory carrying costs from wind turbine operators to equipment vendors. |
Research Methodology
Bottom-up automotive and aerospace end-use modeling reconciled against top-down machine tool production tracking forms the analytical core. Primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads combined with secondary validation from customs/trade data, SEC 10-K filings, and IHS Markit vehicle production databases. Triangulation across supply-side capacity surveys and demand-side capital expenditure disclosures ensures cross-verification.
Historical trendline analysis of installed base depreciation cycles and replacement demand patterns informs the projection framework. Segmentation dimensions span product architecture, application vertical, process technology maturity, and end-user procurement authority. CAGRs derive from slope analysis of technology adoption curves and regulatory compliance phase-in schedules. Forecast inputs incorporate EPA Tier 4 and Euro 7 emissions framework stringency trajectories alongside MIIT dual carbon goal implementation pacing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to abrasive stone supply concentration disruptions and grinding technology substitution acceleration. Forecasts reflect assumptions around ISO 6336 standard revision timelines and EU Green Deal funding continuity. A model refresh is warranted upon material change in NIST advanced manufacturing grant allocation or hybrid electrochemical process commercialization velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Gas Cutting Machine Market
Tools
US Power Tools Market
Tools
Squeegee Market
Tools
Chainsaw Market
Tools
Metal Forming Tools Market
Tools
Multi Wire Cutting Machine Market
Tools
Europe Woodworking Power Tools Market
Tools
Pneumatic Bolting Tools Market
Tools
Automatic Lathe Machines Market
Tools
Automatic Heat Press Machines Market
Tools
Cutting Equipment Market
Tools
Floor Scraper Market
Tools
Bearing Installation Tool Kit Market
Tools
Rotary Knife Cutters Market
Tools
3D Milling Machines Market
Tools
Industrial Plate Bending Machines Market