
 Global Scaffolding Market | 2026-2036
Global Scaffolding Market Size, Share, and Industry Trends Forecast 2026-2036
Global Scaffolding Market Intelligence
Heavy-duty galvanized specification tiers is collapsing the cost gap between rental fleets and disposable tube-and-coupler sets across commercial job sites. PERI Group leverages its modular system scaffolding portfolio to dominate airport and stadium contracts in Germany and the Middle East. BrandSafway sustains the largest maintained rental inventory in North America, giving it channel control over multi-year infrastructure frameworks. Layher Holding GmbH differentiates through its allround wedge-lock engineering, which positions the firm for wind-energy tower maintenance in Northern Europe.
Scaffolding comprises temporary elevated work platforms assembled from steel tubes, aluminum frames, or composite modules to support workers, tools, and materials during construction, maintenance, or repair operations; load-bearing capacity and plank spacing are governed by EN 12811 and OSHA 1926 Subpart L specifications that mandate guardrails, mid-rails, and toe boards for fall protection. System scaffolding captures the dominant share of new commercial and infrastructure spending because its standardized rosette or cup-lock joints cut assembly labor by half versus traditional tube-and-coupler methods. Aluminum material grades are gaining fastest in event staging and shipyard applications where weight reduction accelerates repositioning cycles. Frame scaffolding remains mature in residential markets across the southern United States and parts of Latin America, with margin pools concentrating in used-equipment refurbishment and secondary rental channels.
The US OSHA scaffold standard and the EU's EN 12811 framework together mandate periodic inspection protocols and engineer-stamped drawings for suspended platforms above certain heights, which shifts demand toward certified rental providers and away from informal job-built systems. China's SAMR enforces GB 51210 for steel tubular scaffolds in high-rise construction, compelling domestic manufacturers to upgrade weld quality and traceability documentation for market access. India's BIS certification for steel scaffold tubes is tightening import thresholds, favoring local mills with integrated galvanizing capacity. Stakeholders must monitor how carbon-border adjustments and scrap-steel sourcing rules reshape material cost structures and supplier qualification timelines.
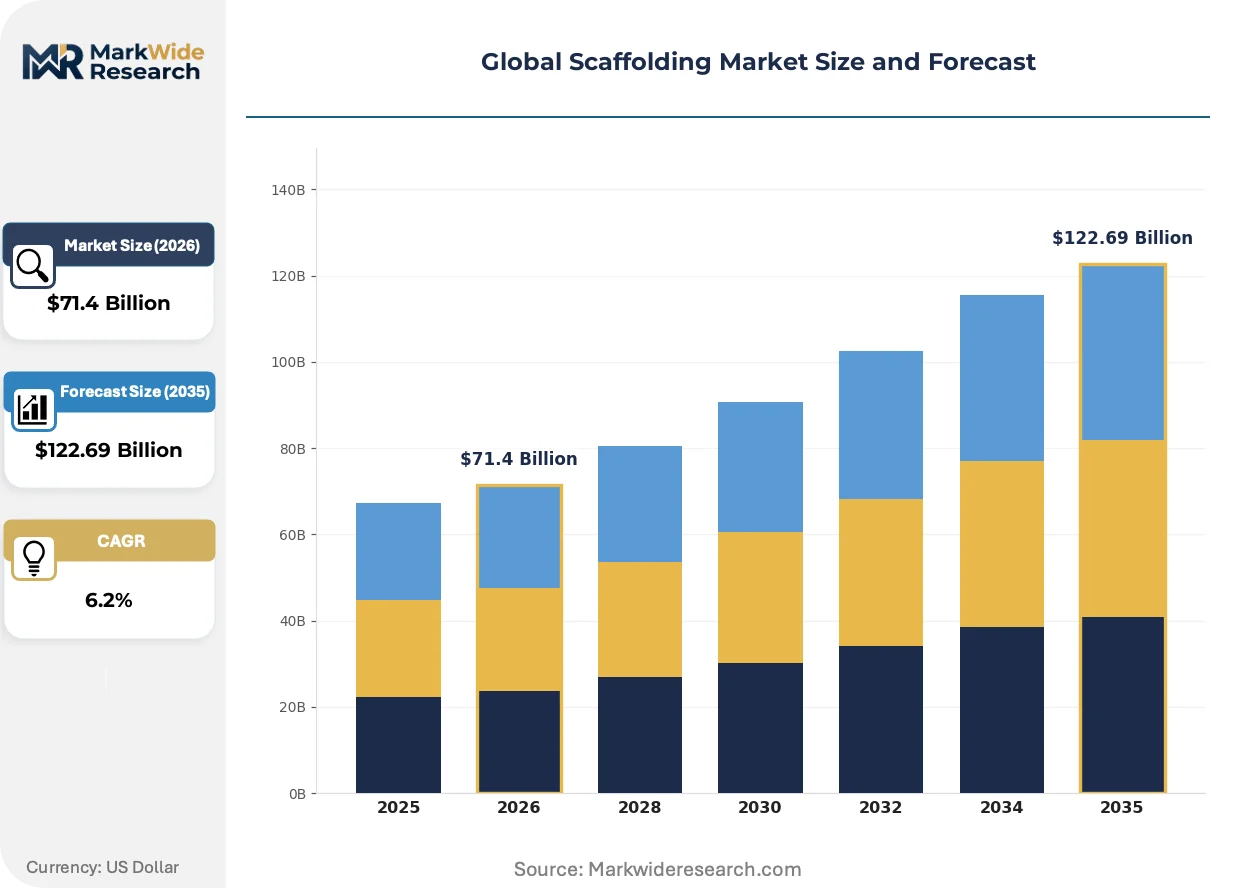
Market Dynamics
Heavy-duty galvanized specification tiers are collapsing the cost gap between rental fleets and disposable tube-and-coupler sets, forcing commercial contractors to reassess ownership economics across multi-year infrastructure frameworks.
Growth Catalysts
- EN 12811 and OSHA 1926 Subpart L mandates:Periodic inspection protocols and engineer-stamped drawings for suspended platforms above threshold heights shift demand toward certified rental providers and away from informal job-built systems.
- Wind-energy tower maintenance:Northern European offshore installations require specialized allround wedge-lock engineering for safe access at extreme heights, creating sustained equipment demand.
- India's industrial corridor concentration:Gujarat and Maharashtra zones are driving scaffold rental volumes as petrochemical and port infrastructure projects accelerate.
Market Restraints
- Scrap-steel cost volatility:Galvanized tube feedstock prices fluctuate with carbon-border adjustment mechanisms, compressing margin predictability for rental fleet operators.
- Chinese mill concentration:GB 51210 compliance upgrades have consolidated domestic supply, reducing export availability of certified steel tubular components to Southeast Asian contractors.
- Aluminum substitution ceiling:Load-bearing limitations prevent aluminum grades from displacing steel in high-rise concrete formwork applications above 30 meters.
Strategic Opportunities
- Saudi Arabia's giga-project pipeline:NEOM and Red Sea tourism developments are generating multi-year scaffold rental contracts with performance-based maintenance clauses.
- Event staging modularization:Lightweight aluminum frame systems are penetrating music festival and exhibition markets where rapid assembly cycles command premium pricing.
- India's BIS certification tightening:Import thresholds for steel scaffold tubes favor local mills with integrated galvanizing capacity, creating captive supply advantages for domestic rental chains.
Industry Challenges
- Weld-quality certification timelines:China's SAMR traceability documentation requirements extend supplier qualification periods by four to six months for new market entrants.
- System-to-tube-and-coupler integration:Mixed fleet operations create inventory complexity for contractors managing legacy equipment alongside modular rosette systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Scaffolding Market |
| Market Size in 2026 | $71.4 Billion |
| Market Size in 2035 | $122.69 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frame Scaffolding, System Scaffolding, Suspended Scaffolding, Mobile Scaffolding, Cantilever Scaffolding Material: Steel, Aluminum, Wood, Bamboo, Composite Application: Residential Construction, Commercial Construction, Infrastructure Projects, Industrial Maintenance, Event Staging End User: General Contractors, Specialty Contractors, Facility Managers, Event Organizers, Shipyards |
| Companies Covered | Altrad Group, ADTO Group, BrandSafway, MJ-Gerüst GmbH, Waco Kwikform, PERI Group, ULMA Construction, Stepup Scaffold, Layher Holding GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Scaffolding Market Strategic Shifts & Innovations
Modular system scaffolding is fragmenting traditional procurement patterns as standardized joints cut assembly labor requirements and reshape competitive positioning across commercial and infrastructure segments.
Composite material modules are fragmenting the historical steel-aluminum duopoly in elevated work platforms. Shipyard maintenance crews in South Korea and Japan are adopting carbon-fiber reinforced components to halve repositioning cycles during vessel overhaul schedules. The technology is fragmenting equipment ownership models as lighter assets enable shorter rental minimums and just-in-time delivery contracts.
China's GB 51210 enforcement through SAMR is mandating upgraded weld quality and traceability documentation for steel tubular scaffolds in high-rise construction. Domestic manufacturers must retrofit production lines with automated inspection systems to maintain market access. Export-oriented mills in Jiangsu and Shandong provinces are absorbing compliance costs to preserve Southeast Asian distribution relationships.
Performance-based rental contracts are displacing day-rate pricing in German airport and stadium construction. PERI Group and regional competitors now bundle engineering support, assembly labor, and dismantling services into single-scope agreements. The model concentrates in publicly funded infrastructure where total-cost transparency satisfies municipal procurement audit requirements.
Global Scaffolding Market Segmentation
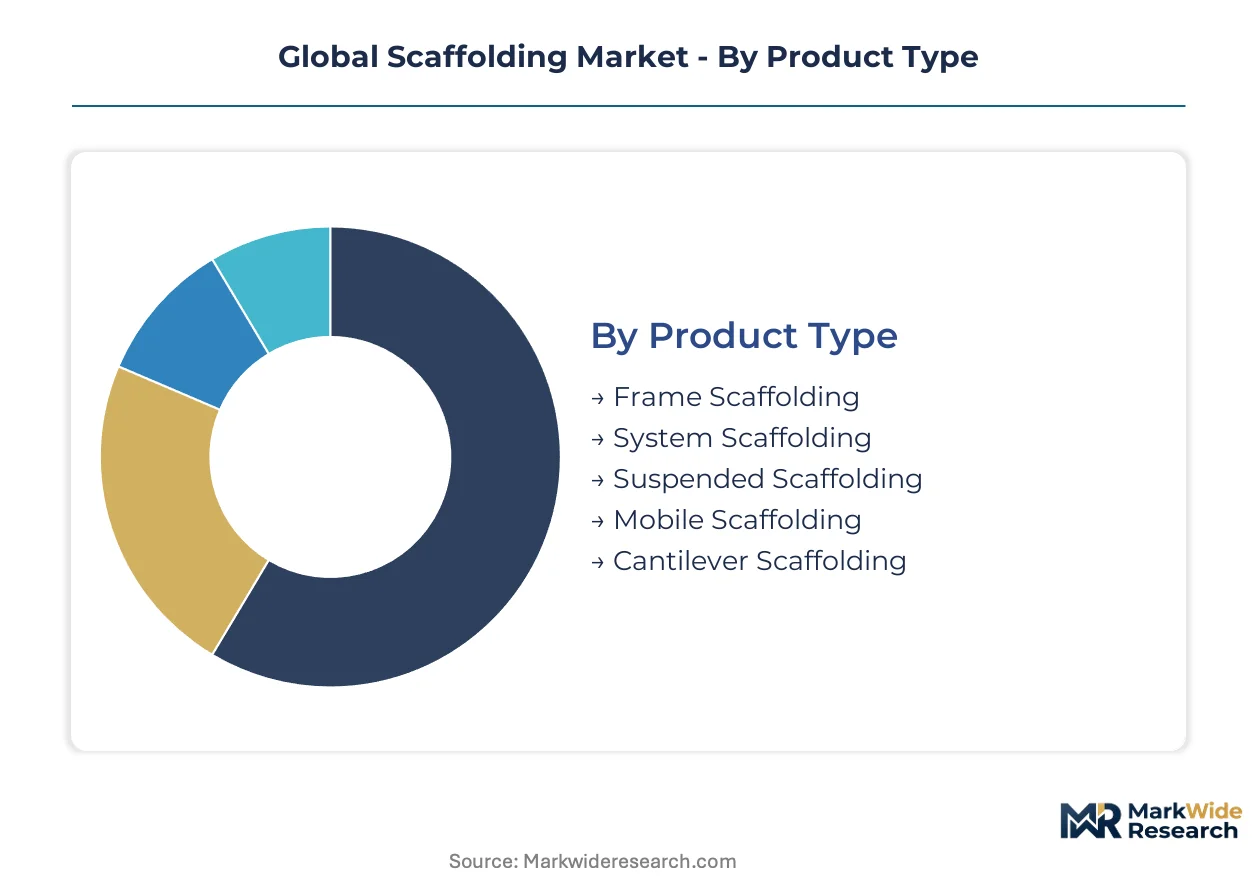
Scaffolding procurement patterns fragment sharply across product architecture and material grade, with rental fleet economics and regulatory compliance tiers determining where margin pools concentrate. System scaffolding commands premium positioning in infrastructure frameworks while frame systems defend volume in residential channels.
Product Type:
Margin pools sit heaviest in modular systems where engineering support and assembly labor bundle into multi-year contracts, while commodity tube-and-coupler sets compete on depreciation cycles.
- Frame Scaffolding:Steel tube and coupler assemblies dominate residential construction across the southern United States and Latin America. Demand concentrates in refurbishment channels and secondary rental markets where used-equipment margin pools exceed new product sales.
- System Scaffolding:Standardized rosette or cup-lock joints cut assembly labor requirements by half versus traditional methods. Commercial and infrastructure spending in Germany and the Middle East rotates toward these systems where engineer-stamped drawings satisfy EN 12811 and municipal audit requirements.
- Suspended Scaffolding:OSHA 1926 Subpart L mandates periodic inspection protocols above threshold heights, shifting demand toward certified rental providers.
- Mobile Scaffolding:Lightweight aluminum configurations serve facility maintenance crews requiring rapid repositioning across industrial sites.
- Cantilever Scaffolding:Specialized configurations address restricted ground access scenarios in dense urban construction zones.
System scaffolding holds installed capacity. Frame scaffolding is rotating up the share rankings in emerging residential markets.
Material:
Cost tier differentiation separates galvanized steel specifications from aluminum grades, with composite modules fragmenting the historical duopoly in specialized applications.
- Steel:Heavy-duty galvanized tubes anchor load-bearing capacity for high-rise concrete formwork above 30 meters. China's SAMR enforces GB 51210 compliance upgrades that consolidate domestic supply and extend supplier qualification timelines.
- Aluminum:Weight reduction accelerates repositioning cycles in event staging and shipyard applications. South Korean and Japanese vessel maintenance crews adopt these grades where rapid assembly commands premium pricing.
- Wood:Traditional plank configurations persist in residential markets with lower regulatory scrutiny.
- Bamboo:Regional availability supports cost-sensitive construction in Southeast Asian markets.
- Composite:Carbon-fiber reinforced components halve repositioning cycles during vessel overhaul schedules, enabling shorter rental minimums.
Steel maintains dominant load-bearing specifications. Aluminum is climbing the fastest in weight-sensitive applications.
Application:
Volume concentration tracks public infrastructure spending cycles, with industrial maintenance creating sustained equipment demand through recurring contract structures.
- Commercial Construction:Airport and stadium contracts in Germany bundle engineering support, assembly labor, and dismantling services into single-scope agreements. Performance-based pricing displaces day-rate models where total-cost transparency satisfies procurement audit requirements.
- Infrastructure Projects:Saudi Arabia's NEOM and Red Sea tourism developments generate multi-year scaffold rental contracts with maintenance clauses. India's industrial corridor zones in Gujarat and Maharashtra drive rental volumes as petrochemical and port projects accelerate.
- Residential Construction:Frame systems dominate margin pools in refurbishment and secondary rental channels.
- Industrial Maintenance:Wind-energy tower installations in Northern Europe require specialized allround wedge-lock engineering for safe access at extreme heights.
- Event Staging:Lightweight aluminum frame systems penetrate music festival and exhibition markets where rapid assembly cycles command premium pricing.
Infrastructure projects hold installed capacity. Event staging is gaining share fastest in seasonal premium segments.
End User:
Customer type determines procurement sophistication, with general contractors managing mixed fleet complexity while specialty contractors concentrate in certified rental relationships.
- General Contractors:Mixed fleet operations create inventory complexity when managing legacy tube-and-coupler equipment alongside modular rosette systems. India's BIS certification tightening favors domestic rental chains with integrated galvanizing capacity.
- Specialty Contractors:Suspended platform expertise requires engineer-stamped drawings and periodic inspection protocols, concentrating demand with certified rental providers.
- Facility Managers:Mobile scaffolding configurations support rapid-response maintenance schedules across distributed industrial assets.
- Event Organizers:Aluminum frame procurement emphasizes just-in-time delivery contracts enabled by lighter asset repositioning.
- Shipyards:South Korean and Japanese maintenance crews adopt composite modules to compress vessel overhaul schedules.
General contractors hold installed capacity. Specialty contractors are rotating up the share rankings through certified rental concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel mill capacity and rental fleet density concentrate in China, Germany, the United States, India, and the United Arab Emirates. Regulatory divergence across OSHA, EN 12811, GB 51210, and BIS certification frameworks fragments procurement standards. Project pipelines in Saudi Arabia and India's industrial corridors are redrawing equipment demand geography.
United States
Multi-year infrastructure frameworks and commercial construction drive scaffold rental volumes. OSHA 1926 Subpart L mandates periodic inspection protocols and engineer-stamped drawings for suspended platforms. Gulf Coast petrochemical clusters and Texas energy corridors sustain heavy-duty galvanized equipment demand through recurring maintenance cycles.
Germany
Airport and stadium contracts bundle engineering support with assembly labor into performance-based agreements. EN 12811 frameworks govern load-bearing specifications and fall protection requirements. Bavarian and North Rhine-Westphalian construction hubs rotate procurement toward modular system scaffolding for municipal audit compliance.
China
High-rise construction and domestic infrastructure spending absorb certified steel tubular output. SAMR enforces GB 51210 compliance with upgraded weld quality and traceability documentation. Jiangsu and Shandong export-oriented mills absorb retrofit costs to preserve Southeast Asian distribution relationships.
India
Petrochemical and port infrastructure projects in Gujarat and Maharashtra industrial corridors accelerate rental volumes. BIS certification tightening for steel scaffold tubes favors domestic mills with integrated galvanizing capacity. Local rental chains capture captive supply advantages as import thresholds rise.
United Arab Emirates
NEOM and Red Sea tourism developments generate multi-year scaffold rental contracts with performance-based maintenance clauses. Commercial construction expansion in Dubai and Abu Dhabi concentrates demand for heavy-duty galvanized specifications. MOHAP and municipal regulators align procurement standards with Gulf Cooperation Council safety frameworks.
Global Scaffolding Market Key Industry Players
Concentration sits with diversified rental fleet operators and specialized modular system engineers. The vendor base spans three tiers: integrated international providers with multi-regional coverage, domestic rental chains with captive galvanizing capacity, and regional fabricators serving project-specific demand. Competitive moves center on backward integration into steel processing and strategic partnerships for wind-energy access platforms.
Among German-based specialists, PERI Group and Layher Holding GmbH exemplify the premium-tier engineering archetype through modular system dominance. BrandSafway anchors the integrated rental fleet model in North American markets. Altrad Group occupies a position spanning both equipment manufacturing and rental services across European and Middle Eastern corridors.
| Leading Market Players |
|---|
| Altrad Group |
| ADTO Group |
| BrandSafway |
| MJ-Gerüst GmbH |
| Waco Kwikform |
| PERI Group |
| ULMA Construction |
| Stepup Scaffold |
| Layher Holding GmbH |
| Others |
Cost & Logistics Intelligence
GB 51210 certification gates both supplier qualification timelines and price differentiation across steel tubular scaffold tiers, compressing margin pools for uncertified imports while rewarding domestic mills with integrated traceability systems.
Pricing Analysis
OSHA 1926 Subpart L dictates the pricing tier structure across suspended platform categories, separating certified rental providers from informal job-built competitors through engineer-stamped documentation requirements. Three-tier pricing stratification across premium, standard, and economy levels tracks galvanizing specification grades and inspection protocol bundling. Cost compression in disposable tube-and-coupler segments intensifies as heavy-duty galvanized rental fleets narrow ownership economics. General contractors managing mixed fleet operations exhibit highest price sensitivity, while specialty contractors concentrated in wind-energy maintenance accept premium positioning for allround wedge-lock engineering.
Supply Chain Analysis
China and India anchor global steel tubular scaffold production, with Jiangsu and Shandong export mills absorbing GB 51210 compliance costs and Gujarat-based integrated galvanizers capturing BIS certification advantages. Feedstock draws from scrap-steel markets and primary billet suppliers, with zinc coating inputs tethered to carbon-border adjustment exposure. Single-source vulnerability concentrates in Chinese mill certification backlogs extending supplier qualification timelines. Distribution runs through rental fleet operators and secondary refurbishment channels, with project-direct sales penetrating giga-project pipelines in Saudi Arabia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineering support and assembly labor bundling expands faster than hardware rental rates, reframing competitive advantage around service-attach depth rather than equipment depreciation cycles alone.
For Market Incumbents: Compound fleet utilization through backward integration into galvanizing capacity and captive supply of certified steel tubes. Defend position against aluminum substitution in event staging by embedding rosette system expertise into municipal audit-compliant infrastructure frameworks. Channel control over multi-year maintenance contracts anchors pricing power against commodity spot competitors.
For New Entrants and Emerging Players: Aftermarket inspection and recertification services represent the most penetrable white-space target, as incumbent rental chains under-serve distributed industrial maintenance crews with rapid-response mobile scaffolding needs. Target India's BIS-tightening import environment through domestic mill partnerships with integrated traceability documentation. Go-to-market execution should emphasize just-in-time delivery contracts enabled by lightweight aluminum asset repositioning.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional rental chains possessing captive galvanizing capacity but fragmented engineering service capabilities. Long-term viability hinges on consolidation plays that merge equipment scale with performance-based contract structuring. Watch for carbon-border adjustment implementation as the inflection signal reshaping feedstock cost structures and supplier qualification economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Galvanizing Capacity | Captive supply of certified steel tubes compresses qualification timelines under SAMR and BIS frameworks. |
| Performance-Based Rental Contract Structuring | Bundled engineering support satisfies municipal audit requirements in German airport and stadium procurement. |
| Composite Material Module Development | Carbon-fiber reinforced components enable shorter rental minimums in South Korean and Japanese shipyard maintenance. |
| Wind-Energy Access Platform Partnership | Allround wedge-lock engineering secures sustained equipment demand from Northern European offshore installations. |
| Event Staging Modularization Launch | Lightweight aluminum frame systems command premium pricing in music festival rapid-assembly cycles. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with rental fleet operators, scaffold engineering directors, municipal procurement officers, and petrochemical maintenance managers; and secondary validation through customs trade databases, SEC filings of listed equipment lessors, OSHA enforcement records, and GB standards documentation. Bottom-up equipment unit economics triangulated against top-down construction spending forecasts across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product architecture, material grade tier, application category, and end-user procurement sophistication. CAGRs derived from regression analysis against construction output indices and infrastructure budget allocations. Industry-specific forecast inputs incorporated wind-energy installation pipelines and Saudi giga-project development schedules.
Material uncertainties — scrap-steel price volatility, certification timeline extensions, and carbon-border adjustment implementation — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and rental fleet replacement cycles. Recalibration cycles align with material shifts in GB 51210 compliance thresholds and BIS import restriction announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Log Splitters Rental Market
Construction Equipment
Hydraulic Press Machine Market
Construction Equipment
Wood Milling Machine Market
Construction Equipment
Global Submerged Arc Welding Market
Construction Equipment
Europe Construction Machinery Rental Market
Construction Equipment
Brazil Metal Fabrication Equipment Market
Construction Equipment
Ceramic Tile Printing Machine Market
Construction Equipment
Welding Fume Extraction Equipment Market
Construction Equipment
Industrial Hydraulic Equipment Market
Construction Equipment
Electric Hot Chamber Die Casting Machines Market
Construction Equipment
Ultrasonic Welding Machine Market
Construction Equipment
Plasma Welding Machine Market
Construction Equipment
Construction Equipment Market
Construction Equipment
Construction Helmet Market
Construction Equipment
Snow Pushers Market
Construction Equipment
Global Industrial Parts Washer Market