
 Trash Rack Cleaning Machine Market | 2026-2036
Trash Rack Cleaning Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Trash Rack Cleaning Machine Market Analytics
Remote sensor integration with automated debris detection is tilting trash rack cleaning from reactive maintenance toward predictive operation. OSSBERGER GmbH + Co leverages its Bavarian manufacturing base to dominate Central European hydropower retrofits. Muhr GmbH sustains a specialized position in high-flow river intake systems for German municipal utilities. General Mechanical Works Pvt. Ltd. anchors South Asian demand through cost-optimized mechanical designs for irrigation canals.
Trash rack cleaning machines are electromechanical or hydraulic systems designed to remove accumulated debris from water intake structures, typically operating at bar spacing of 20–150 mm and rake speeds of 3–15 meters per minute to prevent flow obstruction and protect downstream pumps or turbines. Their primary purpose is maintaining hydraulic efficiency and preventing equipment damage at water extraction points for power generation, treatment, and industrial cooling. Automatic systems capture the dominant share of new installations as labor costs and safety regulations escalate, while robotic cleaners represent the fastest-expanding niche where underwater access limits conventional equipment deployment. Water treatment plants generate the most stable replacement demand, though power generation facilities offer larger per-unit contract values.
German KBA-type river basin authorities enforce debris discharge protocols under the EU Water Framework Directive, compelling operators to upgrade from manual to automated cleaning systems. ISO 20653 ingress protection standards and CE marking requirements under the EU Machinery Directive shape product design and market access for European suppliers. Stakeholders must monitor how stricter EPA cooling water intake regulations in the United States and evolving MEE discharge standards in China redirect procurement budgets toward automated intake protection technologies.
Market Dynamics
The transition from reactive maintenance schedules to predictive debris management is restructuring procurement priorities across water infrastructure operators, with remote sensing integration now a baseline specification rather than premium add-on.
Growth Catalysts
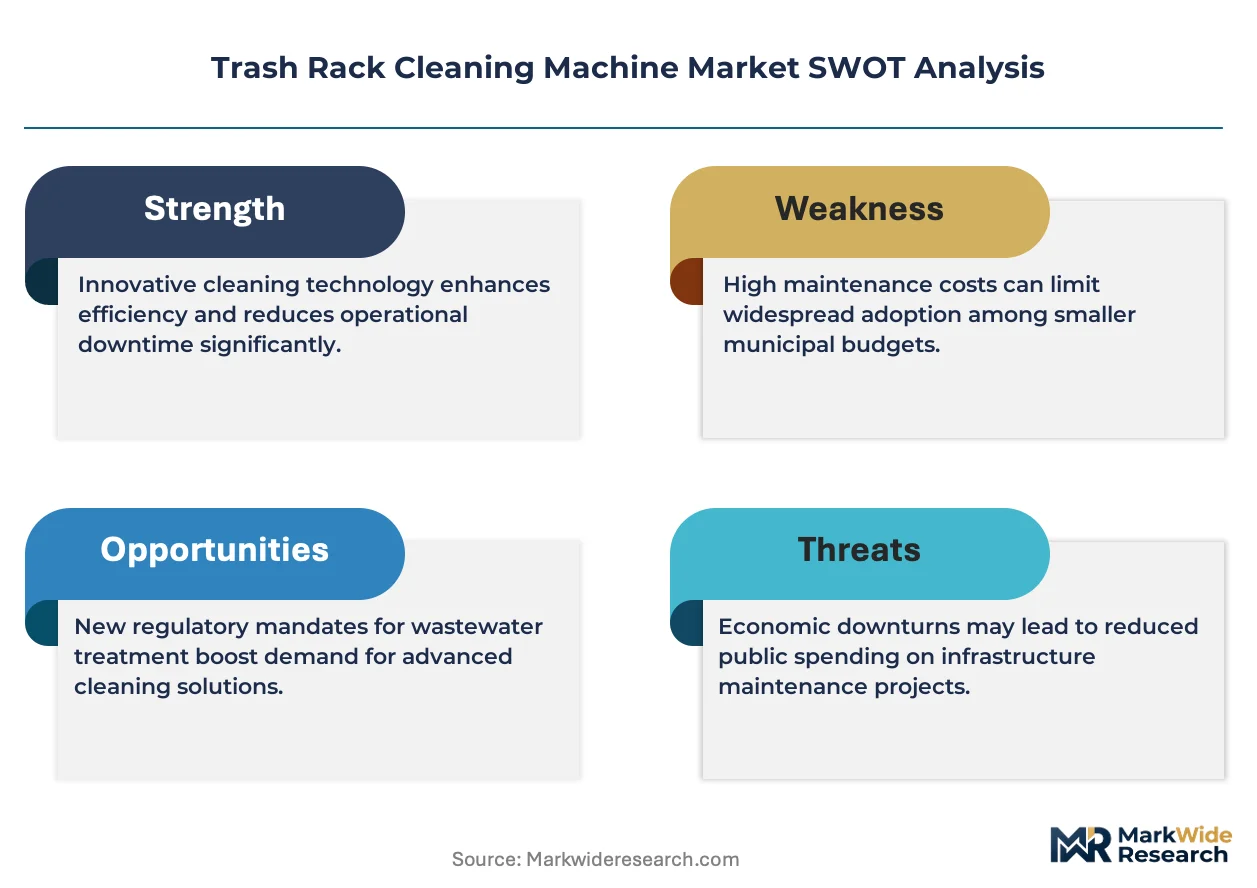
- EU Water Framework Directive mandates:German KBA-type river basin authorities enforce debris discharge protocols that compel hydropower operators to automate previously manual cleaning operations.
- Bar spacing standardization:Convergence on 20–150 mm rack specifications allows manufacturers to achieve production scale economies across municipal and industrial segments simultaneously.
- Rake speed optimization:Hydraulically actuated systems operating at 3–15 meters per minute reduce turbine downtime losses at high-flow river intakes.
Market Restraints
- Stainless steel input volatility:Grade 316L price swings compress fabrication margins for electromechanical system builders.
- Specialized hydraulics supply concentration:German and Austrian component suppliers dominate high-pressure actuator sourcing, creating bottleneck risk.
- Submersible motor IP rating requirements:ISO 20653 ingress protection certification adds 12–18 month validation timelines for new product introductions.
Strategic Opportunities
- Retrofit automation in Bavaria's hydropower corridor:Aging run-of-river installations require electromechanical upgrades to meet current debris management standards.
- Sensor-to-actuator convergence:Integration of acoustic debris detection with automated rake positioning enables predictive cleaning cycles.
- Robotic deployment in confined access:Cable-guided cleaners penetrate submerged intake structures where conventional gantry systems cannot operate.
Industry Challenges
- Subsea electronics integration expertise:Shortage of engineers capable of sealing control systems against 10-bar pressure differentials limits product development velocity.
- CE marking complexity under Machinery Directive:Multi-national conformity assessment procedures delay market entry for specialized equipment builders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trash Rack Cleaning Machine Market |
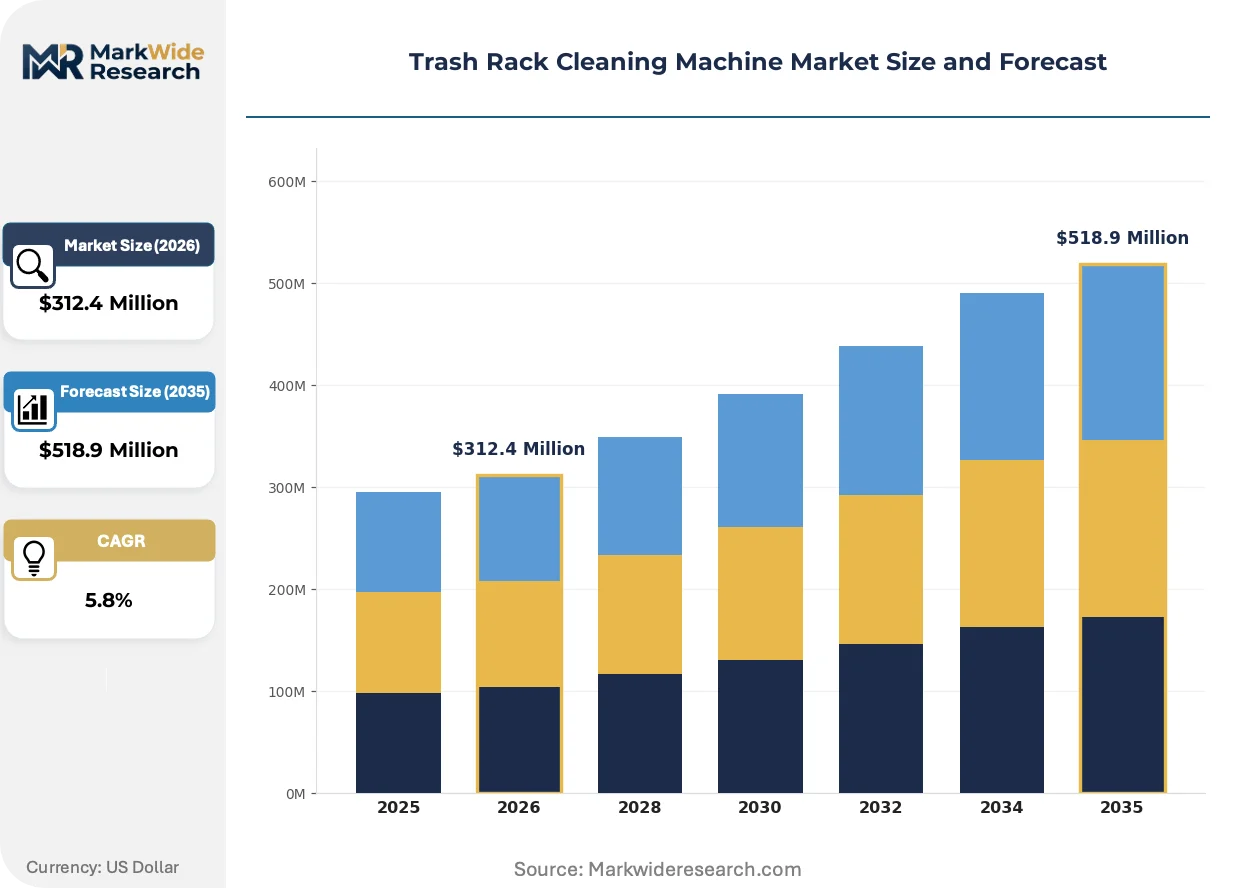
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Systems, Manual Systems, Semi-Automatic Systems, Robotic Cleaners Installation Type: On-site, Off-site, Portable, Fixed End User: Water Treatment Plants, Power Generation Facilities, Industrial Manufacturing, Marine Operations Cleaning Method: Mechanical Cleaning, Hydraulic Cleaning, Air Blasting, Chemical Cleaning |
| Companies Covered | OSSBERGER GmbH + Co, Muhr GmbH, General Mechanical Works Pvt. Ltd., WesTech Engineering, Jash Engineering Ltd., Lakeside Equipment Corporation, BRAUN Maschinenfabrik Gesellschaft m.b.H, Hydrolox LLC, Evoqua Water Technologies LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trash Rack Cleaning Machine Market Evolving Landscape
Debris detection and removal systems are converging with industrial IoT architectures, creating demand for platforms that transmit operational telemetry directly to SCADA networks without intermediary processing layers.
Acoustic imaging technology is hybridizing with traditional mechanical raking systems to enable real-time debris characterization before physical engagement. Hydropower operators in the Rhine basin industrial cluster are piloting these fused systems to optimize rake cycle timing. The convergence is compressing maintenance windows from scheduled intervals to condition-triggered events, reducing unnecessary mechanical wear.
EPA cooling water intake regulations in the United States are tightening impingement and entrainment standards for thermal power facilities. Operators must demonstrate continuous debris management capability to maintain operating permits. This regulatory pressure is redirecting capital budgets toward automated intake protection in the Ohio River Valley and Great Lakes corridor.
Service contracting preferences among German municipal utilities are migrating from equipment purchase toward availability-based agreements. Under these arrangements, OEMs retain ownership and guarantee debris-free intake operation. Muhr GmbH and OSSBERGER GmbH + Co have restructured their Bavarian and Baden-Württemberg sales organizations to capture recurring revenue streams from this model shift.
Trash Rack Cleaning Machine Market Segmentation
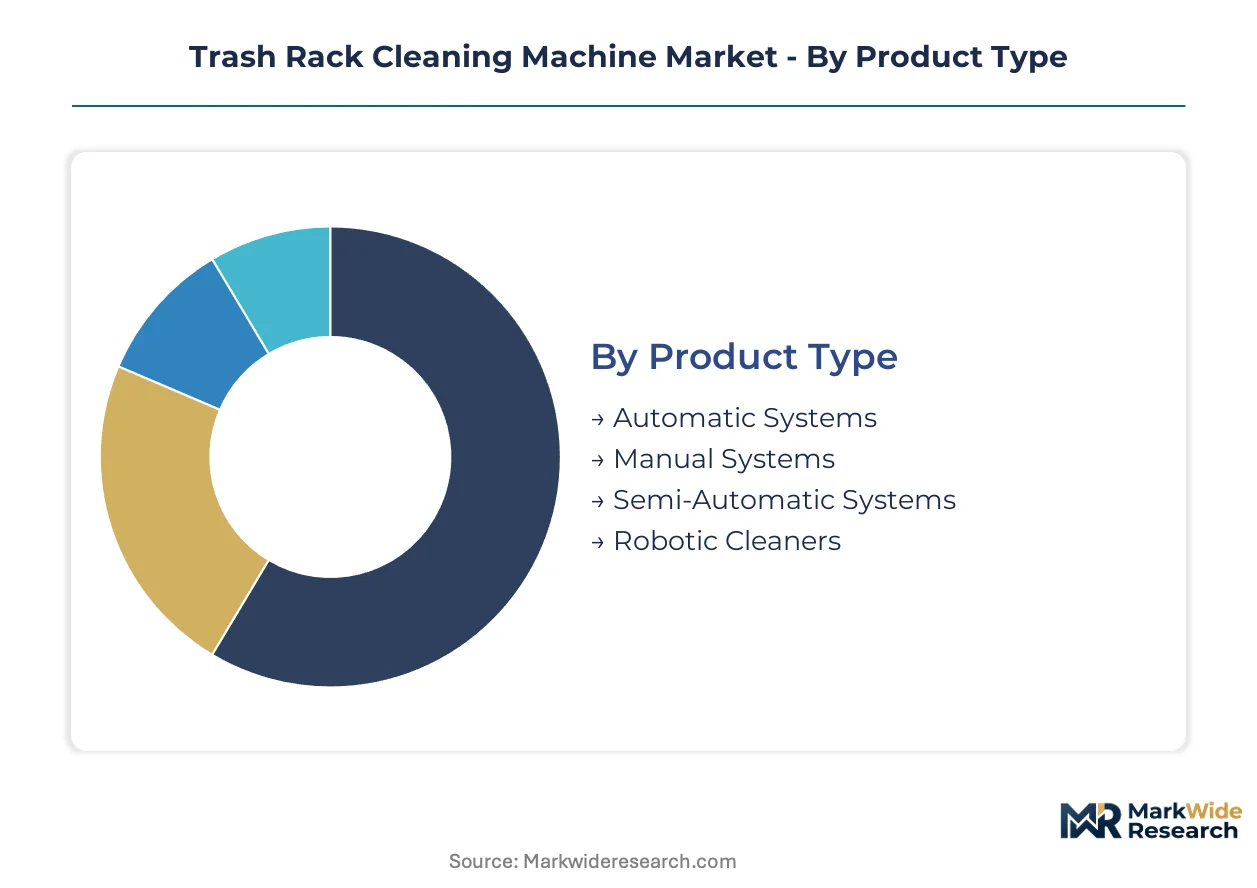
Trash rack cleaning machine procurement varies sharply by operational intensity, site constraints, and regulatory exposure. Segment boundaries determine whether suppliers compete on capital efficiency, lifecycle service contracts, or specialized engineering capability.
Product Type:
Cost tier splits the installed base between labor-substituting automation and capital-light mechanical alternatives.
- Automatic Systems:Electromechanical rakes with programmable logic controllers execute cleaning cycles without operator presence. German municipal utilities in the Rhine basin specify these for 24/7 treatment plant intakes where labor costs and night-shift safety rules have escalated.
- Robotic Cleaners:Cable-guided or autonomous submersible units penetrate confined intake structures where gantry-mounted equipment cannot deploy. Bavarian hydropower operators pilot these for dam face cleaning at reservoirs with submerged trash racks.
- Manual Systems:Hand-operated rakes and winch assemblies persist at small-scale irrigation diversions where capital constraints outweigh labor availability.
- Semi-Automatic Systems:Operator-supervised powered rakes bridge the gap for mid-size industrial cooling intakes with intermittent debris loads.
Automatic systems command the established base. The steepest expansion runs through robotic cleaners.
Installation Type:
Application context dictates whether equipment arrives pre-commissioned or requires extensive civil works.
- Fixed:Permanent gantry or bridge-mounted installations dominate high-flow river intakes where structural integration with intake piers is mandatory. These anchor revenue for European suppliers serving run-of-river hydropower.
- Portable:Modular skid-mounted units relocate between seasonal irrigation diversions or temporary construction dewatering sites. Indian canal authorities deploy these during monsoon debris surges.
- On-site:Equipment fabricated and commissioned at the intake structure accommodates non-standard rack geometries at aging infrastructure.
- Off-site:Factory-integrated systems reduce commissioning time for standardized new-build treatment plants.
Fixed installations retain the revenue concentration. Portable configurations are gaining share fastest in seasonal water management applications.
End User:
Customer type determines contract structure, with availability guarantees replacing equipment sales in regulated utilities.
- Water Treatment Plants:Municipal authorities generate stable replacement demand through 15-20 year asset lifecycles. German KBA-type river basin authorities mandate automated cleaning under EU Water Framework Directive debris protocols.
- Power Generation Facilities:Hydropower operators offer larger per-unit contract values but concentrated procurement cycles tied to turbine overhaul schedules. Bavaria's hydropower corridor drives retrofit automation programs.
- Industrial Manufacturing:Steel, chemical, and data center cooling intakes require customized bar spacing to protect heat exchangers from macrofouling.
- Marine Operations:Port authorities and shipyard dry docks deploy specialized cleaners for berth maintenance and vessel cooling system protection.
Water treatment plants anchor recurring revenue streams. Power generation facilities concentrate the highest-value individual contracts.
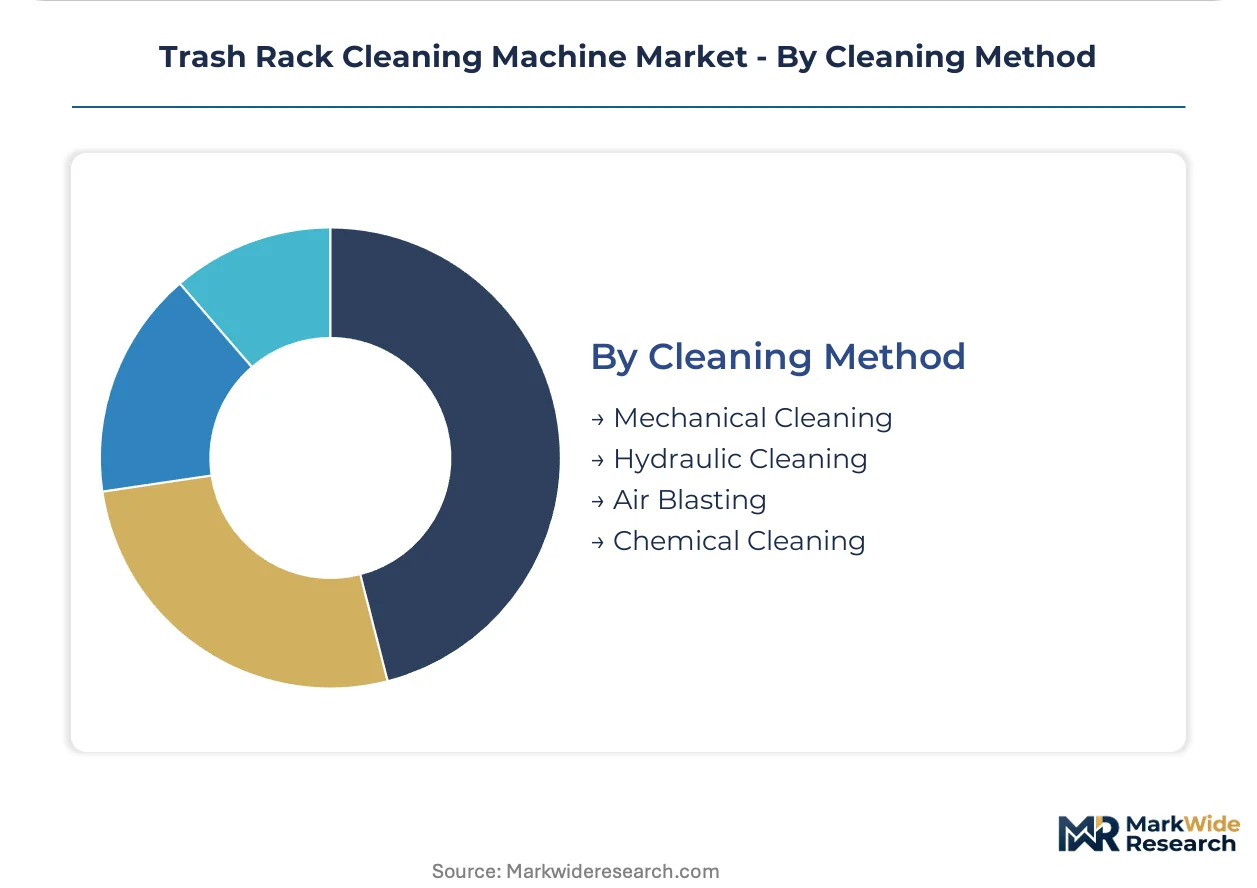
Cleaning Method:
Technology selection hinges on debris composition, with organic loads demanding different approaches than mineral or anthropogenic waste.
- Mechanical Cleaning:Rake-and-screen systems with hardened steel teeth dominate universal debris removal. Rhine basin industrial clusters specify these for mixed urban runoff and natural debris.
- Hydraulic Cleaning:High-pressure water jets flush fine sediment and algal mats without mechanical wear. Operators with high silt loads in Alpine reservoir drawdown zones favor this approach.
- Air Blasting:Compressed air systems dislodge fibrous debris and ice formations at intakes subject to freezing conditions.
- Chemical Cleaning:Biocide or acid treatments address biofouling and mineral scaling in specialized industrial cooling applications.
Mechanical cleaning holds the dominant share. Hydraulic methods are expanding most quickly in reservoir and high-silt river environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export electromechanical cleaning systems to hydropower operators across the Alpine corridor and Rhine basin, while Indian fabricators supply cost-optimized mechanical units to irrigation authorities throughout South Asia.
Germany
Bavaria's hydropower corridor and the Rhine basin industrial cluster drive retrofit automation demand. KBA-type river basin authorities enforce debris discharge protocols under the EU Water Framework Directive. OSSBERGER GmbH + Co leverages its Bavarian manufacturing base to capture Central European hydropower upgrade contracts.
United States
Thermal power facilities in the Ohio River Valley and Great Lakes corridor face tightening EPA cooling water intake regulations. Operators must demonstrate continuous debris management capability to maintain operating permits. WesTech Engineering and Lakeside Equipment Corporation anchor supply relationships with municipal utilities in these watersheds.
India
Irrigation canal authorities in Maharashtra and Gujarat deploy portable skid-mounted units during monsoon debris surges. The Central Electricity Authority mandates intake protection standards for new hydropower installations. General Mechanical Works Pvt. Ltd. anchors South Asian demand through cost-optimized mechanical designs for seasonal water management.
China
Yangtze River Delta hydropower operators upgrade aging intake structures to comply with evolving MEE discharge standards. Provincial water resource bureaus redirect procurement budgets toward automated intake protection technologies. Domestic fabricators compete with European suppliers for high-flow river intake contracts in Sichuan-Chongqing.
Austria
Alpine run-of-river installations require electromechanical upgrades to meet current debris management standards. BRAUN Maschinenfabrik Gesellschaft m.b.H draws on regional hydraulics supply chains to serve Danube basin operators. Salzburg and Tyrol sub-regions concentrate pilot deployments of sensor-integrated predictive cleaning systems.
Trash Rack Cleaning Machine Market Competitive Landscape
On the supply side, the industry is bifurcated between precision-engineered European specialists and volume-oriented Asian fabricators. Tier-one electromechanical suppliers compete on lifecycle service contracts rather than equipment margins. Three archetypes dominate: Bavarian hydropower specialists, Rhine basin municipal system builders, and South Asian irrigation equipment manufacturers. Competitive moves concentrate on sensor-to-actuator technology licensing and availability-based contracting structures.
Among German GmbH-structured specialists, OSSBERGER GmbH + Co and Muhr GmbH exemplify the premium-tier archetype serving regulated European utilities. General Mechanical Works Pvt. Ltd. occupies a position within the cost-optimized mechanical segment, representing how Indian private limited companies capture price-sensitive irrigation demand. These three anchors illustrate how geographic specialization and corporate structure align with distinct procurement channels across municipal, power generation, and agricultural end-uses.
| Leading Market Players |
|---|
| OSSBERGER GmbH + Co |
| Muhr GmbH |
| General Mechanical Works Pvt. Ltd. |
| WesTech Engineering |
| Jash Engineering Ltd. |
| Lakeside Equipment Corporation |
| BRAUN Maschinenfabrik Gesellschaft m.b.H |
| Hydrolox LLC |
| Evoqua Water Technologies LLC |
| Others |
Value Network & Pricing Analysis
Bavaria's hydropower manufacturing cluster concentrates electromechanical system production capacity, translating upstream stainless steel volatility into asymmetric pricing power for tier-one German specialists serving regulated European utilities.
Pricing Analysis
Prior-generation hydraulic rakes command 30-40% discounts against sensor-integrated electromechanical platforms, while next-generation robotic submersibles extract premium positioning through confined-access capabilities. The dominant structure is project-based contracting with availability-guarantee overlays, where price differentiation rests on CE marking tier and after-sales service bundling. Cost compression in mid-tier mechanical systems is intensifying because Indian fabricators are scaling export capacity. Municipal water treatment authorities in the Rhine basin show lowest price sensitivity due to regulatory compliance mandates, while seasonal irrigation operators in South Asia exhibit highest sensitivity.
Supply Chain Analysis
Extended payment terms from 60 to 90 days have become standard for German municipal utility procurement, compressing working capital for component suppliers. Electromechanical system fabrication draws from Germany, Austria, and India, with Grade 316L stainless steel, high-pressure hydraulic actuators, and submersible motor assemblies as critical inputs. Single-source vulnerability concentrates in German-Austrian hydraulic component supply, where two regional specialists control high-pressure actuator sourcing. Distribution runs through direct OEM-utility relationships for large hydropower retrofits, with dealer networks serving fragmented irrigation demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from integrated water intake platforms that bundle debris management with filtration and pumping, threatening standalone trash rack cleaner positioning.
For Market Incumbents: Insulate core revenue through backward integration into sensor hardware and predictive analytics software, locking in switching costs with SCADA-integrated platforms. OSSBERGER GmbH + Co and Muhr GmbH demonstrate this through availability-based contracts that retain equipment ownership. Priority investment in IP68-rated submersible electronics addresses the engineer shortage limiting robotic cleaner development velocity.
For New Entrants and Emerging Players: Portable skid-mounted units for monsoon-driven irrigation authorities in Maharashtra and Gujarat represent the most penetrable entry point, with cost-optimized mechanical designs bypassing electromechanical complexity. Seasonal water management applications lack dedicated suppliers beyond General Mechanical Works Pvt. Ltd. Go-to-market through state irrigation department tender desks, leveraging BIS certification as table stakes.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because EU Water Framework Directive enforcement and EPA cooling water intake tightening create non-discretionary replacement cycles. Acquisition targets should display sensor-to-actuator integration capability or established service contracting relationships with KBA-type river basin authorities. Monitor MEE discharge standard evolution in China as inflection signal for Asian procurement redirection.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-to-Actuator Integration | Acoustic debris detection fused with automated rake positioning enables predictive maintenance cycles for Rhine basin hydropower operators. |
| Availability-Based Contracting | OEM retention of equipment ownership guarantees debris-free intake operation, generating recurring revenue from German municipal utilities. |
| Submersible Electronics Certification | IP68 and ISO 20653 validation accelerates robotic cleaner deployment in confined-access reservoir intakes. |
| Backward Integration into Hydraulics | In-house production of high-pressure actuators mitigates supply concentration risk from German-Austrian component specialists. |
| Geographic Expansion to Alpine Corridor | Danube basin run-of-river installations require electromechanical upgrades to meet current debris management standards. |
Research Methodology
The analysis maps automatic, robotic, manual, and semi-automatic system sub-sectors, each validated through hydropower plant engineers, municipal utility procurement officers, irrigation authority maintenance directors, and aftermarket service heads. Primary interview intelligence combined with secondary validation from EU KBA river basin authority filings, EPA cooling water intake regulation dockets, Central Electricity Authority standards, and customs trade data for stainless steel components. Bottom-up installation tracking and top-down infrastructure spending analysis triangulate market sizing.
Assumptions held fixed include current EU Water Framework Directive enforcement intensity and prevailing stainless steel price bands, while variables included MEE standard evolution in China and monsoon intensity patterns affecting South Asian irrigation demand. The analytical framework models product type, installation configuration, end-user vertical, and cleaning method segmentation across the projection horizon. CAGRs derive from infrastructure replacement cycle analysis and regulatory compliance deadline clustering, with hydropower turbine overhaul schedules and municipal asset lifecycle data as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in stainless steel commodity pricing, hydropower investment flows, or irrigation budget allocations would shift the trajectory. The analysis reflects documented assumptions, with regulatory enforcement intensity, supply chain disruption events, or sensor technology breakthroughs as specific risk factors that could prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
North America Construction Equipment Market
Construction Equipment
Global Industrial Parts Washer Market
Construction Equipment
Bucket Elevator Market
Construction Equipment
Engine Driven Welders Market
Construction Equipment
Asia-Pacific Hydraulic Equipment Market
Construction Equipment
Oxy-Fuel Welding Equipment Market
Construction Equipment
Compaction Equipment Market
Construction Equipment
Canada Construction Equipment Market
Construction Equipment
Compact Power Equipment Rental Market
Construction Equipment
Assembly Machine Market
Construction Equipment
Mini Cranes Market
Construction Equipment
Crane Aftermarket Market
Construction Equipment
Manhole Housing Lifter Hook Market
Construction Equipment
Plasma Welding Machine Market
Construction Equipment
Concrete NDT Testing Equipment Market
Construction Equipment
Asia Pacific Construction Equipment Rental Market