
 North America HVAC Filter Change Service Market | 2026-2036
North America HVAC Filter Change Service Market Size, Share, and Industry Trends Forecast 2026-2036
North America HVAC Filter Change Service Market Insights
Buyer concentration among multi-site property operators is shifting toward national facility management contracts that bundle HVAC filter replacement with broader mechanical services. Aire Serv leverages its franchise network to sustain coverage across secondary metros where independent technicians struggle to scale. Commercial Filter Service, Inc. anchors its position through direct relationships with school districts and municipal building portfolios. Hyland Filter Service competes by specializing in high-occupancy environments such as healthcare and senior living facilities.
HVAC filter change service encompasses the scheduled inspection, removal, disposal, and installation of air filtration media within heating, ventilation, and air conditioning systems, typically performed at intervals calibrated to MERV rating and operating hours. Technicians assess pressure differentials, seal integrity, and frame condition to maintain rated airflow and particulate capture efficiency. Residential service contracts dominate transaction volume but compress margins through price-sensitive homeowners, while commercial quarterly programs generate superior recurring revenue per account. HEPA and pleated filter categories command premium positioning due to tighter particulate standards and longer effective service life. Activated carbon segments serve niche odor and VOC applications with concentrated demand near industrial zones and urban cores.
ASHRAE standards, EPA indoor air quality protocols, and OSHA ventilation requirements collectively elevate compliance burdens for building operators across the United States and Canada. These frameworks mandate documented maintenance intervals and performance verification, converting discretionary filter replacement into contracted obligations. Facility managers must weigh technician certification depth against software-enabled dispatch platforms as service models diverge between labor-heavy and technology-augmented delivery.
Market Dynamics
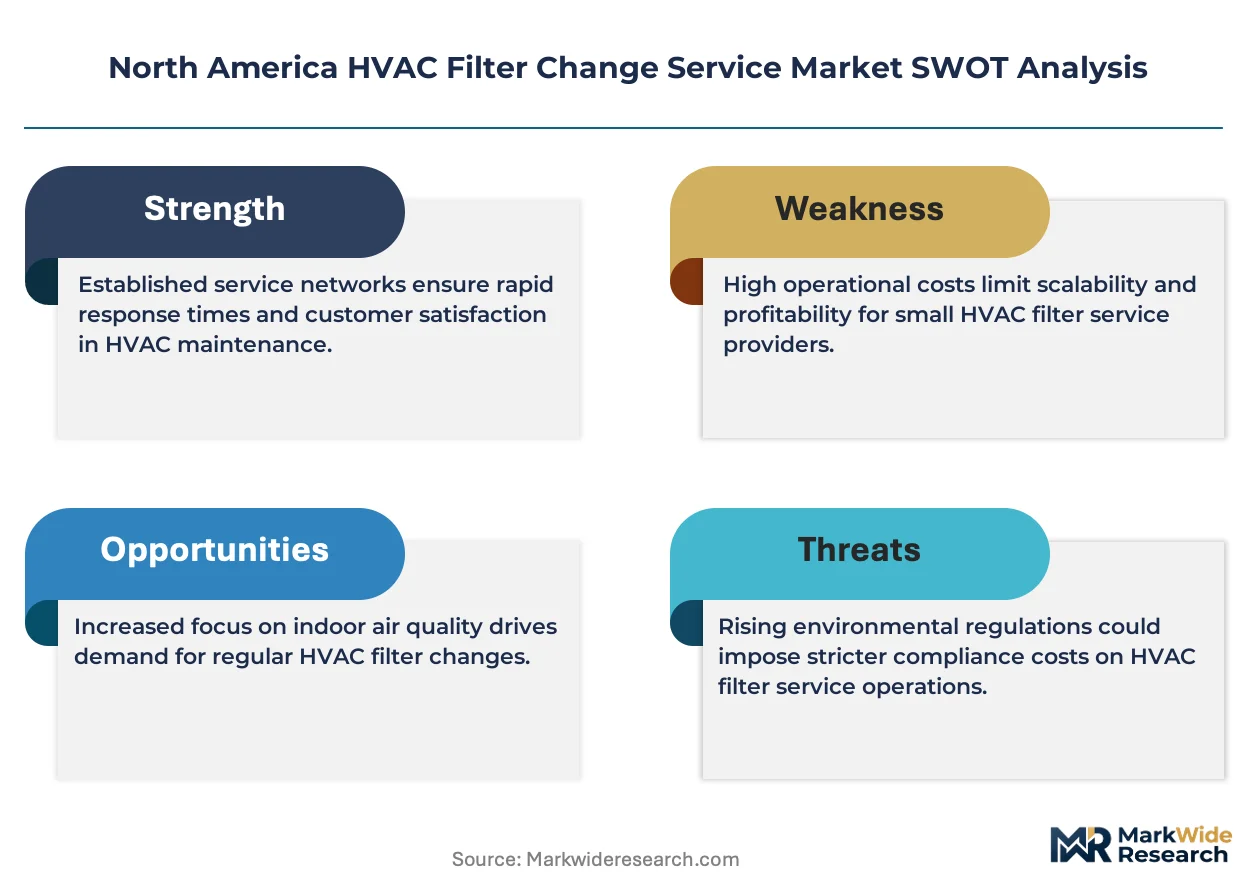
Multi-site property operators are consolidating vendor relationships into bundled facility management contracts, compressing standalone filter service margins while elevating scale requirements for regional providers. This buyer concentration is accelerating platform investments and technician certification depth among surviving competitors.
Growth Catalysts
- ASHRAE Standard 62.1 revisions:The updated ventilation rate requirements mandate documented filter maintenance intervals across commercial buildings, converting discretionary replacement into contracted compliance obligations for facility managers.
- Healthcare occupancy standards:Hospitals and senior living facilities are expanding HEPA-grade filter programs to meet Joint Commission infection control protocols, creating premium service tiers with quarterly inspection cycles.
- Texas metropolitan construction:Dallas-Fort Worth and Houston commercial development corridors are generating concentrated demand for filter change services tied to new HVAC commissioning and energy retrofit projects.
Market Restraints
- Pleated media supply concentration:Domestic manufacturing of MERV 13+ filter media concentrates among three specialized mills, exposing service contractors to input cost volatility and allocation constraints during demand surges.
- OSHA silica exposure rules:Disposal protocols for loaded filters containing construction dust now require documented handling procedures, adding labor cost and liability exposure to residential service routes.
- DIY retail substitution:Big-box retailers and e-commerce platforms are capturing price-sensitive residential replacement volume through subscription delivery models, compressing margins for entry-level service contracts.
Strategic Opportunities
- Canadian commercial underpenetration:Toronto and Vancouver multi-tenant office markets show lower contracted filter service penetration than comparable US metros, offering first-mover expansion paths for US-based platform operators.
- IoT-enabled predictive maintenance:Integration of pressure differential sensors with dispatch software allows technicians to optimize route density and justify premium pricing through documented performance verification.
- IRA commercial building incentives:Federal tax deductions for energy-efficient HVAC upgrades are accelerating system replacements, creating bundled filter service attach opportunities during contractor handoffs.
Industry Challenges
- EPA refrigerant handling certification:Technicians performing filter changes near coil access points now require Section 608 credentials, narrowing the qualified labor pool and extending recruitment timelines for service firms.
- Legacy building automation integration:Older commercial properties with proprietary HVAC control systems resist standardized sensor deployment, forcing costly custom integration work for predictive maintenance platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America HVAC Filter Change Service Market |
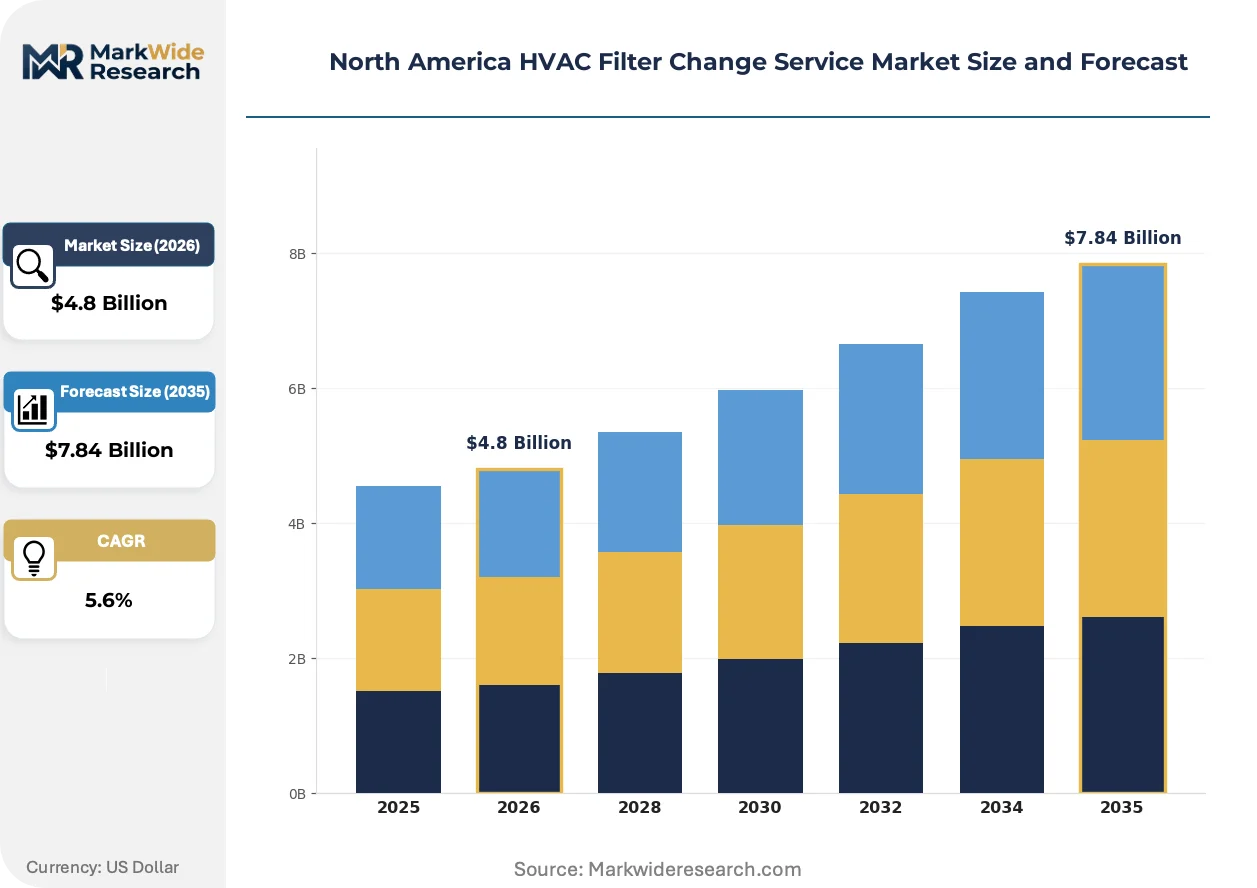
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residential, Commercial, Industrial, Retail Customer Type: Homeowners, Property Managers, Facility Managers, Business Owners Filter Type: HEPA, Pleated, Fiberglass, Activated Carbon Frequency: Monthly, Quarterly, Bi-Annual, Annual |
| Companies Covered | Hyland Filter Service, Snappy Services, Aire Serv, JOE FILTER, LLC, Commercial Filter Service, Inc., Plumbing & Air Conditioning Company, Grande Air Solutions, Joe W. Fly Co., American Residential Services LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America HVAC Filter Change Service Market Trends and Innovations
Electrostatic and antimicrobial filter media are displacing conventional pleated products in high-occupancy environments, while software-enabled dispatch platforms are compressing route inefficiencies that once protected regional incumbents. These shifts are rewriting competitive differentiation from labor density toward data-driven service verification.
Antimicrobial pleated filters incorporating copper and silver ion technology are rewriting service interval economics for healthcare and education facilities. Kaiser Permanente and HCA Healthcare systems are adopting these products on 6-month replacement cycles rather than standard quarterly schedules. The extended effective life is compressing transaction volume per account while elevating per-visit revenue and justifying premium positioning.
EPA indoor air quality guidelines and ASHRAE Standard 62.1-2022 are mandating documented filter performance verification for commercial buildings over 25,000 square feet. Facility managers must now maintain pressure differential logs and MERV rating documentation for inspection. School districts and municipal building portfolios are responding by converting discretionary maintenance into contracted quarterly programs with certified technicians.
Buying committees at multi-site property operators are consolidating mechanical service vendors into single-source national contracts. Cushman & Wakefield and JLL facility management teams are replacing fragmented local filter suppliers with bundled HVAC maintenance agreements. This concentration is most visible in Sun Belt office and industrial markets where portfolio owners prioritize vendor reduction over price minimization.
North America HVAC Filter Change Service Market Segmentation
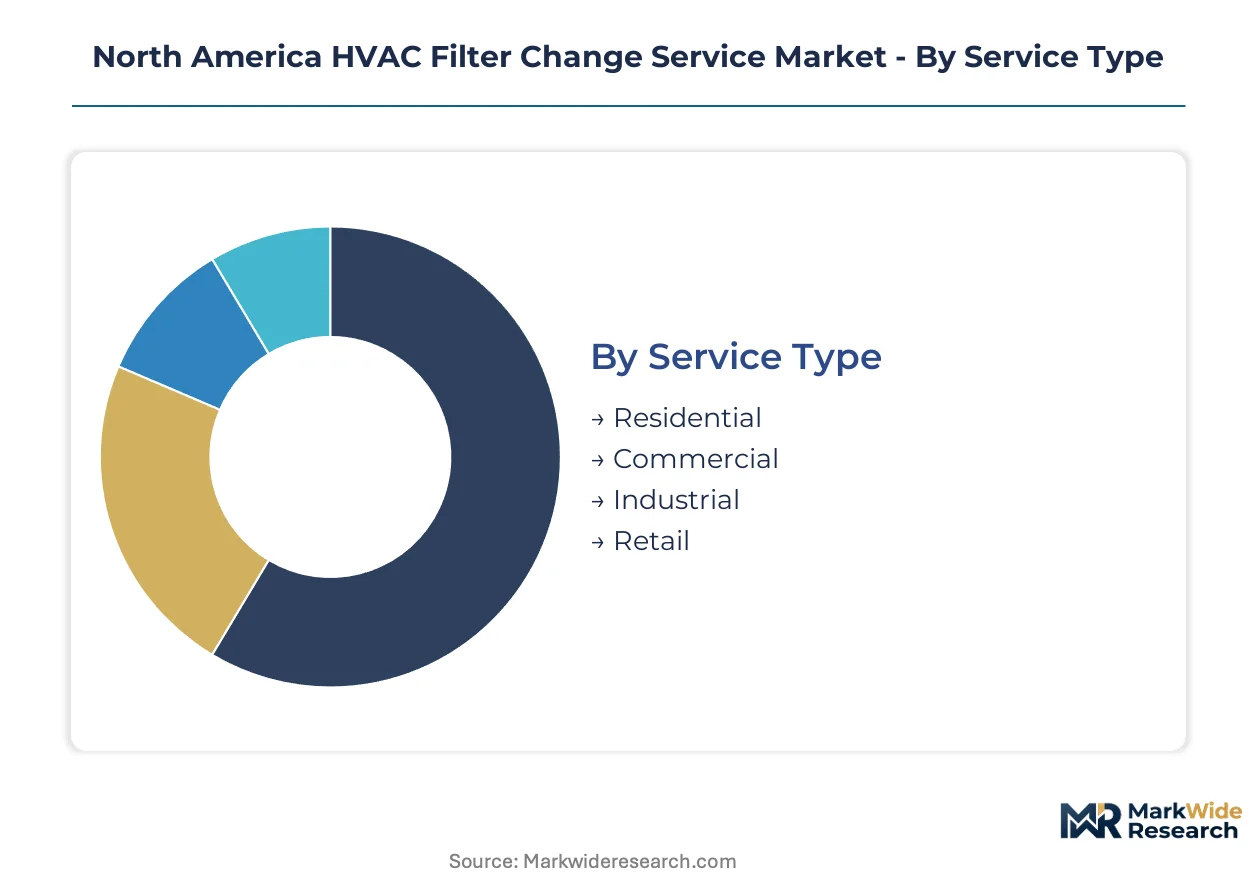
Segmentation in the North America HVAC filter change service market reveals how capital requirements, compliance burdens, and route economics concentrate profitability across distinct service tiers. Understanding these divisions helps operators allocate technician capacity and inventory investments toward the most defensible contract structures.
Service Type:
Capital intensity varies sharply across service tiers, with industrial deployments requiring specialized containment equipment and commercial programs demanding fleet-scale logistics platforms.
- Commercial:Multi-tenant office and healthcare facilities drive contracted quarterly programs with documented ASHRAE compliance. Texas metropolitan corridors concentrate new build commissioning demand alongside energy retrofit filter upgrades.
- Residential:Homeowners purchase discrete replacement visits or annual subscriptions, though DIY retail substitution compresses margins. Route density challenges favor franchise networks with hyperlocal technician placement.
- Industrial:Manufacturing plants and warehouse distribution centers require MERV 13+ media with pressure differential monitoring.
- Retail:Big-box and restaurant chains operate on standardized national schedules with centralized procurement.
Commercial absorbs the bulk of installed capacity; industrial is expanding most quickly.
Customer Type:
Procurement authority concentrates differently across buyer categories, shaping contract terms and service bundling opportunities.
- Facility Managers:Hospital and senior living administrators hold capital budgets for HEPA-grade programs with Joint Commission documentation requirements. Kaiser Permanente and HCA Healthcare systems are consolidating vendor relationships into single-source mechanical service agreements.
- Property Managers:Multi-site operators at Cushman & Wakefield and JLL are bundling filter replacement into national facility management contracts, squeezing standalone providers.
- Homeowners:Price-sensitive residential buyers respond to subscription pricing and seasonal promotions.
- Business Owners:Small commercial accounts lack procurement sophistication and tolerate higher per-visit costs.
Facility managers command the highest contract values; property managers are consolidating fastest.
Filter Type:
Product mix determines inventory carrying costs and technician training depth, with premium media requiring certification investments.
- Pleated:MERV 8-13 synthetic media dominates commercial replacement cycles with 90-day standard intervals. Domestic manufacturing concentrates among three specialized mills, exposing contractors to allocation risk during demand surges.
- HEPA:Healthcare and cleanroom applications mandate 99.97% efficiency at 0.3 microns with sealed frame installation protocols. Extended replacement cycles and premium pricing justify specialized technician certification.
- Fiberglass:Entry-level residential throwaway panels serve price-sensitive replacement demand.
- Activated Carbon:Odor and VOC applications concentrate near industrial zones and urban cores with poor ambient air quality.
Pleated media absorbs the bulk of installed capacity; HEPA is climbing the fastest.
Frequency:
Scheduling patterns reveal compliance-driven versus discretionary demand, with regulatory mandates converting variable replacement into fixed obligations.
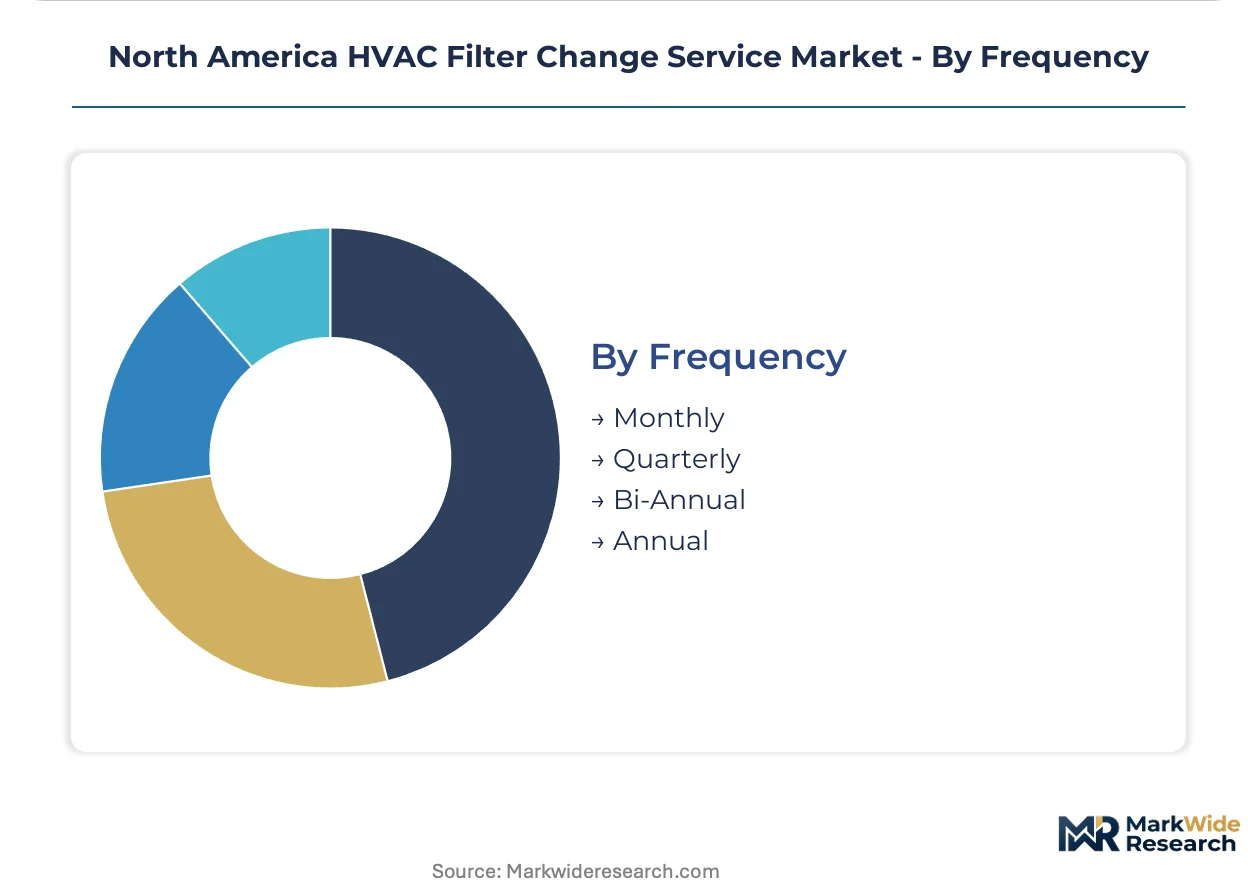
- Quarterly:ASHRAE Standard 62.1-2022 mandates documented filter performance verification for commercial buildings over 25,000 square feet. School districts and municipal portfolios are converting discretionary maintenance into contracted quarterly programs.
- Monthly:High-occupancy healthcare and education facilities with antimicrobial media still require frequent inspection despite extended media life.
- Bi-Annual:Low-utilization commercial and premium residential accounts balance cost against airflow degradation.
- Annual:Minimal-service residential contracts capture price-sensitive homeowners with basic fiberglass replacement.
Quarterly scheduling absorbs the bulk of contracted volume; monthly is gaining share fastest in healthcare segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Synthetic filter media production concentrates in the southeastern United States, where specialized mills supply MERV-grade materials to service contractors across the continent.
United States
Texas metropolitan corridors generate concentrated demand from Dallas-Fort Worth and Houston commercial development, where new HVAC commissioning and energy retrofit projects require contracted filter maintenance. EPA indoor air quality guidelines and ASHRAE Standard 62.1 revisions mandate documented performance verification for buildings exceeding 25,000 square feet. School districts in California and municipal portfolios in Florida are converting discretionary maintenance into quarterly compliance programs.
Canada
Toronto and Vancouver multi-tenant office markets show lower contracted filter service penetration than comparable US metros, creating expansion opportunities for platform operators. Health Canada ventilation guidelines align with ASHRAE protocols, establishing comparable compliance frameworks for commercial building operators. Alberta's energy sector facilities and British Columbia healthcare systems are adopting HEPA-grade programs with documented inspection cycles.
Mexico
Industrial manufacturing zones near Monterrey and Tijuana require MERV 13+ media for dust-sensitive production environments, driving premium service tiers. Mexican environmental regulations under SEMARNAT establish air quality monitoring obligations for manufacturing facilities. Mexico City commercial development and Guadalajara industrial corridors are generating new build commissioning demand for filter service contracts.
North America HVAC Filter Change Service Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue technology-augmented dispatch platforms and predictive maintenance software. The market structure reflects moderate fragmentation with regional incumbents defending route density against national facility management bundling. Three archetypes dominate: franchise networks with hyperlocal technician placement, direct-contract specialists holding school district and municipal relationships, and platform operators integrating IoT sensors for performance verification. Consolidation pressure is accelerating through buyer concentration among multi-site property operators, while differentiation shifts from labor density toward data-driven service verification.
Among franchise-network operators, Aire Serv leverages its distributed coverage model to sustain presence across secondary metros where independent technicians face scaling constraints. Commercial Filter Service, Inc. anchors the direct-contract specialist archetype through relationships with institutional building portfolios. Hyland Filter Service occupies the healthcare-specialist position, serving high-occupancy environments with HEPA-grade programs and extended replacement cycles. These three represent distinct competitive vectors: geographic coverage breadth, institutional relationship depth, and vertical specialization intensity.
| Leading Market Players |
|---|
| Hyland Filter Service |
| Snappy Services |
| Aire Serv |
| JOE FILTER, LLC |
| Commercial Filter Service, Inc. |
| Plumbing & Air Conditioning Company |
| Grande Air Solutions |
| Joe W. Fly Co. |
| American Residential Services LLC |
| Others |
Pricing and Supply Chain Analysis
Antimicrobial pleated media incorporating copper and silver ion technology is simultaneously extending service interval economics and concentrating premium-tier pricing power among certified installation networks. This production-method transition elevates per-visit revenue for healthcare-specialist contractors while compressing transaction volume, reshaping cost structures across the MERV-grade supply base.
Pricing Analysis
Warranty-backed installation protocols and documented ASHRAE compliance verification separate bundled commercial contracts from unbundled residential replacements. Three-tier pricing structure across premium HEPA-grade, standard pleated MERV 8-13, and economy fiberglass panels reflects certification depth and route density advantages. Pricing pressure stems from DIY retail subscription models capturing price-sensitive homeowners, while facility managers at Kaiser Permanente and HCA Healthcare systems show lowest price sensitivity due to Joint Commission documentation requirements.
Supply Chain Analysis
Technician certification bottlenecks in EPA Section 608 credentials and specialized MERV-grade media production in southeastern US mills constrain upstream capacity expansion. Domestic manufacturing of synthetic filter media draws from three specialized mills, with polyester and fiberglass raw materials sourced from petrochemical feedstocks. Single-source vulnerability concentrates in MERV 13+ media allocation during demand surges, while distribution runs through franchise networks, direct-contract specialists, and national facility management bundlers to end-use facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASHRAE Standard 62.1-2022 and EPA indoor air quality guidelines have converted discretionary filter replacement into contracted compliance obligations, erecting regulatory moats that favor certified incumbents with documented technician credentialing and software-enabled dispatch platforms.
For Market Incumbents: Deepen vertical integration into MERV-grade media sourcing through direct mill relationships or captive inventory positions to defend against allocation constraints during demand surges. Reinforce technician certification depth in EPA Section 608 credentials and IoT-enabled predictive maintenance platforms to differentiate from labor-only regional competitors as Cushman & Wakefield and JLL consolidate vendor relationships into bundled national contracts. For New Entrants and Emerging Players: The pricing gap between premium HEPA-grade healthcare programs and economy residential subscriptions offers entry points for mid-tier commercial specialists. Target Toronto and Vancouver multi-tenant office markets showing lower contracted penetration than comparable US metros, leveraging Health Canada ventilation guideline alignment with ASHRAE protocols to accelerate first-mover positioning through direct facility manager relationships rather than franchise network buildout. For Investors and Strategic Acquirers: Re-rating potential sits with platform operators integrating IoT pressure differential sensors and predictive dispatch software given IRA commercial building incentives accelerating HVAC replacement cycles and bundled filter service attach opportunities. Acquisition focus should center on regional incumbents with dense route economics in Texas metropolitan corridors or healthcare-specialist firms holding Joint Commission documentation relationships, with technician certification backlogs and sensor deployment penetration serving as inflection indicators for platform scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Investment | EPA Section 608 credentials narrow qualified labor pools and extend recruitment timelines for scaling service firms. |
| IoT Sensor Platform Integration | Pressure differential monitoring with dispatch software optimizes route density and justifies premium pricing through documented verification. |
| Healthcare Vertical Specialization | Kaiser Permanente and HCA Healthcare systems consolidate vendor relationships into single-source mechanical service agreements with antimicrobial media protocols. |
| Canadian Market Expansion | Toronto and Vancouver multi-tenant offices show lower contracted penetration than US metros, offering first-mover paths. |
| Mill Relationship Deepening | Direct sourcing from southeastern US specialized mills mitigates MERV 13+ allocation risk during demand surges. |
Research Methodology
Independent corroboration across facility management executives at Cushman & Wakefield and JLL, HVAC service contractor operations directors, and filter media procurement leads at specialized mills underwrites the qualitative findings in this study. Primary interviews with franchise network operators, direct-contract specialists, and healthcare facility engineers combined with secondary validation from ASHRAE standard documentation, EPA indoor air quality protocol filings, and Health Canada ventilation guidelines. Bottom-up route density modeling and top-down market sizing triangulate volume estimates across the analysis window.
Rate-of-change decomposition separates installed base expansion from replacement cycle compression and premium-tier mix shift effects across the projection horizon. Segmentation dimensions include service type, customer procurement authority, filter media grade, and scheduling frequency, with Texas metropolitan construction permitting data and healthcare occupancy standards serving as industry-specific forecast inputs. CAGRs derive from logistic curve fitting to regulatory adoption patterns and vendor consolidation trajectories.
Inputs from ASHRAE technical committees and EPA compliance documentation were available through the study window; gaps in real-time franchise network financial disclosures introduce uncertainty bands around market share estimates. Forecasts reflect assumptions regarding regulatory enforcement consistency and technician certification pipeline expansion. Material deviation in IRA incentive renewal schedules or MERV-grade media mill capacity additions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
HVAC Systems Market
HVAC Equipment
Electric Underfloor Heating Market
HVAC Equipment
Warm Air Heater Market
HVAC Equipment
Global Fan Coil Unit Market
HVAC Equipment
Dedicated Outdoor Air System Market
HVAC Equipment
Commercial HVAC Market
HVAC Equipment
Water Softener Equipment Market
HVAC Equipment
Hydro Chillers Market
HVAC Equipment
United Kingdom Commercial HVAC Market
HVAC Equipment
Europe Heating Radiator Market
HVAC Equipment
Heat Moisture Exchanger Market
HVAC Equipment
Compressed Air Treatment Equipment Market
HVAC Equipment
Europe Bus HVAC Market
HVAC Equipment
US Heating Equipment Market
HVAC Equipment
US Residential HVAC Systems Market
HVAC Equipment
Global Home Ventilation System Market