
 Latin America Construction Equipment Market | 2026-2036
Latin America Construction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Construction Equipment Market Outlook
Asset-light leasing and rental-service models are reshaping competitive dynamics across Latin America. Caterpillar leverages its captive finance arm to control customer relationships in Mexico's infrastructure belt. Komatsu sustains manufacturing scale through its regional assembly hub in Brazil. SANY competes on cost-optimized hydraulic excavators tailored for mid-tier contractors.
Latin America construction equipment encompasses earth-moving, lifting, and material-handling machinery powered by diesel, hydraulic, or electric drivetrains, typically engineered for operating temperatures between minus 10 and 50 degrees Celsius and altitudes up to 4,500 meters to serve mining and civil works across varied topography. Excavators dominate volume due to versatility across trenching, loading, and demolition tasks in Brazil's urban renewal sites. Smart Equipment represents the fastest-growing technology segment as telematics-enabled fleet management reduces idle time and fuel burn for mining contractors in Chile. Diesel-powered units retain the largest installed base, though margin pools are shifting toward electric and hybrid configurations where total cost of ownership advantages emerge in high-utilization applications.
Brazil's CONAMA and Mexico's PROFEPA enforce emissions and environmental compliance standards that elevate engine certification costs and reshape product portfolios. ANVISA in Brazil and the country's national mining regulator impose operational safety protocols that drive replacement cycles for aging fleets. Stakeholders must monitor how carbon-border adjustment mechanisms in key export destinations reshape equipment specification requirements for Latin American contractors serving international projects.
Market Dynamics
Fleet electrification pressures are colliding with CONAMA emission mandates across Brazil, forcing OEMs to reconfigure powertrain portfolios while mining contractors in Chile and Peru accelerate autonomous haulage deployments to offset labor scarcity and fuel volatility.
Growth Catalysts
- Autonomous haulage systems:Mining operators in Chile's Atacama Desert are deploying self-driving truck fleets to sustain 24-hour operations amid skilled operator shortages.
- Urban rail infrastructure:São Paulo's metropolitan transit authority is expanding subway and commuter lines, generating sustained demand for tunnel boring machines and hydraulic excavators.
- PROFEPA enforcement protocols:Mexico's environmental regulator is accelerating equipment replacement cycles through stricter site inspection regimes and emission verification mandates.
Market Restraints
- Diesel engine certification costs:Brazil's CONAMA Resolution 693 compliance requirements are elevating R&D expenditure for powertrain manufacturers serving the regional market.
- Import dependency for electronic control modules:Supply concentration in East Asian semiconductor fabs creates vulnerability for telematics-enabled fleet management systems.
- High-altitude performance degradation:Turbocharger efficiency losses above 3,500 meters limit equipment deployment effectiveness in Peru's central mining corridor.
Strategic Opportunities
- Colombia's infrastructure gap:The country's 4G and 5G highway concession programs are opening procurement windows for earth-moving contractors previously focused on Brazilian and Mexican markets.
- Battery-electric compact equipment:Urban demolition and interior renovation segments in Buenos Aires and Santiago are piloting zero-emission mini-excavators for noise-restricted zones.
- Telematics-ERP integration:Construction firms are demanding API-connected fleet data streams to synchronize equipment utilization with project management software.
Industry Challenges
- Mechatronics technician scarcity:Mining contractors in Chile struggle to recruit personnel capable of servicing electro-hydraulic hybrid drivetrains and autonomous control systems.
- ANVISA operational safety recertification:Brazil's health surveillance agency is extending approval timelines for modified equipment configurations, delaying fleet deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Construction Equipment Market |
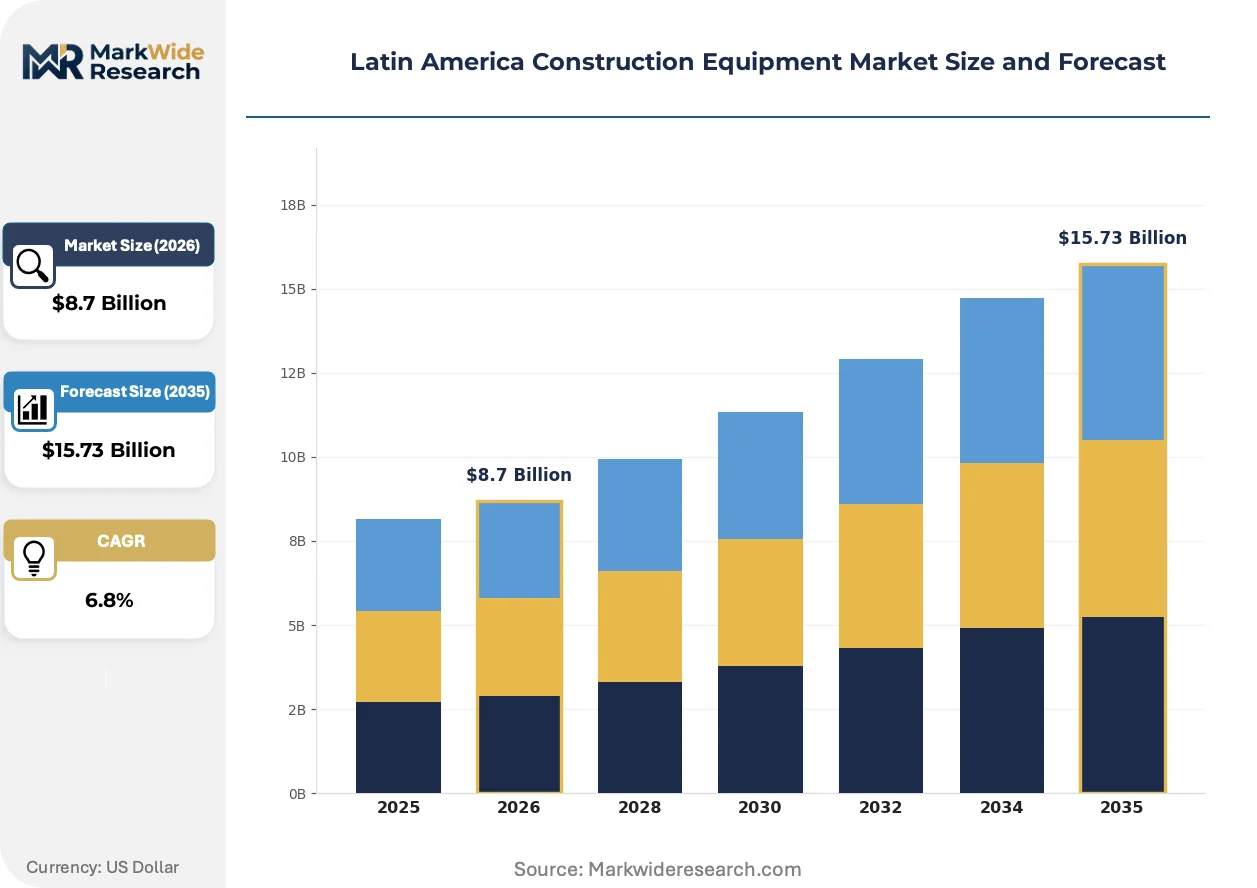
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
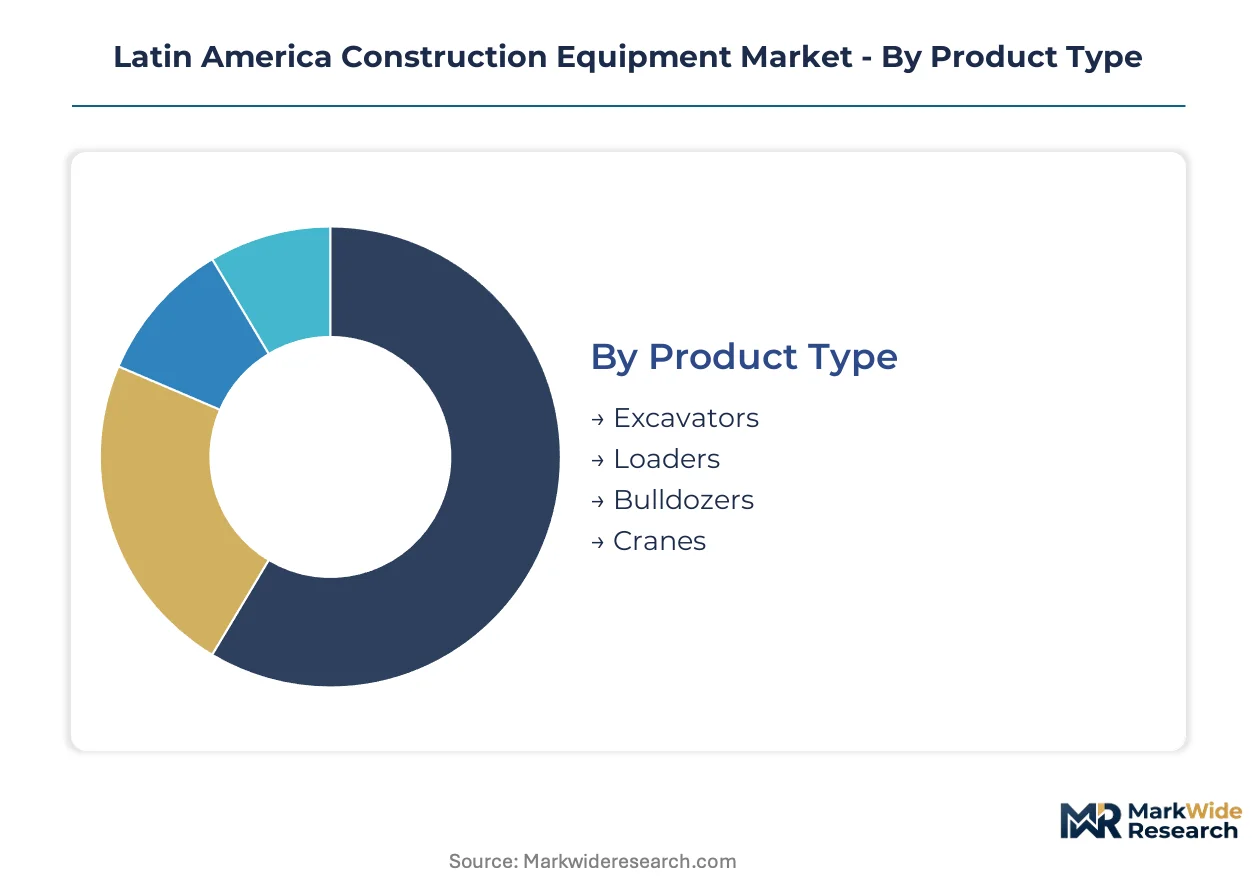
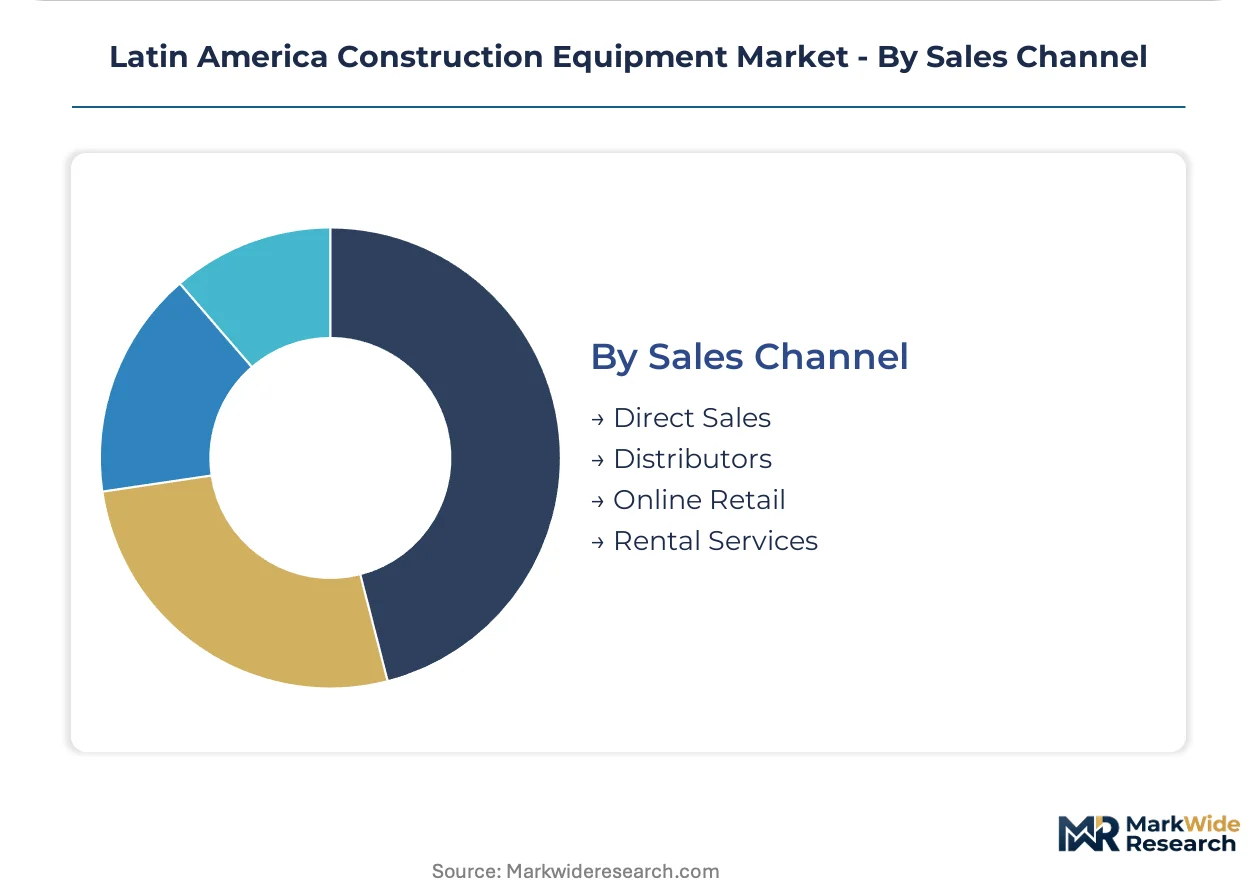
| Segmentation | Product Type: Excavators, Loaders, Bulldozers, Cranes End User: Infrastructure, Mining, Residential, Commercial Technology: Hydraulic, Electric, Diesel, Smart Equipment Sales Channel: Direct Sales, Distributors, Online Retail, Rental Services |
| Companies Covered | Hitachi Construction Machinery, XCMG, Caterpillar, JCB, SANY, Komatsu, Liebherr, Hyundai Construction Equipment, Volvo Construction Equipment, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Construction Equipment Market Strategic Shifts
Digital fleet management architectures are supplanting traditional maintenance scheduling across Latin American mining and civil construction operations, compressing equipment lifecycle economics and reshaping supplier-customer relationships.
Electro-hydraulic hybrid powertrains are integrating regenerative braking and engine-downsizing architectures to reduce fuel consumption in high-cyclic loading applications. Mining contractors in Chile's copper belt are piloting these configurations on 40-ton-class excavators to hedge diesel price volatility. Conventional mechanical-hydraulic systems without energy recovery are rendering obsolete for new fleet acquisitions in high-utilization sites.
Brazil's CONAMA Resolution 693 is mandating Stage V-equivalent emission standards for diesel engines above 130 kW, effective for new equipment registrations. Engine manufacturers are consolidating product lines to limit certification burden, reducing model variety available to regional distributors. Earth-moving equipment in the 20-50 ton class faces the steepest compliance cost escalation, pushing rental fleets toward extended depreciation cycles.
Equipment-as-a-service contracting is displacing traditional capital purchase and operating lease structures among mid-tier Brazilian contractors. Rio de Janeiro-based construction firms are unbundling maintenance, telematics, and operator training into per-hour usage fees. This model concentrates most visibly in southeastern Brazil's urban renewal and port logistics verticals, where project duration uncertainty discourages balance-sheet asset ownership.
Latin America Construction Equipment Market Segmentation
Equipment specification requirements diverge sharply across Latin American operating environments. Mining contractors in Chile's Atacama prioritize altitude-rated powertrains, while Brazilian urban developers demand compact footprints for dense São Paulo construction zones.
Product Type:
Replacement cycles stretch from 8,000 hours for utility excavators to 15,000+ hours for heavy mining loaders, creating distinct aftermarket revenue timing across the installed base.
- Excavators:Hydraulic boom and arm configurations dominate trenching, loading, and demolition tasks. Demand concentrates in Brazil's southeastern urban renewal sites where São Paulo's metropolitan transit authority deploys mid-size units for subway line extensions.
- Loaders:Articulated wheel and track configurations handle bulk material movement with rapid cycle times. Mining contractors in Peru's central corridor specify high-altitude turbocharged variants to offset efficiency losses above 3,500 meters.
- Bulldozers:Crawler-mounted blade systems serve site preparation and grading applications across Colombian 4G highway concessions.
- Cranes:Tower and mobile lifting equipment support vertical construction in Rio de Janeiro's port upgrade zones.
Excavators anchor the volume base while Smart Equipment configurations gain share at the steepest rate.
End User:
Customer procurement sophistication spans from price-driven residential contractors to total-cost-of-ownership focused mining houses with captive maintenance infrastructure.
- Mining:Large-scale extraction operations demand 24-hour utilization rates and autonomous haulage compatibility. Chilean copper belt operators are retrofitting existing fleets with telematics-enabled predictive maintenance systems to minimize unplanned downtime in remote Atacama locations.
- Infrastructure:Government-backed transit and highway projects require equipment compliance with ANVISA safety protocols and CONAMA emission standards. Brazil's southeastern states generate sustained machinery deployment for São Paulo urban rail extensions.
- Residential:Small-scale developers and individual contractors favor rental service models to avoid balance-sheet asset ownership amid project duration uncertainty.
- Commercial:Office and retail construction segments in Buenos Aires and Santiago are piloting battery-electric compact equipment for noise-restricted urban zones.
Mining anchors the volume base while Infrastructure expands most quickly on concession program momentum.
Technology:
Powertrain cost structures stratify sharply, with diesel certification burdens pushing mid-tier contractors toward hybrid alternatives where utilization rates justify premium acquisition costs.
- Smart Equipment:Telematics-integrated fleet management systems compress maintenance scheduling and fuel consumption tracking. Mining contractors in Chile deploy these configurations to synchronize equipment utilization with ERP project management software.
- Diesel:Stage V-equivalent engines above 130 kW face CONAMA Resolution 693 compliance cost escalation. Brazilian distributors are consolidating model variety to limit certification burden on earth-moving equipment in the 20-50 ton class.
- Hydraulic:Conventional mechanical-hydraulic systems without energy recovery are rendering obsolete for new fleet acquisitions in high-utilization sites.
- Electric:Battery-electric compact excavators serve interior renovation and demolition segments with zero-emission profiles for PROFEPA-monitored work zones.
Diesel anchors the volume base while Smart Equipment climbs the fastest on digital fleet management adoption.
Sales Channel:
Channel economics shift from capital-intensive inventory ownership toward recurring revenue models that align supplier incentives with customer uptime requirements.
- Rental Services:Per-hour contracting bundles maintenance, telematics, and operator training into usage-based fees. Rio de Janeiro construction firms favor this structure for port logistics and urban renewal verticals where project duration uncertainty discourages asset ownership.
- Distributors:Regional dealer networks provide aftermarket parts availability and field service coverage across Brazil's extended geography.
- Direct Sales:Large mining houses negotiate fleet procurement directly with OEM captive finance arms for autonomous haul truck deployments.
- Online Retail:Digital platforms serve small contractor spare parts procurement and used equipment remarketing.
Distributors anchor the volume base while Rental Services expands most quickly on asset-light model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
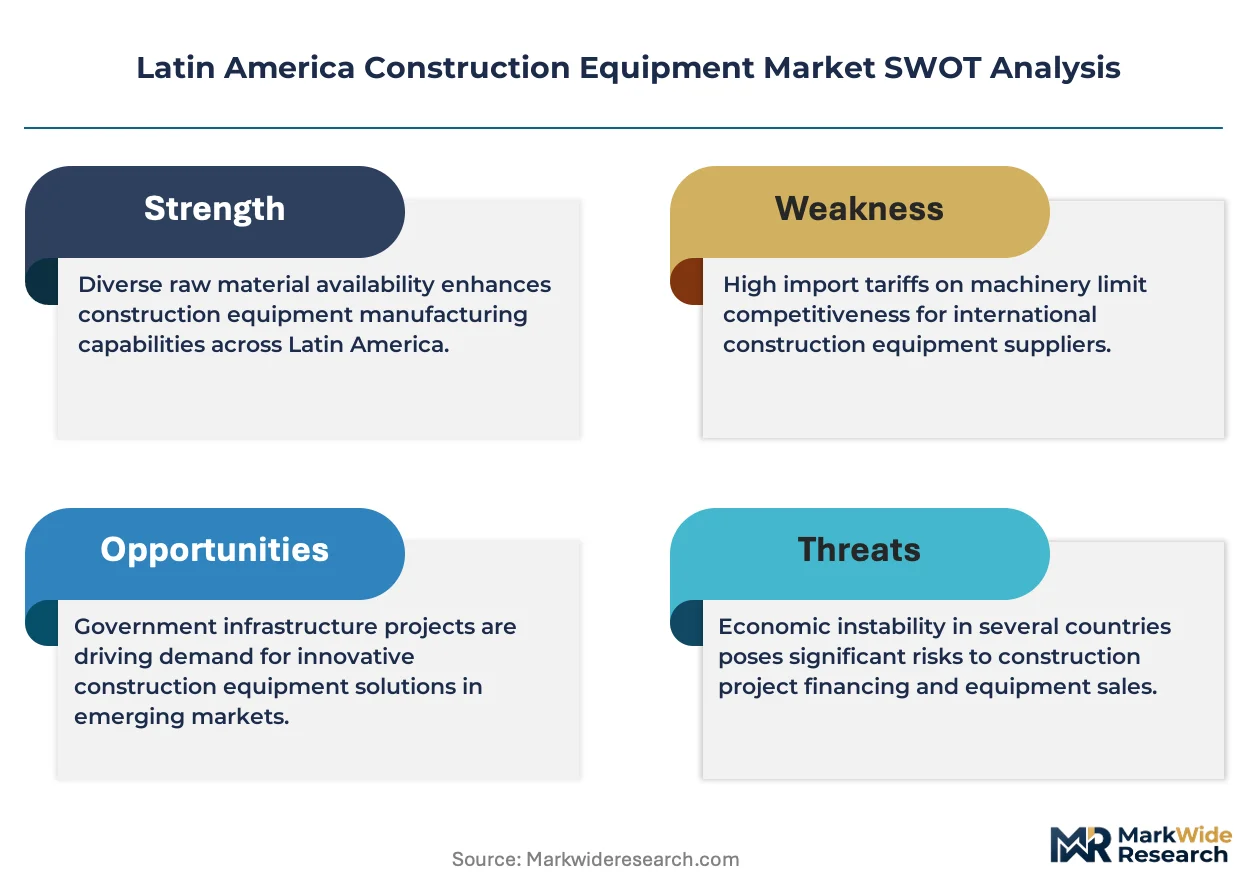
Import dependency for electronic control modules and powertrain components shapes trade balances across Latin American construction equipment markets. Brazil and Mexico absorb the largest equipment import volumes while Chile and Peru concentrate mining machinery deployments.
Brazil
São Paulo's metropolitan transit authority drives sustained demand for tunnel boring machines and hydraulic excavators through urban rail extensions. CONAMA Resolution 693 mandates Stage V-equivalent emission standards for diesel engines above 130 kW, elevating certification costs for regional distributors. The southeastern states cluster machinery deployment around Rio de Janeiro port upgrades and urban renewal corridors.
Mexico
PROFEPA enforcement protocols accelerate equipment replacement cycles through stricter site inspection regimes and emission verification mandates. The Mexico City Metro and infrastructure belt generate procurement volumes for mid-size excavators and material handlers. Nuevo León's industrial corridor concentrates fleet orders from construction firms serving manufacturing facility expansions.
Chile
Mining operators in the Atacama Desert deploy autonomous haul truck fleets to sustain 24-hour operations amid skilled operator shortages. The national mining regulator imposes operational safety protocols that drive replacement cycles for aging fleets. Antofagasta and Calama anchor copper belt machinery deployment where altitude-rated powertrains offset efficiency losses.
Peru
High-altitude performance requirements above 3,500 meters limit turbocharger efficiency in the central mining corridor, constraining equipment specification options. The Ministry of Energy and Mines oversees environmental compliance standards for extraction operations. Cerro de Pasco and La Oroya concentrate bulk material handling equipment serving polymetallic mining complexes.
Colombia
4G and 5G highway concession programs open procurement windows for earth-moving contractors previously focused on Brazilian and Mexican markets. The National Infrastructure Agency supervises concession compliance and equipment specification standards. Bogotá's urban periphery clusters compact equipment demand for road corridor development and residential vertical construction.
Latin America Construction Equipment Market Competitive Environment
On the supply side, the industry is tiered across integrated multinational OEMs, regional assembly specialists, and emerging cost-optimized manufacturers. Japanese and North American incumbents anchor premium positioning through captive finance and telematics integration. Chinese manufacturers occupy mid-market penetration through hydraulic excavator specialization. Strategic moves concentrate on rental-service model expansion and electrification portfolio reconfiguration.
Among Japanese heavy machinery specialists, Hitachi Construction Machinery and Komatsu exemplify integrated OEM archetypes with regional manufacturing footprints. XCMG and SANY represent Chinese manufacturers competing on cost-optimized equipment specifications for mid-tier contractors. Caterpillar anchors the premium tier through captive finance arms controlling customer relationships across Mexico's infrastructure belt.
| Leading Market Players |
|---|
| Hitachi Construction Machinery |
| XCMG |
| Caterpillar |
| JCB |
| SANY |
| Komatsu |
| Liebherr |
| Hyundai Construction Equipment |
| Volvo Construction Equipment |
| Others |
Value Chain & Pricing Dynamics
East Asian semiconductor fabs concentrate electronic control module supply for telematics-enabled fleet management systems, anchoring margin pools in aftermarket service contracts and predictive maintenance software rather than hardware sales alone. Brazilian distributors absorb CONAMA Resolution 693 certification cost escalations while Chilean mining contractors capture value through uptime-guaranteed rental structures.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers command brand premiums and captive finance bundling from Japanese and North American incumbents. Standard segments compete on hydraulic excavator specifications with Chinese manufacturers. Economy tiers face cost compression from extended depreciation cycles on diesel-powered units in Brazil's rental fleets. Mining houses with captive maintenance infrastructure exhibit lowest price sensitivity; residential contractors in Buenos Aires and Santiago show highest sensitivity.
Supply Chain Analysis
Contract manufacturers in China, South Korea, and Japan hold capacity for electronic control modules and telematics hardware. Powertrain components draw from German and Japanese engine specialists. Steel and hydraulic systems rest on Brazilian and Mexican foundries. Single-source vulnerability concentrates in East Asian semiconductor fabs. Distribution runs through regional dealer networks with aftermarket parts coverage across Brazil's extended geography.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a service-attach opportunity where predictive maintenance contracts and telematics-ERP integration layers expand faster than equipment hardware sales. Recurring revenue from per-hour rental structures and uptime guarantees now captures margin pools previously locked in capital sales.
For Market Incumbents: Build captive finance moats through equipment-as-a-service contracting that bundles maintenance, telematics, and operator training. Deepen backward integration into powertrain assembly to offset CONAMA certification cost pressure. Consolidate model variety to limit regulatory burden on 20-50 ton earth-moving equipment.
For New Entrants and Emerging Players: Build out battery-electric compact equipment portfolios for noise-restricted urban demolition segments in Buenos Aires and Santiago. Target Colombia's 4G and 5G highway concession programs where procurement windows have opened for contractors previously focused on Brazilian markets. Lead with API-connected fleet data streams that synchronize equipment utilization with project management software.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed rental fleet operators in southeastern Brazil where urban rail and port logistics verticals concentrate deployment. Long-term viability hinges on electrification portfolio reconfiguration and telematics platform ownership. Monitor ANVISA approval timeline extensions for modified equipment configurations as inflection indicator for fleet deployment delays.
| Strategic Initiative | Industry Significance |
|---|---|
| Rental-Service Model Expansion | Equipment-as-a-service contracting displaces capital purchases in Rio de Janeiro port zones. |
| Electrification Portfolio Reconfiguration | Battery-electric compact excavators penetrate PROFEPA-monitored work zones in Buenos Aires. |
| Telematics Platform Integration | API-connected fleet data streams synchronize utilization with ERP project management software. |
| Backward Integration into Powertrain Assembly | Regional engine manufacturing hedges CONAMA Resolution 693 certification cost escalation. |
| Geographic Manufacturing Footprint | Brazilian assembly hubs serve Chilean mining contractors with altitude-rated powertrain variants. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through primary interviews with mining fleet managers, construction project directors, OEM procurement teams, aftermarket service heads, and rental fleet operators. Secondary validation drew from ANVISA equipment safety filings, CONAMA emission compliance records, Chilean national mining regulator protocols, customs trade data for machinery imports, and SEC 10-K disclosures from listed OEMs. Bottom-up equipment deployment estimates triangulated against top-down market sizing across the analysis window.
Calibration anchored volume and value outputs to segment-level deployment rates across product type, end user, technology, and sales channel dimensions. CAGRs derived from fitted growth curves applied to equipment replacement cycles and concession program timelines. Industry-specific forecast inputs included São Paulo metropolitan transit authority procurement schedules, Chilean copper belt autonomous haulage deployment rates, and Colombian 4G/5G highway concession award progressions.
Sensitivities concentrate around CONAMA regulatory enforcement intensity, East Asian semiconductor supply disruptions, and Chilean mining labor contract negotiations. Forecasts reflect documented assumptions on equipment replacement timing and concession program execution. Quarterly review of ANVISA approval timelines, PROFEPA inspection regime expansion, and autonomous haulage pilot scale-up is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
(AWP) Aerial Work Platform Rental Market
Construction Equipment
Earthmoving Equipment Undercarriage Market
Construction Equipment
Middle East Flexible Concrete Vibrator Market
Construction Equipment
Industrial Steam Washer Market
Construction Equipment
Global PDC Drill Bits Market
Construction Equipment
Wood Chipping Machinery Market
Construction Equipment
Rotary Trommel Market
Construction Equipment
Concrete Placing Booms Market
Construction Equipment
Heavy Duty IBC Market
Construction Equipment
Crane Pumps Market
Construction Equipment
North America Crane Rental Market
Construction Equipment
Cutting and Bending Machine Market
Construction Equipment
Bitumen Sprayer Market
Construction Equipment
Rotary Blasthole Drilling Rig Market
Construction Equipment
CNC Router Market
Construction Equipment
Walform Machines Market