
 Middle-East and Africa Construction Adhesives Market | 2026-2036
Middle-East and Africa Construction Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Construction Adhesives Market Foresight
Low-VOC and water-based adhesive technology is tilting procurement specifications across Middle-East and Africa construction supply chains toward environmentally compliant formulations. Henkel AG & Co. KGaA leverages its regional formulation centers to adapt European-certified products for Gulf humidity extremes. Sika AG anchors its position through dedicated concrete bonding and waterproofing adhesive portfolios engineered for African infrastructure durability. Dow competes on silane-modified polymer chemistry that extends service life in Saudi coastal corrosion environments.
Construction adhesives comprise formulated bonding systems—typically incorporating polyurethane prepolymers, epoxy resins, or acrylic emulsions with viscosities ranging from 500 to 50,000 cPs—that structurally or semi-structurally join building materials without mechanical fasteners. Their primary industrial purpose spans facade assembly, flooring installation, and prefabricated panel bonding where thermal cycling resistance and substrate compatibility determine specification. Polyurethane formulations command the largest value share due to their elasticity and gap-filling performance in concrete and wood applications across Gulf residential towers. Water-based technology represents the fastest-expanding category as Dubai Municipality green building regulations and South Africa's SANS energy efficiency codes restrict solvent-based product specification. Reactive adhesive systems, including epoxies and moisture-cure polyurethanes, capture concentrated margin pools in infrastructure anchoring and structural glazing where load-bearing certification commands premium pricing.
Saudi Standards, Metrology and Quality Organization building material codes, South African Bureau of Standards adhesive performance specifications, and Dubai Municipality green building regulations collectively restrict solvent content and mandate bond-strength testing for structural applications. These frameworks compel manufacturers to reformulate product lines and obtain local certification before market access. Buyers and suppliers must monitor evolving harmonization between Gulf Cooperation Council technical regulations and African regional standards bodies to anticipate compliance cost structures and specification divergence.
Market Dynamics
Gulf Cooperation Council giga-project timelines and South African energy efficiency mandates are compressing specification cycles for high-performance bonding systems, forcing adhesive suppliers to accelerate certification throughput while reformulating for humidity extremes and thermal cycling resistance.
Growth Catalysts
- Saudi giga-project pipeline:NEOM, Red Sea Project, and Qiddiya developments require prefabricated panel bonding and structural glazing adhesives at scale, concentrating demand for certified polyurethane and epoxy systems.
- SANS 10400-XA energy codes:South Africa's building envelope thermal performance regulations mandate high-strength bonding for insulated facade systems, displacing mechanical fastening in commercial construction.
- Silane-modified polymer chemistry:Advanced hybrid formulations deliver extended service life in coastal corrosion environments, opening specification in Saudi Arabia's Red Sea and UAE's maritime-adjacent developments.
Market Restraints
- Petrochemical feedstock volatility:Polyurethane prepolymer costs fluctuate with regional propylene oxide supply, compressing margin stability for formulation-dependent product lines.
- Import concentration risk:Specialty epoxy hardeners and acrylic emulsion intermediates concentrate through UAE and Saudi ports, exposing supply security to Red Sea shipping disruptions.
- Humidity-cure limitations:Moisture-cure polyurethane systems face technical performance ceilings in Gulf summer conditions above 85% relative humidity, restricting application windows.
Strategic Opportunities
- Egypt's new administrative capital:Government-mandated smart city construction creates underpenetrated demand for structural glazing and flooring installation adhesives outside traditional Gulf markets.
- Water-based technology convergence:Hybrid acrylic-polyurethane emulsions combine low-VOC compliance with performance parity, enabling specification in Dubai Municipality green building-rated projects.
- Direct contractor procurement platforms:Digital sourcing channels bypass traditional distributor layers, allowing manufacturers to capture margin and accelerate specification feedback loops.
Industry Challenges
- SASO certification timelines:Saudi Standards, Metrology and Quality Organization adhesive performance testing requires 6-12 month validation cycles, delaying product launches behind project bid windows.
- Substrate compatibility mapping:Gulf concrete alkalinity variations and African aggregate quality inconsistency demand extensive on-site bond testing, inflating technical service costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Construction Adhesives Market |
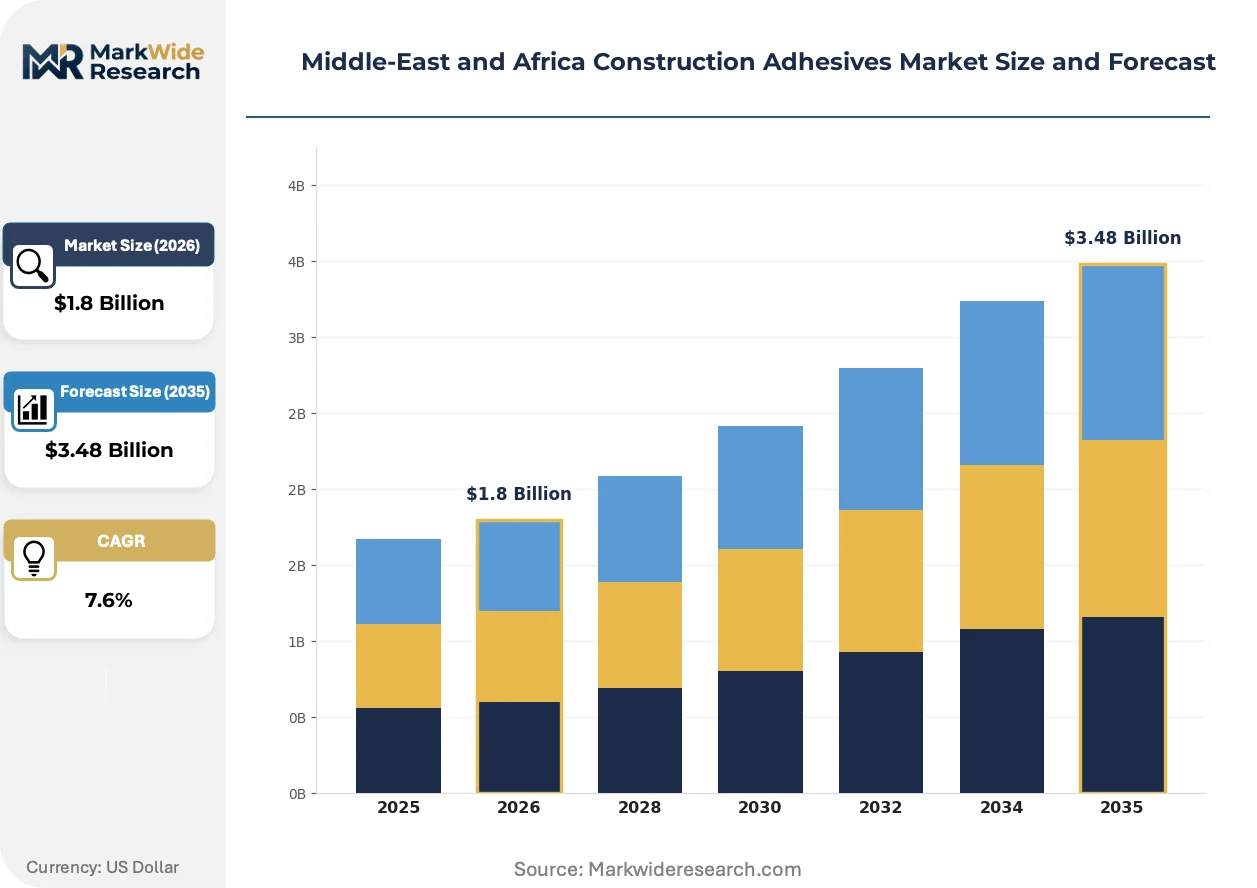
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Acrylic, PVA End User: Residential, Commercial, Industrial, Infrastructure Application: Flooring, Wall Covering, Furniture, Woodworking Technology: Water-based, Solvent-based, Hot Melt, Reactive |
| Companies Covered | Henkel AG & Co. KGaA, Sika AG, H.B. Fuller Company, Dow, 3M, Arkema Group, Wacker Chemie AG, Huntsman International LLC, Avery Dennison Corporation, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Construction Adhesives Market Shifts & Advancements
Formulation chemistry and procurement digitization are compressing traditional specification pathways, while regulatory stringency accelerates the displacement of solvent-based systems across Middle-East and African construction supply chains.
Hybrid silane-terminated polyurethane technology combines the elasticity of conventional urethanes with silane crosslinking density, delivering superior hydrolytic stability for facade assembly in Saudi coastal zones. Major developers in Riyadh and Jeddah now mandate this chemistry for projects exceeding 15-year warranty terms. The technology is rendering obsolete two-part epoxy systems in non-structural glazing applications where movement accommodation matters.
Dubai Municipality's Al Sa'fat green building rating system now restricts VOC content in interior-grade adhesives below 50 g/L, mirroring tightening trajectories in Abu Dhabi's Pearl Rating System. Formulators must maintain separate product SKUs for Gulf green-rated projects versus conventional specifications. Water-based acrylic emulsions capture accelerated specification share in UAE commercial interiors as a direct response.
Consolidated contractor procurement through government-backed project aggregators concentrates buying power among Saudi Public Investment Fund developments and UAE sovereign wealth real estate platforms. Traditional distributor networks lose specification influence as direct manufacturer-contractor technical partnerships deepen. Egypt and Morocco exhibit the most visible channel compression as state-led housing programs centralize adhesive procurement at ministry level.
Middle-East and Africa Construction Adhesives Market Segmentation
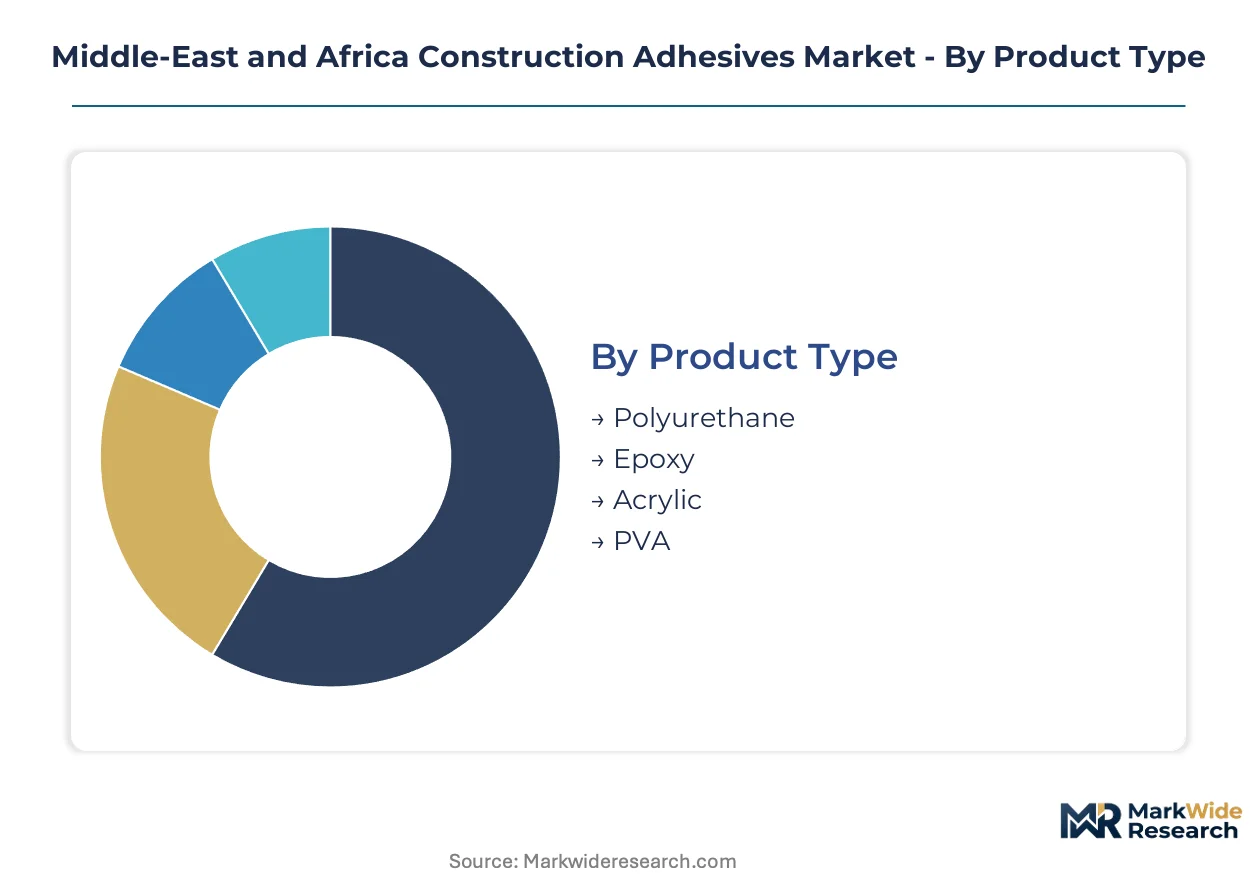
Segmentation in Middle-East and Africa construction adhesives reveals how formulation chemistry, application environment, and regulatory pressure intersect to determine procurement decisions across Gulf megaprojects and African infrastructure programs.
Product Type:
Polyurethane and epoxy formulations dominate structural applications where load-bearing certification and thermal cycling resistance command specification premiums.
- Polyurethane:Elastic prepolymer systems with gap-filling performance anchor demand in Saudi residential towers and prefabricated panel assembly. Gulf humidity extremes and concrete substrate variability concentrate procurement around moisture-cure and silane-modified variants.
- Epoxy:Two-part reactive systems deliver compressive strength for infrastructure anchoring and structural glazing in UAE maritime developments. Premium pricing reflects SASO bond-strength certification requirements and extended service life guarantees.
- Acrylic:Water-based emulsions capture interior-grade specification under Dubai Municipality VOC restrictions.
- PVA:Cost-effective woodworking and furniture bonding sees concentrated use in Egyptian state housing programs.
Established volume favors polyurethane; emerging adoption favors acrylic.
End User:
Project scale and warranty duration differentiate adhesive specification across customer tiers, with sovereign wealth developments demanding certified systems unavailable to smaller contractors.
- Residential:High-rise tower construction in Riyadh and Jeddah specifies polyurethane flooring and facade adhesives for rapid assembly schedules. Developer consolidation around Saudi Public Investment Fund platforms concentrates procurement among certified suppliers.
- Commercial:UAE green building-rated office developments mandate low-VOC systems for interior applications. Dubai Municipality Al Sa'fat compliance restricts solvent-based specification below 50 g/L VOC thresholds.
- Industrial:Manufacturing facility flooring in South Africa requires chemical-resistant epoxy systems under SANS 10400-XA energy envelope regulations.
- Infrastructure:Bridge and tunnel bonding in African markets faces substrate quality inconsistency and extended technical service requirements.
Commercial projects lead technology transition; infrastructure delivers longest contract duration.
Application:
Surface preparation standards and climatic exposure determine adhesive selection across interior versus exterior building envelope zones.
- Flooring:Elastic polyurethane systems dominate Saudi giga-project specification for ceramic tile and resilient floor covering installation. Rapid cure requirements compress application windows in NEOM and Red Sea Project timelines.
- Wall Covering:Water-based acrylics displace solvent systems in UAE commercial interiors under tightening green building codes.
- Furniture:PVA and hot-melt systems serve Egyptian and Moroccan state housing furniture manufacturing at ministry-level procurement scale.
- Woodworking:Moisture-cure limitations in Gulf summer conditions restrict polyurethane specification to climate-controlled fabrication facilities.
Flooring commands formulation R&D investment; wall covering drives regulatory compliance fastest.
Technology:
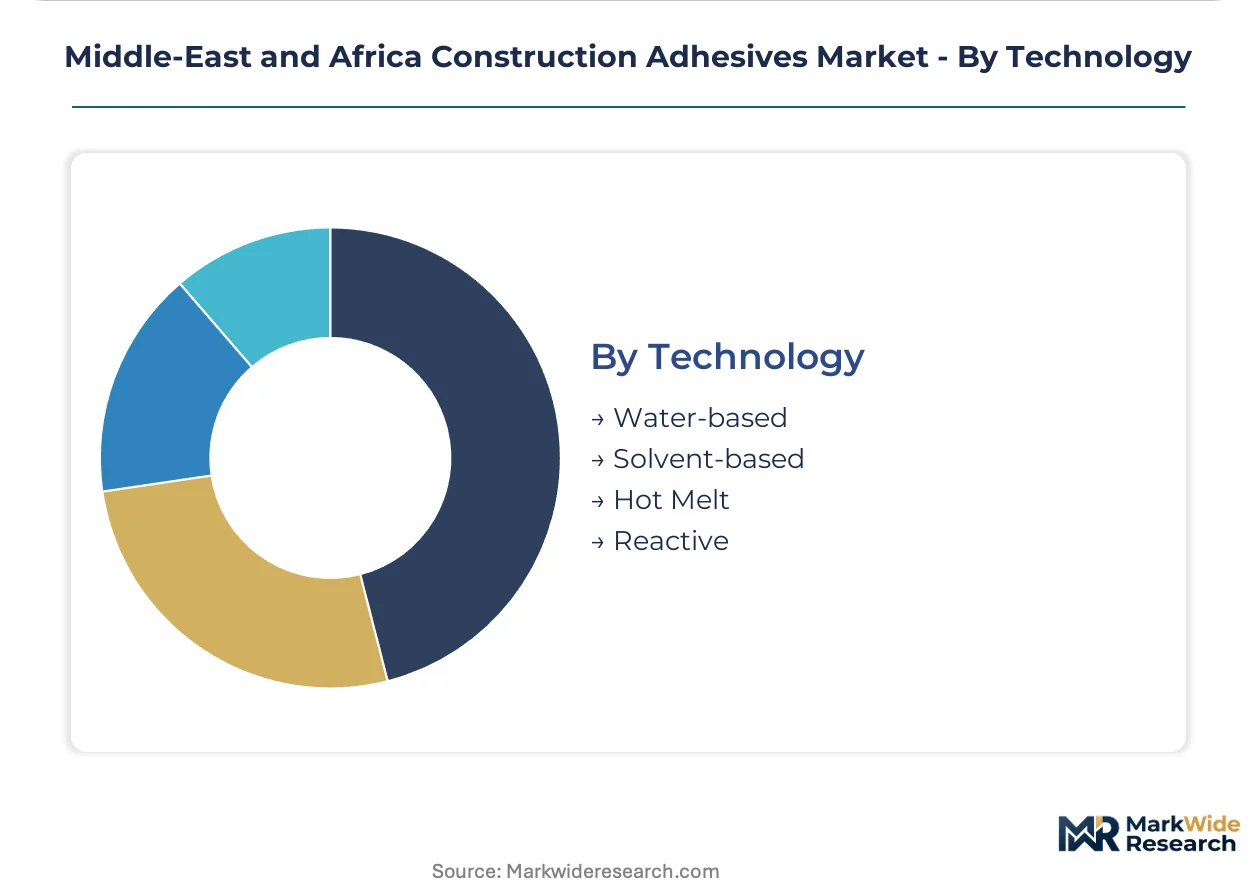
Cure chemistry and VOC content structure competitive positioning as regional environmental codes accelerate solvent system displacement.
- Water-based:Hybrid acrylic-polyurethane emulsions combine Dubai Municipality compliance with performance parity in commercial interior specification. Technology is climbing the fastest as green building ratings expand across GCC states.
- Solvent-based:Declining specification share reflects SASO building material code restrictions and South African SANS energy efficiency mandates.
- Hot Melt:Rapid-setting thermoplastic systems serve furniture and woodworking manufacturing in Egypt's new administrative capital construction programs.
- Reactive:Epoxy and moisture-cure polyurethane systems capture infrastructure and structural glazing margins where load-bearing certification commands premium pricing.
Reactive systems retain structural premium; water-based technology captures volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German adhesive exports flow into UAE and Saudi Arabia megaproject sites, while South African distributors source European water-based formulations for green building compliance. Egyptian procurement channels concentrate through government-backed housing ministries.
Saudi Arabia
NEOM and Qiddiya developments drive prefabricated panel bonding demand at unprecedented scale. SASO building material codes mandate bond-strength certification for structural applications, compressing supplier qualification timelines. Riyadh and Jeddah construction clusters specify silane-modified polyurethane systems for warranty terms exceeding fifteen years.
United Arab Emirates
Dubai's Al Sa'fat green building rating restricts interior adhesive VOC content below fifty grams per liter. Abu Dhabi Pearl Rating System mirrors these thresholds, accelerating water-based acrylic specification. Dubai Maritime City and Yas Island developments anchor demand for coastal corrosion-resistant formulations.
South Africa
SANS 10400-XA energy envelope regulations displace mechanical fastening with high-strength bonded facade systems in commercial construction. Cape Town and Johannesburg building codes tighten thermal performance requirements annually. Industrial flooring in Durban manufacturing zones specifies chemical-resistant epoxy systems.
Egypt
The new administrative capital construction program generates underpenetrated demand for structural glazing and flooring installation adhesives. Government-mandated smart city specifications diverge from traditional Gulf procurement patterns. Cairo and Alexandria furniture manufacturing clusters concentrate PVA demand through ministry-level procurement platforms.
Middle-East and Africa Construction Adhesives Market Competitive Landscape
Channel-controlling players compete with product-specialist players across specification-influencer and direct-procurement pathways. The vendor base clusters around three tiers: multinational formulation houses with regional certification capabilities, mid-scale regional blenders serving price-sensitive segments, and technology licensors supplying hybrid chemistry to local partners. Strategic moves concentrate on SASO certification acceleration and humidity-stable formulation adaptation.
Among European-headquartered multinationals, Henkel AG & Co. KGaA and Sika AG occupy positions reflecting distinct archetype specialization. Henkel exemplifies the product-adaptation model through regional formulation centers. Sika anchors the infrastructure-durability segment with concrete bonding portfolios. Dow represents the hybrid-chemistry vector competing on silane-modified polymer service life extension.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Sika AG |
| H.B. Fuller Company |
| Dow |
| 3M |
| Arkema Group |
| Wacker Chemie AG |
| Huntsman International LLC |
| Avery Dennison Corporation |
| Others |
Supply & Pricing Matrix
Overcapacity in UAE-based acrylic emulsion production is compressing regional pricing discipline while simultaneously accelerating supplier consolidation around certified polyurethane formulation hubs. This utilization imbalance forces mid-scale blenders toward price-driven competition in interior-grade segments, whereas silane-modified polymer specialists maintain premium positioning through SASO-certified structural applications.
Pricing Analysis
Current-generation silane-modified polyurethane systems command substantial premia over conventional moisture-cure formulations and first-generation water-based acrylics. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with SASO bond-strength certification and fifteen-year warranty eligibility as primary differentiation drivers. Cost compression in standard-tier water-based emulsions is intensifying because Egyptian state housing programs centralize procurement at ministry level. Project developers in Saudi giga-projects exhibit lowest price sensitivity due to warranty term requirements, while Egyptian furniture manufacturers demonstrate highest sensitivity to per-kilogram input costs.
Supply Chain Analysis
Red Sea shipping disruptions between European specialty chemical ports and Jeddah industrial zones dominate supply chain risk assessment for epoxy hardener and acrylic emulsion intermediates. Manufacturing concentration in Germany, Belgium, and the UAE anchors regional supply, with propylene oxide and isocyanate feedstocks drawing from Saudi petrochemical complexes and Asian polymer plants. Single-source vulnerability concentrates around silane coupling agents for hybrid polyurethane formulations, with limited qualified suppliers meeting Gulf humidity stability specifications. Distribution runs through Dubai Jebel Ali consolidators serving Saudi and UAE megaproject sites, with direct manufacturer-contractor partnerships increasingly bypassing traditional distributor layers in Egypt and Morocco.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle-East and Africa construction adhesives sector is recovering from cyclical lows driven by Saudi giga-project acceleration and South African energy code enforcement, creating differentiated opportunity windows across stakeholder archetypes.
For Market Incumbents: Pre-empt certification bottlenecks by accelerating SASO validation throughput for silane-modified polyurethane portfolios before Qiddiya and NEOM tender windows close. Defensive consolidation around humidity-stable formulation R&D counters emerging regional blenders with European technology licenses. Backward integration into captive propylene oxide supply secures margin stability against petrochemical feedstock volatility. For New Entrants and Emerging Players: Egypt's new administrative capital construction represents underpenetrated demand for structural glazing and flooring installation adhesives outside traditional Gulf supply relationships. Moroccan state housing programs and Nigerian infrastructure bonding offer secondary white-space targets with lower incumbent saturation. A technical partnership route with German or Swiss formulation licensors bypasses eighteen-month proprietary R&D cycles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across water-based acrylic emulsion manufacturing as Egyptian and UAE capacity additions absorb technology transfer costs. Long-term viability over a five-to-ten-year window favors acquisition targets with established SASO certification relationships and direct contractor procurement platforms rather than distributor-dependent revenue models. The signal to watch is Dubai Municipality green building rating expansion into Saudi and Qatari regulatory harmonization.| Strategic Initiative | Industry Significance |
|---|---|
| SASO Certification Acceleration | Shortens product launch timelines behind Saudi giga-project bid windows. |
| Backward Integration into Feedstocks | Captures margin stability against propylene oxide price volatility. |
| Direct Contractor Procurement Platforms | Bypasses distributor layers in Egypt and Morocco state housing programs. |
| Hybrid Silane-Polyurethane R&D Investment | Secures specification in Red Sea coastal corrosion environments. |
| Water-Based Technology Licensing | Enables rapid Dubai Municipality VOC compliance without proprietary development. |
Research Methodology
The analysis maps polyurethane, epoxy, acrylic, and reactive adhesive sub-sectors, each validated through formulation chemists, procurement directors at Saudi Public Investment Fund developers, UAE distributor technical sales leads, and South African industrial flooring contractors. Primary interview data triangulates against SASO certification databases, Dubai Municipality green building compliance filings, customs import records for epoxy hardeners and acrylic emulsions, and SEC disclosures from multinational adhesive manufacturers. Bottom-up volume estimates from application-level consumption patterns reconcile with top-down market sizing derived from construction spend allocations across the forecast period.
Fixed assumptions include sustained Saudi giga-project execution timelines, continued SANS 10400-XA energy code enforcement in South Africa, and stable petrochemical feedstock availability from regional crackers. Variable dimensions across the modeling period encompass formulation chemistry adoption curves, green building rating expansion trajectories, and direct procurement channel penetration rates. CAGRs derive from segmented volume projections calibrated to construction sector output indices and adhesive intensity per square meter benchmarks. Forecast inputs include humidity-cure performance limitations in Gulf summer conditions and substrate compatibility testing cost inflation.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese adhesive exporters or sudden Red Sea logistics disruptions would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Prefab Wood Building Market
Building & Construction Materials
Artificial Bowling Surface Market
Building & Construction Materials
Sliding Bearing Market
Building & Construction Materials
North America Ceramic Tiles Market
Building & Construction Materials
Dimension Stone Market
Building & Construction Materials
Roof Window Market
Building & Construction Materials
Vinyl Windows Market
Building & Construction Materials
Vegetal Concrete Market
Building & Construction Materials
Oriented Strand Board (OSB) Market
Building & Construction Materials
France Oriented Strand Board Market
Building & Construction Materials
Spray Foam Market
Building & Construction Materials
Europe Construction Chemicals Market
Building & Construction Materials
Residential and Commercial Smart Glass Market
Building & Construction Materials
Architectural Membrane Market
Building & Construction Materials
Fiber Cement Rainscreen Panels Market
Building & Construction Materials
Seal Coat Market