
 Global Wheel Trenchers Market | 2026-2036
Global Wheel Trenchers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wheel Trenchers Market Outlook
Modular attachment configurations is shifting buyer preference away from dedicated single-purpose machines toward versatile platforms. Ditch Witch leverages its deep catalog of interchangeable trencher heads to capture cross-application contracts. Vermeer sustains engineering leadership through integrated vacuum excavation systems bundled with wheeled trencher chassis. Tesmec anchors European demand with heavy-duty configurations engineered for rocky soil conditions in southern Europe.
Wheel trenchers are self-propelled excavation machines mounted on rubber-tired or track-driven chassis, utilizing continuous digging chains or rotating rock wheels to cut narrow trenches at controlled depths and widths for buried infrastructure installation. Operating weights range from compact walk-behind units under 500 kg to ride-on models exceeding 15,000 kg, with trenching depths typically spanning 30 cm to 240 cm depending on boom configuration and ground conditions. Ride-on trenchers generate the largest revenue pool due to their dominance in utility-scale projects requiring sustained daily output across varied terrain. Walk-behind units represent the fastest-expanding configuration category as landscaping contractors and small municipalities prioritize maneuverability in congested urban corridors with limited access.
EPA Tier 4 Final emissions mandates for non-road diesel engines compel manufacturers to integrate aftertreatment systems or alternative powertrains, directly affecting equipment pricing and maintenance protocols in the United States. CE marking requirements under EU machinery directives govern safety interlocks, operator visibility standards, and noise emissions for wheeled trenchers sold across European member states. ISO 3450 and ISO 5010 stability standards further constrain chassis design for large-format units operating on slopes. Stakeholders must monitor evolving battery-electric powertrain viability against diesel-hybrid architectures as total cost of ownership calculations shift with energy infrastructure maturation and carbon pricing mechanisms.
Market Dynamics
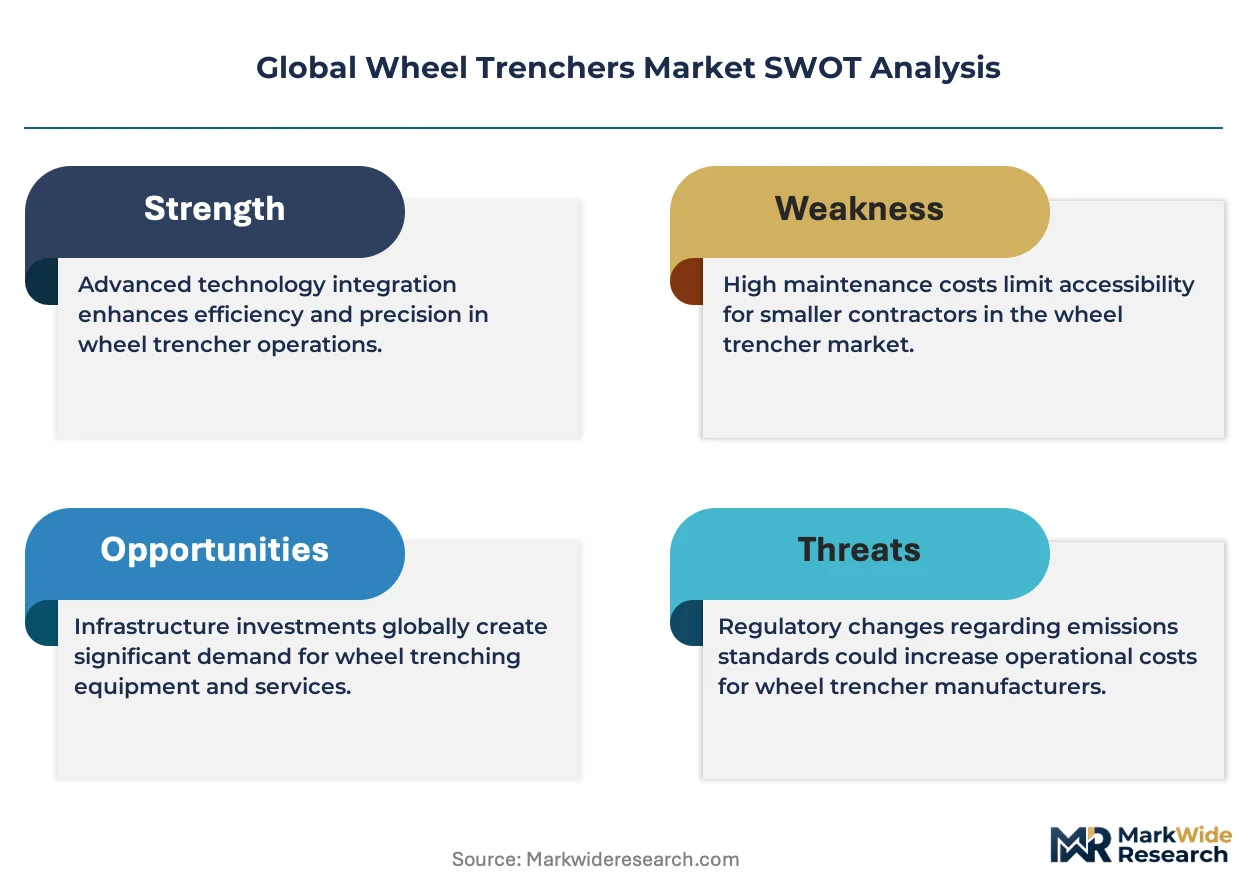
Federal broadband infrastructure programs in the United States are compressing project timelines for fiber-optic deployment, forcing municipal contractors to prioritize equipment uptime and rapid mobilization over capital cost minimization.
Growth Catalysts
- EPA Tier 4 Final mandates:Stringent emissions standards for off-road diesel engines are accelerating fleet turnover among utility contractors seeking compliant equipment.
- Fiber-optic cable deployment:Telecommunications infrastructure expansion is generating sustained demand for ride-on trenchers capable of continuous daily operation across varied terrain.
- Modular attachment platforms:Interchangeable trencher head configurations are enabling single-machine versatility across multiple contract types, improving asset utilization rates.
Market Restraints
- Aftertreatment system costs:Diesel particulate filters and selective catalytic reduction hardware are elevating base equipment pricing and complicating maintenance protocols.
- Specialized operator certification:OSHA excavation safety requirements and manufacturer-specific training programs are extending workforce onboarding timelines.
- Battery energy density limitations:Current lithium-ion cell technology constrains electric powertrain runtime for heavy-duty trenching applications exceeding eight-hour shifts.
Strategic Opportunities
- CE marking harmonization:Unified EU machinery directive compliance is streamlining cross-border equipment sales across Germany, France, and Italy.
- Vacuum excavation integration:Converging trencher chassis with hydro-excavation systems is opening utility contracts requiring precision digging near existing buried infrastructure.
- Walk-behind urban penetration:Compact units under 500 kg are capturing landscaping and municipal maintenance contracts in congested European and Japanese city centers.
Industry Challenges
- ISO 3450 stability certification:Slope-operation safety standards are extending engineering validation cycles for large-format ride-on units.
- Supply chain reconfiguration:Engine aftertreatment component sourcing is forcing manufacturers to qualify alternative Tier 4 Final compliant suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wheel Trenchers Market |
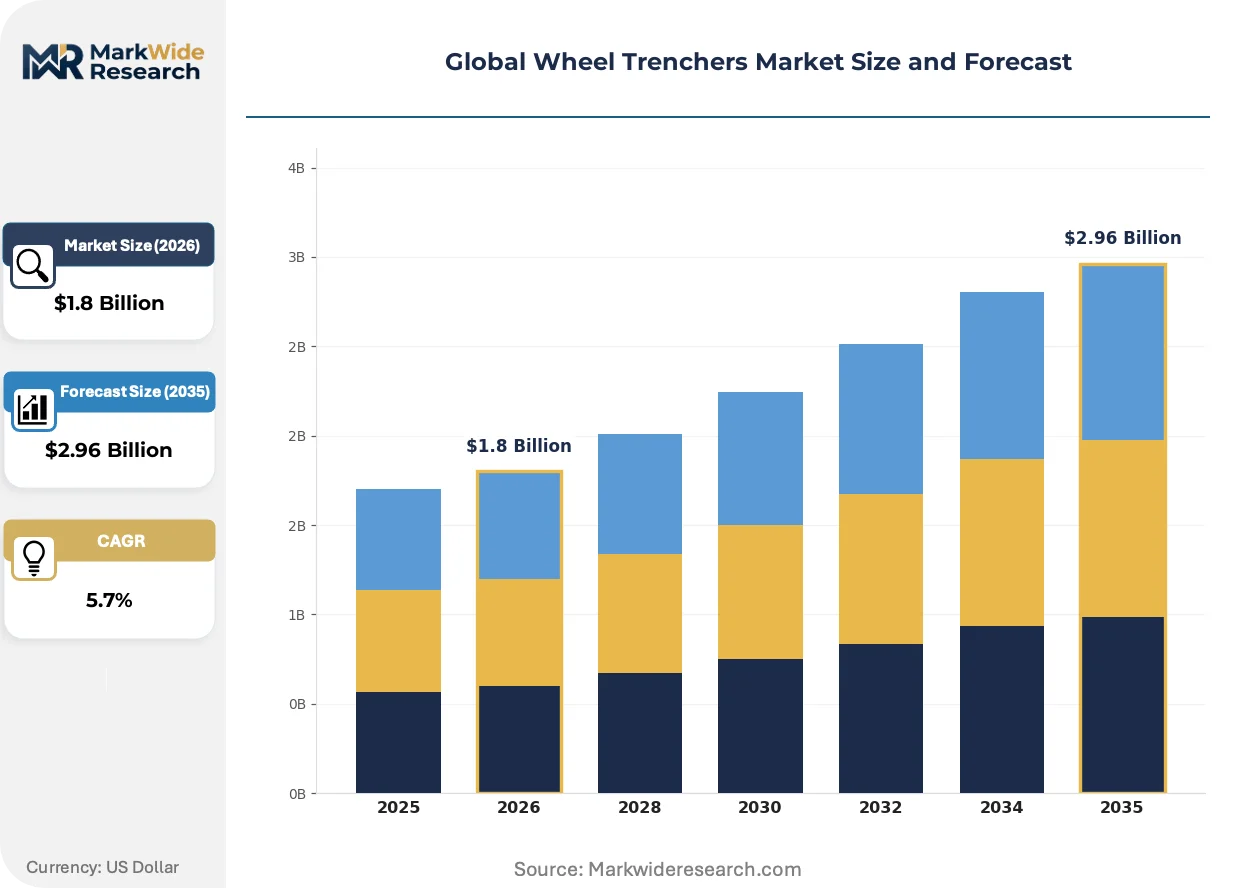
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trencher Attachments, Ride-On Trenchers, Walk-Behind Trenchers, Chain Trenchers Application: Telecommunications, Electrical Installations, Water Supply, Gas Distribution End User: Contractors, Municipalities, Utility Companies, Agricultural Firms Size: Small, Medium, Large, Extra Large |
| Companies Covered | Ditch Witch, Vermeer, Tesmec, Wolfe Heavy Equipment, Marais, Port Industries, Guntert & Zimmerman, Barreto, Toro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wheel Trenchers Market Strategic Shifts
Equipment manufacturers are converging mechanical trenching capability with real-time soil sensing and automated depth control, compressing the skill gap between veteran operators and entry-level crews.
Electrified powertrains are absorbing development resources across major equipment portfolios as battery pack energy density improves and charging infrastructure matures near urban utility depots. Municipal fleet managers in California and New York are piloting electric ride-on units for short-haul fiber deployment contracts. This transition is absorbing service revenue from traditional engine overhaul intervals while creating new competency requirements for high-voltage system diagnostics.
REACH chemical restrictions and EU F-Gas Regulation are constraining hydraulic fluid formulations and refrigerant choices for climate-controlled operator cabs sold across European member states. Manufacturers are reformulating component specifications to maintain CE marking compliance without sacrificing cold-weather performance. German and French utility contractors are experiencing extended equipment specification review cycles as procurement teams validate substance compliance documentation.
Rental channel expansion is fragmenting traditional dealer-direct sales relationships as national equipment lessors build dedicated trencher fleets for telecommunications infrastructure projects. Regional rental houses in Texas and Florida are capturing municipal maintenance contracts previously awarded through capital purchase programs. This channel shift is most visible in the United States, where federal broadband subsidy programs are accelerating project starts faster than municipal capital budgets can accommodate.
Global Wheel Trenchers Market Segmentation
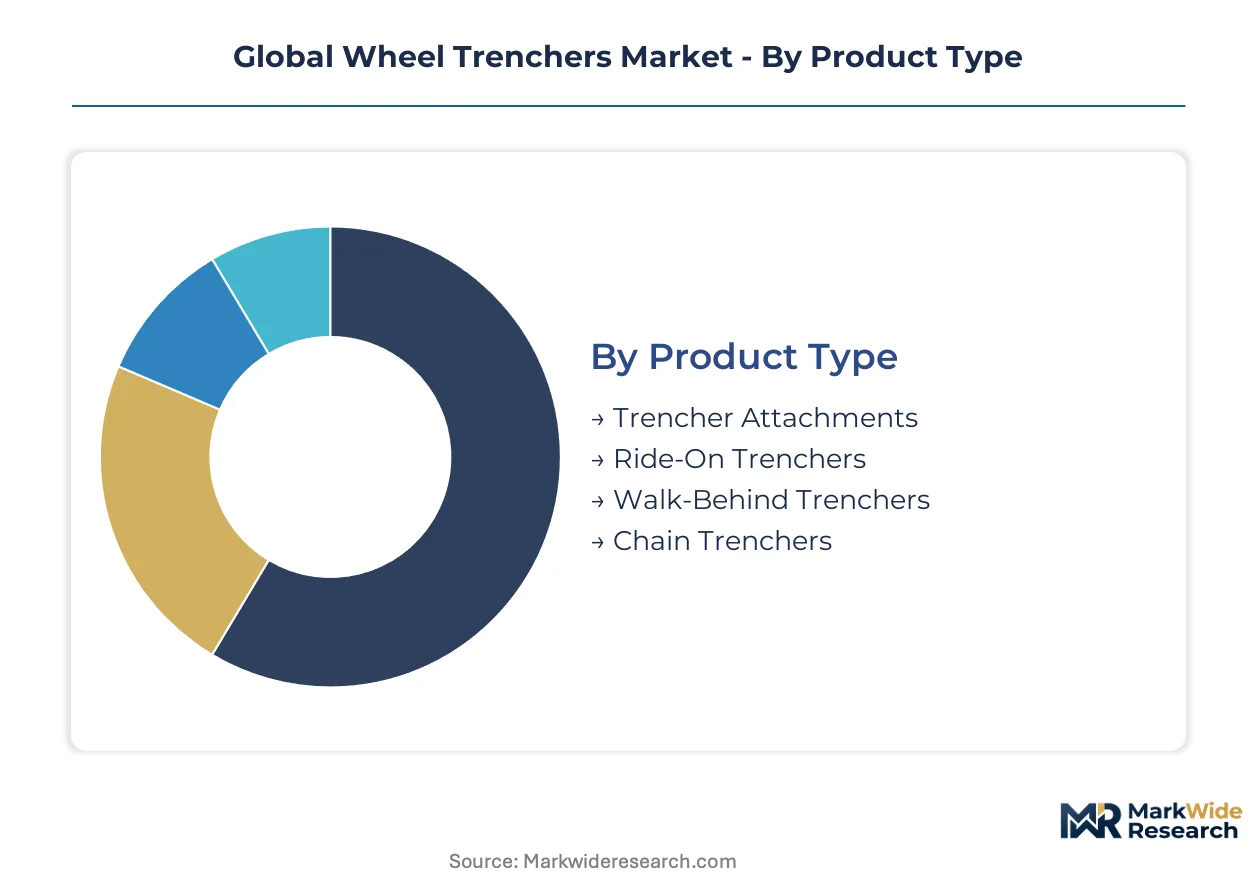
Wheel trencher procurement patterns diverge sharply across operational scales and regulatory environments, forcing manufacturers to engineer platform flexibility rather than single-purpose optimization. Segmentation reveals how equipment specifications map to project economics, with powertrain choices and attachment modularity becoming primary purchase determinants.
Product Type:
Equipment selection hinges on whether buyers prioritize continuous daily output or maneuverability in constrained access corridors.
- Ride-On Trenchers:Self-propelled units mounted on rubber-tired or track-driven chassis deliver sustained trenching depths spanning 30 cm to 240 cm across varied terrain. Utility companies in the United States dominate procurement of these configurations for fiber-optic cable deployment programs requiring daily operational continuity.
- Walk-Behind Trenchers:Compact configurations under 500 kg enable precision trenching in congested urban corridors with limited site access. Municipalities in Japan and European city centers are expanding walk-behind fleet allocations for landscaping and maintenance contracts where larger equipment cannot mobilize.
- Chain Trenchers:Continuous digging chain systems engineered for aggressive soil conditions and rocky substrate penetration.
- Trencher Attachments:Modular head configurations converting standard wheeled chassis into multi-application platforms through quick-coupler interfaces.
Ride-on configurations lead volumes today; walk-behind units are gaining share fastest.
Application:
Project timelines and regulatory oversight intensity create divergent equipment specification requirements across infrastructure categories.
- Telecommunications:Fiber-optic cable deployment demands trenching precision within narrow width tolerances to protect adjacent conduit infrastructure. Federal broadband infrastructure programs in the United States are compressing project schedules and elevating uptime requirements over capital cost minimization for contractors serving this segment.
- Gas Distribution:High-consequence excavation near pressurized pipelines mandates integration of vacuum excavation systems for precision soil removal. Vermeer has captured cross-application contracts by bundling hydro-excavation capability with wheeled trencher chassis for utility contractors operating under OSHA excavation safety requirements.
- Electrical Installations:Underground power distribution and renewable energy interconnection projects requiring controlled depth trenching for cable protection.
- Water Supply:Municipal pipeline replacement and rural distribution network expansion with emphasis on corrosion-resistant bedding installation.
Telecommunications applications command the largest equipment allocation today; gas distribution specifications are climbing fastest.
End User:
Capital availability and fleet utilization economics separate procurement behavior across customer categories.
- Utility Companies:Vertically integrated infrastructure owners with multi-year capital planning horizons and standardized fleet specifications. North American electric and gas utilities are expanding ride-on trencher purchases through dedicated equipment lessors rather than dealer-direct channels to accelerate project mobilization under federal subsidy timelines.
- Contractors:Project-based operators with equipment selection driven by contract mix flexibility and rental channel access. Regional rental houses in Texas and Florida have captured municipal maintenance contracts previously awarded through capital purchase programs.
- Municipalities:City and county public works departments with constrained capital budgets prioritizing walk-behind configurations for urban corridor access.
- Agricultural Firms:Drainage tile installation and irrigation system deployment operators in midwestern United States and Canadian prairie provinces.
Utility companies anchor procurement volumes; contractor reliance on rental channels is expanding most quickly.
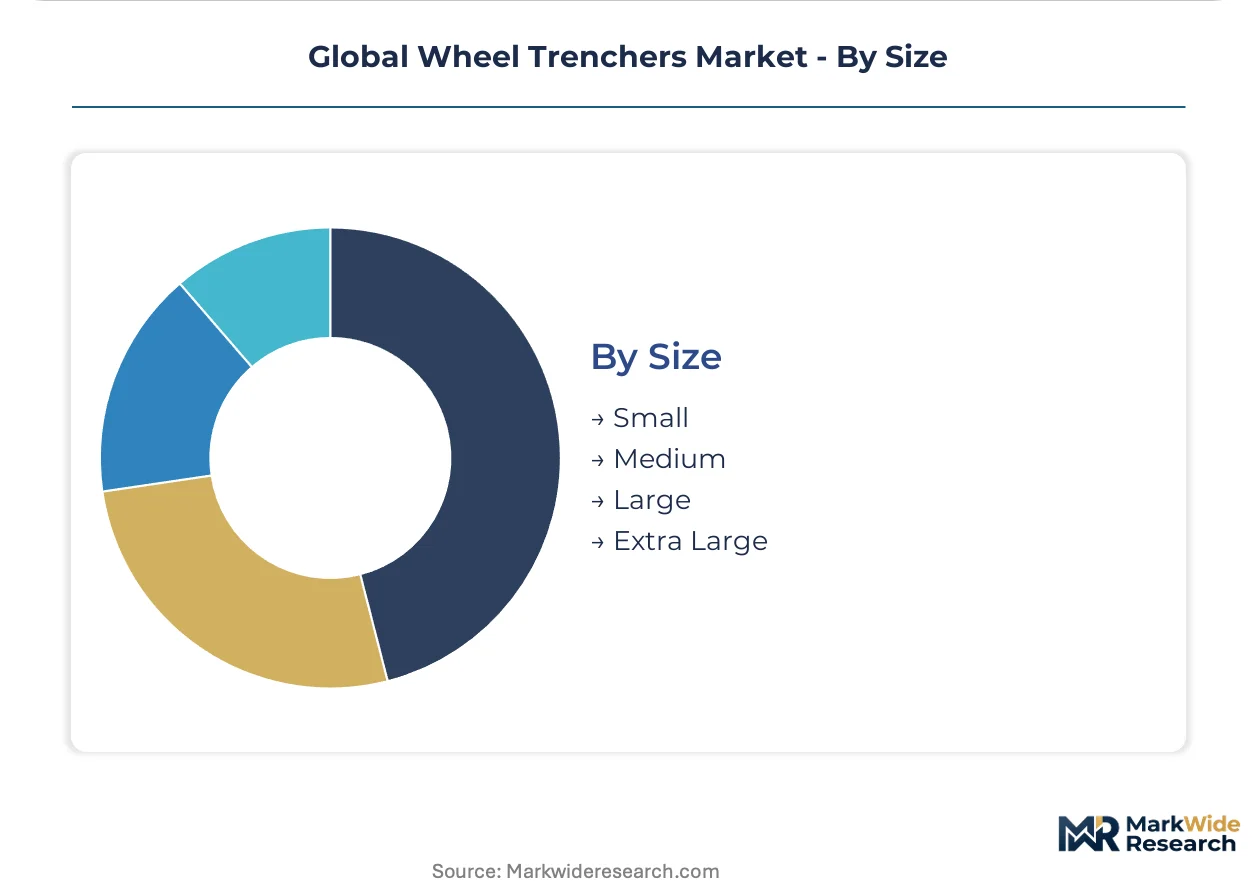
Size:
Operating weight classes determine transport logistics, slope stability certification requirements, and operator licensing thresholds.
- Large:Units exceeding 15,000 kg operating weight engineered for continuous daily output across rocky soil conditions in southern Europe. Tesmec anchors European demand with heavy-duty configurations requiring ISO 3450 stability validation for slope operation.
- Small:Configurations under 500 kg enabling single-operator deployment without specialized transport permitting. Japanese and European municipal fleets are standardizing on compact units for congested urban maintenance corridors.
- Medium:Mid-range platforms balancing trenching depth capability with site mobility for regional utility contractors.
- Extra Large:Specialized configurations for mining drainage and major pipeline corridor development with dedicated transport and assembly requirements.
Large units dominate revenue contribution today; small configurations show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The wheel trencher industry traces its commercial origins to post-war American utility infrastructure expansion, with early mechanized trenching systems developed for rural electrification and telephone network deployment across the Midwestern United States.
United States
Federal broadband infrastructure programs are compressing fiber-optic deployment timelines and elevating equipment uptime requirements above capital cost minimization. EPA Tier 4 Final emissions mandates for non-road diesel engines are accelerating fleet turnover among utility contractors seeking compliant equipment. Municipal trenching contracts concentrate in Texas and Florida, where regional rental houses are capturing maintenance work previously awarded through capital purchase programs.
Germany
Utility contractors are experiencing extended equipment specification review cycles as procurement teams validate REACH chemical compliance documentation for hydraulic fluid formulations. CE marking requirements under EU machinery directives govern safety interlocks and operator visibility standards for wheeled trenchers sold across member states. Manufacturing and engineering activity clusters in North Rhine-Westphalia, where component suppliers are reformulating specifications to maintain cold-weather performance.
Japan
Municipal fleets are standardizing on compact walk-behind configurations for congested urban maintenance corridors where larger equipment cannot mobilize. METI industrial standards influence equipment certification protocols for domestic and export-bound machinery. Tokyo metropolitan area contractors are prioritizing maneuverability in dense infrastructure environments with limited site access.
Italy
Heavy-duty trencher configurations engineered for rocky soil conditions anchor southern European demand, particularly for gas distribution and water supply infrastructure. EU F-Gas Regulation constrains refrigerant choices for climate-controlled operator cabs sold across member states. Industrial activity concentrates in Lombardy and Emilia-Romagna, where manufacturers are adapting chassis designs for slope-operation stability certification.
Canada
Agricultural drainage tile installation and irrigation system deployment drive mid-sized equipment procurement across prairie provinces. Health Canada and provincial environmental regulators oversee emissions compliance parallel to EPA standards for cross-border equipment movement. Alberta and Saskatchewan farming cooperatives are expanding mechanized trenching capacity for large-scale field drainage projects.
Global Wheel Trenchers Market Competitive Environment
Premium-margin players sit above commodity-margin players across attachment modularity and integrated system bundling. The vendor base organizes into three tiers: diversified construction equipment conglomerates with trencher divisions, specialized underground utility machinery manufacturers, and regional fabrication shops serving agricultural and landscaping niches. Dominant competitive moves include strategic partnerships between chassis manufacturers and aftertreatment system suppliers, plus portfolio diversification into vacuum excavation integration.
Among specialized underground utility machinery manufacturers, Ditch Witch, Vermeer, and Tesmec exemplify distinct competitive archetypes. Ditch Witch represents the attachment-modularity approach through its catalog of interchangeable trencher heads. Vermeer occupies a position emphasizing integrated system bundling, particularly around vacuum excavation convergence. Tesmec anchors the heavy-duty configuration segment with equipment engineered for demanding soil conditions.
| Leading Market Players |
|---|
| Ditch Witch |
| Vermeer |
| Tesmec |
| Wolfe Heavy Equipment |
| Marais |
| Port Industries |
| Guntert & Zimmerman |
| Barreto |
| Toro |
| Others |
Value Chain & Pricing Dynamics
Steel price indices and diesel engine aftertreatment component costs cascade through wheel trencher manufacturing tiers, compressing margins on mid-range configurations while premium modular platforms capture pricing power through attachment ecosystem lock-in. Tier 4 Final compliance hardware elevates base equipment costs across all weight classes, forcing procurement teams to weigh capital expenditure against rental channel flexibility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies wheel trencher markets by attachment modularity depth and integrated system bundling. Price differentiation hinges on EPA Tier 4 Final certification tier and aftermarket service contract inclusion, with utility contractors showing lowest sensitivity due to federal subsidy timelines compressing mobilization decisions. Cost compression in economy walk-behind segments is intensifying because rental channel expansion fragments traditional dealer-direct relationships.
Supply Chain Analysis
Workforce availability constraints in Iowa and North Rhine-Westphalia manufacturing clusters are extending component qualification cycles for Tier 4 Final aftertreatment systems. Supply concentrates in the United States, Germany, and Italy, with hydraulic pump assemblies and high-strength steel boom fabrications drawing from captive foundry networks. Single-source vulnerability sits with selective catalytic reduction hardware suppliers. Distribution runs through national equipment lessors and regional dealer networks serving municipal and utility contractor segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wheel trencher market functions as a regulatory compounder where EPA Tier 4 Final mandates and federal broadband infrastructure programs synchronize to accelerate fleet turnover and elevate equipment uptime premiums above capital cost minimization.
For Market Incumbents: Lock in attachment ecosystem dominance by expanding quick-coupler interface standardization across trencher head configurations, defending against emerging electric powertrain specialists through backward integration into battery pack thermal management systems. Prioritize certification investment for ISO 3450 slope stability validation to capture European gas distribution contracts requiring ruggedized heavy-duty platforms. For New Entrants and Emerging Players: Launch via rental channel partnerships targeting Texas and Florida municipal maintenance contracts, where federal broadband subsidy acceleration outpaces capital budget cycles. White-space opportunity concentrates in compact walk-behind electric configurations for Japanese urban corridors and California fiber deployment pilots, with go-to-market positioning emphasizing maneuverability and emissions compliance over raw trenching depth. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized underground utility machinery manufacturers possessing vacuum excavation integration capability and established CE marking documentation. Long-term viability favors acquisition targets with modular platform architectures and service revenue streams from high-voltage system diagnostics. Watch battery energy density improvements exceeding eight-hour shift thresholds as the inflection signal for electric powertrain mass adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum Excavation Integration | Captures OSHA-compliant utility contracts near pressurized gas pipelines through precision soil removal capability. |
| Attachment Modularity Expansion | Enables single-machine versatility across fiber-optic, gas distribution, and water supply contract types. |
| Electric Powertrain Pilot Programs | Positions municipal fleets in California and New York for zero-emissions infrastructure deployment mandates. |
| Rental Channel Partnership Buildout | Accelerates project mobilization under compressed federal broadband subsidy timelines. |
| CE Marking Harmonization Investment | Streamlines cross-border equipment sales across Germany, France, and Italy under unified EU machinery directives. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with utility fleet managers, municipal procurement officers, and rental channel operators alongside secondary validation through SEC equipment manufacturer filings, EPA certification databases, and EU machinery directive compliance registries. Bottom-up unit shipment estimates triangulate against top-down infrastructure spending projections from federal broadband program disclosures.
Granularity-level modeling disaggregates volume and value outputs by product type, application, end user, and operating weight class, with powertrain architecture and attachment modularity depth as additional industry-specific segmentation dimensions. CAGRs derive from trend extrapolation of fleet turnover rates, regulatory compliance deadlines, and infrastructure deployment schedules across the projection horizon. Forecast inputs incorporate diesel-electric hybrid adoption curves and lithium-ion battery pack cost trajectories.
Several conditions sit outside the modeled scope, including abrupt shifts in federal subsidy allocation, supply chain disruptions affecting Tier 4 Final aftertreatment component availability, and breakthrough advances in solid-state battery technology. Forecasts reflect assumptions about regulatory stability and commodity price trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Global Tablet Press Machine Market
Construction Equipment
Global Portable Light Towers Market
Construction Equipment
Mobile Elevating Work Platform (MEWP) Market
Construction Equipment
Latin America Heavy Construction Equipment Rental Market
Construction Equipment
Commercial Laundry Machines Market
Construction Equipment
(AWP) Aerial Work Platform Rental Market
Construction Equipment
Mini Excavators Market
Construction Equipment
Global Skid Steer Attachments Market
Construction Equipment
North America Mini and Midi Horizontal Directional Drilling Market
Construction Equipment
Autonomous Heavy Equipment Market
Construction Equipment
Truck Mounted Concrete Pump Market
Construction Equipment
Winch Market
Construction Equipment
North America Mobile Light Tower Market
Construction Equipment
Crossover Ladder Market
Construction Equipment
Concrete Placing Booms Market
Construction Equipment
Tower Crane Market